
 Animal Derivatives Market | 2026-2036
Animal Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Derivatives Market Outlook
Maintenance and technical service contracts for rendering and bioprocessing equipment is rebalancing how value gets captured downstream from raw material supply. Cargill leverages its integrated protein-to-derivatives infrastructure across North American feedstock zones. Darling Ingredients anchors its position through specialized rendering and grease recovery operations that sustain margin density in lower-volume product lines.
Animal derivatives comprise proteinaceous and structural materials recovered from livestock and poultry processing, including collagen with triple-helix molecular weights ranging from 300 to 400 kDa, gelatin formed through controlled hydrolysis of collagen, and keratinous by-products such as horn. These materials serve as functional inputs across food stabilization, pharmaceutical encapsulation, cosmetic matrices, and leather tanning. Gelatin and collagen together concentrate the highest margin pools, with pharmaceutical-grade variants commanding premium positioning over standard food-industrial grades. Leather as a segment retains substantial volume but faces substitution pressure from bio-based alternatives, while nutraceutical applications for collagen peptides represent the fastest-growing demand channel.
EMA pharmaceutical guidelines, REACH substance registration requirements, and USDA FSIS inspection protocols collectively shape product standards and cross-border market access for animal-derived inputs. FDA biologics regulations and BIS certification standards in India further segment quality tiers, with pharmaceutical-grade materials subject to stricter species-origin documentation than food or cosmetic grades. Stakeholders must monitor evolving regulatory divergence between jurisdictions to anticipate where compliance costs will reshape competitive positioning.
Market Dynamics
Pharmaceutical-grade collagen and gelatin specifications are tightening traceability requirements back to slaughterhouse origin, forcing rendering operations to deploy blockchain-enabled batch tracking systems that restructure capital allocation across the value chain.
Growth Catalysts
- REACH substance registration:ECHA documentation mandates for bovine-derived inputs accelerate investment in certified rendering capacity across European member states.
- Drug delivery matrices:Pharmaceutical manufacturers expand gelatin encapsulation for controlled-release formulations, absorbing higher-margin refined outputs.
- China nutraceutical demand:Collagen peptide consumption for skin health supplements concentrates manufacturing investment in Shandong and Guangdong provinces.
Market Restraints
- Feedstock cost volatility:Cattle and poultry slaughter volumes fluctuate with livestock disease outbreaks, compressing rendering margins during supply contractions.
- Substitution threat:Plant-based collagen alternatives from microbial fermentation gain formulation share in cosmetic applications.
- Regulatory friction:USDA FSIS species-origin documentation requirements extend certification timelines for cross-border pharmaceutical shipments.
Strategic Opportunities
- India cosmetic formulations:BIS certification standards for imported animal derivatives create first-mover advantage for compliant suppliers establishing local blending operations.
- Regulatory tailwind:EU Green Deal bioplastics mandates stimulate keratin-derived biopolymer development for packaging films.
- Technology convergence:Enzymatic hydrolysis combined with membrane filtration enables production of sub-5 kDa collagen peptides for nutraceutical absorption claims.
Industry Challenges
- Specialized technician scarcity:Rendering facilities face recruitment gaps for operators qualified in HACCP-compliant bioprocessing equipment maintenance.
- Pharmaceutical-grade certification timelines:EMA documentation requirements for novel gelatin sources extend qualification periods to 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Derivatives Market |
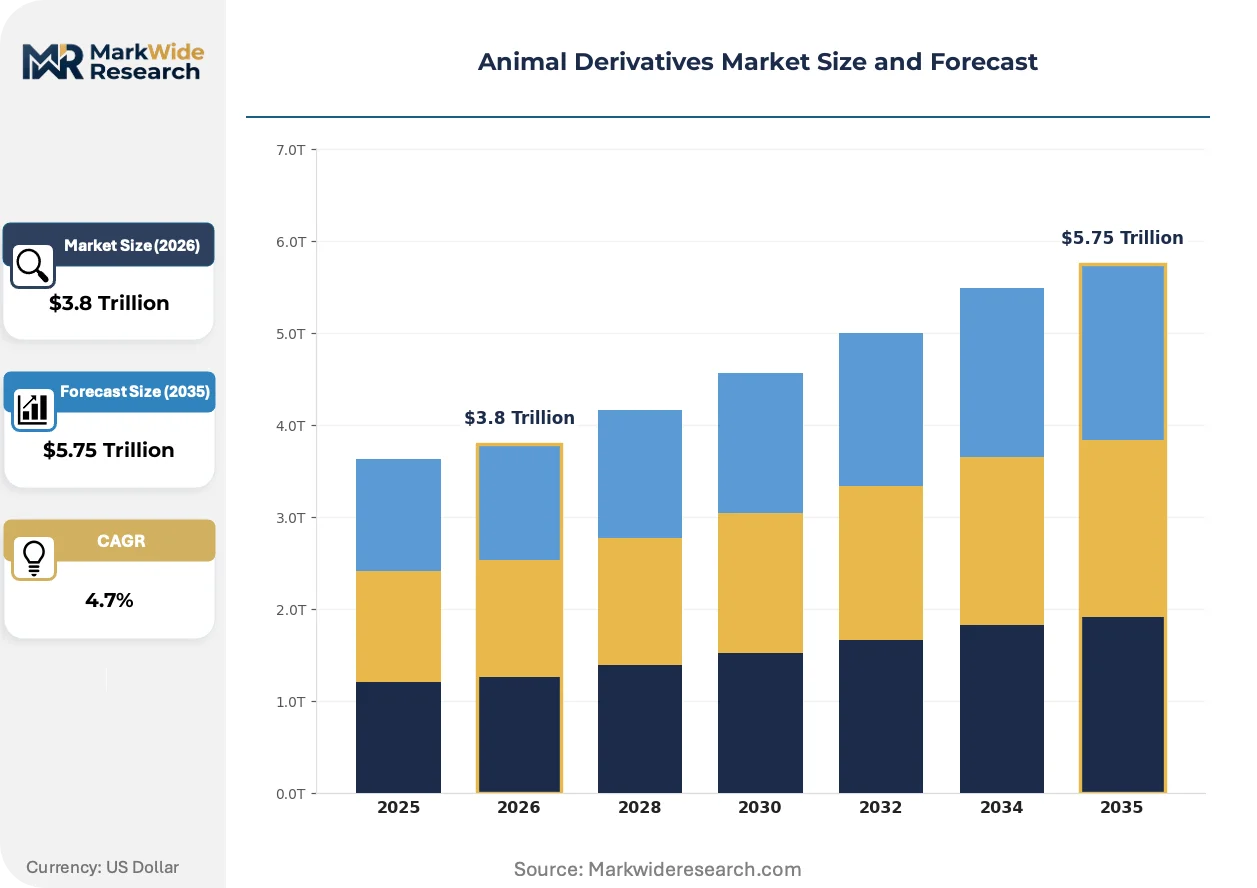
| Market Size in 2026 | $3.8 Trillion |
| Market Size in 2035 | $5.75 Trillion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin, Collagen, Leather, Horn Application: Food Industry, Pharmaceutical, Cosmetics, Nutraceuticals End User: Food Manufacturers, Cosmetic Companies, Healthcare Providers, Research Institutions Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Cargill, Tyson Foods, Darling Ingredients, JBS, Archer Daniels Midland, Rousselot, Gelita, Kerry Group, Glanbia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Derivatives Market Strategic Shifts
Enzymatic processing advances and traceability digitization are compressing the gap between raw material recovery and pharmaceutical-grade output, reshaping where value accumulates in the supply chain.
Controlled enzymatic hydrolysis is unifying collagen extraction across food, pharmaceutical, and cosmetic grade streams into single production lines with real-time molecular weight monitoring. Nutraceutical manufacturers in Japan and South Korea adopt these systems fastest, reducing batch rejection rates. This technology is unifying previously separate rendering operations into integrated biorefineries that capture margin across multiple grade tiers.
ECHA substance restriction updates under REACH tighten bovine spongiform encephalopathy traceability to individual animal identification. Rendering operations must now maintain 10-year record archives linking each output batch to slaughterhouse source documentation. Pharmaceutical-grade gelatin producers in Germany and France face the steepest compliance cost increases, driving consolidation toward vertically integrated protein processors.
Buyers in cosmetic formulations now demand ISO 17025-accredited third-party testing for collagen peptide molecular weight distribution before contract execution. Traditional certificate-of-analysis documentation no longer suffices for premium positioning. This specification escalation is most visible in South Korean and Chinese skincare manufacturing clusters, where brand owners transfer testing costs upstream to derivative suppliers.
Animal Derivatives Market Segmentation
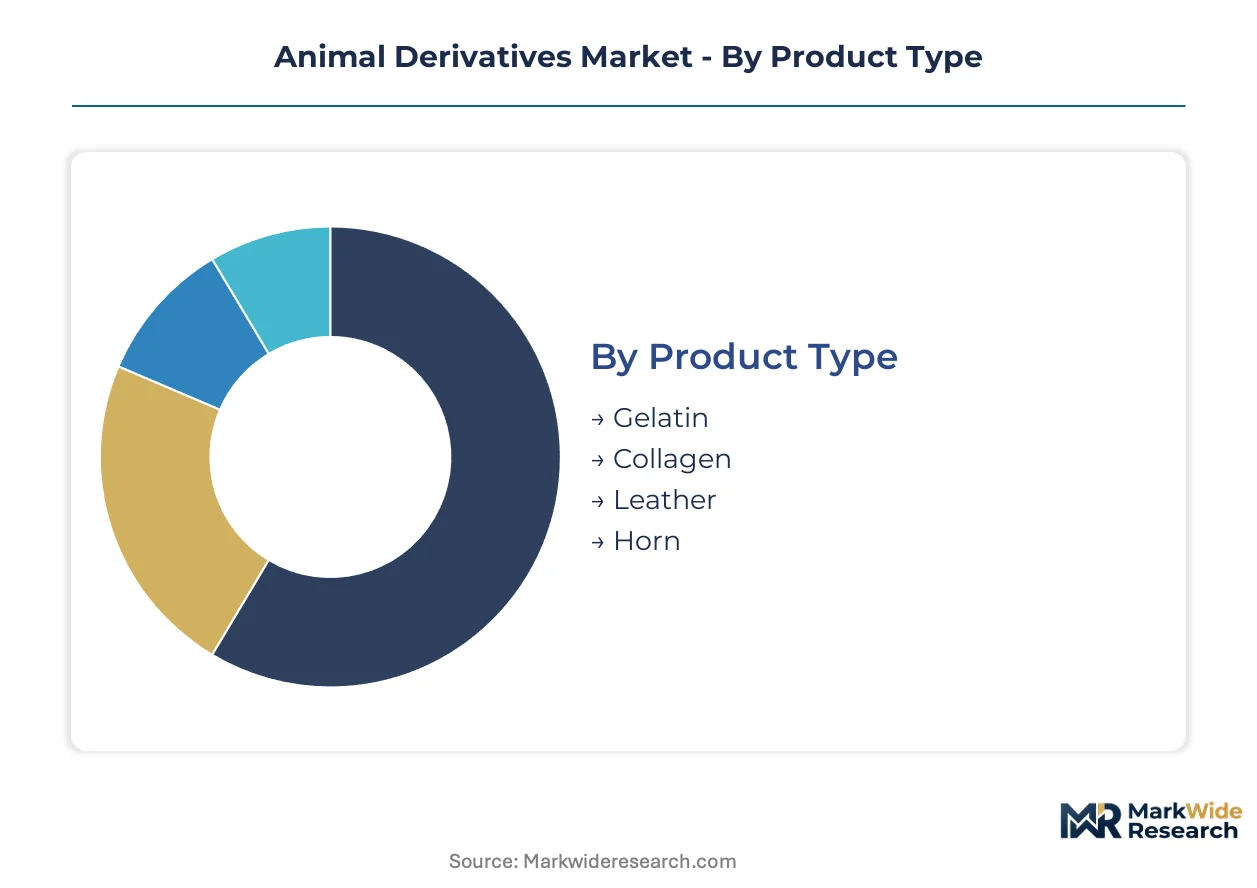
Animal derivatives fragment into distinct value pools based on molecular complexity and certification grade. Each segment commands divergent margin structures tied to end-use scrutiny and regulatory documentation burden.
Product Type:
Supply concentration in rendering infrastructure determines which molecular fractions capture downstream value in pharmaceutical and food applications.
- Gelatin:Controlled hydrolysis of collagen yields this proteinaceous hydrocolloid with bloom strength specifications from 50 to 300. Pharmaceutical manufacturers in Germany absorb expanding volumes for capsule encapsulation as EMA traceability mandates tighten. This segment commands the steepest premium tiering between food-grade and pharmaceutical-grade certifications.
- Collagen:Triple-helix proteins with molecular weights spanning 300 to 400 kDa undergo enzymatic extraction for nutraceutical peptide production. Demand clusters in China's Shandong province for skin health supplements, where sub-5 kDa hydrolysates absorb the fastest capacity expansion. Collagen peptides represent the steepest expansion trajectory across all product types.
- Leather:Structural collagen matrices preserved through tanning chemistry retain substantial volume in automotive and luxury goods. Bio-based substitutes from mycelium and plant polymers displace share in premium fashion applications.
- Horn:Keratinous by-products from bovine and ovine sources supply niche applications in traditional medicine and decorative crafts. Limited pharmaceutical traction constrains margin development.
Today's leader: Gelatin. Tomorrow's challenger: Collagen.
Application:
End-use certification requirements stratify pricing power, with pharmaceutical and nutraceutical applications extracting premiums unavailable to commodity food channels.
- Pharmaceutical:Drug delivery matrices demand gelatin with endotoxin limits below 10 EU/g and full slaughterhouse traceability. FDA biologics regulations and EMA guidelines force 18-24 month qualification timelines for new suppliers, entrenching incumbent positions.
- Nutraceuticals:Collagen peptides for joint and skin health supplements absorb capacity fastest in South Korea and China. ISO 17025-accredited molecular weight verification now precedes contract execution for premium positioning.
- Cosmetics:Topical formulations utilize hydrolyzed collagen for moisture retention claims. Plant-based microbial alternatives gain formulation share in clean-label product lines.
- Food Industry:Stabilization and gelling applications in confectionery and dairy absorb standard-grade gelatin volumes. Price sensitivity limits margin capture compared to pharmaceutical channels.
Pharmaceutical applications defend margin density. Nutraceuticals climb fastest.
End User:
Procurement sophistication separates institutional buyers with captive technical staff from distributors serving fragmented downstream accounts.
- Healthcare Providers:Hospital systems and specialty clinics source pharmaceutical-grade gelatin for compounding pharmacies. Direct relationships with certified renderers bypass distribution markups.
- Cosmetic Companies:South Korean and Chinese skincare manufacturers demand batch-specific molecular weight certificates before contract execution. Testing cost transfers upstream compress supplier margins.
- Food Manufacturers:Confectionery and dairy processors purchase standard-grade gelatin through established distributor networks. Volume contracts dominate procurement patterns.
- Research Institutions:Cell culture and biomedical research applications require low-endotoxin, high-clarity collagen with full origin documentation. Small batch sizes limit supplier interest.
Healthcare providers anchor premium volume. Cosmetic companies drive specification escalation.
Distribution Channel:
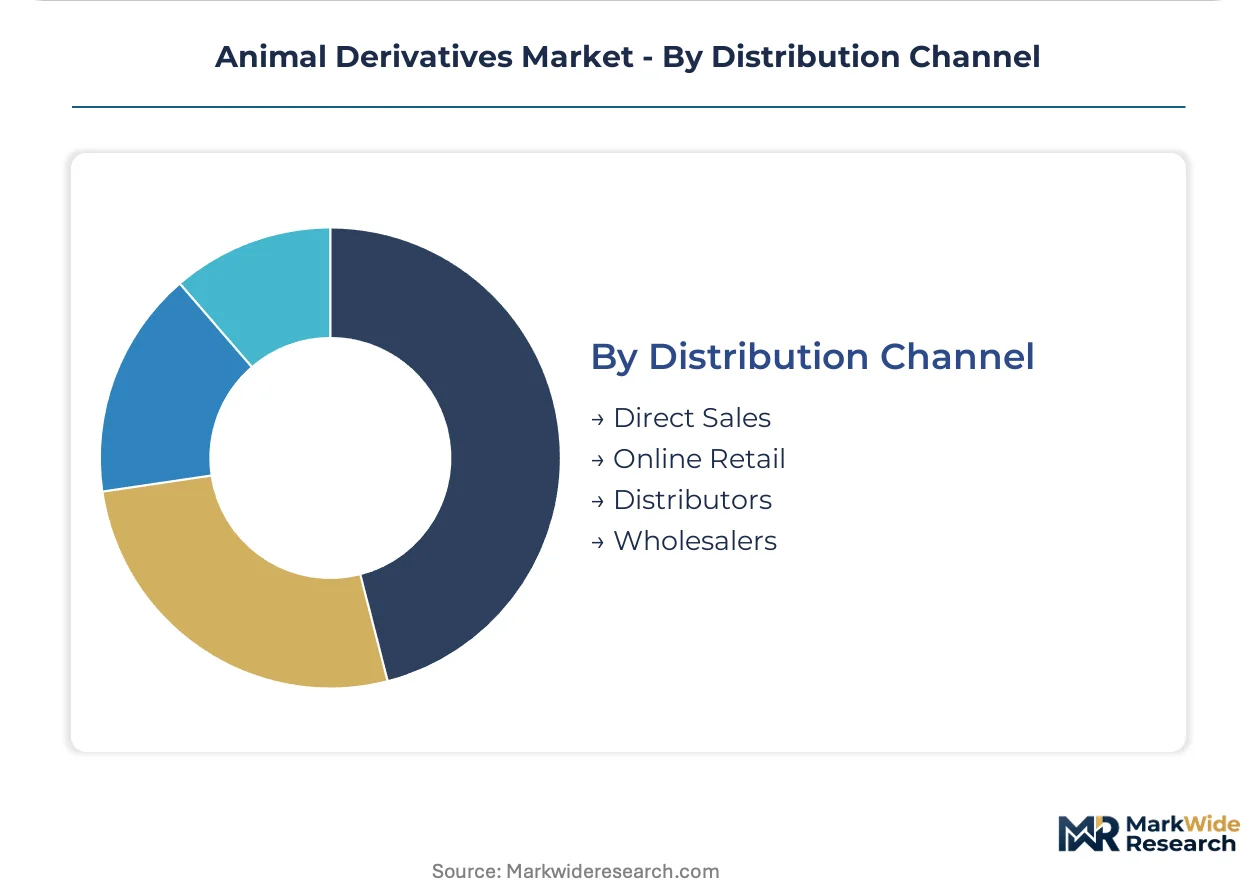
Channel selection tracks buyer scale and technical capability, with direct sales capturing pharmaceutical accounts and distributors serving fragmented food and cosmetic processors.
- Direct Sales:Pharmaceutical and large nutraceutical manufacturers negotiate multi-year supply agreements with rendering operations. Blockchain-enabled batch tracking satisfies ECHA documentation mandates.
- Distributors:Regional chemical and ingredient distributors aggregate demand from mid-sized food and cosmetic formulators. Inventory carrying costs concentrate in distributor networks.
- Wholesalers:Commodity gelatin for industrial applications moves through protein and rendering product wholesalers. Price transparency limits value-added service premiums.
- Online Retail:Small-scale cosmetic formulators and research laboratories source specialty collagen peptides through B2B platforms. Certificate verification delays constrain transaction velocity.
Direct sales dominate pharmaceutical value. Distributors retain food industry reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates nutraceutical manufacturing investment while Germany anchors pharmaceutical-grade gelatin certification standards, revealing how geography stratifies value capture across the animal derivatives supply chain.
China
Shandong and Guangdong provinces absorb the fastest capacity expansion for collagen peptide production serving skin health supplement brands. NMPA cosmetic ingredient filings now require sub-5 kDa molecular weight verification for absorption claims. Guangzhou manufacturing clusters transfer ISO 17025 testing costs upstream to derivative suppliers.
Germany
EMA pharmaceutical guidelines force 18-24 month qualification timelines for new gelatin suppliers to drug manufacturers. REACH substance registration mandates under ECHA tighten bovine-origin traceability to individual animal identification. Rendering operations near Frankfurt and Hamburg deploy blockchain-enabled batch tracking to satisfy decade-long record archive requirements.
United States
FDA biologics regulations and USDA FSIS inspection protocols segment quality tiers for cross-border pharmaceutical shipments. Cargill leverages integrated protein-to-derivatives infrastructure across Midwest feedstock zones. Darling Ingredients anchors specialized rendering and grease recovery operations sustaining margin density in lower-volume product lines.
India
BIS certification standards for imported animal derivatives create first-mover advantage for compliant suppliers establishing local blending operations. CDSCO pharmaceutical-grade documentation requirements extend approval timelines for novel collagen sources. Maharashtra and Gujarat cosmetic manufacturing clusters demand accredited third-party molecular weight certificates before contract execution.
South Korea
MFDS cosmetic ingredient regulations drive specification escalation for collagen peptide molecular weight distribution verification. Seoul and Busan skincare manufacturing clusters adopt enzymatic hydrolysis systems with real-time monitoring fastest among Asian markets. Brand owners transfer ISO 17025 testing costs upstream, compressing supplier margins for premium positioning.
Animal Derivatives Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-grade certification entrenching incumbent positions while nutraceutical channels fragment around regional peptide suppliers. The vendor base concentrates around three strategic archetypes: integrated protein processors with captive rendering infrastructure, specialized gelatin manufacturers with EMA-qualified production lines, and regional collagen peptide specialists serving cosmetic formulators. Competitive dynamics center on backward integration into slaughterhouse sourcing and enzymatic processing technology licensing.
Within the integrated infrastructure tier, Cargill and Tyson Foods exemplify North American protein processors leveraging feedstock proximity. Rousselot and Gelita occupy positions as European pharmaceutical-grade specialists with EMA-qualification depth. Darling Ingredients anchors the specialized rendering archetype through grease recovery and lower-volume product line focus.
| Leading Market Players |
|---|
| Cargill |
| Tyson Foods |
| Darling Ingredients |
| JBS |
| Archer Daniels Midland |
| Rousselot |
| Gelita |
| Kerry Group |
| Glanbia |
| Others |
Value Chain & Pricing Dynamics
Enzymatic hydrolysis systems with real-time molecular weight monitoring are compressing production costs while concentrating margin capture among integrated biorefinery operators in Germany and China. This technology shift simultaneously reduces batch rejection rates and raises capital barriers for standalone renderers without multi-grade certification capabilities.
Pricing Analysis
Capacity additions in China's Shandong province are reshaping price floors for standard-grade collagen peptides while pharmaceutical-grade gelatin premiums widen in Europe. Three-tier pricing structure across pharmaceutical, nutraceutical, and food-industrial levels segments buyers by certification burden. Cost compression in food-grade channels stems from enzymatic processing standardization. Food manufacturers exhibit highest price sensitivity; pharmaceutical drug delivery matrix buyers accept premium positioning for EMA-qualified supply.
Supply Chain Analysis
Bovine and poultry slaughter volumes rest on feedstock availability across the United States, Brazil, and Australia. Raw material dependencies center on cattle hide collection networks, poultry by-product aggregation, and specialized grease recovery operations. Single-source vulnerability concentrates in pharmaceutical-grade gelatin where EMA qualification timelines extend to 18-24 months. Distribution runs through direct sales agreements for pharmaceutical accounts and regional chemical distributors serving fragmented cosmetic formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Animal derivatives function as a stable compounder anchored by irreversible pharmaceutical formulation lock-in for gelatin encapsulation. Nutraceutical peptide demand adds cyclical growth optionality without threatening baseline margin structures.
For Market Incumbents: Anchor EMA-qualified production capacity through blockchain-enabled batch tracking that satisfies REACH decade-long archive mandates. Defend against plant-based collagen substitutes by accelerating sub-5 kDa peptide certification for absorption claims. Prioritize backward integration into slaughterhouse sourcing to control species-origin documentation costs. For New Entrants and Emerging Players: EU Green Deal bioplastics mandates open a window for keratin-derived biopolymer development in packaging films. Target India's BIS certification gap for imported animal derivatives by establishing local blending operations in Maharashtra. Pursue white-label peptide supply agreements with South Korean skincare manufacturers demanding ISO 17025 molecular weight verification. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized rendering operators with grease recovery expertise but limited pharmaceutical-grade certification. Five-to-ten year viability hinges on enzymatic processing technology licensing positions. Watch ECHA substance restriction updates as inflection triggers for consolidation toward vertically integrated protein processors.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Hydrolysis Technology Licensing | Enables sub-5 kDa collagen peptide production for nutraceutical absorption claims in South Korea. |
| Blockchain-Enabled Batch Tracking Deployment | Satisfies ECHA decade-long record archive requirements for bovine-origin traceability in Germany. |
| Pharmaceutical-Grade Certification Investment | Entrenches supplier position through EMA's 18-24 month qualification timelines for novel gelatin sources. |
| Backward Integration into Slaughterhouse Sourcing | Captures margin density and controls species-origin documentation for FDA biologics compliance. |
| Local Blending Operations in India | Exploits BIS certification standards creating first-mover advantage for compliant imported derivative suppliers. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement covered rendering facility operators, pharmaceutical procurement managers at German drug manufacturers, nutraceutical formulators in China's Shandong province, and cosmetic R&D directors in South Korea's Seoul cluster. Secondary validation drew from ECHA substance registration databases, FDA biologics guidance documents, NMPA cosmetic ingredient filings, and customs trade records for collagen peptide imports. Bottom-up capacity modeling triangulated against top-down demand aggregation across application segments.
Historical reference periods anchored projections across the analysis window through verified production capacity and consumption patterns. Segmentation dimensions modeled include product type, certification grade tier, end-use application, and regional regulatory cluster. CAGRs derived from slope-consistency checks against feedstock availability forecasts and pharmaceutical formulation growth trajectories. Industry-specific inputs incorporated enzymatic processing yield improvements and EMA qualification timeline distributions.
Revisions become necessary when livestock disease outbreaks contract feedstock supply, ECHA tightens bovine-origin traceability mandates, or plant-based microbial fermentation achieves cost parity in cosmetic applications. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Uncaria Tomentosa Market
Agriculture and Agri Products
Ginseng Market
Agriculture and Agri Products
US Residential Organic Compost Market
Agriculture and Agri Products
Non GMO Soybean Market
Agriculture and Agri Products
Cassava Starch Market
Agriculture and Agri Products
Taro Market
Agriculture and Agri Products
Sugar Cane Market
Agriculture and Agri Products
Alfalfa Market
Agriculture and Agri Products
Argentina Agriculture Market
Agriculture and Agri Products
Global Coco Peat Market
Agriculture and Agri Products
Organic Soymeal Market
Agriculture and Agri Products
Faba Beans Flour Market
Agriculture and Agri Products
Tarragon Market
Agriculture and Agri Products
GCC Poultry Meat Market
Agriculture and Agri Products
North America Alfalfa Hay Market
Agriculture and Agri Products
Marine Algae Market