
 Alfalfa Pellets Market | 2026-2036
Alfalfa Pellets Market Size, Share, and Industry Trends Forecast 2026-2036
Alfalfa Pellets Market Analysis
The widening protein content gap between premium certified-organic lots and commodity-grade alfalfa pellets is repositioning procurement strategies across the value chain. Standlee Premium Products LLC leverages vertical integration from Idaho growing operations to controlled dehydration, sustaining quality premiums through batch-traceable supply chains. Anderson Hay & Grain Co Inc anchors its position in Pacific Northwest dairy contracts, while ACX Global competes on export logistics to Asian livestock markets.
Alfalfa pellets are compressed forage products manufactured from dried Medicago sativa, typically containing 15-22% crude protein and 25-30% fiber by dry weight, serving as standardized nutrition inputs for ruminant and monogastric livestock operations. Conventional pellets dominate volume flows through agricultural supply stores and wholesale channels, while organic pellets command margin premiums among certified dairy operations subject to USDA National Organic Program feed requirements. Dehydrated pellets retain higher carotene and vitamin E levels than sun-cured alternatives, positioning this sub-category for equestrian and specialty pet food applications where nutrient density justifies price spreads.
USDA grading standards for alfalfa hay and pellet products shape quality benchmarks that determine contract eligibility for federal dairy support programs. EPA manure management regulations in concentrated animal feeding operations indirectly drive pellet adoption by enabling precise ration formulation that reduces nitrogen excretion. Stakeholders must monitor evolving FDA feed safety rules under the Food Safety Modernization Act and state-level agricultural extension guidance on forage substitution rates to anticipate procurement cost shifts.
Market Dynamics
USDA nutrient disclosure mandates for grazing operations are compressing informal hay trading into standardized pellet procurement, forcing dairy cooperatives to document protein consistency through certified supply chains rather than visual inspection.
Growth Catalysts
- EPA Manure Management Rules:Concentrated animal feeding operations in the United States adopt precision rationing with alfalfa pellets to reduce nitrogen excretion and comply with discharge permits.
- Organic Certification Thresholds:USDA National Organic Program feed requirements pull certified dairy operations toward traceable pellet sources with verified non-GMO status.
- Dehydration Technology:Controlled thermal processing preserves carotene and vitamin E levels, opening premium positioning in equestrian nutrition and specialty pet food formulations.
Market Restraints
- Input Cost Volatility:Diesel prices and natural gas rates for dehydration create margin pressure on pellet processors during harvest compression windows.
- Geographic Supply Concentration:Idaho and California Central Valley growing regions concentrate 60% of US dehydrated pellet capacity, exposing buyers to regional drought risk.
- Sun-Cured Substitution:Lower-cost sun-cured hay retains price-sensitive livestock feeder demand in beef cattle backgrounding operations.
Strategic Opportunities
- Asian Export Logistics:Containerized pellet shipments to Japanese and South Korean dairy operations bypass domestic commodity price ceilings.
- Precision Fermentation Integration:Hybrid rations combining alfalfa fiber with microbial protein address monogastric feed trials in poultry research stations.
- Veterinary Channel Expansion:Equine clinics and reproduction centers source nutrient-dense pellets for broodmare conditioning programs.
Industry Challenges
- Batch-Traceability Systems:Field-to-pellet documentation requires RFID integration and laboratory testing infrastructure that mid-scale processors lack.
- Organic Certification Timelines:Three-year land conversion periods and annual inspector audits delay entry into premium dairy contract pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alfalfa Pellets Market |
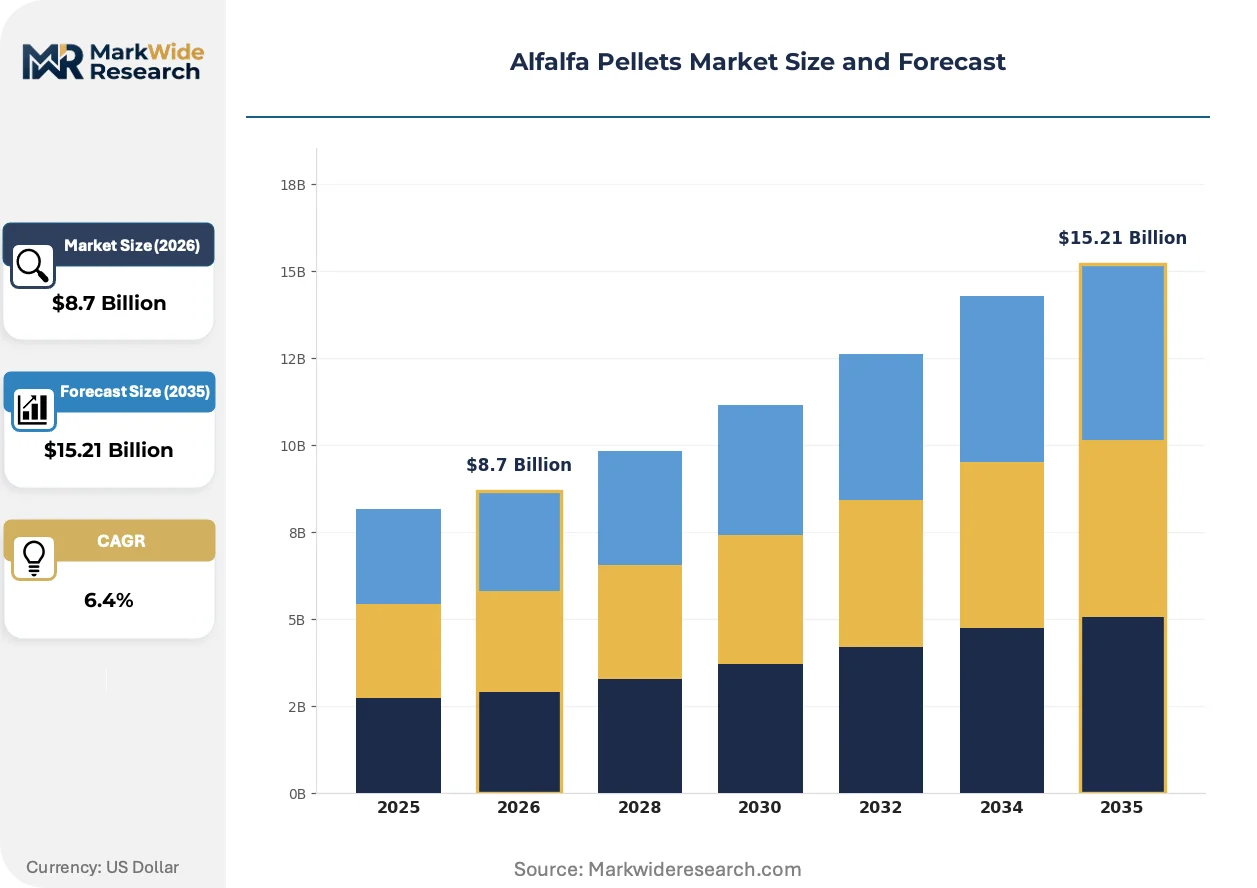
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Pellets, Conventional Pellets, Dehydrated Pellets, Compressed Pellets Application: Animal Feed, Livestock Feeding, Equestrian Use, Pet Food End User: Dairy Farmers, Poultry Farmers, Horse Owners, Pet Owners Distribution Channel: Online Retail, Specialty Stores, Agricultural Supply Stores, Wholesale |
| Companies Covered | Bailey Farms Inc, Green Prairie International Inc, Anderson Hay & Grain Co Inc, Sacate Pellet Mills, Border Valley Trading, Standlee Premium Products LLC, Alfalfa Monegros SL, Alfalfa Supply Inc, ACX Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alfalfa Pellets Market Emerging Trajectories
Automation in dehydration facilities and digital procurement platforms are compressing the traditional hay broker layer, while regulatory traceability requirements force technology adoption across previously manual supply chains.
Steam-conditioning extrusion is consolidating fragmented regional processing into centralized facilities with continuous-flow thermal control. Large-scale dairy cooperatives in California and Idaho specify extruded pellets for total mixed ration consistency. This thermal precision is consolidating quality variance into narrower protein bands that satisfy USDA grading contracts.
EPA enforcement of Clean Water Act discharge permits tightens nitrogen management in concentrated animal feeding operations. Dairy operations respond by substituting pelleted forage for fresh-cut hay to enable precise ration formulation. Midwest feedlot operators now face similar pressure as regional water quality districts extend nutrient management rules.
Direct contracting between dairy cooperatives and dehydration plants displaces agricultural supply store intermediaries. Large herds in California's Central Valley negotiate annual volume agreements with named protein specifications. This disintermediation is most visible in organic-certified operations where batch documentation requirements exceed distributor capabilities.
Alfalfa Pellets Market Segmentation
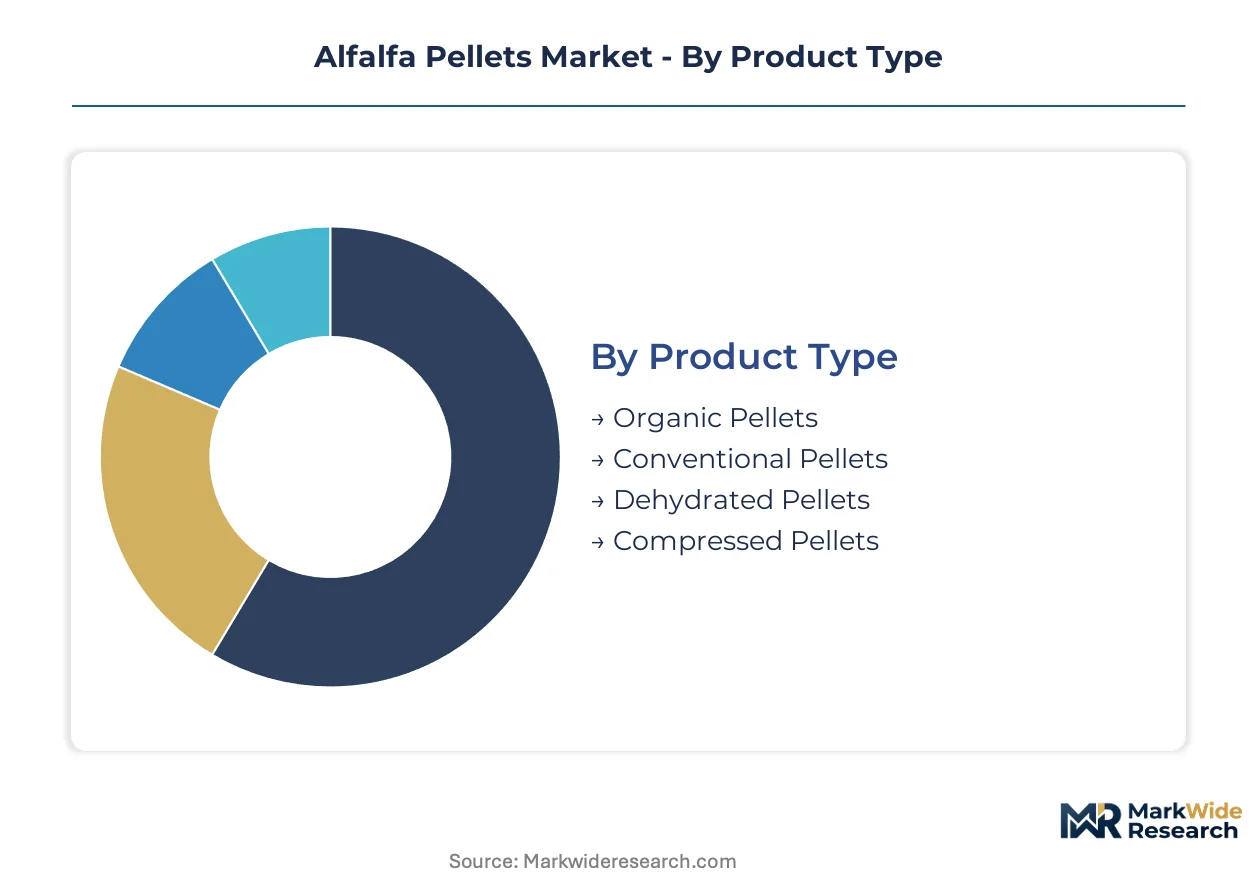
Alfalfa pellet segmentation reflects divergent certification burdens across the value chain. USDA National Organic Program compliance separates premium supply pools from commodity channels, while dehydration technology tiers determine eligibility for export and specialty nutrition contracts.
Product Type:
USDA National Organic Program certification requirements split this category into traceable supply chains with multi-year land conversion timelines and conventional alternatives with minimal documentation overhead.
- Organic Pellets:Certified organic pellets require three-year land conversion and annual inspector audits under USDA National Organic Program standards. California Central Valley dairy cooperatives source these for premium milk contracts where non-GMO verification commands price premiums.
- Conventional Pellets:Standard-grade pellets dominate volume flows through agricultural supply stores and wholesale channels. Midwest beef cattle backgrounding operations absorb the majority of this output where price sensitivity outweighs certification requirements.
- Dehydrated Pellets:Controlled thermal processing preserves carotene and vitamin E levels for equestrian and specialty pet food applications. Idaho processing clusters supply Japanese and South Korean export markets where nutrient density specifications exceed domestic thresholds.
- Compressed Pellets:Mechanical compression without thermal treatment offers lower-cost forage standardization for domestic livestock feeders. Sun-cured raw material inputs reduce energy costs but limit shelf stability and export eligibility.
Conventional pellets sit at the top of the volume ranking, with dehydrated pellets climbing the fastest.
Application:
End-use specifications determine protein band requirements and batch-traceability intensity, with dairy and export channels demanding narrowest variance.
- Animal Feed:Standardized ruminant nutrition inputs require 15-22% crude protein consistency for total mixed ration formulation. EPA manure management regulations in concentrated animal feeding operations drive precision rationing adoption.
- Livestock Feeding:Broader category encompassing beef cattle backgrounding and small ruminant operations. Price-sensitive demand concentrates in agricultural supply store channels with minimal documentation requirements.
- Equestrian Use:Nutrient-dense pellets target broodmare conditioning and performance horse maintenance. Veterinary clinics and reproduction centers specify dehydrated lots with elevated vitamin E retention.
- Pet Food:Specialty formulations for small companion animals require contaminant screening and packaging standards exceeding agricultural grades. Premium positioning justifies price spreads over conventional feed applications.
Animal feed captures the largest volume share, while pet food applications expand most quickly.
End User:
Scale and certification sophistication separate procurement patterns, with large operations bypassing intermediaries through direct plant contracts.
- Dairy Farmers:Large-scale operations in California and Idaho negotiate annual volume agreements with named protein specifications. USDA grazing standards tighten nutrient disclosure requirements, forcing documented pellet procurement over informal hay trading.
- Poultry Farmers:Monogastric feed trials explore hybrid rations combining alfalfa fiber with microbial protein. Research station partnerships drive experimental demand distinct from established ruminant channels.
- Horse Owners:Individual and small-commercial operations source through veterinary channels and specialty retailers. Broodmare conditioning programs prioritize carotene-retentive dehydrated pellets.
- Pet Owners:Urban consumers access products through online retail and pet specialty chains. Packaging and branding requirements separate this channel from agricultural distribution.
Dairy farmers anchor procurement volume, with poultry farmers gaining share fastest.
Distribution Channel:
Channel selection reflects batch-traceability requirements and scale economics, with direct contracting displacing traditional intermediaries in certified segments.
- Online Retail:E-commerce platforms serve dispersed pet owners and small-scale horse operations with packaged consumer formats. Digital procurement compresses traditional hay broker layers.
- Specialty Stores:Equine clinics and pet retailers stock premium dehydrated pellets with nutrient density positioning. Veterinary channel relationships drive repeat purchasing.
- Agricultural Supply Stores:Regional distributors serve conventional livestock feeders with commodity-grade inventory. Price competition and service relationships dominate procurement decisions.
- Wholesale:Volume aggregators supply beef cattle backgrounding operations and smaller dairy herds. Geographic concentration in Midwest and Plains states matches production location.
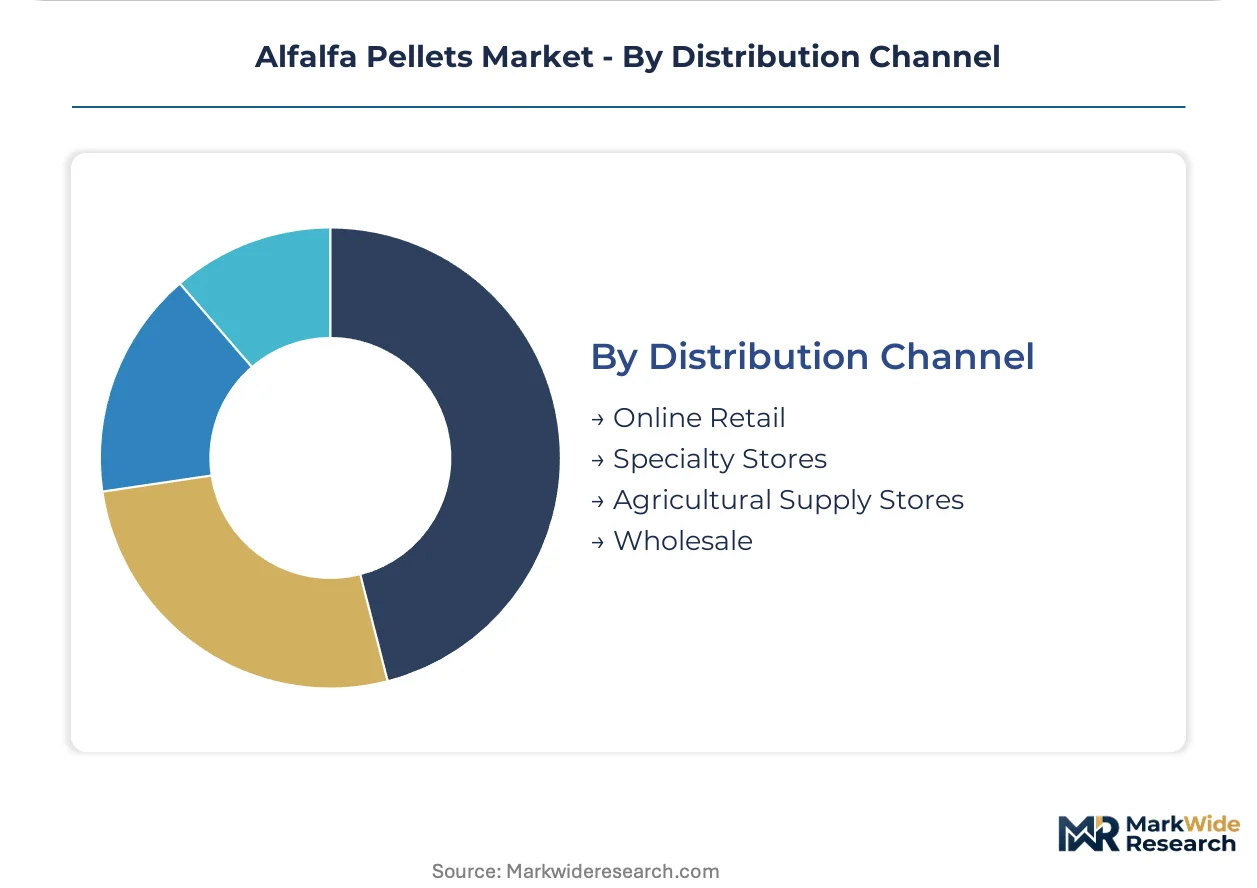
Agricultural supply stores maintain volume leadership, with online retail channels expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Idaho's dehydration plant workforce anchors North American pellet manufacturing, with California's Central Valley dairy operators driving procurement volume. Geographic concentration in these two states shapes supply security calculations for buyers.
United States
USDA grazing standards tighten nutrient disclosure requirements for dairy operations, compressing informal hay trading into certified pellet procurement. EPA Clean Water Act discharge permits force concentrated animal feeding operations toward precision rationing. Idaho processing clusters supply dehydrated pellets to California's Central Valley, where large-scale dairies negotiate annual volume agreements with named protein specifications.
Spain
Alfalfa Monegros SL exemplifies the Aragon region's sun-cured pellet production for Mediterranean livestock feeders. The country's national agricultural regulator enforces feed safety standards under EU hygiene regulations. The Ebro Valley concentration serves domestic ruminant operations and North African export channels with lower-cost mechanical compression alternatives.
Japan
Japanese dairy cooperatives source nutrient-dense dehydrated pellets for protein consistency in total mixed rations. METI import standards enforce contaminant screening and packaging specifications exceeding domestic US thresholds. Containerized shipments from Idaho and California bypass Japanese commodity price ceilings through direct plant-to-cooperative contracting.
South Korea
Korean livestock operations import dehydrated pellets to meet dairy sector protein specifications. The Ministry of Agriculture, Food and Rural Affairs enforces feed safety registration requirements for imported forage products. Busan-Ulsan port logistics clusters handle containerized pellet volumes from North American dehydration plants.
Canada
Alberta and Saskatchewan beef cattle backgrounding operations absorb conventional pellets through agricultural supply store channels. Health Canada feed regulations align with FDA safety standards under USMCA integration. Prairie province growing regions supply sun-cured inputs to domestic pellet processors serving price-sensitive livestock feeders.
Alfalfa Pellets Market Vendor Landscape
Capital-heavy dehydration plant operators compete with asset-light trading houses in a bifurcated structure. The vendor base splits between integrated processors controlling Idaho and California growing operations and regional distributors aggregating sun-cured volumes. Three archetypes dominate: vertically integrated quality specialists, export-logistics platforms, and commodity-grade regional aggregators. Competitive moves concentrate on backward integration into captive hay supply and direct contracting displacement of agricultural supply store intermediaries.
Within the integrated processor tier, Standlee Premium Products LLC and Anderson Hay & Grain Co Inc exemplify archetypes of quality-premium positioning and dairy contract anchoring respectively. ACX Global occupies the export-logistics specialist position. Bailey Farms Inc and Green Prairie International Inc represent regional trading houses competing on geographic coverage rather than processing asset ownership. Sacate Pellet Mills and Border Valley Trading sit within the mechanical compression segment serving price-sensitive domestic channels. Alfalfa Supply Inc anchors the agricultural supply store distribution layer being displaced by direct contracting trends.
| Leading Market Players |
|---|
| Bailey Farms Inc |
| Green Prairie International Inc |
| Anderson Hay & Grain Co Inc |
| Sacate Pellet Mills |
| Border Valley Trading |
| Standlee Premium Products LLC |
| Alfalfa Monegros SL |
| Alfalfa Supply Inc |
| ACX Global |
| Others |
Supply Flow & Price Mechanics
Natural gas rates for dehydration plants in Idaho and California flow through three distinct pricing tiers downstream, with energy-intensive processing costs separating premium dehydrated pellets from sun-cured mechanical compression alternatives in dairy contract negotiations.
Pricing Analysis
Certified organic pellets bundle three-year land conversion documentation and annual USDA inspector audits into per-ton premiums, while conventional grades trade on spot protein specifications without traceability overhead. Price differentiation hinges on certification tier and dehydration technology, with EPA discharge permit compliance intensifying cost compression in the conventional segment. Large-scale California Central Valley dairies exhibit lowest price sensitivity due to federal program eligibility requirements, whereas Midwest beef cattle backgrounding operations drive aggressive procurement of sun-cured alternatives.
Supply Chain Analysis
Alfalfa hay supply rests on Idaho and California Central Valley growing regions that concentrate sixty percent of domestic dehydrated pellet capacity, with diesel-dependent harvest logistics and natural gas-powered thermal processing as critical cost inputs. Single-source vulnerability concentrates in the Ebro Valley for Mediterranean sun-cured alternatives and the Idaho-California corridor for premium dehydration. Distribution runs through direct plant-to-cooperative contracting that displaces agricultural supply store intermediaries in certified organic channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Alfalfa Pellets Market functions as a regulatory compounder where USDA National Organic Program feed requirements and EPA Clean Water Act discharge mandates continuously tighten procurement specifications, converting compliance burdens into structural demand for documented supply chains.
For Market Incumbents: Cement position through backward integration into captive hay supply in Idaho growing regions and direct contracting displacement of wholesale distributors. Batch-traceability RFID infrastructure and in-house laboratory testing capacity defend against emerging dehydration technology entrants from the mechanical compression segment. Three-year organic certification timelines create moats that mid-scale processors cannot replicate quickly.
For New Entrants and Emerging Players: Small-scale horse operations and dispersed pet owners represent underserved buyer archetypes with fragmented procurement through veterinary channels and online retail platforms. Precision fermentation hybrid ration trials at poultry research stations offer the most penetrable application expansion with minimal incumbent presence. Go-to-market execution should leverage e-commerce platform partnerships with nutrient density positioning rather than agricultural supply store penetration.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale dehydration processors lack capital for batch-traceability infrastructure required by California dairy cooperatives. Long-term viability favors vertically integrated operators controlling Idaho growing operations through named protein specification contracts. Watch METI import standard enforcement in Japan as inflection indicator for premium export channel expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hay Supply | Captive alfalfa production in Idaho insulates processors from drought-driven input cost volatility. |
| Batch-Traceability Infrastructure Investment | RFID field-to-pellet documentation satisfies USDA National Organic Program audit requirements for premium contracts. |
| Direct Plant-to-Cooperative Contracting | Annual volume agreements with California Central Valley dairies displace agricultural supply store intermediaries. |
| Export Logistics Platform Development | Containerized shipment capabilities to Japanese and South Korean ports bypass domestic commodity price ceilings. |
| Precision Fermentation Partnership | Hybrid ration trials combining alfalfa fiber with microbial protein open monogastric feed applications. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Dehydration plant managers, dairy cooperative procurement officers, agricultural supply store distributors, and veterinary channel specialists provided operational perspective. USDA enforcement guidance, EPA discharge permit databases, FDA feed safety rulemakings, and customs trade records supplied secondary triangulation against bottom-up volume estimates and top-down market sizing.
Granularity-level modeling distinguished organic certification status, dehydration technology tier, end-use application, and distribution channel across the projection horizon. CAGRs derived from segment-level volume trajectories weighted by protein specification intensity and regulatory compliance burden. Forecast inputs incorporated diesel price volatility assumptions for harvest logistics and natural gas rate projections for thermal processing economics.
Underlying measurement precision varies by segment; certified organic and dehydrated pellet categories carry tighter precision than conventional mechanical compression alternatives due to documented contract flows. Forecasts reflect assumptions about EPA enforcement continuity and USDA grazing standard implementation timelines. Material deviation in METI import standard revisions or California drought severity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Floriculture Market
Agriculture and Agri Products
Canada Animal Protein Market
Agriculture and Agri Products
Seaweed Market
Agriculture and Agri Products
Brazil Compound Feed Market
Agriculture and Agri Products
Africa Cashew Market
Agriculture and Agri Products
Europe Alfalfa Hay Market
Agriculture and Agri Products
Middle East Animal Protein Market
Agriculture and Agri Products
North America Animal Protein Market
Agriculture and Agri Products
Japan Compound Feed Market
Agriculture and Agri Products
Fish Feed Market
Agriculture and Agri Products
Netherlands Cashew Market
Agriculture and Agri Products
Forage Feed Market
Agriculture and Agri Products
Africa Olive Market
Agriculture and Agri Products
South Africa Agriculture Market
Agriculture and Agri Products
North America Eggs Market
Agriculture and Agri Products
Australia Lime Market