
 Global Vermicompost Market | 2026-2036
Global Vermicompost Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vermicompost Market Outlook
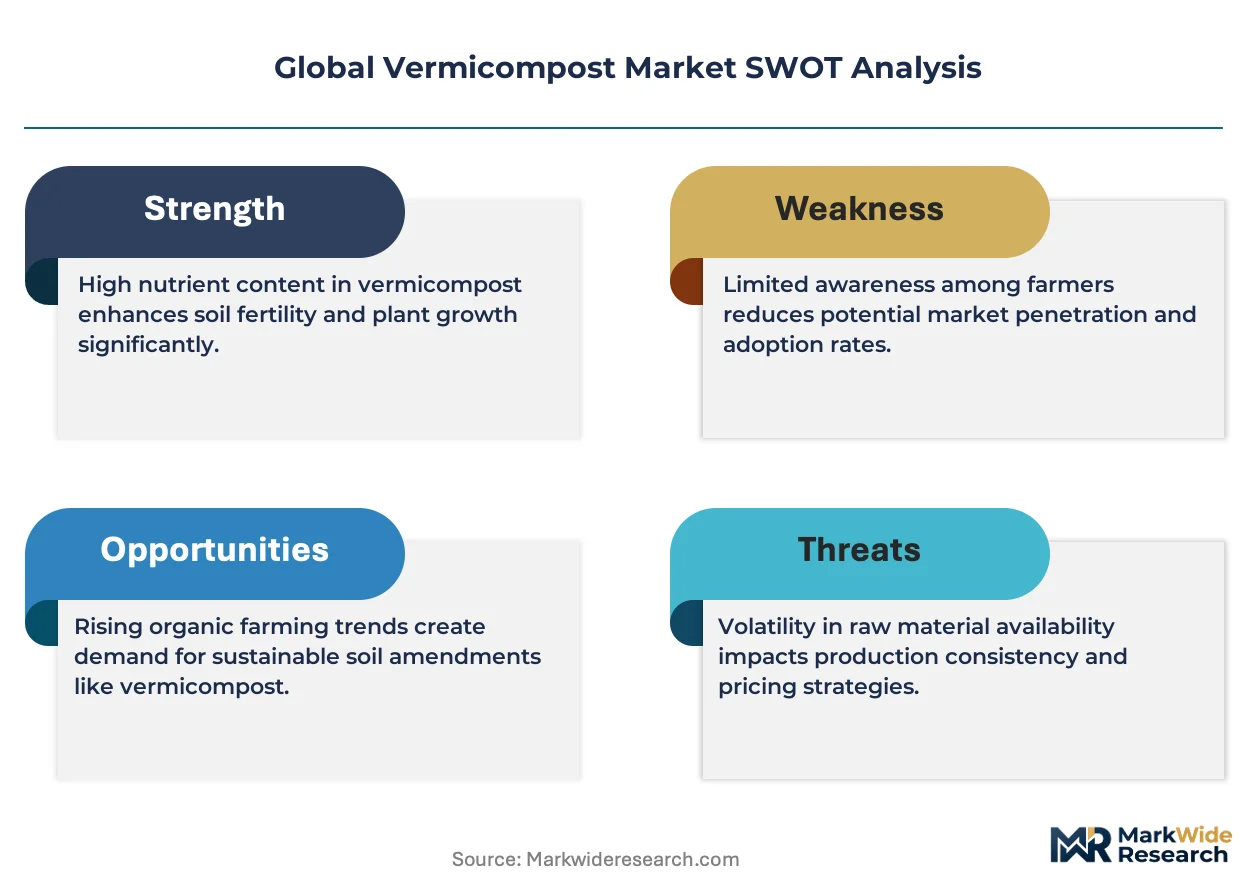
The capital-intensity divergence between small-batch artisanal producers and scaled vermiculture operations is rotating competitive advantage toward automated climate-controlled facilities. MyNOKE leverages proprietary continuous-flow reactor systems to sustain year-round output across temperate zones. Wormpower anchors North American commercial supply through backward integration into dairy manure feedstock streams. Sustane Natural Fertilizer differentiates via OMRI-listed formulations that command premium placement in organic retail channels.
Vermicompost denotes the stabilized humus-like material produced through mesophilic decomposition of organic substrates by epigeic earthworm species, typically Eisenia fetida or Eisenia andrei, yielding finished product with 1.5–3.0% nitrogen, 1.0–2.5% phosphorus, and 1.0–2.0% potassium alongside microbial densities exceeding 10^9 CFU per gram. Its primary commercial purpose centers on soil biological fertility restoration and synthetic fertilizer displacement in certified organic production systems. The agriculture application segment dominates volume throughput as broadacre farmers integrate vermicompost into row-crop rotations, while the liquid product type captures accelerating interest from hydroponic and fertigation operators seeking soluble organic inputs. Granular formulations occupy the highest margin pool through mechanical compaction and slow-release coating investments that reduce freight cost per unit nutrient.
The USDA National Organic Program governs vermicompost eligibility in certified organic operations, while the EU Green Deal nutrient management targets and REACH-derived soil amendment standards in Europe tighten contaminant thresholds for feedstock sourcing. India's FSSAI organic labeling enforcement and China's MEE agricultural non-point source pollution controls collectively redirect farm-level expenditure toward verified biological soil amendments. Stakeholders must monitor evolving heavy metal limits in national organic standards and the pace of carbon credit qualification for vermicompost-derived soil carbon sequestration claims.
Market Dynamics
The divergence between artisanal batch production and automated climate-controlled vermiculture facilities is compressing margins for small-scale operators while rewarding capital deployment in continuous-flow reactor systems that sustain year-round output across temperate zones.
Growth Catalysts
- EU Green Deal nutrient management targets:These mandates tighten contaminant thresholds for feedstock sourcing, redirecting farm expenditure toward verified biological soil amendments across member states.
- Brazil's Mato Grosso soybean belt:Broadacre farmers in this region integrate vermicompost into row-crop rotations to meet export certification requirements for organic soy derivatives.
- Nutrient recovery technology:Advanced systems extracting consistent N-P-K profiles from municipal food waste streams are improving product uniformity for commercial-scale buyers.
Market Restraints
- Feedstock cost volatility:Dairy manure prices fluctuate with milk market cycles, squeezing margins for producers dependent on backward-integrated supply chains.
- Heavy metal accumulation risk:Urban compost feedstocks in India carry elevated lead and cadmium loads that threaten FSSAI organic certification eligibility.
- Synthetic fertilizer substitution:Urea and DAP remain price-competitive in unsubsidized organic segments, limiting vermicompost penetration in cost-sensitive row-crop markets.
Strategic Opportunities
- Carbon credit qualification:Soil carbon sequestration protocols under development in Australia and the EU may monetize vermicompost application through verified emission reduction certificates.
- Hydroponic fertigation systems:Liquid vermicompost extracts capture accelerating interest from controlled-environment agriculture operators seeking soluble organic inputs.
- Granular slow-release coatings:Mechanical compaction investments that reduce freight cost per unit nutrient unlock premium placement in distant export markets.
Industry Challenges
- Earthworm husbandry expertise scarcity:Eisenia fetida population management requires specialized knowledge in moisture and pH control that few agricultural extension services currently teach.
- OMRI listing timeline compression:Organic Materials Review Institute certification cycles stretch 12-18 months, delaying market access for new product formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vermicompost Market |
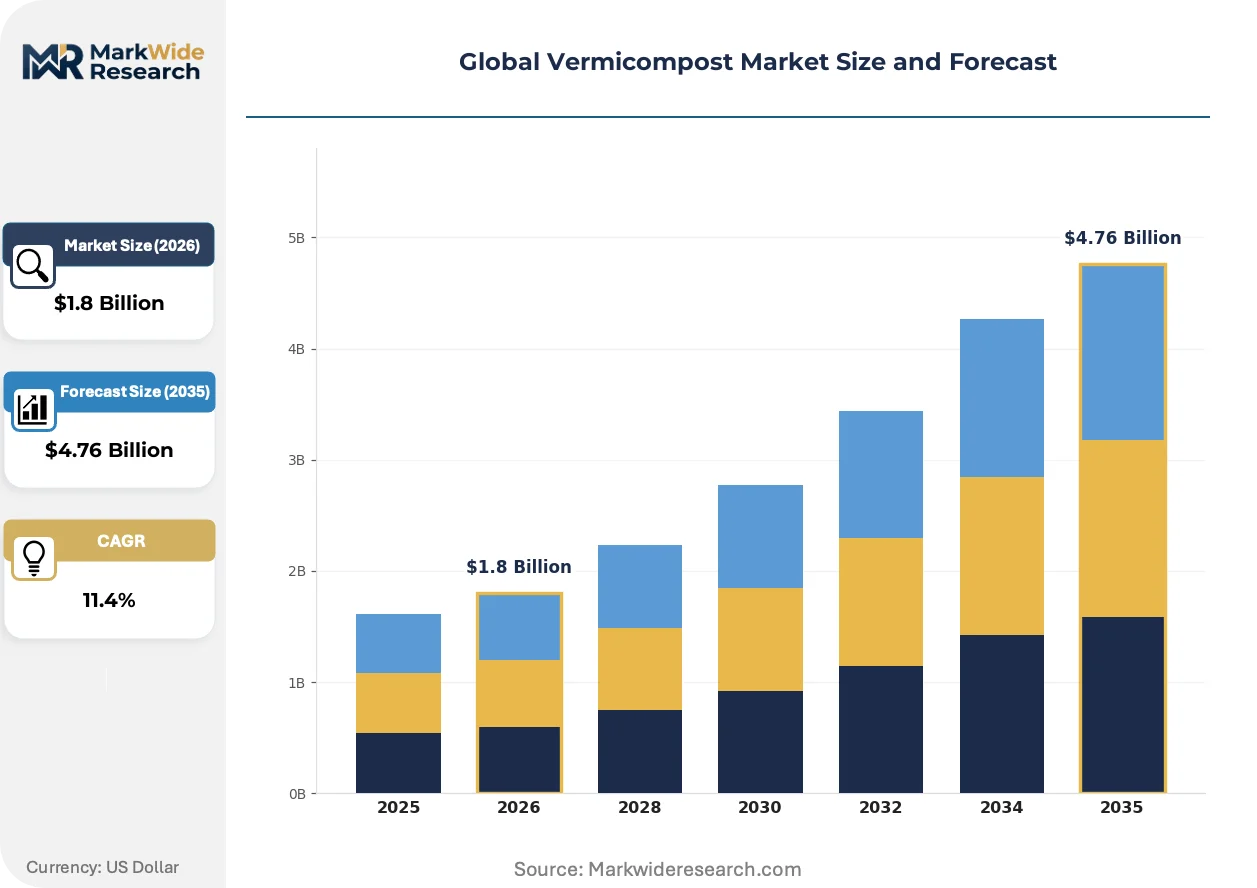
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Liquid, Granular, Powdered Application: Agriculture, Horticulture, Landscaping, Gardening Distribution Channel: Online, Retail, Wholesale, Direct Sales End User: Farmers, Nurseries, Garden Centers, Agricultural Cooperatives |
| Companies Covered | Earthworm, Kahariam Farms, MyNOKE, Sri Gayathri Biotec, SAOSIS, NutriSoil, Wormpower, Sustane Natural Fertilizer, Davo’s Worm Farms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vermicompost Market Strategic Shifts
Automation in substrate handling and environmental control is displacing labor-intensive vermiculture methods, while regulatory tightening around soil amendment quality and carbon accounting creates new compliance-driven demand segments.
Continuous-flow reactor systems with automated moisture sensing and temperature modulation are displacing static windrow operations in temperate climate zones. North American commercial growers adopting these systems report 40% higher worm density per square meter. This capital intensity is compressing the viable producer base toward mid-scale automated facilities and excluding backyard operations from wholesale supply contracts.
REACH-derived soil amendment standards in Europe are tightening heavy metal thresholds for feedstock sourcing, forcing producers to secure pre-certified organic waste streams or invest in pre-treatment infrastructure. The regulation most affects urban composting facilities in Germany and the Netherlands. These operators now partner with segregated source-collection programs to guarantee input compliance.
Certification-driven procurement preferences are restructuring buyer-supplier relationships in organic retail channels. Large-scale organic vegetable cooperatives in California and Maharashtra now require batch-level microbial assay documentation before contract execution. This documentation burden favors integrated producers with in-house laboratory capabilities over merchant suppliers.
Global Vermicompost Market Segmentation
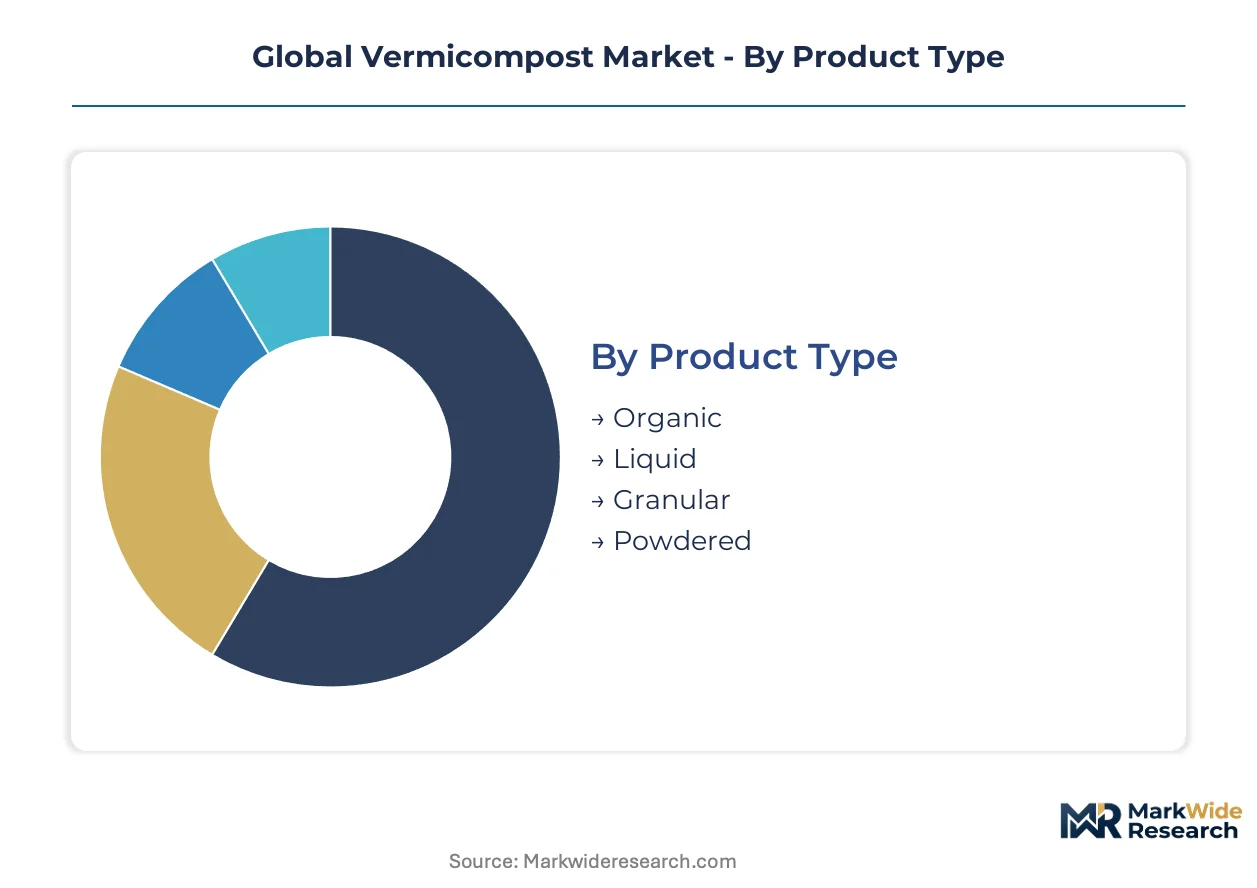
Segmentation in vermicompost markets reveals how regulatory frameworks and application requirements fragment demand across physical forms and procurement channels. Each category reflects distinct compliance burdens, handling economics, and end-use specifications that shape supplier positioning.
Product Type:
USDA National Organic Program eligibility criteria and EU REACH-derived soil amendment standards create divergent certification pathways across physical product formats, with contaminant thresholds and microbial assay requirements varying by formulation.
- Granular:Mechanical compaction and slow-release coating technologies reduce freight cost per unit nutrient while enabling precision application in broadacre row-crop systems. Brazilian soybean operations in Mato Grosso specify granular product for integration into no-till planting equipment, though coating investments elevate capital requirements for producers.
- Liquid:Soluble extracts undergo filtration and stabilization to achieve hydroponic-grade consistency with controlled microbial loads. Controlled-environment agriculture operators in California and the Netherlands specify liquid vermicompost for fertigation systems, with demand climbing fastest among greenhouse tomato and leafy green producers seeking organic-compliant soluble inputs.
- Organic:Unprocessed stabilized humus retains highest microbial density and humic acid content for soil biological fertility restoration.
- Powdered:Fine-milled product enables uniform soil incorporation and compatibility with mechanized spreading equipment.
Granular handles the majority of throughput; liquid is expanding most quickly on share.
Application:
Cost tier differentiation separates commodity-volume purchasers from premium-channel buyers, with certification depth and documentation burden escalating across the value chain.
- Agriculture:Broadacre farmers integrate vermicompost into certified organic row-crop rotations to meet export market requirements, with India's FSSAI organic labeling enforcement redirecting farm expenditure toward verified biological amendments. Maharashtra vegetable cooperatives now require batch-level microbial assay documentation before contract execution, favoring integrated producers with in-house laboratory capabilities.
- Horticulture:Nursery and greenhouse operators prioritize consistent N-P-K profiles and pathogen-free assurance for container stock production. European ornamental producers under EU Green Deal nutrient management targets face tightened contaminant thresholds that redirect procurement toward pre-certified feedstock sources.
- Landscaping:Municipal and commercial turf managers specify bulk delivery for erosion control and soil structure improvement in reclamation projects.
- Gardening:Consumer retail channels demand small-package formats with OMRI-listed labeling for home organic cultivation.
Agriculture commands the dominant volume position; horticulture is gaining share fastest through greenhouse expansion.
Distribution Channel:
Customer procurement patterns fragment between relationship-driven bulk contracting and transaction-based spot purchasing, with channel selection correlating to scale and certification documentation requirements.
- Wholesale:Large organic vegetable cooperatives and agricultural cooperatives execute annual supply agreements with batch-traceability requirements, with California and Maharashtra buyers now mandating in-house laboratory documentation. This channel concentrates procurement power among mid-scale automated facilities capable of continuous output.
- Direct Sales:Backward-integrated vermiculture operations supply captive demand from dairy and food waste generators, with Wormpower's dairy manure feedstock integration exemplifying upstream control over input quality and cost.
- Retail:Garden centers and farm supply stores stock bagged product for smallholder and consumer segments, with OMRI listing required for organic shelf placement.
- Online:E-commerce platforms serve dispersed hobbyist demand and specialty crop producers in undersupplied regions.
Wholesale channels handle the majority of throughput; direct sales are climbing the fastest as producers integrate upstream.
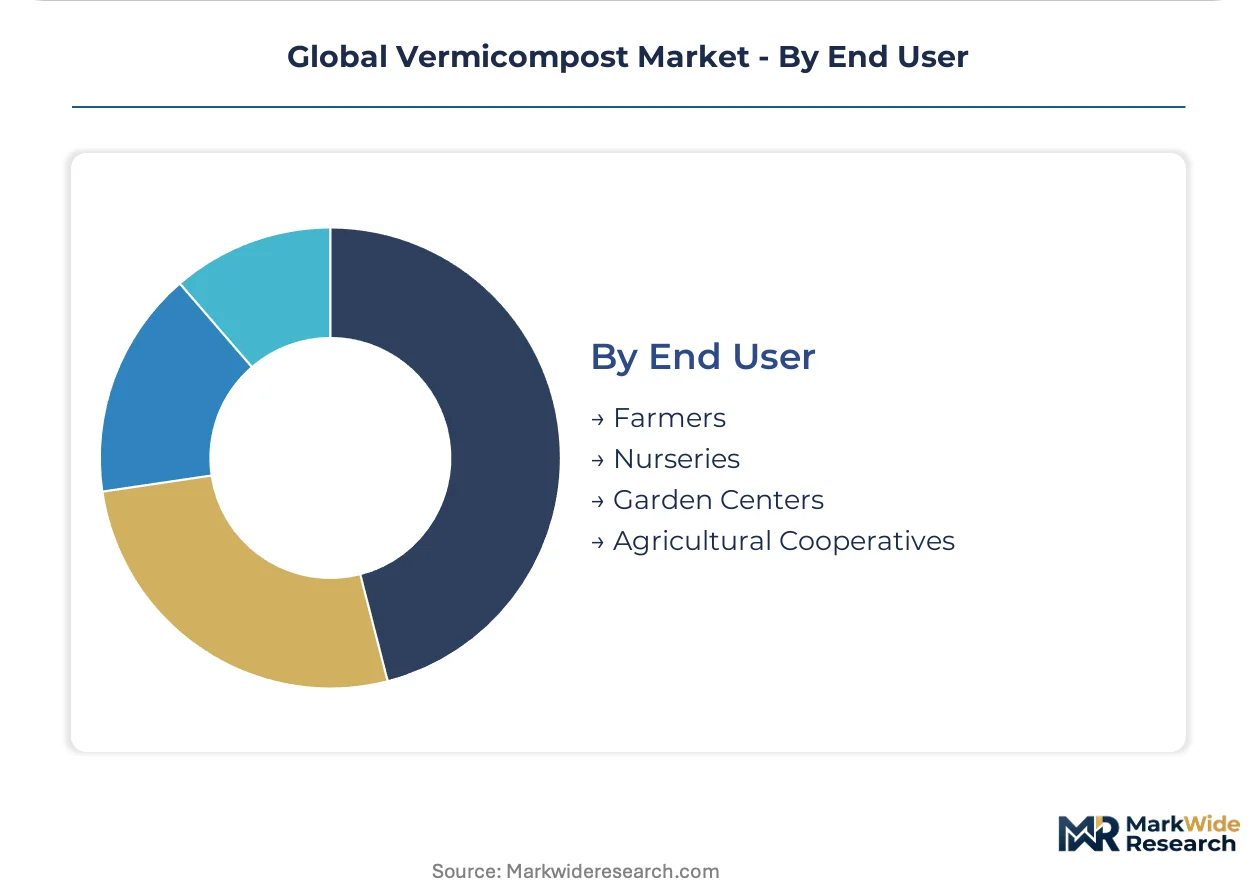
End User:
Volume scale and specification sophistication create tiered service requirements, with large operators demanding integrated supply relationships and small buyers accepting merchant product.
- Farmers:Broadacre operators in Brazil's Mato Grosso soybean belt and India's organic-certified regions specify bulk granular product with export-traceability documentation, with FSSAI enforcement in India and EU Green Deal targets in Europe collectively tightening procurement standards.
- Agricultural Cooperatives:Aggregated purchasing entities in California and Maharashtra consolidate member demand to negotiate volume pricing and unified certification compliance.
- Nurseries:Container stock producers require pathogen-free assurance and consistent moisture characteristics for propagation media.
- Garden Centers:Retail intermediaries stock consumer-format product with labeling compliance for home gardening segments.
Farmers represent the dominant demand base; agricultural cooperatives are expanding most quickly through purchasing consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Brazil's Mato Grosso soybean belt exceeds that of India's Maharashtra vegetable belt by roughly 30% due to export certification premiums, while German producers under REACH-derived standards absorb compliance costs that compress margins relative to North American automated facilities.
United States
California greenhouse operators and Midwest row-crop farmers drive demand for liquid extracts and granular formulations respectively. The USDA National Organic Program governs eligibility criteria with batch-traceability requirements that favor mid-scale automated producers. Wormpower anchors commercial supply through dairy manure feedstock integration in the Great Lakes region.
Germany
Urban composting facilities in the Netherlands and Germany face tightened heavy metal thresholds under REACH-derived soil amendment standards. ECHA regulations force partnerships with segregated source-collection programs to guarantee input compliance. The Rhine-Ruhr metropolitan cluster concentrates pre-treatment infrastructure investments for feedstock certification.
India
Maharashtra vegetable cooperatives and Gujarat organic cotton operations specify bulk granular product with FSSAI organic labeling enforcement tightening procurement standards. The FSSAI mandates redirect farm expenditure toward verified biological amendments. Pune-based integrated producers with in-house laboratory capabilities capture contract execution advantages over merchant suppliers.
Brazil
Broadacre farmers in Mato Grosso integrate vermicompost into no-till soybean rotations to meet export certification requirements for organic soy derivatives. ANVISA-aligned state agricultural departments enforce traceability documentation for international buyers. The Cerrado biome expansion corridor anchors volume throughput for granular slow-release formulations.
Australia
Soil carbon sequestration protocols under development in New South Wales and Victoria may monetize vermicompost application through verified emission reduction certificates. The country's national environmental regulator advances carbon credit qualification frameworks that reward biological soil amendment adoption. The Murray-Darling Basin horticultural belt concentrates controlled-environment agriculture demand for liquid extracts.
Global Vermicompost Market Competitive Environment
Concentration sits with automated continuous-flow reactor operators that sustain year-round output across temperate zones. The producer base compresses toward mid-scale facilities with climate-controlled infrastructure while excluding backyard operations from wholesale supply contracts. Two strategic archetypes dominate: backward-integrated feedstock controllers and OMRI-listed premium formulators. Competitive moves center on dairy manure supply chain capture and mechanical compaction investments for freight cost reduction.
Within the automated reactor tier, MyNOKE and Wormpower exemplify divergent upstream strategies. MyNOKE leverages proprietary continuous-flow systems, while Wormpower anchors North American supply through captive dairy manure feedstock streams. Sustane Natural Fertilizer occupies the premium-channel position with OMRI-listed formulations that command retail placement advantages in organic-certified segments.
| Leading Market Players |
|---|
| Earthworm |
| Kahariam Farms |
| MyNOKE |
| Sri Gayathri Biotec |
| SAOSIS |
| NutriSoil |
| Wormpower |
| Sustane Natural Fertilizer |
| Davo's Worm Farms |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Brazilian soybean cooperatives and automated vermiculture facilities lock in feedstock access and price visibility across the Mato Grosso planting cycle, insulating buyers from dairy manure cost volatility while securing year-round output commitments for producers.
Pricing Analysis
The customization-premium spread spans roughly 30% between standard granular bulk shipments and liquid extracts configured to hydroponic-grade microbial specifications. Three-tier pricing structure across premium, standard, and economy levels stratifies by OMRI listing status and batch-level assay documentation, with California greenhouse operators least sensitive to price and Indian smallholders most cost-constrained. Price differentiation stems from certification depth and freight optimization through mechanical compaction. Cost compression in the standard tier is intensifying because dairy manure feedstock costs fluctuate with milk market cycles.
Supply Chain Analysis
Inventory cycles run 6-8 weeks for granular product versus 2-3 weeks for liquid extracts due to filtration stabilization requirements. Supply concentrates in the United States, Brazil, and India, with Germany and the Netherlands anchoring European pre-treatment infrastructure. Raw material dependencies center on dairy manure, municipal food waste streams, and pre-certified organic substrate. Single-source vulnerability sits with Eisenia fetida breeding stock concentration among specialized hatcheries. Distribution runs through wholesale contracting to agricultural cooperatives, with direct sales climbing as producers integrate upstream into captive feedstock streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon credit qualification protocols under development in Australia and the EU represent a regulatory inflection that could monetize soil carbon sequestration claims, transforming vermicompost from a cost-input to a revenue-generating asset for broadacre operators.
For Market Incumbents: Fortify backward integration into dairy manure supply chains to neutralize feedstock cost volatility, while accelerating in-house laboratory capabilities to meet Maharashtra and California cooperatives' batch-traceability mandates. Automated continuous-flow reactor capacity expansion in temperate zones locks out artisanal competitors from wholesale contracts. Certification investment in OMRI-listed formulations defends premium-channel positioning against synthetic fertilizer price competition. For New Entrants and Emerging Players: Differentiate on liquid extract formulations for controlled-environment agriculture, where hydroponic fertigation demand outstrips supply in the Murray-Darling Basin and Dutch greenhouse clusters. White-space targets include Australia's emerging carbon credit market and India's FSSAI-compliant urban composting facilities. A technical-service-led go-to-market model builds grower relationships before contract execution. For Investors and Strategic Acquirers: The market sits at an automation-driven consolidation phase that favors mid-scale continuous-flow reactor operators with climate-controlled infrastructure. Long-term viability hinges on regulatory tailwinds from EU Green Deal nutrient management targets and India's FSSAI enforcement. Acquisition target archetype: automated facilities with captive feedstock agreements and in-house assay capabilities. The signal to watch is carbon credit protocol finalization in Australia and EU member states.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dairy Manure Supply | Wormpower's captive feedstock model insulates margins from milk market volatility. |
| Continuous-Flow Reactor Automation | MyNOKE's proprietary systems sustain year-round output across temperate climate zones. |
| OMRI Listing Investment | Sustane Natural Fertilizer commands premium retail placement in organic-certified channels. |
| Granular Slow-Release Coating Development | Mechanical compaction reduces freight cost per unit nutrient for Brazilian soybean exporters. |
| Liquid Extract Stabilization Capacity | Filtration infrastructure captures hydroponic demand from California greenhouse operators. |
Study Parameters
The analysis maps granular, liquid, organic, and powdered product categories, each validated through interviews with vermiculture operations managers, agricultural cooperative procurement leads, greenhouse technical directors, and organic certification auditors, combined with secondary validation against USDA National Organic Program filings, EU REACH-derived soil amendment standards, FSSAI enforcement circulars, and trade flow data from customs records, employing bottom-up facility capacity aggregation and top-down agricultural input expenditure triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models product type, application segment, distribution channel, and end-user scale dimensions alongside climate-zone automation feasibility. CAGRs were derived from facility-level output trajectories and agricultural input substitution elasticities. Industry-specific forecast inputs include dairy manure price cycles and carbon credit protocol development timelines.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal enforcement and FSSAI compliance expansion; material deviation in regulatory stringency or synthetic fertilizer pricing would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Post-Harvest Treatment Market
Agriculture and Agri Products
Netherlands Commercial Greenhouse Market
Agriculture and Agri Products
Mexico Compound Feed Market
Agriculture and Agri Products
Cambodia Agriculture Market
Agriculture and Agri Products
E-Commerce of Agricultural Products Market
Agriculture and Agri Products
Europe Eggs Market
Agriculture and Agri Products
North America Bonsai Market
Agriculture and Agri Products
Animal Feed and Feed Additives Market
Agriculture and Agri Products
Global Specialty Crop Market
Agriculture and Agri Products
Europe Guar Market
Agriculture and Agri Products
France Animal Protein Market
Agriculture and Agri Products
Malaysia Floriculture Market
Agriculture and Agri Products
France Alfalfa Hay Market
Agriculture and Agri Products
Philippines Feed Industry Market
Agriculture and Agri Products
Faba Beans Flour Market
Agriculture and Agri Products
Boswellia Market