
 Europe Feed Premix Market | 2026-2036
Europe Feed Premix Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Feed Premix Market Foresight
Precision fermentation and enzyme engineering is fragmenting traditional vitamin and amino acid sourcing pathways across European premix supply chains. Cargill Inc. leverages its integrated grain-to-premix infrastructure to control input costs across Benelux operations. Nutreco NV anchors its position through species-specific premix formulations for aquaculture and poultry. Evonik Industries AG differentiates via synthetic amino acid technologies that reduce nitrogen excretion in swine diets.
Feed premix denotes a homogeneous mixture of micronutrients—vitamins, minerals, amino acids, enzymes, and trace elements—blended at concentrations typically ranging from 0.5% to 3% of finished feed weight, designed for uniform dispersion into compound feeds to prevent nutritional deficiency or metabolic disorder in livestock. Poultry feed premix maintains the largest volume share across Europe, driven by broiler density in Poland and layer operations in Spain, while aquaculture feed premix represents the fastest-expanding category as salmon and trout producers in Norway and Scotland substitute marine ingredients with optimized micronutrient packages. Amino acid premixes command premium positioning due to lysine and methionine precision requirements in low-protein diet formulations mandated by EU environmental regulations.
EMA guidelines on veterinary medicinal products, REACH chemical registration requirements for feed additives, and EU Green Deal sustainability benchmarks collectively restrict antibiotic growth promoter use while elevating documentation burdens for novel enzyme and probiotic introductions. EFSA evaluates functional claims for digestive support and immune modulation premixes, creating a multi-year approval pathway that favors established players with dedicated regulatory affairs capacity. Stakeholders must monitor the interplay between national farm subsidy restructuring and feed cost pass-through mechanisms as protein autonomy targets reshape raw material sourcing economics.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing antibiotic use timelines while accelerating enzyme and probiotic premix incorporation across European compound feed supply chains. This regulatory compression is restructuring formulation priorities from growth promotion toward metabolic efficiency and nitrogen excretion reduction.
Growth Catalysts
- EU Green Deal antibiotic reduction mandates:Binding targets for antimicrobial use in livestock farming are forcing compound feed manufacturers to reformulate with functional additives that support gut health and immune modulation.
- Precision fermentation technologies:Engineered microbial platforms are enabling domestic production of high-purity amino acids and vitamins, reducing import dependency for critical micronutrient inputs.
- Netherlands livestock clustering density:Concentrated poultry and swine operations around Gelderland and North Brabant sustain premix consumption intensity through centralized feed mill demand and export-oriented production.
Market Restraints
- Phosphate and trace mineral price volatility:Feed-grade phosphate sourcing from Moroccan and Russian suppliers exposes premix manufacturers to input cost swings that compress margin stability.
- EFSA multi-year approval pathways:Novel enzyme and probiotic premixes face extended safety and efficacy evaluation timelines that delay commercialization and favor incumbents with established regulatory affairs infrastructure.
- Plant protein substitution limits:Low-protein diet formulations face amino acid balancing constraints that restrict complete removal of soybean meal from poultry and swine rations.
Strategic Opportunities
- Poland broiler production expansion:Rising poultry meat exports to Middle Eastern and African markets are driving demand for species-specific premix formulations optimized for rapid growth phases.
- EU protein autonomy targets:Domestic legume cultivation incentives under the Common Agricultural Policy are creating demand for amino acid premixes that balance reduced-soy diets.
- Digital feed formulation platforms:Real-time nutrient optimization software integration with premix dosing systems is enabling precision nutrition service models that extend supplier value capture beyond commodity sales.
Industry Challenges
- Enzyme stability in pelleting thermal stress:Maintaining activity of thermolabile phytases and carbohydrases through high-temperature feed processing requires coating technologies that add cost and complexity.
- Cross-border premix labeling harmonization:Divergent national implementations of EU feed additive regulations create compliance fragmentation for manufacturers supplying multiple member states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Feed Premix Market |
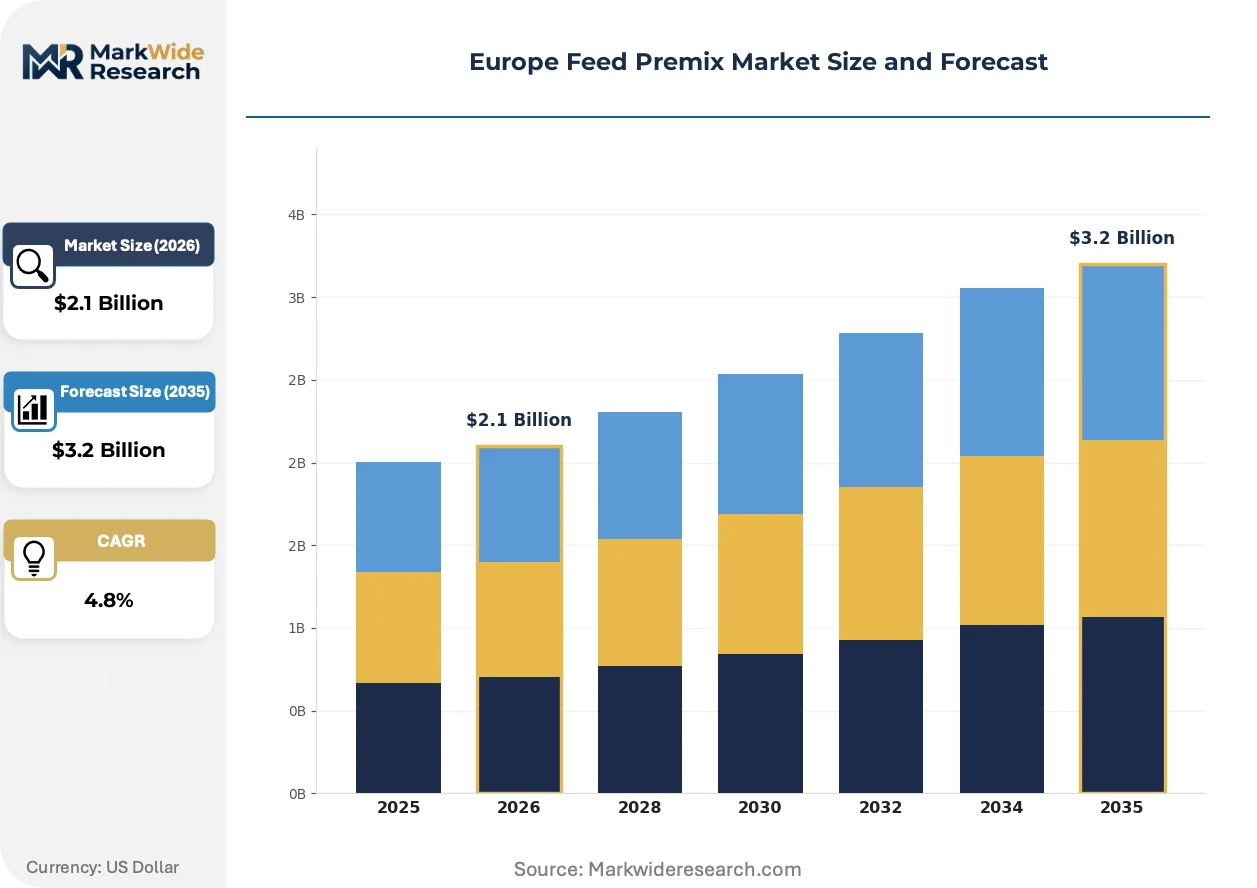
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Poultry Feed, Swine Feed, Ruminant Feed, Aquaculture Feed Additive Type: Vitamins, Minerals, Amino Acids, Enzymes Functionality: Nutritional, Therapeutic, Growth Promotion, Digestive Support Distribution Channel: Direct Sales, Retail, Distributors, Online Sales |
| Companies Covered | Cargill Inc., Archer-Daniels-Midland Co, Nutreco NV, De Heus Voeders BV, Koninklijke DSM NV, Agrifirm Group BV, Danish Agro AMBA, Kemin Industries Inc, Evonik Industries AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Feed Premix Market Shifts & Advancements
Digital integration and biological engineering are converging to transform how micronutrients are formulated, dosed, and verified across European livestock operations. These shifts are compressing traditional premix value chains while opening new service-based revenue models.
Near-infrared spectroscopy coupled with cloud-based nutrient databases is digitizing real-time premix quality verification at feed mill intake points. Major poultry integrators in Spain and France are deploying these systems to reduce analytical laboratory dependency and accelerate batch release decisions. The technology is digitizing quality assurance workflows that previously required centralized lab infrastructure.
REACH chemical registration requirements for novel feed additives are tightening substance documentation burdens while extending approval timelines for enzyme and probiotic innovations. Manufacturers must now generate extensive toxicological and environmental fate data before market entry. Aquaculture premix suppliers targeting Norwegian salmon farms are most affected, as marine ingredient substitution pressures collide with extended regulatory gatekeeping.
Consolidated livestock integrators are unbundling premix procurement from compound feed supply contracts to negotiate direct micronutrient sourcing. This disintermediation is compressing traditional premix distributor margins while rewarding suppliers with technical service capabilities. The shift is most visible in Germany, where vertically coordinated pork production systems are centralizing nutritional decision-making at headquarters level.
Europe Feed Premix Market Segmentation
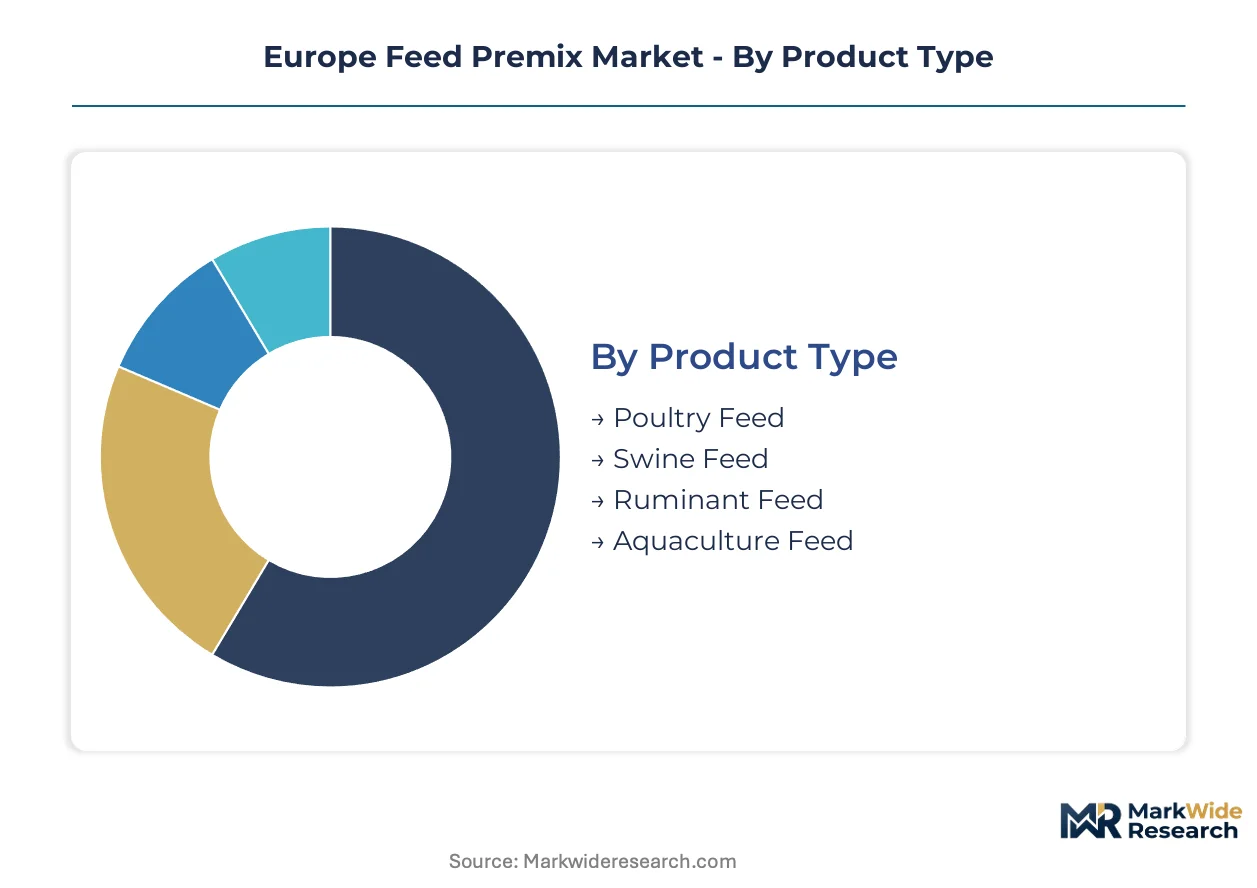
Feed premix segmentation in Europe reflects divergent nutritional requirements across livestock species and the regulatory-driven shift from growth promotion toward metabolic efficiency. Understanding these divisions reveals where formulation complexity concentrates and where margin structures differ most sharply.
Product Type:
Species-specific nutritional requirements create distinct premix formulation intensities across European livestock sectors.
- Poultry Feed:Broiler density in Poland and layer operations in Spain drive concentrated demand for vitamin-mineral premixes optimized for rapid growth cycles and egg production efficiency. EFSA antibiotic reduction mandates are accelerating probiotic and enzyme incorporation in broiler starter diets.
- Aquaculture Feed:Salmon and trout producers in Norway and Scotland substitute marine ingredients with precision micronutrient packages, creating the steepest formulation complexity escalation as fishmeal replacement intensifies.
- Swine Feed:German and Dutch pork operations require amino acid premixes balancing low-protein diets to meet nitrogen excretion regulations under EU environmental directives.
- Ruminant Feed:Dairy herds in France and Ireland utilize mineral premixes targeting metabolic health during transition periods, with lower per-animal premix intensity than monogastric species.
Poultry feed premix commands the established base. The steepest expansion runs through aquaculture feed as marine ingredient substitution accelerates.
Additive Type:
Functional sophistication and input cost exposure vary dramatically across micronutrient categories.
- Amino Acids:Lysine and methionine precision requirements dominate low-protein poultry and swine formulations, with synthetic production technologies from German chemical suppliers reducing import dependency.
- Enzymes:Phytase and carbohydrase demand concentrates in Dutch and Spanish feed mills where thermal stability during pelleting creates technical differentiation among suppliers.
- Vitamins:Fat-soluble and water-soluble vitamin premixes face price volatility from Chinese fermentation capacity fluctuations, pressuring margin stability for European blenders.
- Minerals:Feed-grade phosphate sourcing from Moroccan suppliers exposes trace mineral premix manufacturers to geopolitical input cost swings.
Amino acid premixes capture premium positioning. Enzyme premixes are climbing the fastest as antibiotic replacement intensifies.
Functionality:
Regulatory compression is restructuring which functional claims premix suppliers can legally market across EU member states.
- Nutritional:Basal vitamin-mineral supplementation maintains volume dominance across all livestock categories, with standardization highest in ruminant applications.
- Digestive Support:Probiotic and prebiotic premixes face EFSA multi-year evaluation timelines that delay commercialization while rewarding established players with regulatory affairs infrastructure.
- Therapeutic:Zinc oxide and copper reduction mandates are constraining traditional therapeutic mineral premix applications in swine diets.
- Growth Promotion:Antibiotic growth promoter prohibition under EU veterinary medicinal product regulations has eliminated this category from legal premix formulation.
Nutritional functionality anchors volume. Digestive support premixes are gaining share fastest as gut health becomes the primary antibiotic replacement pathway.
Distribution Channel:
Channel selection reflects customer scale concentration and technical service requirements across European livestock operations.
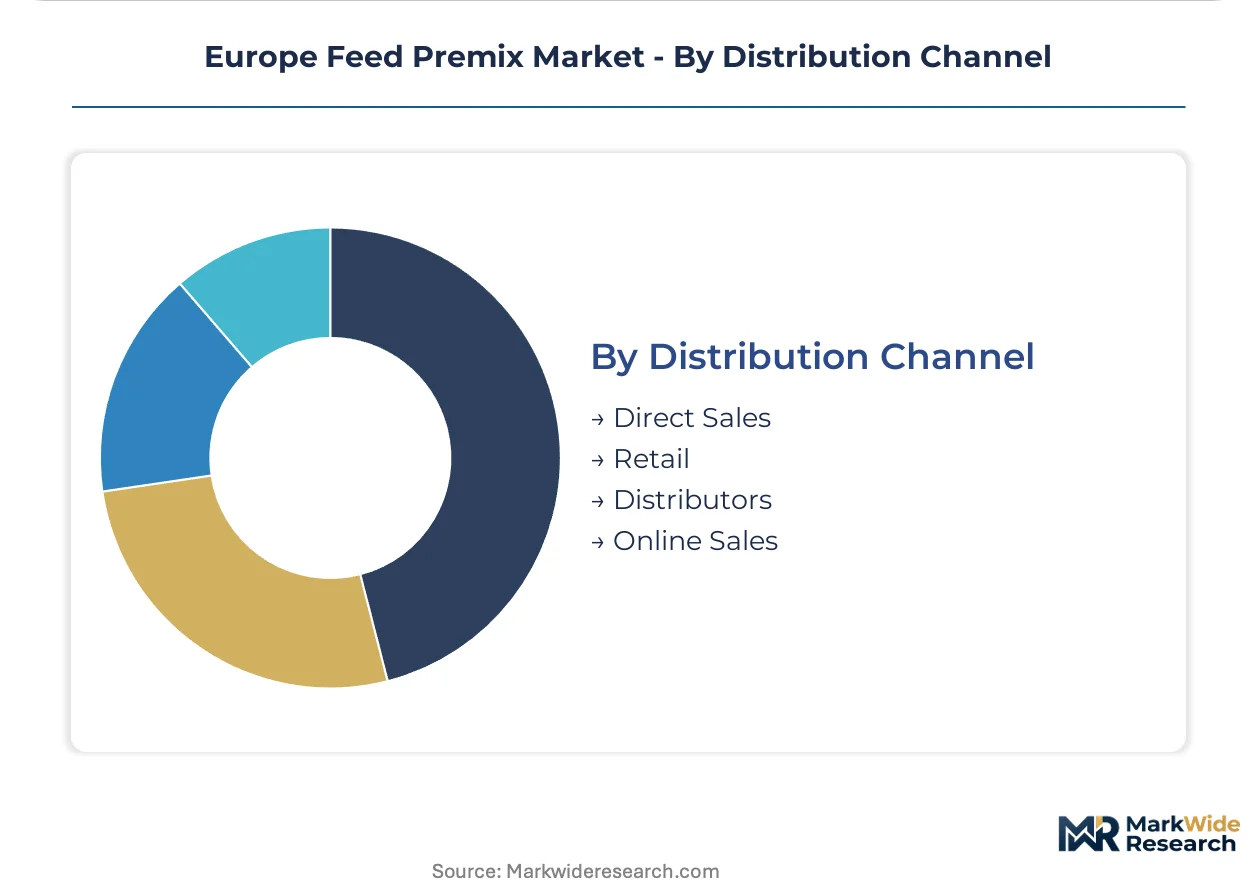
- Direct Sales:Vertically integrated poultry and pork producers in Germany and France centralize procurement at headquarters level, bypassing traditional distributors for micronutrient sourcing.
- Distributors:Regional feed additive distributors maintain relevance for mid-scale compound feed manufacturers in Poland and Italy requiring local inventory and technical support.
- Retail:Farm supply cooperatives in France and Benelux serve smaller livestock operations with standardized premix SKUs and limited formulation customization.
- Online Sales:Digital procurement platforms are emerging for routine vitamin and mineral reorders among tech-adopting poultry integrators in Spain.
Direct sales channels capture the largest transaction values. Distributor relationships are expanding most quickly among mid-tier compound feed manufacturers seeking technical service bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vertically integrated poultry and pork producers in Germany, the Netherlands, and France drive concentrated premix procurement through centralized headquarters. Dutch feed mills cluster around Gelderland and North Brabant, while Spanish layer operations anchor Mediterranean demand. Polish broiler expansion and Norwegian aquaculture sustain growth vectors across Eastern and Northern Europe.
Germany
Precision pork production systems in Lower Saxony and North Rhine-Westphalia demand amino acid premixes for low-protein diet compliance. The German Federal Ministry of Food and Agriculture enforces strict nitrogen excretion limits under the Fertilizer Ordinance. Cuxhaven and Oldenburg host feed mill clusters where premix incorporation rates exceed European averages.
Netherlands
Dense livestock clustering around Gelderland sustains Europe's highest premix consumption intensity per hectare. The Dutch government accelerates antibiotic reduction timelines through the One Health approach policy framework. Veghel and Boxmeer anchor multinational premix formulation facilities serving export-oriented poultry integrators.
Spain
Layer operations in Catalonia and Aragon drive vitamin-mineral premix demand for egg production efficiency. Spanish agricultural authorities implement EU Green Deal Farm to Fork targets through regional farm subsidy restructuring. Lleida province concentrates automated feed mills where real-time premix dosing systems reduce batch variability.
Poland
Broiler density in Greater Poland and Lower Silesia expands to serve Middle Eastern and African poultry meat export markets. The Polish Ministry of Agriculture channels EU Common Agricultural Policy funds toward protein autonomy and domestic legume cultivation. Poznań feed manufacturers adopt species-specific premix formulations optimized for rapid growth phases.
Norway
Salmon and trout producers in Nordland and Møre og Romsdal substitute marine ingredients with precision micronutrient packages. Norwegian Food Safety Authority regulations under EEA alignment extend EFSA evaluation timelines for novel aquaculture feed additives. Ålesund hosts marine ingredient substitution R&D clusters where enzyme premix stability under thermal stress commands technical differentiation.
Europe Feed Premix Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a moderately consolidated structure where integrated grain handlers leverage input cost advantages. Three archetypes dominate: diversified agribusiness conglomerates with captive supply chains, species-focused nutrition specialists, and synthetic amino acid technology providers. Competitive moves concentrate on backward integration into fermentation capacity and digital feed formulation platform deployment.
Among diversified agribusiness conglomerates, Cargill Inc. and Archer-Daniels-Midland Co occupy positions defined by integrated grain-to-premix infrastructure. Nutreco NV exemplifies the species-specialist archetype through aquaculture and poultry formulation focus. Evonik Industries AG anchors the synthetic amino acid technology tier. These three represent distinct competitive vectors: input cost control, species-specific technical service, and precision micronutrient engineering.
| Leading Market Players |
|---|
| Cargill Inc. |
| Archer-Daniels-Midland Co |
| Nutreco NV |
| De Heus Voeders BV |
| Koninklijke DSM NV |
| Agrifirm Group BV |
| Danish Agro AMBA |
| Kemin Industries Inc |
| Evonik Industries AG |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese vitamin fermentation facilities is compressing global micronutrient spot prices and forcing European premix blenders toward long-term offtake contracts to stabilize input costs. This utilization imbalance transfers pricing power upstream to fermentation specialists while squeezing margin capture at the formulation tier.
Pricing Analysis
Cost-plus contracts indexed to phosphate rock and amino acid futures dominate European premix procurement, with Dutch and German compound feed manufacturers locking in twelve-month supply agreements to hedge Moroccan phosphate volatility. Three-tier pricing structure across premium, standard, and economy levels separates species-specific formulations with EFSA digestive-support claims from commodity vitamin-mineral blends. Cost compression in standard-tier amino acid premixes is intensifying because precision fermentation startups are eroding synthetic lysine premiums. Mid-scale Polish poultry integrators exhibit highest price sensitivity, while Norwegian salmon producers accept premium positioning for thermostable enzyme packages.
Supply Chain Analysis
Extended payment terms stretching to ninety days from Dutch feed mill clusters are forcing premix suppliers to utilize supply-chain finance facilities backed by grain trader balance sheets. Critical micronutrient inputs draw from Chinese fermentation capacity for B-vitamins, German chemical synthesis for methionine, and Moroccan mining operations for feed-grade phosphates. Single-source vulnerability concentrates in Chinese citric acid and vitamin C fermentation, where export license disruptions would cascade through European blending schedules. Distribution runs through Benelux formulation hubs serving export-oriented poultry integrators, with secondary flows reaching Polish and Spanish compound feed manufacturers via regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry expertise and regulatory affairs infrastructure constitute the scarcest capabilities in European premix markets, with EFSA approval timelines extending to thirty-six months for novel probiotic strains. This capability gap separates incumbent compounders from commodity blenders and creates acquisition premiums for targets with established dossier portfolios.
For Market Incumbents: Build regulatory data moats by pre-submission engagement with EFSA on next-generation enzyme stability claims, insulating against precision fermentation entrants lacking toxicological study archives. Backward integration into domestic fermentation capacity secures lysine supply continuity against Chinese export tariff exposure. Channel control through embedded nutritionist teams at German pork integrators raises switching costs for competitor premix formulations.
For New Entrants and Emerging Players: Build out digital feed formulation platforms targeting mid-tier Spanish layer operations where real-time nutrient optimization remains undersupplied by incumbent technical service models. Polish broiler export expansion offers the most penetrable geography, with Poznań feed manufacturers seeking species-specific growth-phase formulations for Middle Eastern markets. Partner with aquafeed distributors in Ålesund to bypass established Norwegian salmon integrator procurement lock-in.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among species-specialist premix suppliers with embedded formulation software subscriptions, offering visibility through protein autonomy policy cycles. Long-term viability centers on targets with dual capabilities in synthetic amino acid engineering and EFSA regulatory navigation. Watch for inflection signals in Dutch government antibiotic reduction timeline acceleration, which would compress enzyme premix demand spikes into shorter commercialization windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Domestic lysine production reduces exposure to Chinese export license volatility under REACH substance controls. |
| EFSA Pre-Submission Engagement | Early regulatory dialogue compresses novel probiotic approval timelines from thirty-six to twenty-four months. |
| Digital Formulation Platform Deployment | Real-time nutrient optimization software captures service revenue beyond commodity premix sales to Spanish integrators. |
| Species-Specific R&D Expansion | Aquaculture premix development addresses Norwegian salmon marine ingredient substitution mandates under EEA alignment. |
| Supply-Chain Finance Facility Structuring | Payment term extension capabilities differentiate procurement offers to Dutch feed mill clusters. |
Research Methodology
A spread of perspectives from premix formulation chemists, compound feed procurement directors, EFSA regulatory affairs consultants, and aquaculture nutrition specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews across Benelux, German, and Spanish operations with secondary validation through EU feed additive registration databases, Cefic chemical trade statistics, and national agricultural ministry subsidy disclosures. Bottom-up volume modeling from species-specific feed consumption rates triangulated against top-down premix value estimates derived from customs trade flows.
Demand-supply-balance framing anchored the forecast framework, with livestock population projections, protein autonomy policy implementation rates, and antibiotic reduction timeline compliance across the analysis window driving consumption estimates. Segmentation dimensions modeled include livestock species, additive functionality tier, and distribution channel concentration. CAGRs were derived from weighted scenario analysis incorporating policy acceleration and delay variants, with industry-specific inputs capturing marine ingredient substitution rates in Norwegian aquaculture and low-protein diet adoption in German pork operations.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese fermentation entrants or accelerated EFSA approval streamlining would shift outcomes beyond modeled ranges. Macroeconomic volatility in phosphate and grain markets, regulatory deviation in national farm subsidy restructuring, or breakthroughs in precision fermentation yield rates would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Global Agricultural Micronutrients Market
Agricultural Chemicals
Vietnam Feed Additives Market
Agricultural Chemicals
Amino Acid for Agriculture Market
Agricultural Chemicals
Europe Feed Antioxidants Market
Agricultural Chemicals
Feed Preservatives Market
Agricultural Chemicals
South America Feed Minerals Market
Agricultural Chemicals
Asia Pacific Feed Pelletizing Agents Market
Agricultural Chemicals
North America Soil Treatment Market
Agricultural Chemicals
Asia-Pacific Feed Mycotoxin Detoxifiers Market
Agricultural Chemicals
Agriculture Micronutrients Market
Agricultural Chemicals
North America Feed Phytogenics Market
Agricultural Chemicals
Feed Amino Acids Market
Agricultural Chemicals
South America Plant Growth Regulators Market
Agricultural Chemicals
Africa Feed Antioxidants Market
Agricultural Chemicals
Asia-Pacific Feed Antioxidants Market
Agricultural Chemicals
Global Fertigation and Chemigation Market