
 Asia-Pacific Swine Feed Premix Market | 2026-2036
Asia-Pacific Swine Feed Premix Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Swine Feed Premix Market Outlook
Precision nutrition technology is fragmenting traditional one-size-fits-all premix formulations into phase-specific, genotype-matched diets. DSM leverages its vitamin stability research to anchor premium positioning in heat-stressed tropical environments. Charoen Pokphand Group dominates integrated supply chains across Thailand and Vietnam, while New Hope Group sustains manufacturing scale through captive feed mill networks in Sichuan and Hubei provinces.
Swine feed premix refers to a concentrated blend of vitamins, minerals, amino acids, and functional additives typically dosed at 0.5% to 3.0% of finished feed weight, manufactured through sequential micro-pulverization and carrier coating to ensure homogeneous dispersion and nutrient stability during pelleting at 80-90°C. Its primary purpose is to standardize micronutrient delivery across large-scale operations where raw material variability would otherwise compromise growth performance and reproductive efficiency. Vitamin premix commands the largest value share due to heat-labile nutrient premiums in tropical climates, while probiotic premix represents the fastest-growing category as antibiotic growth promoter bans deepen across ASEAN member states. Amino acid premix carries concentrated margin pools where crystalline lysine, methionine, and threonine replace costlier intact protein sources.
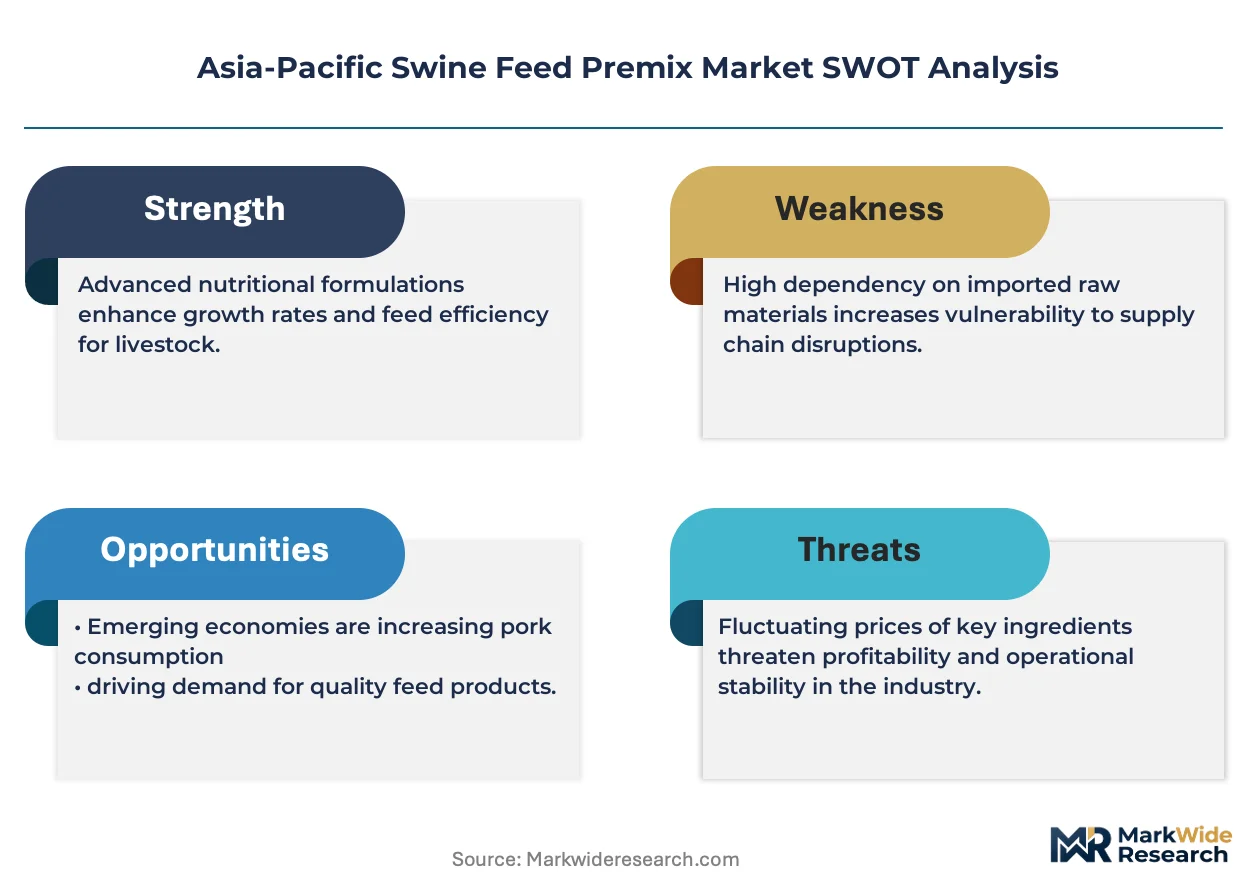
China's Ministry of Agriculture and Rural Affairs (MARA) enforces GB 13078 feed hygiene standards and maintains the national catalog of permitted feed additives, directly determining which premix formulations gain market access. India's FSSAI and BIS jointly oversee imported premix quality benchmarks while the country's PLI scheme for animal husbandry infrastructure indirectly stimulates commercial farm demand for standardized nutrition. Vietnam's Ministry of Agriculture and Rural Development implements circulars on antibiotic residue limits that force reformulation toward enzyme and organic mineral alternatives. Stakeholders must monitor regulatory divergence between China's domestic additive approvals and ASEAN harmonization timelines to avoid stranded inventory in cross-border supply chains.
Market Dynamics
Antibiotic growth promoter bans across ASEAN member states are forcing wholesale reformulation of premix portfolios toward enzyme and organic mineral alternatives, compressing legacy product margins while opening premium positioning for functional additive suppliers.
Growth Catalysts
- China's GB 13078 feed hygiene standards:Mandatory compliance with MARA's national catalog of permitted feed additives creates standardized procurement frameworks that favor certified premix manufacturers over informal suppliers.
- Contract farming consolidation:Vietnam's Mekong Delta integrators are centralizing nutrition programs, concentrating demand volume among qualified premix vendors capable of technical service support.
- Heat-stress formulation premiums:Tropical climates across Southeast Asia command vitamin stability investments that lift average selling prices for premix products with enhanced carrier coating technologies.
Market Restraints
- Vitamin raw material volatility:Feed-grade vitamin A and E synthesis depends on petrochemical intermediates whose price swings transmit directly to premix cost structures.
- Cross-border regulatory divergence:China's domestic additive approvals operate on timelines misaligned with ASEAN harmonization efforts, stranding inventory in regional supply chains.
- Intact protein substitution limits:Crystalline amino acid premixes face technical ceilings in young piglet diets where intact protein sources retain digestive tolerance advantages.
Strategic Opportunities
- Philippines commercial farm underpenetration:Backyard operations still dominate swine production, creating conversion runway as vertical integration accelerates in Luzon and Visayas.
- Probiotic-enzyme convergence:Multi-strain Bacillus formulations combined with non-starch polysaccharide enzymes address post-weaning diarrhea without antibiotic residues.
- India's PLI scheme for animal husbandry:Infrastructure incentives indirectly stimulate commercial farm demand for standardized micronutrient delivery systems.
Industry Challenges
- Precision nutrition talent scarcity:Phase-specific diet formulation requires swine nutritionists with genotype-matching expertise that outpaces regional university pipeline output.
- Micro-pulverization capex thresholds:Homogeneous dispersion at 0.5% inclusion rates demands capital-intensive sequential milling equipment that fragments manufacturing scale economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Swine Feed Premix Market |
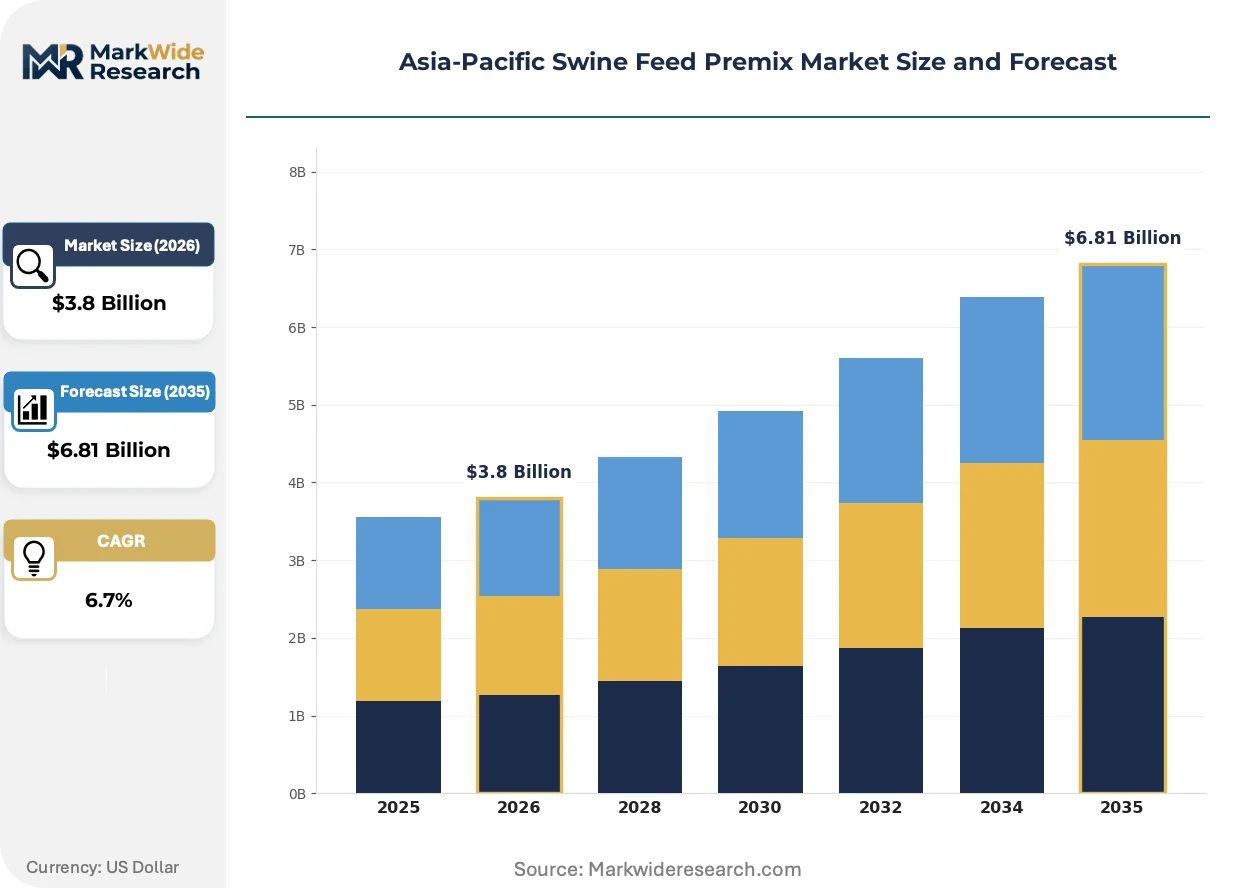
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamin Premix, Mineral Premix, Amino Acid Premix, Probiotic Premix Form: Powder, Liquid, Granules, Pellets Distribution Channel: Online, Retail, Direct Sales, Distributors End User: Commercial Farms, Smallholder Farms, Integrators, Research Institutions |
| Companies Covered | Adisseo, Kemin Industries, Charoen Pokphand Group, Nutreco, New Hope Group, Cargill, DSM, Guangdong Haid Group, BASF SE, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Swine Feed Premix Market Strategic Shifts
Digital feeding systems and real-time growth monitoring are collapsing the feedback loop between diet formulation and barn-level performance, compressing reformulation cycles from months to weeks.
Near-infrared spectroscopy coupled with automated feed mills is rendering obsolete manual sampling and laboratory analysis for premix verification. Large Thai integrators are deploying inline NIR sensors at a pace that halves quality assurance labor while compressing the specification tolerance bands that premix suppliers must hit, squeezing mid-tier manufacturers unable to guarantee coefficient of variation below 3%.
Vietnam's Ministry of Agriculture and Rural Development circulars on antibiotic residue limits are forcing reformulation toward organic trace minerals and exogenous enzyme cocktails. Industrial consequence includes 18-month product development cycles for legacy antibiotic-dependent portfolios. Sow farms in the Red River Delta are responding fastest, converting entire premix procurement to enzyme-based alternatives ahead of pork export certification requirements.
Integrator-controlled nutrition programs are displacing independent feed mill purchasing across Southeast Asian contract farming clusters. The independent distributor channel faces compression as Charoen Pokphand Group and comparable integrators internalize premix specification and procurement. This concentration is most visible in Vietnam's Mekong Delta, where three integrators now control nutrition decisions for over sixty percent of commercial sow inventory.
Asia-Pacific Swine Feed Premix Market Segmentation
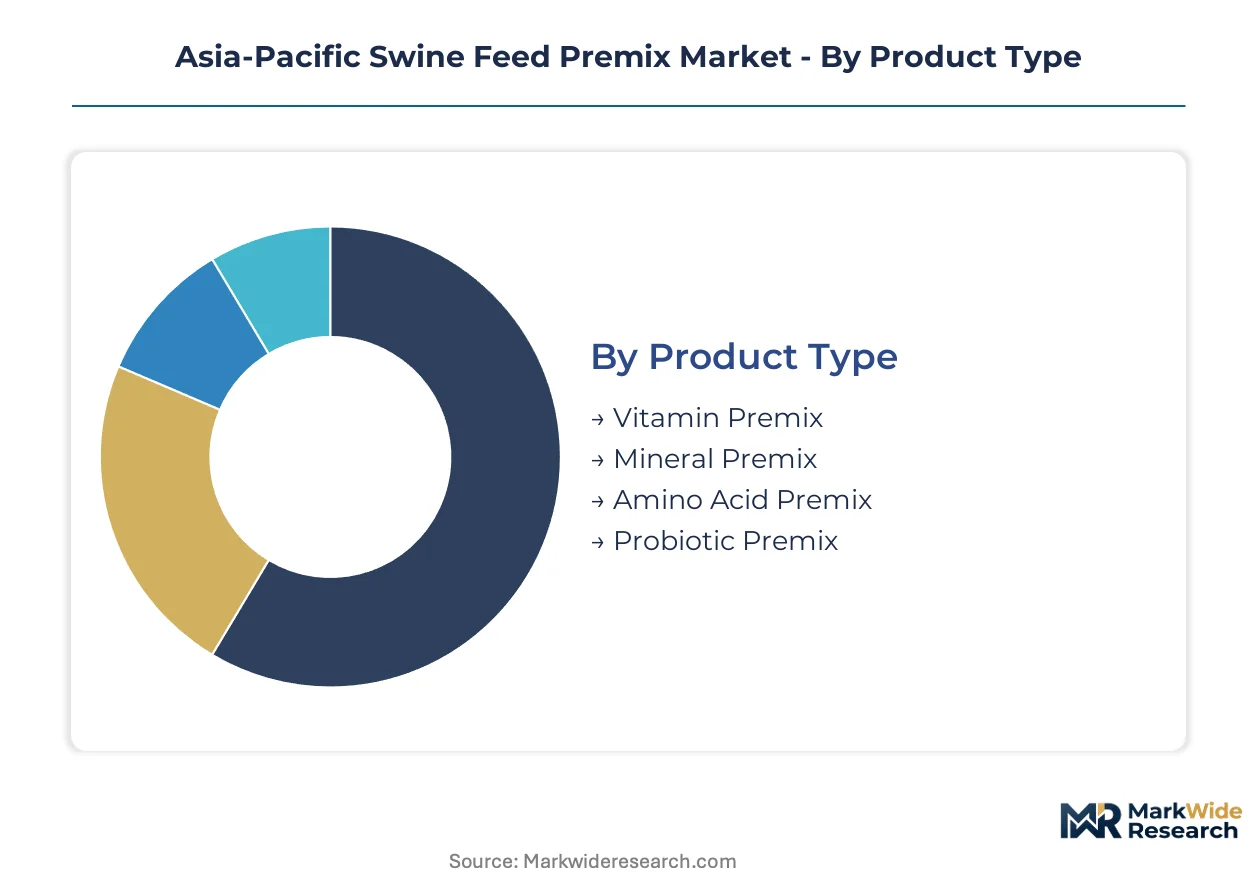
Segmentation in the Asia-Pacific swine feed premix market reveals how procurement patterns diverge between industrial-scale integrators and fragmented smallholder operations. Understanding these divides exposes where formulation complexity commands premium pricing versus where standardization drives volume.
Product Type:
Mature vitamin and mineral formulations anchor procurement budgets while emerging functional categories reshape growth trajectories across tropical production zones.
- Vitamin Premix:Concentrated blends of heat-labile vitamins A, D, E, and K with B-complex carriers engineered for 80-90°C pelleting stability. Demand concentrates in Thailand's Central Plains and Vietnam's Mekong Delta where commercial sow herds require reproductive micronutrient precision under chronic heat stress.
- Mineral Premix:Inorganic and chelated trace elements including selenium, zinc, and copper formulated for bioavailability in high-fiber regional feedstuffs. China's Shandong and Henan provinces drive volume through MARA-certified premix procurement mandates at vertically integrated operations.
- Amino Acid Premix:Crystalline lysine, methionine, threonine, and tryptophan replacing intact protein sources in cost-optimized grower-finisher diets.
- Probiotic Premix:Multi-strain Bacillus and Lactobacillus formulations accelerating as antibiotic growth promoter bans deepen across ASEAN member states.
Vitamin premix handles the majority of throughput; probiotic premix is the fastest mover on share.
Form:
Physical delivery formats segment by manufacturing integration depth and on-farm mixing infrastructure maturity.
- Powder:Micro-pulverized homogeneous blends with sequential carrier coating for 0.5-3.0% inclusion rates. Vietnam's contract farming clusters and Philippines commercial farms in Batangas and Bulacan standardize on powder for flexible diet phase adjustments.
- Liquid:Emulsified fat-soluble vitamins and organic trace minerals for post-pelleting application or drinking water delivery. China's Guangdong and Fujian provinces adopt liquid forms for heat-stressed lactating sow programs where feed intake depression demands alternative delivery vectors.
- Granules:Agglomerated premix with enhanced flowability for automated batching systems at large Thai integrator feed mills.
- Pellets:Pre-compacted premix forms reducing dust generation and improving handling safety in smallholder cooperatives.
Powder handles the majority of throughput; liquid is gaining share fastest in coastal tropical provinces.
Distribution Channel:
Channel structure reflects the displacement of independent feed mill purchasing by integrator-controlled nutrition programs.
- Direct Sales:Technical service-intensive relationships where premix manufacturers embed nutritionists within integrator operations. Charoen Pokphand Group and comparable Thai-Vietnamese conglomerates internalize direct procurement for captive sow herds exceeding 10,000 head.
- Distributors:Regional warehousing networks serving independent commercial farms and cooperative associations. India's Maharashtra and Karnataka states rely on distributor channels where PLI scheme infrastructure investments have not yet consolidated procurement.
- Online:E-procurement platforms emerging for standardized vitamin and mineral premix reorders at mid-scale operations.
- Retail:Counter sales at agricultural supply cooperatives serving backyard and smallholder producers with basic premix formulations.
Direct sales handles the majority of throughput; online is climbing the fastest as integrator subsidiaries digitize procurement.
End User:
Customer type segmentation tracks the structural shift from backyard production to contract farming consolidation.
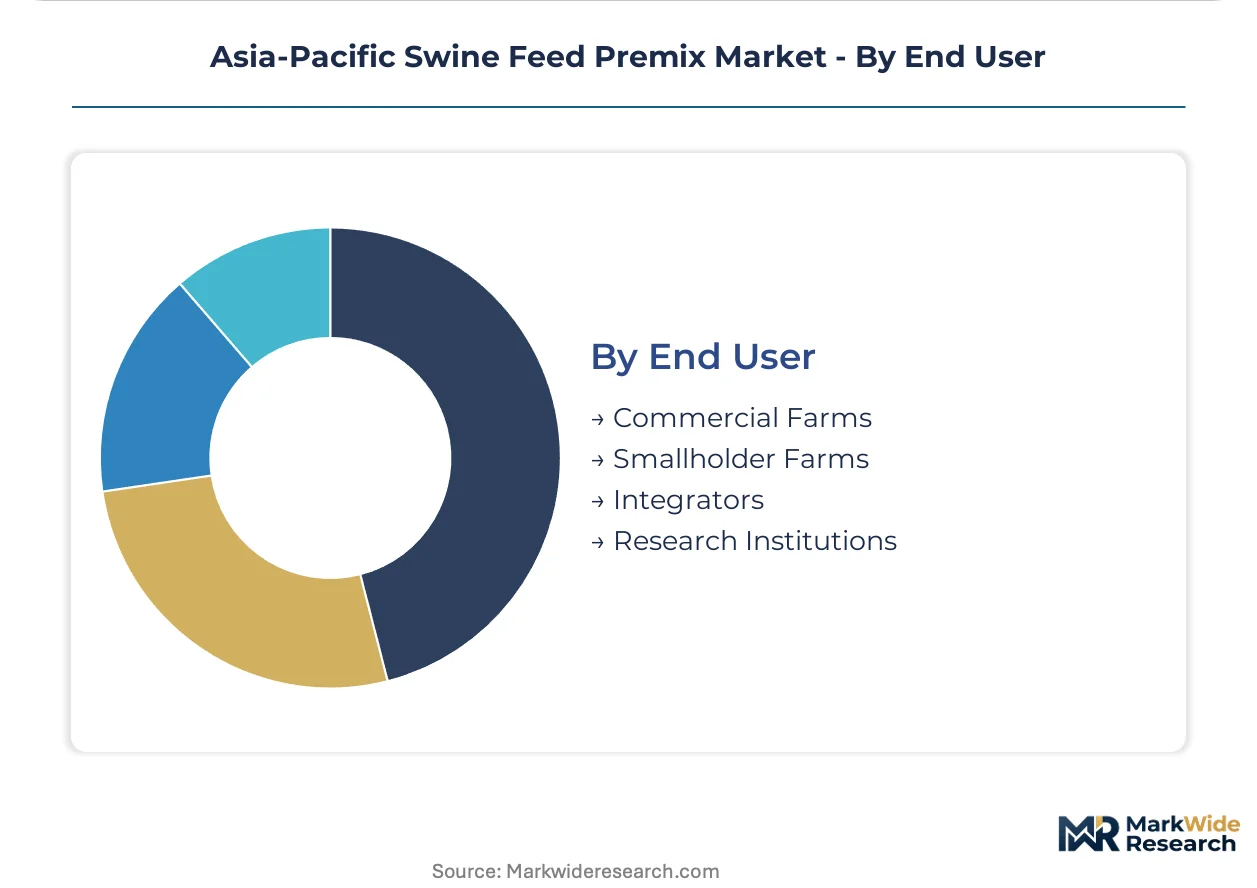
- Integrators:Vertically coordinated operations controlling nutrition specifications across multiplier farms, nurseries, and finishing facilities. Vietnam's Mekong Delta concentration sees three integrators directing premix procurement for the majority of commercial sow inventory.
- Commercial Farms:Independent large-scale operations with 500+ sow capacity operating under technical service agreements with premix suppliers. China's Sichuan and Hubei provinces sustain this segment through New Hope Group and comparable captive feed mill networks.
- Smallholder Farms:Backyard and village-level producers with sub-50 sow herds purchasing basic premix through cooperative aggregators.
- Research Institutions:University and government experimental stations evaluating genotype-specific formulation responses.
Integrators handle the majority of throughput; commercial farms are expanding most quickly where PLI scheme incentives accelerate infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam exports formulated premix to Philippine commercial farms under technical service agreements, establishing a southward trade corridor that concentrates procurement expertise in Ho Chi Minh City logistics hubs.
China
Sichuan and Hubei provinces drive premix volume through captive feed mill networks serving commercial sow herds. MARA enforces GB 13078 feed hygiene standards and maintains the national catalog of permitted feed additives, restricting formulation options. Yangtze River Delta integrators centralize nutrition programs across multiplier farms, nurseries, and finishing facilities.
Vietnam
Mekong Delta contract farming clusters concentrate demand among three integrators controlling nutrition decisions for over sixty percent of commercial sow inventory. Ministry of Agriculture and Rural Development circulars on antibiotic residue limits force reformulation toward enzyme and organic mineral alternatives. Red River Delta sow farms convert entire premix procurement to enzyme-based alternatives ahead of pork export certification requirements.
Thailand
Central Plains commercial sow herds require reproductive micronutrient precision under chronic heat stress, commanding vitamin stability investments. Large integrators deploy inline NIR sensors at feed mills, halving quality assurance labor while compressing specification tolerance bands. Bangkok-based conglomerates internalize premix specification and procurement across vertically coordinated operations.
India
Maharashtra and Karnataka states rely on distributor channels where PLI scheme infrastructure investments have not yet consolidated procurement. FSSAI and BIS jointly oversee imported premix quality benchmarks while the country's PLI scheme for animal husbandry infrastructure indirectly stimulates commercial farm demand. Commercial farms with 500+ sow capacity operate under technical service agreements with premix suppliers in emerging production zones.
Philippines
Luzon and Visayas vertical integration accelerates conversion from backyard operations to commercial farm structures. Batangas and Bulacan commercial farms standardize on powder premix for flexible diet phase adjustments. Independent distributor channels face compression as integrator-controlled nutrition programs displace independent feed mill purchasing.
Asia-Pacific Swine Feed Premix Market Competitive Environment
Channel-controlling players compete with product-specialist players across procurement concentration points. The vendor base stratifies into three tiers: integrated conglomerates with captive feed mill networks, multinational additive suppliers with technical service capabilities, and regional premix manufacturers serving fragmented smallholder channels. Two strategic archetypes dominate: integrators internalizing nutrition decisions and independent suppliers embedding nutritionists within customer operations. Competitive moves center on backward integration into vitamin synthesis and geographic expansion through distributor network acquisition.
Within the integrated conglomerate tier, Charoen Pokphand Group and New Hope Group exemplify channel control through captive supply chains. Charoen Pokphand Group anchors integrated supply chains across Thailand and Vietnam, while New Hope Group sustains manufacturing scale through in-house production networks in Sichuan and Hubei provinces. Among multinational specialists, DSM occupies a position anchored by vitamin stability research, and BASF SE represents the chemical-industry archetype with feed additive portfolios. Adisseo and Kemin Industries sit within the functional additive specialist category, serving reformulation demand as antibiotic growth promoter bans deepen.
| Leading Market Players |
|---|
| Adisseo |
| Kemin Industries |
| Charoen Pokphand Group |
| Nutreco |
| New Hope Group |
| Cargill |
| DSM |
| Guangdong Haid Group |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
Ho Chi Minh City to Manila freight corridors transmit vitamin raw material volatility directly into Philippine commercial farm procurement costs, compressing margins for distributors while enabling Thai integrators to leverage captive logistics for price differentiation across ASEAN contract farming clusters.
Pricing Analysis
Carrier-coating technology-generation pricing gaps separate enhanced heat-stability formulations from standard vitamin premixes and next-generation nano-encapsulation alternatives. Three-tier pricing structure across premium, standard, and economy levels tracks inclusion rate precision and technical service bundling. Pricing pressure stems from crystalline amino acid commoditization in grower-finisher diets. Smallholder cooperatives exhibit highest price sensitivity; integrators with captive feed mills demonstrate lowest sensitivity due to volume aggregation.
Supply Chain Analysis
Supplier-financing facilities extended by DSM and BASF SE anchor working capital for Vietnamese contract farming clusters facing 90-day payment cycles. China, Thailand, and India concentrate vitamin synthesis and micro-pulverization capacity. Feed-grade vitamin A and E synthesis draws from petrochemical intermediates. Single-source vulnerability concentrates in heat-labile vitamin carriers. Distribution runs through integrator-controlled nutrition programs displacing independent feed mill channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and embedded nutritionist deployments expand faster than commodity premix volumes, transforming supplier relationships from transactional supply to recurring advisory partnerships across Southeast Asian contract farming clusters.
For Market Incumbents: Entrench position through backward integration into vitamin synthesis capacity and certification investment for MARA GB 13078 compliance. Charoen Pokphand Group-style integrator consolidation threatens independent distributor margins. Channel control via direct technical service embedding defends against displacement.
For New Entrants and Emerging Players: Build out probiotic-enzyme convergence portfolios targeting Vietnam's Red River Delta sow farms ahead of pork export certification deadlines. Philippines commercial farm underpenetration in Luzon and Visayas offers most penetrable conversion runway. Digital feeding system partnerships provide differentiated go-to-market positioning against legacy distributors.
For Investors and Strategic Acquirers: Regional premix manufacturers with MARA-certified formulations and existing technical service infrastructure present acquisition targets with integration-ready compliance assets. Long-term viability hinges on antibiotic growth promoter ban acceleration across ASEAN member states. Monitor Vietnam Ministry of Agriculture and Rural Development circular enforcement timelines as inflection indicator for enzyme-premix demand spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vitamin Synthesis | Captive supply of heat-labile nutrients insulates margin from petrochemical price swings. |
| Embedded Nutritionist Technical Service | DSM-style advisory deployment locks integrator relationships beyond commodity supply. |
| Probiotic-Enzyme Portfolio Development | Multi-strain Bacillus formulations capture reformulation demand from antibiotic bans. |
| Inline NIR Sensor Deployment | Thai integrator adoption halves quality assurance labor while tightening supplier specifications. |
| Distributor Network Acquisition | Geographic expansion through India's Maharashtra and Karnataka channel consolidation. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of MARA additive catalogs, Vietnamese Ministry circulars, and ASEAN trade flow databases through structured interviews with swine nutritionists, integrator procurement directors, feed mill operations managers, and premix formulation scientists. Bottom-up volume triangulation from sow herd counts and inclusion rate assumptions cross-validates against top-down value estimates derived from manufacturer revenue disclosures and customs premix trade records.
Forecast inputs incorporate product type segmentation across vitamin, mineral, amino acid, and probiotic premix categories alongside form factors and distribution channel concentration. Modeled dimensions span genotype-specific formulation complexity, heat-stability tier, and integrator versus commercial farm procurement archetypes. CAGRs derive from segment-level volume trajectories and price evolution assumptions across the projection horizon, with specific weighting for PLI scheme infrastructure incentives in India and antibiotic ban implementation timelines in Vietnam.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by chemical conglomerates or accelerated ASEAN regulatory harmonization would shift outcomes. Macroeconomic volatility in petrochemical feedstocks, divergence between China's GB standards and ASEAN additive approvals, or technological breakthroughs in nano-encapsulation delivery would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
ASEAN Livestock Disinfectant Market
Agricultural Chemicals
Organic Bromide Market
Agricultural Chemicals
Thailand Feed Additives Market
Agricultural Chemicals
Field Marking Paint Market
Agricultural Chemicals
North America Herbicide Market
Agricultural Chemicals
South America Silage Inoculant Market
Agricultural Chemicals
Asia-Pacific Feed Antibiotics Market
Agricultural Chemicals
Neem Extract Market
Agricultural Chemicals
Agricultural Coatings Market
Agricultural Chemicals
Neonicotinoid Insecticides Market
Agricultural Chemicals
Aquafeed Additives Market
Agricultural Chemicals
United States Feed Amino Acids Market
Agricultural Chemicals
North America Feed Pigments Market
Agricultural Chemicals
Feed Binders Market
Agricultural Chemicals
North America Feed Antioxidants Market
Agricultural Chemicals
Middle East Feed Binders Market