
 Africa Compound Feed Market | 2026-2036
Africa Compound Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Compound Feed Market Outlook
Aftermarket nutritional consulting is reshaping margin distribution across the Africa compound feed value chain, shifting profit pools from basic manufacturing toward formulation services and farm-level technical support. Cargill Inc leverages its Pan-African grain origination network to secure cost-advantaged raw material positions. Nutreco NV anchors premium aquaculture and poultry premix supply through specialized facilities in Morocco and Egypt. Alltech Inc differentiates via yeast-based additive technology that addresses mycotoxin challenges prevalent in tropical grain storage.
Africa compound feed comprises scientifically blended mixtures of grains, protein meals, vitamins, and minerals formulated to deliver precise metabolizable energy and crude protein specifications for targeted livestock performance. Manufacturers employ hammer milling, batching, steam pelleting, and extrusion processes to achieve uniform nutrient density and feed conversion efficiency in commercial animal operations. Complete feed formulations dominate volume flows across the continent due to their turnkey convenience for smallholder cooperatives and commercial farms with limited on-farm mixing infrastructure. Poultry farms represent the most structurally important end-user segment, absorbing the majority of pelleted and crumble-form output as integrated broiler operations expand from South Africa into Zambia and Tanzania.
South Africa's Department of Agriculture, Land Reform and Rural Development enforces compulsory feed registration and labeling standards that govern cross-border trade within the Southern African Development Community. Nigeria's National Agency for Food and Drug Administration and Control regulates import permits for vitamin premixes and amino acid additives, creating compliance barriers for informal suppliers. Kenya's Kenya Bureau of Standards mandates aflatoxin maximum limits that reshape maize and groundnut cake procurement patterns for domestic millers. Stakeholders must monitor evolving national feed safety harmonization initiatives and the pace of commercial farming consolidation to calibrate capacity investments and distribution partnerships.
Market Dynamics
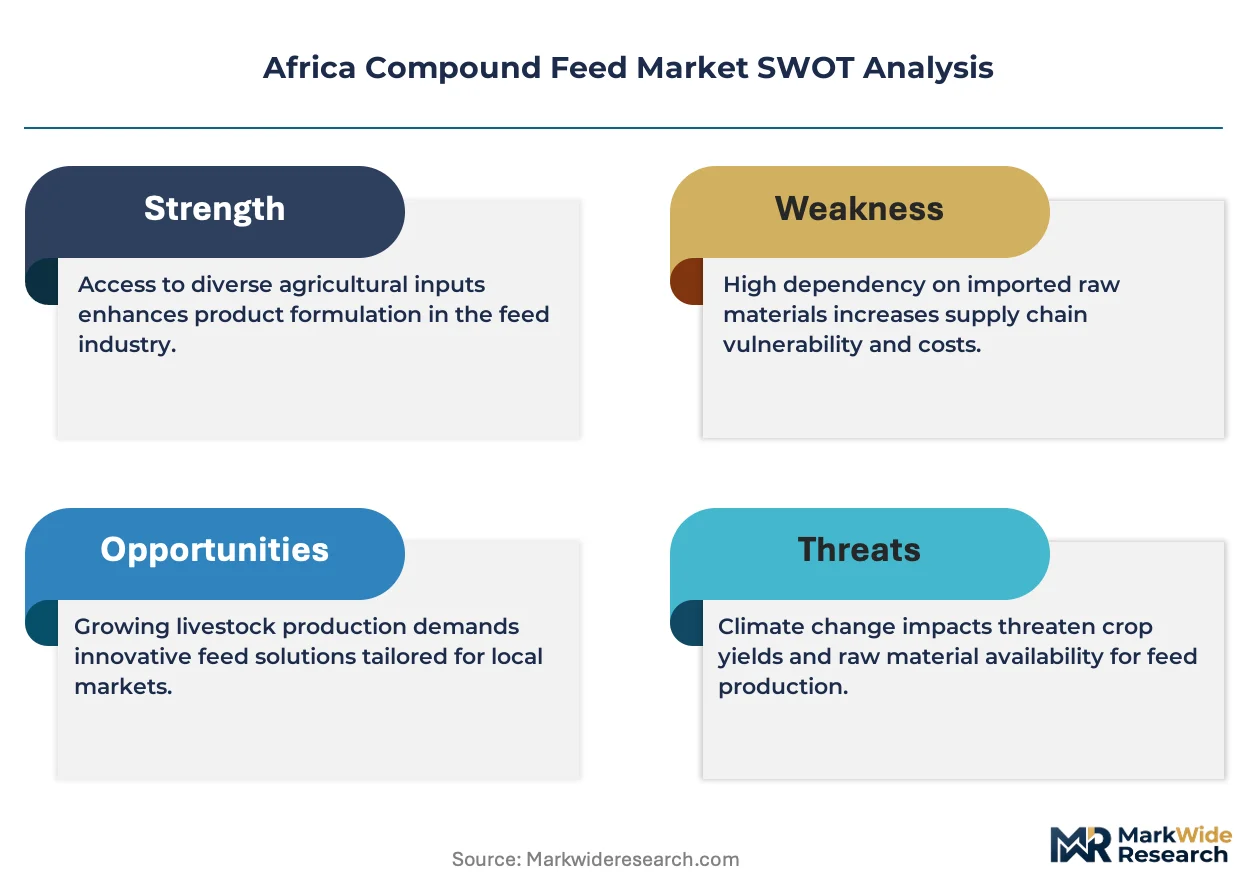
Intensive livestock operations across Nigeria, Kenya, and South Africa are consolidating feed procurement around complete pelleted formulations, compressing margins for independent millers while rewarding integrated suppliers with captive grain origination and technical service capabilities.
Growth Catalysts
- Feed Safety Mandates:Kenya Bureau of Standards aflatoxin limits and Nigeria's NAFDAC premix import permits are formalizing supply chains and disqualifying informal blenders, creating volume concentration among compliant manufacturers.
- Poultry Intensification:Broiler and layer operations in Zambia and Tanzania are adopting automated feeding systems that require uniform crumble and pellet specifications, driving demand for precision-manufactured compound feeds.
- Aquaculture Expansion:Egyptian and Moroccan fish farming corridors are scaling extruded aquafeed consumption as Nile tilapia and seabass production shifts from extensive to semi-intensive pond systems.
Market Restraints
- Maize Price Volatility:Drought cycles in Southern Africa and currency depreciation in Nigeria create input cost instability that erodes formulation margins and discourages long-term supply contracts.
- Port and Logistics Bottlenecks:Container congestion at Durban and Lagos Apapa ports delays vitamin premix and amino acid deliveries, forcing millers to carry expensive safety stocks of critical micro-ingredients.
- Limited On-Farm Mixing Infrastructure:Smallholder cooperatives lack hammer mills and batching equipment, constraining addressable market for concentrate and premix products outside commercial farm clusters.
Strategic Opportunities
- Dairy Corridor Development:East African highland zones in Ethiopia and Uganda present underpenetrated demand for high-energy dairy concentrates as commercial milk collection networks expand.
- Yeast-Based Mycotoxin Binders:Tropical grain storage conditions create adoption potential for biotechnological feed additives that neutralize aflatoxin and fumonisin contamination in groundnut cake and maize.
- Mobile Batching Units:Franchise-operated decentralized mixing services can reach scattered smallholders in Ghana and Senegal with customized rations without requiring capital-intensive central mill expansion.
Industry Challenges
- Formulation Chemist Shortage:Qualified nutritionists capable of optimizing metabolizable energy and amino acid matrices for tropical ingredient availability remain scarce across East and West African mill operations.
- Registration Timeline Compression:Multi-jurisdictional feed product approvals across SADC, ECOWAS, and EAC trade blocs create compliance complexity that delays new formulation launches by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Compound Feed Market |
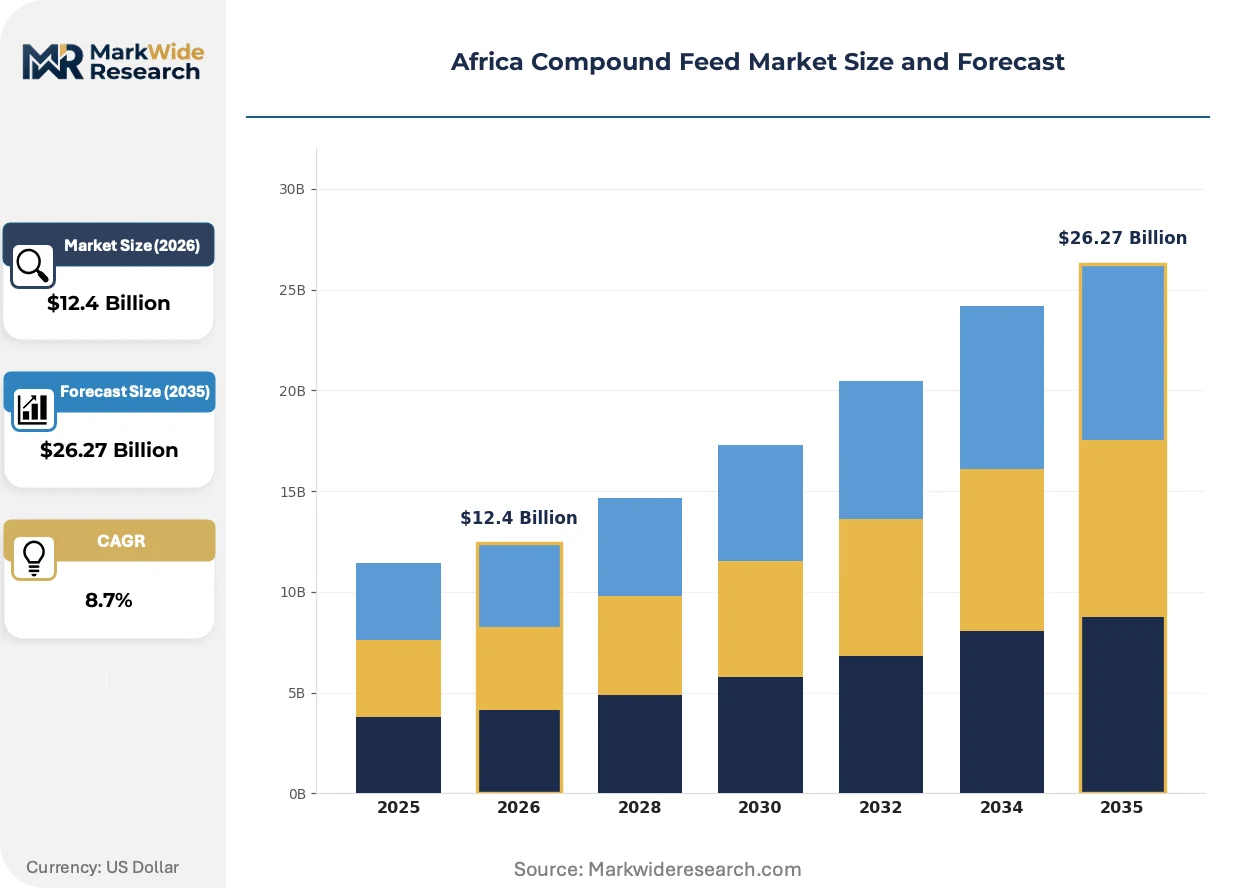
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.27 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Complete Feed, Supplementary Feed, Concentrate Feed, Mash Feed End User: Poultry Farms, Cattle Ranches, Aquaculture, Swine Operations Distribution Channel: Online Retail, Wholesale Distributors, Direct Sales, Agricultural Cooperatives Form: Pellets, Crumbles, Powder, Liquid |
| Companies Covered | Cargill Inc, Nutreco NV, Alltech Inc, New Hope Group, Novus International, Archer Daniels Midland, Land O Lakes Purina, Neovia Group, Charoen Pokphand Foods PCL, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Compound Feed Market Strategic Shifts
Digital feed formulation platforms and precision livestock monitoring are converging to enable real-time diet adjustment based on actual flock performance rather than static nutritional tables.
Near-infrared spectroscopy is collapsing traditional laboratory-based proximate analysis timelines for crude protein and moisture verification. Integrated broiler operations in South Africa and Nigeria are deploying inline NIR sensors at receiving bays to reject off-spec grain deliveries within minutes rather than days. This compression of quality assurance cycles is collapsing buffer inventory requirements and accelerating cash conversion for large-scale poultry integrators.
Kenya Bureau of Standards and Nigeria's NAFDAC are tightening parallel import restrictions on vitamin premixes and trace mineral additives, requiring certificate-of-origin documentation and GMP facility audits. These measures are forcing informal traders to exit the premix segment while creating compliance-driven consolidation among registered importers. West African poultry belts are responding by shifting procurement toward SADC-registered suppliers with established East African distribution.
Commercial farms are unbundling nutritional consulting from basic feed supply contracts, purchasing formulation optimization and flock performance auditing as separate service lines. Layer operations in Tanzania and broiler farms in Ghana now retain independent nutritionists who specify feed suppliers based on least-cost formulation outcomes rather than legacy relationships. This service-layer separation is most visible in peri-urban farming clusters where technical staff density supports competitive advisory markets.
Africa Compound Feed Market Segmentation
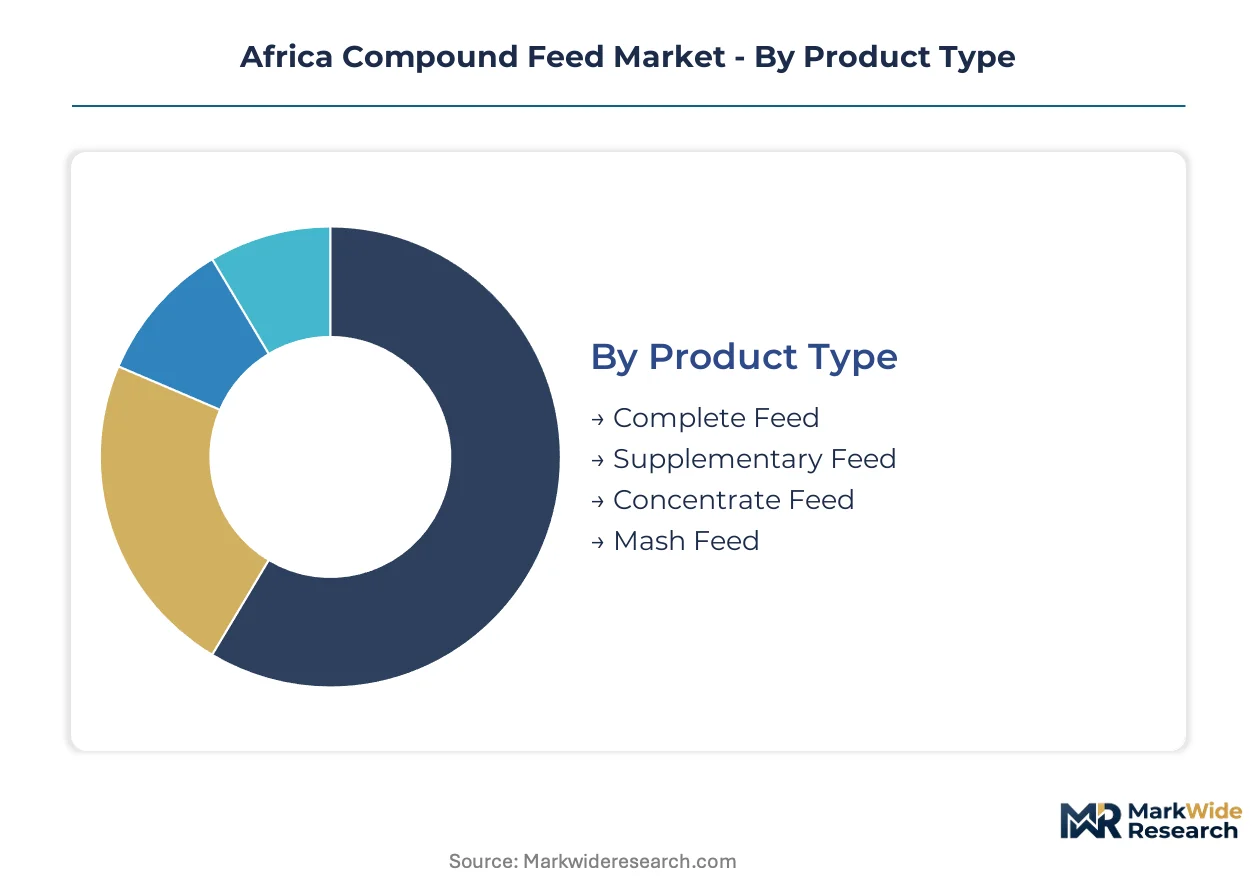
Segmentation in the Africa compound feed market reveals how formulation complexity and delivery logistics create distinct service intensity requirements across product categories. Manufacturers calibrate technical support, inventory positioning, and credit terms differently for each segment based on customer sophistication and supply chain reach.
Product Type:
After-sales service intensity varies dramatically across product types, with complete feed demanding minimal technical intervention while concentrates require intensive on-farm nutritional consulting to achieve correct inclusion rates.
- Complete Feed:Ready-to-use formulations containing all required nutrients at specified metabolizable energy levels eliminate on-farm mixing complexity. Poultry farms across Nigeria and Kenya absorb the majority of pelleted complete feed volumes as integrated broiler operations expand. This segment holds the largest share; momentum sits with Concentrate Feed.
- Supplementary Feed:Mineral blocks, vitamin premixes, and protein supplements designed to correct nutritional deficiencies in basal rations. Cattle ranches in East African highland zones procure supplementary feeds through agricultural cooperatives to complement pasture-based systems during dry seasons.
- Concentrate Feed:High-density nutrient packages requiring dilution with farm-sourced roughages or grains before feeding. Dairy operations in Ethiopia and Uganda are scaling concentrate procurement as commercial milk collection networks professionalize, creating demand for technical support in ration balancing.
- Mash Feed:Unpelleted ground formulations offering lower capital requirements for small-scale millers. Informal blenders in Ghana and Senegal dominate mash feed supply to backyard poultry keepers, though feed safety mandates are compressing this channel.
Complete Feed holds the largest share; momentum sits with Concentrate Feed.
End User:
Customer sophistication tiers determine pricing power and contract structures, with large-scale integrators commanding volume discounts and technical service bundling unavailable to fragmented smallholder segments.
- Poultry Farms:Broiler and layer operations consume the majority of manufactured compound feed volumes across the continent. Automated feeding systems in Zambian and Tanzanian poultry houses require uniform crumble and pellet specifications that only precision millers can reliably supply.
- Cattle Ranches:Commercial beef and dairy operations in South Africa and Kenya drive demand for high-energy rations and mineral supplements. Feedlot operators in the Free State province procure complete pelleted rations on long-term contracts tied to maize price indices.
- Aquaculture:Egyptian and Moroccan fish farming corridors are scaling extruded aquafeed consumption as Nile tilapia production intensifies. This end user category is expanding most quickly as semi-intensive pond systems displace extensive capture-based supply.
- Swine Operations:Commercial pig farms in Nigeria and South Africa require lysine-fortified formulations to optimize feed conversion ratios. African swine fever containment protocols are restructuring procurement toward certified suppliers with biosecurity-verified delivery fleets.
Poultry Farms dominate volume absorption; Aquaculture is climbing the fastest.
Distribution Channel:
Channel selection reflects infrastructure maturity and customer density, with direct sales concentrating around commercial clusters while cooperatives extend reach into dispersed smallholder territories.
- Online Retail:Digital platforms connecting millers to commercial farms are emerging in South Africa and Nigeria, though logistics constraints limit penetration outside major urban corridors. Vitamin premix and specialty additive orders increasingly flow through B2B e-commerce portals.
- Wholesale Distributors:Regional stockists with warehousing capabilities aggregate demand from scattered farms and negotiate volume terms with manufacturers. Kenyan and Tanzanian distributors maintain buffer inventories to buffer customers against port delays for imported micro-ingredients.
- Direct Sales:Millers deploy dedicated sales teams to large integrated operations requiring customized formulation services. South African poultry integrators negotiate direct supply agreements that include on-farm nutritional auditing and flock performance guarantees.
- Agricultural Cooperatives:Member-owned buying groups consolidate smallholder demand in Ghana, Senegal, and Ethiopia. Cooperatives pool procurement to qualify for truckload pricing on complete feeds and shared technical advisory services.
Wholesale Distributors capture the broadest geographic footprint; Direct Sales yield the highest margin per ton.
Form:
Physical form selection balances manufacturing cost, feed conversion efficiency, and on-farm handling infrastructure, with pellets commanding premium pricing against powder alternatives.
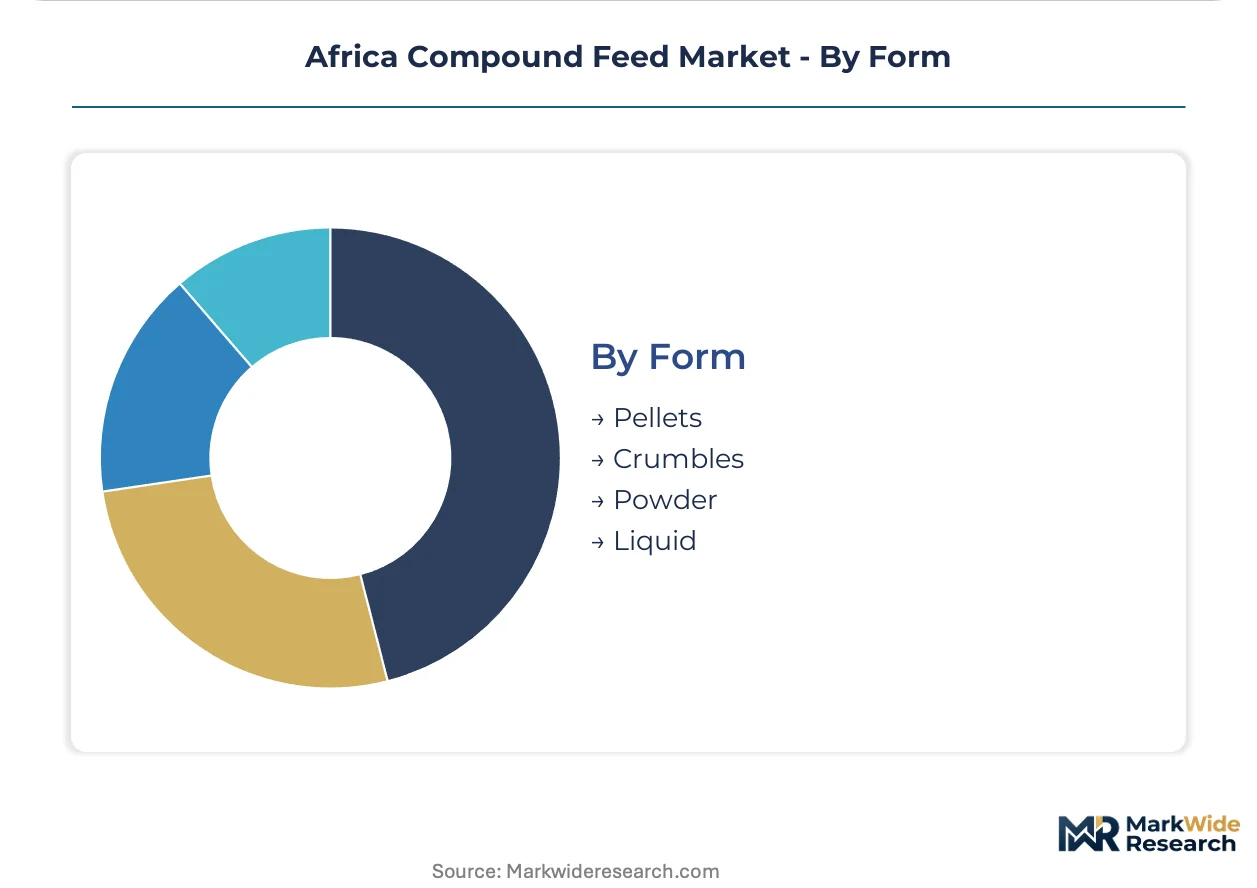
- Pellets:Steam-conditioned and die-pressed formulations minimize feed waste and improve nutrient digestibility in automated feeding systems. Broiler operations across Zambia and Nigeria specify pellet durability indices above 95 percent to prevent fines accumulation in pan feeders.
- Crumbles:Broken pellet fragments sized for layer chicks and young broilers optimize intake while reducing selective feeding. Crumble demand concentrates in hatchery-linked rearing facilities with dedicated early-stage nutrition protocols.
- Powder:Unpelleted mash formulations serve smallholder poultry keepers lacking automated feeding infrastructure. Powdered feeds dominate informal market channels in West African peri-urban zones where hammer milling capacity remains limited.
- Liquid:Molasses-based supplements and emulsified fat blends deliver concentrated energy to high-producing dairy cattle. Liquid feed adoption is restricted to large-scale ranches with specialized mixing and delivery equipment.
Pellets command the highest volume; Crumbles are gaining share fastest among precision-formulation customers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across African feed markets. Nigerian poultry integrators absorb premium formulations with minimal volume contraction, while Ghanaian smallholders slash procurement when maize prices spike. South African commercial operators negotiate index-linked contracts that buffer cost volatility.
South Africa
Integrated broiler and layer operations in the Free State and KwaZulu-Natal drive concentrated demand for pelleted complete feeds. The Department of Agriculture, Land Reform and Rural Development enforces compulsory feed registration that governs cross-border trade within the Southern African Development Community. Durban port congestion delays vitamin premix imports, forcing millers around Pietermaritzburg to carry expensive safety stocks.
Nigeria
Intensive poultry farms across Ogun State and Kaduna corridor scale compound feed procurement to support automated broiler houses. The National Agency for Food and Drug Administration and Control regulates import permits for amino acid additives, creating compliance barriers for informal blenders. Lagos-anchored distributors are consolidating procurement volumes to qualify for manufacturer-direct pricing.
Kenya
Commercial dairy operations in the Central Highlands and Rift Valley expand concentrate consumption as milk collection networks professionalize. The Kenya Bureau of Standards mandates strict aflatoxin maximum limits that reshape maize and groundnut cake sourcing patterns for domestic millers. Nakuru-based feed manufacturers are investing in near-infrared testing infrastructure to verify incoming grain quality.
Egypt
Nile tilapia and seabass producers in the Nile Delta intensify extruded aquafeed consumption as pond systems shift from extensive to semi-intensive models. The country's national food safety regulator enforces mycotoxin control standards that elevate sourcing requirements for imported fishmeal. Alexandria corridor millers are expanding extrusion capacity to serve Mediterranean aquaculture clusters.
Ethiopia
Commercial dairy farms around Addis Ababa and the Awash Valley scale high-energy concentrate procurement to support crossbred herd expansion. The national agricultural standards body is developing feed safety protocols that will formalize supply chains currently dominated by informal blenders. Bishoftu industrial zone manufacturers are piloting mobile batching units to reach scattered smallholder cooperatives.
Africa Compound Feed Market Competitive Environment
Capability concentration sits with multinational nutrition specialists; scale advantage sits with diversified agribusiness conglomerates. The market structures around three tiers: global integrated suppliers with captive grain origination, regional premix specialists with formulation expertise, and local millers competing on logistics proximity. Strategic moves center on backward integration into grain trading and forward integration into farm-level technical services.
Within the multinational integrated tier, Cargill Inc and Nutreco NV exemplify divergent positioning strategies. Cargill leverages Pan-African grain origination infrastructure to secure cost-advantaged raw material positions across multiple jurisdictions. Nutreco anchors premium aquaculture and poultry premix supply through specialized facilities in North African production corridors. Alltech Inc occupies a distinct technology-driven position, differentiating via yeast-based additive platforms that address mycotoxin challenges prevalent in tropical grain storage conditions.
| Leading Market Players |
|---|
| Cargill Inc |
| Nutreco NV |
| Alltech Inc |
| New Hope Group |
| Novus International |
| Archer Daniels Midland |
| Land O Lakes Purina |
| Neovia Group |
| Charoen Pokphand Foods PCL |
| Others |
Value Chain & Pricing Dynamics
Durban-Lagos freight corridors transmit container cost volatility directly into compound feed pricing tiers, concentrating margin pressure on millers lacking captive grain origination while enabling integrated suppliers to sustain price premiums through logistics control and technical service bundling.
Pricing Analysis
Contract structures stratify across long-term offtake agreements, spot maize purchases, and project-based formulation services. Price differentiation hinges on volume scale and certification grade, with Kenya Bureau of Standards-compliant manufacturers commanding premiums over informal blenders. Pricing pressure stems from currency depreciation in Nigeria and drought-driven maize cost spikes in Southern Africa. Smallholder cooperatives in Ghana and Senegal exhibit highest price sensitivity, while South African poultry integrators absorb premium formulations with minimal volume contraction.
Supply Chain Analysis
Supplier-financing through extended payment terms and inventory floor-planning facilities anchors distributor relationships across East and West African markets. Raw material sourcing concentrates in South Africa, Nigeria, and Kenya for domestic grain; Argentina and Ukraine for imported soybean meal; and Morocco for specialized aquafeed inputs. The supply chain rests on vitamin premix and amino acid dependencies from European and Asian manufacturers. Single-source vulnerability around Durban and Lagos Apapa port congestion creates delivery risk. Distribution runs through wholesale distributors with regional warehousing capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across national regulatory regimes and smallholder dispersion creates multiple niche entry points, particularly as dairy corridor professionalization and aquaculture intensification generate demand for specialized formulation services.
For Market Incumbents: Build formulation expertise moats through captive nutritionist teams and NIR testing infrastructure. Cargill and Nutreco should expand technical service bundling to defend against regional premix specialists. Backward integration into grain trading in Zambia and Tanzania buffers maize cost volatility. Certification investment ahead of harmonized ECOWAS feed safety standards secures first-mover positioning. For New Entrants and Emerging Players: Mobile batching services for scattered Ethiopian and Ugandan smallholders represent the most penetrable entry point before central mill competition intensifies. Yeast-based mycotoxin binder distribution through existing veterinary channels offers low-capital market access. Partnership with agricultural cooperatives in Ghana and Senegal provides aggregated demand without direct farmer acquisition costs. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified agribusiness conglomerates with underoptimized feed divisions lacking formulation depth. Mid-cap millers with established SADC registration but limited technical service capabilities offer consolidation platforms. Monitor Kenya Bureau of Standards and NAFDAC enforcement intensity as inflection indicator for informal blender displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Origination | Cargill's Pan-African infrastructure secures cost-advantaged maize positions against spot-market competitors. |
| Mobile Batching Unit Deployment | Decentralized mixing services reach Ethiopian smallholders without capital-intensive central mill expansion. |
| Yeast-Based Additive Platform Development | Alltech's mycotoxin binders address tropical storage conditions prevalent in Nigerian groundnut cake supply. |
| Direct Sales Force Expansion | On-farm nutritional auditing locks in South African poultry integrator contracts against distributor competition. |
| Regulatory Certification Pre-Investment | Early SADC and ECOWAS compliance positions manufacturers for formal market consolidation. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, national agricultural ministry statistics, and feed industry association reports across the analysis window. Interviews with feed mill operations managers, poultry farm procurement directors, agricultural cooperative buying committee members, and national standards body officials informed demand-side validation. Secondary sources include Kenya Bureau of Standards aflatoxin surveillance data, NAFDAC import permit registries, and SADC trade flow documentation. Bottom-up capacity assessments and top-down consumption estimates triangulate market sizing.
Forecast inputs incorporate livestock herd expansion projections, commercial farming consolidation trajectories, and regulatory harmonization timelines across the projection horizon. Segmentation dimensions span product type, end-user species, physical form, and distribution channel. CAGRs derive from fitted trend analysis against historical consumption patterns and elasticity-adjusted price scenarios. Industry-specific inputs include mycotoxin incidence rates affecting formulation costs and port efficiency indices impacting micro-ingredient delivery reliability.
Practitioners should monitor drought frequency in Southern Africa, currency stability in Nigeria, and feed safety enforcement intensity for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
France Animal Protein Market
Agriculture and Agri Products
Saudi Arabia Eggs Market
Agriculture and Agri Products
Elaeis Guineensis (Palm) Fruit Extract Market
Agriculture and Agri Products
Middle East Animal Protein Market
Agriculture and Agri Products
Taro Market
Agriculture and Agri Products
Organic Quinoa Market
Agriculture and Agri Products
Germany Compound Feed Market
Agriculture and Agri Products
Africa Cashew Market
Agriculture and Agri Products
Kuwait Poultry Meat Market
Agriculture and Agri Products
North America Eggs Market
Agriculture and Agri Products
Cashew Market
Agriculture and Agri Products
Seaweed Market
Agriculture and Agri Products
United Kingdom Poultry Meat Market
Agriculture and Agri Products
United Kingdom Animal Protein Market
Agriculture and Agri Products
Global Palm Oil Market
Agriculture and Agri Products
Tarragon Market