
 Lentil Bread Market | 2026-2036
Lentil Bread Market Size, Share, and Industry Trends Forecast 2026-2036
Lentil Bread Market Foresight
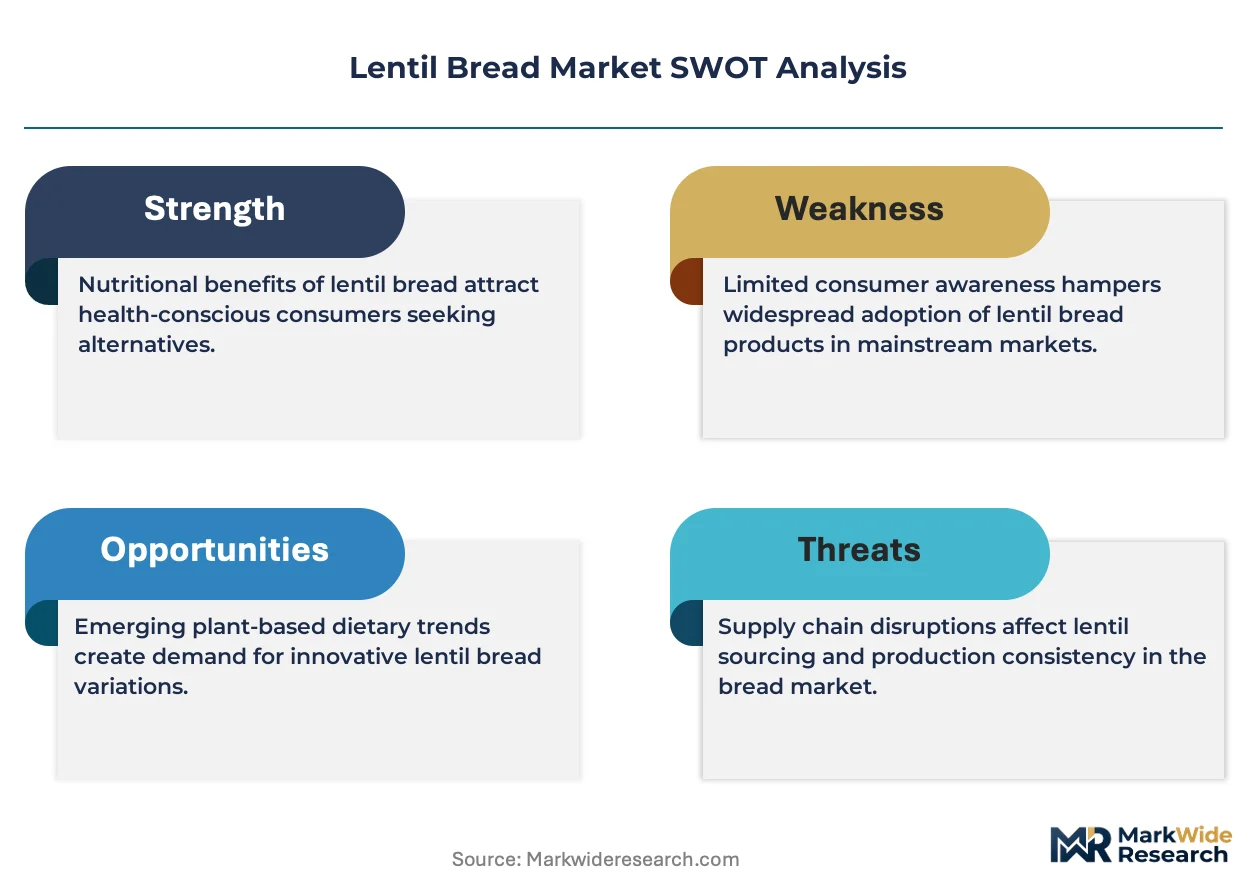
Restaurant procurement is rebalancing toward allergen-friendly menu items, pulling lentil bread into commercial kitchens at higher volumes. Food for Life leverages its sprouted-grain expertise to anchor the premium organic channel. Silver Hills Bakery competes through clean-label positioning across North American natural retailers. Grupo Bimbo extends its manufacturing scale into emerging gluten-free production lines.
Lentil bread denotes baked goods formulated with lentil flour or sprouted lentil meal as a primary structural ingredient, typically containing protein levels of 8-12% and achieving moisture retention through hydrocolloid binding systems rather than gluten networks. The product serves consumers seeking high-protein, low-glycemic alternatives to wheat-based staples. Gluten-free loaf bread dominates current retail velocity while flatbread formats capture faster growth in foodservice channels. Specialty stores command the deepest margin pools due to educated staff driving conversion, whereas supermarket distribution is concentrating in perimeter bakery sections rather than center aisles.
The FDA enforces gluten-free labeling thresholds below 20 ppm, compelling precise ingredient segregation and third-party certification investments. The USDA Organic seal and Non-GMO Project verification create tiered market access barriers that favor vertically integrated ingredient suppliers. EFSA's novel food assessments in Europe add compliance complexity for extruded lentil protein innovations. Stakeholders must monitor whether clean-label demands shift from ingredient exclusion toward carbon footprint transparency in pulse sourcing.
Market Dynamics
The lentil bread market is compressing around celiac-safe certification standards, with the FDA's 20 ppm gluten threshold forcing manufacturers to rebuild production lines around segregated ingredient flows and third-party audit protocols rather than conventional bakery infrastructure.
Growth Catalysts
- EFSA novel food pathways:European processors are accelerating extruded lentil protein applications through streamlined safety assessments, opening shelf-stable formats previously blocked by regulatory uncertainty.
- Restaurant procurement rebalancing:Commercial kitchens are expanding allergen-friendly menu sections, pulling lentil flatbreads into foodservice at volumes exceeding retail velocity in several metropolitan clusters.
- Sprouted-grain processing:Enzymatic activation of lentil meal is improving protein bioavailability and reducing anti-nutrient loads, enabling cleaner label claims that convert educated consumers in specialty channels.
Market Restraints
- Pulse flour input volatility:Canadian and Australian lentil harvest variability creates margin pressure for processors lacking multi-origin sourcing contracts or forward coverage.
- Hydrocolloid supply concentration:Binding system dependence on guar and xanthan gum suppliers concentrated in India and China exposes formulations to export restriction risks and price spikes.
- Moisture retention ceiling:Absence of gluten networks limits shelf life extension, constraining distribution radius for ambient loaf formats against modified-atmosphere wheat alternatives.
Strategic Opportunities
- German retail penetration:Bakery innovation around legume flours has established proof points in Berlin and Munich, creating template for expansion into underdeveloped Austrian and Swiss markets.
- Carbon footprint labeling:Pulse sourcing transparency is emerging as a tiered market access barrier, favoring processors with farm-level traceability systems and regenerative agriculture partnerships.
- Perimeter bakery placement:Supermarkets are relocating gluten-free items from center aisles to fresh bakery sections, capturing impulse traffic and reducing comparison shopping against commodity wheat breads.
Industry Challenges
- Certification timeline compression:Simultaneous pursuit of USDA Organic, Non-GMO Project, and gluten-free third-party audits strains quality assurance teams and delays product launches.
- Retrofitting legacy equipment:Conventional wheat-dedicated mixers and ovens require capital-intensive modification to prevent cross-contamination, particularly for mid-scale regional bakeries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lentil Bread Market |
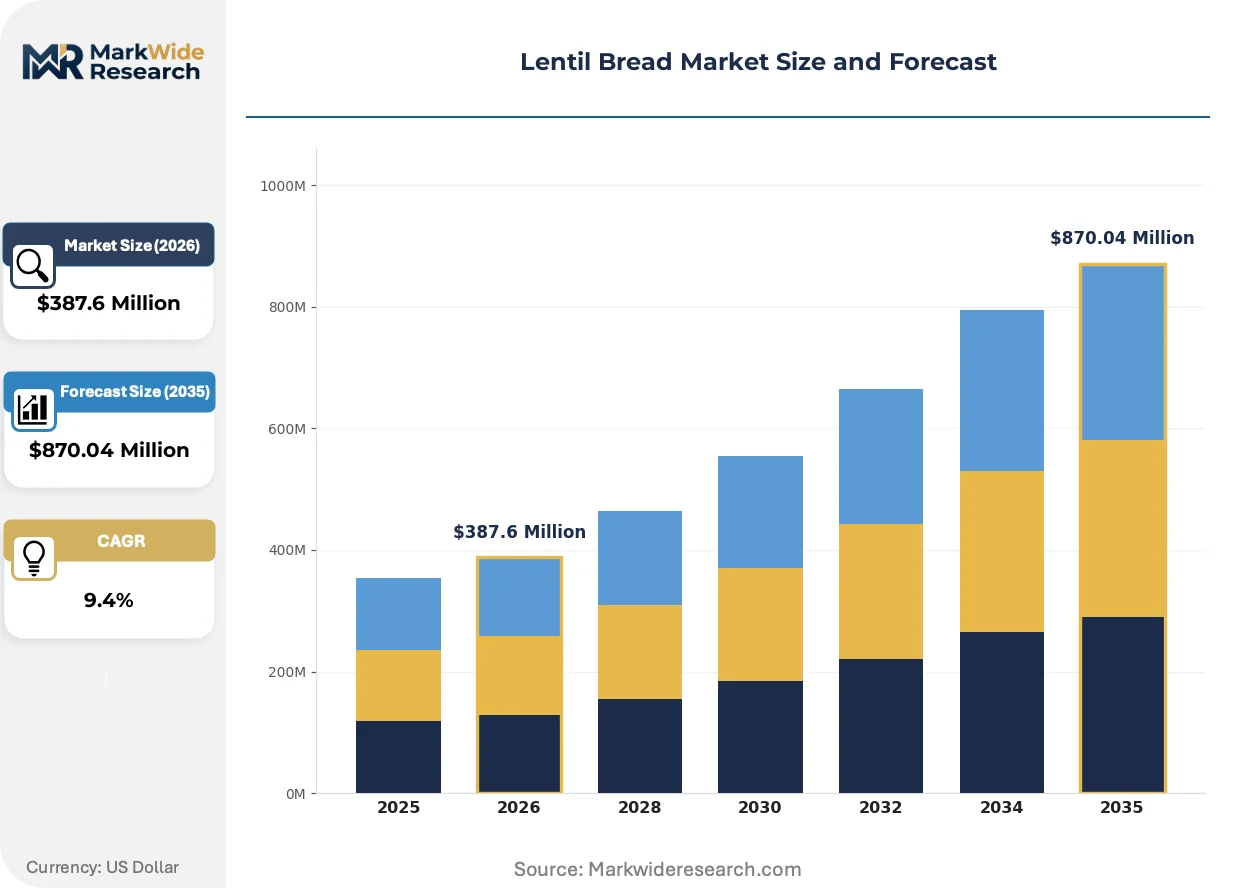
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $870.04 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gluten-Free Bread, Flatbread, Loaf Bread, Tortilla End User: Households, Restaurants, Cafés, Health Food Stores Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales Ingredient Type: Organic Lentils, Traditional Lentils, Seeds, Herbs |
| Companies Covered | Warburtons, Food for Life, Grupo Bimbo, Silver Hills Bakery, One Degree Organic Foods, Flowers Foods, Aryzta, Dave’s Killer Bread, Mondelēz International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lentil Bread Market Shifts & Advancements
Formulation science and distribution architecture are converging to redefine how lentil-based baked goods reach end consumers. Three developments are compressing development cycles and reshaping competitive positioning.
Extrusion technology for lentil protein texturization is modularizing production economics for mid-scale manufacturers. Food ingredient houses are licensing compact extrusion systems to regional bakeries previously excluded by capital barriers. This equipment diffusion is enabling distributed manufacturing models that reduce freight costs and improve freshness positioning against centralized gluten-free production.
The FDA's gluten-free labeling rule is tightening enforcement protocols for ingredient segregation and cleaning validation. Manufacturing facilities are deploying dedicated production suites with physical barriers and air handling separation to maintain sub-20 ppm thresholds. Premium loaf segments are absorbing certification costs through specialty channel pricing power, while economy formats face margin compression.
Health food store staff education is converting browsing behavior into purchase at rates exceeding supermarket self-service environments. Specialty retailers in Portland, Toronto, and Melbourne are deploying trained associates to perimeter bakery sections, displacing center-aisle commodity positioning. This channel behavior is concentrating margin pools with vertically integrated brands capable of supporting field-level training investments.
Lentil Bread Market Segmentation
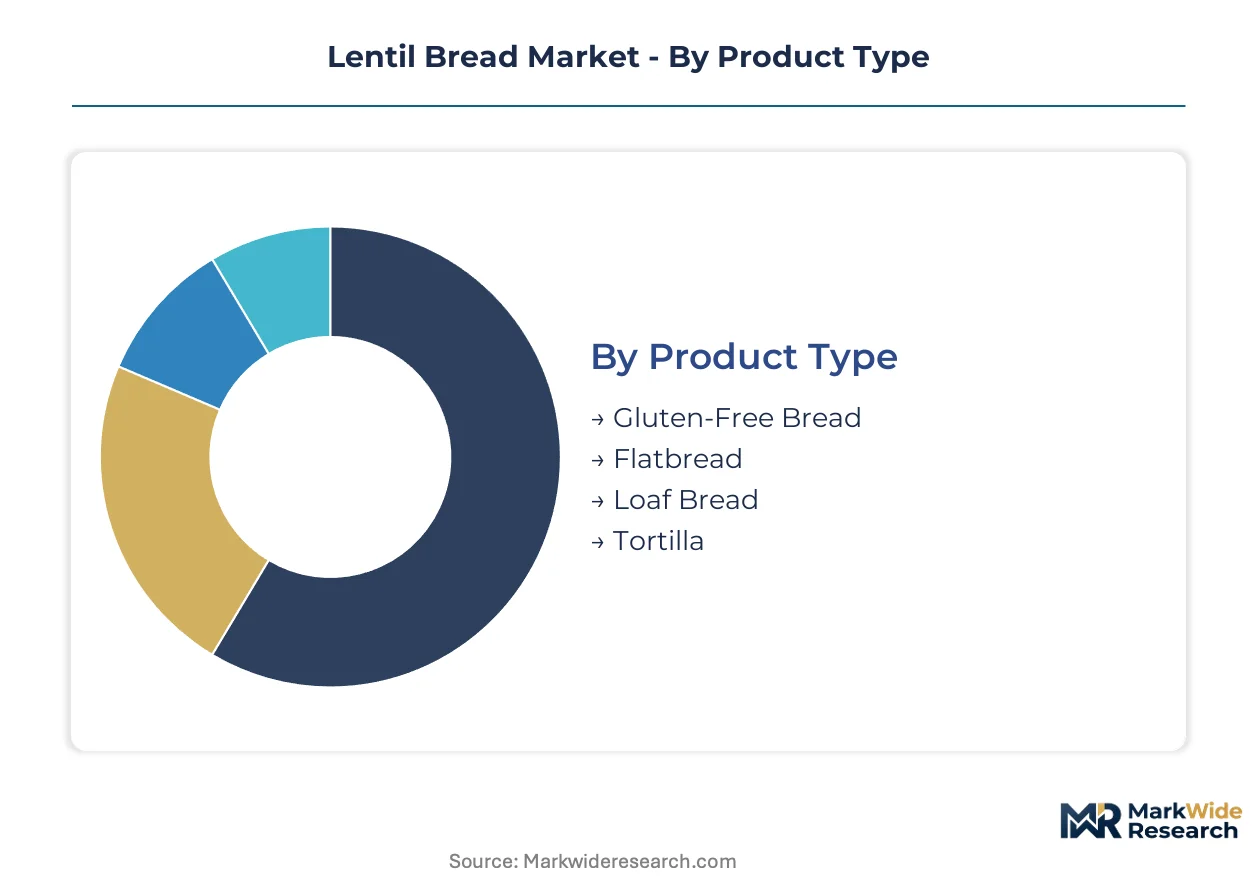
Lentil bread segmentation reveals divergent growth mechanics across product formats and channel access. Volume concentration in conventional retail contrasts with premium capture in specialty and foodservice channels, requiring distinct formulation and certification strategies per segment.
Product Type:
Volume leadership clusters in shelf-stable formats while premium positioning concentrates in fresh and flatbread varieties with shorter ingredient lists.
- Gluten-Free Bread:Formulated with lentil flour, hydrocolloid binders, and leavening systems to achieve sub-20 ppm gluten thresholds per FDA requirements. Demand concentrates in US and German supermarket perimeter sections where celiac-safe certification commands price premiums over commodity wheat alternatives.
- Flatbread:Thin-pressed or sheeted formats with moisture content of 35-45%, enabling foodservice portion control and wrap applications. Restaurant procurement in Berlin, Melbourne, and Toronto metropolitan clusters is absorbing volumes exceeding retail velocity for this format.
- Loaf Bread:Pan-baked sandwich slices with density profiles matching wheat bread for direct substitution.
- Tortilla:Pressed circular formats targeting Latin American cuisine adaptation and breakfast wrap segments.
Mature deployment sits with Gluten-Free Bread. Newer deployment is concentrated in Flatbread.
End User:
Procurement authority fragments across household discretionary spending, commercial kitchen specifications, and retail buyer gatekeeping with divergent certification demands.
- Households:Consumers purchasing for home preparation, prioritizing shelf stability and direct wheat substitution in sandwich applications. German and Australian households show highest per-capita penetration due to established gluten-free retail infrastructure and dietitian recommendation networks.
- Restaurants:Commercial kitchens requiring consistent portioning, holdability, and allergen documentation for liability protection. Portland, Toronto, and Melbourne foodservice clusters are expanding dedicated allergen-friendly menu sections faster than other metropolitan areas.
- Cafés:Coffee-focused establishments seeking grab-and-go breakfast options with clean-label appeal.
- Health Food Stores:Staff-assisted retail environments converting browsing behavior through education on sprouted-grain benefits and low-glycemic indexing.
Volume concentration remains with Households. Margin expansion is accelerating fastest in Restaurants.
Distribution Channel:
Channel selection determines certification burden, freshness positioning, and price realization through differential staffing and inventory turnover.
- Supermarkets:High-velocity retail with perimeter bakery placement capturing impulse traffic and reducing comparison shopping against center-aisle commodity wheat breads. Placement in fresh sections requires shorter shelf-life formats but enables 20-40% price premiums over ambient gluten-free alternatives.
- Specialty Stores:Staffed environments with trained associates explaining protein content, sprouting benefits, and anti-nutrient reduction. Portland, Toronto, and Melbourne specialty retailers are deploying field-level education investments that concentrate margin pools with vertically integrated brands.
- Online Retail:Direct-to-consumer and third-party marketplace fulfillment with subscription model potential for repeat purchase automation.
- Direct Sales:Bakery-owned storefronts and farmers market presence enabling maximum freshness claims and ingredient transparency.
Established infrastructure sits with Supermarkets. Channel expansion is climbing the fastest in Specialty Stores.
Ingredient Type:
Input certification tiers create market access barriers that favor suppliers with farm-level traceability and multi-standard audit capabilities.
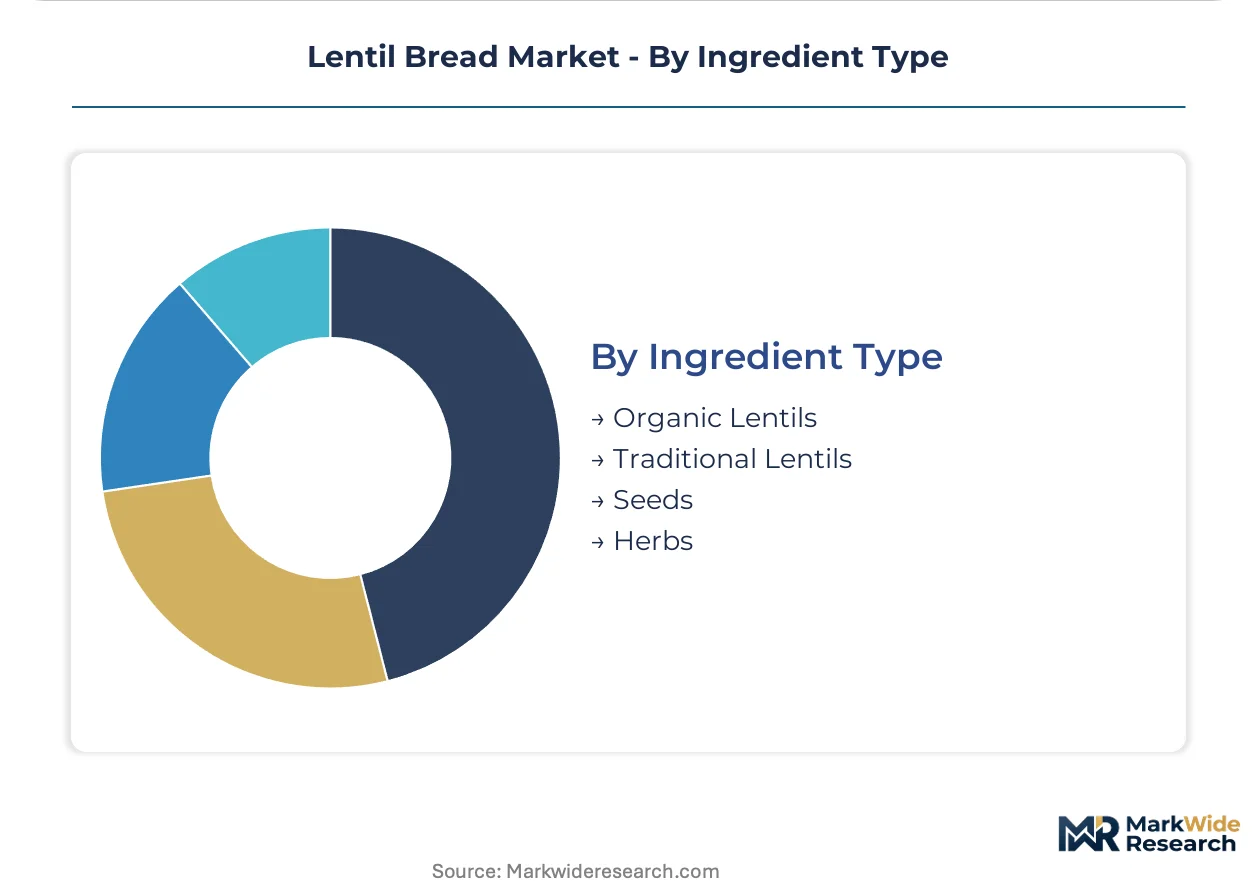
- Organic Lentils:USDA Organic or equivalent certified pulses grown without synthetic pesticides or fertilizers, requiring segregated handling through processing. Supply contracts with Canadian and Australian organic growers are concentrating among processors with backward integration into regenerative agriculture partnerships.
- Traditional Lentils:Conventionally grown pulses with standard agricultural inputs, serving price-sensitive formulations and economy-tier positioning.
- Seeds:Flax, chia, or sunflower additions for texture, omega-3 content, and visual differentiation in artisan positioning.
- Herbs:Rosemary, oregano, or proprietary savory blends for Mediterranean flavor profiles and premium differentiation.
Certification density sits with Organic Lentils. Formulation experimentation is expanding most quickly in Seeds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of lentil flour concentrates in Canadian prairie provinces and Australian grain belts, while consumption clusters in Germany, the United States, and Australia where gluten-free retail infrastructure and dietitian networks have matured.
Germany
Berlin and Munich metropolitan areas drive retail velocity for legume-based bakery innovation, with health food stores expanding dedicated shelf space for sprouted-grain formats. EFSA novel food assessments govern extruded protein applications, creating compliance templates for Austrian and Swiss market entry. Bavarian bakery clusters are piloting carbon footprint labeling on pulse sourcing to capture premium positioning.
United States
FDA enforcement of sub-20 ppm gluten thresholds compels dedicated production suites with physical segregation and third-party audit protocols. Portland, Oregon anchors West Coast specialty retail concentration where trained staff convert browsing into purchase at rates exceeding supermarket self-service. Restaurant procurement in Los Angeles and New York City is absorbing flatbread volumes faster than retail velocity.
Canada
Saskatchewan and Alberta organic lentil harvests supply North American processors, though harvest variability creates margin pressure for manufacturers lacking multi-origin contracts. Health Canada and PMRA jointly regulate pesticide residues on pulse inputs entering gluten-free supply chains. Toronto specialty retailers are deploying field-level education investments that concentrate margin pools with vertically integrated brands.
Australia
TGA oversight of gluten-free labeling aligns with FDA thresholds, enabling export format standardization for US-bound production. Melbourne health food stores represent the deepest specialty channel penetration outside Germany, with staff-assisted conversion rates driving premium capture. Sydney and Brisbane supermarkets are relocating gluten-free items to perimeter bakery sections to reduce comparison shopping.
United Kingdom
FSA gluten-free labeling standards and post-Brexit regulatory divergence create dual compliance burdens for manufacturers serving EU and UK markets. London specialty retail clusters in Camden and Shoreditch are experimenting with regenerative agriculture partnerships for pulse sourcing transparency. Manchester and Birmingham supermarkets are trailing perimeter bakery placement strategies tested in German markets.
Lentil Bread Market Competitive Landscape
Top-tier vendors anchor premium organic and specialty channels, while mid-scale regional bakeries and diversified multinationals occupy standard and economy positioning. The vendor base organizes around three strategic archetypes: sprouted-grain specialists leveraging enzymatic activation expertise, clean-label purists competing through ingredient transparency, and scale-driven manufacturers retrofitting legacy wheat infrastructure for segregated gluten-free production. Dominant competitive moves include backward integration into regenerative agriculture partnerships for supply security and certification timeline compression through simultaneous multi-standard audits.
Within the sprouted-grain specialist tier, Food for Life and Silver Hills Bakery exemplify clean-label positioning through staff-assisted specialty retail channels. Grupo Bimbo occupies a scale-driven position, representing the retrofitting of conventional bakery infrastructure toward segregated gluten-free production lines. These three anchors illustrate how certification density, channel access, and sourcing control separate premium capture from margin compression in lentil-based bakery segments.
| Leading Market Players |
|---|
| Warburtons |
| Food for Life |
| Grupo Bimbo |
| Silver Hills Bakery |
| One Degree Organic Foods |
| Flowers Foods |
| Aryzta |
| Dave's Killer Bread |
| Mondelēz International |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between USDA Organic and conventional lentil inputs splits pricing power across segregated supply chains, with premium tiers absorbing third-party audit costs through specialty channel markups while economy formulations face margin compression from spot-market pulse volatility. This divergence manifests in divergent procurement strategies: premium brands pursue multi-year contracts with Canadian organic growers, while standard-tier processors absorb harvest variability through commodity exchanges.
Pricing Analysis
Short lead-time premiums dominate lentil bread pricing, with fresh perimeter bakery placement commanding 20-40% markups over ambient shelf-stable alternatives due to compressed distribution windows. Three-tier pricing structure across premium, standard, and economy levels reflects certification density, with USDA Organic and Non-GMO Project verification creating access barriers that sustain price premiums in staff-assisted specialty channels. Cost compression in economy tiers is intensifying because Canadian and Australian harvest variability exposes processors lacking forward coverage to spot-price spikes. Households exhibit highest price sensitivity, deferring to private-label alternatives when premiums exceed wheat-bread benchmarks by more than 50%, while restaurants demonstrate lowest sensitivity due to menu-price pass-through mechanisms.
Supply Chain Analysis
Hydrocolloid supply rests on Indian guar gum processors and Chinese xanthan manufacturers, creating binding-system dependencies that expose formulations to export restriction risks. Lentil flour sourcing draws from Canadian prairie provinces and Australian grain belts, with Saskatchewan organic harvests supplying North American premium tiers and Victorian conventional pulses serving Asia-Pacific standard formulations. Single-source vulnerability concentrates in hydrocolloid binders, where alternative suppliers require 12-18 month qualification timelines that prevent rapid substitution. Distribution runs through regional bakery clusters with dedicated gluten-free production suites, bypassing conventional wheat infrastructure to maintain FDA-mandated sub-20 ppm thresholds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organic lentil acreage expansion lags demand growth by 3-4 years, creating structural supply tightness that props pricing across certification tiers and rewards processors with captive sourcing arrangements.
For Market Incumbents: Deepen regenerative agriculture partnerships with Saskatchewan and Alberta organic growers to lock in multi-year supply contracts before acreage competition intensifies. Retrofit legacy wheat-dedicated mixers and ovens with physical segregation barriers to prevent cross-contamination, converting regional bakery infrastructure into dedicated gluten-free production suites that command specialty channel placement premiums.
For New Entrants and Emerging Players: Compact extrusion systems for lentil protein texturization offer capital-efficient entry into regional manufacturing, enabling distributed production models that reduce freight costs and improve freshness positioning against centralized competitors. Target Austrian and Swiss markets with German-proven formulation templates, leveraging EFSA novel food assessment precedents to accelerate regulatory clearance. Deploy direct-to-health-food-store relationships with field-level training investments that convert staff education into purchase conversion.
For Investors and Strategic Acquirers: Re-rating potential sits with sprouted-grain specialists given enzymatic activation expertise scarcity and clean-label conversion rates exceeding conventional gluten-free alternatives. Long-term viability frames around 5-10 year supply security horizons, with backward-integrated processors possessing organic acreage contracts representing prime acquisition targets. Monitor carbon footprint labeling adoption in Bavarian retail clusters as inflection indicator for premium-tier demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Agriculture Partnership | Canadian organic lentil contracts secure supply against harvest variability and ESG positioning. |
| Dedicated Production Suite Retrofit | Physical segregation barriers enable FDA sub-20 ppm compliance and specialty channel access. |
| Compact Extrusion Licensing | Regional bakery equipment diffusion reduces freight costs and improves freshness claims. |
| Carbon Footprint Labeling Program | Bavarian retail pilot creates template for Austrian and Swiss market expansion. |
| Field-Level Staff Training Investment | Portland and Toronto specialty store education converts browsing behavior into premium capture. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with bakery procurement managers, health food store category buyers, organic lentil growers, gluten-free certification auditors, and foodservice distribution specialists. FDA gluten-free labeling guidance, EFSA novel food assessment databases, USDA organic handler certificates, and Canadian Grain Commission export statistics provided validation benchmarks. Bottom-up volume modeling across product formats triangulated against top-down category spending estimates from retail audit providers.
Granularity-level modeling distinguished fresh versus shelf-stable formats, perimeter versus center-aisle placement, and certified organic versus conventional ingredient tiers across the projection horizon. Segmentation dimensions included product type, end-user procurement authority, distribution channel access, and ingredient certification grade. CAGRs derived from trend extrapolation of celiac diagnosis rates, gluten-free retail shelf space expansion, and restaurant allergen-menu adoption curves. Pulse harvest variability coefficients and hydrocolloid price indices fed sensitivity analyses.
Several conditions sit outside the modeled scope, including unforeseen regulatory threshold changes, trade restriction impacts on Indian guar exports, and climate disruption effects on Canadian prairie yields. Forecasts reflect documented assumptions regarding continued FDA enforcement posture and stable EFSA novel food assessment timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Organic Bread Flour Market
Bakery Products
Low-Calorie Pie Market
Bakery Products
Asia-Pacific Baked Food and Cereals Market
Bakery Products
Packaged Bread Market
Bakery Products
Gluten-Free Bread Market
Bakery Products
Bakery Cases Market
Bakery Products
Middle East and Africa Sweet Biscuits Market
Bakery Products
Low-Calorie Toast Market
Bakery Products
Southeast Asia Bakery Products Market
Bakery Products
APMEA Frozen Bakery Products Market
Bakery Products
Layer Cake Mixes Market
Bakery Products
Bread Market
Bakery Products
Cake Concentrate Market
Bakery Products
Bakery Flavors Market
Bakery Products
Pizza Crust Mix Market
Bakery Products
Pizza Dough Balls Market