
 GCC Frozen Bakery Products Market | 2026-2036
GCC Frozen Bakery Products Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Frozen Bakery Products Market Insights
Saudi Arabia is narrowing its reliance on imported frozen bakery inputs through industrial park expansions near Riyadh and Jeddah. Almarai Company leverages integrated dairy and bakery supply chains to dominate domestic retail freezers. Sunbulah Group anchors its position through deep distribution across Gulf cooperative society stores. Americana Group Inc. competes via specialized production for its own quick-service restaurant network.
GCC frozen bakery products comprise dough-based goods preserved at sub-zero temperatures through blast or cryogenic freezing, typically par-baked or fully baked, with shelf lives extending twelve to twenty-four months depending on formulation and packaging barriers. These products serve commercial kitchens seeking labor reduction, portion consistency, and waste minimization without on-site fermentation infrastructure. Breads and pastries capture the dominant volume share, reflecting daily consumption rituals and breakfast-centric dining patterns across Gulf households. Foodservice channels sustain the fastest throughput growth, as hotel groups and airline caterers shift from scratch production to thaw-and-serve models. Flash freezing technology leads capital deployment, since rapid temperature descent preserves crumb structure and sensory attributes superior to conventional methods.
SFDA in Saudi Arabia and the UAE's national food control authority enforce halal integrity, additive limits, and cold-chain documentation that determine market access for imported and locally manufactured frozen bakery goods. The GCC Standardization Organization harmonizes labeling and shelf-life declaration requirements, reducing regulatory friction for pan-regional suppliers. Stakeholders must monitor evolving fortification mandates and single-use packaging restrictions that could reformulate cost structures and equipment requirements.
Market Dynamics
Flash freezing technology is compressing production cycles across GCC frozen bakery supply chains, forcing capital reallocation toward cryogenic tunnel systems that preserve sensory integrity while eliminating on-site fermentation infrastructure for foodservice buyers.
Growth Catalysts
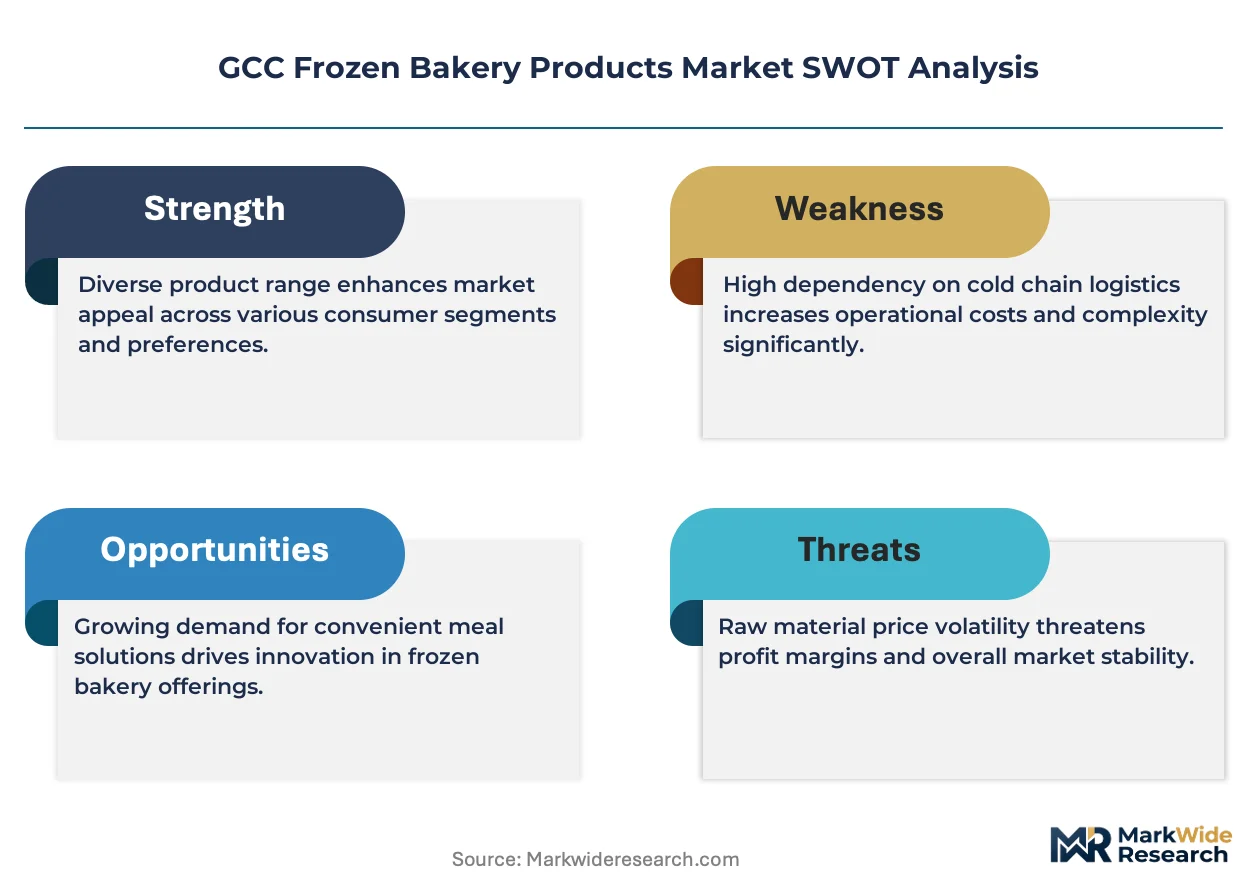
- Foodservice channel expansion:Quick-service restaurant chains across Saudi Arabia and the UAE are eliminating scratch kitchens in favor of thaw-and-serve par-baked inventory, compressing labor costs and portion variance.
- SFDA halal certification harmonization:Unified documentation standards across Saudi Arabia are reducing cross-border inspection friction for frozen dough imports from neighboring GCC states.
- Blast freezing capex subsidies:Industrial park operators near Riyadh and Jeddah are offering equipment financing to localize production capacity and narrow import dependency.
Market Restraints
- Natural gas price volatility:Cryogenic freezing operations depend on liquid nitrogen and carbon dioxide feedstocks whose Gulf contract prices fluctuate with petrochemical benchmark movements.
- European equipment supplier concentration:Tunnel freezer and spiral blast systems are sourced from a narrow base of German and Dutch manufacturers, creating delivery backlogs and currency exposure.
- Cold-chain integrity gaps:Last-mile refrigerated transport in secondary Saudi cities lacks real-time temperature logging, triggering SFDA detention and product write-offs.
Strategic Opportunities
- Airline catering pivot:Gulf carriers expanding long-haul route networks are sourcing individually quick-frozen artisan breads and laminated pastries for premium cabin service.
- Hotel group central kitchen consolidation:Property management companies across Dubai and Abu Dhabi are aggregating procurement through single-source frozen bakery contracts to standardize guest experience.
- Fortification mandate alignment:GCC Standardization Organization draft guidelines on vitamin D and iron enrichment in staple breads create formulation differentiation for early adopters.
Industry Challenges
- Cryogenic technician scarcity:Maintenance and calibration of automated freezing tunnels requires specialized refrigeration engineering skills that Gulf technical institutes have not scaled to match equipment deployment.
- Halal certification timeline compression:SFDA and MOHAP audit backlogs are extending product registration cycles, delaying market entry for reformulated SKUs and seasonal varieties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Frozen Bakery Products Market |
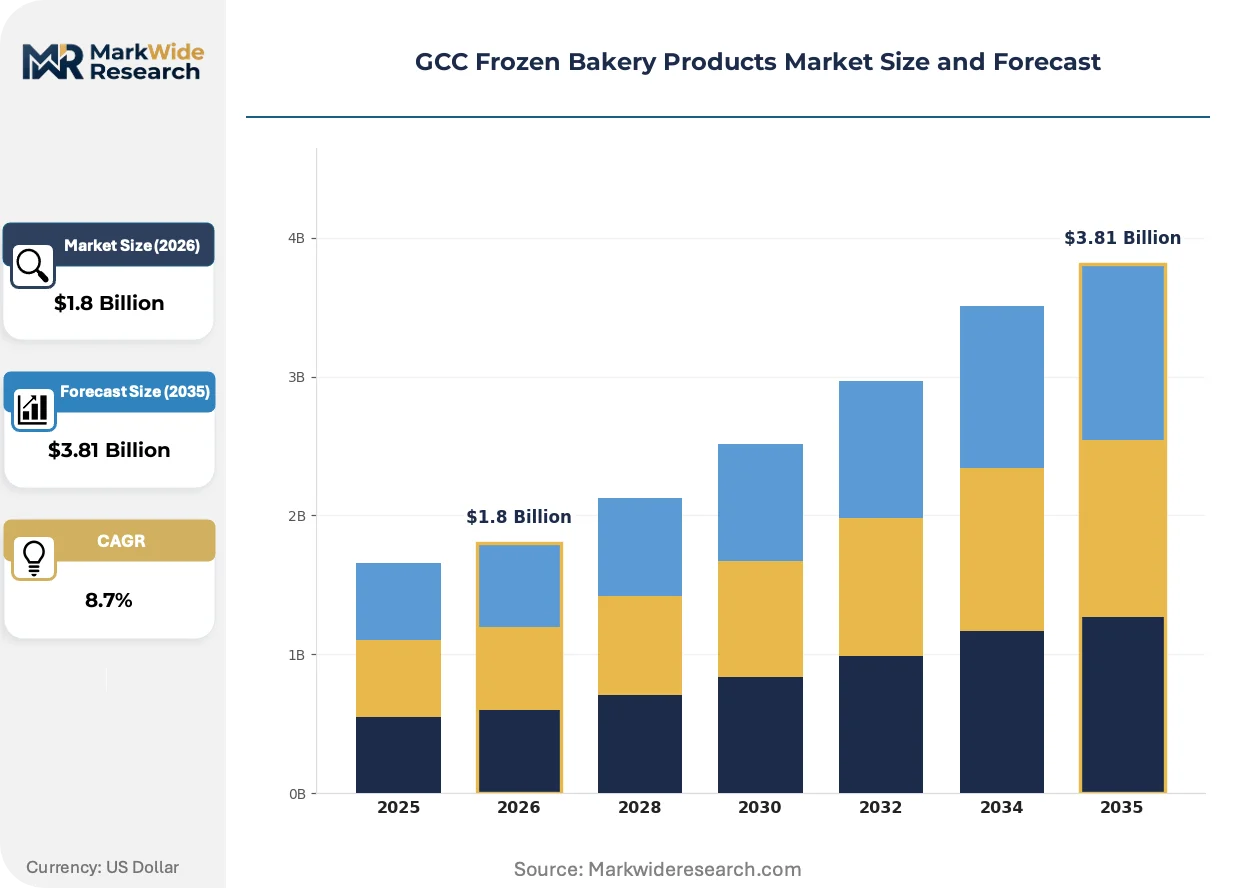
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breads, Pastries, Doughnuts, Pizza Bases End Use: Foodservice, Retail, Hospitality, Catering Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Wholesalers Technology: Flash Freezing, Blast Freezing, Cryogenic Freezing, Plate Freezing |
| Companies Covered | Almarai Company, Sunbulah Group, IFFCO, Americana Group Inc., Switz Group, Agthia Group, Dofreeze LLC, Modern Bakery LLC, Al Jadeed Bakery, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Frozen Bakery Products Market Trends and Innovations
Digital twin technology is penetrating frozen bakery production lines, enabling real-time simulation of thermal profiles before physical batch commitment and reducing waste from freezing parameter misalignment.
Cryogenic nitrogen injection systems are virtualizing traditional blast freezing workflows by embedding rapid temperature descent directly into mixing and forming stages. European equipment integrators are retrofitting existing lines across Jeddah industrial zones with modular injection nozzles. This convergence is compressing the capital footprint required for flash-freezing capacity and enabling smaller batch runs for specialty SKUs.
SFDA and MOHAP are tightening additive disclosure requirements for frozen dough emulsifiers and preservatives, mandating QR-code traceability from flour mill to retail freezer. Reformulation costs are concentrating among suppliers serving private-label retail chains. Saudi manufacturers are accelerating clean-label transitions to preempt enforcement actions and secure shelf placement in cooperative society stores.
Consolidated procurement desks at hotel management groups are displacing decentralized bakery purchasing across individual properties. Volume aggregation is compressing supplier margins while demanding extended payment terms and dedicated freezer inventory at distributor warehouses. This pattern is most visible across Dubai's hospitality corridor, where three property groups now control a majority of frozen pastry procurement decisions.
GCC Frozen Bakery Products Market Segmentation
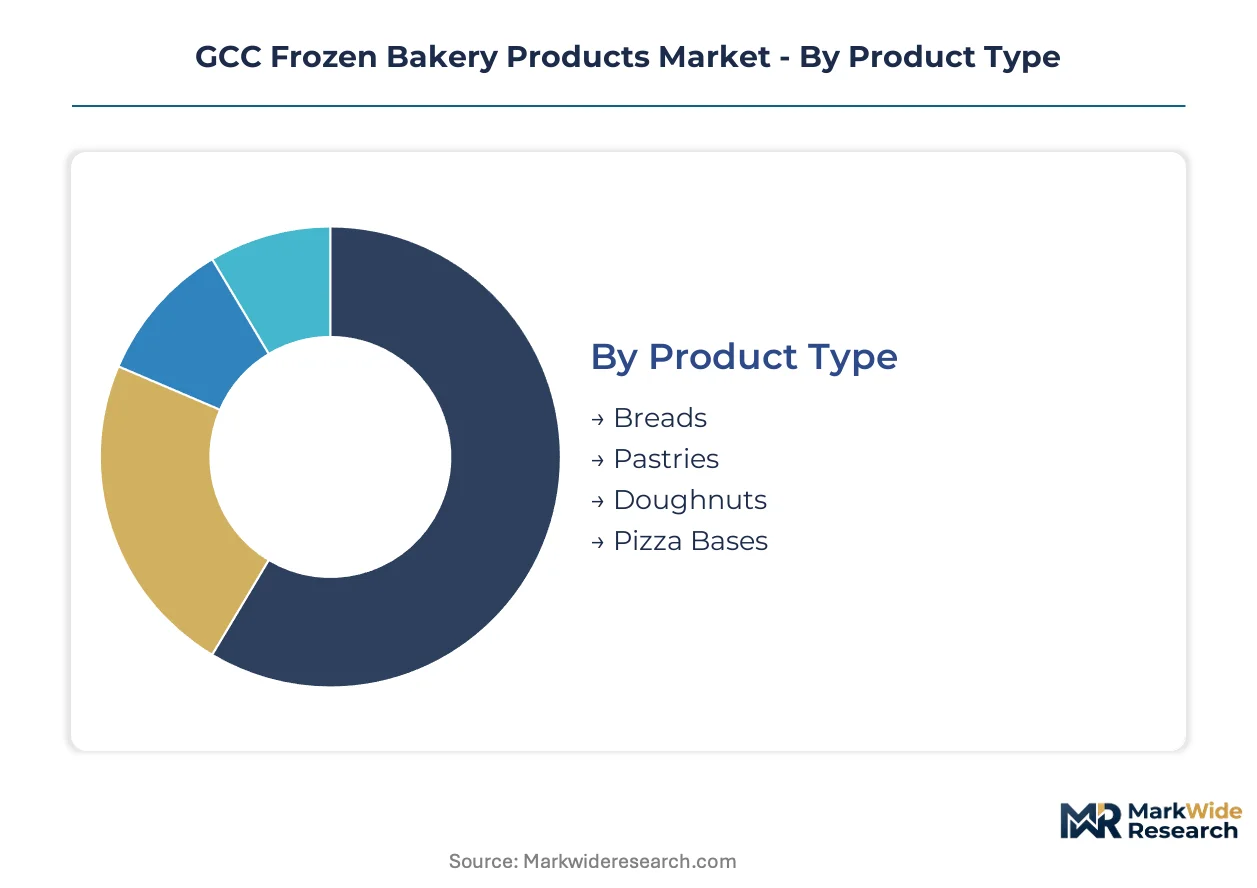
Segmentation in the GCC frozen bakery market reveals distinct operational requirements across product formats and customer channels. Each dimension shapes capital deployment, cold-chain specifications, and regulatory compliance pathways differently.
Product Type:
Product variety spans from daily staple consumption to specialized foodservice inputs, with formulation and shelf-life specifications varying dramatically by category.
- Breads:Par-baked loaves and rolls dominate procurement volumes across Saudi quick-service restaurant chains, where thaw-and-serve protocols eliminate on-site proofing. SFDA fortification mandates for vitamin D and iron enrichment are reformulating standard white and brown bread lines.
- Pastries:Croissants, Danish, and laminated products command premium positioning in UAE hotel breakfast buffets and airline premium cabins. Cryogenic freezing preserves butter layer integrity through long-haul distribution to secondary Saudi cities.
- Doughnuts:Yeast-raised and cake varieties serve convenience store coffee programs across Dubai and Abu Dhabi retail corridors.
- Pizza Bases:Thin-crust and deep-pan formats supply independent pizzerias and ghost kitchen operators seeking portion consistency without dough preparation labor.
The dominant share belongs to Breads, while Pastries is closing the gap fastest.
End Use:
Customer archetypes range from high-volume institutional buyers to fragmented household consumption, each demanding different packaging formats and delivery frequencies.
- Foodservice:Quick-service restaurant chains and airline caterers across Saudi Arabia and the UAE are aggregating procurement through centralized thaw-and-serve contracts. Flash freezing technology enables menu consistency without kitchen fermentation infrastructure.
- Hospitality:Hotel groups in Dubai and Abu Dhabi are consolidating bakery purchasing through single-source frozen contracts to standardize guest experience across property portfolios.
- Retail:Cooperative society stores and supermarket chains stock private-label frozen dough for home baking occasions.
- Catering:Event service providers source par-baked items for large-scale banquet execution with minimal on-site labor.
Foodservice channels absorb the largest volume, though Hospitality is expanding most quickly as hotel groups centralize procurement.
Distribution Channel:
Route-to-market structures reflect cold-chain maturity and buyer concentration patterns across Gulf urban corridors.
- Supermarkets:Hypermarket chains across Riyadh and Jeddah maintain dedicated freezer aisles for branded and private-label bakery, with Almarai and Sunbulah commanding shelf placement through integrated supply chains.
- Wholesalers:Foodservice distributors operate multi-temperature warehouses serving restaurant chains and hotel groups with scheduled delivery frequencies.
- Convenience Stores:Smaller format retailers in secondary Saudi cities rely on frozen pastry and doughnut SKUs for coffee companion sales.
- Online Retail:E-grocery platforms are piloting frozen bakery delivery with insulated packaging, though last-mile cold-chain integrity remains inconsistent outside major UAE metros.
Supermarkets control the widest penetration, while Online Retail is gaining share fastest despite operational constraints.
Technology:
Freezing methodology determines sensory preservation, capital intensity, and operational flexibility for manufacturers serving diverse customer specifications.
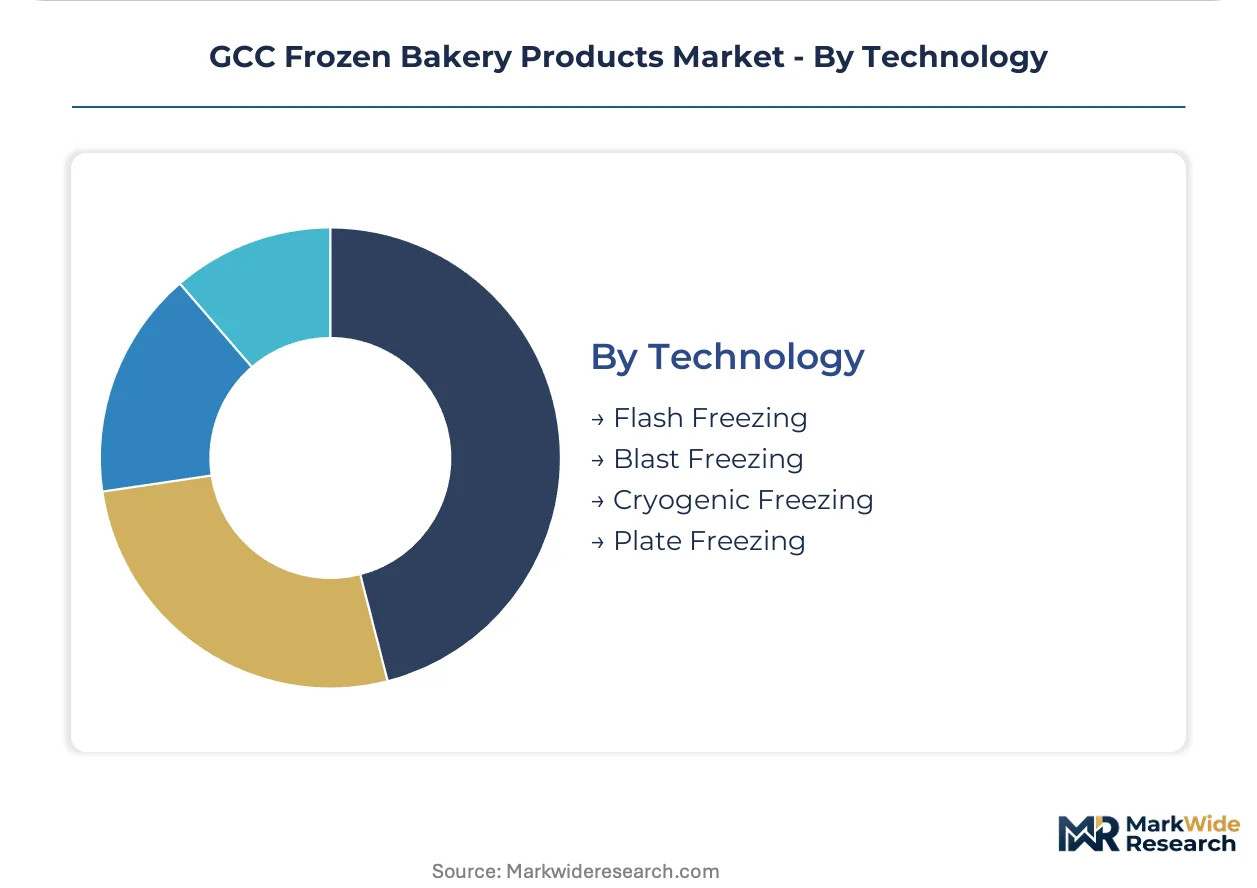
- Flash Freezing:Rapid temperature descent through cryogenic tunnels preserves crumb structure and moisture distribution in artisan breads and laminated pastries. European equipment suppliers from Germany and the Netherlands dominate system installations across Jeddah industrial zones.
- Blast Freezing:Conventional forced-air systems serve high-volume commodity production lines with lower capital requirements but extended freezing cycles.
- Cryogenic Freezing:Liquid nitrogen injection enables smaller batch runs for specialty SKUs, compressing equipment footprints in retrofit production environments.
- Plate Freezing:Contact freezing systems handle uniform dough blocks and pizza bases with consistent thermal transfer and minimal dehydration.
Flash Freezing leads capital deployment, while Cryogenic Freezing is climbing fastest as manufacturers seek flexible batch capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA halal certification protocols anchor Saudi Arabia's regulatory framework, establishing compliance benchmarks that neighboring Gulf states reference for cross-border frozen bakery trade. This regulatory gravity shapes formulation standards and cold-chain documentation across the entire GCC corridor.
Saudi Arabia
Quick-service restaurant chains and hotel groups in Riyadh and Jeddah drive frozen bread and pastry procurement volumes. SFDA enforces vitamin D and iron fortification mandates in staple bread lines, reformulating standard SKUs. Industrial parks near Riyadh and Jeddah attract localization investments with blast freezing equipment subsidies.
United Arab Emirates
MOHAP regulates additive disclosure for frozen dough emulsifiers, mandating QR-code traceability from flour mill to retail freezer. Dubai's hospitality corridor sees hotel management groups consolidating bakery procurement through single-source frozen contracts. Abu Dhabi property portfolios standardize guest experience via centralized frozen pastry agreements.
Kuwait
Cooperative society stores anchor retail distribution for private-label frozen dough products. The national food control authority aligns with GCC Standardization Organization labeling harmonization. Industrial zones south of Kuwait City host emerging production capacity serving domestic foodservice channels.
Qatar
Airline catering operations for expanding long-haul route networks source individually quick-frozen artisan breads and laminated pastries. Qatari regulatory frameworks mirror SFDA halal integrity standards. Doha-based hospitality developments drive demand for premium frozen pastry SKUs in hotel breakfast programs.
Oman
Secondary city retail corridors rely on frozen pastry and doughnut SKUs for convenience store coffee companion sales. Cold-chain infrastructure gaps in last-mile distribution create compliance challenges for temperature-sensitive imports. Muscat industrial areas see gradual production localization to narrow import dependency.
GCC Frozen Bakery Products Market Competitive Landscape
Capability concentration sits with integrated dairy-bakery conglomerates; scale advantage sits with diversified foodservice suppliers. The market structures around three tiers: vertically integrated national champions controlling retail freezer placement, specialized foodservice producers serving captive restaurant networks, and regional distributors leveraging cooperative society relationships. Dominant competitive moves include industrial park capacity expansion near Riyadh and Jeddah, and strategic partnerships with European equipment suppliers for cryogenic tunnel installations.
Among Saudi-based integrated producers, Almarai Company exemplifies the vertically integrated national champion archetype through combined dairy and bakery supply chain control. Sunbulah Group occupies a position within the cooperative society distribution tier, anchoring shelf placement across Gulf retail channels. Americana Group Inc. represents the captive foodservice producer model, with specialized production alignment to quick-service restaurant network requirements. These three players collectively illustrate the market's structural segmentation between retail freezer dominance, distribution depth, and foodservice integration.
| Leading Market Players |
|---|
| Almarai Company |
| Sunbulah Group |
| IFFCO |
| Americana Group Inc. |
| Switz Group |
| Agthia Group |
| Dofreeze LLC |
| Modern Bakery LLC |
| Al Jadeed Bakery |
| Others |
Pricing and Supply Chain Analysis
German and Dutch equipment suppliers for cryogenic tunnel systems command premium positioning in capital expenditure negotiations, compressing margin pools for GCC manufacturers seeking flash-freezing capacity while foodservice buyers extract volume discounts through consolidated procurement desks.
Pricing Analysis
Price spreads between Riyadh and Dubai reflect logistics cost differentials and local regulatory compliance burdens rather than product quality variance. Three-tier pricing structure across artisan laminated pastries, standard par-baked breads, and commodity pizza bases tracks cryogenic processing intensity and halal certification tier. Pricing pressure stems from hotel group procurement consolidation demanding extended payment terms and dedicated freezer inventory. Quick-service restaurant chains exhibit highest price sensitivity due to standardized menu cost targets, while airline caterers accept premium positioning for sensory consistency.
Supply Chain Analysis
European export controls on advanced refrigeration compressor technology limit system upgrade pathways for Saudi manufacturers retrofitting Jeddah industrial zones. Supply concentration centers on Germany, the Netherlands, and Denmark for tunnel freezer engineering, while liquid nitrogen feedstocks draw from Gulf petrochemical complexes. Wheat flour and butter derivatives constitute critical input dependencies with exposure to Black Sea supply disruptions. Distribution runs through multi-temperature wholesalers serving foodservice channels and cooperative society retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from cyclical compression as foodservice channel reopening and airline route expansion restore throughput volumes to pre-contraction levels.
For Market Incumbents: Pre-empt margin erosion from hotel procurement consolidation by securing captive supply agreements with quick-service restaurant networks and investing in SFDA clean-label certification ahead of enforcement tightening. Anchor shelf placement in cooperative society stores through backward integration into flour milling. For New Entrants and Emerging Players: Secondary Saudi cities lacking real-time cold-chain logging represent the most penetrable entry point for regional distributors offering temperature-validated delivery services. Target ghost kitchen operators and independent pizzerias with flexible batch cryogenic freezing for specialty pizza base SKUs, leveraging modular nitrogen injection systems to minimize capital footprint. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale manufacturers with established halal certification pathways and underutilized blast freezing capacity ripe for cryogenic retrofit. Long-term viability hinges on fortification mandate alignment and airline catering contract renewals. Monitor SFDA audit backlog resolution timelines as the signal for product registration velocity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Tunnel Installation | European equipment partnerships with German suppliers secure sensory preservation capabilities for laminated pastry lines. |
| Halal Certification Acceleration | SFDA pre-clearance investment preempts competitor exclusion from cooperative society freezer placement. |
| Foodservice Contract Consolidation | Single-source agreements with Dubai hotel groups displace fragmented property-level procurement decisions. |
| Industrial Park Localization | Riyadh and Jeddah capacity expansion narrows import dependency and captures equipment financing subsidies. |
| Clean-Label Reformulation | QR-code traceability compliance ahead of MOHAP enforcement secures private-label retail shelf positioning. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with frozen bakery plant managers, foodservice procurement directors, hotel group supply chain heads, and SFDA regulatory affairs specialists; and secondary validation through customs trade databases, GCC Standardization Organization draft guidelines, industrial park investment disclosures, and SEC filings from listed dairy-bakery conglomerates. Bottom-up volume triangulation across product type and end-use segments was cross-checked against top-down market sizing from channel throughput estimates.
Forecast inputs span product type segmentation, freezing technology deployment, and distribution channel evolution across the analysis window. CAGRs were derived from trajectory fitting to historical channel volume patterns and projected foodservice outlet expansion. Modeled dimensions include bread versus pastry formulation intensity, flash versus blast freezing capital allocation, and foodservice versus retail channel mix. Industry-specific inputs incorporate airline catering route network announcements and hotel group property pipeline disclosures.
Macroeconomic conditions sit as an overlay; deviation in natural gas contract pricing and wheat import tariff regimes would shift the trajectory. Forecasts reflect assumptions around SFDA enforcement consistency and European equipment delivery schedules. Material shifts in cryogenic feedstock cost structures or halal certification timeline compression would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Cake Base Discs Market
Bakery Products
Low Fat Baked Goods Market
Bakery Products
Asia-Pacific Frozen Bakery Market
Bakery Products
Pancakes Market
Bakery Products
Cream Cheese Frosting Market
Bakery Products
Low Calorie Bread Market
Bakery Products
Fortified Bakery Market
Bakery Products
Gulf Cooperation Council Frozen Bakery Products Market
Bakery Products
Global Cake Mix Market
Bakery Products
Bakery Contract Manufacturing Market
Bakery Products
Bread Dough Improver Market
Bakery Products
Low Fat Chocolate Cake Market
Bakery Products
Bakery Conditioner Market
Bakery Products
Gluten-Free Bakery Premixes Market
Bakery Products
Organic Bread Flour Market
Bakery Products
Pastry Premixes Market