
 Healthy Biscuits Market | 2026-2036
Healthy Biscuits Market Size, Share, and Industry Trends Forecast 2026-2036
Healthy Biscuits Market Analysis
E-commerce grocery platforms are reshaping how healthy biscuits reach consumers in tier-one and tier-two cities. Mondelēz International leverages its direct-to-retail distribution to sustain shelf presence across modern trade formats. Britannia Industries anchors its competitive position through deep penetration into India's traditional kirana network. Parle Products competes on price-accessible whole grain offerings that occupy mid-market shelf space effectively.
Healthy biscuits denote baked flour-based products formulated with reduced sugar, elevated fiber content, functional ingredients such as oats or chia seeds, and minimal artificial additives, produced through controlled-temperature baking to preserve nutrient density. These products serve consumers seeking convenient snacking alternatives aligned with metabolic health and dietary restriction requirements. Gluten-free and whole grain product types lead volume contribution, with gluten-free variants recording the fastest expansion as celiac awareness spreads and clean-label preferences intensify among health-conscious buyers. Nut-based ingredient formulations command premium positioning, while seed-based alternatives gain traction among athletes seeking protein-dense portable nutrition.
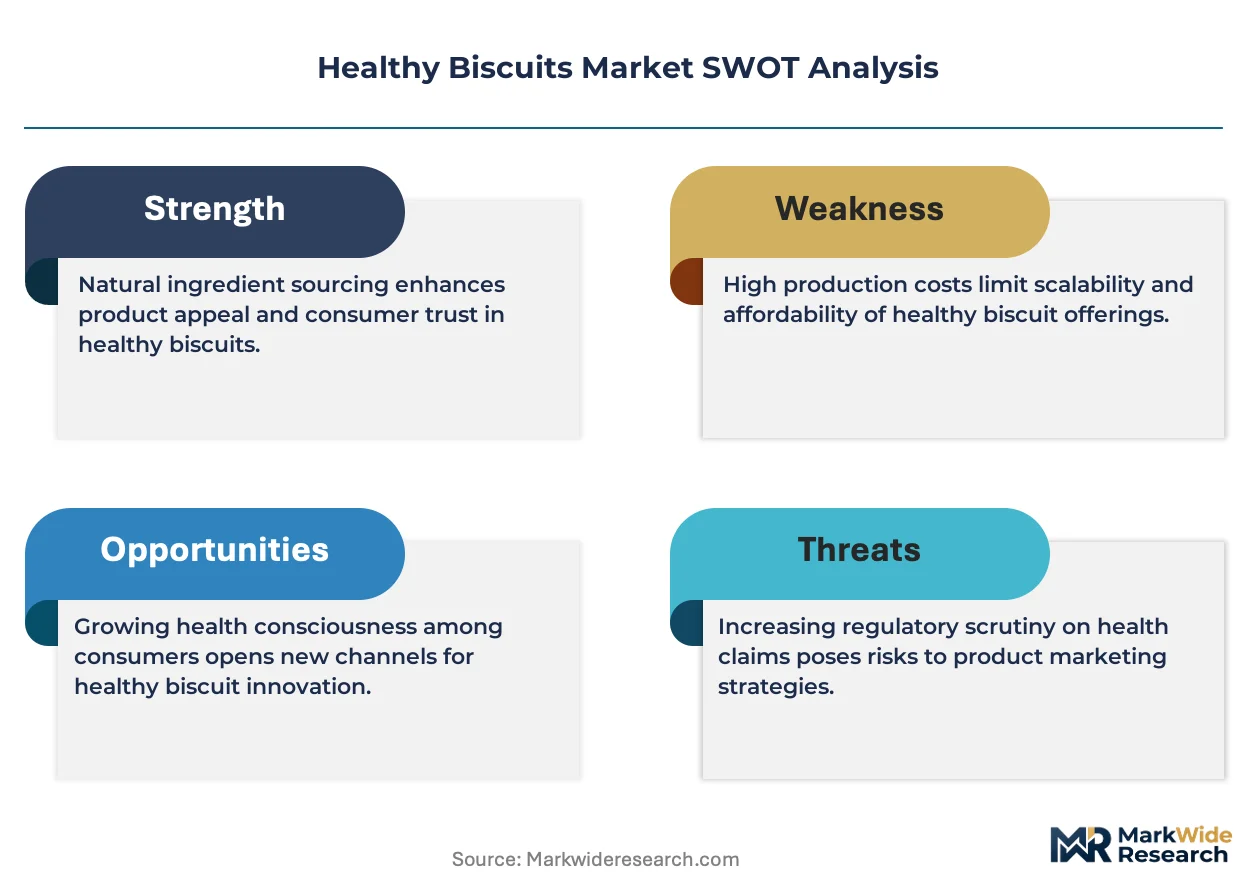
FSSAI labeling mandates in India, EFSA health claim protocols across Europe, and FDA nutritional disclosure rules in the United States collectively elevate compliance costs while filtering out substandard formulations. These frameworks reward manufacturers with certified clean-label portfolios and penalize opaque ingredient sourcing. Stakeholders must monitor evolving glycemic index certification standards and regional sugar taxation proposals that threaten to recalibrate formulation economics and pricing power across priority markets.
Market Dynamics
Clean-label certification requirements from India's FSSAI are forcing manufacturers to reformulate recipes and rebuild supplier networks around traceable ingredient sourcing, compressing margins for mid-tier producers while rewarding vertically integrated players with captive milling operations.
Growth Catalysts
- Urban metabolic health awareness:India's tier-one cities generate concentrated demand for low-glycemic index formulations as diabetes prevalence climbs among white-collar professionals seeking convenient workplace snacking.
- FSSAI labeling mandates:India's food safety regulator mandates nutritional transparency that filters out opaque competitors and rewards certified clean-label portfolios with retail shelf priority.
- Oat and chia seed processing advances:Mechanical stabilization techniques now preserve functional nutrient density through controlled-temperature baking, enabling premium positioning for fiber-dense formulations.
Market Restraints
- Wheat and alternative flour cost volatility:Input price swings for gluten-free flours compress formulation economics and constrain pricing flexibility for mid-market producers.
- Specialty ingredient supply concentration:Chia seed sourcing clusters in select Latin American growing regions, exposing manufacturers to climate-driven harvest variability and freight cost spikes.
- Clean-label certification timelines:FSSAI's multi-stage approval process for novel ingredient claims extends product launch cycles and defers revenue recognition.
Strategic Opportunities
- Tier-two and tier-three city expansion:India's secondary urban corridors including Pune, Hyderabad, and Ahmedabad present underpenetrated demand for packaged healthy snacking alternatives.
- E-commerce direct-to-consumer channels:Platform-native brands bypass traditional kirana network dependence and capture margin through subscription-based replenishment models.
- Protein-fortified athletic positioning:Seed-based formulations targeting runners and gym enthusiasts command premium shelf space in sports nutrition retail formats.
Industry Challenges
- Formulation scientist talent scarcity:India's food technology programs produce insufficient graduates skilled in low-temperature baking and functional ingredient stabilization.
- Legacy equipment retrofit requirements:Existing biscuit ovens require capital-intensive modification to achieve precise temperature control for nutrient preservation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthy Biscuits Market |
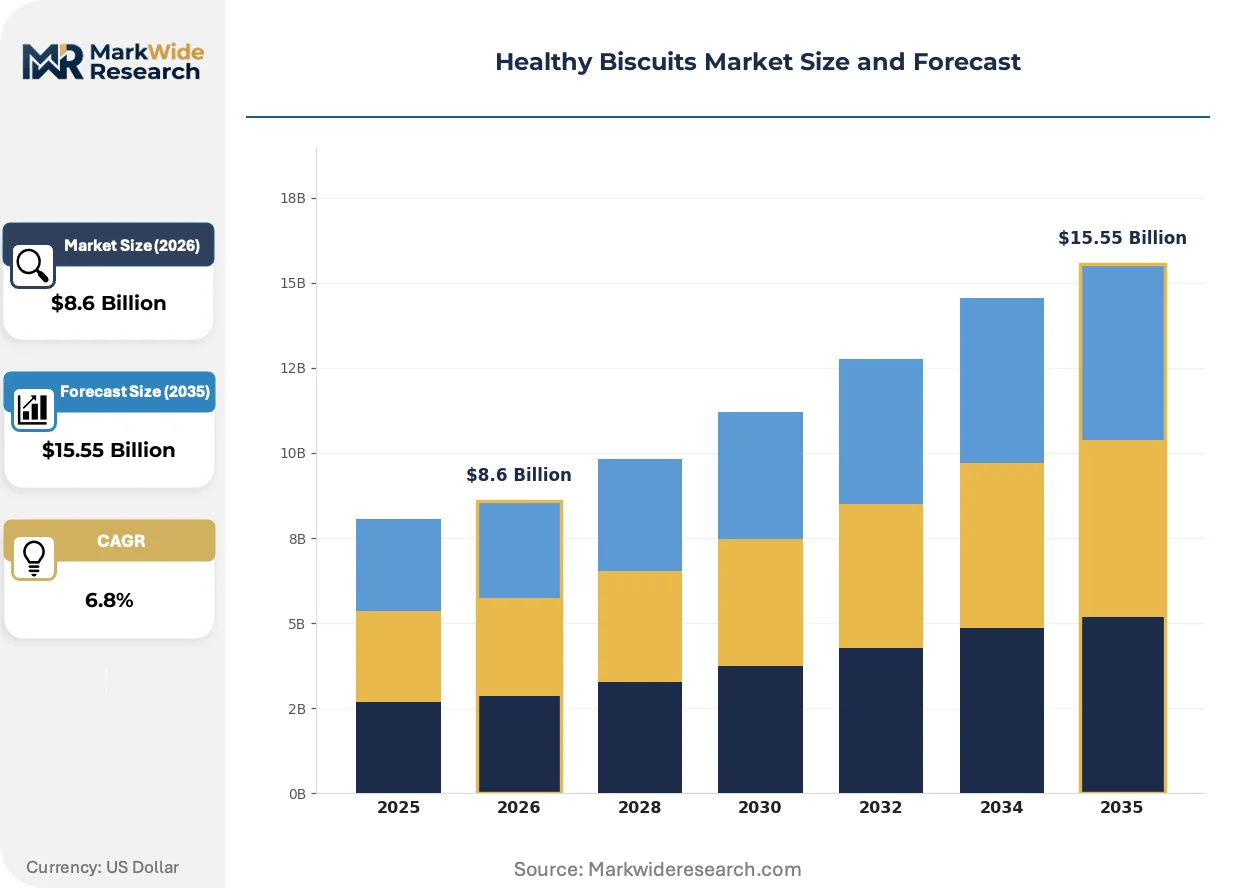
| Market Size in 2026 | $8.6 Billion |
| Market Size in 2035 | $15.55 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gluten-Free, Whole Grain, Organic, Sugar-Free Ingredient Type: Nut-Based, Seed-Based, Legume-Based, Fruit-Based Packaging Type: Resealable Bags, Boxes, Jars, Eco-Friendly Pouches Consumer Type: Health-Conscious, Diabetics, Athletes, Children |
| Companies Covered | ITC Limited, Pladis, Mondelēz International, Grupo Bimbo, Nestlé, Britannia Industries, General Mills, Kellogg's, Parle Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthy Biscuits Market Emerging Trajectories
Ingredient science and distribution architecture are converging to redefine how healthy biscuits reach Indian consumers, with technology-enabled traceability and channel-specific formulation emerging as decisive competitive differentiators.
Controlled-temperature baking technology is hybridizing traditional biscuit production with nutrient preservation science. Premium manufacturers in Mumbai and Delhi are retrofitting ovens with precision thermal management to maintain fiber integrity and vitamin stability. This convergence is enabling clean-label claims that command retail price premiums while compressing the addressable market for conventional high-heat processing equipment.
FSSAI's evolving glycemic index certification framework is mandating clinical validation for metabolic health claims. Manufacturers must now submit third-party testing documentation linking specific formulations to measurable blood glucose response. India's metropolitan retail chains are responding by prioritizing certified SKUs in planogram negotiations, effectively gatekeeping shelf access for unsubstantiated products.
Quick-commerce platforms are fragmenting bulk purchasing patterns into immediate-need replenishment cycles. Urban professionals in Bangalore and Gurgaon now order single-serve healthy biscuit packs through delivery apps rather than stocking pantries through monthly kirana purchases. This behavioral shift is compressing packaging run sizes and forcing manufacturers to reconfigure production scheduling around micro-lot flexibility.
Healthy Biscuits Market Segmentation
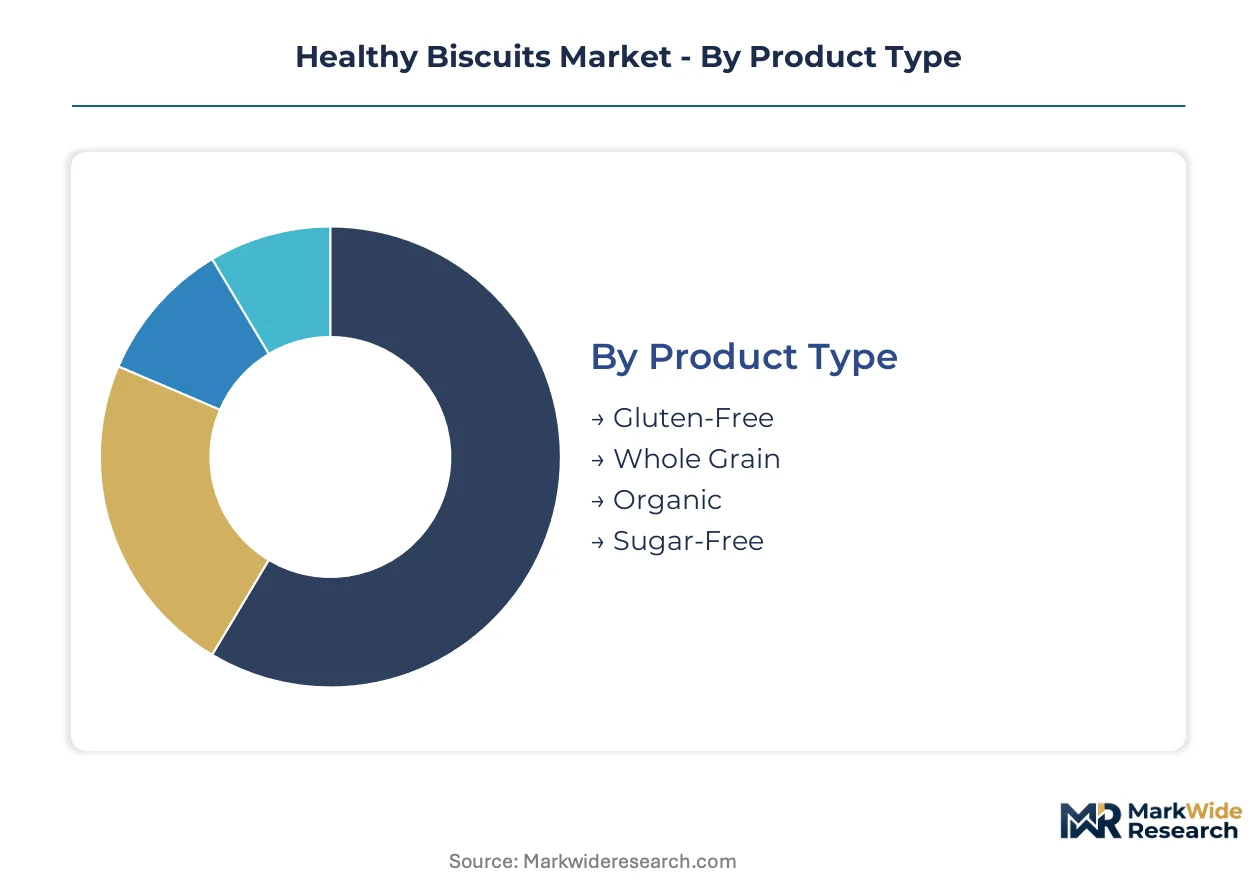
Segmentation in the healthy biscuits market reveals how formulation science, packaging innovation, and consumer health status intersect to create distinct commercial battlegrounds. Manufacturers must align R&D investment and distribution strategy with the specific technical and regulatory requirements of each segment cluster.
Product Type:
Mature segments anchor revenue stability while emerging categories reshape competitive positioning through certification premiums.
- Gluten-Free:Formulations utilize rice flour, sorghum, or millet bases with xanthan gum binding systems to replicate wheat texture. Demand concentrates in Mumbai and Delhi among diagnosed celiac patients and clean-label seekers, with FSSAI's allergen disclosure rules accelerating shelf access for certified variants. Clinical validation requirements for glycemic claims extend launch timelines but defend premium pricing power.
- Whole Grain:Retains bran and germ fractions through controlled milling to preserve fiber density and B-vitamin content. Bangalore's white-collar workforce drives workplace snacking demand for sustained energy release formulations, though wheat cost volatility compresses margin flexibility for mid-tier producers without captive milling operations.
- Organic:Requires FSSAI-certified organic ingredient sourcing with full traceability documentation and zero synthetic pesticide residues.
- Sugar-Free:Relies on erythritol, stevia, or monk fruit sweetening systems with glycemic index testing protocols for metabolic health claims.
Whole grain handles the majority of throughput; gluten-free is expanding most quickly on share.
Ingredient Type:
Cost tier stratification separates premium positioning from mass-market accessibility across sourcing geographies.
- Nut-Based:Almond, cashew, and walnut flours deliver protein density and healthy fat profiles that command sports nutrition retail placement. Premium pricing in Gurgaon and Hyderabad fitness channels reflects Latin American and Californian nut sourcing costs, with climate-driven harvest variability threatening formulation economics.
- Seed-Based:Chia, flax, and pumpkin seeds provide omega-3 fatty acids and complete protein for athletic endurance positioning. Quick-commerce adoption in Pune and Ahmedabad favors single-serve seed-fortified packs for immediate post-workout replenishment cycles.
- Legume-Based:Chickpea and lentil flours offer cost-accessible protein fortification for mid-market penetration.
- Fruit-Based:Dried berry and banana formulations target children's palates with natural sweetness masking reduced sugar content.
Nut-based formulations command the steepest price premiums; seed-based variants are climbing the fastest on volume contribution.
Packaging Type:
Volume concentration in modern trade formats drives format selection, while e-commerce penetration rewards flexibility.
- Resealable Bags:Multi-layer barrier films with zip-lock closures preserve crispness across India's humid monsoon seasons. Metro kirana networks in Chennai and Kolkata prioritize shelf-stable resealable formats for pantry stocking behavior, though quick-commerce fragmentation is compressing run sizes toward smaller lot production.
- Boxes:Paperboard secondary packaging enables planogram visibility and gift-set positioning in modern retail.
- Jars:Rigid PET or glass containers suit premium nut-based assortments with visual ingredient transparency.
- Eco-Friendly Pouches:Compostable films address Bangalore and Mumbai sustainability mandates while facing cost premiums versus conventional plastics.
Resealable bags handle the majority of throughput; eco-friendly pouches are gaining share fastest among platform-native brands.
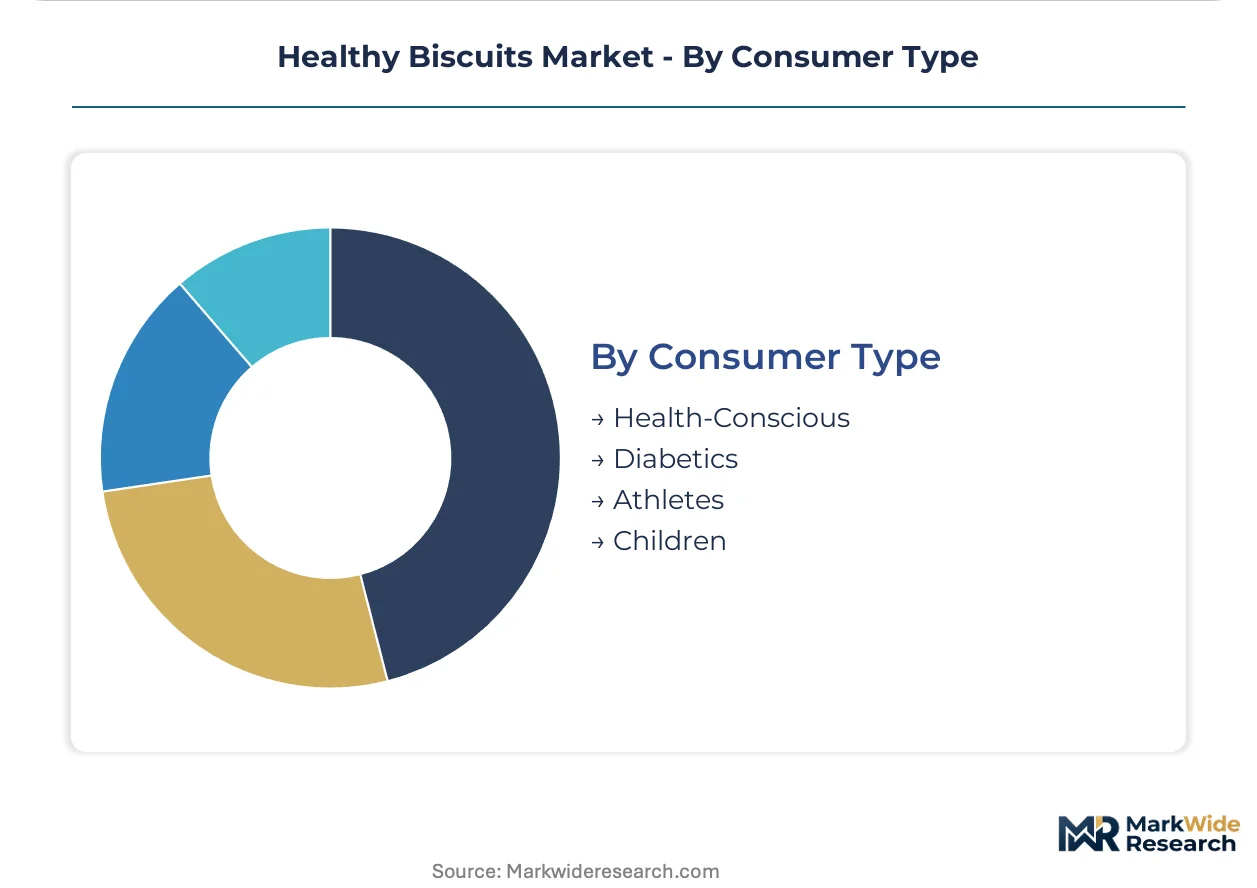
Consumer Type:
Application-specific requirements dictate formulation rigor, with medical-grade segments demanding clinical validation infrastructure.
- Health-Conscious:Broad clean-label seekers prioritizing fiber content and artificial additive avoidance for general wellness maintenance. Tier-two city expansion into Jaipur and Lucknow concentrates demand for price-accessible whole grain variants without specialty certification premiums.
- Diabetics:Requires FSSAI glycemic index certification with third-party blood glucose response documentation. Clinical validation protocols filter out unsubstantiated competitors and reward manufacturers with dedicated formulation science teams.
- Athletes:Protein-per-calorie optimization drives seed-based and nut-based premium positioning in sports retail formats.
- Children:Palatability engineering with reduced sugar and hidden vegetable inclusions targets parental purchasing decisions.
Health-conscious consumers handle the majority of throughput; diabetic-certified formulations are expanding most quickly on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Mumbai and Delhi commands 30-40% premiums over equivalent formulations in Jakarta and Manila, reflecting divergent certification infrastructure and retail consolidation levels. This asymmetry shapes manufacturer prioritization across emerging Asian corridors.
India
FSSAI glycemic index certification and quick-commerce penetration drive tier-one city demand for clinically validated formulations. The regulator's multi-stage approval process for novel ingredient claims filters shelf access, rewarding manufacturers with dedicated compliance teams. Britannia Industries and Parle Products anchor production clusters in Maharashtra and Karnataka, supplying resealable formats through modern trade and kirana networks.
United States
FDA nutritional disclosure rules and clean-label retail mandates elevate compliance costs for imported formulations. The agency's serving-size regulations and added-sugar line-item requirements shape package design and reformulation cycles. Mondelēz International and General Mills concentrate manufacturing and R&D in Chicago and Minneapolis corridors, serving club-store and e-commerce channels with fiber-fortified variants.
United Kingdom
EFSA health claim protocols and retailer-specific plastic-reduction commitments reshape packaging and substantiation requirements. The framework's clinical evidence thresholds for metabolic benefit claims extend product development timelines. Pladis operates formulation facilities in London and Manchester, distributing through Tesco and Sainsbury's planograms with reduced-sugar whole grain lines.
Mexico
Grupo Bimbo's captive distribution infrastructure and front-of-pack labeling regulations under NOM-051 drive local formulation adaptation. The standard's octagonal warning symbols for excess sugar, sodium, and calories compress permissible formulation ranges. Production concentrates in Mexico City and Monterrey metro areas, supplying Central American export corridors and domestic modern trade.
Indonesia
BPOM registration requirements and halal certification through MUI shape ingredient sourcing and labeling protocols. The dual framework extends launch timelines but unlocks access to Southeast Asia's largest Muslim consumer base. Nestlé and local joint-venture partners manufacture in Java-based industrial zones, distributing through Indomaret and Alfamart convenience networks with price-accessible whole grain variants.
Healthy Biscuits Market Vendor Landscape
Multinational conglomerates and domestic specialists split the market across certification-intensive premium tiers and price-accessible mass segments. Consolidation pressure concentrates around FSSAI compliance infrastructure and captive milling capabilities, filtering mid-tier producers without vertical supply control. Three archetypes dominate: global FMCG majors with direct-to-retail scale, regional specialists with kirana network penetration, and platform-native brands with subscription-based replenishment models. Competitive moves center on M&A for clean-label certification assets and capacity expansion into tier-two Indian cities.
Within the multinational tier, Mondelēz International, Nestlé, and General Mills exemplify scale-driven positioning through modern trade and e-commerce channel dominance. These companies occupy shelf space through planogram negotiation power and glycemic index certification portfolios. Among India-based specialists, Britannia Industries and Parle Products represent kirana-network penetration archetypes with deep distribution into traditional retail. ITC Limited anchors a diversified conglomerate position spanning biscuits and adjacent snacking categories. The competitive terrain rewards backward integration into ingredient sourcing and rapid FSSAI compliance turnaround.
| Leading Market Players |
|---|
| ITC Limited |
| Pladis |
| Mondelēz International |
| Grupo Bimbo |
| Nestlé |
| Britannia Industries |
| General Mills |
| Kellogg's |
| Parle Products |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Latin American chia seed processing is squeezing ingredient availability for Indian manufacturers while simultaneously elevating spot-market premiums for gluten-free flour alternatives, forcing mid-tier producers to absorb margin compression or cede shelf space to vertically integrated competitors with captive milling operations.
Pricing Analysis
The customization-premium spread between FSSAI-certified glycemic index formulations and standard whole grain variants spans significant price differentiation, with certification-grade products commanding substantial retail premiums in Mumbai and Delhi modern trade channels. Three-tier pricing structure across premium, standard, and economy levels reflects divergent ingredient sourcing costs, where nut-based formulations anchored in Latin American supply sit atop the value hierarchy. Price erosion runs through the mid-market tier as wheat cost volatility and alternative flour procurement challenges compress formulation economics. Health-conscious consumers in tier-two cities exhibit highest price sensitivity, while diabetic-certified segments demonstrate lowest elasticity due to limited clinically validated alternatives.
Supply Chain Analysis
Supplier-financing facilities extended by Indian conglomerates with captive milling operations are restructuring procurement relationships, enabling preferred payment terms that disadvantage cash-constrained mid-tier producers competing for limited specialty ingredient allocations. Raw material sourcing draws from Latin American chia regions, Australian nut growing belts, and domestic Indian wheat corridors, creating geographic dispersion that elevates freight cost exposure. Single-source vulnerability concentrates in chia seed supply chains tethered to specific Argentine and Bolivian harvest zones. Distribution runs through hybrid kirana-modern trade architectures in tier-one cities, with quick-commerce platforms fragmenting downstream fulfillment into micro-lot replenishment cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based replenishment models for healthy biscuits are expanding faster than traditional retail throughput, creating a service-attach opportunity where recurring revenue streams from direct-to-consumer platforms outpace one-time transactional growth in conventional channels.
For Market Incumbents: Insulate market position by deepening backward integration into certified organic ingredient sourcing and accelerating FSSAI compliance infrastructure investments. Platform-native brands with rapid certification turnaround threaten shelf access in quick-commerce channels, making captive milling capacity in Maharashtra and Karnataka a critical defensive lever against margin compression. For New Entrants and Emerging Players: Establish a beachhead in tier-two city diabetic-certified segments where clinical validation requirements filter established competitors and demand concentration in Pune and Hyderabad remains underpenetrated. Seed-based protein fortification for athletic replenishment cycles offers the most penetrable white space, with single-serve packaging formats enabling direct-to-consumer subscription acquisition. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform-native brands with subscription-based replenishment models, indicating superior cash-flow quality relative to traditional kirana-dependent incumbents. Acquisition targets should prioritize vertically integrated specialists with FSSAI certification assets and captive milling operations, with inflection signals to monitor including glycemic index certification standardization and tier-two city quick-commerce penetration rates.| Strategic Initiative | Industry Significance |
|---|---|
| FSSAI Certification Acceleration | Expedited glycemic index validation unlocks premium shelf placement in modern trade planograms. |
| Captive Milling Capacity Expansion | In-house flour production insulates margin from wheat price volatility and supply disruption. |
| Quick-Commerce Platform Integration | Direct-to-consumer channel access captures subscription revenue and bypasses kirana dependence. |
| Seed-Based Protein Fortification | Athletic positioning commands premium pricing in sports nutrition retail formats. |
| Tier-Two City Distribution Buildout | Secondary urban corridor penetration captures underexploited demand in Pune and Ahmedabad. |
Methodological Framework
A spread of perspectives from brand managers at multinational FMCG conglomerates, category buyers at modern retail chains, supply planners at domestic specialists, and formulation scientists at food technology institutes converged on the working assumptions underlying demand projections. Primary interview insights were cross-referenced against FSSAI regulatory filings, Nielsen retail audit data, customs import records for specialty ingredients, and SEC disclosures from listed competitors. Bottom-up volume modeling triangulated with top-down market sizing across product type, ingredient category, packaging format, and consumer health status segmentation dimensions.
Demand-supply-balance framing anchored the forecast framework, with consumption growth trajectories assessed against processing capacity expansion timelines and ingredient harvest variability throughout the projection horizon. Segmentation dimensions modeled included product type certification tier, ingredient sourcing geography, packaging format flexibility, and channel penetration depth. CAGRs were derived from regression analysis of historical volume trends adjusted for regulatory inflection points and channel shift acceleration. Forecast inputs incorporated FSSAI approval pipeline velocity and quick-commerce platform expansion rates.
Stress conditions across wheat and alternative flour price volatility, chia seed harvest disruption scenarios, and FSSAI regulatory timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding urban metabolic health awareness trajectories and e-commerce penetration curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
United States Bread Market
Bakery Products
Specula Market
Bakery Products
Gluten-Free Bakery Products Market
Bakery Products
Bread Premix Market
Bakery Products
Middle East and Africa Bakery Products Market
Bakery Products
US Retail Packaged Bread Market
Bakery Products
Bakery Cases Market
Bakery Products
Frosting, Toppings, and Decorations Market
Bakery Products
Fortified Bakery Market
Bakery Products
Cake Base Discs Market
Bakery Products
Bakery Fillings Market
Bakery Products
Matcha Cookie Market
Bakery Products
Ice Cream Market
Bakery Products
Bakery Premixes Market
Bakery Products
Low-Gluten Emmer and Einkorn Flour Blends Market
Bakery Products
Global Rice Cakes Market