
 Europe Bakery Products Market | 2026-2036
Europe Bakery Products Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Bakery Products Market Foresight
Multi-source flour procurement is recalibrating cost structures for European industrial bakers as wheat volatility persists. Associated British Foods Plc leverages its integrated milling and retail network to secure margin stability across the United Kingdom. Europastry anchors its position through frozen dough specialization, supplying foodservice operators from Barcelona to Berlin. Vandemoortele competes on shortening and margarine formulations that reduce saturated fat content without compromising laminated pastry performance.
Europe bakery products encompass leavened and unleavened goods manufactured from milled cereals, water, and functional additives, with critical parameters including moisture content, specific volume, and shelf-life extension through modified atmosphere packaging. These items serve household consumption, foodservice replenishment, and out-of-home snacking occasions across the continent. Bread retains the largest volume share but faces margin compression from private-label competition in supermarkets, while pastries command premium positioning in specialty stores and cafes where butter content and laminated layer count drive price differentiation. Online retailers represent the fastest-growing distribution channel as direct-to-consumer bakery subscriptions gain traction in urban France and the Netherlands.
EFSA governs food contact materials and enzyme approvals that determine which improvers enter industrial bread formulas, while the EU Green Deal's Farm to Fork strategy restricts pesticide residues in wheat destined for milling. CE marking on processing equipment plus national hygiene inspections by France's DGCCRF and Germany's BVL create layered compliance costs that favor scaled producers over artisan entrants. Stakeholders must track how the EU Deforestation Regulation reshapes palm oil and cocoa butter sourcing for margarine and chocolate-enrobed products.
Market Dynamics
Carbon accounting mandates under the EU Green Deal are forcing flour millers and industrial bakeries to restructure wheat sourcing and energy consumption patterns across European supply chains.
Growth Catalysts
- EU Green Deal Farm to Fork strategy:Pesticide residue restrictions on wheat destined for milling are accelerating certified sustainable grain procurement across France and Germany.
- Urban cafe expansion:Foodservice operators in Berlin, Paris, and Amsterdam are increasing artisan bread and pastry orders as out-of-home snaking occasions recover.
- Modified atmosphere packaging:Shelf-life extension technologies are enabling longer distribution radii for fresh products without preservative additives.
Market Restraints
- Black Sea wheat volatility:Input cost instability for European millers persists due to concentrated grain origination from Ukraine and Russia.
- CE marking compliance:Layered equipment certification and national hygiene inspections by France's DGCCRF and Germany's BVL create capital barriers for artisan entrants.
- Private-label compression:Supermarket chains are expanding own-brand bread lines, squeezing margin pools for branded industrial bakers.
Strategic Opportunities
- Direct-to-consumer subscriptions:Online bakery subscription models remain underdeveloped in urban Netherlands and Belgium relative to France.
- Frozen dough specialization:Foodservice operators from Barcelona to Warsaw seek consistent quality without on-site mixing capabilities.
- EU Deforestation Regulation:Palm oil and cocoa butter traceability mandates create first-mover advantages for bakeries with certified sustainable shortening supply chains.
Industry Challenges
- Laminated pastry craftsmanship:Industrial production of croissants and Danish pastries requires skilled operators for butter layer integrity, creating recruitment bottlenecks.
- Legacy equipment retrofitting:Energy-efficient oven upgrades demand capital outlays that strain mid-scale producers in Italy and Spain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Bakery Products Market |
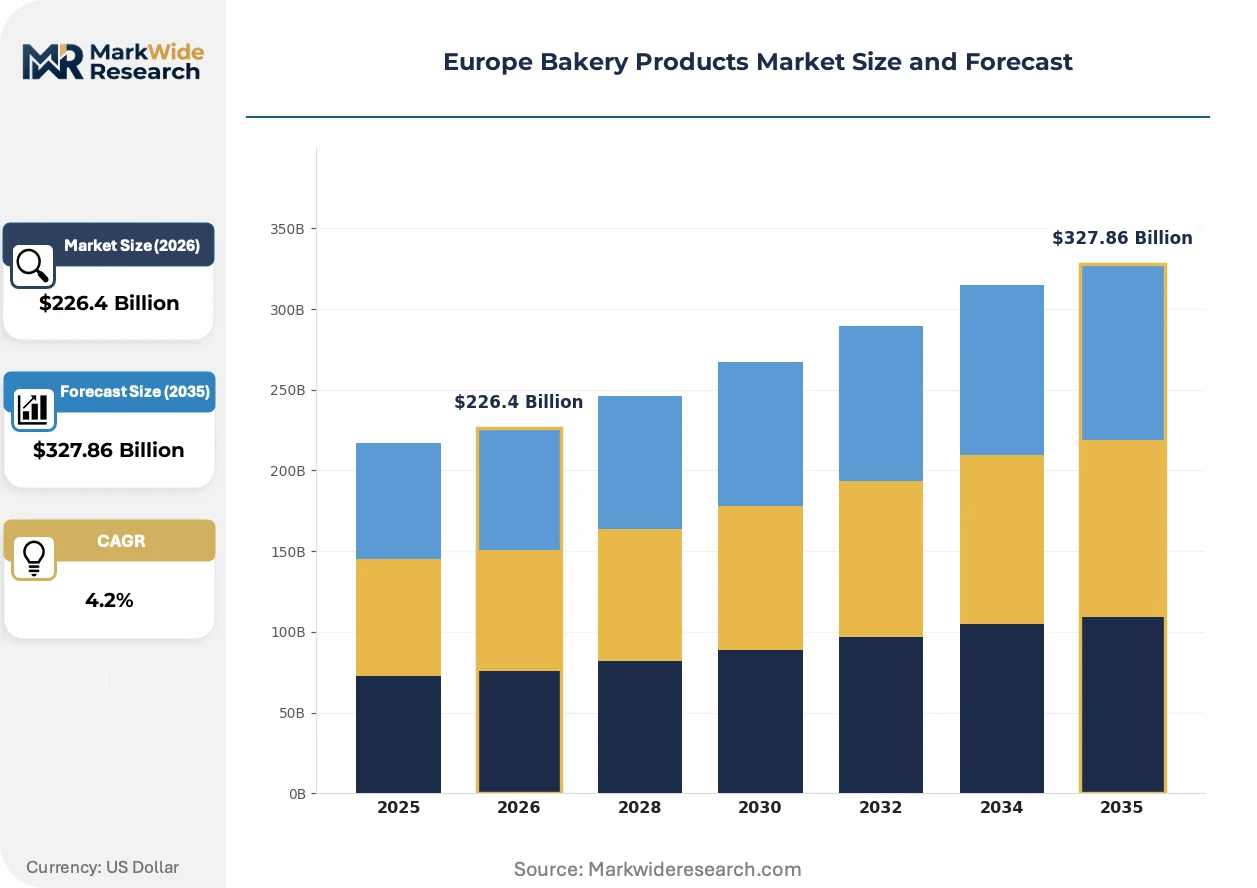
| Market Size in 2026 | $226.4 Billion |
| Market Size in 2035 | $327.86 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bread, Pastries, Cakes, Cookies Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Stores Ingredients: Flour, Sugar, Yeast, Dairy End User: Households, Restaurants, Cafes, Catering Services |
| Companies Covered | Warburtons Ltd, Pladis, Associated British Foods Plc, Vandemoortele, Europastry, Grupo Bimbo, Aryzta, Yıldız Holding, Mondelēz International, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Bakery Products Market Shifts & Advancements
Automation and clean-label formulation are converging to reshape competitive capabilities across European industrial and artisan bakery segments simultaneously.
Continuous mixing systems are unifying dough development consistency across high-output facilities. Industrial bakeries in the United Kingdom and Poland are adopting these lines to reduce batch variation. The technology is unifying quality parameters between automated plants and traditional artisan outputs, compressing the premium that handmade positioning previously commanded.
EFSA enzyme approval pathways are tightening industrial bread formulation options. The regulator's evolving stance on improvers is forcing reformulation cycles for packaged sliced bread. France's industrial producers are responding fastest, accelerating natural fermentation and sourdough alternatives to maintain shelf-life performance.
Cafe procurement departments are consolidating supplier panels and demanding butter-origin documentation. Specialty coffee chains in Germany and Scandinavia are replacing fragmented local sourcing with contracted regional millers. This concentration is most visible in Copenhagen and Stockholm, where single-source traceability now determines vendor selection.
Europe Bakery Products Market Segmentation
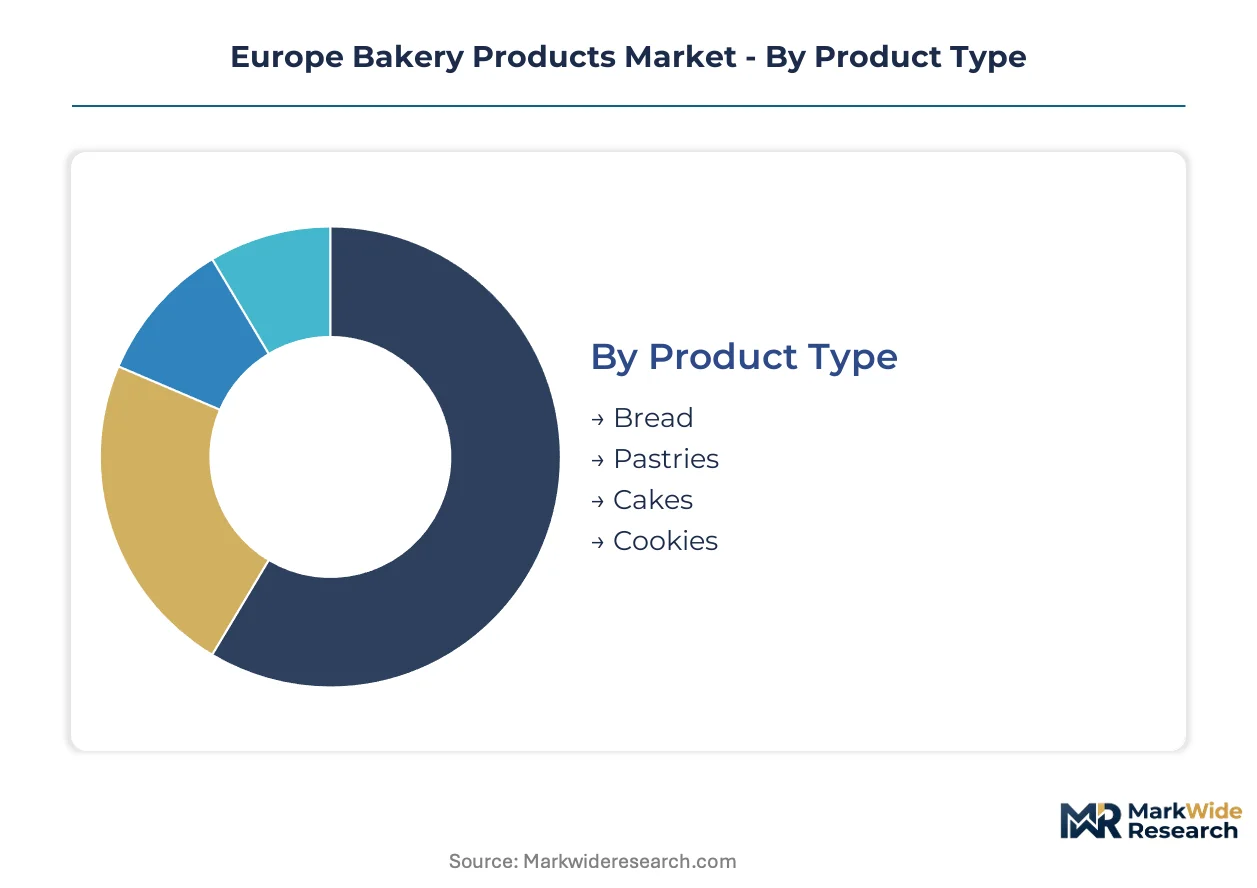
Segmentation in European bakery products tracks divergent margin architectures across commodity bread and premium laminated goods. Volume concentration in industrial bread channels contrasts with value capture in specialty pastry and foodservice segments. Understanding these splits enables targeted capital allocation across frozen dough platforms, clean-label reformulation, and direct-to-consumer infrastructure.
Product Type:
Bread commands volume leadership while pastries extract premium pricing through butter content and craftsmanship positioning.
- Bread:Leavened and unleavened cereal-based products ranging from industrial sliced loaves to artisan sourdough boules. Demand concentrates in German and French retail channels where private-label competition compresses branded margins. EFSA enzyme approvals are accelerating natural fermentation alternatives among industrial producers seeking clean-label positioning.
- Pastries:Laminated dough products including croissants, Danish, and puff pastry requiring precise butter layer integrity and controlled fermentation. Procurement is consolidating across Copenhagen, Stockholm, and Berlin cafe chains where single-source traceability determines supplier selection. Skilled operator shortages create recruitment bottlenecks for industrial croissant production.
- Cakes:Aerated batter products with sponge, chiffon, and butter cake variants serving celebration and daily indulgence occasions. German and UK supermarket chains dominate volume procurement.
- Cookies:Low-moiture baked goods with extended shelf stability through modified atmosphere packaging. Dutch and Belgian online retailers are expanding direct-to-consumer subscription models for premium cookie assortments.
Mature deployment sits with bread. Newer deployment is concentrated in pastries where laminated craftsmanship commands price differentiation.
Distribution Channel:
Channel selection determines margin retention versus volume throughput trade-offs for European bakers.
- Supermarkets:High-volume retail formats with centralized bakery procurement and expanding private-label bread lines. France's consolidated retail channels intensify competition between industrial producers and traditional boulangeries for shelf space.
- Convenience Stores:Small-format urban retail with limited fresh bakery capacity relying on frozen dough thaw-and-bake programs. Polish and Spanish operators are adopting these systems to reduce on-site mixing requirements.
- Online Retailers:Direct-to-consumer platforms and subscription services gaining traction in urban France and the Netherlands. Amsterdam and Paris demonstrate fastest adoption of recurring bakery delivery models.
- Specialty Stores:Artisan bakeries and patisseries emphasizing butter-origin documentation and provenance storytelling. Scandinavian coffee chains are consolidating supplier panels around regional millers with certified sustainable grain.
Volume concentration remains with supermarkets. Margin expansion is concentrating in specialty stores and online channels.
Ingredients:
Input cost volatility and sustainability certification are reshaping procurement priorities across European milling and baking operations.
- Flour:Milled wheat, rye, and spelt with protein content and ash specifications determining end-use suitability. Black Sea supply disruptions are forcing multi-source origination strategies among UK and German millers.
- Sugar:Sucrose and glucose syrups with EU Green Deal Farm to Fork pesticide restrictions extending to beet sugar supply chains. Reformulation toward reduced-sugar alternatives is accelerating in packaged sliced bread.
- Yeast:Compressed and instant dried cultures for fermentation control, with sourdough starters gaining share in clean-label positioning. French industrial producers are responding fastest to EFSA improver restrictions by accelerating natural fermentation.
- Dairy:Butter, milk powder, and cream with origin documentation increasingly required by cafe procurement departments. EU Deforestation Regulation traceability mandates are creating first-mover advantages for bakeries with certified sustainable shortening supply chains.
Commodity procurement dominates flour and sugar. Premium differentiation is concentrating in dairy traceability and specialty yeast cultures.
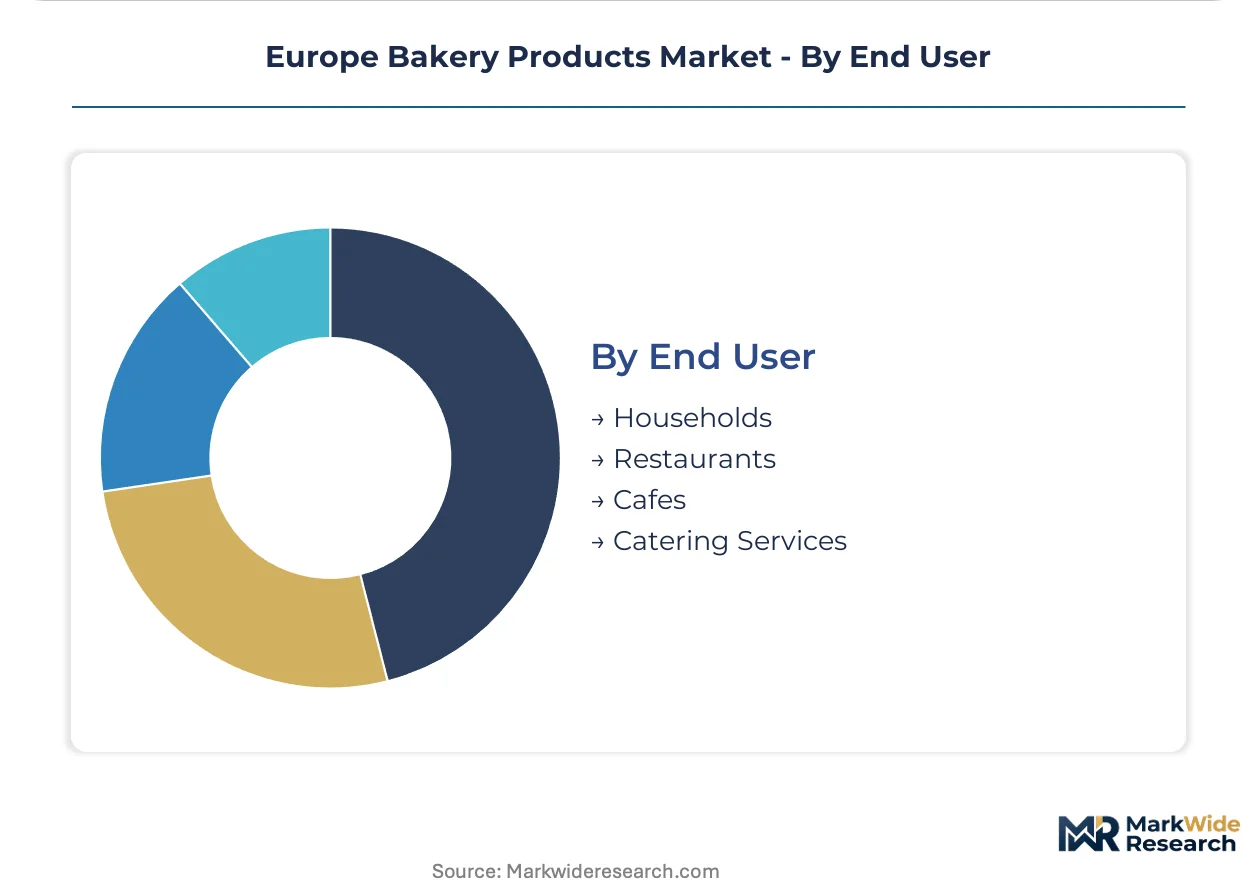
End User:
Final demand splits between household stock-up patterns and foodservice replenishment cycles with divergent quality specifications.
- Households:Weekly bread purchasing with growing subscription adoption for premium pastry assortments in Dutch and Belgian urban centers.
- Restaurants:Frozen dough demand for consistent quality without on-site mixing capabilities from Barcelona to Warsaw.
- Cafes:Artisan bread and pastry procurement with butter-origin documentation and laminated layer count driving vendor selection across Berlin, Paris, and Amsterdam.
- Catering Services:High-volume event provisioning with shelf-life extension requirements through modified atmosphere packaging for distribution radius expansion.
Volume stability sits with household consumption. Steepest expansion trajectory is visible in cafe procurement as out-of-home snacking occasions recover.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France and Germany concentrate the highest demand for premium bakery products, with artisan procurement patterns spreading from Paris and Berlin into secondary urban markets. Regional divergence reflects varying retail consolidation levels and foodservice recovery trajectories.
Germany
Berlin's cafe chains are consolidating artisan bread procurement around regional millers with certified sustainable grain. The EU Green Deal's Farm to Fork pesticide restrictions are accelerating certified wheat sourcing across Baden-Württemberg and Bavaria. Industrial bakeries in North Rhine-Westphalia are retrofitting energy-efficient ovens to meet carbon accounting mandates.
France
Traditional boulangeries and industrial producers compete intensely for shelf space in Île-de-France's consolidated retail channels. DGCCRF hygiene inspections create layered compliance costs that favor scaled producers over artisan entrants. Lyon and Marseille are witnessing fastest adoption of direct-to-consumer bakery subscription models.
United Kingdom
Supermarket private-label expansion is compressing branded bread margins across England and Scotland. CE marking on processing equipment plus national hygiene protocols create capital barriers for mid-scale entrants. London's foodservice operators are increasing frozen dough orders to reduce on-site mixing requirements.
Netherlands
Amsterdam demonstrates fastest adoption of recurring bakery delivery models among urban households. EFSA enzyme approval pathways are tightening industrial bread formulation options and accelerating natural fermentation alternatives. Rotterdam's industrial bakers are adopting continuous mixing systems to reduce batch variation.
Spain
Barcelona's foodservice operators are sourcing frozen dough for consistent quality without on-site mixing capabilities. Legacy equipment retrofitting demands capital outlays that strain mid-scale producers in Catalonia and Andalusia. Madrid's convenience stores are expanding thaw-and-bake programs to limit fresh bakery capacity investments.
Europe Bakery Products Market Competitive Landscape
Capacity expansion dominates the current landscape as industrial bakers retrofit facilities to meet EU Green Deal carbon mandates. The vendor base clusters around three strategic tiers: integrated milling-retail conglomerates, frozen dough specialists, and ingredient formulation providers. Two archetypes anchor competitive positioning — those controlling upstream grain supply and those commanding foodservice distribution density. M&A activity and geographic expansion into underpenetrated subscription markets represent the dominant competitive vectors.
Among UK-based integrated operators, Associated British Foods Plc occupies a position exemplifying margin stability through captive milling networks. Frozen dough specialists Europastry and Vandemoortele represent the foodservice-focused archetype, anchoring supply relationships from Barcelona to Berlin through consistent quality positioning without on-site production requirements.
| Leading Market Players |
|---|
| Warburtons Ltd |
| Pladis |
| Associated British Foods Plc |
| Vandemoortele |
| Europastry |
| Grupo Bimbo |
| Aryzta |
| Yıldız Holding |
| Mondelēz International |
| Others |
Supply & Pricing Matrix
Captive milling networks across the United Kingdom and Germany anchor margin stability for integrated industrial bakers while compressing pricing power for non-integrated competitors dependent on spot flour markets. This upstream control over wheat origination and processing creates divergent cost structures that reshape competitive positioning across French retail channels and German foodservice procurement.
Pricing Analysis
Service bundling separates frozen dough supply agreements with technical training and equipment calibration from unbundled commodity flour transactions. Three-tier pricing structure across premium artisan, standard industrial, and economy private-label levels tracks butter-origin documentation and laminated layer count as differentiation drivers. Pricing pressure stems from supermarket chains expanding own-brand bread lines across England and France. Private-label procurement teams exhibit highest price sensitivity while Copenhagen cafe chains prioritizing single-source traceability show lowest.
Supply Chain Analysis
Skilled operator shortages in French and Belgian laminated pastry production constrain manufacturing capacity expansion for industrial croissant lines. Wheat sourcing concentrates in Germany, France, and Poland with multi-source origination strategies accelerating among UK millers responding to Black Sea supply disruptions. Raw material dependencies center on certified sustainable grain, palm oil traceability for shortening formulations, and natural fermentation cultures. Single-source vulnerability in butter supply chains from designated origin regions creates concentration risk. Distribution runs through consolidated retail procurement in France and frozen dough platforms serving Barcelona to Berlin foodservice operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
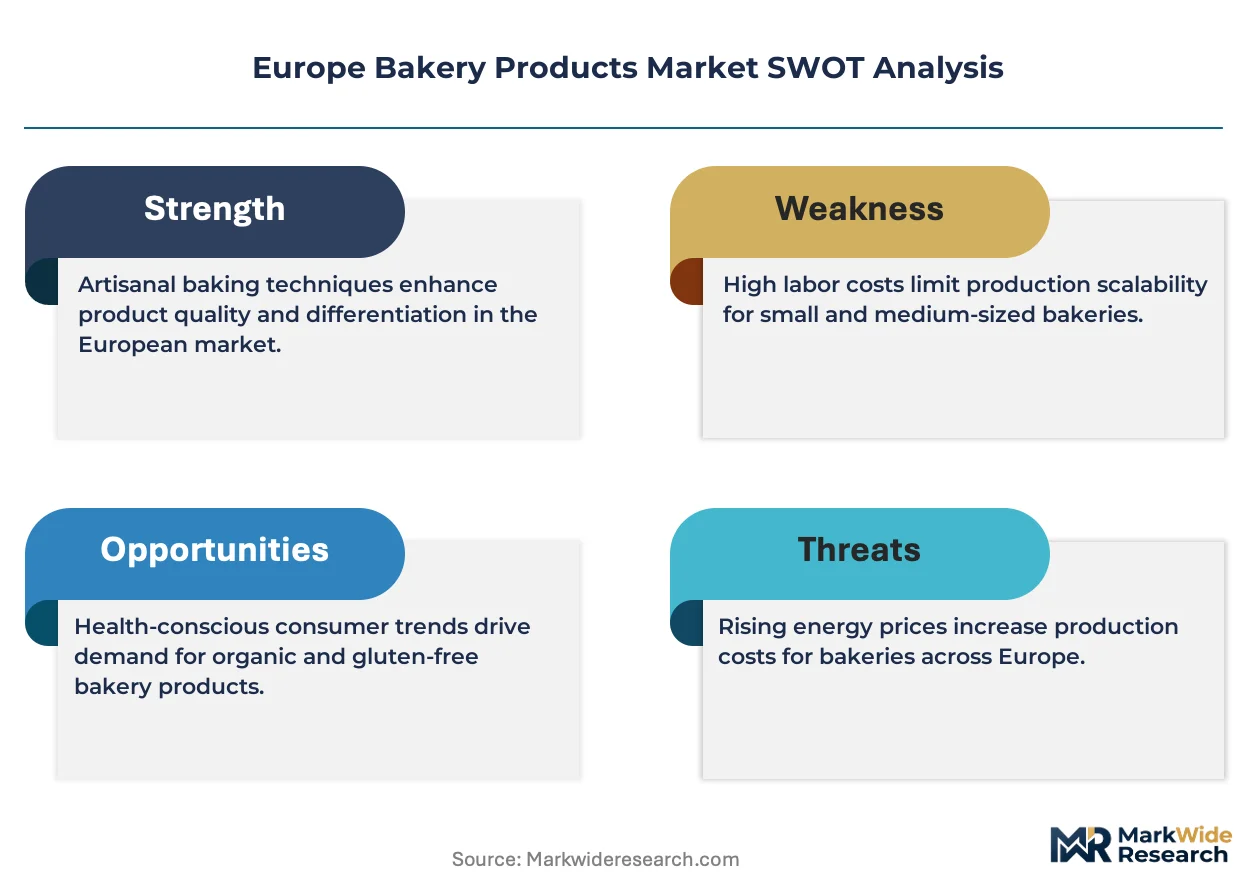
The EU Green Deal's Farm to Fork pesticide residue restrictions function as a compliance moat that advantages scaled producers with certified sustainable grain procurement infrastructure over artisan entrants lacking capital for traceability systems.
For Market Incumbents: Acquire regional milling assets in Baden-Württemberg and Bavaria to secure captive wheat supply chains against Black Sea volatility. Expand frozen dough platform capacity serving Warsaw and Amsterdam foodservice operators to capture out-of-home snacking recovery. CE marking compliance costs and DGCCRF inspection regimes create defensive barriers against mid-scale Italian and Spanish competitors lacking retrofit capital.
For New Entrants and Emerging Players: Enter via direct-to-consumer subscription models in underpenetrated Belgian urban centers where Amsterdam and Paris demonstrate proven demand. Target online retail channels for premium cookie assortments with modified atmosphere packaging enabling distribution radius expansion. Partner with Scandinavian coffee chains consolidating supplier panels around single-source traceability requirements.
For Investors and Strategic Acquirers: Exit pathways concentrate in frozen dough specialists with foodservice distribution density from Barcelona to Berlin and certified sustainable shortening supply chains. Long-term viability favors vertically integrated operators controlling upstream grain origination and downstream retail presence. Watch EFSA enzyme approval pathway tightening as inflection signal accelerating natural fermentation investment cycles among French industrial producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Milling | Captive wheat supply chains insulate Associated British Foods from Black Sea price volatility. |
| Frozen Dough Platform Expansion | Europastry's Barcelona-to-Berlin network captures foodservice operators seeking consistent quality. |
| Clean-Label Reformulation Investment | Natural fermentation alternatives respond to EFSA improver restrictions in French industrial bread. |
| Direct-to-Consumer Channel Launch | Subscription models in Lyon and Marseille bypass consolidated retail shelf-space competition. |
| Sustainability Certification Program | EU Deforestation Regulation traceability creates first-mover advantage in palm oil sourcing. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with industrial bakery procurement directors, flour miller operations heads, cafe chain sourcing managers, and EFSA regulatory affairs specialists provided demand-side validation. DGCCRF inspection protocols, BVL hygiene enforcement patterns, and EU Green Deal implementation guidance supplied regulatory boundary conditions. Bottom-up volume modeling across product types and distribution channels reconciled with top-down value estimates derived from trade flow analysis.
Reconciling production capacity disclosures from milling and baking trade associations with retail audit data from French and German supermarket chains established volume baselines. Segmentation dimensions modeled include product type, distribution channel, ingredient composition, and end-user application across the projection horizon. CAGRs derived from trend extrapolation of certified sustainable grain procurement rates, frozen dough platform adoption curves, and online retail penetration patterns in urban Netherlands and Belgium.
Revisions become necessary when Black Sea wheat supply disruptions intensify, EFSA enzyme approval pathways tighten beyond current trajectories, or EU Deforestation Regulation enforcement accelerates palm oil sourcing constraints. Forecasts reflect documented assumptions regarding foodservice recovery rates and carbon accounting mandate implementation schedules. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Bread Slicer Blades Market
Bakery Products
Specialty Frozen Bakery Market
Bakery Products
Ready-To-Finish Bakery Products Market
Bakery Products
Laminated Dough Market
Bakery Products
Low-Carb Low-Fat Bread Market
Bakery Products
Toasted Flour Market
Bakery Products
Baking Mats Market
Bakery Products
Healthy Biscuits Market
Bakery Products
Bread Dough Improver Market
Bakery Products
Europe Zwieback Market
Bakery Products
Asia-Pacific Frozen Bakery Market
Bakery Products
India Cake Market
Bakery Products
Malted Rye Flour Market
Bakery Products
Soft Biscuit Market
Bakery Products
Aerating Cake Emulsifier Market
Bakery Products
Low-Calorie Pie Market