
 India Cake Market | 2026-2036
India Cake Market Size, Share, and Industry Trends Forecast 2026-2036
India Cake Market Outlook
Asset-light franchising is rewriting competitive entry dynamics in the India cake sector, allowing regional operators to scale without heavy capital deployment. Britannia Industries Limited leverages its pan-India distribution infrastructure to sustain shelf presence across modern trade and kirana networks. Monginis Foods Pvt. Ltd. anchors its position through an extensive franchise model that controls last-mile bakery access in metros and emerging towns. Just Bake differentiates via made-to-order customization capabilities that occupy the premium celebration segment.
Cake denotes a baked dessert comprising flour, sugar, eggs, and fat, aerated through mechanical beating or chemical leavening, with moisture content typically ranging between twenty-five and forty percent to achieve shelf-stable softness for retail distribution. The product serves both everyday indulgence and ceremonial gifting purposes across Indian consumer occasions. Chocolate Cake and Red Velvet Cake dominate value contribution in the product type dimension, while the online distribution channel records the fastest route-to-consumer expansion as quick-commerce platforms compress delivery timelines. Small and medium sizes lead volume throughput, though extra-large formats command disproportionate margin pools in the celebration and wedding segments.
FSSAI labeling mandates and state-level food safety enforcement under FSSAI and BIS nutritional standards shape permissible ingredient declarations and shelf-life claims across the India cake market. The FSSAI fortification guidelines and BIS product standards create compliance thresholds that filter out unorganized local bakeries from modern retail and institutional channels. Stakeholders must monitor evolving FSSAI clean-label requirements and quick-commerce platform commission structures to calibrate portfolio mix and channel economics.
Market Dynamics
Quick-commerce platform expansion into tier-two Indian cities is compressing delivery timelines and forcing traditional bakery chains to reconfigure their fulfillment infrastructure around sub-30-minute service guarantees.
Growth Catalysts
- Quick-commerce penetration:Swiggy Instamart and Blinkit are extending same-day cake delivery to 50+ tier-two cities, unlocking celebration demand outside metro cores.
- FSSAI fortification mandates:Mandatory micronutrient enrichment in mass-market baked goods is pushing organized manufacturers to upgrade formulations and capture institutional channel access.
- Celebration economy formalization:Wedding and corporate event planners in Maharashtra and Karnataka are consolidating procurement through branded bakery chains, displacing unorganized local suppliers.
Market Restraints
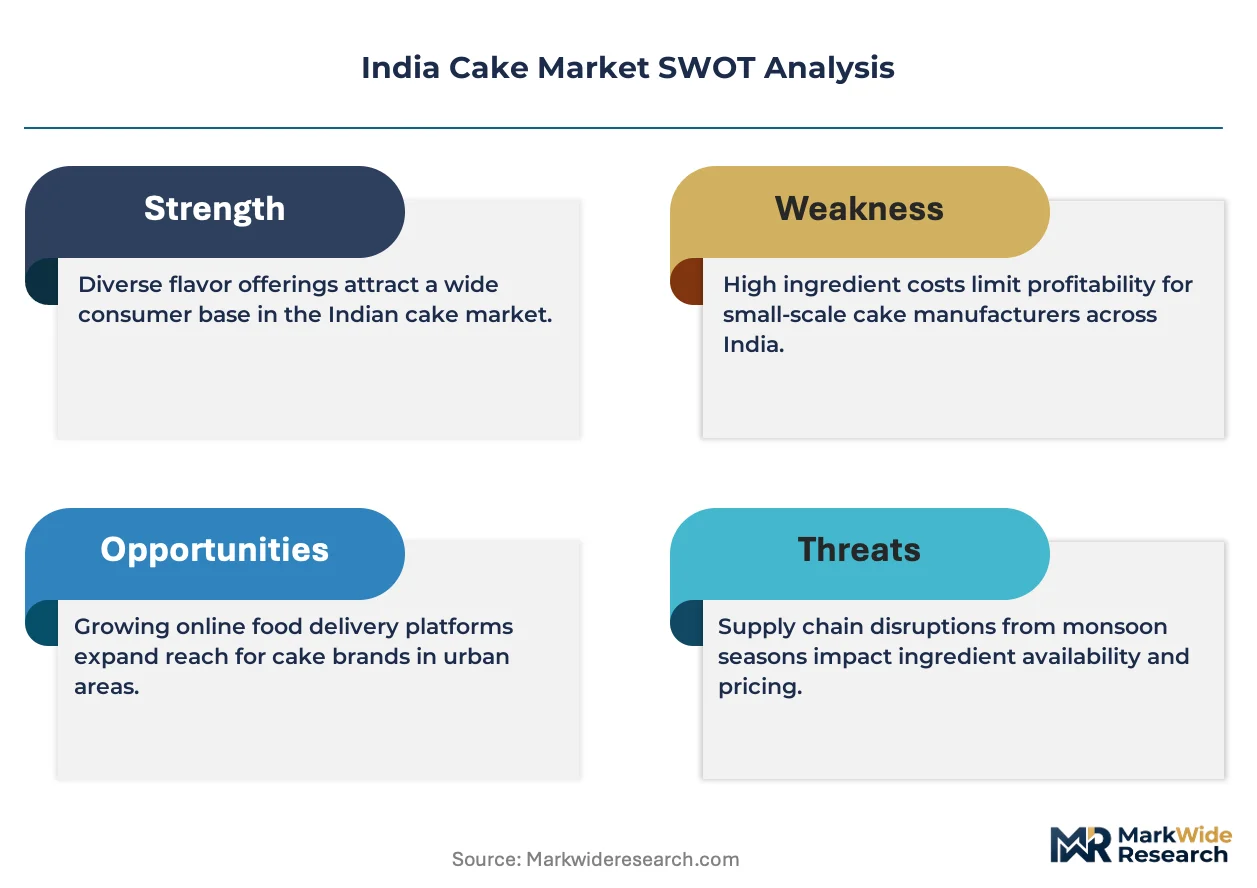
- Input cost volatility:Butter and cocoa powder prices fluctuate with global commodity cycles, compressing margins for mid-tier operators without forward-contracting capabilities.
- Cold chain gaps:Last-mile refrigerated logistics remain underdeveloped in Rajasthan and Uttar Pradesh, limiting cream-based product distribution to ambient-stable formulations.
- Substitution pressure:Traditional Indian sweets (mithai) retain dominant share in festival gifting, constraining cake adoption in Tier-3 towns and rural belts.
Strategic Opportunities
- Clean-label ingredient platforms:FSSAI draft guidelines on artificial additive disclosure create first-mover advantage for brands building preservative-free supply chains.
- Institutional catering contracts:IT parks and hospital cafeterias in Bangalore and Hyderabad are tendering multi-year bakery supply agreements with HACCP-mandated vendors.
- AI-driven customization:Computer-vision cake design tools are enabling made-to-order production at scale, collapsing the cost gap between standard and personalized formats.
Industry Challenges
- Skilled baker shortage:Industrial-scale fondant work and precision temperature control require trained artisans, but vocational institutes in Gujarat and Tamil Nadu graduate fewer than 2,000 certified pastry chefs annually.
- Quick-commerce commission squeeze:Platform fees of 18-25% on order value are eroding unit economics for premium cake SKUs, forcing brands to absorb costs or sacrifice volume.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Cake Market |
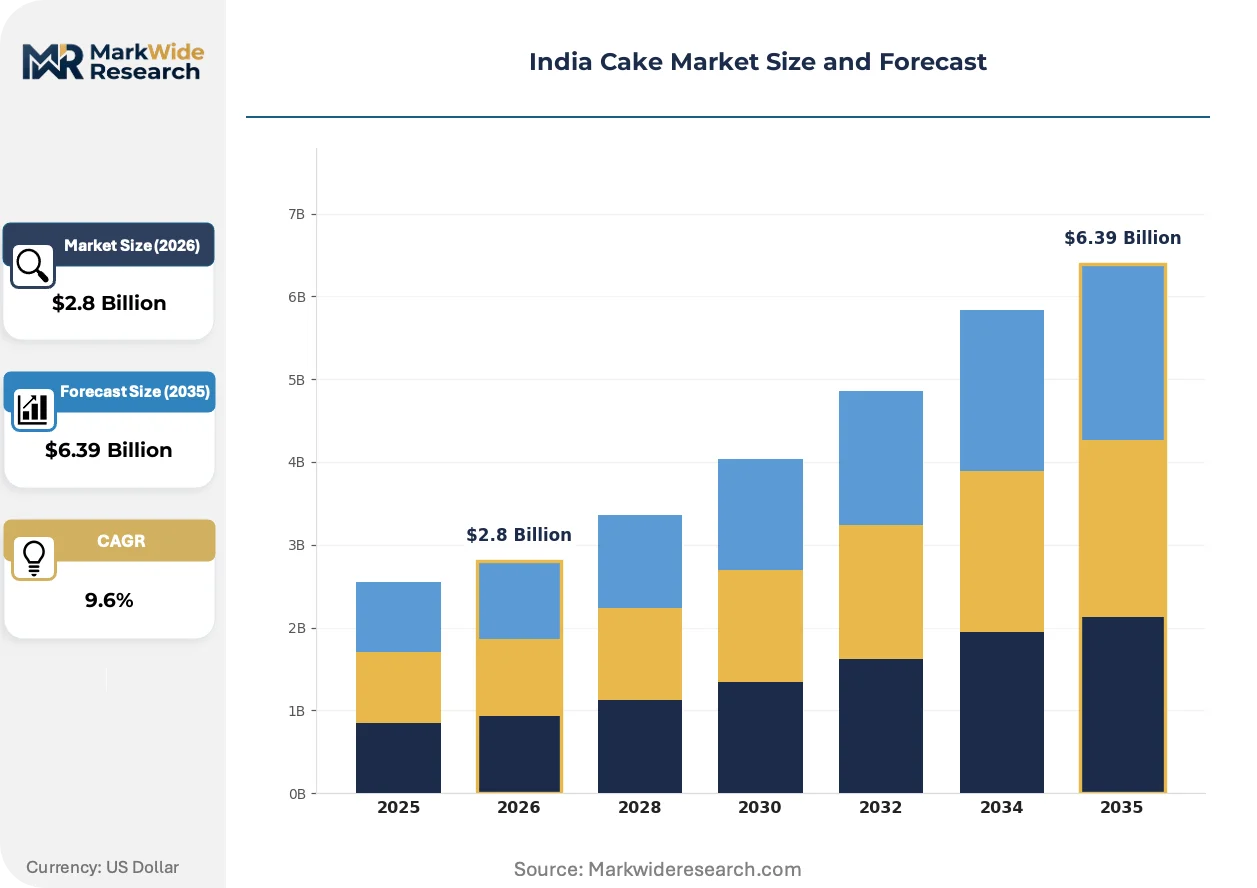
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.39 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate Cake, Vanilla Cake, Red Velvet Cake, Fruit Cake Size: Small, Medium, Large, Extra Large Distribution Channel: Online, Supermarkets, Bakeries, Convenience Stores Flavor: Choco Chip, Butterscotch, Pineapple, Coffee |
| Companies Covered | Monginis Foods Pvt. Ltd., Elite Foods, Britannia Industries Limited, Merwans Confectioners Pvt. Ltd., General Mills, ITC Limited, Anmol Industries Ltd., Just Bake, Parle Products Pvt. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Cake Market Strategic Shifts
Three parallel forces are restructuring how cakes are formulated, distributed, and consumed across Indian urban markets: clean-label chemistry, algorithmic logistics, and occasion-based personalization.
Enzyme-based shelf-life extension systems are replacing chemical preservatives in mass-market sponge cakes. Britannia and regional cooperatives in Kerala are piloting amylase and lipase treatments that maintain 21-day ambient stability without potassium sorbate. This biotechnology is rendering obsolete the traditional trade-off between clean labels and distribution reach.
FSSAI's 2023 draft notification on front-of-pack labeling is tightening disclosure requirements for sugar and saturated fat content. Organized retail chains in Mumbai and Delhi are preemptively reformulating portfolios to qualify for voluntary "Healthier Choice" symbols. Premium positioned brands face the steepest compliance costs as they rebalance indulgence claims with nutritional transparency.
Occasion-based micro-fulfillment is displacing advance-order bakery models. Consumers in Pune and Chennai now expect four-hour customization turnaround for birthday and anniversary cakes, compressing production planning cycles. This behavioral shift favors asset-light cloud kitchen operators over capital-intensive storefront networks in high-rent urban cores.
India Cake Market Segmentation
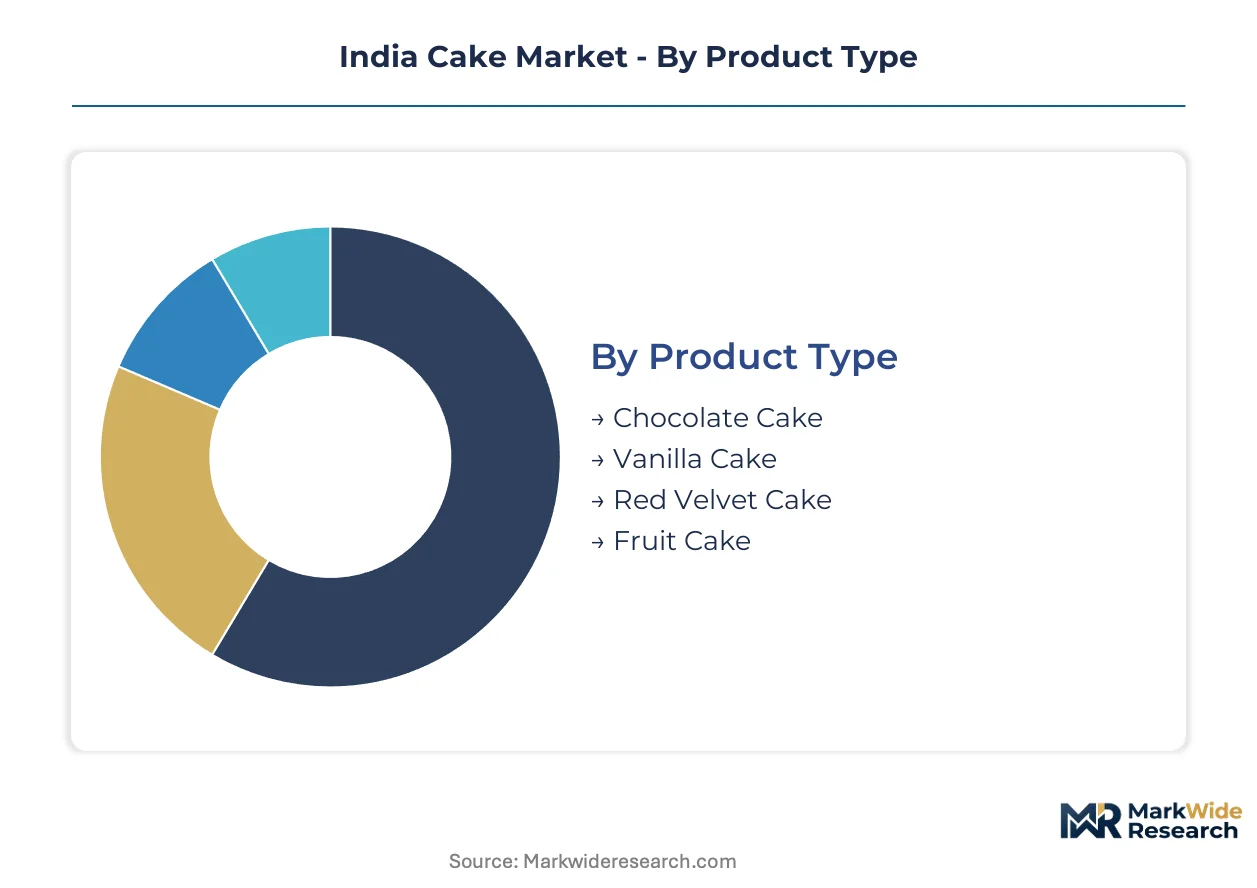
India's cake market segments reveal distinct consumption patterns across celebration intensity, household size, and digital adoption. Understanding these divides enables manufacturers to calibrate formulation, packaging, and channel strategy for margin capture.
Product Type:
Occasion intensity and gifting culture define the use-case spectrum across cake varieties.
- Chocolate Cake:Cocoa-based sponge or layered formats with ganache or buttercream frosting dominate birthday and anniversary gifting. Maharashtra and Karnataka households drive volume through year-round celebration demand, with premium dark chocolate variants gaining traction in Mumbai and Bangalore metro clusters.
- Vanilla Cake:Neutral-flavored sponge serves as the base for customization and tiered wedding cakes. Demand concentrates in Gujarat's institutional catering segment, where banquet halls specify vanilla bases for fondant work and edible printing.
- Red Velvet Cake:Buttermilk-based crimson sponge with cream cheese frosting anchors premium celebration positioning. Urban millennials in Delhi-NCR and Hyderabad drive adoption through social media visibility.
- Fruit Cake:Rum-soaked dried fruit formulations tied to Christmas and New Year gifting traditions. Kerala and Goa maintain concentrated demand through colonial-era consumption habits.
The dominant share belongs to Chocolate Cake, while Red Velvet Cake is closing the gap fastest.
Size:
Household nuclearization and celebration scale determine format selection across urban India.
- Small:Single-serve portions (200-400g) target impulse indulgence and nuclear family consumption. Quick-commerce platforms in Pune and Chennai push this format through sub-30-minute delivery guarantees.
- Medium:500g-1kg formats serve standard birthday gatherings of 4-8 guests. Tier-two city bakeries in Indore and Lucknow record highest throughput here.
- Large:1.5-2kg cakes address extended family celebrations. Wedding planners in Jaipur and Chandigarh specify this tier for pre-wedding functions.
- Extra Large:Tiered formats above 3kg command ceremonial centerpiece roles. Corporate event budgets in Bangalore IT parks absorb premium pricing for logo-customized installations.
Medium sizes generate the highest absolute volume, though Extra Large formats capture disproportionate margin pools.
Distribution Channel:
Speed-to-consumer and experiential purchase drivers split the route-to-market landscape.
- Online:Quick-commerce and dedicated bakery apps compress delivery windows to under four hours for customized orders. Blinkit and Swiggy Instamart expansion into 50+ tier-two cities is accelerating this channel's expansion trajectory.
- Supermarkets:Modern trade chains stock ambient-stable packaged cakes for planned purchase. Big Bazaar and DMart in Maharashtra and Gujarat dedicate end-cap displays to festive seasonal variants.
- Bakeries:Neighborhood storefronts retain trust advantage for fresh cream and customization. Monginis franchise density in Kolkata and Ahmedabad sustains last-mile penetration.
- Convenience Stores:Kirana networks distribute single-serve packaged formats for immediate consumption. Rajasthan and Uttar Pradesh reliance on this channel reflects cold chain limitations for fresh products.
Bakeries retain the volume lead, but Online is expanding most quickly through quick-commerce infrastructure deployment.
Flavor:
Regional palate preferences and generational taste shifts fragment the flavor landscape.
- Choco Chip:Semi-sweet morsels embedded in vanilla or chocolate sponge target children's birthday segments. Demand clusters in Bangalore and Hyderabad nuclear families.
- Butterscotch:Caramelized sugar and nut praline combinations dominate South Indian preference. Tamil Nadu and Karnataka bakeries stock this as the default non-chocolate option.
- Pineapple:Tropical fruit flavoring persists in tier-three towns and older demographics. Kerala and coastal Karnataka maintain residual demand through plantation economy associations.
- Coffee:Espresso-infused sponge targets adult palates and corporate gifting. Metropolitan white-collar clusters in Mumbai and Delhi-NCR drive adoption.
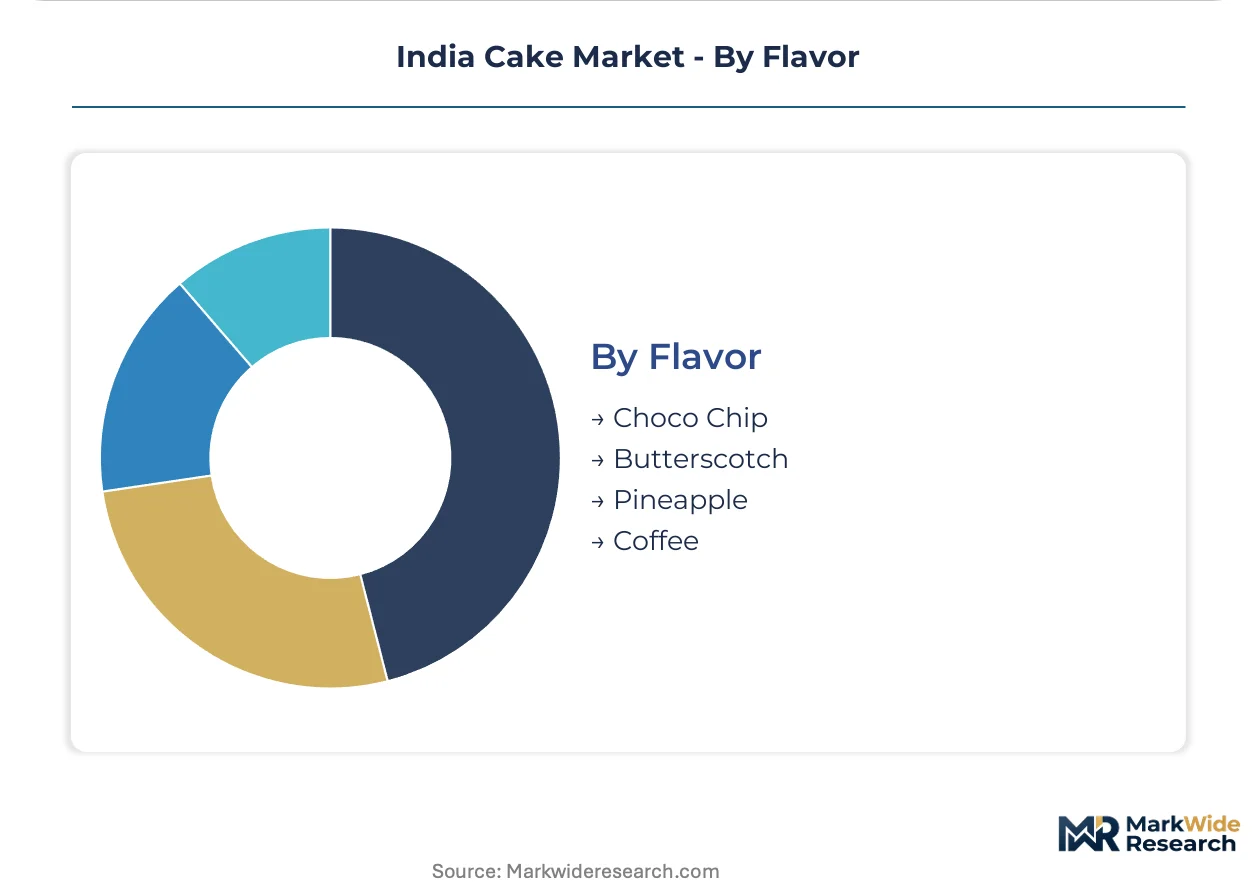
Butterscotch commands the largest regional share, while Coffee is gaining share fastest among premium urban consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's cake market exhibits strong domestic consumption orientation with limited export activity, as perishable logistics constrain cross-border movement of cream-based products. Import penetration remains negligible given robust local manufacturing capacity across organized and unorganized segments. Regional demand clusters concentrate in western and southern states where urbanization rates and celebration spending run highest.
Maharashtra
Mumbai and Pune metropolitan clusters drive premium cake consumption through nuclear family gifting culture and corporate celebration budgets. FSSAI state licensing enforcement through Maharashtra FDA tightens hygiene compliance for bakery registrations in Mumbai municipal limits. Thane and Navi Mumbai industrial corridors host centralized commissary kitchens supplying quick-commerce dark stores across the Mumbai Metropolitan Region.
Karnataka
Bangalore's IT workforce sustains year-round demand for personalized celebration cakes and corporate event catering. The state's implementation of FSSAI's Food Safety and Standards Act through Karnataka Food Safety Department mandates display license numbers at all retail bakery outlets. Whitefield and Electronic City technology parks concentrate institutional procurement contracts with HACCP-certified bakery suppliers.
Gujarat
Ahmedabad and Surat urban households anchor western India's highest per-capita cake consumption through extended family celebration traditions. Bureau of Indian Standards product certification requirements filter unorganized players from modern retail shelf access in Gujarat's cooperative store networks. GIFT City and Gandhinagar corporate campuses generate weekday impulse demand through cafeteria and catering channels.
Tamil Nadu
Chennai's dense bakery network serves both retail walk-ins and quick-commerce delivery commitments across the metropolitan sprawl. Tamil Nadu Food Safety Department inspections enforce FSSAI labeling mandates on shelf-life declarations and allergen warnings. Coimbatore's emerging IT corridor and wedding industry drive medium-format cake volume through banquet hall procurement.
Delhi-NCR
Gurgaon and Noida corporate headquarters sustain premium celebration cake demand through executive gifting and event marketing budgets. Delhi's municipal corporations coordinate with FSSAI on street food and bakery vendor registration drives in high-footfall commercial districts. Faridabad and Ghaziabad manufacturing zones supply ambient-stable packaged cakes to modern trade chains across northern India.
India Cake Market Competitive Environment
On the supply side, the industry is bifurcated between capital-intensive national packaged food conglomerates and asset-light regional bakery chains. Organized manufacturers leverage pan-India distribution infrastructure to sustain kirana network penetration, while franchise-operated storefronts control last-mile customization and freshness perception. Three strategic archetypes dominate: packaged goods majors with ambient-stable portfolios, franchise bakery networks with dense metro presence, and cloud-kitchen operators optimizing for quick-commerce fulfillment. Competitive intensity centers on M&A consolidation of regional bakery chains and strategic partnerships with quick-commerce platforms for exclusive SKU distribution.
Within the national packaged goods tier, Britannia Industries Limited anchors shelf-stable cake presence across modern trade and traditional retail, while ITC Limited occupies a parallel position through its bakery portfolio extension. Among dedicated bakery specialists, Monginis Foods Pvt. Ltd. exemplifies the franchise-scaling archetype with extensive storefront networks controlling neighborhood access in metros and emerging towns. Just Bake represents the customization-focused segment, occupying premium positioning through made-to-order capabilities for celebration occasions.
| Leading Market Players |
|---|
| Monginis Foods Pvt. Ltd. |
| Elite Foods |
| Britannia Industries Limited |
| Merwans Confectioners Pvt. Ltd. |
| General Mills |
| ITC Limited |
| Anmol Industries Ltd. |
| Just Bake |
| Parle Products Pvt. Ltd. |
| Others |
Value Chain & Pricing Dynamics
The Mumbai-Ahmedabad freight corridor shapes cost dynamics across the India cake market, with logistics expenses feeding into both supply concentration among western manufacturers and downstream price differentiation between ambient-stable and fresh cream segments.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium celebration, standard retail, and economy packaged formats. Price differentiation hinges on FSSAI certification tier and cold chain delivery cost, with premium HACCP-certified SKUs commanding substantial premiums over ambient-stable economy lines. Pricing pressure stems from quick-commerce platform commission structures, which compress margins for mid-tier operators. Price sensitivity concentrates among kirana network distributors, while corporate catering procurement shows lowest elasticity.
Supply Chain Analysis
Contract manufacturing concentrates among specialized commissary operators in Maharashtra, Karnataka, and Gujarat, with Britannia and regional cooperatives holding dominant ambient-stable capacity. Raw material dependencies center on butter imports from New Zealand, cocoa powder from West African origins, and domestic wheat flour from Punjab and Haryana mills. Supply chain risk manifests through single-source vulnerability in cocoa butter supply. Distribution runs through franchise bakery networks for fresh products and modern trade chains for packaged formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India cake market operates as a substitution defense against traditional mithai gifting, requiring incumbents to navigate festival-season demand volatility and rural consumer retention.
For Market Incumbents: Pre-empt cloud-kitchen encroachment by securing exclusive quick-commerce SKU distribution and upgrading commissary capacity for sub-four-hour customization turnaround. Consolidate regional bakery chains in Tamil Nadu and Delhi-NCR to defend against unorganized supplier displacement. Channel control through franchise density remains the priority lever against platform commission erosion.
For New Entrants and Emerging Players: Tier-two city cloud-kitchen infrastructure gaps in Indore, Lucknow, and Coimbatore represent the most penetrable entry point for asset-light operators. Clean-label enzyme-based shelf-life extension technology offers differentiation against chemical preservative formulations. Direct-to-consumer bakery apps with AI-driven design tools provide the optimal go-to-market angle for premium celebration positioning.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors HACCP-certified regional bakery chains with established quick-commerce relationships and scalable commissary infrastructure. Long-term viability across the analysis window hinges on FSSAI fortification compliance capabilities and clean-label formulation pipelines. Monitor FSSAI draft additive disclosure timelines as the critical inflection signal for portfolio rebalancing.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Formulation Transition | Enzyme-based shelf-life systems from Britannia preempt FSSAI additive disclosure mandates. |
| Quick-Commerce Exclusive Distribution | Blinkit and Swiggy Instamart partnerships lock out competitor access in tier-two expansion zones. |
| Franchise Network Consolidation | Monginis-style density models in Kolkata and Ahmedabad secure last-mile penetration against cloud kitchens. |
| HACCP Certification Investment | Compliance opens institutional catering contracts at Bangalore IT parks and Hyderabad hospital cafeterias. |
| AI-Driven Customization Platform | Computer-vision design tools collapse cost gaps between standard and personalized celebration formats. |
Study Parameters
The analysis maps product type segments, distribution channels, and regional consumption clusters, each validated through primary interviews with bakery chain operations directors, FSSAI regulatory consultants, quick-commerce category managers, and institutional catering procurement heads. Secondary sources include FSSAI notification archives, BIS product standard databases, Maharashtra and Karnataka Food Safety Department inspection records, and modern trade point-of-sale data. Bottom-up volume modeling triangulates against top-down value estimates derived from organized manufacturer revenue disclosures.
Assumptions held fixed include FSSAI fortification mandate implementation timelines and quick-commerce platform commission structures, while commodity input costs and regional cold chain development trajectories were varied across sensitivity scenarios. Segmentation dimensions encompass product type, size format, distribution channel, and flavor preference, with regional regulatory enforcement intensity as an industry-specific overlay. CAGRs derive from regression analysis against historical consumption elasticities and urbanization penetration curves, incorporating wedding industry spending patterns and IT workforce demographic expansion as forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in butter and cocoa commodity cycles, or accelerated FSSAI clean-label enforcement, would shift the trajectory substantially. Forecasts reflect documented assumptions without guarantee of realization. Quarterly review of quick-commerce platform expansion announcements and FSSAI draft notification releases is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Frozen Bakery Market
Bakery Products
Canada Frozen Bakery Market
Bakery Products
Cream Cheese Frosting Market
Bakery Products
North America Bakery Products Market
Bakery Products
Instant Cake Emulsifier Market
Bakery Products
Diabetic Bakery Products Market
Bakery Products
North America Par Baked Bread Market
Bakery Products
Wedding Cakes Market
Bakery Products
Low Calorie Flour Market
Bakery Products
Bakery Mixes Market
Bakery Products
Gluten-Free Baking Mixes Market
Bakery Products
Oman Frozen Bakery Products Market
Bakery Products
Cake Concentrate Market
Bakery Products
Global Bakery Product Market
Bakery Products
Pancake Mixes Market
Bakery Products
Tunnel Bakery Oven Market