
 Global Baked Food and Cereals Market | 2026-2036
Global Baked Food and Cereals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Baked Food and Cereals Market Foresight
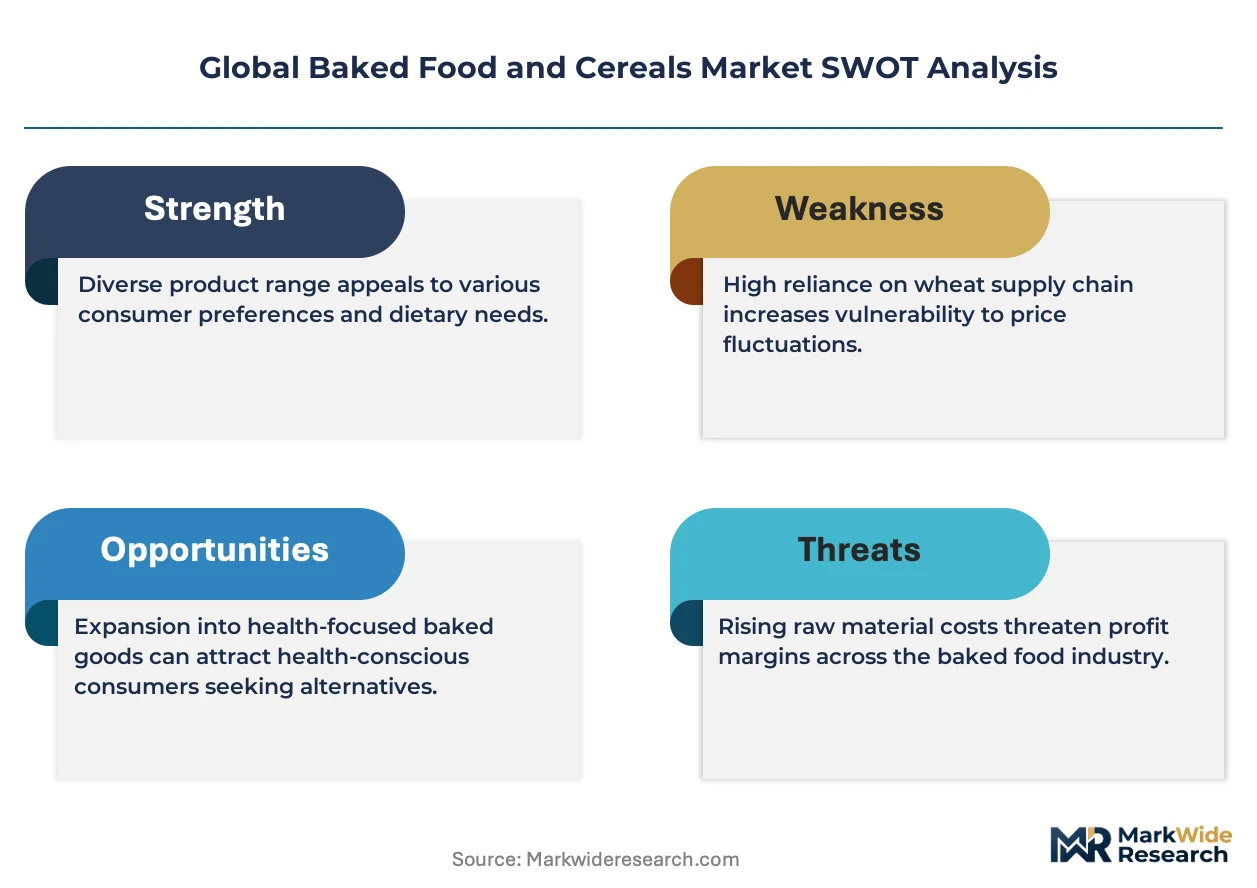
EU Green Deal compliance is rebalancing the cost-of-entry calculus for new baked food entrants across European markets. Nestlé S.A. leverages its R&D intensity to reformulate cereal portfolios ahead of tightening carbon-footprint disclosure rules. Grupo Bimbo, S.A.B. de C.V. anchors its competitive position through backward integration into corn and wheat sourcing across Latin American supply basins. Mondelez International, Inc. differentiates via specialty biscuit lines that command premium positioning in duty-free and travel-retail channels.
Baked food and cereals encompass grain-based products manufactured through thermal processing including fermentation, extrusion, baking, or toasting, with moisture content typically ranging from 2% to 40% depending on preservation requirements and shelf-life targets. These products serve as staple caloric inputs for household consumption, commercial foodservice operations, and institutional feeding programs requiring standardized nutrition delivery. Breakfast cereals and biscuits capture the deepest margin pools due to brand loyalty and packaging-driven premiumization, while bread remains the highest-volume category with compressed profitability. Online retailers represent the fastest-expanding distribution channel as direct-to-consumer subscription models bypass traditional wholesale markups in North American and European markets.
FDA nutrition-labeling rules and USDA organic certification standards govern product composition and marketing claims in the United States, while EFSA health-claim assessments and EU F-Gas Regulation phase-down schedules reshape manufacturing equipment investments across European production facilities. China's SAMR food-safety traceability mandates and GB standards for cereal fortification impose parallel compliance burdens on exporters serving Asian markets. Stakeholders must monitor divergence between regional sustainability disclosure regimes and calibrate capital allocation toward flexible production lines capable of switching between conventional and clean-label formulations without throughput penalties.
Market Dynamics
The EU Green Deal's farm-to-fork mandates are forcing wholesale reformulation of wheat-based product lines, compressing margins for conventional bakers while advantaging early movers in clean-label portfolios. This regulatory pressure cascades through procurement, manufacturing, and labeling decisions across every major production basin.
Growth Catalysts
- EU F-Gas Regulation phase-down:Equipment replacement cycles accelerate adoption of low-carbon thermal processing systems in European facilities.
- India's urban middle-class households:Packaged bread displaces traditional flatbread consumption, expanding addressable market for industrial bakeries.
- Southeast Asian healthcare catering:Breakfast cereal adoption spreads through institutional feeding programs requiring standardized nutrition delivery.
Market Restraints
- Wheat input cost volatility:Black Sea supply disruptions transmit directly to flour procurement budgets, compressing bakery margins.
- Chinese SAMR traceability mandates:Exporters face parallel compliance burdens for cereal fortification and safety documentation.
- Plant-based substitutes:Alternative protein breakfast formats capture morning occasion share from conventional cereals.
Strategic Opportunities
- Direct-to-consumer subscription models:Online retailers bypass wholesale markups in North American and European markets.
- USDA organic certification tailwinds:Premium positioning for certified clean-label lines captures margin pools from conventional products.
- Extrusion-pulse protein convergence:Novel processing enables legume-based baked goods with improved amino acid profiles.
Industry Challenges
- Legacy equipment retrofit timelines:F-Gas phase-down deadlines compress capital deployment windows for European manufacturers.
- Clean-label formulation expertise:Shortage of food scientists capable of maintaining shelf-life without synthetic preservatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Baked Food and Cereals Market |
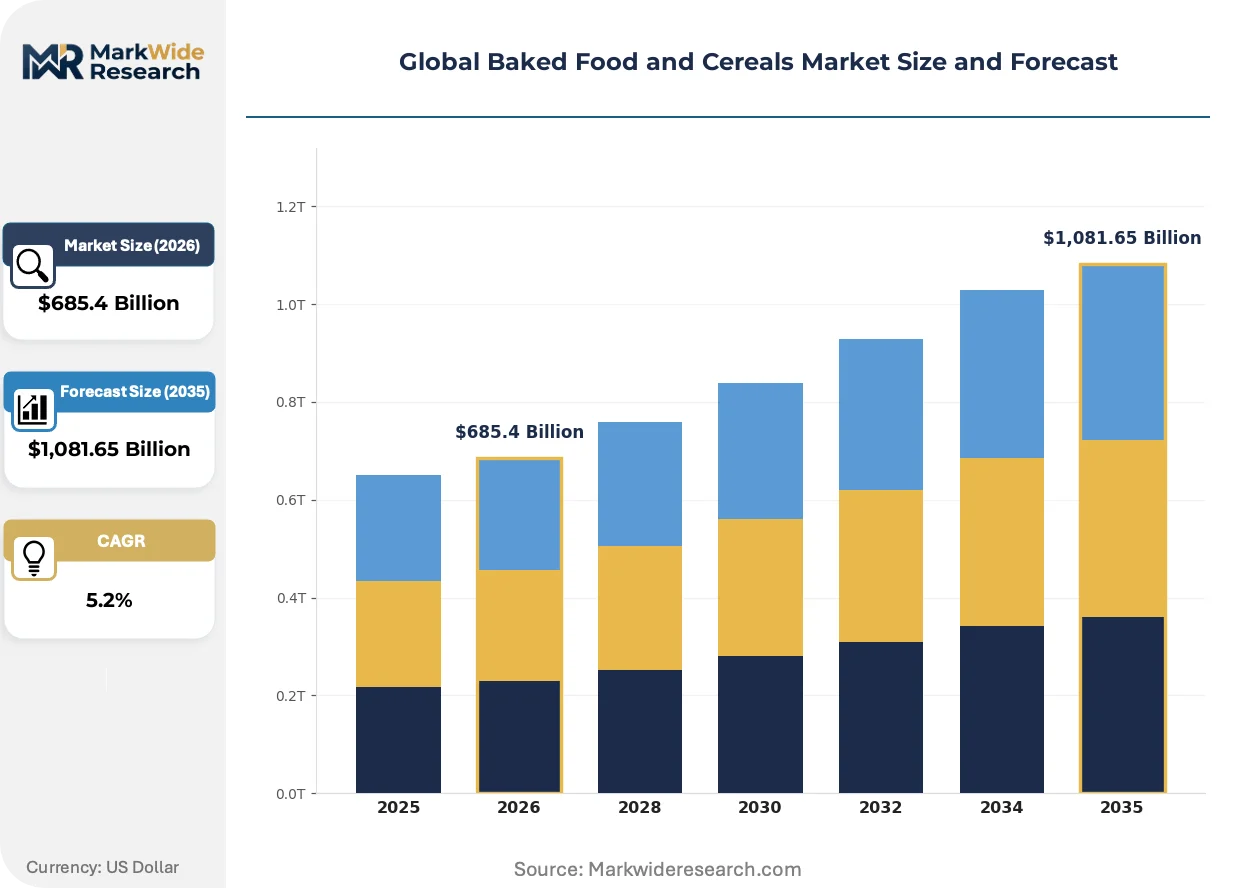
| Market Size in 2026 | $685.4 Billion |
| Market Size in 2035 | $1,081.65 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bread, Cakes, Breakfast Cereals, Biscuits, Rusks, Crackers Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Stores, Wholesale Markets End User: Households, Foodservice Outlets, Institutional Catering, Hotels, Cafes Packaging Type: Plastic Pouches, Paper Bags, Rigid Boxes, Foil Packs, Vacuum Packs |
| Companies Covered | Nestlé S.A., General Mills, Inc., Mondelez International, Inc., Grupo Bimbo, S.A.B. de C.V., Associated British Foods plc, Kellanova, Flowers Foods, Inc., Conagra Brands, Inc., Post Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Baked Food and Cereals Market Shifts & Advancements
Three intersecting forces reshape competitive positioning: thermal processing decarbonization, procurement model digitization, and ingredient transparency mandates. Each trend carries distinct capital and talent requirements.
Precision fermentation for functional proteins is rewriting protein enrichment economics in cereal formulations. North American and European manufacturers integrate these inputs at pilot scale. The technology compresses cost curves for high-protein positioning previously dependent on dairy or soy isolates.
EFSA health-claim assessments tighten evidentiary standards for marketing language across European markets. Reformulation costs rise as substantiation requirements extend to prebiotic and fiber claims. Biscuit and cereal segments face the steepest compliance burdens given their reliance on functional positioning.
Urban Indian households accelerate packaged bread adoption, displacing fresh flatbread procurement from neighborhood mills. Modern trade and quick-commerce platforms capture this rotation through chilled distribution infrastructure. Mumbai and Bangalore clusters exhibit the fastest channel shift velocity.
Global Baked Food and Cereals Market Segmentation
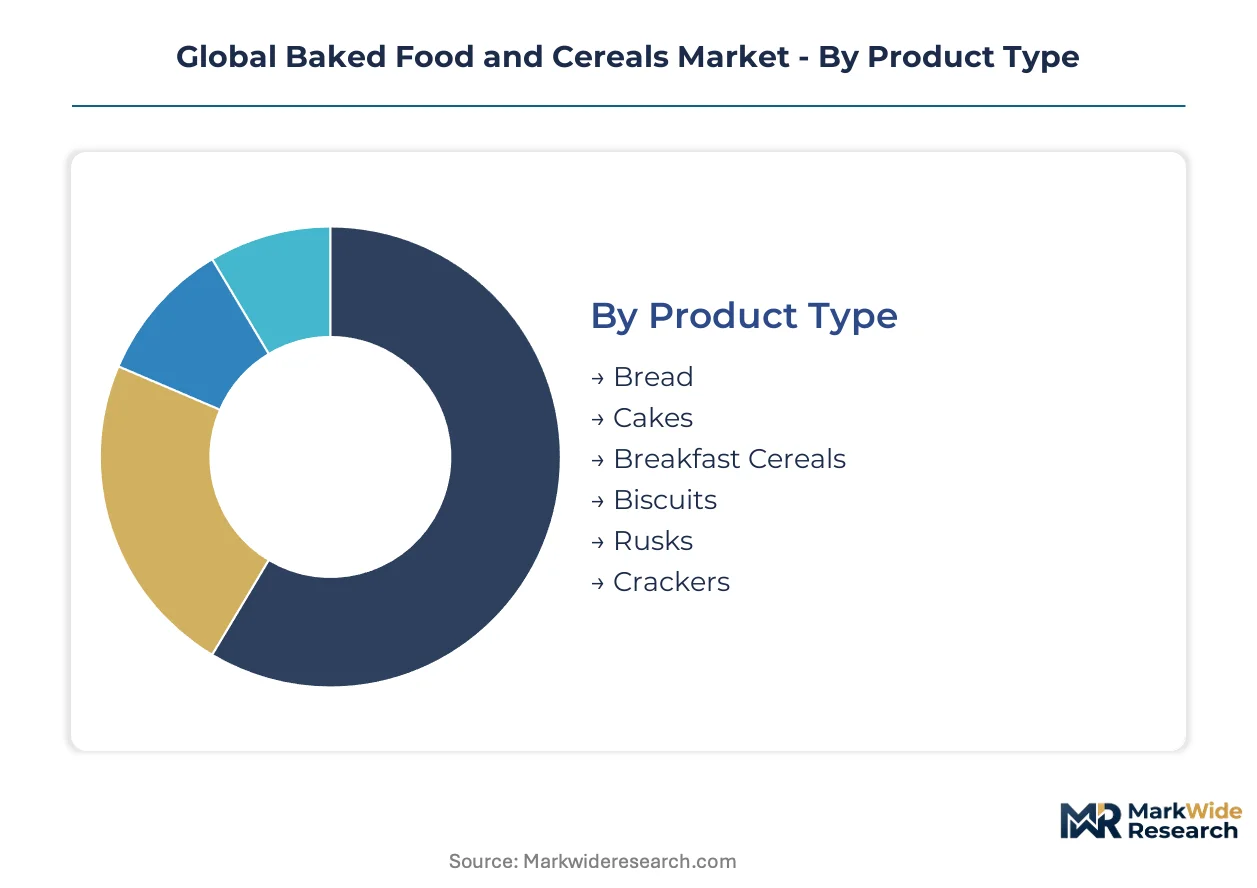
Grain-based product portfolios demand precise segmentation mapping to align thermal processing investments with divergent margin structures and channel access requirements across household, commercial, and institutional demand pools.
Product Type:
Buyers differentiate primarily by consumption occasion frequency and per-unit margin tolerance, with daily staples commanding volume scale and impulse categories capturing premium positioning.
- Bread:High-moisture fermented wheat products with shelf-life targets of 3-7 days for fresh variants and 14-30 days for industrial packaged lines. Demand concentrates in India's urban middle-class households where packaged formats displace traditional flatbread procurement from neighborhood mills.
- Breakfast Cereals:Extruded or flaked grain formulations with moisture content below 5% for ambient stability and extended distribution reach. Southeast Asian healthcare facilities drive institutional adoption through standardized nutrition delivery requirements for patient feeding programs.
- Cakes:Aerated batter products with higher fat and sugar content requiring chilled distribution for extended shelf-life in modern trade channels.
- Biscuits:Low-moisture baked goods with dense packaging ratios enabling premium positioning in duty-free and travel-retail channels.
- Rusks:Twice-baked dried bread products with sub-10% moisture for extended ambient storage in price-sensitive markets.
- Crackers:Fermented flatbreads with neutral flavor profiles serving as carrier platforms for spreads and toppings in snacking occasions.
Volume sits with bread; growth tilts toward breakfast cereals.
Distribution Channel:
Channel selection determines working capital intensity and margin capture, with direct routes bypassing wholesale markups while traditional retail maintains mass-market penetration.
- Supermarkets:Full-range self-service formats with refrigerated and ambient shelving infrastructure supporting fresh and packaged bakery lines. Mumbai and Bangalore clusters exhibit the fastest modern trade expansion velocity in Indian urban markets.
- Online Retailers:Direct-to-consumer subscription models with chilled last-mile delivery capability. North American and European markets bypass traditional wholesale markups through platform-controlled logistics networks.
- Convenience Stores:Small-format proximity retail with limited SKU breadth favoring long-life packaged biscuits and crackers.
- Specialty Stores:Artisan and premium positioning channels with in-store baking capability and clean-label certification focus.
- Wholesale Markets:Bulk distribution nodes serving foodservice and institutional buyers with case-lot minimums and compressed per-unit pricing.
Supermarkets anchor current throughput; online retailers are expanding most quickly.
End User:
User categories separate by nutrition standardization requirements and procurement scale, with institutional buyers demanding batch consistency and households prioritizing variety and convenience.
- Households:Fragmented consumption with preference rotation across fresh and packaged formats. EU urban households face reformulation-driven price adjustments as Green Deal compliance costs transmit through wheat-based product lines.
- Foodservice Outlets:Commercial kitchens requiring consistent portion control and supply reliability for menu integration.
- Institutional Catering:Large-scale feeding programs with mandatory fortification and allergen documentation. SAMR traceability mandates in China impose parallel compliance burdens on exporters serving Asian healthcare and education facilities.
- Hotels:Premium breakfast and in-room dining presentations with brand-differentiated pastry and bread programs.
- Cafes:Beverage-accompaniment focus with pastry and biscuit SKUs selected for display appeal and holding stability.
Households dominate absolute consumption; institutional catering is gaining share fastest.
Packaging Type:
Material selection balances barrier performance against sustainability disclosure requirements, with regulatory pressure accelerating shifts away from conventional plastic formats.
- Plastic Pouches:Flexible multilayer structures with oxygen and moisture barriers for shelf-life extension. EU F-Gas Regulation phase-down timelines compress capital deployment windows for European manufacturers transitioning to lower-carbon production systems.
- Paper Bags:Kraft-based formats with grease-resistant coatings for fresh bread and pastry applications. German and French retail chains mandate paper-first policies ahead of packaging waste directive implementation.
- Rigid Boxes:Structural cartons with premium printing capability for gift and seasonal biscuit assortments.
- Foil Packs:Metallized films with complete light and oxygen exclusion for sensitive cereal and rusk products.
- Vacuum Packs:Modified atmosphere systems with residual oxygen below 1% for extended ambient distribution of sliced bread and specialty cakes.
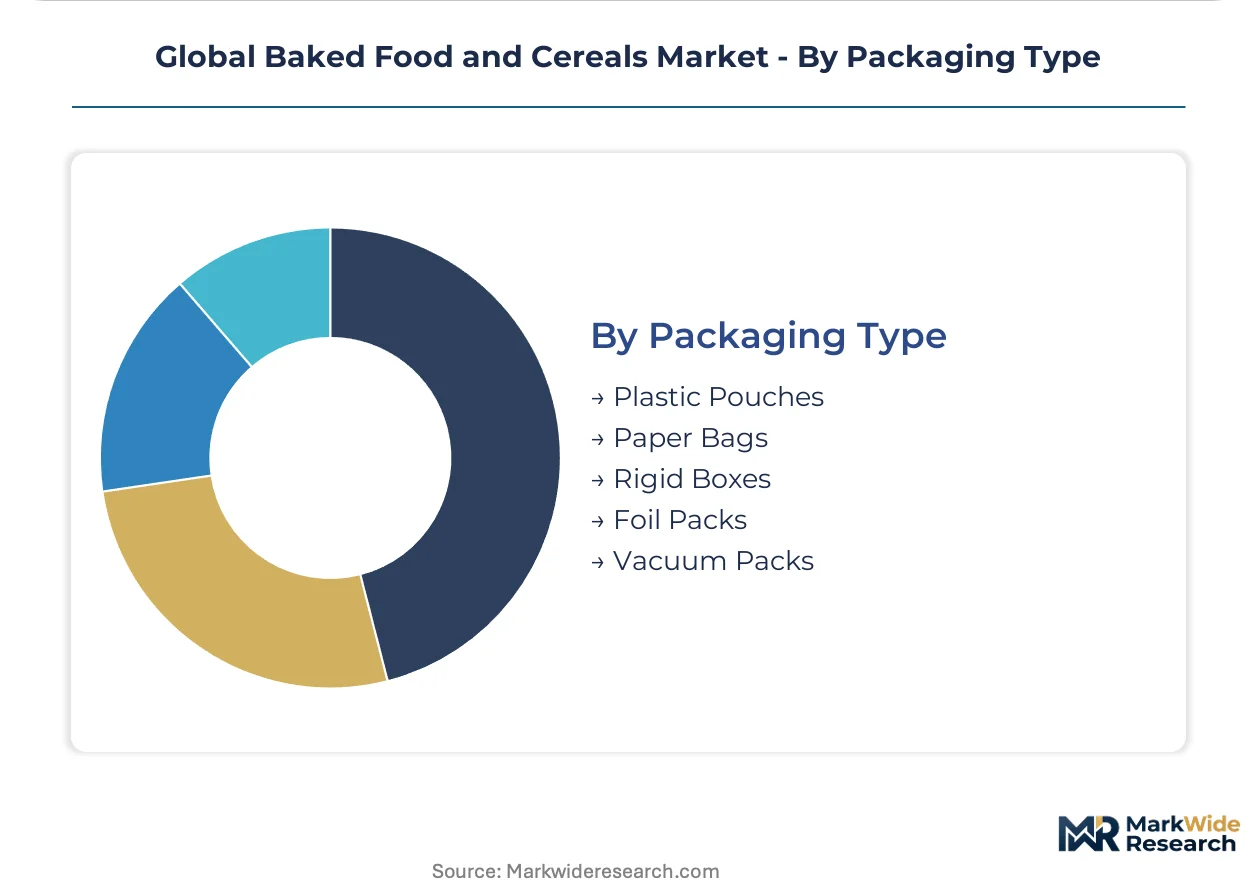
Plastic pouches retain volume leadership; paper bags show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's food processing special economic zones concentrate contract manufacturing for multinational bakery brands seeking tariff-efficient export platforms to Middle Eastern and African markets.
United States
USDA organic certification tailwinds accelerate clean-label cereal launches as FDA nutrition-labeling rules tighten substantiation requirements for health claims. The EPA oversees emissions compliance for thermal processing equipment upgrades in Midwest manufacturing corridors. Chicago anchors industrial baking automation clusters where extrusion technology providers cluster around commodity grain terminals.
Germany
EFSA health-claim assessments compress marketing vocabulary for functional biscuit positioning while EU F-Gas Regulation phase-down mandates accelerate equipment replacement cycles. The EU Green Deal's farm-to-fork sustainability mandates force wheat-based product reformulation across Rhine-Ruhr industrial bakeries. Munich specialty retailers pioneer paper-first packaging policies ahead of EU packaging waste directive implementation.
China
SAMR food-safety traceability mandates impose documentation burdens on cereal exporters while GB standards for fortification reshape product composition for institutional healthcare catering. The MIIT coordinates smart manufacturing upgrades in Shandong grain processing hubs. Qingdao clusters concentrate modified-atmosphere packaging technology for extended shelf-life bread distribution.
India
FSSAI fortification mandates expand addressable markets for packaged breakfast cereals in urban healthcare institutions while PLI scheme incentives attract multinational contract manufacturers. Mumbai and Bangalore exhibit fastest modern trade expansion velocity as quick-commerce platforms displace neighborhood flatbread mills. Gujarat food processing SEZs concentrate export-oriented biscuit and rusk production.
Brazil
ANVISA nutritional labeling convergence with Mercosur standards simplifies cross-border cereal trade while the central bank's monetary policy affects working capital intensity for wheat importers. São Paulo state anchors Latin America's largest industrial bakery complex with backward integration into Paraná wheat sourcing basins. Minas Gerais clusters specialize in gluten-free and clean-label formulation for health-conscious urban consumers.
Global Baked Food and Cereals Market Competitive Landscape
European producers anchor the premium clean-label tier; Latin American specialists hold cost-efficient commodity positions through captive grain sourcing. The vendor base concentrates around three strategic archetypes: multinational diversified food conglomerates with R&D-intensive cereal portfolios, regional bakery chains with dense distribution networks, and private-label manufacturers serving retail channel consolidation. Competitive moves center on M&A for geographic footprint expansion and strategic partnerships for alternative protein ingredient sourcing.
Within the multinational conglomerate tier, Nestlé S.A., General Mills, Inc., and Mondelez International, Inc. exemplify divergent strategic positioning. Nestlé occupies a position emphasizing R&D intensity for reformulation ahead of regulatory deadlines. General Mills represents the archetype of North American market depth with heritage brand portfolios. Mondelez anchors premium positioning through specialty biscuit lines in travel-retail channels. Each sits within distinct geographic and segment specializations rather than direct head-to-head competition.
| Leading Market Players |
|---|
| Nestlé S.A. |
| General Mills, Inc. |
| Mondelez International, Inc. |
| Grupo Bimbo, S.A.B. de C.V. |
| Associated British Foods plc |
| Kellanova |
| Flowers Foods, Inc. |
| Conagra Brands, Inc. |
| Post Holdings, Inc. |
| Others |
Supply & Pricing Matrix
Backward integration into wheat and corn sourcing across Latin American supply basins anchors Grupo Bimbo's cost position while compressing procurement volatility for rival bakers dependent on spot grain markets. This captive supply model generates pricing power through input cost stability that spot-dependent competitors cannot match.
Pricing Analysis
Short lead-time premiums for chilled last-mile delivery command 15-25% markups over ambient distribution in North American and European quick-commerce channels. Three-tier pricing structure across premium clean-label, standard fortified, and economy private-label lines separates organic-certified SKUs from conventional formulations. Pricing pressure stems from Black Sea wheat supply disruptions transmitting directly to flour procurement budgets. Institutional catering buyers exhibit highest price sensitivity due to standardized nutrition mandates and volume procurement scale.
Supply Chain Analysis
Workforce availability constraints in Shandong grain processing hubs and Paraná wheat sourcing basins compress equipment utilization rates for extrusion and thermal processing lines. Manufacturing concentrates in China, Brazil, and Germany, with each node drawing from distinct regional grain reserves. Supply chains rest on wheat, corn, and pulse protein inputs vulnerable to commodity price volatility and climate-driven yield variation. Single-source vulnerability runs through Black Sea wheat corridors. Distribution runs through modern trade supermarkets in India, direct-to-consumer platforms in North America, and wholesale markets serving institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing upstream control over grain sourcing to defend margin position against input cost volatility and regulatory compliance burdens.
For Market Incumbents: Deepen backward integration into regional wheat and corn supply basins to neutralize Black Sea supply disruption risks. Accelerate equipment replacement cycles ahead of EU F-Gas Regulation phase-down deadlines. Prioritize clean-label formulation R&D to capture USDA organic certification tailwinds before disclosure rules tighten. For New Entrants and Emerging Players: The price-point gap between premium organic-certified cereals and economy private-label lines offers white-space entry through mid-tier fortified positioning. Target India's urban middle-class households where packaged bread displaces traditional flatbread procurement. Deploy direct-to-consumer subscription models to bypass wholesale markups in North American markets. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational conglomerates seeking geographic footprint expansion and captive grain supply. Long-term viability hinges on reformulation capability ahead of tightening sustainability disclosure regimes. Watch EFSA health-claim assessment stringency as inflection indicator for marketing compliance costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Sourcing | Captive wheat and corn supply from Paraná basins neutralizes Black Sea volatility for Latin American producers. |
| Clean-Label Reformulation Investment | EU Green Deal farm-to-fork mandates force synthetic preservative elimination ahead of carbon-footprint disclosure deadlines. |
| Direct-to-Consumer Channel Launch | Subscription models bypass wholesale markups in North American markets while capturing repeat purchase data. |
| Precision Fermentation Partnership | Novel protein enrichment technology compresses cost curves for high-protein cereal positioning without dairy isolates. |
| Equipment Decarbonization Upgrade | Low-carbon thermal processing systems satisfy EU F-Gas Regulation phase-down timelines in Rhine-Ruhr facilities. |
Research Methodology
Multi-period observation of grain procurement cost indices, regulatory filing timelines, and channel shift velocities anchored the trend analysis, supplemented by interviews with plant managers at industrial bakery complexes, procurement leads at multinational food conglomerates, category buyers at modern trade retailers, and regulatory affairs specialists navigating EFSA and SAMR compliance frameworks. Secondary validation drew from EU F-Gas Regulation implementation schedules, USDA organic certification databases, FSSAI fortification mandate documents, and customs trade data for wheat and corn flows. Bottom-up volume modeling triangulated against top-down market sizing across product type, distribution channel, and end-user segments.
Segment-weighting approaches applied differential growth assumptions to breakfast cereals versus bread categories based on institutional adoption curves and household penetration rates. Product type, distribution channel, end-user category, and packaging format dimensions structured the analytical framework across the projection horizon. CAGRs were derived from regression analysis of historical volume trajectories adjusted for regulatory inflection points. Forecast inputs incorporated SAMR traceability mandate compliance costs and EU Green Deal reformulation expenditure timelines.
Inputs from regulatory filing databases and grain futures markets were available through the study window; gaps in private-label manufacturer financial disclosures introduce uncertainty bands around margin compression estimates. Forecasts reflect assumptions regarding wheat supply corridor stability and clean-label consumer willingness-to-pay elasticity. Material deviation in Black Sea export volumes or EFSA health-claim evidentiary standards warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Teaseed Cake Market
Bakery Products
Pastries Market
Bakery Products
Ezekiel Bread Market
Bakery Products
Europe Sourdough Market
Bakery Products
Bahrain Bakery Product Market
Bakery Products
Dough Conveyor Market
Bakery Products
APMEA Frozen Bakery Products Market
Bakery Products
Global Wafer Biscuits Market
Bakery Products
Frozen Bakery Products Market
Bakery Products
Cakes and Pastries Market
Bakery Products
North America Pizza Oven Market
Bakery Products
Bread Market
Bakery Products
Bread Improver Market
Bakery Products
Ice Cream Market
Bakery Products
United States Cookies Market
Bakery Products
Wedding Cakes Market