
 ASEAN Luxury Vinyl Tile (LVT) Market | 2026-2036
ASEAN Luxury Vinyl Tile (LVT) Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Luxury Vinyl Tile (LVT) Market Outlook
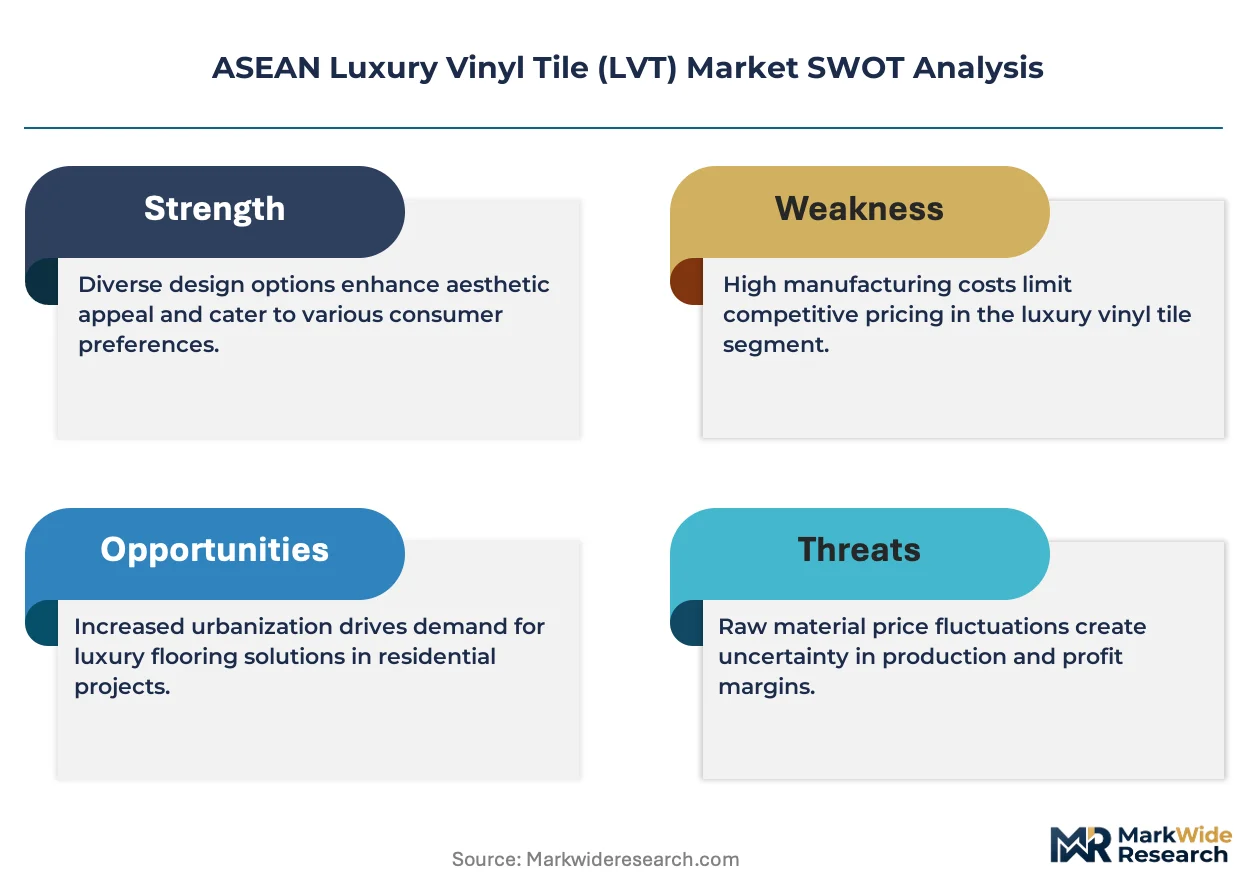
Malaysia's Green Building Index accreditation is pivoting commercial developers toward low-emission flooring specifications across Kuala Lumpur and Penang. Tarkett leverages its European manufacturing heritage to supply certified low-VOC plank collections to ASEAN hospitality chains. Inovar anchors its competitive position through integrated production facilities in Thailand that compress lead times for regional distributors. Gerflor differentiates via specialized acoustic-backed LVT systems targeting high-rise residential towers in Singapore and Bangkok.
Luxury Vinyl Tile denotes a multi-layer synthetic flooring product comprising a PVC core, printed decorative film, and protective wear layer typically measured in mil thickness, engineered to replicate natural materials while delivering superior water resistance and dimensional stability. Planks dominate ASEAN commercial procurement due to their wood-look authenticity and compatibility with floating click-lock systems, while WPC cores capture margin pools in premium hospitality installations requiring enhanced underfoot comfort. The hospitality end-user segment leads volume absorption across Thailand and Vietnam resort developments, whereas glue-down installation sustains share in institutional healthcare and education projects demanding permanent adhesion and seam integrity.
Thailand's Industrial Standards Institute (TISI) mandates formaldehyde emission thresholds for interior finishes, compelling importers to certify compliance through accredited testing laboratories. Singapore's Building and Construction Authority (BCA) Green Mark program incentivizes flooring selections with recycled content and regional material sourcing, reshaping supplier qualification criteria. Indonesia's Ministry of Industry enforces SNI labeling for PVC building products, creating compliance barriers for uncertified imports. Stakeholders must monitor evolving sub-national green procurement rules in Vietnam's Da Nang and Ho Chi Minh City corridors, where municipal authorities are drafting stricter indoor air quality standards for public buildings.
Market Dynamics
Green building certification mandates across ASEAN member states are compressing supplier qualification timelines and redrawing procurement specifications toward low-emission, certified flooring systems.
Growth Catalysts
- Malaysia's Green Building Index:Commercial developers in Kuala Lumpur and Penang now specify low-VOC finishes as accreditation prerequisites, expanding the addressable market for certified plank collections.
- Hospitality sector concentration:Thailand and Vietnam resort corridors absorb substantial plank volumes for high-traffic lobbies and guest rooms where moisture resistance and dimensional stability outweigh natural material alternatives.
- Urban belt densification:Indonesia's Jakarta-Bandung corridor generates sustained institutional demand for glue-down LVT in healthcare and education facilities requiring permanent adhesion and seam integrity.
Market Restraints
- PVC resin price volatility:Feedstock cost fluctuations compress margin pools for producers lacking backward integration into polymer supply.
- Import certification barriers:Indonesia's SNI labeling mandate for PVC building products creates compliance friction for uncertified foreign suppliers, concentrating supply among accredited domestic distributors.
- Ceramic tile substitution:Price-sensitive residential segments in secondary Vietnamese cities pivot toward glazed porcelain alternatives where water exposure is minimal.
Strategic Opportunities
- Da Nang municipal standards:Vietnam's emerging indoor air quality regulations for public buildings will favor early-moving suppliers with pre-certified low-emission inventories.
- Acoustic-backed systems:High-rise residential towers in Singapore and Bangkok create demand for specialized underlayment-integrated planks addressing impact sound transmission.
- WPC core convergence:Premium hospitality installations are specifying wood-plastic composite cores for enhanced underfoot comfort, opening margin expansion above standard SPC alternatives.
Industry Challenges
- Multi-jurisdiction compliance talent:Suppliers struggle to staff regulatory affairs functions capable of navigating simultaneous TISI, SNI, and BCA Green Mark certification pathways.
- Testing laboratory capacity:Accredited facilities for formaldehyde emission verification face backlog pressures, extending product launch timelines by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Luxury Vinyl Tile (LVT) Market |
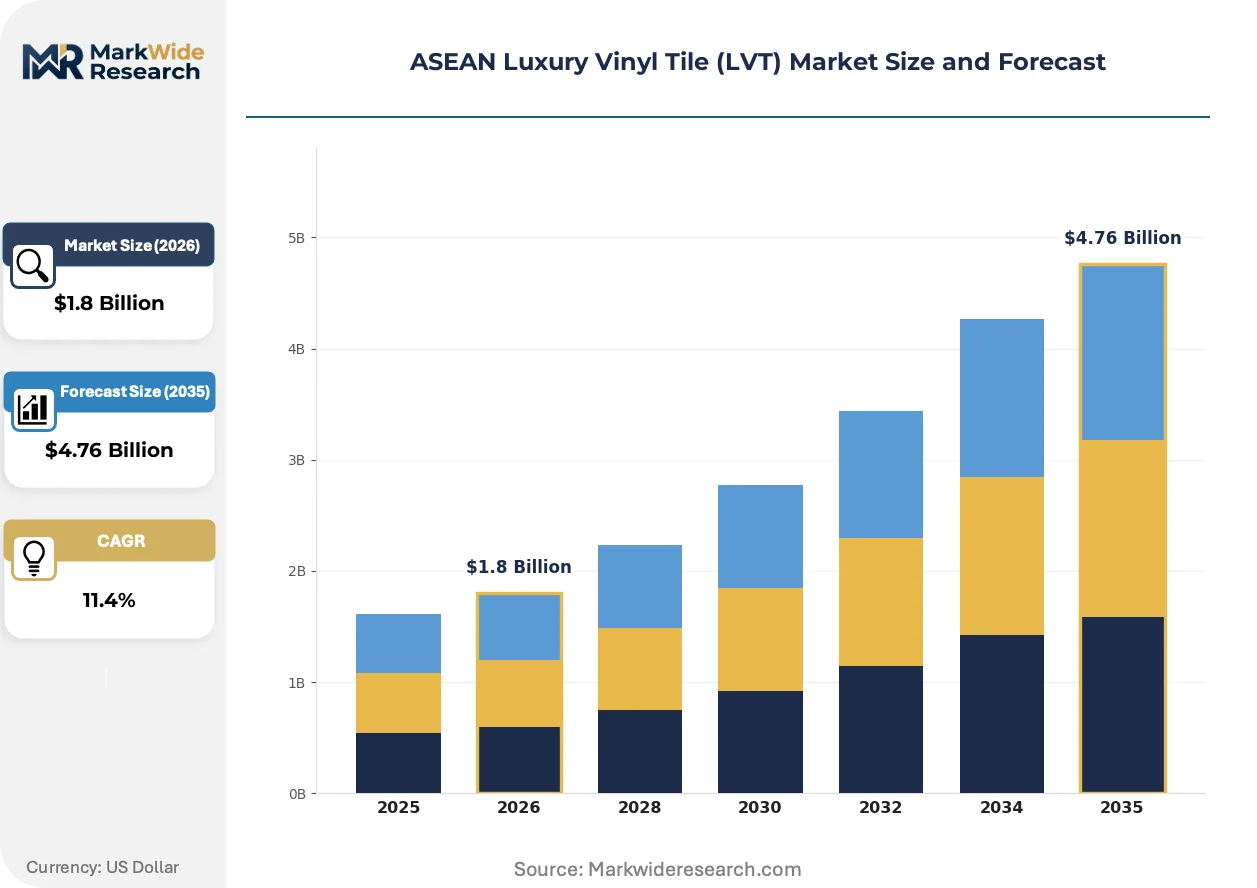
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Planks, Tiles, Sheets, WPC End User: Residential, Commercial, Institutional, Hospitality Installation Type: Glue-down, Floating, Loose Lay, Click Lock Design Style: Natural Wood, Stone Look, Abstract, Others |
| Companies Covered | APO Floors, Tarkett, Inovar, Gerflor, Armstrong Flooring, Polyflor, Rumah Lantai Indonesia, Forbo Flooring Systems, Hanyo, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Luxury Vinyl Tile (LVT) Market Strategic Shifts
Digital printing fidelity and core material engineering are collapsing the performance gap between synthetic flooring and natural substrates, while certification-driven procurement filters reshape competitive access.
Advanced rotogravure and digital inkjet systems are integrating photorealistic wood-grain replication with embossed-in-register texture mapping. Hospitality developers across Phuket and Nha Trang specify these collections for luxury villa installations where visual authenticity must withstand close inspection. The technology is integrating premium aesthetic tiers into mid-range price bands, compressing differentiation windows for basic print-film alternatives.
Singapore's Building and Construction Authority Green Mark program now weights recycled content and regional material sourcing in flooring selection scoring. Commercial fit-out contractors must document supply chain provenance to achieve certification tiers, reshaping supplier qualification criteria. High-specification office developments in the Marina Bay district are responding by mandating recycled-content LVT with third-party chain-of-custody verification.
Developer procurement teams are consolidating flooring specifications across multi-site hospitality portfolios, replacing project-by-project bidding with framework agreements. Regional hospitality chains in Thailand and Vietnam now engage directly with manufacturers for master supply contracts, disintermediating traditional distributor layers. This concentration is most visible in Bangkok and Ho Chi Minh City, where procurement functions have centralized under group-level technical directors with material science backgrounds.
ASEAN Luxury Vinyl Tile (LVT) Market Segmentation
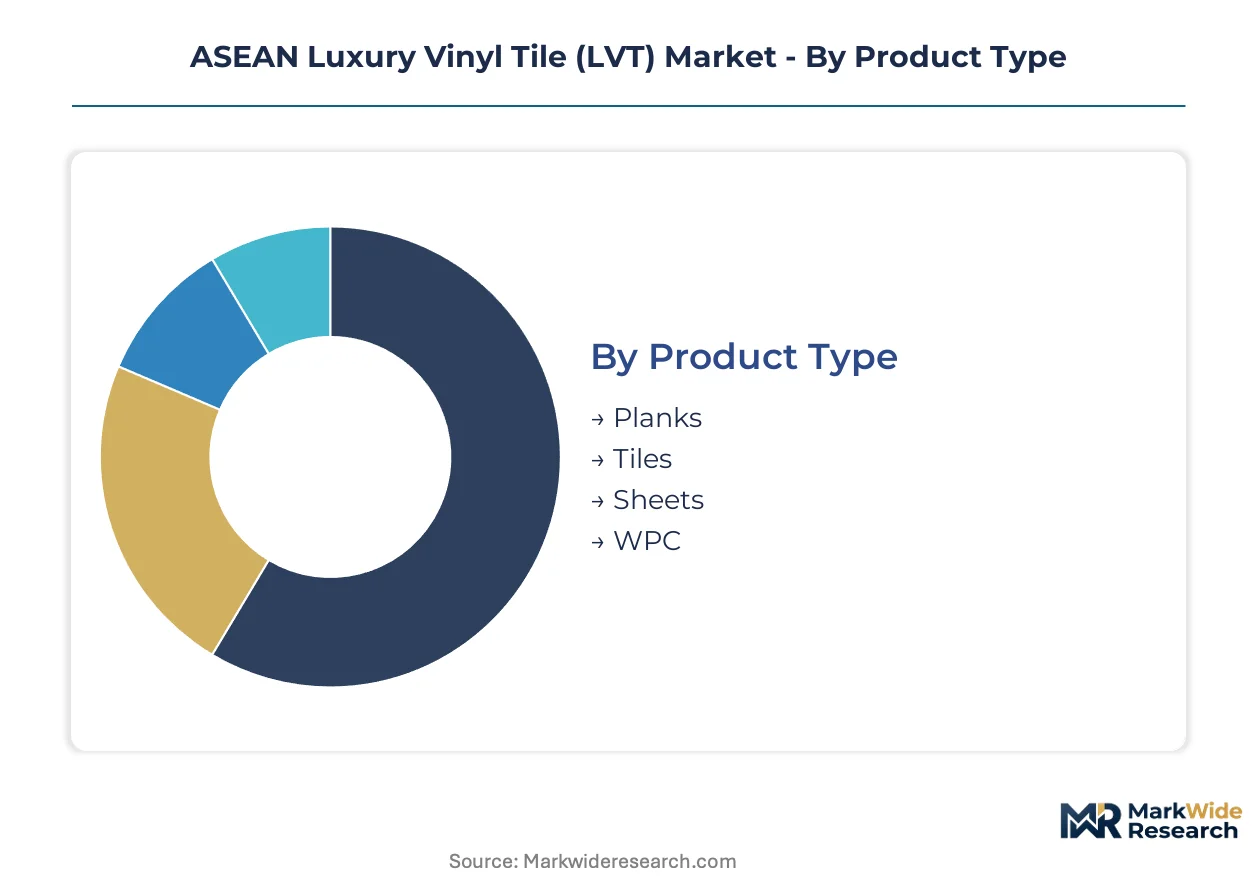
Segmentation in the ASEAN LVT market reveals how specification choices cascade through procurement decisions, certification requirements, and installation protocols. Each dimension—product architecture, end-use environment, mechanical fixation method, and surface aesthetic—creates distinct competitive arenas with divergent margin structures and compliance obligations.
Product Type:
Core composition and dimensional format define performance ceilings, installation labor requirements, and moisture resistance ratings across tropical deployment environments.
- Planks:Rectilinear formats with printed decorative film layers replicate timber aesthetics while accommodating floating click-lock systems. Hospitality developers across Thailand's Phuket and Vietnam's Nha Trang corridors specify planks for guest room installations where dimensional stability must withstand humidity cycling. The format dominates commercial procurement due to compatibility with rapid-install floating systems.
- WPC:Wood-plastic composite cores integrate foamed polymer matrices with cellulose fiber content, delivering enhanced underfoot cushioning and acoustic dampening. Premium resort developments in Indonesia's Bali and Vietnam's Da Nang specify WPC for luxury villa applications where occupant comfort justifies material cost premiums. The segment captures margin expansion above standard SPC alternatives in hospitality installations prioritizing experiential quality.
- Tiles:Square-format products replicate ceramic or stone aesthetics with grout-line simulation for traditional flooring replacement scenarios.
- Sheets:Continuous roll formats enable seamless installation across large healthcare and institutional footprints requiring hygienic surface continuity.
Mature deployment sits with planks. Newer deployment is concentrated in WPC.
End User:
Procurement authority and specification complexity vary sharply across customer categories, from centralized hospitality chains to fragmented residential decision-makers.
- Hospitality:Resort and hotel developers operate through consolidated procurement functions with material science competencies, enabling direct manufacturer engagement. Thailand and Vietnam resort corridors absorb substantial volumes for high-traffic lobbies and guest rooms where moisture resistance and dimensional stability outweigh natural material alternatives. Framework agreements across multi-site portfolios are displacing project-by-project bidding.
- Commercial:Office and retail fit-out contractors respond to green building certification mandates with documented supply chain provenance requirements. Malaysia's Green Building Index accreditation in Kuala Lumpur and Penang drives specification toward low-VOC finishes with third-party chain-of-custody verification.
- Residential:Individual homeowners and small-scale renovators prioritize visual authenticity and installation simplicity over technical specifications.
- Institutional:Healthcare and education procurement in Indonesia's Jakarta-Bandung corridor demands permanent adhesion and seam integrity for heavy-duty traffic loads.
Volume concentration resides with hospitality. Specification sophistication is climbing fastest in commercial.
Installation Type:
Mechanical fixation method determines substrate preparation requirements, installation speed, and long-term repairability across ASEAN building stock.
- Glue-down:Permanent adhesive bonding delivers maximum dimensional stability and seam integrity for institutional healthcare and education projects. Indonesia's Jakarta-Bandung urban belt generates sustained demand where heavy rolling loads and permanent occupancy patterns justify extended installation timelines.
- Click Lock:Floating mechanical interlock systems enable rapid deployment without adhesive curing periods, aligning with hospitality renovation windows. Thailand resort developers favor click-lock planks for phased guest room refreshes minimizing revenue displacement.
- Floating:Loose-lay systems with perimeter anchoring accommodate substrate irregularities common in ASEAN renovation projects.
- Loose Lay:Friction-backed products target temporary or modular installations requiring future repositioning capability.
Permanent fixation dominates institutional procurement. Floating systems are gaining share fastest in hospitality renovation cycles.
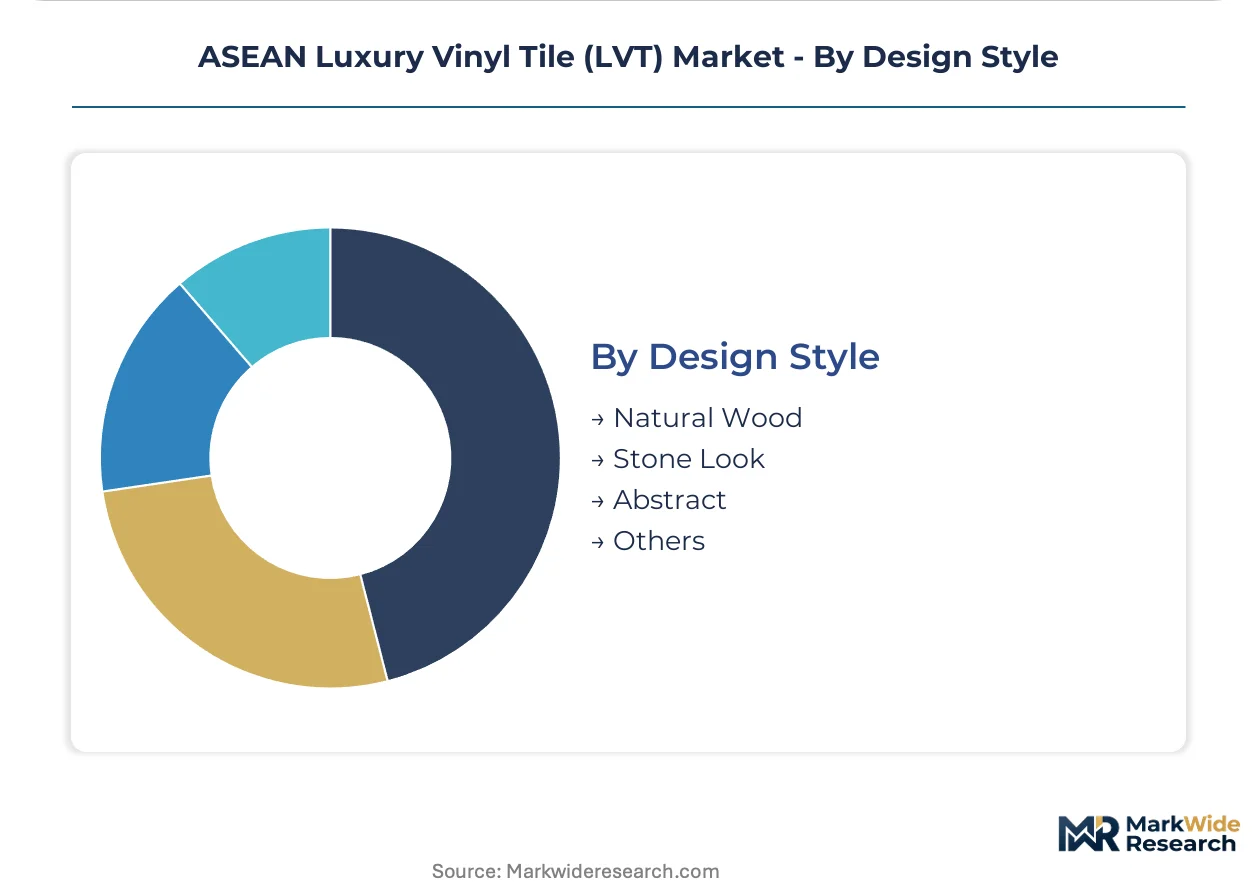
Design Style:
Surface aesthetic selection reflects regional material preferences, architectural vernaculars, and the performance limitations of natural substrates in tropical climates.
- Natural Wood:Photorealistic timber grain replication with embossed-in-register texture mapping satisfies demand for warm interior environments without hardwood's moisture susceptibility. Advanced rotogravure and digital inkjet systems integrate premium aesthetic tiers into mid-range price bands across Phuket and Nha Trang luxury villa installations.
- Stone Look:Marble and travertine replication targets commercial lobbies and hospitality public areas where natural stone maintenance costs are prohibitive.
- Abstract:Non-representational patterns serve contemporary commercial interiors and branded hospitality concepts seeking differentiation.
- Others:Specialty designs including metallic finishes and custom-printed corporate identity flooring serve niche specification requirements.
Natural wood aesthetics command the largest specification share. Abstract patterns are expanding most quickly in contemporary commercial fit-outs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jakarta anchors ASEAN LVT demand through Indonesia's Ministry of Industry enforcement of SNI labeling for PVC building products, which concentrates supply among accredited domestic distributors serving the Jakarta-Bandung urban belt.
Thailand
Phuket and Bangkok resort corridors absorb substantial plank volumes for high-traffic lobbies and guest rooms. The Industrial Standards Institute mandates formaldehyde emission thresholds for interior finishes, compelling importers to certify compliance through accredited testing laboratories. Hospitality developers favor click-lock planks for phased guest room refreshes minimizing revenue displacement.
Vietnam
Nha Trang and Da Nang resort developments specify photorealistic timber grain collections for luxury villa installations. Municipal authorities in Da Nang and Ho Chi Minh City corridors are drafting stricter indoor air quality standards for public buildings. Vietnam's booming resort corridor generates sustained institutional demand for glue-down LVT in healthcare and education facilities.
Malaysia
Kuala Lumpur and Penang commercial developers now specify low-VOC finishes as Green Building Index accreditation prerequisites. The national green building certification program weights recycled content and regional material sourcing in flooring selection scoring. High-specification office developments in the Marina Bay district mandate recycled-content LVT with third-party chain-of-custody verification.
Singapore
High-rise residential towers in Singapore and Bangkok create demand for specialized acoustic-backed LVT systems addressing impact sound transmission. The Building and Construction Authority Green Mark program incentivizes flooring selections with recycled content and regional material sourcing. Commercial fit-out contractors must document supply chain provenance to achieve certification tiers.
Indonesia
Bali resort developments specify WPC cores for luxury villa applications where occupant comfort justifies material cost premiums. The Ministry of Industry enforces SNI labeling for PVC building products, creating compliance barriers for uncertified imports. The Jakarta-Bandung urban belt generates sustained institutional demand for glue-down LVT in healthcare and education projects demanding permanent adhesion.
ASEAN Luxury Vinyl Tile (LVT) Market Competitive Environment
The competitive structure tilts toward integrated regional manufacturers with captive polymer supply and European heritage brands leveraging certification credibility. Tiered differentiation separates premium hospitality specialists from standard commercial suppliers, with mid-market players competing on distributor network density. Two strategic archetypes dominate: vertically integrated producers compressing lead times through regional manufacturing bases, and design-forward brands commanding specification authority through green certification alignment. Capacity expansion and portfolio diversification toward WPC cores represent the dominant competitive moves reshaping positioning.
Among European heritage suppliers, Tarkett leverages its manufacturing base to supply certified low-VOC plank collections to ASEAN hospitality chains. Inovar anchors its competitive position through integrated production facilities in Thailand that compress lead times for regional distributors. Gerflor occupies a position within the acoustic-specialist tier, differentiating via specialized acoustic-backed LVT systems targeting high-rise residential towers. These three exemplify how certification alignment and regional manufacturing integration determine competitive access under tightening green procurement standards.
| Leading Market Players |
|---|
| APO Floors |
| Tarkett |
| Inovar |
| Gerflor |
| Armstrong Flooring |
| Polyflor |
| Rumah Lantai Indonesia |
| Forbo Flooring Systems |
| Hanyo |
| Others |
Value Chain & Pricing Dynamics
Ethylene price indices from Singapore and Northeast Asian benchmarks cascade through PVC resin markets into three distinct pricing tiers across ASEAN LVT procurement. Feedstock volatility compresses margins for distributors lacking captive polymer supply while amplifying bargaining power for integrated manufacturers serving hospitality chains.
Pricing Analysis
Value-based pricing anchors on green certification outcomes, with Green Building Index and BCA Green Mark compliance commanding material premiums over uncertified alternatives. Price differentiation separates SPC core specifications from WPC hospitality tiers and acoustic-backed residential systems. Cost compression in standard-grade planks is intensifying due to ceramic tile substitution in Vietnamese secondary cities. Residential renovators exhibit highest price sensitivity, whereas hospitality procurement teams prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
PVC resin supply rests on petrochemical complexes in Thailand, South Korea, and Singapore, with specialty additives drawn from Japanese and German chemical producers. Raw material dependencies encompass plasticizers from Malaysian oleochemical plants, calcium carbonate fillers from Vietnamese quarries, and wear-layer films from Taiwanese extrusion facilities. Single-source vulnerability concentrates in SNI-certified domestic distribution for Indonesian institutional projects. Distribution runs through regional distributor networks in Bangkok, Jakarta, and Ho Chi Minh City, with direct manufacturer engagement displacing intermediaries in hospitality procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASEAN LVT competition is a vertical-integration race, with players pursuing backward control over PVC resin supply to defend margin pools against feedstock volatility.
For Market Incumbents: Cement market position through captive production of WPC cores in Thailand and certification pre-positioning for Vietnam's emerging municipal air quality standards. Ceramic tile substitution in price-sensitive Vietnamese residential segments threatens volume share. Backward integration into polymer compounding operations preserves margin capture. For New Entrants and Emerging Players: Launch via specialized acoustic-backed systems targeting Singapore high-rise residential towers, where impact sound transmission regulations create specification barriers for generic competitors. Da Nang's draft indoor air quality standards represent the most penetrable regulatory entry point. Pursue direct engagement with centralized hospitality procurement functions replacing traditional distributor relationships. For Investors and Strategic Acquirers: The window for entry favors integrated manufacturers with SNI certification pathways and regional production footprints over pure-brand distributors. Long-term viability hinges on green certification alignment as procurement filters tighten across Malaysia and Singapore. Watch for backlog pressures at TISI-accredited testing laboratories as an inflection indicator for product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PVC Resin | Captive polymer supply insulates margin pools from ethylene price volatility in Singapore benchmarks. |
| Green Certification Pre-Positioning | Early compliance with Da Nang municipal air quality standards secures specification lock-in for public building projects. |
| WPC Core Capacity Expansion | Wood-plastic composite production captures hospitality premium tiers in Bali and Phuket resort developments. |
| Direct Hospitality Procurement Engagement | Framework agreements with centralized technical directors disintermediate distributor layers in Bangkok and Ho Chi Minh City. |
| Acoustic-Backed System Development | Specialized underlayment integration addresses BCA Green Mark requirements for Singapore high-rise residential towers. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hospitality procurement directors, commercial fit-out contractors, flooring distributors, green building consultants, and polymer supply specialists. Secondary sources encompassed TISI certification databases, BCA Green Mark project registries, SNI labeling records, and ASEAN customs harmonized system trade flows. Bottom-up volume estimates triangulated against top-down construction spending allocations.
Data-stream reconciliation across product type, installation method, end-user segment, core composition, and design aesthetic dimensions generated volume and value outputs over the projection horizon. CAGRs derived from regression analysis of historical construction activity, hospitality development pipelines, and green building certification adoption curves. Forecast inputs incorporated PVC resin price elasticity coefficients and substitution elasticity estimates for ceramic tile competitive dynamics.
The model assumes a particular technology adoption path; alternative pathways for WPC core penetration would alter the outlook if hospitality developers accelerate comfort-specification trends. Forecasts reflect assumptions regarding regulatory enforcement continuity for SNI, TISI, and BCA programs. A small set of triggers—municipal air quality standard finalization in Vietnam, ethylene price shock magnitude, ceramic tile pricing campaigns—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Mechanically Fastened Cross-Laminated Timber Market
Building & Construction Materials
North America Rainscreen Cladding Market
Building & Construction Materials
Concrete Resurfacer Market
Building & Construction Materials
PU Roof Window Market
Building & Construction Materials
Asia-Pacific Gypsum Board Market
Building & Construction Materials
Global Screw Piles Market
Building & Construction Materials
North America Metallic Barn Doors Market
Building & Construction Materials
China Marble Market
Building & Construction Materials
GCC Ceramic Tiles Market
Building & Construction Materials
North America Ceiling Tiles Market
Building & Construction Materials
North America Concrete Superplasticizer Market
Building & Construction Materials
Sheet Piling Market
Building & Construction Materials
Insulated Wall Panels Market
Building & Construction Materials
India Faucet Market
Building & Construction Materials
Poland Ceramic Tiles Market
Building & Construction Materials
Floor Screeds Market