
 Travertine Market | 2026-2036
Travertine Market Size, Share, and Industry Trends Forecast 2026-2036
Travertine Market Analysis
Multi-source procurement from Anatolian and Mexican quarries is broadening supply options for large-scale facade projects. Temmer Marble leverages its integrated quarry-to-fabrication model to sustain margin control across the value chain. Levantina anchors Mediterranean supply through its extensive Spanish and Portuguese stone holdings. Buechel Stone Corp competes in North American architectural specifications with its domestic travertine and limestone portfolio.
Travertine is a terrestrial sedimentary limestone formed by mineral precipitation from geothermal springs, characterized by natural voids and veining that require resin filling and honing for structural applications. Its primary commercial purpose centers on interior flooring, exterior cladding, and landscape hardscaping where aesthetic warmth and natural variation command premium positioning. Slabs and tiles occupy the highest value tiers in finish-sensitive hospitality and residential projects, while pavers dominate volume in outdoor landscaping where tumbled and brushed finishes reduce slip hazards. Polished travertine leads margin pools in countertop applications despite its porosity limitations, whereas honed surfaces sustain broader flooring adoption.
Turkey's Ministry of Environment applies extraction quotas through MEE oversight, while CE marking under EU CPR governs structural stone performance in European construction. Saudi Arabia's Saudi Building Code and giga-project material specifications are reshaping import certification requirements for facade-grade travertine. Stakeholders must monitor how evolving carbon-border adjustments and embodied-carbon disclosure rules affect quarry-to-site supply economics.
Market Dynamics
Saudi Arabia's giga-project pipeline is compressing specification timelines and forcing travertine suppliers to pre-certify large-format facade slabs before quarry allocation, fundamentally restructuring how extraction capacity gets committed.
Growth Catalysts
- Saudi Building Code facade mandates:Structural performance requirements for exterior cladding in tourism zones are specifying travertine over composite alternatives. Certification protocols under the Saudi Building Code are accelerating material pre-approval cycles.
- Resin-injection void filling:Automated vacuum-pressure resin systems are reducing slab rejection rates and enabling thinner cuts for high-rise applications. Fabricators in Turkey and Italy are retrofitting production lines with this equipment.
- Spa and wellness construction:Thermal properties and aesthetic warmth of honed travertine are dominating specification for hydrotherapy environments. Mediterranean resort developers are standardizing on cross-cut vein patterns.
Market Restraints
- Diesel and electricity input volatility:Quarry extraction and block cutting are energy-intensive processes. Turkish operations face compressed margins when fuel costs spike during seasonal demand windows.
- Anatolian supply concentration:Denizli and Afyon provinces control over half of export-grade reserves. Permit delays under Turkey's MEE environmental compliance rules are extending lead times for new quarry openings.
- Porosity versus porcelain substitution:Engineered sintered stone offers lower maintenance for high-traffic flooring. Specifiers in commercial hospitality are substituting away from travertine in lobby and corridor applications.
Strategic Opportunities
- Mexican quarry development:Coahuila and Nuevo Leon deposits remain underexploited for architectural-grade material. North American fabricators are exploring direct offtake agreements to bypass Mediterranean shipping bottlenecks.
- Carbon-border adjustment positioning:EU CBAM implementation is creating first-mover advantage for quarries with verified low-carbon extraction. Portuguese and Spanish operators are investing in photovoltaic-powered cutting plants.
- Digital templating and waterjet integration:CNC-guided waterjet cutting combined with 3D surface scanning is enabling complex geometric facade panels. Italian equipment suppliers are bundling software-hardware packages for mid-scale fabricators.
Industry Challenges
- Master stone carver skill scarcity:Hand-finishing of custom architectural elements requires generational knowledge transfer. Italian and Turkish vocational pipelines are not replacing retiring craftsmen at replacement rates.
- CE marking timeline compression:CPR compliance testing for structural stone performance now requires extended freeze-thaw and flexural strength documentation. Laboratories in Modena and Istanbul are booking six-month lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Travertine Market |
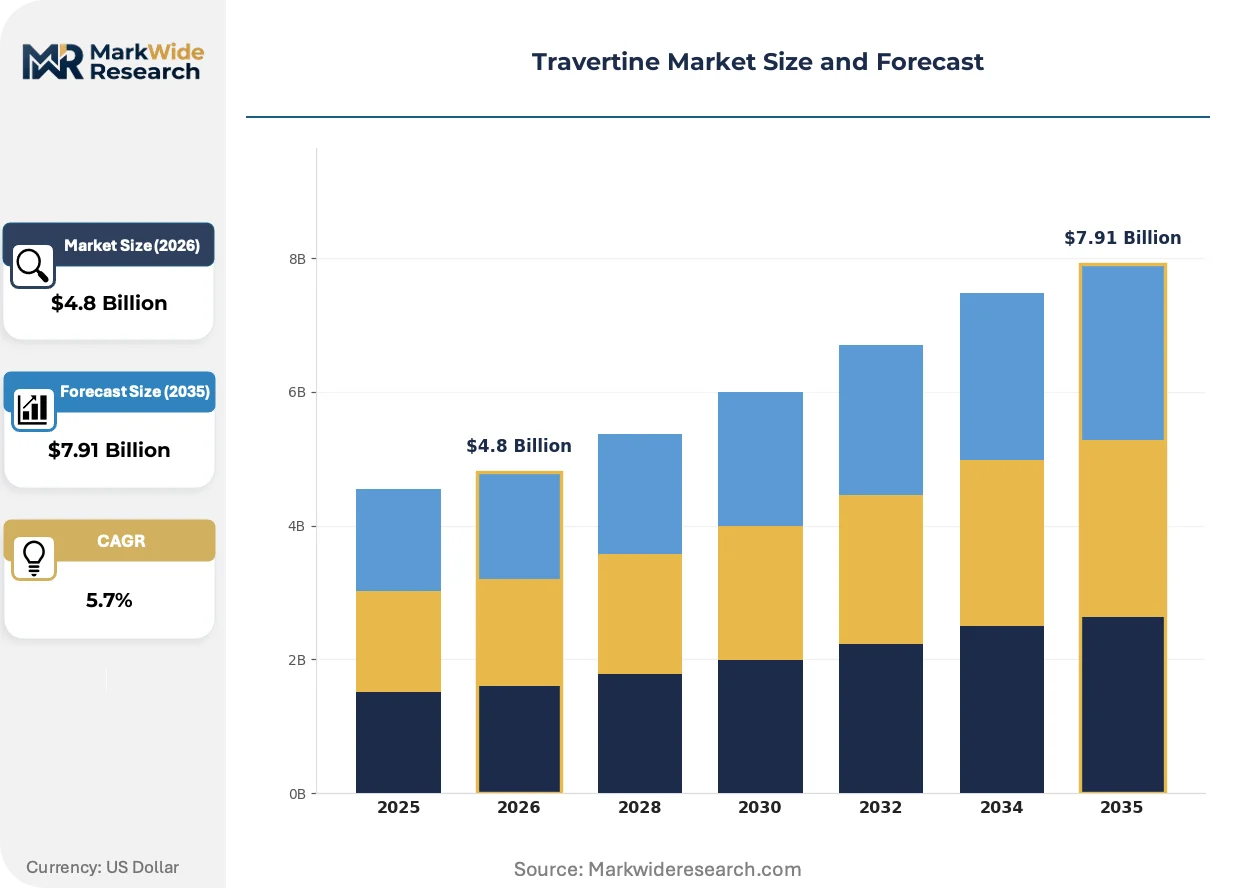
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blocks, Slabs, Tiles, Pavers Application: Flooring, Wall Cladding, Countertops, Landscaping Finish Type: Polished, Honed, Tumbled, Brushed Distribution Channel: Online Retail, Direct Sales, Showrooms, Distributors |
| Companies Covered | Temmer Marble, Dermitzakis, Indiana Limestone Company, Topalidis, Namco CO. Srl, Buechel Stone Corp, Levantina, MGT Stone Co, Natamar Madencilik San. Ve Tic.lTd Sti, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Travertine Market Emerging Trajectories
Digital measurement and automated finishing are collapsing the traditional gap between raw block extraction and precision architectural installation. These technologies are enabling new geometries while compressing project delivery schedules.
Resin-injection systems with vacuum-pressure control are integrating into continuous processing lines at major fabrication centers. High-end hospitality developers in the Middle East are specifying pre-filled slabs to eliminate field sealing delays. This integration is compressing the traditional separation between quarry rough-processing and final architectural finishing, consolidating margin capture at integrated operators.
EU Carbon Border Adjustment Mechanism reporting requirements are reshaping documentation obligations for stone importers. Travertine shipments into European construction projects now require verified embodied-carbon declarations from extraction through fabrication. Mediterranean suppliers with photovoltaic-powered cutting operations are capturing specification preference from sustainability-focused developers in Germany and the Netherlands.
Direct quarry-to-project procurement models are displacing traditional distributor intermediaries in large-scale developments. Saudi giga-project developers are establishing multi-year offtake agreements with specific Turkish quarries, locking in volume and vein consistency. This pattern is most visible in the Red Sea tourism corridor, where facade material continuity across multiple resorts is being written into master development agreements.
Travertine Market Segmentation
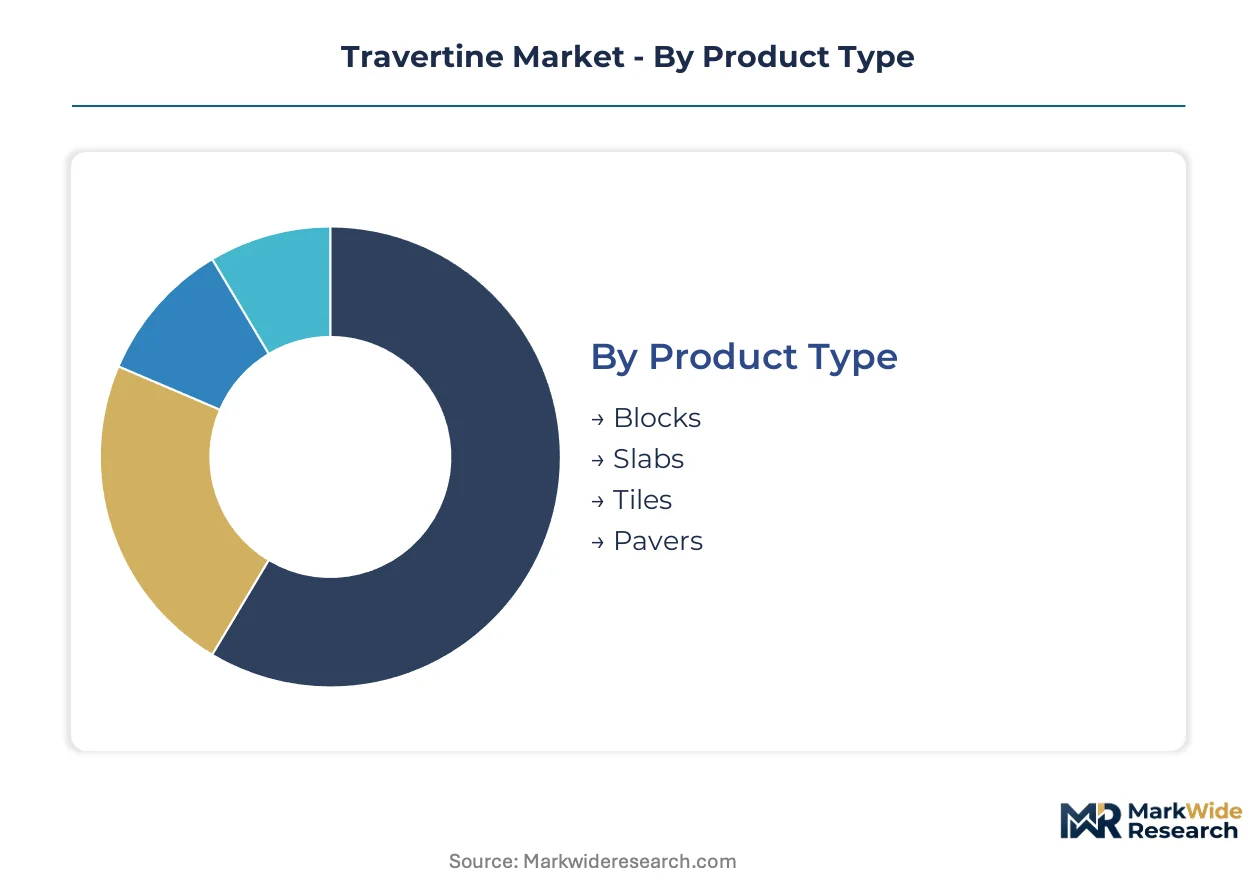
Travertine procurement decisions split sharply between structural performance requirements and aesthetic finish specifications. Architects and developers navigate four distinct segmentation dimensions that determine quarry allocation, fabrication routing, and final installed cost.
Product Type:
Volume economics and installation labor intensity drive buyer selection across raw material formats.
- Blocks:Unfinished quarry blocks serve as feedstock for integrated fabricators with captive cutting capacity. Saudi giga-project developers are securing multi-year offtake agreements directly with Denizli quarries to guarantee vein consistency across resort campuses.
- Slabs:Large-format sawn slabs command premium positioning in facade and countertop applications where book-matched veining creates architectural impact. Resin-injection pre-filling is becoming standard specification for high-rise cladding to eliminate field sealing delays.
- Tiles:Standardized dimensions reduce waste and accelerate installation timelines for hospitality flooring.
- Pavers:Thicker cuts with tumbled or brushed finishes dominate exterior hardscaping and pool decking.
Slabs lead on scale; tiles lead on momentum.
Application:
End-use environment dictates porosity tolerance, structural loading requirements, and maintenance protocol selection.
- Flooring:Honed finishes with resin-filled voids balance slip resistance and cleanability for hotel lobbies and spa circulation areas. Mediterranean wellness developers are standardizing cross-cut travertine for hydrotherapy zones.
- Wall Cladding:Large-format slabs with mechanical anchoring systems dominate exterior facade specifications in Saudi Arabia's tourism corridor. CE marking under EU CPR governs structural performance documentation for European installations.
- Countertops:Polished surfaces capture margin despite porosity limitations in residential kitchens.
- Landscaping:Tumbled pavers with brushed edges reduce slip hazards in wet exterior environments.
Wall cladding captures the steepest specification trajectory; flooring retains the broadest volume base.
Finish Type:
Surface treatment determines both aesthetic character and functional performance in specific use environments.
- Honed:Smooth matte surfaces without gloss dominate commercial flooring and spa interiors where slip resistance and understated warmth are prioritized. Turkish fabricators are retrofitting continuous honing lines to meet compressed Saudi project timelines.
- Polished:High-gloss surfaces maximize color saturation and vein definition for luxury residential countertops. The finish requires more aggressive resin filling to compensate for exposed voids.
- Tumbled:Antique-weathered edges and surfaces create informal character for exterior pavers.
- Brushed:Wire-brushed texture adds grip without the irregularity of full tumbling.
Honed finishes dominate current specification volumes; polished surfaces are expanding most quickly in residential premium tiers.
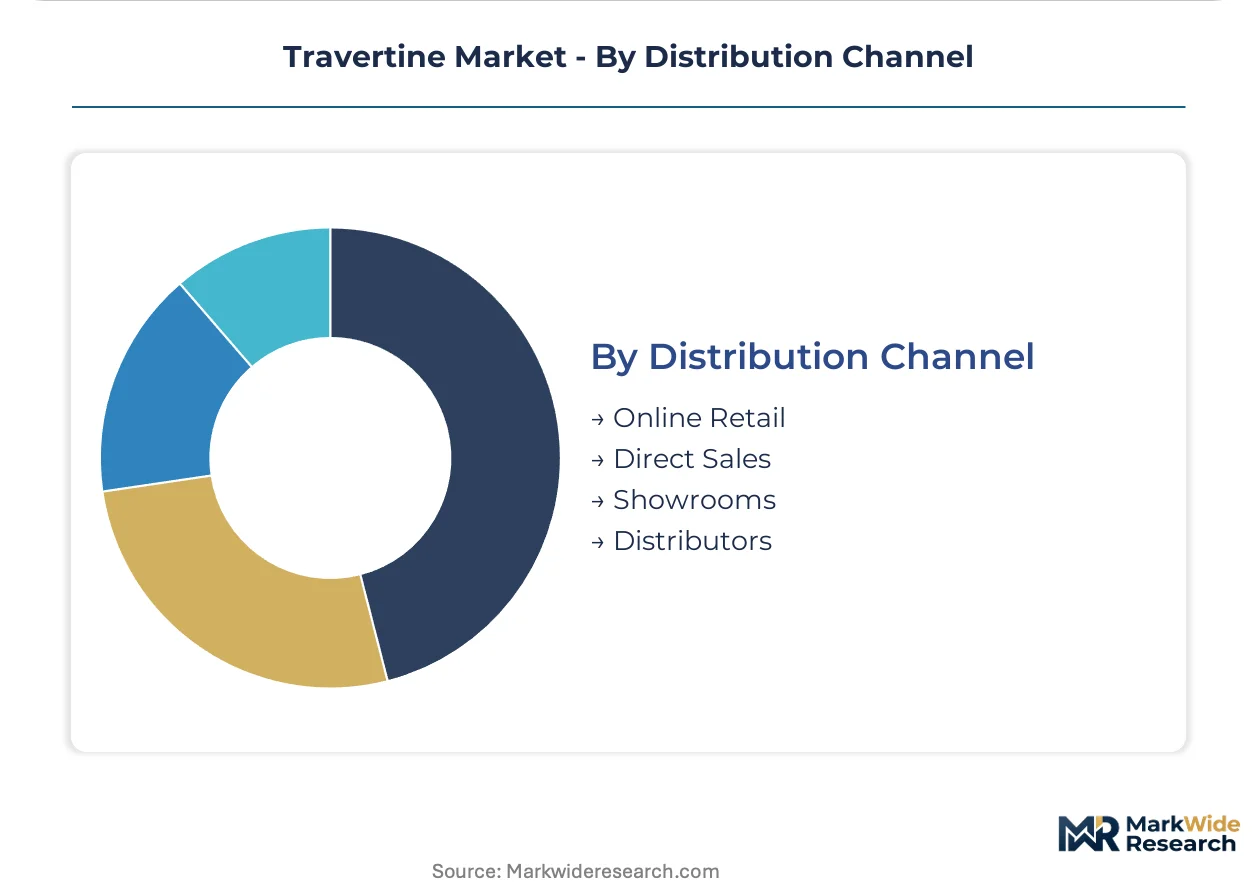
Distribution Channel:
Project scale and specification complexity determine whether buyers route through intermediaries or source direct.
- Direct Sales:Quarry-to-project contracting eliminates distributor margins for large developments with predictable volume requirements. Saudi giga-project master agreements are displacing traditional stone distributors in the Red Sea corridor.
- Distributors:Inventory-holding intermediaries provide specification flexibility and just-in-time delivery for mid-scale commercial contractors.
- Showrooms:Physical material libraries support architect and designer selection for finish-sensitive hospitality projects.
- Online Retail:Digital templating and sample logistics serve residential renovation and small commercial replacement markets.
Direct sales anchor volume concentration; showrooms sustain specification influence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denizli Province anchors travertine extraction capacity through its dense cluster of mechanized quarries and resin-injection fabrication facilities serving Middle Eastern hospitality developments.
Turkey
Saudi giga-projects are absorbing record volumes of cross-cut travertine for resort facades. The Ministry of Environment and Urbanization (MEE) applies extraction quotas that extend permit timelines for new quarry openings. Afyonkarahisar Province houses secondary processing centers where vacuum-pressure resin systems are retrofitting existing slab finishing lines.
Saudi Arabia
NEOM and Red Sea tourism corridor developments are specifying large-format travertine cladding with mechanical anchoring systems. The Saudi Building Code mandates structural performance documentation for exterior stone applications. Riyadh-based project offices are negotiating multi-year offtake agreements directly with Anatolian quarries to lock vein consistency across master-planned communities.
Italy
Mediterranean spa and wellness developers are standardizing honed travertine for hydrotherapy environments. CE marking under the Construction Products Regulation (CPR) governs freeze-thaw and flexural strength testing for structural facade applications. Modena Province maintains specialized laboratories where certification documentation faces six-month booking backlogs.
United States
Residential countertop fabricators are specifying polished travertine despite porosity limitations in high-moisture kitchens. The Environmental Protection Agency (EPA) oversees quarry runoff standards that affect domestic limestone and travertine extraction permits. Indiana limestone quarries are diversifying into architectural travertine finishing to capture hospitality specification share.
Mexico
North American distributors are exploring direct quarry offtake to bypass Mediterranean shipping bottlenecks. The Secretariat of Environment and Natural Resources (SEMARNAT) regulates mining concessions in Coahuila and Nuevo León. Saltillo-based fabricators are developing resin-injection capacity to serve Texas and California construction markets with reduced lead times.
Travertine Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue carbon-certified positioning and digital templating capabilities. The market structures around integrated quarry-to-fabrication operators, regional slab distributors with resin-filling capacity, and project-direct procurement specialists serving giga-developments. Three archetypes dominate: Anatolian integrated operators with captive extraction, Mediterranean finishers with CE-marking expertise, and North American distributors with regional inventory positioning. Competitive moves center on multi-year offtake contracting for vein consistency and photovoltaic-powered cutting investments for EU Carbon Border Adjustment Mechanism compliance.
Among Turkey-based integrated operators, Temmer Marble exemplifies quarry-to-fabrication consolidation with its Denizli extraction base and resin-injection finishing capacity. Levantina represents Mediterranean supply anchoring through Iberian stone holdings and CE-marking infrastructure. Buechel Stone Corp occupies North American architectural specification positioning with domestic limestone and travertine portfolio breadth. These three entities illustrate how geographic extraction concentration, regulatory certification capability, and project-direct contracting authority are separating competitive tiers in facade-grade travertine procurement.
| Leading Market Players |
|---|
| Temmer Marble |
| Dermitzakis |
| Indiana Limestone Company |
| Topalidis |
| Namco CO. Srl |
| Buechel Stone Corp |
| Levantina |
| MGT Stone Co |
| Natamar Madencilik San. Ve Tic.lTd Sti |
| Others |
Supply Flow & Price Mechanics
Diesel and electricity input indices cascade through Turkish quarry operations into three distinct pricing tiers for travertine procurement. Resin-injection pre-filling, CE marking documentation, and direct quarry contracting each command premium positioning over standard slab distribution.
Pricing Analysis
Input-cost pass-through from fuel and power expenses shapes contract-based long-term offtake as the dominant pricing model for Saudi giga-project developers. Price differentiation centers on certification level — CE marking under EU CPR versus domestic Turkish standards — and volume scale for multi-year vein-consistency agreements. Cost compression in standard-grade slabs is intensifying because resin-injection retrofitting requires capital outlays that smaller fabricators cannot absorb. Mid-scale commercial contractors show highest price sensitivity, while luxury hospitality developers prioritize vein matching over unit economics.
Supply Chain Analysis
Certification gating through CE marking and Saudi Building Code compliance documentation filters supplier access to structural facade specifications. Extraction concentrates in Turkey, Italy, and Mexico, with Denizli Province anchoring half of export-grade reserves. Production draws from diesel-powered block cutting, grid electricity for slab finishing, and epoxy resin systems for void filling. Single-source vulnerability around Anatolian quarry concentration creates exposure when Turkey's MEE environmental permits delay new capacity. Distribution runs through integrated quarry-to-fabrication operators for large projects, with regional slab distributors serving mid-scale commercial contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The travertine market functions as a regulatory compounder where EU Carbon Border Adjustment Mechanism documentation requirements and Saudi Building Code facade mandates are accelerating specification preference toward certified, low-carbon suppliers.
For Market Incumbents: Lock in multi-year offtake agreements with Saudi giga-project developers before Mexican quarry development matures into viable competition. Secure backward integration into photovoltaic-powered cutting plants to capture CBAM-compliant positioning as European demand hardens around embodied-carbon disclosure. Resin-injection capacity expansion in Afyonkarahisar Province defends margin control against smaller fabricators facing capital constraints. For New Entrants and Emerging Players: Direct-to-architect digital templating platforms offer the lowest-friction entry path for mid-scale North American commercial contractors seeking reduced lead times. Saltillo-based resin-injection partnerships penetrate Texas and California construction markets where Mediterranean shipping bottlenecks create specification windows. Target carbon-certified positioning in German and Dutch sustainability-focused developments where verified low-carbon extraction commands specification premium. For Investors and Strategic Acquirers: Asymmetric upside sits with Iberian quarries combining CE-marking infrastructure with photovoltaic cutting investments ahead of full CBAM implementation. Five-to-ten year viability favors operators with integrated quarry-to-fabrication models and established Saudi giga-project relationships. Monitor Turkey's MEE permit approval velocity as the critical inflection signal for Anatolian supply expansion capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Photovoltaic Cutting Plant Investment | Portuguese and Spanish operators capture CBAM-compliant specification preference from German developers. |
| Resin-Injection Line Retrofitting | Turkish fabricators reduce slab rejection rates for Saudi high-rise cladding applications. |
| Direct Quarry Offtake Agreement | Saudi giga-project developers lock vein consistency across Red Sea tourism corridor master plans. |
| Digital Templating Platform Launch | North American fabricators bypass distributor intermediaries for mid-scale commercial contractors. |
| Mexican Quarry Development | Coahuila deposits reduce Mediterranean shipping dependency for Texas construction markets. |
Methodological Framework
Coverage spans Turkey, Saudi Arabia, Italy, Mexico, and the United States, with primary inputs from each regional cluster of quarry operators and fabrication centers. The approach combines primary interviews with quarry managers, resin-injection equipment suppliers, Saudi project procurement officers, Italian CE-marking laboratory directors, and North American architectural specification consultants with secondary validation from Turkish Ministry of Environment permit filings, Saudi Building Code documentation requirements, EU CPR compliance registries, and customs trade data for travertine block and slab movements. Bottom-up project pipeline tracking and top-down extraction capacity estimates provide triangulation.
Rate-of-change decomposition separates volume growth from price evolution across the analysis window. The analytical framework models travertine demand through product type segmentation — blocks, slabs, tiles, pavers — application environment — flooring, wall cladding, countertops, landscaping — finish specification — honed, polished, tumbled, brushed — and distribution channel routing. CAGRs derive from quarry capacity expansion schedules, giga-project construction timelines, and substitution elasticity between travertine and engineered sintered stone in commercial hospitality specifications.
Turkey's MEE permit delays, Saudi giga-project timeline compression, and EU CBAM implementation velocity are the dominant revision risks to modeled travertine demand. Forecasts reflect assumptions around resin-injection technology adoption rates and carbon certification documentation standardization. A model refresh is warranted upon material change in Anatolian environmental compliance enforcement or Saudi tourism corridor construction pacing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Outside Door Handle Market
Building & Construction Materials
US Terracotta Cladding Market
Building & Construction Materials
Carbon Textile Reinforced Concrete Market
Building & Construction Materials
Wood Shingles Market
Building & Construction Materials
India Ceramic Tiles Market
Building & Construction Materials
Global Hydraulic Door Closer Market
Building & Construction Materials
Europe Timber Construction Connectors Market
Building & Construction Materials
India Faucet Market
Building & Construction Materials
Artificial Wood Beams Market
Building & Construction Materials
Building Insulation Materials Market
Building & Construction Materials
Building and Construction Sealants Market
Building & Construction Materials
ASEAN Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Indonesia Ceramic Tiles Market
Building & Construction Materials
Stone Veneer Market
Building & Construction Materials
Wood House Frame Market
Building & Construction Materials
Latex Caulk Market