
 North America Fabricated Metal Products Market | 2026-2036
North America Fabricated Metal Products Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fabricated Metal Products Market Analytics
Mexico's northern industrial corridor is tilting toward fabricated metal capacity as nearshoring accelerates. O'Neal Manufacturing Services leverages its multi-site US footprint to serve energy and construction clients with heavy welded structures. Valmont Industries anchors its position through vertical integration in galvanizing and coating for infrastructure applications. Mayville Engineering Company specializes in high-mix, low-volume precision components for agricultural and construction equipment.
Fabricated metal products encompass steel, aluminum, and alloy components shaped through cutting, bending, welding, machining, and assembly processes, typically conforming to ASTM material specifications and AWS welding codes for structural integrity. These products serve as intermediate inputs across capital-intensive industries, from structural steel framing in commercial buildings to precision stampings in automotive powertrains. Stamped products dominate volume throughput due to automotive and appliance demand, while machined products capture premium margins in aerospace and medical device applications. Laser cutting technology leads capital investment as fabricators pursue faster turnaround on complex geometries with minimal material waste.
US OSHA workplace safety standards and EPA emissions regulations govern shop-floor operations and finishing processes, while Mexico's PROFEPA enforces environmental compliance at maquiladora fabrication facilities. The US Inflation Reduction Act domestic content thresholds and Buy America provisions in federal infrastructure spending reshape procurement criteria for structural steel and welded assemblies. Stakeholders must monitor how evolving trade remedy investigations on steel and aluminum imports affect raw material cost structures and sourcing strategies.
Market Dynamics
The US Inflation Reduction Act's domestic content thresholds are forcing structural reconfiguration of supply chains across fabricated metal procurement, redirecting capital from offshore sourcing toward American fabrication facilities and Mexican maquiladora expansion.
Growth Catalysts
- Federal infrastructure spending:The Buy America provisions in the Infrastructure Investment and Jobs Act mandate domestic steel and iron content for federally funded projects, pulling demand toward certified US fabricators.
- Reshoring of aerospace supply chains:OEMs are rebuilding captive supplier networks for precision-machined titanium and aluminum components, eliminating tariff exposure and logistics risk from Asian sourcing.
- Laser cutting adoption:Fiber laser systems are compressing turnaround times for complex geometries while reducing material kerf waste, enabling fabricators to compete on prototype speed against stamping houses.
Market Restraints
- Scrap aluminum price volatility:Secondary smelter feedstock costs swing with LME pricing and export demand from Chinese billet producers, compressing margin predictability for extrusion-dependent fabricators.
- Canadian steel import concentration:Flat-rolled supply for US structural fabrication remains tethered to Hamilton and Sault Ste. Marie mill complexes, creating single-source vulnerability during labor disruptions.
- AWS D1.1 certification bottlenecks:The American Welding Society's structural welding qualification backlog delays contractor approval for federal bridge and building projects, extending sales cycles.
Strategic Opportunities
- Monterrey-Tijuana corridor expansion:Northern Mexico's industrial real estate pipeline offers tariff-advantaged production platforms for US-bound structural steel and precision components.
- Electrolyzer and hydrogen vessel fabrication:The Department of Energy's hydrogen hub funding is creating demand for ASME-certified pressure vessels and high-alloy welded assemblies in Texas and California.
- Digital twin integration:Convergence of CAD nesting software with real-time machine monitoring is enabling fabricators to offer guaranteed throughput pricing rather than time-and-material contracts.
Industry Challenges
- CNC programming talent scarcity:The gap between retiring G-code machinists and graduates trained on modern CAM software is forcing fabricators to absorb six-month onboarding cycles for complex five-axis work.
- EPA NESHAP compliance capital:Metal finishing operations face seven-figure investments in thermal oxidizers and wastewater treatment to meet hazardous air pollutant standards for chromium and nickel emissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fabricated Metal Products Market |
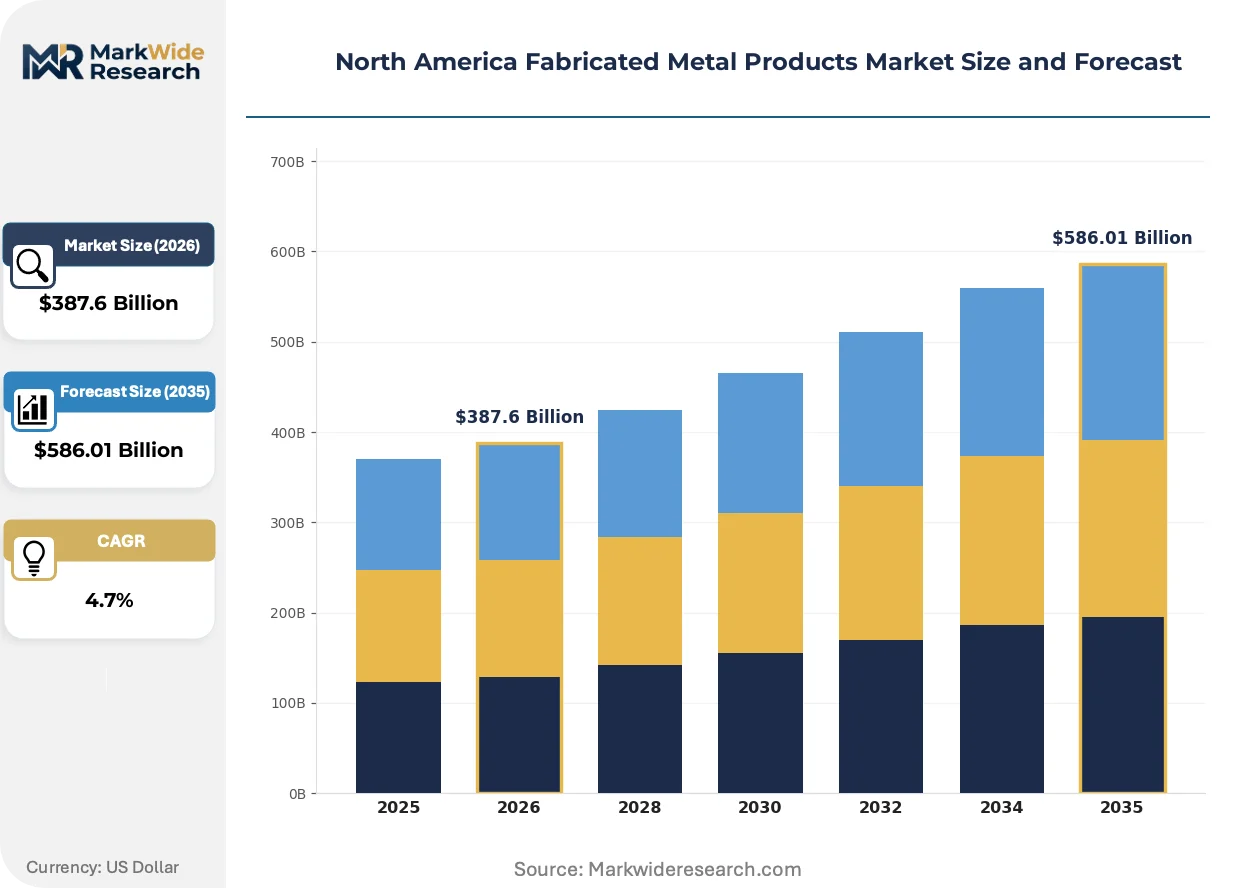
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $586.01 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Welded Products, Stamped Products, Machined Products, Forged Products End User: Aerospace, Construction, Automotive, Electronics Technology: Laser Cutting, CNC Machining, Waterjet Cutting, Additive Manufacturing Application: Building, Infrastructure, Transportation, Industrial Equipment |
| Companies Covered | O’Neal Manufacturing Services, Mayville Engineering Company, Valmont Industries, BTD Manufacturing, Kapco Metal Stamping, PMF Industries, Monti Inc., Standard Iron & Wire Works, Ryerson Holding Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fabricated Metal Products Market Evolving Landscape
Automation and digital thread technologies are compressing the traditional fabrication workflow from quotation through delivery, collapsing the historical separation between engineering design and shop-floor execution.
Hybrid additive-subtractive manufacturing cells are rendering obsolete the conventional sequence of rough machining, heat treatment, and finish grinding for aerospace bracketry and medical implant blanks. Tier-one suppliers in Connecticut and Arizona are installing these systems for lot sizes below fifty units, eliminating fixture costs and reducing lead times from twelve weeks to ten days. The technology is rendering obsolete the economic advantage of high-volume stamping for complex low-volume geometries.
The US Inflation Reduction Act's domestic content bonus credits are rewriting procurement specifications for solar racking, EV charging infrastructure, and transmission towers. Fabricators must now document steel melt and pour origins through mill test reports to qualify for tax-advantaged project finance. The structural steel segment is responding by integrating backward into electric arc furnace partnerships and captive rolling mill offtake agreements.
Buyers are consolidating vendor lists and demanding vendor-managed inventory programs with consignment stocking at fabrication facilities. Automotive Tier 1s and agricultural equipment OEMs in the Midwest are replacing spot purchasing with three-year blanket orders tied to Kanban replenishment signals. This shift is most visible in Illinois and Ohio, where stamping houses are converting excess press capacity into dedicated contract fabrication cells for single-source customers.
North America Fabricated Metal Products Market Segmentation
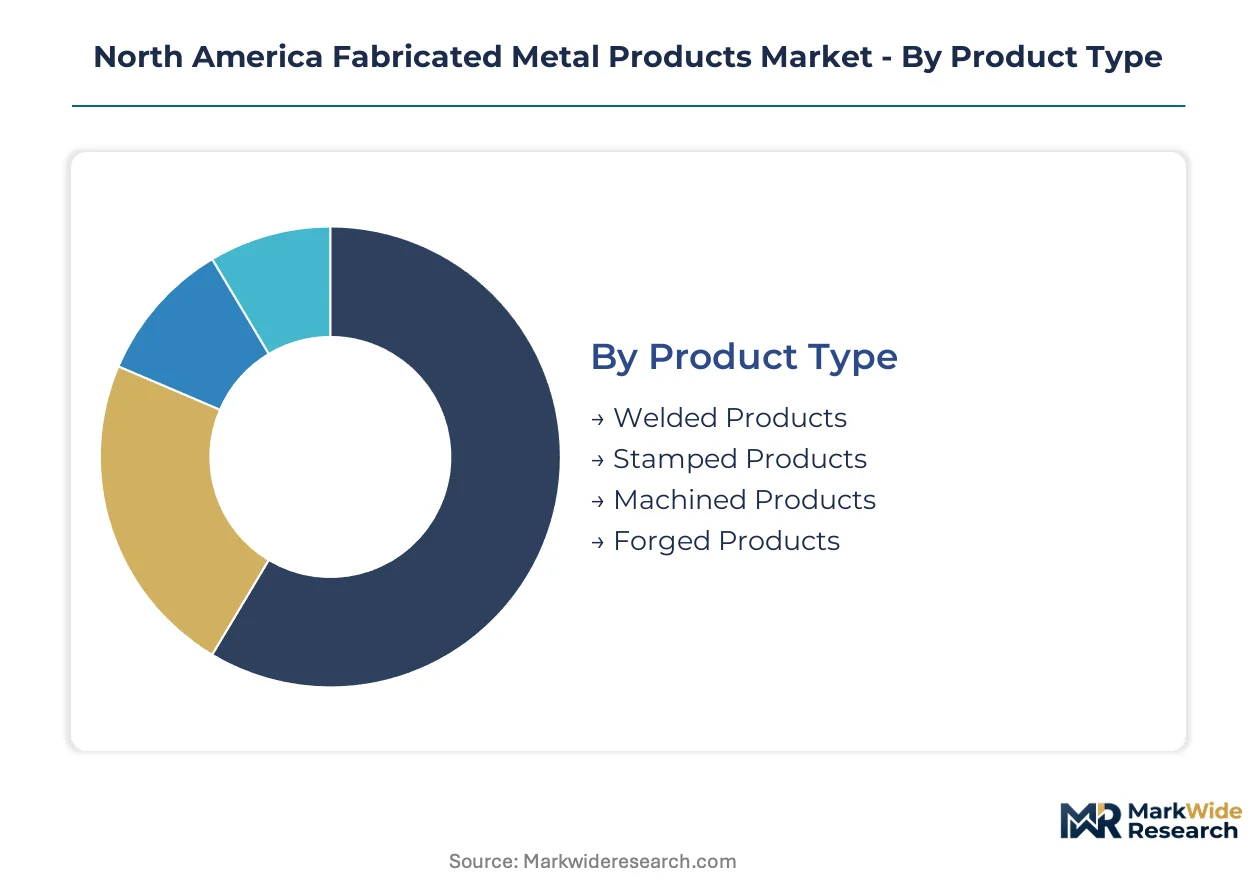
Segmentation reveals how fabrication technologies and end-use demands fragment across distinct value pools. Understanding these divisions exposes where capital equipment investments concentrate and which customer verticals command premium pricing.
Product Type:
Mature processes dominate volume throughput while emerging techniques capture margin expansion.
- Welded Products:Heavy structural assemblies joined through arc, MIG, or TIG processes per AWS D1.1 codes. Demand clusters along the US Gulf Coast petrochemical corridor where infrastructure renewal drives consumption of pressure vessels and pipeline spools. EPA NESHAP compliance costs for welding fume capture systems compress margins for smaller job shops.
- Stamped Products:High-speed press operations forming sheet metal through progressive dies for automotive and appliance applications. Michigan and Ohio stamping houses supply Detroit automakers with chassis and powertrain stampings under long-term blanket orders tied to production schedules. Tooling amortization across million-unit runs sustains cost leadership.
- Machined Products:Precision components produced through subtractive processes for aerospace and medical device OEMs. Connecticut and Arizona suppliers rebuild captive networks for titanium and aluminum flight-critical parts.
- Forged Products:Hammer or press-formed metal shapes for high-strength applications in heavy machinery and energy equipment. Texas and Pennsylvania forgers serve oilfield and power generation clients with crankshafts and connecting rods.
Stamped products retain volume leadership; machined products hold the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive OEMs from price-sensitive project contractors.
- Aerospace:Precision-machined titanium and aluminum components for commercial and defense platforms. OEMs in Washington and California states reshore critical supply chains to eliminate tariff exposure and logistics risk from Asian sourcing.
- Construction:Structural steel framing, rebar assemblies, and architectural metalwork for commercial and infrastructure projects. The Buy America provisions in federal infrastructure spending mandate domestic steel content for bridges and federal buildings.
- Automotive:Stamped body panels, chassis components, and powertrain stampings for light vehicle production. Midwest stamping houses convert excess press capacity into dedicated contract fabrication cells.
- Electronics:Precision metal enclosures, heat sinks, and connector housings for semiconductor and consumer device manufacturers. Mexican maquiladora facilities near Tijuana serve California-based technology OEMs with tariff-advantaged production.
Construction commands the largest revenue pool; aerospace delivers the highest value-added per kilogram.
Technology:
Application requirements dictate capital allocation between speed-oriented and precision-oriented systems.
- Laser Cutting:Fiber and CO2 systems slicing sheet and plate with minimal kerf waste. Fabricators in Illinois and Ohio deploy these systems to compress prototype turnaround against traditional stamping houses.
- CNC Machining:Computer-numerical control mills and lathes executing complex geometries from solid billet. The gap between retiring G-code machinists and CAM-trained graduates forces six-month onboarding cycles for five-axis work.
- Waterjet Cutting:Abrasive jet processing for heat-sensitive materials and thick plate sections. Gulf Coast fabricators use waterjet for exotic alloys in petrochemical applications where thermal distortion must be eliminated.
- Additive Manufacturing:Powder-bed fusion and directed energy deposition for low-volume aerospace bracketry and medical implants. Hybrid additive-subtractive cells in Connecticut and Arizona collapse lead times from twelve weeks to ten days for lot sizes below fifty units.
Laser cutting anchors equipment investment volumes; additive manufacturing posts the steepest capability expansion.
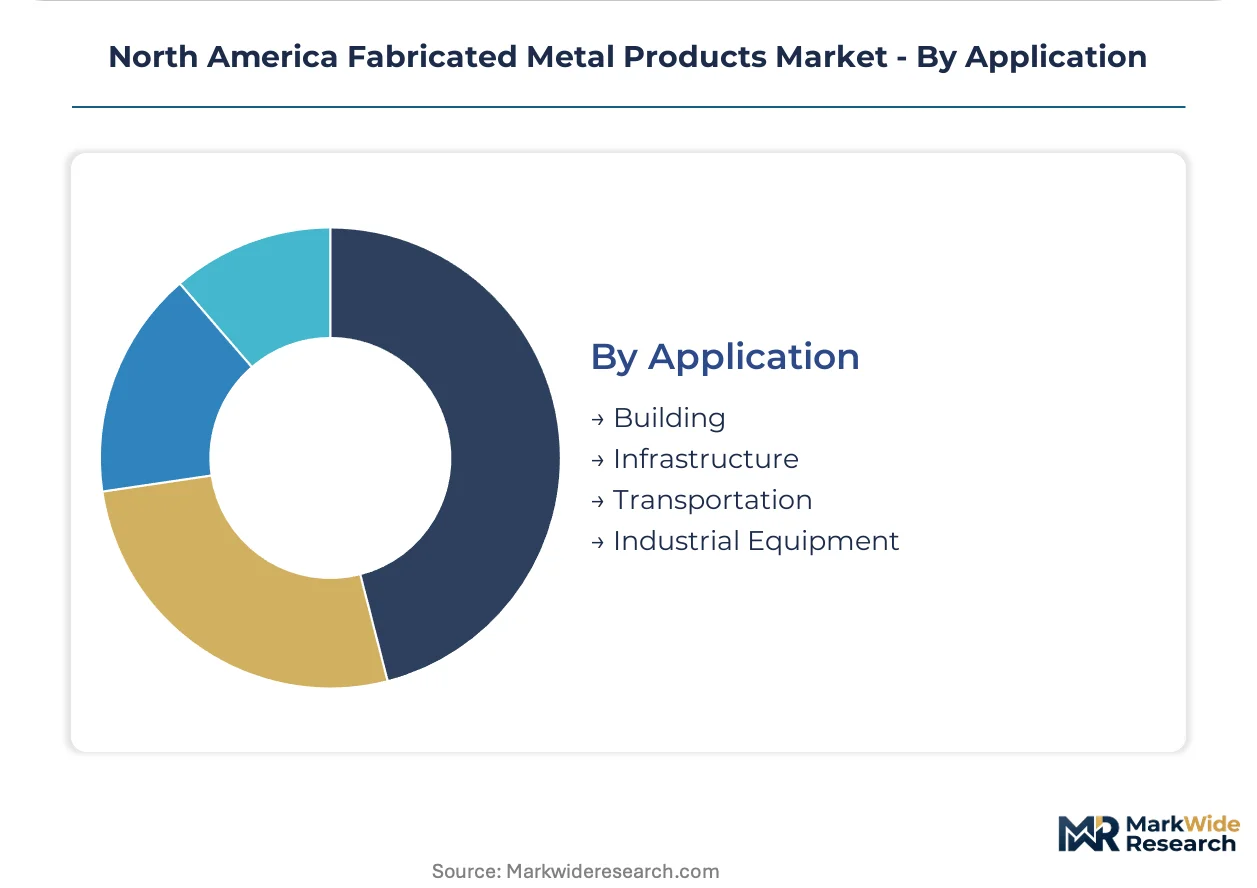
Application:
Customer type fragmentation separates project-based contractors from OEM production schedules.
- Building:Structural steel framing, metal roofing, and architectural facades for commercial and residential construction. Fabricators document steel melt and pour origins through mill test reports to qualify for Inflation Reduction Act tax credits.
- Infrastructure:Bridge girders, transmission towers, and transportation hardware for federal and state projects. Buy America provisions pull demand toward certified US fabricators with domestic melt-and-pour certification.
- Transportation:Railcar components, truck bodies, and marine vessel assemblies. Mexican northern industrial corridor capacity expands to serve US-bound transportation equipment demand.
- Industrial Equipment:Machinery frames, process equipment skids, and material handling systems. Agricultural and construction equipment OEMs in the Midwest consolidate vendor lists and demand vendor-managed inventory programs.
Building applications consume the widest product mix; infrastructure projects drive the most stringent certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Raw material access and federal procurement rules concentrate fabrication capacity in specific sub-regional corridors. The US Gulf Coast, Midwest industrial belt, and Mexico's northern border states each host distinct specialization clusters shaped by end-user proximity and trade policy advantages.
United States Gulf Coast
Petrochemical infrastructure renewal and hydrogen hub development drive demand for ASME-certified pressure vessels and heavy welded assemblies. The Department of Energy's hydrogen funding directs capital toward Texas and Louisiana fabrication yards. Houston-area fabricators supply pipeline spools and process equipment for downstream energy clients.
United States Midwest
Automotive stamping and agricultural equipment production anchor demand for high-volume sheet metal and precision components. Buy America provisions in federal infrastructure spending pull structural steel procurement toward certified domestic fabricators. Illinois and Ohio stamping houses convert excess press capacity into dedicated contract cells for Tier 1 suppliers.
Mexico Northern Border States
Nearshoring acceleration and tariff-advantaged access to US markets expand maquiladora fabrication capacity. PROFEPA enforces environmental compliance at assembly and finishing operations in Nuevo León and Baja California. Monterrey-Tijuana corridor facilities serve California technology OEMs with precision metal enclosures and connector housings.
Canada Ontario and Quebec
Flat-rolled steel supply from Hamilton and Sault Ste. Marie mill complexes feeds structural fabrication for cross-border infrastructure projects. Labor disruptions at primary steel producers create single-source vulnerability for US-bound beam and plate orders. Toronto-area fabricators document melt-and-pour origins to qualify for Inflation Reduction Act domestic content thresholds.
United States Southwest and Mountain West
Aerospace OEMs in Washington and California states reshore precision-machined titanium and aluminum component supply chains. FAA certification requirements and defense procurement rules favor captive supplier networks over Asian sourcing. Arizona and Connecticut machine shops install hybrid additive-subtractive cells for low-volume flight-critical parts.
North America Fabricated Metal Products Market Competitive Landscape
Vertically integrated conglomerates and specialized job shops split the market along volume and complexity vectors. Tier-one suppliers with captive steel mill partnerships capture federal infrastructure contracts requiring domestic melt-and-pour certification. Independent precision machinists occupy the aerospace and medical device niches where lot sizes fall below fifty units. Competitive moves center on backward integration into raw material supply and geographic expansion into tariff-advantaged Mexican production platforms.
Among US-based multi-site operators, O'Neal Manufacturing Services and Valmont Industries exemplify divergent scale strategies. O'Neal leverages dispersed fabrication yards to serve energy and construction clients with heavy welded structures requiring proximity to project sites. Valmont anchors its position through in-house production of galvanizing and coating capacity for infrastructure applications. Mayville Engineering Company occupies the specialized tier, representing high-mix, low-volume precision component suppliers serving agricultural and construction equipment OEMs under long-term contract arrangements.
| Leading Market Players |
|---|
| O'Neal Manufacturing Services |
| Mayville Engineering Company |
| Valmont Industries |
| BTD Manufacturing |
| Kapco Metal Stamping |
| PMF Industries |
| Monti Inc. |
| Standard Iron & Wire Works |
| Ryerson Holding Corporation |
| Others |
Value Network & Pricing Analysis
Tariff exposure on Canadian flat-rolled steel determines both pricing tier spreads and supply chain shape across North American fabricated metal procurement. The Inflation Reduction Act's domestic content thresholds force buyers to absorb melt-and-pour certification premiums while redirecting sourcing toward US mills and Mexican maquiladora platforms.
Pricing Analysis
The US Inflation Reduction Act dictates the pricing tier structure through its domestic content bonus thresholds. Three-tier pricing structure across premium, standard, and economy levels separates ASME-certified pressure vessel fabricators from commodity structural steel job shops and uncertified Mexican border producers. Cost compression in the standard tier is intensifying because AWS D1.1 certification backlogs delay contractor approvals and extend sales cycles. Automotive Tier 1s exhibit the highest price sensitivity due to production-schedule blanket orders, while aerospace OEMs accept premium pricing for reshoring flight-critical titanium components.
Supply Chain Analysis
Export controls on advanced fiber laser and additive manufacturing systems limit technology transfer to Chinese fabricators and concentrate precision capability in US and Mexican facilities. Raw material supply draws from Canadian Hamilton and Sault Ste. Marie mill complexes, US Gulf Coast electric arc furnace operators, and Mexican scrap-fed secondary smelters. Single-source vulnerability runs through the Canadian flat-rolled concentration exposed to labor disruption risk. Distribution runs through project-site proximity networks for heavy welded structures and vendor-managed inventory programs for automotive stampings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment. The Inflation Reduction Act's domestic content rules and AWS certification requirements create switching costs that lock in certified fabricators and exclude uncertified competitors.
For Market Incumbents: Harden AWS D1.1 and ASME certification portfolios to defend against Mexican maquiladora competitors exploiting tariff-advantaged labor arbitrage. Capture backward integration into electric arc furnace partnerships to secure melt-and-pour documentation required for federal infrastructure awards. Channel control through dedicated contract fabrication cells for Midwest automotive Tier 1s reinforces volume commitments against spot-market volatility.
For New Entrants and Emerging Players: Pursue electrolyzer and hydrogen vessel fabrication white space created by Department of Energy hub funding in Texas and California. The Monterrey-Tijuana corridor offers the most penetrable geography for tariff-advantaged production serving US-bound solar racking and EV charging infrastructure demand. A go-to-market angle anchored in digital twin integration enables guaranteed throughput pricing against incumbent time-and-material contracts.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated mid-cap specialists with captive galvanizing and coating capacity. Long-term viability hinges on exposure to federal infrastructure spending and reshoring aerospace supply chains. The signal to watch is AWS certification approval velocity as an inflection indicator for contractor capacity expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Supply | Captive melt-and-pour documentation secures Inflation Reduction Act tax credit eligibility for federal projects. |
| AWS D1.1 Certification Expansion | Structural welding qualification backlog creates first-mover advantage for bridge and building contractors. |
| Monterrey-Tijuana Capacity Buildout | Tariff-advantaged production platforms serve California technology OEMs with precision metal enclosures. |
| Hybrid Additive-Subtractive Cell Deployment | Arizona and Connecticut installations collapse aerospace bracket lead times from twelve weeks to ten days. |
| Digital Twin Integration | CAD nesting software convergence enables guaranteed throughput pricing against traditional time-and-material contracts. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade flow databases, EPA enforcement records, and federal procurement disclosures. Primary interviews engaged fabrication plant managers, OEM procurement leads at Detroit automakers and Houston energy clients, AWS certification auditors, and Mexican PROFEPA compliance officers. Secondary sources incorporated US Census Bureau trade data, Department of Energy hydrogen hub funding announcements, and SEC filings from publicly traded metal service centers. Bottom-up capacity modeling triangulated against top-down demand projections from infrastructure spending authorization levels.
Forecast inputs span product type segmentation across welded, stamped, machined, and forged categories; end-user verticals including aerospace, construction, automotive, and electronics; and technology tiers from laser cutting through additive manufacturing. Growth trajectories across the analysis window reflect equipment investment cycles, certification pipeline constraints, and reshoring momentum in flight-critical component supply chains. Modeled outputs incorporate raw material cost pass-through elasticity and labor productivity differentials between US and Mexican production platforms.
Macroeconomic conditions sit as an overlay; deviation in interest rate trajectories, scrap aluminum LME pricing, or Canadian dollar exchange rates would shift the trajectory. Forecasts reflect assumptions regarding federal infrastructure appropriation continuity and aerospace OEM reshoring commitment durability. Material shifts in trade remedy investigations on steel and aluminum imports or EPA NESHAP compliance stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
United Kingdom Prefab Wood Buildings Market
Building & Construction Materials
Point Supported Glass Curtain Wall Market
Building & Construction Materials
Door System Market
Building & Construction Materials
Porcelain Tiles Market
Building & Construction Materials
Building Acoustic Insulation Market
Building & Construction Materials
Artificial Marble Market
Building & Construction Materials
North America Wood Based Panel Market
Building & Construction Materials
Exterior Sheathing Market
Building & Construction Materials
Construction Aggregates Market
Building & Construction Materials
US Geosynthetics Market
Building & Construction Materials
Mosaic Tiles Market
Building & Construction Materials
Structural Insulated Panels (Sips) Market
Building & Construction Materials
Europe Faucet Market
Building & Construction Materials
Italy Prefab Wood Buildings Market
Building & Construction Materials
Marble Market
Building & Construction Materials
Steel Roofing Market