
 Insulated Metal Panels Market | 2026-2036
Insulated Metal Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Insulated Metal Panels Market Foresight
Distribution through contractor-direct channels is rewriting how insulated metal panels reach end users in North America. Kingspan Group leverages its captive distribution network to control specification conversations with large cold storage developers. Metl-Span anchors the southern US market through regional manufacturing scale and rapid-turn fabrication capabilities. All Weather Insulated Panels differentiates via polyurethane core formulations tailored to seismic zones.
Insulated metal panels are factory-engineered composite assemblies comprising steel or aluminum skins bonded to rigid insulating cores, delivering thermal resistance values that exceed site-built insulation systems. The product achieves its primary purpose by eliminating thermal bridging in envelope assemblies while providing structural shear capacity in a single installation step. Wall panels dominate commercial building specifications due to speed of erection and integrated air-barrier performance. Cold storage applications command premium pricing for polyurethane-core products because of the material's superior R-value per inch and zero-tolerance moisture performance. Mineral wool cores occupy a narrower but defensible position where fire-rated assemblies are mandated by code.
US building codes enforced by the International Code Council and state-level amendments shape fire-performance testing requirements for core materials. The EPA's SNAP program and evolving state-level HFC restrictions are pushing manufacturers toward next-generation blowing agents with lower global warming potential. ECHA's REACH framework in Europe adds substance-of-concern screening for adhesives and coatings used in panel lamination. Stakeholders must monitor how dual regulatory pressure on thermal performance and chemical content reshapes core material selection and regional supply qualifications.
Market Dynamics
The EU F-Gas Regulation is compressing hydrofluorocarbon blowing agent availability, forcing polyurethane core manufacturers to reformulate around pentane and hydro-olefin alternatives. This single regulatory pressure is cascading through specification chains, elevating mineral wool and PIR core alternatives while redrawing qualified supplier lists across member states.
Growth Catalysts
- Cold storage construction surge:Warehouse-to-cold-chain conversions in Germany and the Netherlands are specifying high-R-value polyurethane cores for temperature-sensitive logistics facilities.
- EU Green Deal embodied-carbon thresholds:Member states are tightening environmental product declaration requirements, advantaging panels with recycled steel content and low-GWP cores.
- Seismic zone building codes:California and Japan are mandating lighter envelope systems, pulling specification toward aluminum-skinned panels with engineered connection details.
Market Restraints
- Steel price volatility:Galvanized coil costs fluctuate with energy-intensive European smelter output, compressing fabricator margins on fixed-price contracts.
- Adhesive supply concentration:Isocyanate and polyol feedstock production clusters in the US Gulf Coast and Northeast Asia create geographic vulnerability for polyurethane core lamination.
- Fire-test protocol fragmentation:Divergent NFPA 285, EN 13501, and FM 4880 testing requirements force regional SKU proliferation that dilutes manufacturing scale economies.
Strategic Opportunities
- India cold chain infrastructure:The country's PLI scheme for food processing and pharmaceutical logistics is creating first-mover advantage for panel suppliers establishing local lamination capacity.
- Building-integrated photovoltaics convergence:Panel manufacturers partnering with solar module producers can capture envelope-plus-generation specification in net-zero commercial projects.
- Direct contractor distribution:Bypassing traditional distributor networks in North America allows specification control and margin capture on large cold storage developments.
Industry Challenges
- Specialized installer scarcity:Proper panel erection demands certified crews proficient in thermal-bridge-free detailing and integrated air-barrier sequencing that outstrips current training pipeline output.
- Multi-jurisdiction certification lag:Securing concurrent UL, FM, and CE marking for a single product variant extends time-to-revenue by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulated Metal Panels Market |
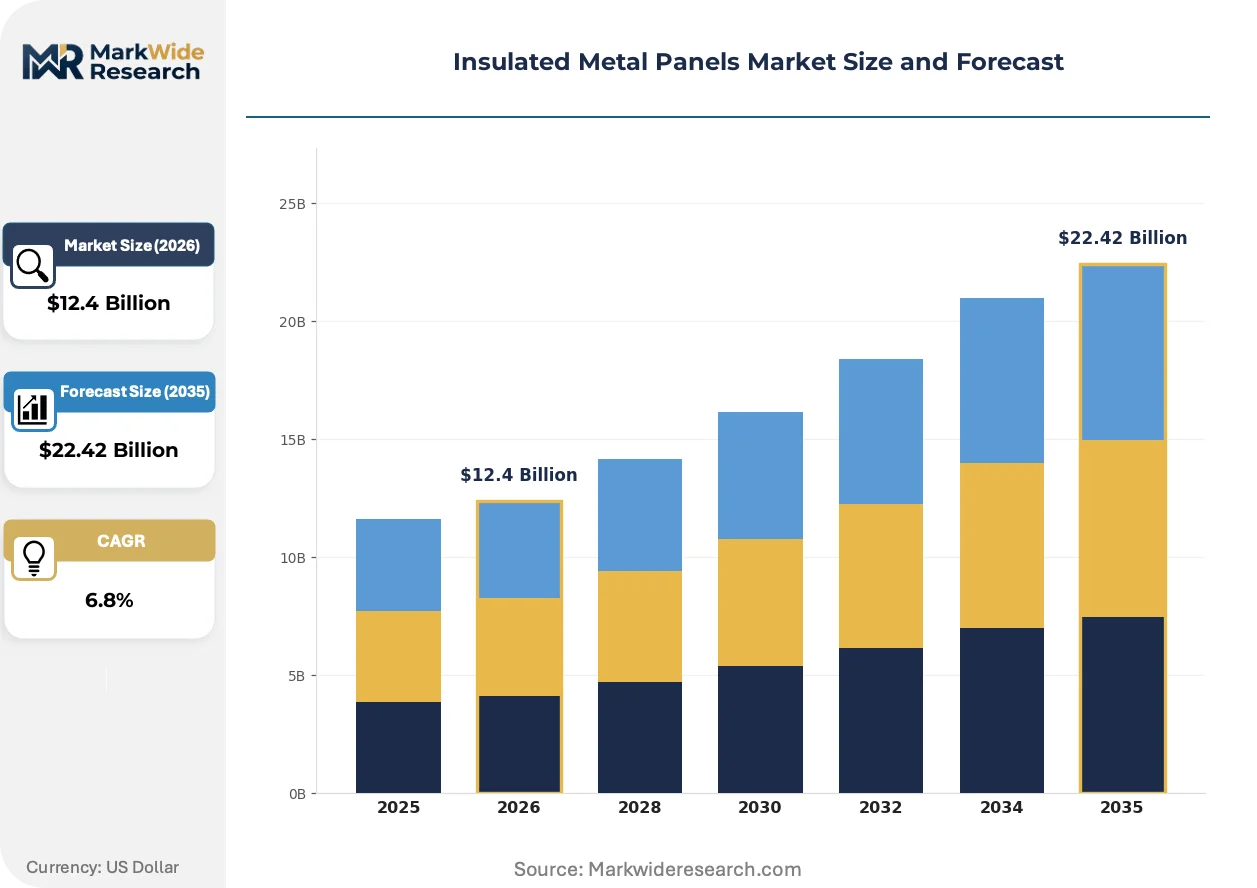
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Structural Panels, Wall Panels, Roof Panels, Ceiling Panels Material: Polyurethane, Polystyrene, Mineral Wool, EPS Application: Commercial Buildings, Industrial Facilities, Cold Storage, Residential Structures End User: Contractors, Manufacturers, Builders, Distributors |
| Companies Covered | Metl-Span, All Weather Insulated Panels, Kingspan Group, MBCI, Owens Corning Insulating Systems, Cornerstone Building Brands, CENTRIA, Petersen Aluminum Corporation, Nucor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulated Metal Panels Market Shifts & Advancements
Digital specification tools and virtual building envelope modeling are compressing traditional design-bid-build timelines. Manufacturers now compete on computational access to thermal performance data rather than sample delivery speed alone.
Building information modeling integration is virtualizing how envelope assemblies are specified and procured. Large cold storage developers in Germany and the Netherlands now require BIM-native panel objects with embedded thermal bridging calculations. This capability is compressing the competitive set to suppliers with computational engineering resources, marginalizing catalog-only competitors.
The EPA's SNAP program and state-level HFC restrictions are accelerating next-generation blowing agent adoption. Pentane and hydro-olefin formulations are displacing legacy HFC-245fa in polyurethane cores, though flammability handling requirements are elevating capital intensity for lamination facilities. Cold storage applications in California and Washington face the most compressed compliance timelines.
Buyer concentration among national cold storage developers is consolidating specification authority. Regional contractors now source through direct manufacturer relationships rather than distribution intermediaries, compressing channel margins and elevating price transparency. This pattern is most pronounced in the southern United States where rapid-turn fabrication demands favor integrated supply chains.
Insulated Metal Panels Market Segmentation
Segmentation in the insulated metal panels market determines specification pathways, installation complexity, and long-term service requirements. Product architecture and core material selection cascade through thermal performance guarantees, fire-code compliance, and regional supply qualifications. Understanding these divides exposes where margin concentrates and where technical differentiation commands premium positioning.
Product Type:
After-sales service intensity varies sharply across product architectures, with structural and envelope systems demanding distinct technical support footprints over their operational lifecycles.
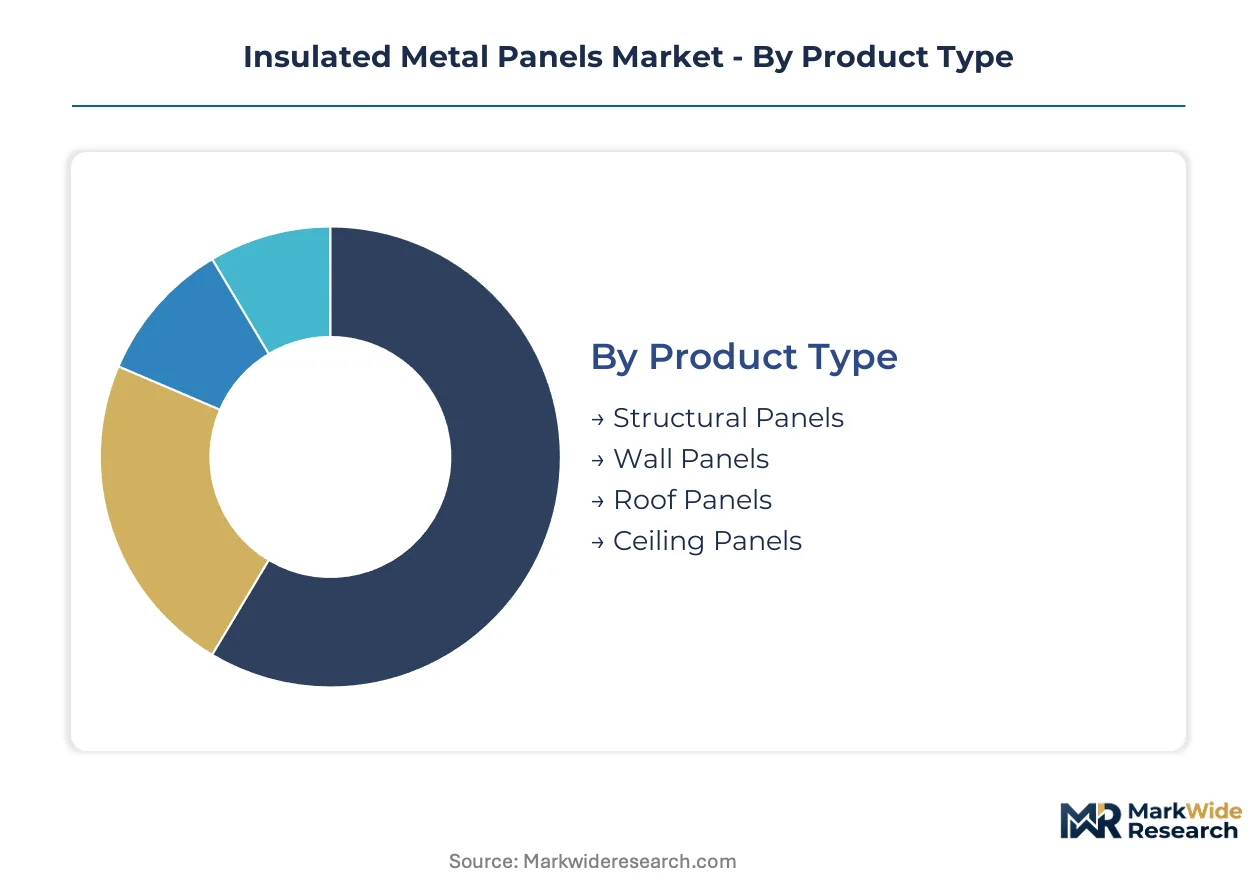
- Structural Panels:Composite assemblies combining steel skins with rigid insulation cores that deliver shear capacity and thermal resistance simultaneously. Cold storage developers in Germany specify these for warehouse conversions requiring rapid enclosure with minimal structural steel. The integrated load-bearing function eliminates separate framing, compressing construction schedules for temperature-sensitive logistics facilities.
- Wall Panels:Non-load-bearing envelope components optimized for vertical installation speed and air-barrier continuity. Demand concentrates in California commercial construction where seismic codes favor lighter aluminum-skinned variants with engineered connection details. Speed of erection and integrated weatherproofing drive specification among contractor-direct procurement channels.
- Roof Panels:Span-capable assemblies with standing-seam or through-fastened profiles for weather protection and thermal performance.
- Ceiling Panels:Interior-facing systems for hygienic environments and controlled-atmosphere spaces with wash-down requirements.
Wall panels hold the largest share; momentum sits with structural panels.
Material:
Core chemistry determines regulatory compliance pathways, with blowing agent transitions and fire-performance mandates reshaping qualified supplier lists across jurisdictions.
- Polyurethane:Closed-cell foam cores delivering superior R-value per inch and zero-tolerance moisture performance for sub-zero applications. Cold storage specifications in the Netherlands and Germany command premium pricing for this chemistry despite EU F-Gas Regulation forcing reformulation toward pentane and hydro-olefin alternatives.
- Mineral Wool:Inorganic fiber cores occupying defensible positions where EN 13501 fire ratings mandate non-combustible assemblies. Commercial and institutional projects in high-rise zones specify these despite thermal performance penalties versus polymer alternatives.
- Polystyrene:Cost-optimized expanded foam cores for standard commercial envelopes without extreme thermal demands.
- EPS:Moldable bead-foam cores for custom-profile applications and budget-sensitive residential construction.
Polyurethane dominates value concentration; mineral wool is climbing fastest on regulatory tailwinds.
Application:
End-use thermal requirements stratify the market into performance tiers, with sub-zero logistics commanding fundamentally different material specifications than ambient commercial space.
- Cold Storage:Temperature-controlled facilities requiring continuous envelope performance from ambient to frozen conditions. Warehouse-to-cold-chain conversions in Germany and the Netherlands specify high-R-value polyurethane cores with vapor-tight detailing that eliminates condensation risk in year-round operation.
- Commercial Buildings:Office, retail, and institutional envelopes where speed of enclosure and architectural finish drive selection. California seismic mandates pull specification toward lighter aluminum-skinned systems with documented connection engineering.
- Industrial Facilities:Manufacturing and processing plants with combined thermal, acoustic, and durability requirements.
- Residential Structures:Single-family and multi-family construction where first-cost sensitivity limits penetration of factory-engineered panel systems.
Cold storage commands the highest margins; commercial buildings represent the deepest volume pool.
End User:
Procurement authority concentration is rewriting channel economics, with national developers bypassing traditional distribution to capture specification control and margin.
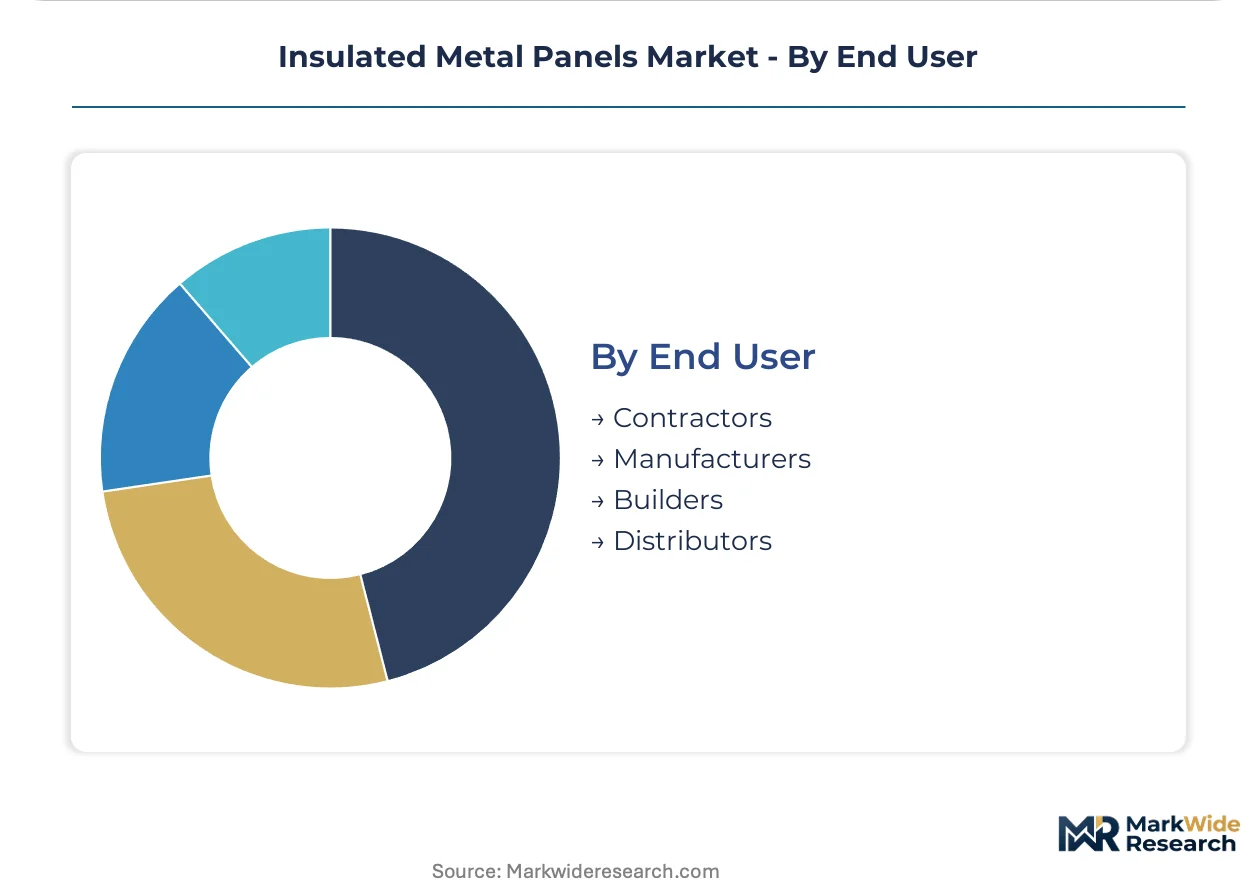
- Contractors:Installation firms with growing direct-manufacturer relationships, particularly in the southern United States where rapid-turn fabrication demands favor integrated supply chains. These stakeholders now control specification conversations for large cold storage developments, compressing traditional distributor roles.
- Builders:Construction management entities aggregating envelope procurement across multi-site programs with standardized performance specifications.
- Manufacturers:Panel fabricators serving as both producers and direct sellers in consolidated regional markets.
- Distributors:Traditional intermediaries facing margin compression as contractor-direct channels expand.
Contractors are gaining procurement authority fastest; distributors defend position through inventory availability and local technical support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal and F-Gas Regulation are redrawing material qualification requirements across member states. National building codes and cold chain infrastructure programs are concentrating specification authority in specific industrial corridors.
Germany
Warehouse-to-cold-chain conversion rates in Germany outpace neighboring economies, pulling demand toward high-R-value polyurethane cores. The country's national implementation of EU F-Gas Regulation is accelerating pentane-based reformulation timelines. Industrial clusters in North Rhine-Westphalia and Bavaria host qualified lamination facilities serving temperature-sensitive logistics developers.
United States
Seismic zone building codes in California and rapid-turn fabrication demands across the southern states are bifurcating specification patterns. EPA SNAP program enforcement and state-level HFC restrictions are compressing blowing agent transition timelines. Contractor-direct procurement channels in Texas and Florida are consolidating specification authority away from traditional distribution networks.
Netherlands
Port-centric cold storage expansion around Rotterdam is commanding premium envelope specifications for pharmaceutical and food logistics. REACH framework compliance requirements are screening adhesive and coating substances used in panel lamination. The Randstad corridor concentrates qualified fabricators capable of delivering BIM-native specification objects.
India
PLI scheme incentives for food processing and pharmaceutical logistics are creating first-mover opportunities for panel suppliers establishing local capacity. BIS certification requirements and state-level building code adoption are shaping qualified supplier lists. Industrial corridors in Maharashtra and Gujarat are emerging as lamination hub candidates for cold chain infrastructure rollout.
Japan
Seismic code mandates for lighter envelope systems are pulling specification toward aluminum-skinned panels with engineered connection details. METI efficiency standards for commercial building envelopes are tightening thermal performance thresholds. The Kanto and Kansai metropolitan areas concentrate demand for high-specification cold storage serving pharmaceutical distribution.
Insulated Metal Panels Market Competitive Landscape
On the supply side, the industry is consolidating around integrated manufacturers with captive distribution networks and regional fabrication scale. Tiered competitive positioning separates specification-control players from catalog-dependent competitors. Two strategic archetypes dominate: vertically integrated systems suppliers with direct contractor relationships, and regional fabricators competing on rapid-turn delivery. M&A activity targets distribution access, while capacity expansion concentrates in southern US and European industrial corridors.
Among North American fabricators, Kingspan Group, Metl-Span, and All Weather Insulated Panels exemplify divergent competitive vectors. Kingspan Group represents the integrated systems supplier archetype with captive distribution reach. Metl-Span anchors regional manufacturing scale in the southern United States. All Weather Insulated Panels occupies a specialization position around seismic-zone product engineering. Each exemplifies how supply-side configuration maps to specification authority in distinct geographic and application contexts.
| Leading Market Players |
|---|
| Metl-Span |
| All Weather Insulated Panels |
| Kingspan Group |
| MBCI |
| Owens Corning Insulating Systems |
| Cornerstone Building Brands |
| CENTRIA |
| Petersen Aluminum Corporation |
| Nucor Corporation |
| Others |
Supply & Pricing Matrix
Galvanized steel coil production clusters in European smelters concentrate upstream margin capture, leaving fabricators exposed to energy-cost pass-throughs on fixed-price cold storage contracts. This asymmetry compresses working capital buffers while rewarding manufacturers with captive coil inventories or long-term offtake arrangements with integrated steel producers.
Pricing Analysis
Volume-discount tiering structures separate national cold storage developers receiving project-scale rebates from regional contractors paying list prices. Certification grade—specifically UL, FM, and CE marking tiers—drives price differentiation alongside core chemistry and thermal performance ratings. Cost compression in standard commercial wall panels is intensifying because Chinese import competition is elevating spot-market availability. Regional contractors show highest price sensitivity, while pharmaceutical logistics developers accept premiums for zero-tolerance moisture performance guarantees.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for contractor-direct procurement, with supply-chain finance facilities emerging as a competitive differentiator among tier-one fabricators. Isocyanate and polyol feedstock production draws from the US Gulf Coast, Northeast Asia, and Northwest Europe, creating geographic concentration risk. Single-source vulnerability in adhesive lamination inputs amplifies disruption exposure from weather events or regulatory shutdowns. Distribution runs through manufacturer-captive networks in North America and traditional distributor channels in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cold chain infrastructure buildouts represent an early-cycle expansion story. Warehouse-to-cold-chain conversion rates in Germany and the Netherlands are pulling material specification toward premium thermal performance grades faster than supply capacity can respond.
For Market Incumbents: Pre-empt margin erosion in standard commercial panels by securing long-term steel coil offtakes and accelerating pentane-based core reformulation ahead of EU F-Gas Regulation deadlines. Backward integration into blowing agent chemistry protects against feedstock price volatility. Certification investment in concurrent UL, FM, and CE marking compresses time-to-revenue for new product variants.
For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized cold chain infrastructure rollout before incumbent lamination capacity localizes. Maharashtra and Gujarat industrial corridors offer first-mover positioning with lower qualified supplier density than European markets. Partner with regional EPC contractors on BIM-native specification objects to bypass distributor gatekeeping.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional fabricators in the southern United States lacking captive distribution reach. Long-term viability hinges on specification authority migration toward direct contractor channels. Monitor California seismic code amendment timing as an inflection signal for aluminum-skinned panel demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Coil Supply | Captive inventory buffers margin against European smelter energy-cost volatility. |
| Pentane Core Reformulation Investment | EU F-Gas Regulation compliance secures qualified supplier status in member states. |
| BIM-Native Specification Object Development | German cold storage developers now mandate embedded thermal bridging calculations. |
| Local Lamination Capacity in India | PLI scheme incentives create structural cost advantage versus import-dependent competitors. |
| Supply-Chain Finance Facility Launch | Extended payment terms win contractor-direct procurement authority from distributors. |
Research Methodology
Cross-validation between primary interviews with cold storage developers, EPC contractors, and plant engineers and secondary sources including SEC filings, customs trade data, and EU EPD databases anchors the qualitative findings. Technical R&D directors at core material suppliers and procurement leads at national logistics developers provided forward-looking specification intelligence. Bottom-up project pipeline analysis triangulates against top-down construction spend forecasts across the analysis window.
Calibration against historical capacity utilization rates and regional building permit data shapes the analytical framework. Segmentation dimensions span product architecture, core chemistry, application thermal requirements, and procurement channel authority. CAGRs derive from regression against cold storage square footage expansion and embodied-carbon regulatory stringency indices. Blowing agent transition timelines and seismic code adoption curves serve as industry-specific forecast inputs.
Stress conditions across steel price volatility, adhesive supply disruption, and certification timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation schedules and infrastructure investment continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Honeycomb Sandwich Panels Market
Building & Construction Materials
Concrete Resurfacer Market
Building & Construction Materials
Nordic Solar Shades Market
Building & Construction Materials
Door System Market
Building & Construction Materials
Cement Sacks Market
Building & Construction Materials
Roof Window Market
Building & Construction Materials
Structural Insulated Panels (Sips) Market
Building & Construction Materials
India Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Balustrade Market
Building & Construction Materials
Prefabricated Building System Market
Building & Construction Materials
US Precast Concrete Market
Building & Construction Materials
Glass Tiles Market
Building & Construction Materials
Gulf Corporation Council Cement Market
Building & Construction Materials
North America Ready-Mix Concrete Market
Building & Construction Materials
Pocket Door Market
Building & Construction Materials
Europe Timber Construction Connectors Market