
 Corn Sweeteners Market | 2026-2036
Corn Sweeteners Market Size, Share, and Industry Trends Forecast 2026-2036
Corn Sweeteners Market Outlook
Commodity refining margins is fragmenting across the corn sweeteners value chain as processors diversify into specialty starches and higher-margin modified ingredients. Cargill, Incorporated leverages its North American grain origination network to sustain cost-advantaged feedstock access. Archer Daniels Midland Company anchors its position through integrated wet milling complexes that span multiple sweetener and starch outputs. Ingredion Incorporated differentiates via clean-label ingredient portfolios targeting reformulation mandates from major beverage customers.
Corn sweeteners comprise glucose, fructose, and maltose derivatives extracted from wet-milled corn starch through enzymatic hydrolysis and isomerization processes, with dextrose equivalent values ranging from 20 to 100 depending on intended application. These ingredients function primarily as cost-effective bulking agents, humectants, and browning facilitators across mass-market food manufacturing. High Fructose Corn Syrup retains dominant volume share in beverage applications despite sustained reformulation pressures, while Liquid Sweeteners capture expanding share in dairy and confectionery segments where solubility and freeze-thaw stability prove critical. Powder and Granulated forms command premium positioning in bakery channels where handling characteristics and controlled moisture absorption determine procurement decisions.
The U.S. FDA enforces added sugars disclosure on Nutrition Facts panels, directly pressuring food manufacturers to reformulate or justify corn sweetener inclusion rates in consumer-facing products. EPA biofuel mandates and USDA crop insurance programs indirectly shape corn availability and price volatility for sweetener processors. Stakeholders must monitor evolving WHO sugar reduction guidelines and their translation into national dietary policies, as these frameworks increasingly influence procurement specifications from multinational food and beverage customers.
Market Dynamics
Corn sweetener processors face intensifying margin compression as beverage manufacturers accelerate reformulation timelines under added-sugar disclosure mandates. Wet millers must now balance commodity dextrose output against specialty maltodextrin premiums while managing enzymatic hydrolysis cost curves.
Growth Catalysts
- EPA biofuel mandates:Ethanol production quotas sustain corn offtake volumes, stabilizing feedstock basis for integrated wet milling operations.
- Southeast Asian bottlers:Carbonated and ready-to-drink expansion in Vietnam, Indonesia, and Thailand drives liquid sweetener procurement at scale.
- FDA added-sugar labeling:Reformulation urgency pushes manufacturers toward optimized fructose-glucose blends that maintain sweetness perception at reduced inclusion rates.
Market Restraints
- Input cost volatility:Corn price swings tied to USDA crop insurance program adjustments and weather pattern uncertainty compress refining margins unpredictably.
- Substitution threat:Allulose and monk fruit extracts displace high-fructose corn syrup in premium beverage lines seeking clean-label positioning.
- Supply concentration risk:North American grain origination networks dominate feedstock access, leaving processors in Brazil and Argentina at freight-cost disadvantages.
Strategic Opportunities
- Modified starch convergence:Enzymatic hydrolysis platforms are expanding into specialty maltodextrins and resistant starches for sports nutrition applications.
- Clean-label tailwinds:WHO sugar reduction guidelines are translating into procurement specifications from multinational beverage customers seeking non-GMO corn derivatives.
- Dairy application white space:Freeze-thaw stable liquid sweeteners penetrate ice cream and yogurt segments where solubility performance commands premium positioning.
Industry Challenges
- Enzyme optimization expertise:Shortage of process engineers capable of tuning isomerization yields across dextrose equivalent ranges strains operational efficiency.
- Retrofitting capex burdens:Legacy wet mills require substantial capital to segregate non-GMO processing lines for clean-label contract manufacturing.
- Reformulation timeline compression:Beverage customers demand 12-18 month product redevelopment cycles that strain R&D throughput across multiple sweetener grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corn Sweeteners Market |
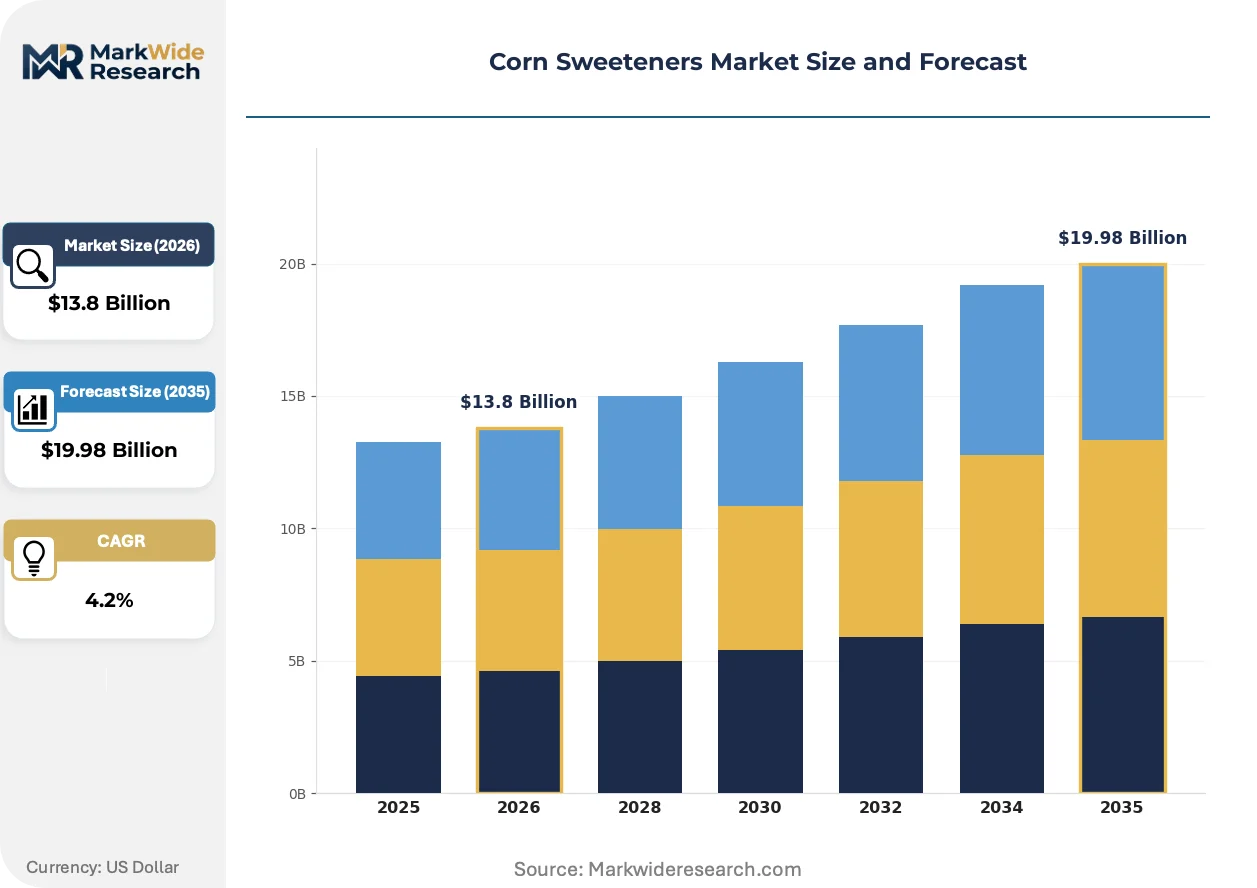
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $19.98 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Fructose Corn Syrup, Corn Syrup, Corn Starch, Liquid Sweeteners Application: Beverages, Bakery Products, Dairy Products, Confectionery End User: Food Manufacturers, Beverage Companies, Retailers, Foodservice Providers Form: Liquid, Powder, Granulated, Crystalline |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Ingredion Incorporated, Tate & Lyle PLC, Roquette Frères, Global Sweeteners Holdings Limited, Tereos Group, Südzucker AG, Grain Processing Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corn Sweeteners Market Strategic Shifts
Process control systems and enzymatic engineering are converging to reshape how corn refiners optimize yield curves across dextrose equivalent specifications. These developments compress the gap between commodity and specialty sweetener production economics.
Inline near-infrared spectroscopy is digitizing real-time monitoring of saccharide profiles during enzymatic hydrolysis. Wet millers in the US Corn Belt deploy these sensors to adjust residence times and enzyme dosing automatically. The technology is digitizing quality control labor costs while tightening batch-to-batch consistency for beverage customers demanding precise sweetness equivalence.
The EU Green Deal's Farm to Fork Strategy is tightening sustainability traceability requirements for imported agricultural inputs. Corn sweetener shipments into European ports must now document deforestation-free supply chains and carbon intensity metrics. Food manufacturers in Germany and France are reformulating around certified lower-carbon-intensity syrup grades to meet Scope 3 emission targets.
Beverage procurement teams are consolidating supplier relationships around integrated ingredient portfolios rather than single-sweetener contracts. Mid-sized bottlers in Mexico and Brazil now negotiate bundled glucose-fructose-starch agreements with wet millers offering technical service support. This pattern concentrates purchasing power among processors capable of delivering formulation guidance alongside commodity volume.
Corn Sweeteners Market Segmentation
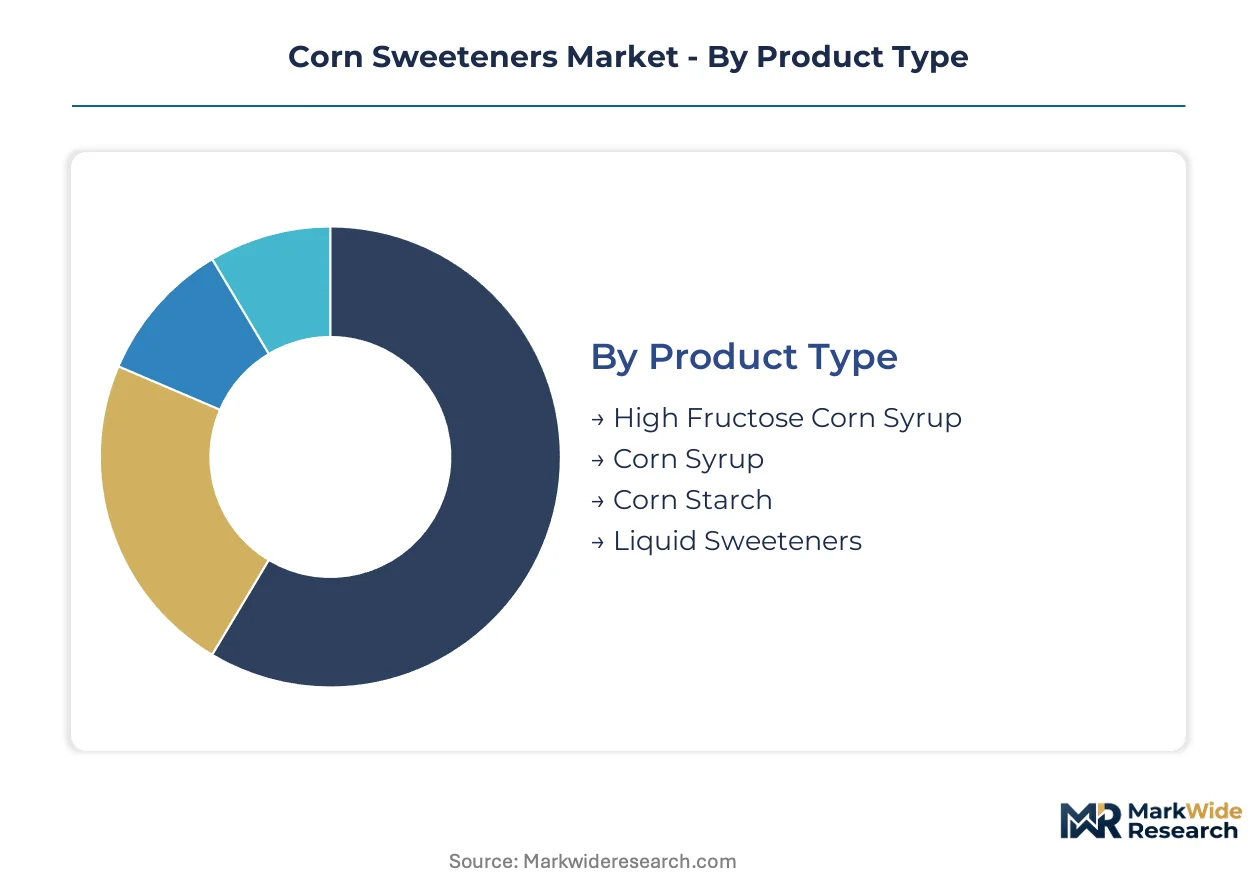
Corn sweetener procurement patterns diverge sharply across product chemistry, application physics, and customer operational scale. Each segmentation dimension captures distinct margin structures and technical service requirements that reshape supplier-customer contracting terms.
Product Type:
Cost tier determines how processors balance commodity dextrose output against specialty maltodextrin premiums in enzymatic hydrolysis operations.
- High Fructose Corn Syrup:Fructose-glucose blends produced through enzymatic isomerization achieve dextrose equivalent values above 90. Beverage manufacturers in Vietnam, Indonesia, and Thailand drive procurement volume as carbonated and ready-to-drink production capacity expands.
- Corn Syrup:Glucose-dominant syrups with moderate dextrose equivalent ranges serve as cost-effective bulking agents. Bakery channels concentrate demand where controlled moisture absorption and browning kinetics determine formulation acceptance.
- Corn Starch:Native and modified starches extracted from wet-milled endosperm provide texturizing and gelling functionality. Food manufacturers leverage these ingredients across sauce and soup applications where viscosity stability proves critical.
- Liquid Sweeteners:Blended glucose-fructose solutions optimized for specific solubility and freeze-thaw performance. Dairy applications in ice cream and yogurt segments command premium positioning where handling characteristics outweigh commodity pricing.
High Fructose Corn Syrup commands the established base. The steepest expansion runs through Liquid Sweeteners.
Application:
Application physics dictates sweetener selection through solubility thresholds, thermal stability requirements, and finished-product moisture targets.
- Beverages:Carbonated soft drinks and ready-to-drink formulations demand precise sweetness equivalence and microbial stability. Southeast Asian bottlers scale procurement as reformulation timelines compress under added-sugar disclosure mandates.
- Bakery Products:Humectancy and Maillard browning control dominate functional requirements. Granulated and powdered forms penetrate this channel where handling characteristics and moisture management determine procurement decisions.
- Dairy Products:Freeze-thaw stability and protein compatibility differentiate liquid sweetener grades. Sports nutrition and yogurt segments drive specification tightening as clean-label positioning intensifies.
- Confectionery:Controlled crystallization and viscosity modulation shape glucose syrup selection. Hard candy and caramel applications require specific dextrose equivalent ranges to achieve target texture profiles.
Beverages anchor volume concentration. Dairy Products are climbing the fastest as functional formulation demands intensify.
End User:
Customer type segments procurement behavior through technical service intensity, contract scale, and formulation collaboration depth.
- Food Manufacturers:Integrated procurement of sweeteners alongside starches and specialty ingredients. These customers negotiate bundled agreements with wet millers offering R&D support for reformulation mandates.
- Beverage Companies:Consolidated supplier relationships around integrated ingredient portfolios. Procurement teams demand 12-18 month product redevelopment cycles with precise sweetness equivalence guarantees.
- Retailers:Private-label formulation oversight and supplier audit requirements. These end users specify non-GMO and lower-carbon-intensity grades to meet sustainability commitments.
- Foodservice Providers:Volume-driven procurement of standard liquid and granulated sweeteners. Operational simplicity and consistent supply security outweigh specialty functional requirements.
Food Manufacturers command the established base. Beverage Companies are gaining share fastest through technical service integration.
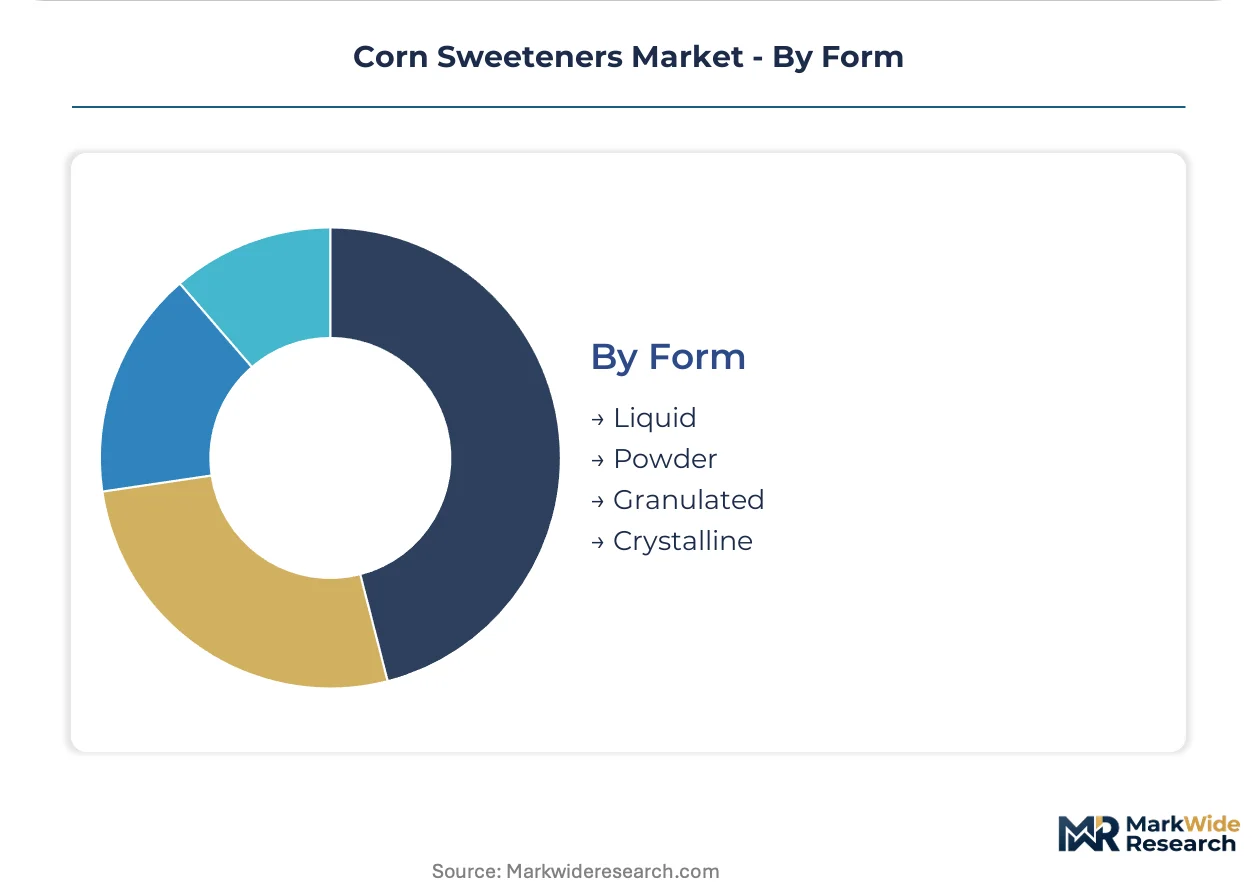
Form:
Physical state determines logistics economics, handling infrastructure requirements, and application flexibility across manufacturing environments.
- Liquid:Pumpable syrups delivered in bulk tanker or intermediate bulk container formats. Beverage and dairy processors favor this form for direct incorporation into continuous production lines.
- Powder:Spray-dried glucose and maltodextrin products with controlled particle size distribution. Dry mix manufacturers leverage handling efficiency and extended shelf stability.
- Granulated:Agglomerated sweeteners with flowability optimized for bakery and confectionery scales. Premium positioning reflects moisture resistance and dispensing precision.
- Crystalline:High-purity dextrose monohydrate or anhydrous products. Pharmaceutical and specialized food applications drive specification where purity thresholds exceed standard food-grade requirements.
Liquid commands the established base. Powder is expanding most quickly through dry mix and sports nutrition proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wet milling capacity clusters tightly across the US Corn Belt, where integrated processors leverage captive grain origination networks. Brazil and Argentina compete on seasonal harvest windows but face freight-cost disadvantages. Southeast Asian demand expansion is reshaping trade flow patterns for liquid sweetener grades.
United States
EPA biofuel mandates sustain corn offtake volumes, stabilizing feedstock basis for integrated wet milling operations. FDA added-sugar labeling requirements pressure beverage manufacturers toward reformulated fructose-glucose blends. Iowa and Illinois host the densest concentration of enzymatic hydrolysis capacity, where processors balance commodity dextrose against specialty maltodextrin output.
Brazil
São Paulo-state bottlers expand carbonated and ready-to-drink production, driving liquid sweetener procurement at scale. ANVISA nutrition labeling standards increasingly align with WHO sugar reduction guidelines, tightening formulation specifications. The Center-West agricultural frontier supplies feedstock, though inland logistics costs erode refining margins relative to North American competitors.
Thailand
Carbonated beverage manufacturers in Bangkok and surrounding industrial zones scale procurement of high-fructose corn syrup variants. National sugar reduction campaigns translate into procurement specifications for optimized sweetness-perception blends. Rayong and Chonburi provinces concentrate wet milling investments serving both domestic bottlers and ASEAN export markets.
Germany
EU Green Deal Farm to Fork Strategy mandates deforestation-free supply chain documentation for imported agricultural inputs. EFSA sustainability traceability requirements reshape procurement specifications from multinational food manufacturers. The Rhine-Ruhr industrial corridor hosts refining capacity oriented toward certified lower-carbon-intensity syrup grades for Scope 3 emission compliance.
Vietnam
Ho Chi Minh City-based bottlers accelerate production capacity for ready-to-drink beverages, concentrating liquid sweetener demand. National dietary guidelines under Health Ministry oversight increasingly reference WHO sugar reduction frameworks. Binh Duong and Dong Nai provinces attract wet milling investments targeting ASEAN regional supply integration.
Corn Sweeteners Market Competitive Environment
Integrated grain processors and specialty ingredient specialists split the market between commodity volume and differentiated premium positioning. Tier-one wet millers anchor supply security through captive origination networks and multi-output enzymatic platforms. Mid-scale regional processors compete on logistics proximity to emerging-market bottlers. Dominant competitive moves include backward integration into grain origination and portfolio diversification into modified starches and clean-label derivatives.
Within the integrated processor tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify archetypes combining grain origination dominance with multi-product wet milling scale. Ingredion Incorporated occupies a position representing specialty ingredient differentiation through clean-label portfolio development. These three entities anchor the competitive structure, with Tate & Lyle PLC and Roquette Frères representing European-based alternatives emphasizing sustainability certification and pharmaceutical-grade purity positioning.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| Roquette Frères |
| Global Sweeteners Holdings Limited |
| Tereos Group |
| Südzucker AG |
| Grain Processing Corporation |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Brazilian wet milling facilities is compressing regional pricing power while simultaneously accelerating supplier consolidation toward North American origination networks. This utilization asymmetry between South American and US Corn Belt processors directly shapes how buyers negotiate contract terms and how suppliers prioritize specialty maltodextrin output over commodity dextrose.
Pricing Analysis
FDA added-sugar labeling dictates the pricing tier structure across the corn sweeteners value chain. Three-tier pricing structure across premium, standard, and economy levels separates certified non-GMO derivatives from conventional grades and bulk commodity syrups. Price differentiation centers on clean-label certification and enzymatic hydrolysis precision. Cost compression in standard-tier liquid sweeteners is intensifying because beverage manufacturers demand 12-18 month reformulation cycles. Foodservice providers exhibit highest price sensitivity due to volume-driven procurement without functional specification requirements.
Supply Chain Analysis
Cargill, Archer Daniels Midland, and Ingredion hold dominant contract-manufacturing capacity across integrated wet milling complexes. Geographic supply concentration centers on the United States, Brazil, and Thailand as primary production hubs. Raw material dependencies draw from #2 yellow corn feedstock, specialized enzyme formulations, and caustic soda for starch extraction. Single-source vulnerability runs through North American grain origination networks that dominate non-GMO seed supply. Distribution runs through bulk tanker networks for liquid grades and rail-served distribution centers for dry products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Corn sweetener markets are cycling through a demand recovery phase anchored to Southeast Asian beverage capacity expansion and reformulation-driven ingredient upgrades. This cyclical upswing rewards processors with enzymatic platform flexibility and clean-label certification capabilities.
For Market Incumbents: Pre-empt substitution threats from allulose and monk fruit extracts by accelerating non-GMO line segregation investments before WHO sugar reduction guidelines harden into customer procurement specifications. Deepen backward integration into captive grain origination networks in Iowa and Illinois to defend feedstock cost position against Brazilian freight-disadvantaged competitors. For New Entrants and Emerging Players: Pursue dairy application white space in ice cream and yogurt segments where freeze-thaw stable liquid sweeteners command premium positioning and technical service intensity limits commodity competition. Vietnam and Indonesia present the most penetrable geographies given bottler capacity expansion and limited local wet milling infrastructure. Lead with formulation collaboration capabilities rather than price undercutting. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among processors offering bundled glucose-fructose-starch agreements with embedded technical service contracts. Long-term viability over the next decade hinges on enzymatic platform adaptability across dextrose equivalent ranges and clean-label certification depth. Monitor EPA biofuel mandate adjustments as the critical inflection signal for corn feedstock availability and wet miller margin structure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Origination | Cargill and ADM leverage Iowa and Illinois elevator networks to secure non-GMO seed supply for clean-label contracts. |
| Specialty Maltodextrin Capacity Expansion | Enzymatic hydrolysis platforms pivot toward sports nutrition applications where resistant starch premiums exceed commodity dextrose. |
| Non-GMO Processing Line Segregation | Legacy wet mills retrofit infrastructure to meet European EFSA traceability requirements and multinational beverage procurement specifications. |
| Integrated Ingredient Portfolio Bundling | Mid-sized bottlers in Mexico and Brazil consolidate supplier relationships around glucose-fructose-starch agreements with technical service support. |
| Sustainability Certification Investment | EU Green Deal Farm to Fork Strategy mandates deforestation-free documentation for corn sweetener shipments into German and French ports. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with wet mill operations managers, beverage procurement directors, and dairy formulation scientists, and secondary validation through USDA crop reports, EPA biofuel mandate filings, and FDA guidance documents. Bottom-up triangulation against top-down trade flow analysis ensured volume estimates aligned with customs data from Vietnam, Thailand, and Brazil.
Forecast inputs considered enzymatic hydrolysis capacity utilization, reformulation timeline compression from beverage customers, and clean-label certification adoption curves across end-use segments. Segmentation dimensions modeled include product chemistry, application physics, customer operational scale, and regional regulatory cluster intensity. CAGRs were derived from demand elasticity analysis relative to corn price volatility and substitution threat progression.
Macroeconomic conditions sit as an overlay; deviation in corn futures pricing, Brazilian real exchange rates, or EPA renewable volume obligations would shift the trajectory. Forecasts reflect documented assumptions regarding WHO guideline translation speed and Southeast Asian bottler capacity commissioning schedules. Quarterly review of enzyme input costs, non-GMO seed premiums, and EU carbon intensity certification uptake is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Japan Allulose Market
Sweeteners
France Food Sweetener Market
Sweeteners
Natural Malt Sweeteners Market
Sweeteners
Allulose Market
Sweeteners
Tapioca Maltodextrin Market
Sweeteners
Naturally Derived Sweeteners Market
Sweeteners
Allulose Powder Market
Sweeteners
Non Sugar Sweeteners Market
Sweeteners
North America Starch Sweetener Market
Sweeteners
South America Stevia Market
Sweeteners
Erythritol Market
Sweeteners
Clarified Rice Syrup Market
Sweeteners
Xylitol Market
Sweeteners
Agave Syrup Market
Sweeteners
Starch Glucose Syrup Market
Sweeteners
India Food Sweetener Market