
 Low-Fat Sugar Market | 2026-2036
Low-Fat Sugar Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Fat Sugar Market Analytics
Recipe-formulation services and flavor-masking technology subscriptions is expanding what ingredient suppliers bundle with core sweeteners. Tate & Lyle PLC leverages its Sweetener University digital platform to lock in beverage and dairy clients with technical support contracts. Cargill, Incorporated anchors North American supply through its corn-based erythritol and stevia blending operations. Ajinomoto Co. Inc specializes in amino-acid-derived sweeteners for precision fermentation partners seeking clean-label positioning.
Low-fat sugar comprises reduced-calorie sweetening systems engineered to deliver sucrose-like taste profiles with diminished or zero metabolizable energy content, typically formulated through enzymatic conversion, fermentation, or extraction from steviol glycosides, monk fruit, or sugar alcohols. These ingredients serve industrial food and beverage producers seeking to maintain sensory performance while complying with calorie-reduction mandates. Sugar substitutes command the deepest margin pools as patent-protected blends command price premiums over commodity alternatives. Bakery products represent the fastest-growing application segment as clean-label bread and pastry formulations replace high-fructose corn syrup with erythritol-allulose combinations.
The FDA governs GRAS self-affirmation pathways for novel sweeteners while the EPA regulates fermentation facility effluent from biomanufacturing operations. USDA organic certification requirements constrain which extraction solvents and processing aids qualify for premium product positioning. Stakeholders must monitor evolving WHO guidance on non-sugar sweeteners and its potential cascade into national dietary guidelines.
Market Dynamics
Reformulation mandates from the FDA's updated Nutrition Facts labeling requirements for added sugars are compressing product development cycles across beverage and bakery categories. Ingredient suppliers now bundle technical support contracts with core sweetener sales to capture locked-in procurement relationships.
Growth Catalysts
- Clean-label mandates:USDA organic certification requirements push manufacturers toward steviol glycoside and monk fruit extraction methods that qualify for premium positioning in retail channels.
- Beverage reformulation:Carbonated drink and ready-to-drink tea manufacturers accelerate adoption of erythritol-allulose blends to maintain mouthfeel while reducing calorie counts.
- Precision fermentation:Amino-acid-derived sweetener platforms enable biomanufacturing partners to achieve GRAS status through self-affirmation pathways with reduced regulatory friction.
Market Restraints
- Corn price volatility:Erythritol production depends on corn feedstock availability, exposing North American processors to commodity input swings that compress margin stability.
- Technical ceiling:Sugar alcohols exhibit laxative thresholds at higher inclusion rates, limiting substitution ratios in confectionery applications without flavor-masking investments.
- WHO guidance uncertainty:Evolving World Health Organization positions on non-sugar sweeteners create hesitation among national dietary guideline committees, slowing institutional adoption.
Strategic Opportunities
- Underpenetrated bakery segment:Clean-label bread and pastry formulations present expansion potential as high-fructose corn syrup replacement accelerates in artisanal and industrial channels.
- Flavor-masking subscriptions:Technical service contracts for taste-optimization platforms create recurring revenue streams beyond commodity sweetener sales.
- Biomanufacturing effluent recovery:EPA fermentation facility regulations incentivize closed-loop processing investments that reduce waste disposal costs and improve license-to-operate security.
Industry Challenges
- GRAS dossier preparation:Novel sweetener entrants face 18-24 month timelines for FDA self-affirmation documentation, delaying market entry against established competitors.
- Enzymatic conversion scale-up:Allulose production requires specialized biocatalyst immobilization systems that demand capital-intensive facility retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Fat Sugar Market |
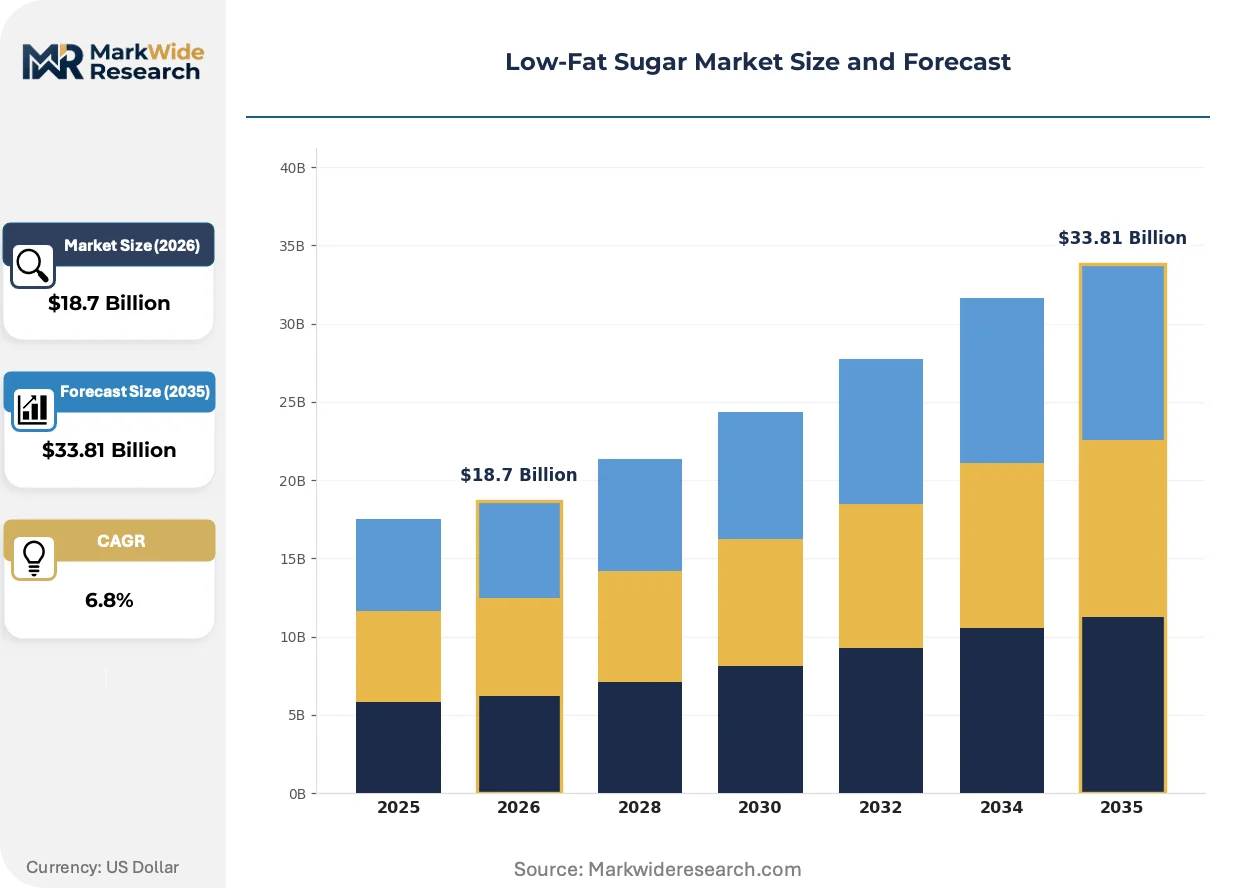
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sugar Substitutes, Sweetening Agents, Syrups, Powdered Sweeteners Application: Beverages, Bakery Products, Confectionery, Dairy Products End User: Food Manufacturers, Beverage Companies, Retail Consumers, Health-Conscious Individuals Distribution Channel: Supermarkets, Online Stores, Specialty Stores, Food Service |
| Companies Covered | Cargill, Incorporated, Tate & Lyle PLC, Archer-Daniels-Midland Company, Ingredion Incorporated, Roquette Freres, Ajinomoto Co. Inc, International Flavors & Fragrances Inc, DuPont, Südzucker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Fat Sugar Market Evolving Landscape
Digital technical support platforms are reshaping how ingredient suppliers secure long-term contracts. The convergence of formulation software with sweetener supply agreements is creating sticky customer relationships that resist price-based switching.
Enzymatic conversion of fructose to allulose is electrifying the low-calorie sweetener landscape. Commercial bakeries and beverage manufacturers are adopting this biocatalytic platform at accelerated rates. The technology is electrifying margin structures by enabling premium pricing for rare sugar positioning that commands formulation exclusivity.
REACH registration requirements for novel extraction solvents are tightening compliance burdens across European stevia supply chains. Industrial users must now document full substance safety profiles before commercial deployment. Botanical extractors serving EU markets are responding by shifting toward aqueous-only processing methods that bypass solvent classification thresholds.
Health-conscious consumer segments are consolidating purchasing decisions around front-of-pack calorie claims. Retail buyers now prioritize reduced-sugar certifications over ingredient transparency alone. This behavioral pivot concentrates demand in United States metropolitan markets where municipal sugar taxation proposals accelerate preemptive reformulation.
Low-Fat Sugar Market Segmentation
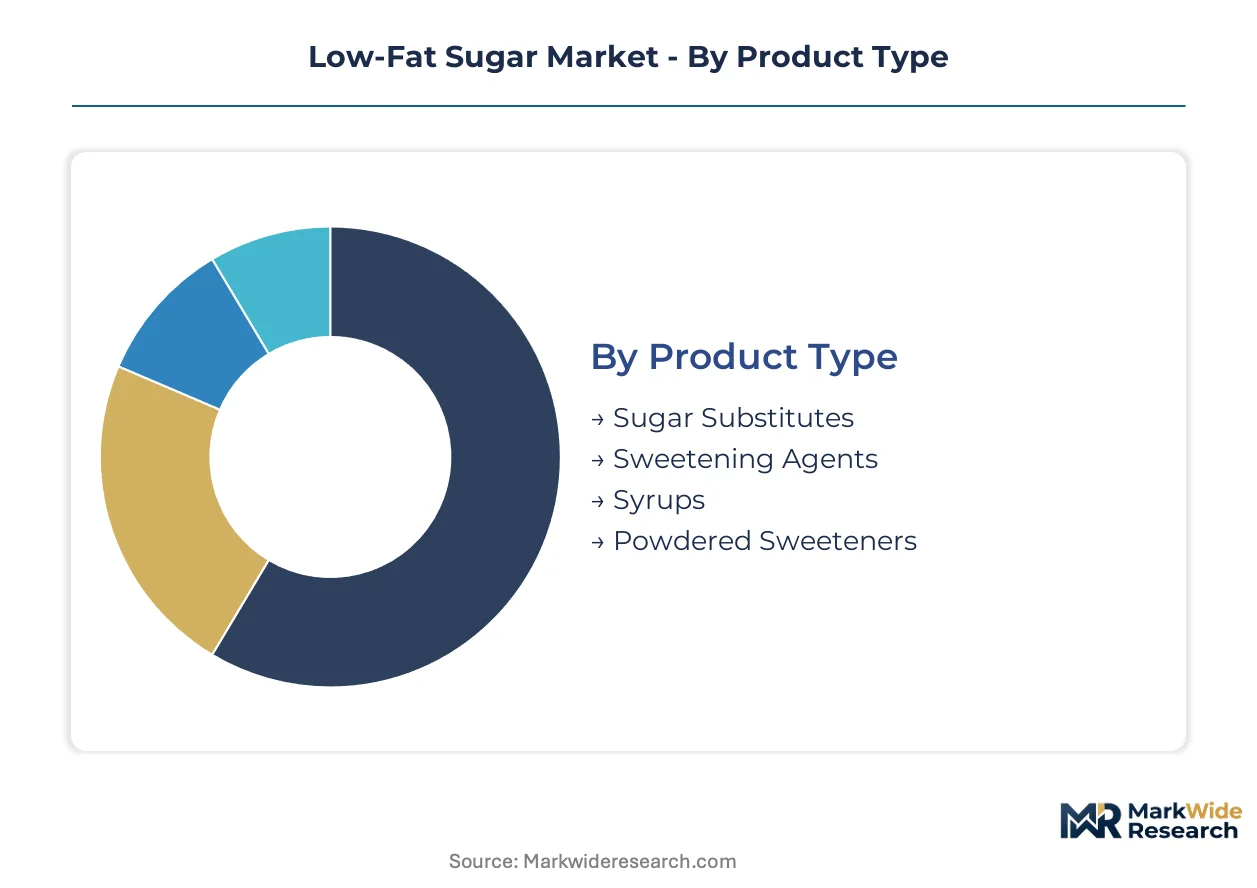
Low-fat sugar markets fragment across formulation technologies and procurement relationships that determine margin capture. Suppliers structure product portfolios around standalone sweetening systems versus embedded technical service bundles that lock in industrial accounts.
Product Type:
Standalone crystalline formats dominate bulk procurement, while liquid and co-processed systems embed deeper into customer formulation workflows.
- Sugar Substitutes:Patent-protected blends of steviol glycosides, monk fruit extracts, and sugar alcohols deliver sucrose-like sweetness with reduced metabolizable energy. Beverage manufacturers in the United States concentrate procurement here as FDA added-sugar labeling mandates compress reformulation timelines.
- Sweetening Agents:Amino-acid-derived compounds produced through precision fermentation enable clean-label positioning for organic-certified product lines. Precision fermentation partners leverage GRAS self-affirmation pathways to accelerate market entry against established erythritol suppliers.
- Syrups:Liquid delivery systems suit high-volume beverage applications requiring pumpable ingredients.
- Powdered Sweeteners:Free-flowing crystalline formats serve bakery and dry-mix manufacturers with standard dosing equipment.
Volume placements concentrate in Sugar Substitutes; the faster expansion belongs to Sweetening Agents.
Application:
End-use differentiation separates reformulation-mandated categories from discretionary premium positioning.
- Beverages:Carbonated drinks and ready-to-drink teas drive the deepest procurement volumes as manufacturers replace high-fructose corn syrup with erythritol-allulose blends. Mouthfeel maintenance requirements push technical service bundling beyond commodity sweetener supply.
- Bakery Products:Clean-label bread and pastry formulations accelerate substitution of traditional sweeteners in artisanal and industrial channels. Enzymatic conversion of fructose to allulose enables rare sugar positioning that commands formulation exclusivity.
- Confectionery:Sugar alcohol laxative thresholds limit substitution ratios without flavor-masking investments.
- Dairy Products:Fermented and flavored milk applications favor heat-stable steviol glycoside variants.
Procurement scale favors Beverages; Bakery Products gain share fastest as clean-label mandates penetrate retail channels.
End User:
Customer type determines contract structure, with industrial accounts demanding technical integration and retail segments prioritizing front-of-pack claims.
- Food Manufacturers:Industrial bakeries and packaged food producers anchor procurement volumes through multi-year supply agreements with embedded formulation support. USDA organic certification requirements constrain extraction solvent choices for premium positioning.
- Beverage Companies:Carbonated and functional drink manufacturers concentrate demand in metropolitan markets where municipal sugar taxation accelerates preemptive reformulation. Digital technical support platforms lock in procurement relationships that resist price-based switching.
- Retail Consumers:Health-conscious households purchase standalone tabletop formats through supermarket and online channels.
- Health-Conscious Individuals:Fitness-oriented segments prioritize zero-calorie claims in protein and supplement applications.
Contract value concentrates in Food Manufacturers; Beverage Companies expand procurement most quickly as reformulation mandates tighten.
Distribution Channel:
Channel structure separates commodity spot purchasing from technical service-dependent supply relationships.
- Supermarkets:Mass retail channels move crystalline and liquid formats to household consumers and small food service operators. Front-of-pack calorie claims drive shelf placement negotiations with reduced-sugar certifications prioritized over ingredient transparency.
- Online Stores:Direct-to-consumer and B2B platforms serve specialty ingredient procurement for artisanal producers and formulation laboratories. Subscription-based flavor-masking technology bundles create recurring revenue streams beyond one-time sweetener sales.
- Specialty Stores:Natural and organic retailers cater to clean-label demand with certified extraction method verification.
- Food Service:Restaurant and institutional channels require bulk liquid delivery with consistent sweetness equivalence.
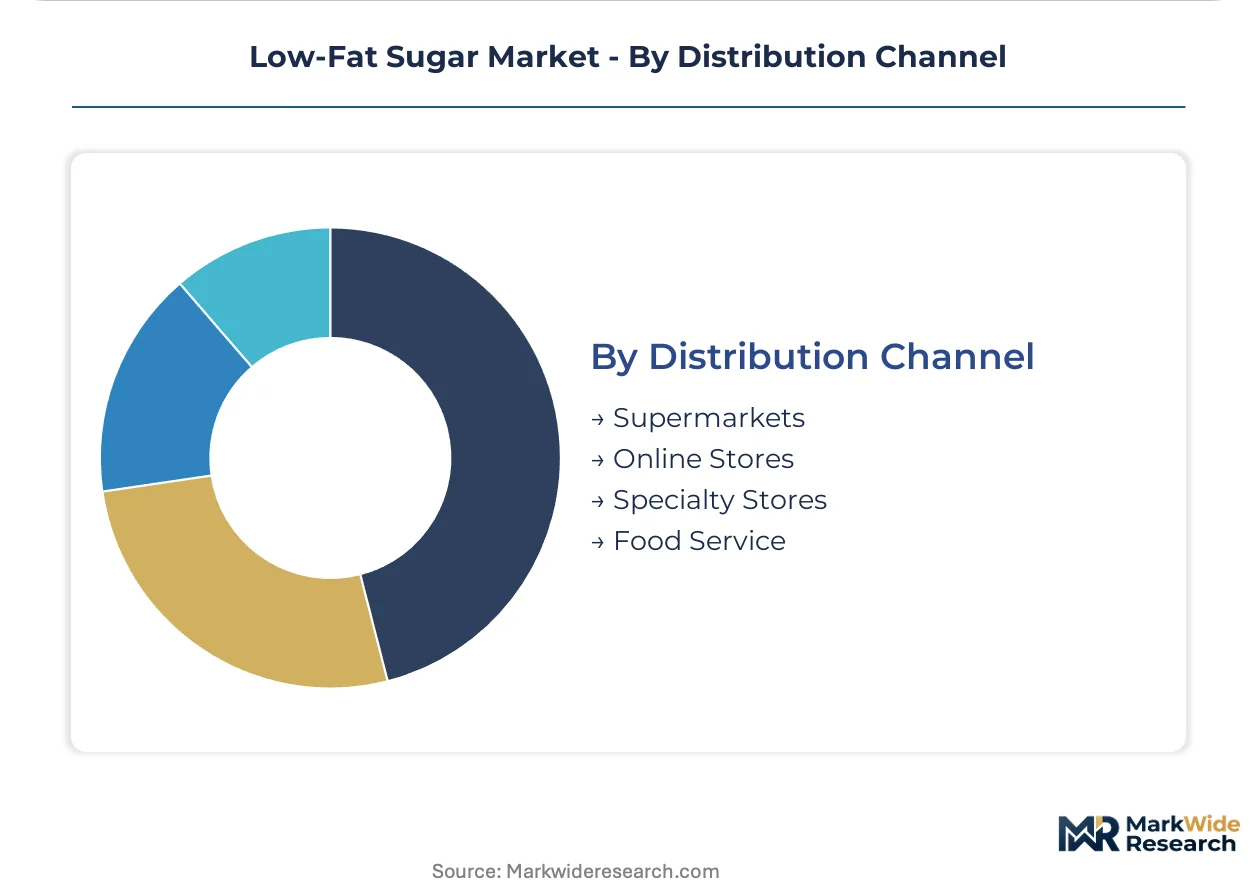
Transaction volume concentrates in Supermarkets; Online Stores climb fastest as technical service subscriptions reshape procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in corn-belt processing facilities while consumption gravitates toward coastal metropolitan markets with sugar-tax exposure. The United States dominates formulation-driven procurement, yet regulatory divergence across jurisdictions fragments supply chain standardization.
United States
FDA added-sugar labeling mandates compress reformulation timelines for beverage manufacturers. Municipal sugar taxation proposals in Philadelphia and Seattle accelerate preemptive ingredient substitution. Corn-based erythritol production clusters in Iowa and Illinois, with biomanufacturing scale-up concentrated in Midwest fermentation corridors.
Germany
REACH registration requirements for novel extraction solvents tighten compliance burdens across stevia supply chains. EFSA guidance on non-sugar sweeteners shapes national dietary recommendations. Botanical processing facilities in Bavaria shift toward aqueous-only methods to bypass solvent classification thresholds.
China
SAMR standards for food additive labeling drive clean-label positioning among domestic brands. Dual carbon goals constrain energy-intensive enzymatic conversion facilities. Steviol glycoside extraction concentrates in Shandong Peninsula provinces with established botanical processing infrastructure.
Brazil
ANVISA regulatory pathways for novel sweetener approval create entry barriers against established suppliers. Sugar-alcohol production leverages existing cane ethanol fermentation capacity. São Paulo state anchors industrial formulation demand from packaged food manufacturers.
India
FSSAI draft regulations on front-of-pack labeling push reformulation in carbonated beverages. PLI scheme incentives attract precision fermentation investment for amino-acid-derived sweeteners. Maharashtra and Gujarat host expanding contract manufacturing for export-oriented bakery applications.
Low-Fat Sugar Market Competitive Landscape
Top-tier vendors anchor patent-protected blending operations, while mid-scale processors compete on commodity erythritol and stevia extraction. The structure bifurcates between integrated agribusiness conglomerates with captive corn supply and specialized biomanufacturing firms leveraging precision fermentation. Strategic archetypes include formulation-technology bundlers, rare-sugar enzymatic converters, and clean-label botanical extractors. Dominant competitive moves encompass technical support contract lock-ins and GRAS dossier acceleration partnerships.
Among North American agribusiness conglomerates, Cargill, Incorporated and Archer-Daniels-Midland Company occupy positions anchored by corn-based feedstock integration. Tate & Lyle PLC exemplifies the formulation-technology bundler archetype through digital platform deployment. Ajinomoto Co. Inc represents the precision fermentation specialist tier with amino-acid-derived positioning.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Tate & Lyle PLC |
| Archer-Daniels-Midland Company |
| Ingredion Incorporated |
| Roquette Freres |
| Ajinomoto Co. Inc |
| International Flavors & Fragrances Inc |
| DuPont |
| Südzucker |
| Others |
Value Network & Pricing Analysis
Biocatalyst engineering talent clustering in Midwest fermentation corridors widens pricing-tier spreads between premium enzymatic-conversion platforms and commodity erythritol supply. Labor-cost differentials between these specialized technical centers and standard corn-processing regions directly feed into three-tier pricing stratification across patent-protected blends, certified-organic extracts, and bulk sugar-alcohol commodities.
Pricing Analysis
Margin tightening in commodity erythritol traces to corn feedstock volatility and processor overcapacity in Iowa and Illinois. Three-tier pricing structure across premium, standard, and economy levels separates patent-protected allulose formulations from USDA-certified organic stevia extracts and unbranded sugar-alcohol commodities. Price differentiation hinges on GRAS dossier completion status and embedded technical support contracts. Beverage manufacturers show lowest price sensitivity due to reformulation mandate urgency, while small bakeries exhibit highest sensitivity to per-kilogram crystalline formats.
Supply Chain Analysis
Dual-sourcing requirements from major beverage manufacturers mandate multi-supplier qualification across corn-belt erythritol processors and Shandong Peninsula steviol glycoside extractors. Geographic supply concentrates in the United States, China, and Brazil, with raw material dependencies on corn feedstock, cane ethanol byproducts, and monk fruit botanical harvests. Supply chain risk centers on single-source vulnerability for immobilized biocatalyst systems used in allulose production. Distribution runs through long-term technical service contracts for industrial accounts, with spot purchasing limited to commodity crystalline formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in this market is accelerating into a vertical-integration race. Players are pursuing captive control over fermentation capacity and proprietary biocatalyst supply to lock in margin capture and secure license-to-operate advantages.
For Market Incumbents: Acquire immobilized enzyme production facilities to secure biocatalyst supply for allulose platforms against precision fermentation entrants. Consolidate formulation-technology assets through technical support contract roll-ups that resist price-based switching. Defensive moves must counter amino-acid-derived sweetener substitutes by accelerating GRAS dossier partnerships with FDA consultants. For New Entrants and Emerging Players: Artisanal bakery channels represent the most penetrable segment given clean-label substitution momentum and limited incumbent technical service penetration. White-space exists in aqueous-only stevia extraction for EU REACH compliance, bypassing solvent registration burdens. Go-to-market should leverage subscription-based flavor-masking platforms to create recurring revenue stickiness beyond commodity sweetener sales. For Investors and Strategic Acquirers: Re-rating potential sits with precision fermentation specialists given amino-acid-derived sweetener platforms' clean-label positioning and reduced regulatory friction through GRAS self-affirmation. Long-term viability favors biomanufacturing assets with closed-loop effluent recovery systems that preempt EPA enforcement exposure. The signal to watch is municipal sugar taxation proposal density in metropolitan markets as a demand-pull indicator for reformulation services.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biocatalyst Production | Captive enzyme supply secures allulose margin structures against fermentation input volatility. |
| Technical Service Contract Roll-ups | Digital formulation platform acquisitions lock in beverage and dairy procurement relationships. |
| Closed-loop Effluent Recovery Investment | EPA fermentation facility compliance reduces waste disposal costs and improves operating security. |
| Aqueous Extraction Method Certification | REACH solvent bypass enables EU market entry without novel substance registration timelines. |
| Flavor-masking Technology Licensing | Recurring revenue streams from taste-optimization subscriptions diversify beyond commodity sales. |
Research Methodology
Multi-period observation of reformulation mandate compliance timelines and procurement contract structures anchored the trend analysis, supplemented by interviews with ingredient R&D directors, beverage formulation scientists, bakery procurement leads, and EPA compliance officers. Secondary validation drew from FDA GRAS notification databases, USDA organic certification registries, ECHA REACH substance filings, and SEC 10-K supply chain disclosures. Bottom-up volume modeling triangulated against top-down market sizing across enzymatic conversion, fermentation, and botanical extraction platforms.
Segment-weighting approaches applied differential growth assumptions across sugar substitutes, sweetening agents, syrups, and powdered formats by end-use intensity in beverages, bakery, confectionery, and dairy. CAGRs were derived from elasticity-adjusted volume projections and value-per-kilogram trends across certification tiers. Forecast inputs incorporated corn price volatility indices, municipal sugar taxation proposal tracking, and precision fermentation capacity buildout announcements.
Caveats apply where WHO non-sugar sweetener guidance revisions or FDA labeling enforcement shifts could materially shift the outlook. Forecasts reflect documented assumptions regarding reformulation mandate adherence rates and biomanufacturing scale-up timelines. A model refresh is warranted upon material change in EPA fermentation facility effluent regulations or EFSA sweetness additive guidance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Sodium Saccharin Market
Sweeteners
Sanding Sugar Market
Sweeteners
North America Food Sweetener Market
Sweeteners
Short-Chain Fructooligosaccharides (Scfos) Market
Sweeteners
Europe Plant-Derived and Synthetic Sugar Market
Sweeteners
Egypt Food Sweetener Market
Sweeteners
Digestion Resistant Maltodextrin Market
Sweeteners
Methyl Glucose Market
Sweeteners
Asia Pacific Food Sweetener Market
Sweeteners
Reduced Sugar Products Market
Sweeteners
Asia-Pacific Sugar Substitute Market
Sweeteners
Germany Food Sweetener Market
Sweeteners
Monk Fruit Sugar Market
Sweeteners
Middle East and Africa Food Sweetener Market
Sweeteners
Sugar Syrups Market
Sweeteners
Rare Sugar Market