
 Global Starch Sweetener Market | 2026-2036
Global Starch Sweetener Market Size, Share, and Industry Trends Forecast 2026-2036
Global Starch Sweetener Market Outlook
Beverage industry procurement is decoupling from traditional high fructose corn syrup contracts as clean-label priorities fragment buyer concentration across craft soda and functional drink startups. Ingredion leverages its specialty sweetener portfolio to anchor supply relationships with reformulating brands. Cargill sustains geographic dominance through integrated corn processing networks in North America and Asia. Tate & Lyle differentiates via advanced enzyme technologies that reduce residual sugars in maltodextrin production.
Starch sweeteners comprise enzymatically or acid-hydrolyzed carbohydrate derivatives derived from corn, wheat, cassava, or potato starches, typically exhibiting dextrose equivalents between 20 and 100 depending on hydrolysis depth; these compounds function as bulking agents, humectants, and fermentable substrates across food, pharmaceutical, and industrial applications. Glucose syrup commands the largest volume share among product types due to its versatility in confectionery and bakery systems, while maltodextrin generates premium margins from sports nutrition and infant formula applications. High fructose corn syrup faces structural pressure in beverage applications as reformulation trends accelerate, though it retains cost advantages in mass-market soft drink production.
The FDA enforces added-sugar labeling requirements under Nutrition Facts panel rules, compelling manufacturers to reformulate with lower-glycemic starch sweeteners or risk consumer rejection. The EU Green Deal and F-Gas Regulation constrain energy-intensive wet-milling operations, redirecting capital toward enzymatic processing upgrades that reduce thermal loads. China's SAMR implements GB standards for starch-based food additives that dictate purity thresholds and residual sulfur limits for imported syrups. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation lock-in that sacrifices cross-border product portability.
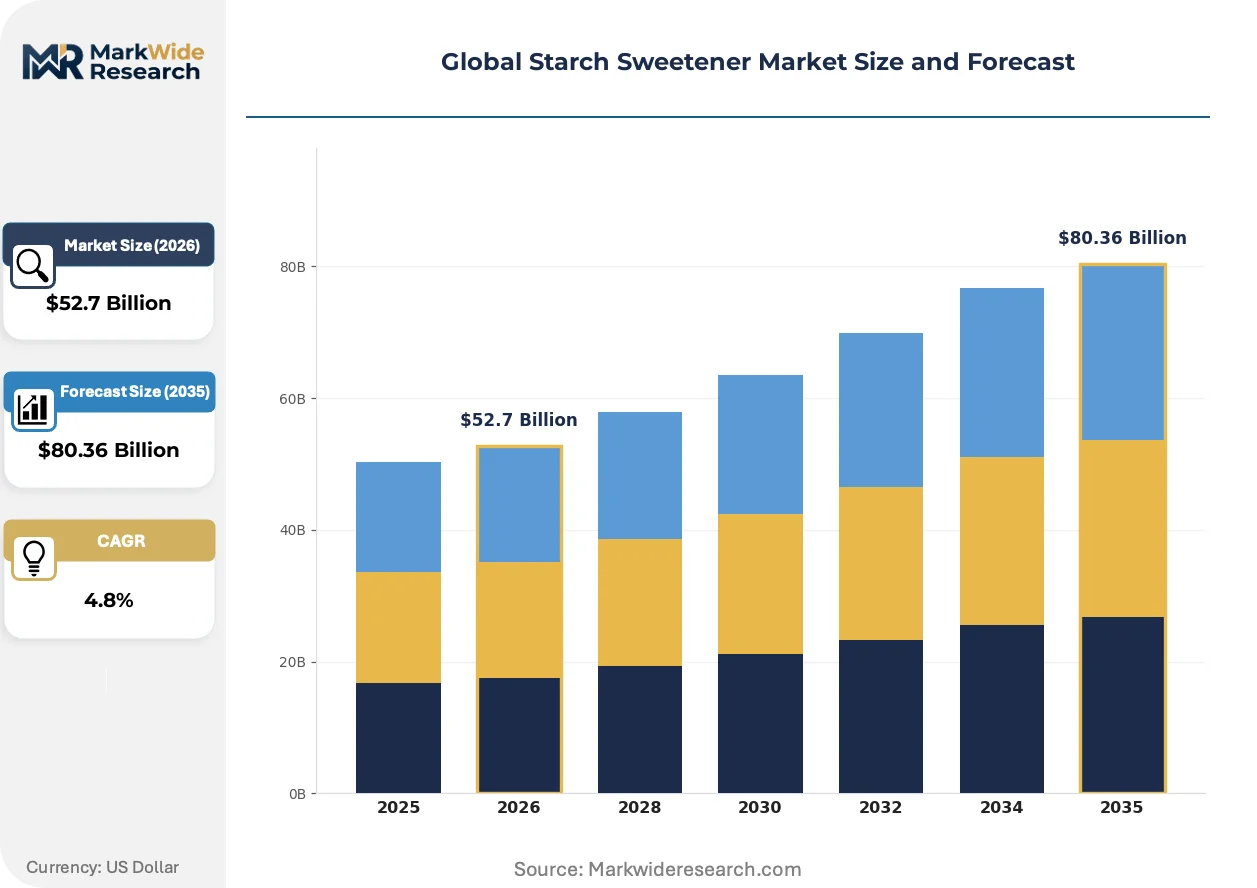
Market Dynamics
Beverage reformulation is fragmenting procurement patterns as clean-label mandates force manufacturers away from high fructose corn syrup toward lower-glycemic starch derivatives, rewiring supplier-buyer relationships across multiple continents.
Growth Catalysts
- FDA Added-Sugar Disclosure:Nutrition Facts panel rules compel reformulation with maltodextrin and glucose syrups that register lower glycemic impact.
- Sports Nutrition Formulation:Rapid-digesting carbohydrate demand from endurance athletes and bodybuilders drives premium maltodextrin volumes.
- EU Green Deal Energy Standards:Wet-milling operators invest in enzymatic upgrades to reduce thermal loads and maintain operating permits.
Market Restraints
- Corn Price Volatility:Feedstock cost swings compress margins for syrup producers lacking long-term agricultural contracts.
- Supply Concentration Risk:Wet-milling capacity clusters in the US Midwest and India's Gujarat corridor, exposing buyers to regional weather disruptions.
- Technical Limitation:Residual sulfur compounds in acid-hydrolyzed syrups trigger rejection under China's GB standards for food additives.
Strategic Opportunities
- Brazilian Ethanol Pivot:Sugar processors redirect cane capacity toward starch sweetener production as biofuel subsidies fluctuate.
- Cell-Cultured Meat Fermentation:Glucose syrups emerge as scalable carbon sources for precision fermentation bioreactors.
- India PLI Scheme:Production-linked incentives for food processing attract wet-milling investment to serve regional confectionery demand.
Industry Challenges
- Enzyme Engineering Talent:Shortage of specialists in thermostable amylase development constrains process efficiency gains.
- Cross-Border Formulation Lock-In:Divergent purity thresholds between FDA, EU, and SAMR regimes force SKU proliferation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Starch Sweetener Market |
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $80.36 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Fructose Corn Syrup, Maltodextrin, Glucose Syrup, Dextrose Application: Beverages, Bakery, Dairy, Confectionery End User: Food Manufacturers, Beverage Industries, Pharmaceutical Companies, Animal Feed Producers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Food Service |
| Companies Covered | Ingredion, COFCO International, Cargill, Associated British Foods, Japan Corn Starch, Archer Daniels Midland, Roquette Frères, Tereos, Tate & Lyle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Starch Sweetener Market Strategic Shifts
Enzymatic processing is displacing thermal hydrolysis as the dominant conversion pathway, while regulatory fragmentation and procurement decentralization reshape how starch derivatives move from mill to formulation facility.
Continuous enzymatic hydrolysis systems are integrating membrane filtration to achieve precise dextrose equivalent control with reduced energy input. Sports nutrition contract manufacturers in Germany and the Netherlands adopt these systems to meet EU Green Deal thermal efficiency targets. The technology is integrating real-time DE monitoring that compresses batch-to-batch variation and reduces rework rates.
REACH substance evaluation and the EU F-Gas Regulation now classify certain wet-milling solvents and refrigerants as restricted substances. Operators face capital decisions between retrofitting existing plants or relocating to jurisdictions with lighter chemical controls. Maltodextrin production for infant formula exports bears the heaviest compliance burden due to residual solvent testing requirements.
Brand procurement teams now mandate supplier sustainability certifications ahead of price negotiations in annual contract cycles. Direct sourcing relationships with wet-mills displace traditional distributor intermediaries in North American craft beverage channels. This pattern concentrates most visibly in California and Pacific Northwest functional drink clusters where clean-label claims determine shelf placement.
Global Starch Sweetener Market Segmentation
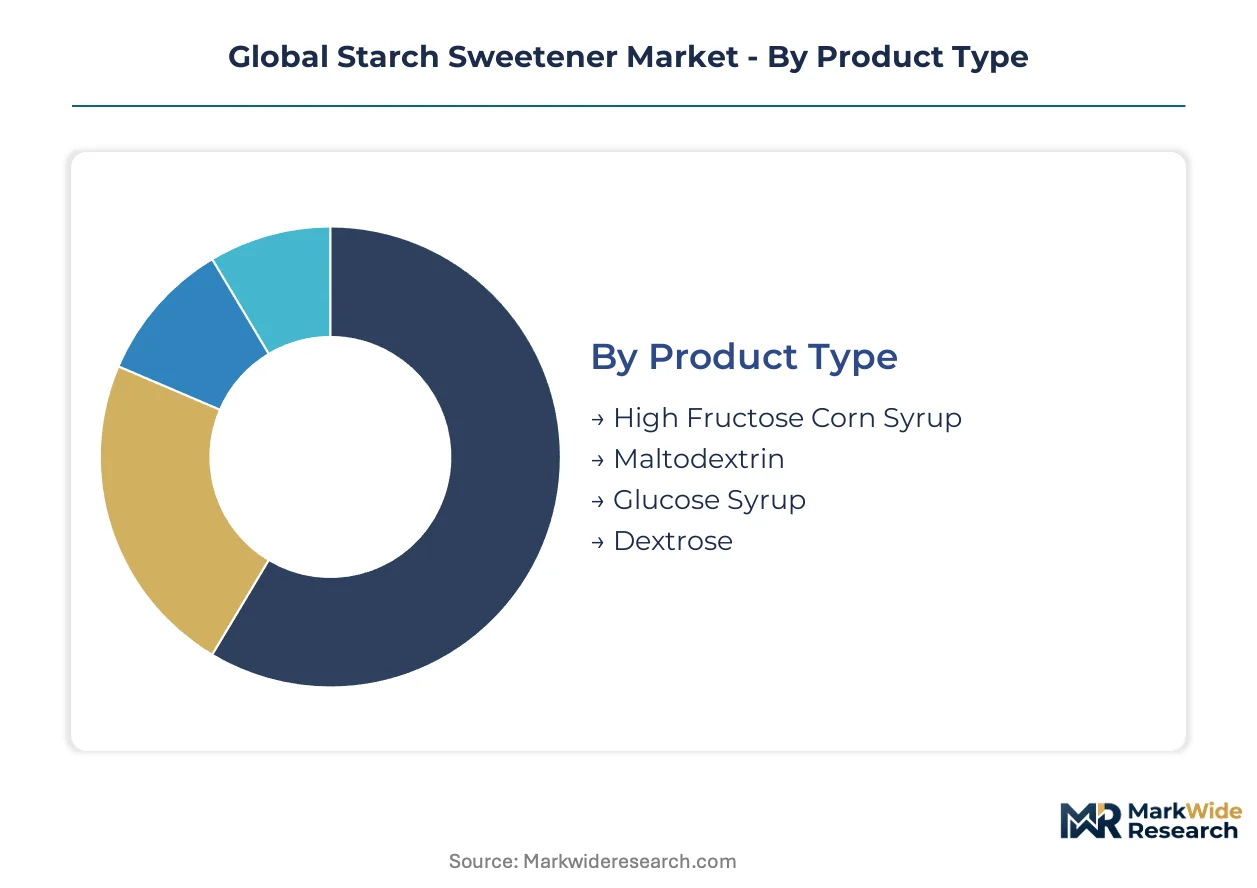
Starch sweetener procurement patterns fragment across formulation requirements, with beverage reformulation driving premium-grade specifications while commodity applications sustain volume throughput. Buyers now segment suppliers by enzymatic capability and regulatory certification rather than price alone.
Product Type:
Manufacturers upgrade from acid-hydrolyzed to enzymatically processed variants as clean-label mandates accelerate replacement cycles across beverage and infant formula channels.
- Glucose Syrup:Enzymatically hydrolyzed starch syrup with dextrose equivalents ranging from 20 to 95, valued for viscosity control and humectancy. Demand concentrates in Indian confectionery and bakery processors expanding capacity under the PLI scheme; FDA added-sugar disclosure rules push reformulation toward lower-DE variants that register reduced glycemic impact.
- Maltodextrin:Partially hydrolyzed starch with DE below 20, prized for rapid digestibility and clean flavor profiles. Sports nutrition contract manufacturers in Germany and the Netherlands absorb premium volumes as endurance athletes and bodybuilders drive rapid-carbohydrate demand; EU Green Deal thermal efficiency targets favor producers with continuous enzymatic systems.
- High Fructose Corn Syrup:Isomerized glucose syrup with fructose content typically 42% or 55%, retaining cost advantages in mass-market soft drink production despite structural pressure from clean-label alternatives.
- Dextrose:Crystalline glucose derived from complete starch hydrolysis, serving pharmaceutical excipient and fermentation substrate applications with high purity requirements.
Volume placements concentrate in glucose syrup; the faster expansion belongs to maltodextrin.
Application:
Cost tier differentiation separates premium functional formulations from commodity bulk sweetening, with certification requirements widening the gap.
- Beverages:Largest volume sink for starch sweeteners, now fragmenting between mass-market high fructose corn syrup formulations and craft functional drinks specifying lower-glycemic alternatives. California and Pacific Northwest clean-label clusters mandate supplier sustainability certifications ahead of price negotiations.
- Confectionery:Glucose syrups dominate for moisture retention and crystallization control; Indian regional processors drive procurement growth as wet-milling capacity expands in Gujarat.
- Bakery:Humectancy and browning control applications favor mid-range DE glucose syrups; European operators face REACH solvent restrictions on residual compounds.
- Dairy:Maltodextrin bulking in infant formula carries heaviest compliance burden from residual solvent testing under export market regimes.
Procurement volume clusters in beverages; dairy applications command the steepest expansion trajectory for premium-grade specifications.
End User:
Customer type determines specification stringency, with pharmaceutical and infant formula buyers imposing purity thresholds that commodity food manufacturers bypass.
- Food Manufacturers:Diverse formulation requirements spanning confectionery, bakery, and prepared foods; procurement decentralizes as clean-label mandates fragment buyer concentration.
- Beverage Industries:Structural shift away from long-term high fructose corn syrup contracts toward flexible supply relationships with enzymatic specialists.
- Pharmaceutical Companies:Dextrose and high-purity maltodextrin for tablet binders and IV solutions; China's GB standards for residual sulfur trigger rejection of acid-hydrolyzed supply.
- Animal Feed Producers:Cost-driven procurement of lower-grade syrups for fermentation substrates and palatability enhancement.
Supply relationships concentrate with food manufacturers; pharmaceutical qualification timelines create the highest switching costs.
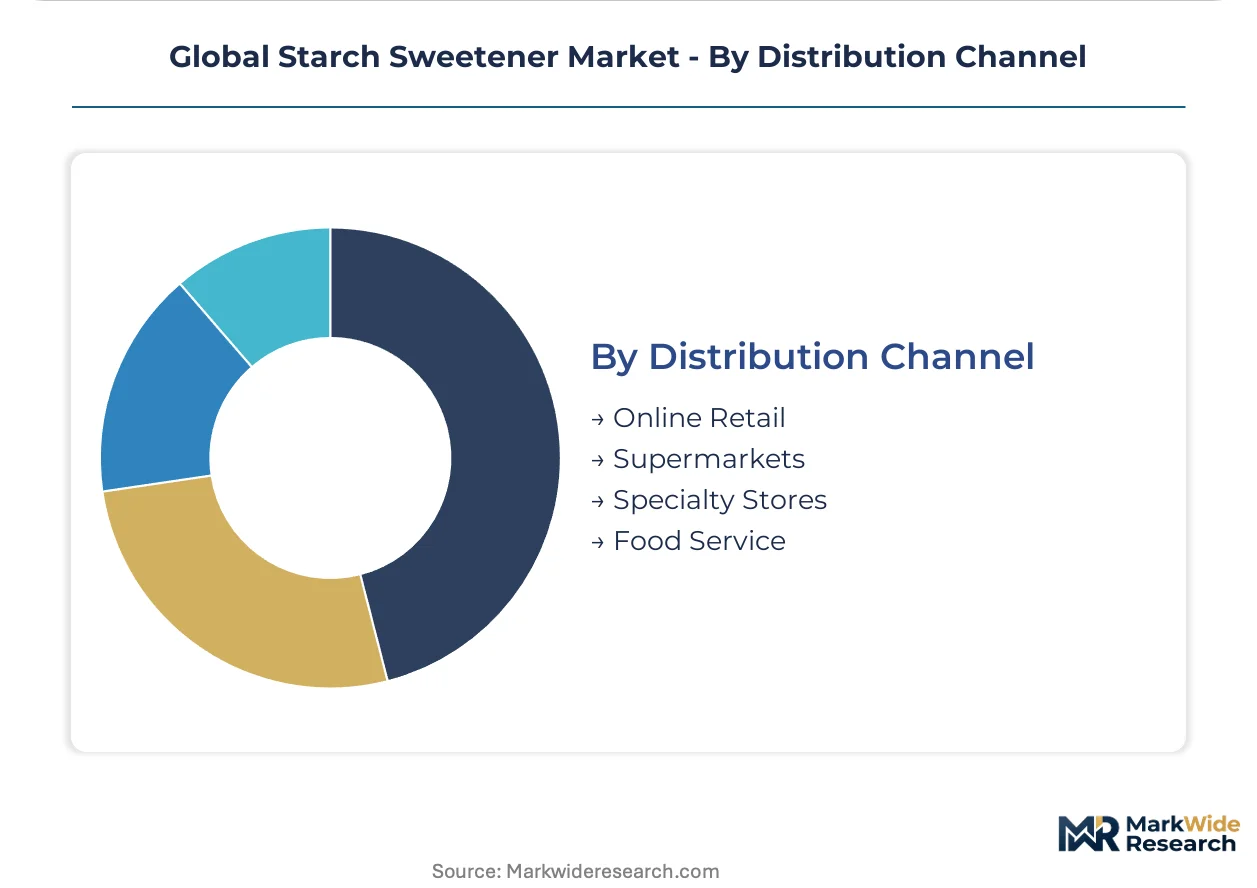
Distribution Channel:
Supply concentration in wet-milling clusters reshapes channel economics, with direct mill relationships displacing intermediaries in specification-sensitive segments.
- Food Service:Bulk glucose syrup for commercial baking and beverage dispensing; procurement favors regional distributors with inventory proximity to major metropolitan clusters.
- Supermarkets:Consumer-packaged maltodextrin and dextrose for home brewing and sports nutrition; shelf placement determined by clean-label claims in California retail.
- Online Retail:Niche specialty sweeteners and small-format sports nutrition products; growth constrained by freight economics on liquid syrup shipments.
- Specialty Stores:Premium-priced organic and non-GMO certified variants for artisan food producers and craft beverage startups.
Channel volume concentrates in food service; specialty stores gain share fastest on clean-label premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian confectionery processors and American beverage reformulators absorb the largest procurement volumes, while European enzyme specialists and Chinese regulatory compliance drive specification divergence across export markets.
United States
Beverage manufacturers in California and the Pacific Northwest mandate supplier sustainability certifications ahead of price negotiations, fragmenting procurement away from traditional high fructose corn syrup contracts. FDA added-sugar disclosure rules under Nutrition Facts panel regulations compel reformulation toward lower-glycemic maltodextrin and glucose syrups. Wet-milling capacity concentrates in the Midwest corn belt, where Cargill and Archer Daniels Midland maintain integrated processing networks.
India
Regional food processors in Gujarat and Maharashtra expand wet-milling capacity to serve domestic confectionery demand. The PLI scheme for food processing attracts capital investment from COFCO International and domestic operators. Procurement growth concentrates in Ahmedabad and Surat, where integrated mills supply glucose syrups for traditional sweetmeat production and modern bakery systems.
Germany
Sports nutrition contract manufacturers absorb premium maltodextrin volumes for endurance athlete formulations. EU Green Deal thermal efficiency targets and REACH solvent restrictions favor producers with continuous enzymatic hydrolysis systems. Processing clusters in the Rhineland and Bavaria integrate membrane filtration technology to reduce batch-to-batch variation and energy input.
China
SAMR implements GB standards for starch-based food additives that dictate purity thresholds and residual sulfur limits for imported syrups. Domestic wet-millers in Shandong and Jilin provinces upgrade from acid-hydrolyzed to enzymatic processing to meet export market requirements. Pharmaceutical buyers reject acid-hydrolyzed supply for dextrose excipient applications.
Brazil
Sugar processors redirect cane capacity toward starch sweetener production as biofuel subsidies fluctuate. The national agricultural regulator enforces evolving standards for food-grade syrup imports that align with Mercosur technical barriers. São Paulo state processors leverage existing fermentation infrastructure to supply glucose substrates for expanding food manufacturing.
Global Starch Sweetener Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue enzymatic specialization and clean-label certification. The vendor base stratifies across three tiers: integrated agricultural processors with captive corn supply, enzyme technology specialists commanding premium specifications, and regional millers competing on logistics proximity. Dominant competitive moves include backward integration into seed genetics and agricultural contracting, plus geographic expansion through joint ventures in high-growth procurement zones.
Within the integrated processor tier, Cargill and Archer Daniels Midland exemplify scale-driven positioning through Midwest corn belt concentration. Ingredion occupies the specialty sweetener vector, anchoring supply relationships with reformulating beverage brands. Tate & Lyle represents the enzyme technology archetype, with European operations favored by sports nutrition contract manufacturers seeking reduced residual sugars. COFCO International sits within the Asia-Pacific expansion category, leveraging Chinese state-linked capital to build Indian wet-milling capacity.
| Leading Market Players |
|---|
| Ingredion |
| COFCO International |
| Cargill |
| Associated British Foods |
| Japan Corn Starch |
| Archer Daniels Midland |
| Roquette Frères |
| Tereos |
| Tate & Lyle |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal thermal efficiency mandates gate qualified supply access and premium-tier pricing eligibility for starch sweetener producers. Wet-millers without enzymatic upgrade capital face margin compression while certified operators command contract premiums from beverage reformulators.
Pricing Analysis
Volume placements concentrate in commodity glucose syrup while maltodextrin captures margin expansion. Three-tier pricing structure across premium, standard, and economy levels separates enzymatically certified supply from acid-hydrolyzed alternatives from ungraded bulk. Price differentiation rests on EU Green Deal compliance certification and clean-label claim substantiation. Cost compression in standard-tier glucose syrup intensifies because Brazilian ethanol pivoters redirect cane capacity, while pharmaceutical buyers show least price sensitivity for dextrose excipient grades.
Supply Chain Analysis
Freight economics on liquid syrup shipments constrain distribution radius and favor regional mill placement over centralized production. Wet-milling capacity clusters in the United States, India, and China, with corn feedstock draws from Midwest agricultural networks, Gujarat corridor procurement, and Shandong province supply bases. Raw material dependencies center on corn, wheat, and cassava starches plus thermostable amylase enzyme inputs. Single-source vulnerability runs through US Midwest weather exposure. Distribution runs through direct mill relationships displacing distributor intermediaries in specification-sensitive segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
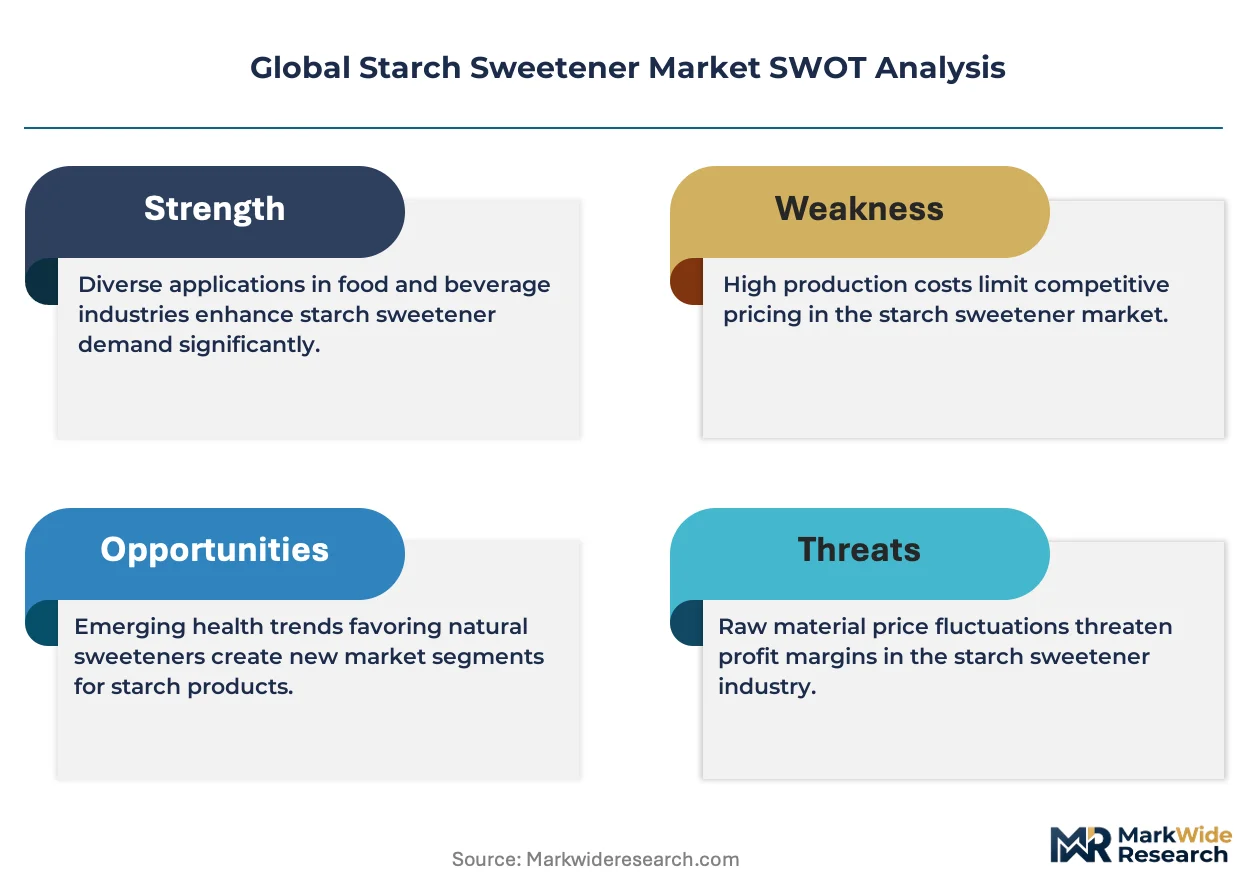
Analyst Recommendations
Starch sweetener procurement consolidation accelerates as FDA added-sugar disclosure rules force reformulation investments that weaker acid-hydrolyzed operators cannot fund.
For Market Incumbents: Anchor supply relationships with enzymatic certification investments that exceed REACH solvent restrictions and SAMR residual sulfur limits. Defend against emerging enzyme technology specialists by securing captive corn supply through agricultural contracting in Iowa and Illinois production zones. Prioritize backward integration into seed genetics to lock feedstock quality specifications. For New Entrants and Emerging Players: India's PLI scheme for food processing opens a window for wet-milling capacity buildout serving Gujarat and Maharashtra confectionery demand. Target sports nutrition contract manufacturers in Germany and the Netherlands seeking reduced residual sugar maltodextrin. Pursue direct sourcing relationships with Pacific Northwest craft beverage clusters that mandate sustainability certifications ahead of price negotiations. For Investors and Strategic Acquirers: Cargill and Archer Daniels Midland capacity announcements in Indian Gujarat corridor is the leading indicator that Asia-Pacific procurement gravity is shifting. Long-term viability favors enzyme technology specialists with continuous hydrolysis systems over thermal-dependent legacy operators. Target acquisition archetype: European mid-cap enzymatic processors with EU Green Deal compliance infrastructure. Watch FDA enforcement actions on added-sugar disclosure as inflection signal for reformulation-driven demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Processing Upgrade | EU Green Deal thermal targets favor continuous systems with membrane filtration in Rhineland operations. |
| Backward Integration into Corn Supply | Captive agricultural contracting in US Midwest insulates margin from feedstock price volatility. |
| Clean-Label Certification Investment | FDA disclosure rules and EU purity standards gate access to beverage reformulation contracts. |
| Joint Venture in Indian Wet-Milling | PLI scheme incentives attract COFCO International capital to serve regional confectionery expansion. |
| Specialty Maltodextrin Capacity Addition | Sports nutrition demand from German contract manufacturers commands premium pricing over commodity grades. |
Study Parameters
Independent corroboration across wet-mill operations executives, beverage procurement directors, and sports nutrition contract manufacturers underwrites the qualitative findings in this study. Primary interviews with enzyme technology R&D leads and regulatory affairs specialists at starch processing operators combined with secondary validation from FDA guidance documents, EU REACH substance evaluations, and SAMR GB standards filings. Bottom-up capacity assessments triangulate against top-down demand modeling from confectionery, bakery, and pharmaceutical end-use channels.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon. Segmentation dimensions modeled include product type tier, application specification grade, enzymatic versus thermal processing pathway, and regional regulatory cluster. CAGRs derive from installed capacity trajectories, reformulation timeline assumptions, and substitution elasticity estimates for high fructose corn syrup displacement. Forecast inputs incorporate PLI scheme investment flows and EU F-Gas Regulation compliance cost curves.
The model assumes a particular technology adoption path; alternative pathways for thermostable amylase development would alter the outlook if enzyme engineering talent scarcity constrains process efficiency gains. Forecasts reflect assumptions about regulatory enforcement consistency and reformulation timeline adherence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Sucrose Esters Market
Sweeteners
Asia-Pacific Sugar Substitute Market
Sweeteners
Middle East and Africa Low Calorie Sweeteners Market
Sweeteners
Brown Rice Syrup Market
Sweeteners
North America Plant-Derived and Synthetic Sugar Market
Sweeteners
India Food Sweetener Market
Sweeteners
South Africa Food Sweetener Market
Sweeteners
Steviol Glycoside Market
Sweeteners
Glucose, Dextrose, and Maltodextrin Market
Sweeteners
Sugar Market
Sweeteners
Maltol and Ethyl Maltol Market
Sweeteners
Europe Low-Calorie Sweeteners Market
Sweeteners
Europe Natural Sweetener Market
Sweeteners
Rare Sugar Market
Sweeteners
Dry Molasses Market
Sweeteners
Europe Plant-Derived and Synthetic Sugar Market