
 Brazil Food Sweetener Market | 2026-2036
Brazil Food Sweetener Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Food Sweetener Market Outlook
Brazilian cane ethanol processors is rebalancing capacity toward crystalline sugar and liquid sweetener derivatives as fuel-alternate margins compress. Cargill leverages its vertical crush footprint to secure year-round dextrose supply to beverage bottlers in the Southeast. Raízen sustains massive sucrose output from its Paulista mill network, anchoring the domestic raw sugar benchmark. Tate & Lyle competes on specialty starch-based sweeteners, differentiating through texture-modifying blends for reduced-sugar bakery applications.
Food sweeteners encompass caloric and non-caloric substances—sucrose, fructose-glucose syrups, steviol glycosides, and high-intensity peptides—that impart sweetness, modify viscosity, and control water activity in processed foods, typically standardized by purity grades exceeding 99.5 percent for refined crystalline forms. Sugar dominates volume flows across Brazilian manufacturing, though stevia extracts capture expanding share in natural-positioned beverages as ANVISA accelerates novel food ingredient approvals. High fructose corn syrup retains cost advantage in mass-market soft drinks, while aspartame occupies stable demand in tabletop and confectionery segments where thermal stability requirements are less stringent.
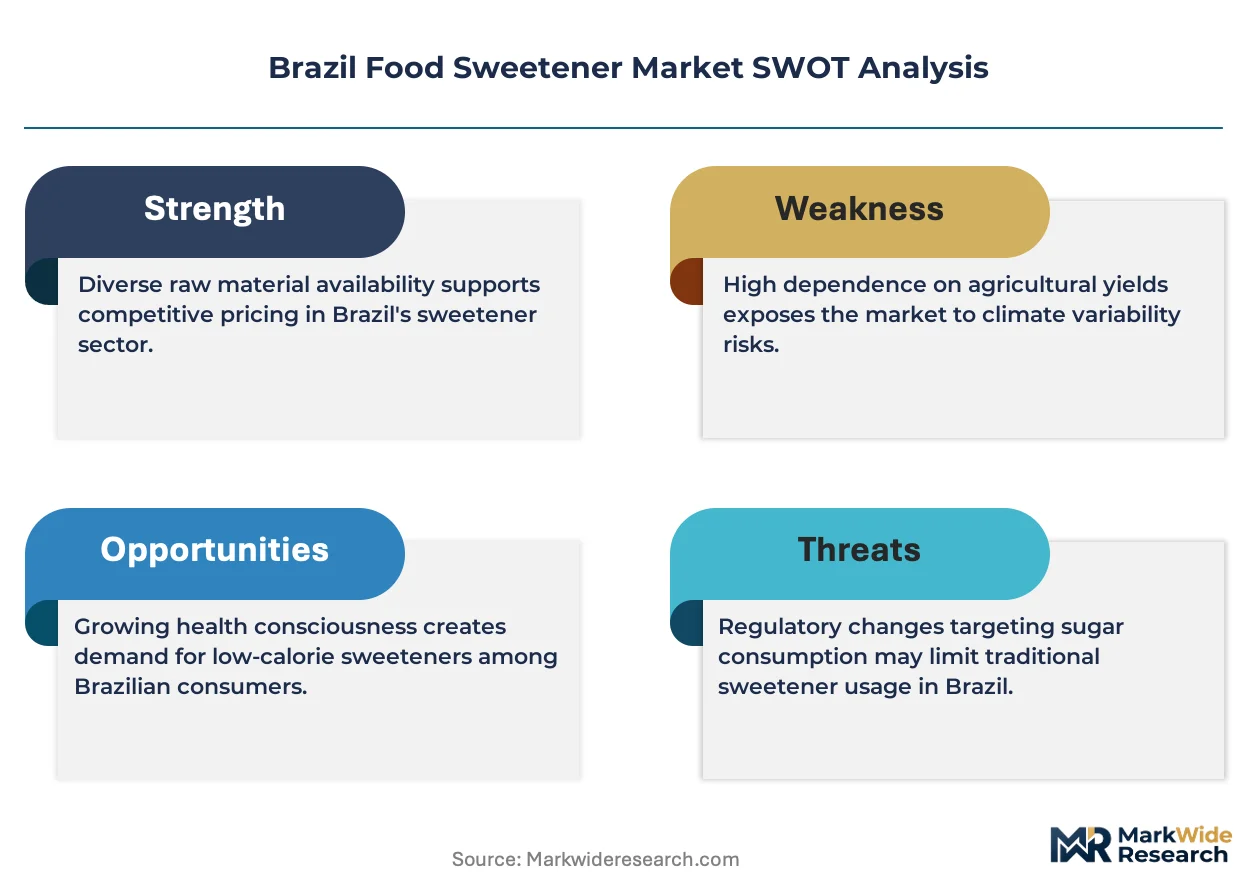
ANVISA enforces maximum residue limits and mandatory front-of-package warning labels for added sugar content, compelling reformulation across processed food categories. The country's national agricultural regulator monitors pesticide application in cane fields, while Mercosur technical standards harmonize cross-border sweetener specifications for intra-regional trade. Stakeholders must monitor pending ANVISA consultations on revised acceptable daily intake levels for high-intensity sweeteners, as these determinations will redirect R&D spending toward next-generation natural alternatives or trigger portfolio consolidation among suppliers lacking clean-label credentials.
Market Dynamics
ANVISA's front-of-package sugar warning labels are forcing beverage and bakery manufacturers to accelerate reformulation timelines, compressing supplier qualification cycles and redirecting procurement toward clean-label alternatives.
Growth Catalysts
- Beverage Reformulation Mandates:ANVISA's added sugar disclosure requirements are pulling high-intensity natural sweeteners into carbonated soft drinks and ready-to-drink teas at unprecedented speed.
- São Paulo Processing Corridor Concentration:The state's dense cluster of food manufacturers creates demand density that justifies dedicated sweetener blending facilities and just-in-time liquid syrup infrastructure.
- Steviol Glycoside Approvals:ANVISA's expanded novel food ingredient pathway is unlocking stevia extracts for dairy and confectionery applications previously restricted to synthetic alternatives.
Market Restraints
- Cane Input Cost Volatility:Brazilian crystalline sucrose pricing tracks ethanol parity swings, exposing food manufacturers to fuel-alternate margin compression at central-south mills.
- High-Intensity Synthetics Concentration:Aspartame and sucralose supply relies on a narrow base of offshore pharmaceutical-grade chemical processors, creating single-source vulnerability for tabletop and confectionery segments.
- Thermal Stability Limitations:Natural high-intensity extracts degrade above 120°C, excluding them from industrial baking and extrusion processes where sucrose and maltodextrin remain irreplaceable.
Strategic Opportunities
- Northeast Brazil Underpenetration:Bahia and Pernambuco food processors remain dependent on imported sweetener blends, creating white space for domestic liquid syrup distribution hubs.
- Pharmaceutical-Grade Dextrose Convergence:Parenteral nutrition and excipient applications are absorbing food-grade dextrose capacity, enabling margin expansion through dual-use fermentation streams.
- Clean-Label Channel Innovation:Direct-to-manufacturer digital procurement platforms are disintermediating traditional distributor networks for mid-sized natural sweetener buyers.
Industry Challenges
- Formulation Chemistry Talent Scarcity:Reduced-sugar product development requires rare expertise in bulking agent interactions and Maillard reaction control that outpaces Brazilian university pipeline output.
- ANVISA Novel Ingredient Timeline Uncertainty:Pending acceptable daily intake consultations for emerging high-intensity sweeteners freeze R&D budgets as manufacturers await clarity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Food Sweetener Market |
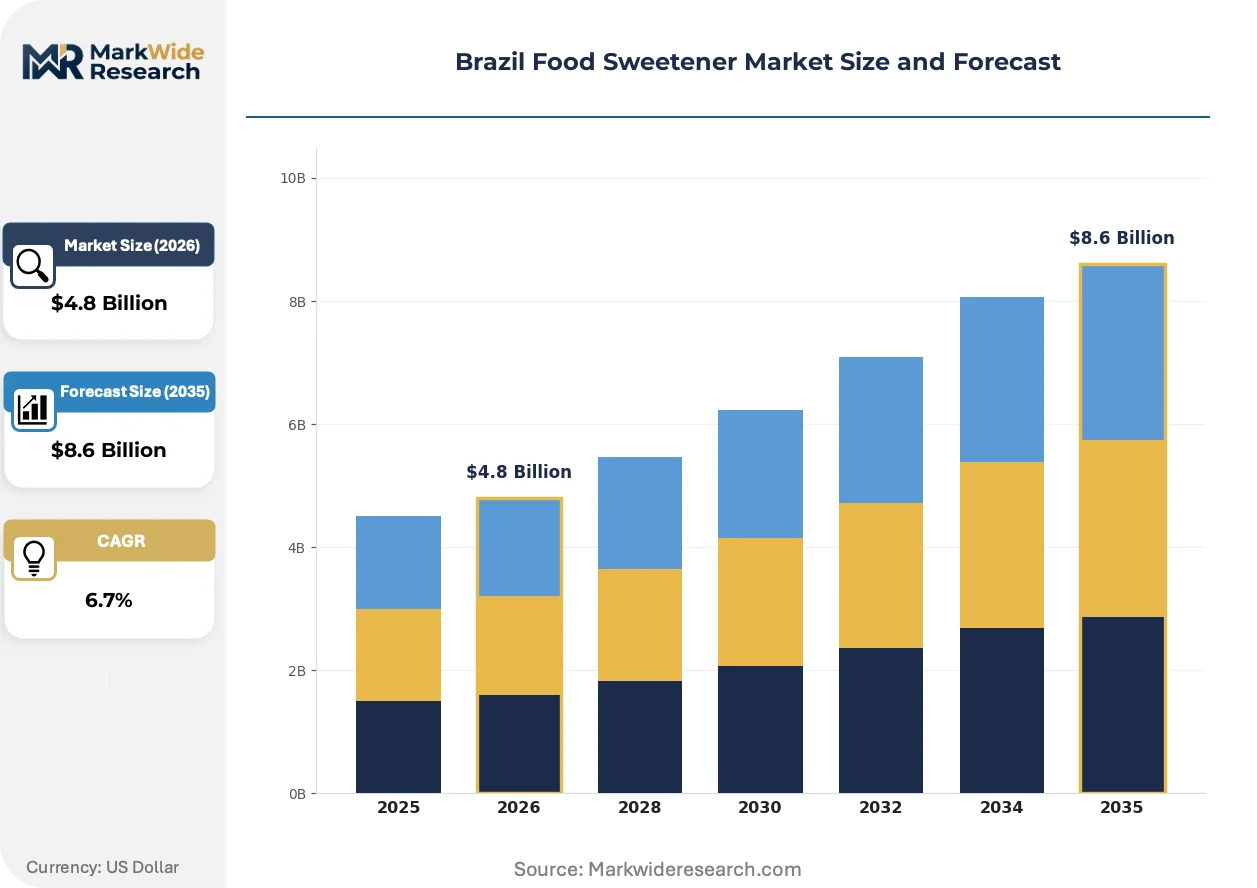
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sugar, High Fructose Corn Syrup, Stevia, Aspartame Application: Beverages, Bakery Products, Confectionery, Dairy Products End User: Household, Food Processing, Restaurants, Cafes Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesale |
| Companies Covered | Raízen, Tate & Lyle, Cargill, Bunge, DuPont de Nemours, Ingredion Incorporated, Tereos, DSM-Firmenich, Archer Daniels Midland Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Food Sweetener Market Strategic Shifts
Enzymatic bioconversion platforms are rewriting cost curves for rare sugar production, while regulatory pressure on added sugars accelerates ingredient substitution timelines across processed food categories.
Fermentation-derived allulose is electrifying reduced-calorie confectionery and ice cream formulations. Major Brazilian dairy processors are trialing the rare sugar at pilot scale. The technology is electrifying price compression in the premium natural sweetener tier, forcing stevia extractors to defend positioning through taste-modifier co-formulations.
ANVISA's pending revision to high-intensity sweetener acceptable daily intake thresholds is compressing supplier certification timelines. Manufacturers are pre-qualifying multiple natural alternatives to avoid portfolio disruption. The tabletop and confectionery segments are most exposed, accelerating dual-track formulation programs that maintain synthetic options while scaling natural backups.
Ingredient buyers in São Paulo state's beverage corridor are consolidating supplier relationships around full-service formulation partners. Traditional commodity sweetener distributors are losing share to technical service providers who deliver finished pre-blends rather than raw inputs. This concentration is most visible among mid-sized juice and dairy processors seeking to internalize less R&D capability.
Brazil Food Sweetener Market Segmentation
ANVISA's novel food ingredient pathways and front-of-package labeling mandates create divergent certification burdens across sweetener categories. Procurement teams in São Paulo's beverage corridor now segment suppliers by approval status rather than price alone.
Product Type:
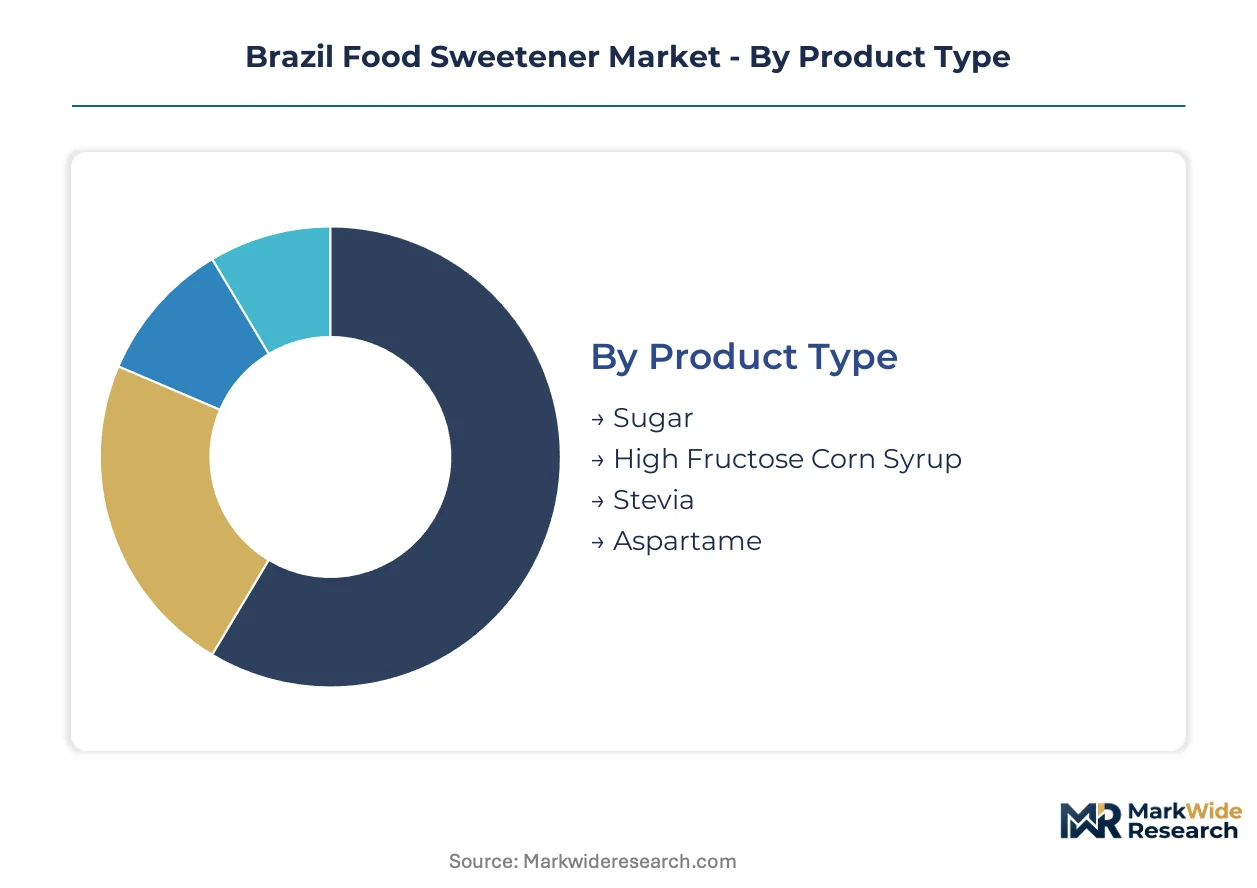
Sugar and high fructose corn syrup require only standard food-grade registration, while stevia extracts demand full novel food dossiers and aspartame faces recurring acceptable daily intake reviews.
- Sugar:Refined crystalline sucrose from central-south cane mills anchors volume flows. São Paulo bottlers absorb the majority of liquid invert syrup output as reformulation pressures intensify.
- High Fructose Corn Syrup:Enzymatically converted starch syrup delivers cost advantage in mass-market carbonated beverages. Cargill's Triângulo Mineiro facility supplies the Southeast corridor under long-term offtake agreements.
- Stevia:Steviol glycoside extracts require ANVISA novel food approval for each specific glycoside ratio. Dairy processors are the fastest adopter as clean-label positioning spreads beyond beverages.
- Aspartame:Synthetic dipeptide sweetener faces pending ADI threshold revisions that freeze expansion into new applications. Confectionery and tabletop segments maintain stable offtake where thermal stability concerns exclude natural alternatives.
Sugar sits at the top of the volume ranking, with stevia climbing the fastest.
Application:
ANVISA's added sugar warning labels hit beverage and bakery categories first, forcing accelerated reformulation timelines compared to dairy and confectionery.
- Beverages:Carbonated soft drinks and ready-to-drink teas face the most aggressive sugar reduction mandates. High-intensity natural sweeteners are displacing sucrose in formulations above 6 Brix.
- Bakery Products:Maillard reaction requirements and crumb structure needs preserve sucrose and maltodextrin dominance. Reduced-sugar positioning relies on rare sugars like allulose where thermal stability permits.
- Confectionery:Hard candies and chewing gum segments combine aspartame with sugar alcohol bulking agents. ANVISA's pending ADI consultations create formulation hedging strategies across major producers.
- Dairy Products:Yogurt and flavored milk applications are expanding stevia adoption fastest. Taste-modifier co-formulations address lingering bitter aftertaste in high-protein matrices.
Beverages command the largest absolute volume, though dairy applications are gaining share fastest.
End User:
Food processing accounts for the bulk of technical specification complexity, while household and foodservice segments drive clean-label premiumization.
- Household:Retail tabletop sweetener demand splits between synthetic sachets and stevia-based natural alternatives. Supermarket shelf placement increasingly segregates by ingredient origin rather than caloric content.
- Food Processing:Industrial buyers in São Paulo state's manufacturing corridor consolidate around full-service formulation partners. Pre-blended sweetener systems displace raw commodity procurement for mid-sized juice and dairy processors.
- Restaurants:Foodservice operators face less direct regulatory pressure than packaged goods manufacturers. Bulk liquid sucrose and HFCS remain standard for fountain beverage systems.
- Cafes:Specialty coffee chains drive premium natural sweetener adoption for consumer-facing ingredient transparency. Single-serve stevia and monk fruit packets replace synthetic alternatives at the condiment station.
Food processing dominates tonnage, with cafes expanding most quickly on a percentage basis.
Distribution Channel:
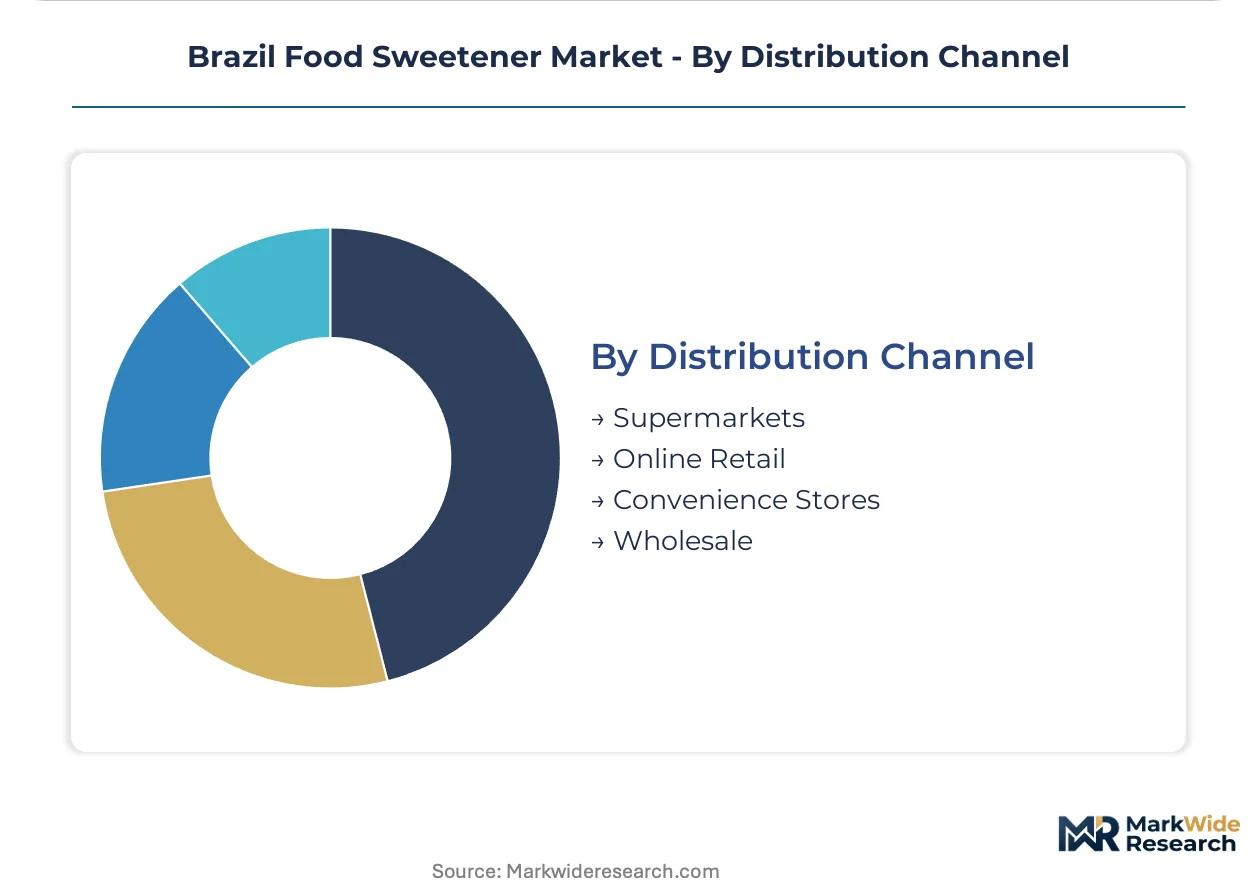
Channel selection determines access to technical support, with wholesale and online platforms diverging most sharply on formulation assistance capabilities.
- Supermarkets:Retail shelf space for natural sweeteners is expanding in premium grocery formats. Front-of-package warning labels drive consumer self-selection toward reduced-sugar household alternatives.
- Online Retail:Direct-to-manufacturer digital procurement platforms disintermediate traditional distributors for mid-sized natural sweetener buyers. Technical documentation and certificate of analysis access differentiate platform offerings.
- Convenience Stores:Limited SKU count favors high-velocity synthetic tabletop formats. Stevia penetration remains minimal due to price point constraints and slower inventory turns.
- Wholesale:Bulk liquid syrup and crystalline sucrose flow through dedicated food ingredient distributors. Just-in-time delivery contracts cover the Southeast manufacturing corridor with dedicated tanker fleets.
Wholesale channels handle the greatest volume, with online retail expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics concentrate sweetener production in states where ANVISA compliance costs align with cane processing infrastructure. Mills in ethanol-parity zones rebalance toward crystalline sugar when fuel-alternate margins compress.
São Paulo
Beverage bottlers in the Paulista processing corridor absorb the majority of liquid invert syrup output. ANVISA's front-of-package warning labels force accelerated reformulation timelines across carbonated soft drink manufacturers. Campinas and Piracicaba host dedicated sweetener blending facilities serving just-in-time procurement contracts.
Minas Gerais
High fructose corn syrup production leverages Triângulo Mineiro corn crush capacity under long-term offtake agreements. The state's central location enables distribution reach into both the Southeast beverage corridor and Northeast food processors. Uberlândia anchors Cargill's enzymatic conversion infrastructure for starch-derived sweeteners.
Rio Grande do Sul
Dairy processors in the southern state are expanding stevia adoption fastest for clean-label yogurt and flavored milk positioning. ANVISA's novel food ingredient pathway unlocks steviol glycoside applications previously restricted to synthetic alternatives. Porto Alegre food manufacturers consolidate supplier relationships around full-service formulation partners.
Bahia
Food processors in the Northeast remain dependent on imported sweetener blends, creating white space for domestic liquid syrup distribution hubs. The state's distance from central-south cane mills elevates logistics costs for crystalline sucrose. Feira de Santana industrial parks attract pre-blended sweetener distributors seeking to capture underpenetrated demand.
Paraná
Cane ethanol processors in the western corridor rebalance capacity toward crystalline sugar as fuel-alternate margins compress. The state's mill network sustains massive sucrose output anchoring domestic raw sugar benchmarks. Londrina and Maringá food manufacturers benefit from proximity to both cane fields and corn starch processing infrastructure.
Brazil Food Sweetener Market Competitive Environment
Central-south cane processors anchor one tier; international specialty ingredient specialists hold differentiated positions in high-intensity and rare sugar segments. Market structure consolidates around vertically integrated agricultural processors with captive sucrose supply, while fragmented niche players compete on formulation services. Three archetypes dominate: raw sugar millers with ethanol hedge flexibility, enzymatic bioconversion platforms, and clean-label natural extractors. Capacity rebalancing and pre-blended system partnerships represent the dominant competitive vectors.
Within the integrated milling tier, Raízen exemplifies scale-driven sucrose production from its Paulista network. Cargill occupies a position bridging agricultural crush and enzymatic syrup conversion for beverage bottlers. Tate & Lyle represents specialty differentiation through starch-based texture-modifying blends for reduced-sugar applications.
| Leading Market Players |
|---|
| Raízen |
| Tate & Lyle |
| Cargill |
| Bunge |
| DuPont de Nemours |
| Ingredion Incorporated |
| Tereos |
| DSM-Firmenich |
| Archer Daniels Midland Company |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between ANVISA novel food dossiers and standard food-grade registrations manifests in both procurement premiums and supplier qualification timelines across Brazilian sweetener markets. Beverage manufacturers absorbing liquid invert syrup face compressed margins when steviol glycoside extracts command documentation-intensive premiums, while crystalline sucrose flows through established commodity channels.
Pricing Analysis
Distributor margin compression in the Northeast corridor elevates landed costs for Bahia processors sourcing from central-south mills. Three-tier pricing structure across premium natural extracts, standard enzymatic syrups, and economy crystalline sucrose reflects ANVISA compliance burden differentials. Price erosion runs through synthetic high-intensity segments as pending ADI consultations freeze expansion budgets. Mid-sized juice processors exhibit highest price sensitivity, while pharmaceutical-grade dextrose buyers absorb premiums for dual-use fermentation streams.
Supply Chain Analysis
Domestic-content preferences embedded in Mercosur technical standards redirect procurement toward central-south cane processors over imported alternatives. Supply concentrates in São Paulo, Minas Gerais, and Paraná states, with raw material flows drawing from sugarcane crush and corn starch enzymatic conversion. Single-source vulnerability pervades offshore pharmaceutical-grade aspartame supply. Distribution runs through dedicated food ingredient wholesalers with just-in-time tanker fleets serving the Southeast manufacturing corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between São Paulo's dense processing corridor and underpenetrated Northeast markets exploits logistics cost differentials exceeding regulatory compliance burdens.
For Market Incumbents: Lock in cane supply through long-term mill offtake agreements before ethanol-parity swings redirect crush capacity. Anchor formulation partnerships with mid-sized dairy processors seeking clean-label positioning. Defend against rare sugar fermentation entrants by accelerating stevia taste-modifier co-development. For New Entrants and Emerging Players: Launch via direct-to-manufacturer digital procurement platforms disintermediating traditional distributor networks. Target Bahia and Pernambuco food processors dependent on imported sweetener blends. Penetrate through pre-blended liquid syrup distribution hubs capturing white-space demand. For Investors and Strategic Acquirers: Consolidation pressure builds where ANVISA novel food approval timelines freeze R&D budgets at sub-scale natural extractors. Five-to-ten-year viability favors enzymatic bioconversion platforms with backward integration into agricultural crush. Watch steviol glycoside ADI threshold determinations as portfolio reallocation signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cane Crush | Raízen's Paulista mill network secures year-round sucrose supply regardless of ethanol parity swings. |
| Novel Food Dossier Investment | Stevia extractors qualifying multiple glycoside ratios preempt ANVISA approval bottlenecks for dairy applications. |
| Liquid Syrup Distribution Hub Buildout | Cargill's Triângulo Mineiro facility captures long-term beverage bottler offtake through dedicated infrastructure. |
| Pre-Blended Formulation Partnership | Tate & Lyle's texture-modifying systems displace raw commodity procurement for reduced-sugar bakery processors. |
| Dual-Use Fermentation Stream Expansion | Pharmaceutical-grade dextrose convergence enables margin expansion through parenteral nutrition and excipient absorption. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cane mill operations managers, beverage procurement leads, ANVISA regulatory affairs specialists, and food formulation chemists with secondary validation against ANVISA novel food registration databases, Mercosur technical standards harmonization records, and central-south crush capacity reports. Bottom-up volume estimates triangulated against top-down agricultural output projections.
Segment-weighting applied differential growth assumptions across product type, application, and end-user dimensions, with additional modeling for ANVISA compliance status tiers. CAGRs derived from trajectory analysis of historical crush data and forward projection of reformulation timelines. Forecast inputs incorporated ethanol-parity swing scenarios and pending ADI consultation outcomes.
Several conditions sit outside the modeled scope, including abrupt ANVISA regulatory reversals, extreme climate impacts on cane yields, and geopolitical disruptions to offshore synthetic sweetener supply. Forecasts reflect documented assumptions subject to revision from these factors. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Asia-Pacific Sugar Substitute Market
Sweeteners
Stevia Mints Market
Sweeteners
Sorbitol Market
Sweeteners
Starch Glucose Syrup Market
Sweeteners
North America Sugar Substitutes Market
Sweeteners
Monk Fruit Sugar Market
Sweeteners
Molasses Market
Sweeteners
North America Stevia Market
Sweeteners
Rice Syrup Market
Sweeteners
Refined Cane Sugar Market
Sweeteners
Beetroot Molasses Market
Sweeteners
Sweeteners Market
Sweeteners
Sodium Saccharin Market
Sweeteners
Europe Plant-Derived and Synthetic Sugar Market
Sweeteners
Clarified Rice Syrup Market
Sweeteners
Global Starch Sweetener Market