
 Saudi Arabia Allulose Market | 2026-2036
Saudi Arabia Allulose Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Allulose Market Insights
SFDA food additive registration requirements is rotating competitive access in the Saudi Arabia allulose sector, privileging suppliers with established halal certification and Gulf-standard compliance. Tate & Lyle PLC leverages its enzymatic conversion expertise to anchor premium positioning across Middle East distribution channels. Ingredion Incorporated sustains formulation partnerships with Saudi beverage manufacturers seeking clean-label sugar reduction. Matsutani Chemical Industry Co., Ltd. competes through specialized crystallization technology that meets regional humidity stability requirements.
Allulose is a rare monosaccharide sugar epimer of fructose, manufactured through enzymatic epimerization of corn or wheat-derived fructose, yielding approximately 70% of sucrose sweetness with negligible caloric contribution and minimal glycemic impact. Its primary commercial purpose centers on enabling food and beverage producers to achieve sugar reduction targets without sacrificing bulk, browning, or freezing-point depression properties. Powder formulations currently dominate manufacturing procurement due to superior shelf stability and handling characteristics in Saudi climatic conditions, while liquid allulose exhibits the fastest growth trajectory driven by ready-to-drink beverage formulation demand. Bakery applications command concentrated margin pools as artisan and industrial producers reformulate traditional Saudi sweets for health-positioned retail segments.
SFDA sweetener approval protocols, SASO halal certification standards, and Gulf Cooperation Council technical regulations collectively determine product eligibility and label claim permissibility across Saudi distribution channels. These frameworks incentivize investments in supply chain traceability and third-party audit documentation. Stakeholders must monitor evolving permissibility for allulose-specific nutrient content claims as regulatory interpretation solidifies.
Market Dynamics
SFDA sweetener approval protocols are rotating competitive access in Saudi Arabia allulose, privileging suppliers with established halal certification and Gulf-standard compliance while compressing timelines for market entry.
Growth Catalysts
- Clean-label beverage reformulation:Saudi beverage manufacturers are accelerating allulose adoption in reduced-sugar carbonated drinks and functional waters to meet consumer demand for recognizable ingredients.
- SFDA regulatory formalization:The Saudi Food and Drug Authority's evolving additive approvals are creating clearer pathways for allulose-specific nutrient content claims on product labels.
- Riyadh-Jeddah retail infrastructure:Modern hypermarket and e-grocery concentration in these metropolitan clusters is enabling rapid distribution scale for health-positioned sweetener products.
Market Restraints
- Corn fructose feedstock volatility:Input costs for enzymatic epimerization fluctuate with global agricultural commodity markets, compressing margin predictability for domestic formulators.
- Single-source enzymatic technology concentration:Proprietary biocatalyst suppliers in East Asia control critical conversion efficiency patents, creating supply vulnerability for Saudi manufacturers.
- SASO halal certification complexity:The Saudi Standards, Metrology and Quality Organization's multi-stage audit requirements extend product registration timelines by 8-14 months versus conventional sweeteners.
Strategic Opportunities
- Eastern Province industrial food manufacturing:Underpenetrated processing capacity in Dammam and Al-Khobar offers greenfield partnership potential for allulose suppliers targeting institutional bakery channels.
- Neom megaproject wellness positioning:The giga-development's planned food-tech ecosystem creates demand for next-generation ingredients aligned with longevity and metabolic health narratives.
- Saudi Vision 2030 food security localization:Domestic manufacturing incentives and import substitution mandates are accelerating joint venture structures for regional enzymatic conversion facilities.
Industry Challenges
- Specialized food biochemistry talent scarcity:Local universities produce limited graduates with enzymatic process engineering expertise, forcing reliance on expatriate technical staff.
- Legacy ERP integration with halal traceability systems:Manufacturers must reconfigure supply chain software to accommodate SASO-mandated blockchain documentation without disrupting existing procurement workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Allulose Market |
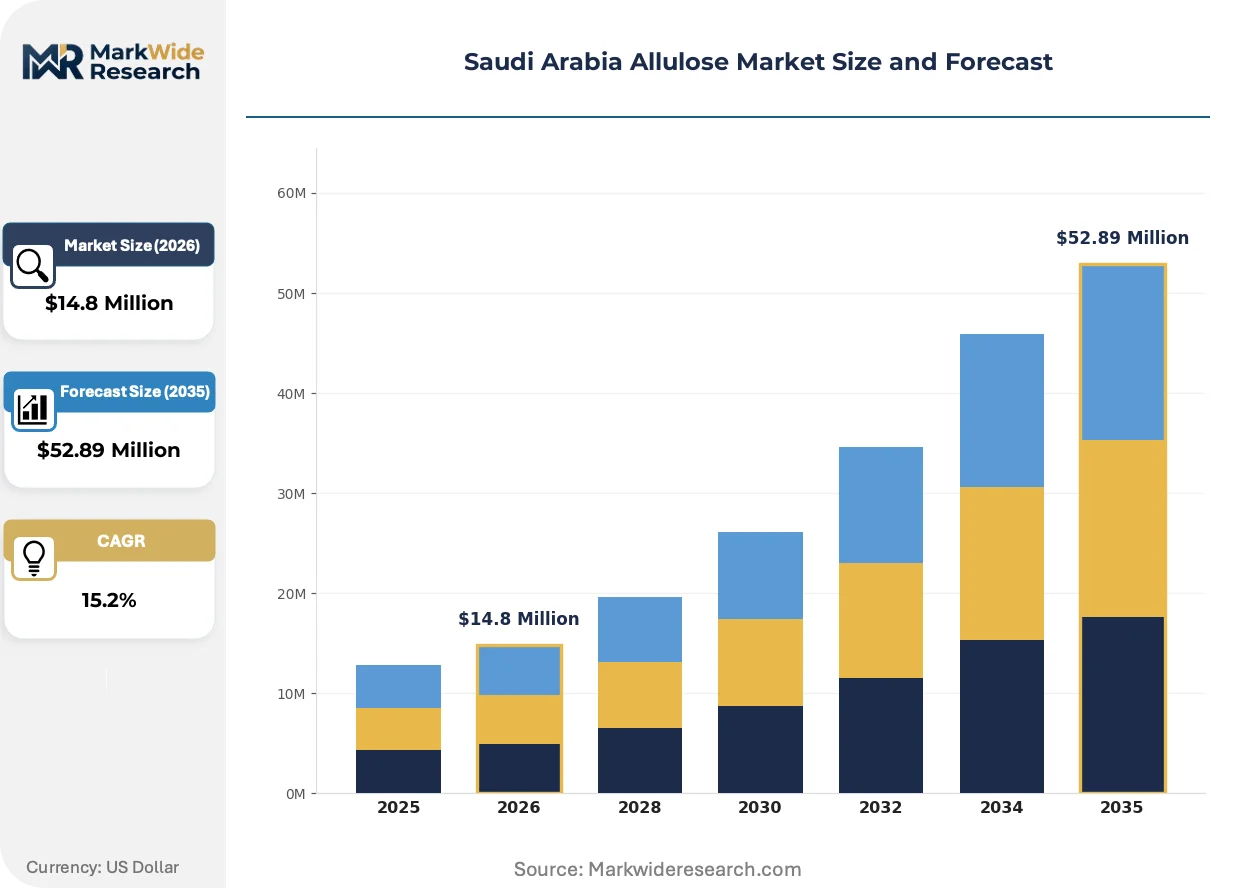
| Market Size in 2026 | $14.8 Million |
| Market Size in 2035 | $52.89 Million |
| CAGR (2026 – 2036) | 15.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Granulated, Syrup Application: Beverages, Bakery, Dairy Products, Confectionery Distribution Channel: Online, Retail Stores, Wholesale, Direct Sale End User: Food Manufacturers, Beverage Companies, Restaurants, Households |
| Companies Covered | Tate & Lyle PLC, Ingredion Incorporated, Matsutani Chemical Industry Co., Ltd., CJ CheilJedang Corporation, Bonumose Inc., Samyang Corporation, Heartland Food Products Group, Roquette Frères S.A., Cargill, Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Allulose Market Trends and Innovations
Enzymatic conversion technologies and regulatory data infrastructure are reshaping how allulose achieves commercial scale in Saudi Arabia. Three distinct vectors are compressing traditional supply timelines and reconfiguring buyer-seller relationships.
Crystallization process technology is bifurcating manufacturing economics in Saudi Arabia's allulose sector. Advanced membrane filtration and controlled cooling systems now enable powder production with moisture stability suited to regional humidity conditions. Industrial bakeries in Jeddah and Riyadh are adopting these stabilized grades at accelerating rates. The technology is bifurcating procurement patterns between commodity liquid imports and premium localized powder processing.
SFDA's implementation of electronic submission portals for novel food additive petitions is compressing regulatory review cycles. The digital infrastructure reduces documentation errors and enables real-time query response between applicants and technical reviewers. Powder allulose formulations with existing Gulf Cooperation Council equivalence recognition are benefiting most from streamlined pathway access.
Direct procurement from certified enzymatic converters is displacing traditional distributor intermediation among Saudi beverage multinationals. Large-scale manufacturers in Riyadh are establishing annual volume contracts with halal-audited Asian suppliers, bypassing regional trading houses. This channel compression is most visible in ready-to-drink tea and coffee segments where formulation consistency requirements are stringent.
Saudi Arabia Allulose Market Segmentation
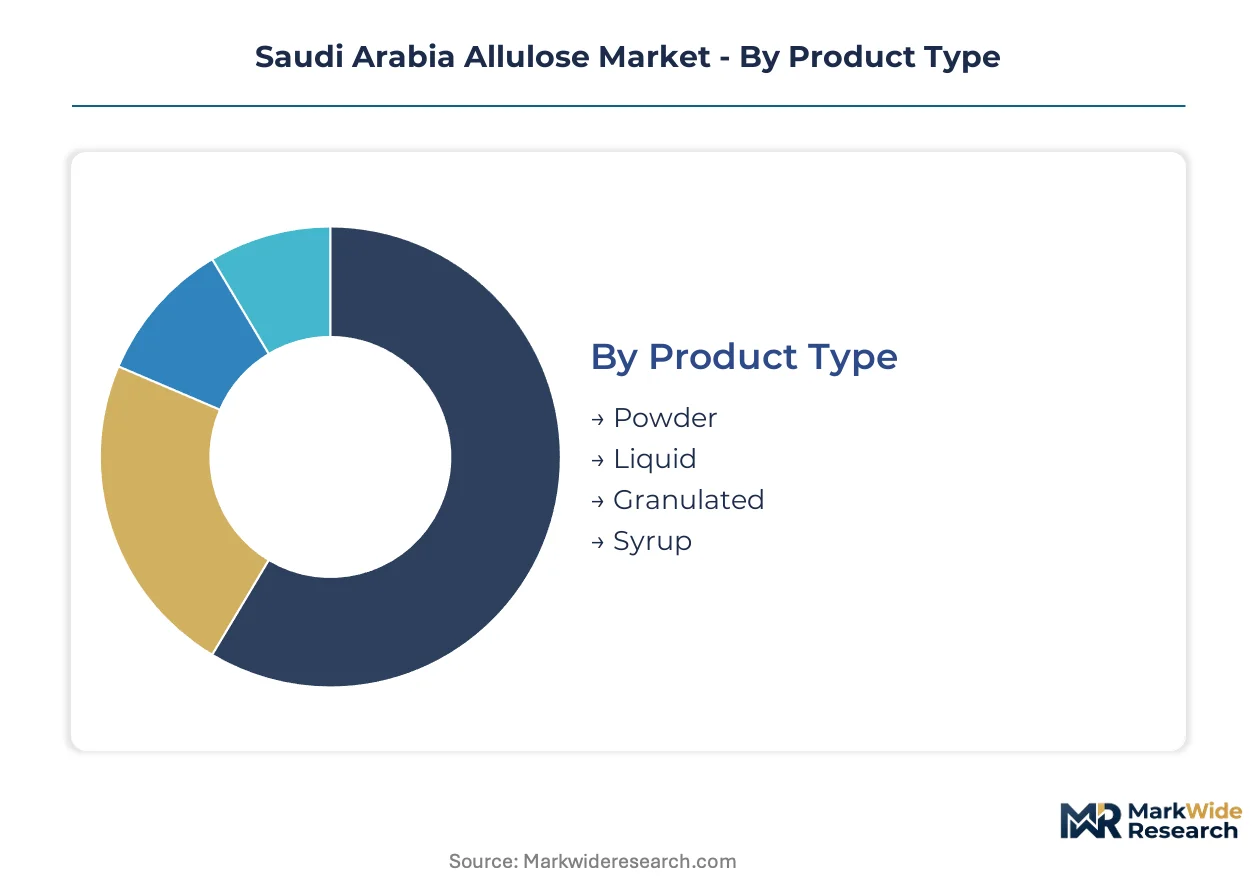
Allulose segmentation in Saudi Arabia reflects divergent technical requirements across humidity-exposed supply chains and formulation-sensitive end-uses. Powder and liquid variants face distinct substitution pressures from stevia blends and sugar alcohols depending on thermal stability needs and clean-label positioning priorities.
Product Type:
Powder allulose confronts the most intense substitute competition from crystalline erythritol and monk fruit blends in Saudi retail channels, while liquid formulations compete primarily with high-intensity sweetener concentrates in beverage manufacturing.
- Powder:Crystalline form produced through controlled cooling and membrane filtration delivers superior shelf stability under Riyadh and Jeddah humidity conditions. Industrial bakeries and confectionery manufacturers in these metropolitan clusters specify powder grades for bulk handling compatibility and Maillard reaction performance in traditional Saudi sweet reformulations.
- Liquid:Aqueous solution concentrates enable rapid dissolution in ready-to-drink beverage formulations without heating stages. Beverage multinationals operating in the Eastern Province are adopting liquid allulose for streamlined batch processing and reduced dust exposure in high-throughput bottling facilities.
- Granulated:Intermediate crystal size distribution targets artisan bakery segments requiring free-flowing properties without powder agglomeration.
- Syrup:High-viscosity aqueous preparations serve confectionery applications demanding precise moisture control and freeze-point depression.
Powder anchors the volume base while liquid gains share at the steepest rate.
Application:
Margin concentration varies sharply across application tiers, with bakery commanding premium pricing for humidity-stabilized grades while beverages drive volume scale through standardized liquid procurement.
- Beverages:Carbonated soft drinks, functional waters, and ready-to-drink teas constitute the largest volume sink for liquid allulose in Saudi Arabia. Manufacturers leverage its clean sweetness profile and minimal glycemic impact to support reduced-sugar claims under evolving SFDA labeling guidelines.
- Bakery:Industrial and artisan producers reformulate traditional Saudi sweets including maamoul and baklava variants for health-positioned retail segments. Powder allulose with specialized crystallization technology maintains structural integrity and browning characteristics critical to authentic product identity.
- Dairy Products:Yogurt and flavored milk applications exploit allulose freezing-point depression for premium ice cream and frozen dessert formulations.
- Confectionery:Hard candies and chewing gum manufacturers value allulose for non-cariogenic positioning and sustained sweetness release profiles.
Beverage procurement dominates tonnage flows while bakery applications capture the widest margin spreads.
Distribution Channel:
Channel configuration reflects buyer scale stratification, with direct procurement displacing intermediaries among volume manufacturers while retail fragmentation persists in household and small commercial segments.
- Direct Sale:Annual volume contracts between Saudi beverage multinationals and halal-certified enzymatic converters eliminate distributor markups. Riyadh-based manufacturers establish direct relationships with Asian suppliers to secure formulation consistency and audit documentation for SASO compliance.
- Wholesale:Regional trading houses aggregate powder and liquid shipments for redistribution to mid-sized food manufacturers lacking import licensing infrastructure.
- Online:E-grocery platforms and B2B marketplaces serve small bakeries and restaurants in secondary cities with flexible order quantities.
- Retail Stores:Hypermarket and specialty ingredient outlets in Jeddah and Riyadh supply household consumers and artisan producers with packaged powder and granulated formats.
Direct sale channels command the highest absolute volumes while online distribution expands most quickly.
End User:
End-user sophistication determines technical service intensity, with food manufacturers requiring formulation support and halal traceability documentation that household purchasers rarely demand.
- Food Manufacturers:Industrial bakeries and confectionery producers in Jeddah, Riyadh, and the Eastern Province specify allulose for clean-label reformulation of traditional Saudi products. These buyers require batch-to-batch consistency, SASO audit trails, and technical support for humidity-stabilized powder integration.
- Beverage Companies:Carbonated drink and functional water producers leverage allulose for sugar reduction targets without artificial sweetener aftertaste. Large-scale manufacturers prioritize direct supplier relationships and Gulf Cooperation Council equivalence recognition for regulatory efficiency.
- Restaurants:Café chains and dessert specialists in metropolitan clusters adopt allulose for menu items targeting health-conscious consumer segments.
- Households:Individual consumers purchase packaged powder and liquid formats through retail and online channels for home baking and beverage preparation.
Food manufacturers anchor procurement volumes while beverage companies drive the steepest adoption trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food manufacturers in Riyadh and Jeddah anchor procurement volumes for humidity-stabilized allulose grades, while Eastern Province industrial clusters drive beverage-sector adoption through direct supplier relationships.
Riyadh
Carbonated drink producers and industrial bakeries concentrate demand for powder allulose in Saudi Arabia's capital. SFDA electronic submission portals compress regulatory review timelines for manufacturers seeking clean-label reformulation approvals. The Riyadh-based food manufacturing corridor hosts annual volume contracts between beverage multinationals and halal-certified enzymatic converters.
Jeddah
Artisan confectionery producers and modern hypermarket chains prioritize humidity-stable crystalline grades for traditional Saudi sweet reformulations. SASO halal certification requirements extend product registration timelines, privileging suppliers with established audit documentation. Jeddah's Red Sea port infrastructure enables rapid customs clearance for imported enzymatic conversion feedstocks.
Eastern Province
Underpenetrated processing capacity in Dammam and Al-Khobar offers greenfield partnership potential for institutional bakery channels. Domestic manufacturing incentives under Saudi Vision 2030 accelerate joint venture structures for regional enzymatic conversion facilities. The province's petrochemical industrial base provides feedstock proximity for prospective fructose epimerization investments.
Western Region
Neom megaproject wellness positioning creates demand for next-generation ingredients aligned with longevity narratives. MOHAP-equivalent standards in the giga-development's planned food-tech ecosystem exceed conventional SFDA requirements. The northwest corridor's zero-carbon industrial zones attract enzymatic technology licensors seeking premium positioning.
Saudi Arabia Allulose Market Competitive Landscape
Player mix skews toward multinational ingredient conglomerates with enzymatic conversion expertise and established Gulf distribution infrastructure. The Saudi Arabia allulose sector exhibits consolidated upstream supply with fragmented downstream formulation partnerships. Three strategic archetypes dominate: halal-certified Asian enzymatic converters, North American formulation technology licensors, and European specialty carbohydrate processors. Competitive moves concentrate on direct procurement contracts with Riyadh beverage manufacturers and SASO audit trail investments.
Within the multinational conglomerate tier, Tate & Lyle PLC and Ingredion Incorporated exemplify positioning anchored in enzymatic conversion expertise and formulation partnership structures. Matsutani Chemical Industry Co., Ltd. occupies a specialist position representing Japanese crystallization technology adapted to regional humidity stability requirements. These three companies illustrate the geographic and technological stratification defining competitive access in Saudi Arabia's allulose sector.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Ingredion Incorporated |
| Matsutani Chemical Industry Co., Ltd. |
| CJ CheilJedang Corporation |
| Bonumose Inc. |
| Samyang Corporation |
| Heartland Food Products Group |
| Roquette Frères S.A. |
| Cargill, Incorporated |
| Others |
Pricing and Supply Chain Analysis
SASO halal certification requirements gate both supplier qualification and price differentiation simultaneously, compressing market entry timelines for uncertified players while enabling premium positioning for audit-documented enzymatic converters. Buyers with established Gulf-standard compliance capture pricing power in contract negotiations with Riyadh beverage manufacturers seeking formulation consistency guarantees.
Pricing Analysis
Cost-plus contracts with corn fructose feedstock indexation dominate procurement between Saudi beverage multinationals and Asian enzymatic converters. Price differentiation rests on halal certification tier and humidity-stabilized crystallization grade, with SASO-audited suppliers commanding spreads over uncertified alternatives. Cost compression in liquid allulose intensifies as direct procurement bypasses distributor markups. Mid-sized food manufacturers exhibit highest price sensitivity due to limited import licensing infrastructure and volume scale constraints.
Supply Chain Analysis
Red Sea port congestion on Asia-Saudi trade lanes elevates inbound logistics costs for crystalline powder shipments during peak import windows. Supply concentrates in China, South Korea, and Japan, where proprietary biocatalyst patents anchor enzymatic conversion capacity. Raw material dependencies include corn-derived fructose, specialized membrane filtration equipment, and halal-certified processing enzymes. Single-source vulnerability in East Asian biocatalyst suppliers creates supply risk for domestic formulators lacking alternative conversion technology access. Distribution runs through direct annual volume contracts for large manufacturers and regional trading house aggregation for mid-tier buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized food biochemistry talent scarcity constrains domestic manufacturing scale-up, forcing reliance on expatriate enzymatic process engineers and compressing joint venture negotiation leverage for Saudi partners.
For Market Incumbents: Secure backward integration into halal-certified enzymatic conversion capacity through joint venture structures with Asian technology licensors, insulating margin pools from feedstock volatility and proprietary biocatalyst supply disruption. Defend positioning by embedding SASO audit documentation into customer ERP systems, creating switching costs for Riyadh beverage manufacturers dependent on seamless traceability compliance. For New Entrants and Emerging Players: Anchor in Eastern Province institutional bakery channels where underpenetrated processing capacity in Dammam and Al-Khobar offers greenfield partnership potential absent entrenched supplier relationships. Target humidity-stabilized powder grades for artisan maamoul and baklava reformulation, leveraging technical service intensity gaps left by commodity-focused incumbents. Lead with formulation support bundled with crystallization expertise rather than price competition. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across regional enzymatic conversion facilities as Saudi Vision 2030 domestic manufacturing incentives reduce import dependency economics. Long-term viability favors acquiring specialists with established Gulf Cooperation Council equivalence recognition and SASO audit infrastructure rather than technology licensors lacking regional compliance documentation. Watch for SFDA allulose-specific nutrient content claim permissibility as inflection signal for premium pricing power expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Investment | SASO audit documentation enables premium pricing tiers in Riyadh-Jeddah procurement corridors. |
| Joint Venture Structure | Domestic enzymatic conversion partnerships satisfy Saudi Vision 2030 localization mandates while securing feedstock proximity. |
| Crystallization Technology Licensing | Humidity-stabilized powder grades command margin premiums in Jeddah artisan bakery segments. |
| Direct Procurement Contract | Annual volume agreements with beverage multinationals eliminate distributor markups and ensure formulation consistency. |
| ERP Traceability Integration | Blockchain-enabled halal documentation creates customer switching costs and compresses competitor access timelines. |
Research Methodology
Operator-level perspectives from enzymatic conversion plant managers, Saudi beverage manufacturer procurement leads, SASO certification auditors, and Red Sea port logistics coordinators anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation across SFDA additive registration databases, SASO halal certification records, Gulf Cooperation Council technical regulation filings, and customs trade flow documentation. Bottom-up demand modeling from end-use application segments triangulated against top-down supply capacity assessments across Asian enzymatic converter facilities.
Sensitivity analysis tested forecast robustness across corn fructose price volatility scenarios, regulatory approval timeline variations, and halal certification audit completion delays. The analytical framework segmented volume and value projections across powder and liquid product types, beverage and bakery applications, direct sale and wholesale distribution channels, and food manufacturer and beverage company end users throughout the forecast period. CAGRs derived from regression analysis of historical adoption curves in comparable reduced-sugar sweetener markets, adjusted for Saudi-specific regulatory formalization pace and modern retail infrastructure expansion rates.
Material uncertainties — SFDA allulose-specific claim permissibility revisions, SASO halal certification requirement modifications, and Gulf-standard harmonization shifts — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding enzymatic conversion technology licensing availability and regional humidity stability specification evolution. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
South America Food Sweetener Market
Sweeteners
Galactose Market
Sweeteners
Xylose Market
Sweeteners
Europe B2B Brown Sugar Market
Sweeteners
Asia-Pacific Sugar Substitute Market
Sweeteners
Sugar Substitutes Market
Sweeteners
Middle East and Africa Plant-Derived and Synthetic Sugar Market
Sweeteners
Smoked Sugar Market
Sweeteners
North America Sugar Substitutes Market
Sweeteners
Caramelized Sugars Market
Sweeteners
Europe Food Sweetener Market
Sweeteners
Global Alternative Sweeteners Market
Sweeteners
Corn Syrup Market
Sweeteners
North America Plant-Derived and Synthetic Sugar Market
Sweeteners
Organic Palm Sugar Market
Sweeteners
South America Stevia Market