
 Methyl Glucose Market | 2026-2036
Methyl Glucose Market Size, Share, and Industry Trends Forecast 2026-2036
Methyl Glucose Market Foresight
Aftermarket technical service revenue is narrowing as manufacturers bundle formulation support with bulk methyl glucose supply. Evonik Industries AG leverages its specialty surfactant heritage to anchor premium-grade methyl glucose production in Europe. Lubrizol sustains North American supply chain control through backward integration into alkoxylated polyol chemistry. KCI Limited competes on cost-efficient powder grades for Asian personal care compounders.
Methyl glucose denotes a class of alkyl polyglucosides synthesized from glucose methylation, typically yielding C1-C4 substituted pyranoside structures with HLB values spanning 13–16 for surfactant functionality. These compounds serve primarily as mild emulsifiers, humectants, and rheology modifiers in cosmetic and pharmaceutical formulations. Liquid methyl glucose derivatives lead volume consumption in rinse-off personal care applications where cold-process compatibility reduces energy input. Powder and granular grades attract pharmaceutical formulators seeking precise dosing control in solid dosage excipient systems. Crystalline variants command margin premiums from biotech firms demanding chiral purity for specialized synthesis pathways.
REACH registration requirements in Europe enforce full toxicological dossiers for cosmetic-grade methyl glucose imports, elevating compliance costs for non-European suppliers. FDA cosmetic ingredient regulations in the United States mandate substantiated safety data for methyl glucose sesquistearate used in leave-on skincare products. China's NMPA and GB standards for cosmetic raw materials impose additional microbial and heavy metal specifications on imported polyol surfactants. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether localized production or reformulation around alternative glucoside chemistries offers superior risk-adjusted returns.
Market Dynamics
REACH compliance in Europe is compressing supplier margins while simultaneously filtering out non-compliant imports, creating a bifurcation between certified European producers and reformulation-dependent compounders elsewhere.
Growth Catalysts
- Cold-process emulsion technology:Cosmetic manufacturers in South Korea and Japan adopt low-energy mixing protocols that favor liquid methyl glucose derivatives over traditional heat-dependent emulsifiers.
- China's GB standards for cosmetic raw materials:Domestic certification requirements accelerate substitution of imported surfactants with locally manufactured methyl glucose sesquistearate in rinse-off formulations.
- Biotech chiral synthesis demand:Pharmaceutical contract manufacturers specify crystalline methyl glucose for enantioselective catalysis, pulling high-purity grades into life sciences supply chains.
Market Restraints
- Glucose feedstock volatility:Corn and wheat price swings in Black Sea export corridors transmit directly into methyl glucose production economics, squeezing contract manufacturers with fixed-price agreements.
- Alkoxylation capacity concentration:Three German chemical parks control over half of European ethoxylation infrastructure for polyol surfactants, creating single-source vulnerability for derivative producers.
- Alkyl polyglucoside substitution:C8-C14 APG surfactants from coconut-derived feedstocks displace methyl glucose in budget shampoo formulations where mildness claims are deprioritized.
Strategic Opportunities
- Indian pharmaceutical excipient market:CDSCO's accelerated approval pathways for imported excipients create first-mover advantage for powder-grade methyl glucose suppliers targeting solid dosage formulators in Hyderabad and Ahmedabad clusters.
- EU Green Deal biobased mandates:Renewable carbon content thresholds in cosmetic formulations position methyl glucose derivatives favorably against petrochemical emulsifiers for premium skincare lines.
- Direct-to-compounder digital platforms:Specialty chemical distributors in Southeast Asia launch e-procurement portals that bypass traditional multi-tier distribution for mid-volume personal care manufacturers.
Industry Challenges
- Alkoxylation process engineering expertise:The specialized knowledge required for controlled ethoxylation of methyl glucose pyranosides resides with a shrinking cohort of European and Japanese process chemists approaching retirement.
- REACH dossier maintenance burden:Annual tonnage band updates and extended one-generation reproductive toxicity studies demand sustained toxicology investment that mid-tier importers struggle to amortize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Methyl Glucose Market |
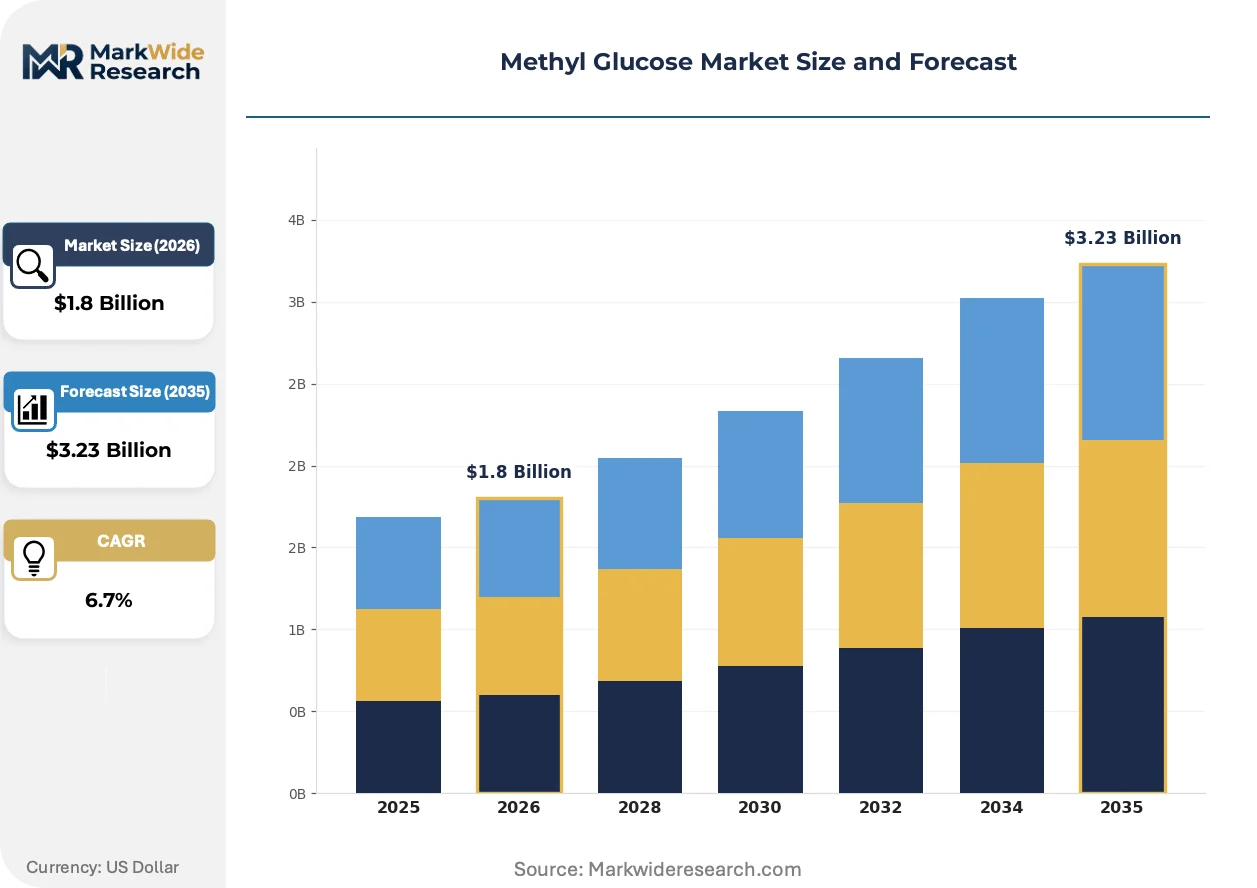
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granular, Crystalline Application: Food Industry, Personal Care, Pharmaceuticals, Industrial End User: Food Manufacturers, Cosmetic Companies, Healthcare Providers, Biotech Firms Distribution Channel: Online Retail, Direct Sales, Wholesalers, Distributors |
| Companies Covered | Reachin Chemical Co. Ltd., Lubrizol, KCI Limited, Kalichem, Hefei TNJ Chemical Industry Co. Ltd., ACAR Chemicals, Evonik Industries AG, Foshan Hytop New Material, NOF Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Methyl Glucose Market Shifts & Advancements
Formulation science and regulatory architecture are converging to reward surfactant architectures that combine biobased provenance with cold-process compatibility, reshaping R&D priorities across cosmetic and pharmaceutical verticals.
Enzymatic transglycosylation is hybridizing methyl glucose production with continuous flow reactor designs. Biocatalysis specialists in the Netherlands and Denmark deploy immobilized lipase systems that reduce solvent intensity and improve stereoselectivity over acid-catalyzed batch processes. Personal care compounders in Scandinavia specify enzyme-derived grades for Nordic Swan Ecolabel certification, compressing demand for conventional acid-catalyzed material.
REACH Annex XIV authorization requirements for residual ethylene oxide impurities are tightening analytical specifications for cosmetic-grade methyl glucose derivatives. ECHA's 2024 update to restricted substance lists forces reformulators to document sub-ppm ethoxylator carryover in leave-on skincare products. German and French contract manufacturers invest in dedicated supercritical CO2 extraction capacity to strip residual alkoxylator catalysts, passing compliance costs through to premium positioning.
Compounders increasingly bundle formulation technical service with raw material procurement rather than purchasing standalone methyl glucose supply. Personal care manufacturers in Brazil and Mexico source complete emulsion systems from distributors who provide stability testing and regulatory dossier support, displacing traditional spot-buying of commodity surfactants. This service integration is most advanced in Mercosur markets where ANVISA registration complexity favors full-service chemical distribution over transactional supply relationships.
Methyl Glucose Market Segmentation
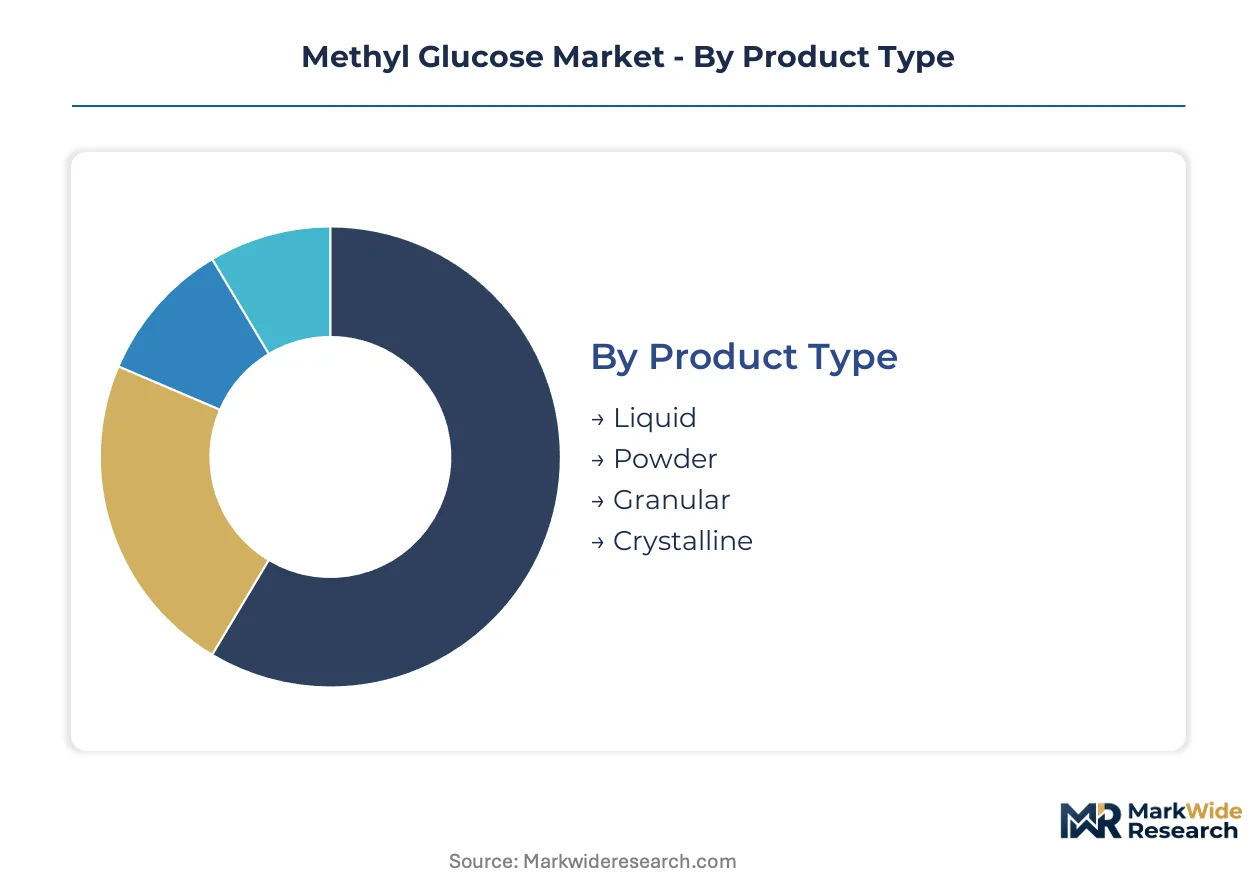
Methyl glucose derivatives exhibit divergent inventory velocities across physical forms, with liquid grades turning over rapidly in high-volume cosmetic compounding while crystalline variants sit in specialized pharmaceutical pipelines for months. Understanding these cycle-time differentials enables suppliers to calibrate working capital deployment and pricing structures against segment-specific demand patterns.
Product Type:
Liquid methyl glucose rotates through personal care supply chains fastest due to cold-process compatibility, whereas crystalline grades accumulate extended holding periods in biotech synthesis workflows.
- Liquid:Low-viscosity aqueous solutions with HLB values of 13–16 enable direct incorporation into cold-mix emulsions without heating stages. Rinse-off cosmetic manufacturers in South Korea and Japan favor this grade for energy-efficient production protocols that reduce facility overhead.
- Crystalline:High-purity chiral pyranoside structures meet enantioselective catalysis specifications for pharmaceutical contract manufacturers. Biotech firms in Basel and Boston pay substantial premiums for documented optical purity certificates that support regulatory filing packages.
- Powder:Free-flowing excipient grades serve solid dosage formulators seeking precise gravimetric dosing control in tablet compression operations.
- Granular:Intermediate particle sizes bridge powder handling convenience with liquid dissolution rates for hybrid manufacturing processes.
Liquid derivatives anchor the volume base while crystalline grades gain share at the steepest rate.
Application:
Cost tier stratification separates premium-positioned pharmaceutical applications from commodity-leaning industrial uses, with personal care occupying the contested middle ground where biobased claims command modest markups.
- Personal Care:Mild emulsifiers and humectants in skincare formulations leverage glucose-derived provenance for clean-label positioning. EU Green Deal biobased carbon thresholds favor methyl glucose sesquistearate over petrochemical alternatives in premium leave-on products subject to Nordic Swan and ECOCERT scrutiny.
- Pharmaceuticals:Excipient and active pharmaceutical ingredient intermediate applications demand full REACH dossiers and documented GMP compliance. Solid dosage manufacturers in Hyderabad and Ahmedabad clusters specify powder grades for immediate-release tablet matrices where compressibility and flow properties determine batch economics.
- Food Industry:Humectant and stabilizer functions in confectionery and bakery applications compete with established polyol chemistries on cost-per-function metrics.
- Industrial:Surfactant and dispersant uses in coatings and agrochemical formulations prioritize unit cost over regulatory certification depth.
Personal care applications generate the highest margin pool while pharmaceutical volumes climb fastest.
End User:
Customer type determines service intensity requirements, with biotech firms demanding extensive analytical documentation and food manufacturers accepting standardized certificates of analysis.
- Cosmetic Companies:Multinational skincare brands reformulate emulsion bases to incorporate methyl glucose derivatives for mildness claims and cold-process compatibility. Procurement teams bundle formulation technical service with raw material supply to accelerate stability testing and regulatory dossier preparation.
- Biotech Firms:Contract development and manufacturing organizations specify crystalline grades with chiral purity documentation for enantioselective synthesis pathways. These users absorb extended lead times and premium pricing in exchange for batch-to-batch consistency that protects high-value synthesis yields.
- Food Manufacturers:Industrial bakeries and confectionery processors source humectant grades through established food ingredient distributors with limited technical service expectations.
- Healthcare Providers:Hospital and clinic procurement of pharmaceutical-grade materials flows through specialized medical supply channels with distinct quality assurance protocols.
Cosmetic companies command the largest aggregate purchasing volume while biotech firms drive the most rapid specification escalation.
Distribution Channel:
Supply concentration varies sharply across channels, with direct sales relationships capturing the most sophisticated compounders and distributor networks serving fragmented mid-volume accounts.
- Direct Sales:Specialty chemical producers maintain technical service teams that co-develop emulsion formulations with major personal care manufacturers. These relationships lock in multi-year supply agreements with price-volume mechanisms that transfer glucose feedstock volatility risk.
- Distributors:Regional chemical distributors in Southeast Asia launch e-procurement portals that aggregate mid-volume compounders seeking smaller minimum order quantities than direct sales programs accommodate.
- Online Retail:Laboratory supply platforms serve research-scale biotech users with rapid fulfillment of gram-to-kilogram quantities for method development.
- Wholesalers:Traditional bulk chemical merchants handle commodity-grade powder and liquid volumes for industrial applications with limited formulation support requirements.
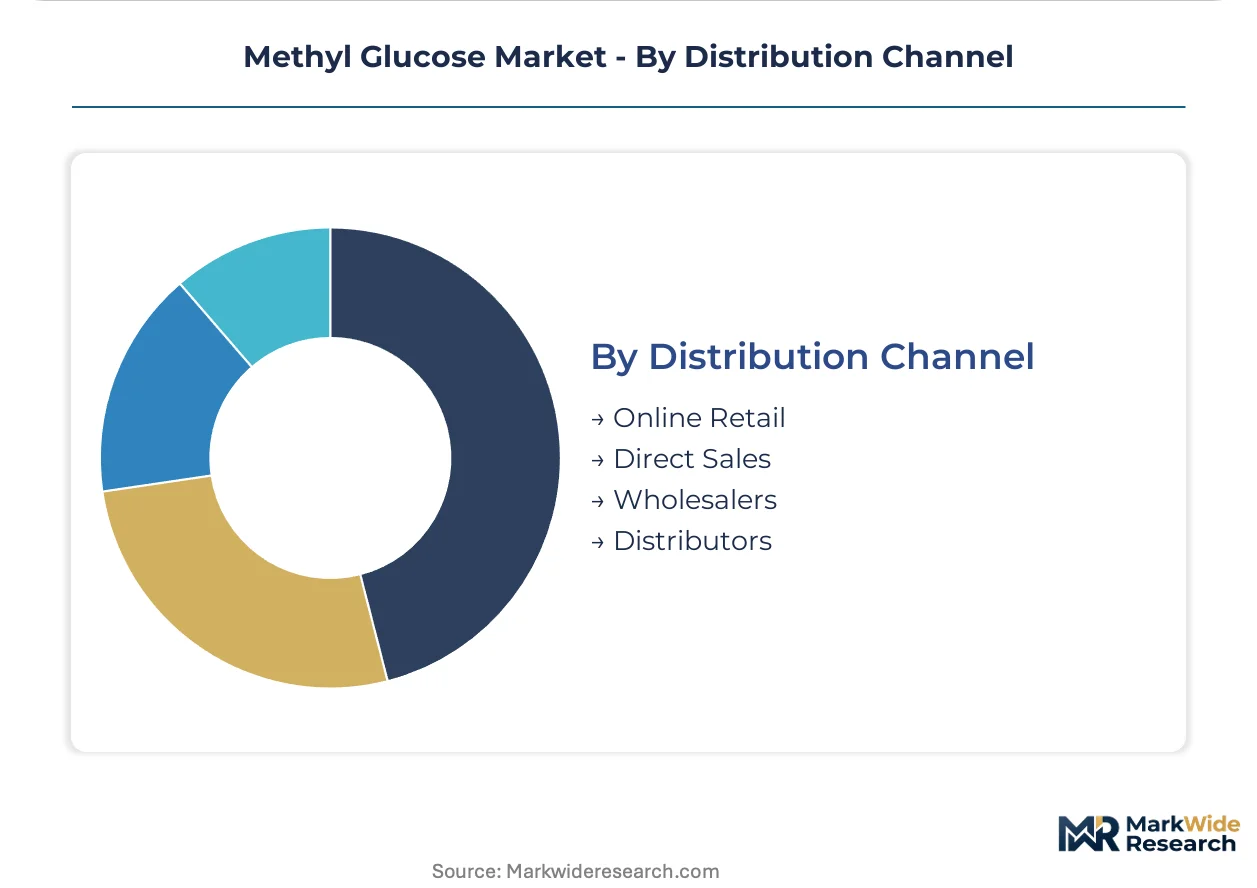
Direct sales relationships secure the deepest customer penetration while distributor digital platforms expand most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Southeast Asia exhibit acute price sensitivity, while pharmaceutical formulators in Switzerland and Japan absorb substantial premiums for chiral purity documentation. This elasticity gradient shapes supplier strategies across major demand centers.
China
Domestic surfactant manufacturers scale methyl glucose sesquistearate production for rinse-off cosmetics under NMPA and GB standards compliance. The Yangtze River Delta cluster around Shanghai hosts rapid capacity expansion as local compounders substitute imported polyol surfactants. Multinational skincare brands operating in China increasingly source from certified domestic producers to circumvent import documentation burdens.
Germany
REACH dossier maintenance and Annex XIV ethylene oxide specifications elevate compliance costs for cosmetic-grade derivatives. The country's national chemical regulator enforces sub-ppm residual alkoxylator thresholds that force investment in supercritical CO2 extraction capacity. Chemical parks in North Rhine-Westphalia concentrate European ethoxylation infrastructure, creating single-source vulnerability for derivative producers.
United States
FDA cosmetic ingredient regulations mandate substantiated safety data for methyl glucose sesquistearate in leave-on skincare formulations. Procurement teams at multinational personal care manufacturers bundle formulation technical service with raw material supply to accelerate stability testing. The New Jersey and California clusters anchor North American demand for premium emulsifier grades.
India
CDSCO accelerated approval pathways for imported excipients create first-mover opportunity for powder-grade suppliers targeting solid dosage formulators. The Hyderabad and Ahmedabad pharmaceutical clusters specify methyl glucose for immediate-release tablet matrices where compressibility determines batch economics. Domestic compounders prioritize cost-efficient grades over premium-certified alternatives.
Japan
METI and PMDA frameworks govern pharmaceutical-grade methyl glucose importation with stringent microbial and heavy metal specifications. Biotech firms in the Kanto region pay substantial premiums for crystalline grades with documented optical purity certificates. Cold-process emulsion technology adoption in Osaka-based cosmetic manufacturing favors liquid derivative specifications.
Methyl Glucose Market Competitive Landscape
Specialty surfactant heritage players and cost-efficient Asian producers split the market along a certification-premium axis. European manufacturers leverage REACH compliance depth to filter out non-compliant imports, while East Asian competitors scale powder and liquid grades for price-sensitive compounders. Three strategic archetypes dominate: backward-integrated chemical conglomerates with captive alkoxylation capacity, enzymatic biocatalysis specialists serving Nordic Swan certification demand, and regional distributors bundling formulation technical service with raw material supply. Capacity expansion and geographic certification acquisition represent the dominant competitive moves.
Within the heritage specialty tier, Evonik Industries AG exemplifies European producers anchoring premium-grade output through compliance depth. Lubrizol occupies a position representing North American supply chain control through upstream integration into alkoxylated polyol chemistry. KCI Limited sits within the cost-efficient Asian producer archetype, competing on powder grades for regional personal care compounders. These three entities collectively illustrate the geographic and strategic segmentation governing competitive positioning.
| Leading Market Players |
|---|
| Reachin Chemical Co. Ltd. |
| Lubrizol |
| KCI Limited |
| Kalichem |
| Hefei TNJ Chemical Industry Co. Ltd. |
| ACAR Chemicals |
| Evonik Industries AG |
| Foshan Hytop New Material |
| NOF Corporation |
| Others |
Supply & Pricing Matrix
Underutilized alkoxylation capacity in North Rhine-Westphalia chemical parks enables European producers to absorb REACH compliance costs through volume leverage, while Asian compounders exploit feedstock proximity to squeeze contract pricing for standard-grade methyl glucose derivatives. This utilization asymmetry bifurcates supplier behavior between premium-certified incumbents and cost-optimized challengers.
Pricing Analysis
Aftermarket technical service revenue now exceeds standalone product margins for liquid-grade suppliers serving multinational cosmetic manufacturers. Three-tier pricing structure across premium-certified, standard-compliant, and economy-ungraded levels separates Evonik's REACH-dossiered output from KCI Limited's powder grades for Asian compounders. Cost compression in economy tiers intensifies because glucose feedstock volatility from Black Sea export corridors transmits directly into fixed-price contract renegotiations. Indian pharmaceutical formulators exhibit acute price sensitivity for excipient grades, while Swiss biotech firms absorb substantial premiums for chiral purity documentation.
Supply Chain Analysis
Glucose feedstock availability from corn and wheat processing centers in the United States, Brazil, and Ukraine anchors methyl glucose production economics for derivative manufacturers. Controlled ethoxylation of methyl glucose pyranosides draws from ethylene oxide supply concentrated in German chemical parks, methanol streams from Middle Eastern producers, and specialized catalyst systems from Japanese suppliers. Single-source vulnerability pervades European ethoxylation infrastructure where three chemical parks control over half of regional capacity. Distribution runs through direct sales relationships for premium compounders and regional distributor networks for mid-volume personal care manufacturers in Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized process engineering expertise for alkoxylation reactor control is concentrated among a retiring cohort of European and Japanese chemists, creating a capability bottleneck that threatens supply continuity for high-purity grades. This scarcity dynamic rewards early movers who secure technical talent or alternative biocatalysis pathways.
For Market Incumbents: Harden compliance moats by investing in supercritical CO2 extraction capacity to meet ECHA's sub-ppm residual alkoxylator thresholds, and anchor backward integration into glucose feedstock processing to insulate margin structures from Black Sea commodity volatility. These moves defend against substitution pressure from coconut-derived C8-C14 alkyl polyglucosides in budget shampoo formulations.
For New Entrants and Emerging Players: Mid-market pharmaceutical excipient supply in India represents the most penetrable entry point, given CDSCO's accelerated approval pathways and Hyderabad-Ahmedabad cluster demand for powder-grade methyl glucose in immediate-release tablet matrices. Enzymatic biocatalysis production methods offer a go-to-market angle for Nordic Swan Ecolabel certification in Scandinavian personal care markets.
For Investors and Strategic Acquirers: Capital is best deployed toward enzymatic biocatalysis specialists with immobilized lipase capabilities and established Nordic Swan supply relationships, as these assets compound value through regulatory tailwinds and process chemistry differentiation. Watch for inflection signals in CDSCO approval velocity for imported excipients, which would validate Indian pharmaceutical demand scaling.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glucose Feedstock | Captive corn and wheat processing insulates margin structures from Black Sea export corridor volatility. |
| Enzymatic Biocatalysis Capacity Buildout | Immobilized lipase systems reduce solvent intensity and unlock Nordic Swan Ecolabel certification premiums. |
| Supercritical CO2 Extraction Investment | Strips residual ethoxylator catalysts to meet ECHA Annex XIV sub-ppm thresholds for leave-on skincare. |
| CDSCO Excipient Registration Acceleration | First-mover positioning in Hyderabad-Ahmedabad pharmaceutical clusters captures solid dosage formulator demand. |
| Direct-to-Compounder Digital Platform Launch | Southeast Asian e-procurement portals bypass multi-tier distribution for mid-volume personal care manufacturers. |
Research Methodology
A standing panel of plant managers at European alkoxylation facilities, procurement leads at multinational personal care OEMs, distribution channel partners in Southeast Asia, and technical R&D directors at enzymatic biocatalysis specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from ECHA restricted substance list updates, Cefic surfactant industry reports, customs and trade data for glucose derivative flows, and SEC filings from publicly traded chemical conglomerates. Bottom-up segment sizing triangulated against top-down market envelope estimates from feedstock consumption patterns.
Scenario-bracketing around regulatory stringency variations and feedstock price volatility bounds anchored the analytical framework across the projection horizon. Segmentation dimensions modeled included physical form grade tier, end-use industry vertical, regional production hub certification status, and chiral purity specification level. CAGRs were derived from elasticity-adjusted volume projections and value-per-ton trajectories by grade tier. Industry-specific forecast inputs encompassed NMPA domestic substitution rates in China and CDSCO approval pathway velocity for imported excipients.
Practitioners should monitor ECHA dossier maintenance burden signals and enzymatic biocatalysis patent filing velocity for early indicators of competitive positioning shifts. Forecasts reflect assumptions around REACH compliance cost pass-through rates and glucose feedstock price normalization patterns. Cross-checking against Cefic surfactant production statistics and NMPA cosmetic raw material registration databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
India Cane Sugar Market
Sweeteners
India Food Sweetener Market
Sweeteners
High-Intensity Sweeteners Market
Sweeteners
Allulose Powder Market
Sweeteners
Gluten-Free Sugar Syrup Market
Sweeteners
North America Food Sweetener Market
Sweeteners
White Sugar Market
Sweeteners
Fructose Market
Sweeteners
Liquid Sugar Market
Sweeteners
Palm Sugar Market
Sweeteners
Caramelized Sugars Market
Sweeteners
Europe Natural Sweetener Market
Sweeteners
France Food Sweetener Market
Sweeteners
Global Low Intensity Sweeteners Market
Sweeteners
Sugar Polyols Market
Sweeteners
South Africa Food Sweetener Market