
 Asia-Pacific Stevia Market | 2026-2036
Asia-Pacific Stevia Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Stevia Market Analysis
Beverage formulation is consolidating around stevia as the dominant natural sugar replacement across Asia-Pacific bottling operations. PureCircle extends its extraction technology leadership through proprietary bioconversion processes for rare steviol glycosides. Cargill, Incorporated leverages its regional supply chain infrastructure to anchor bulk stevia distribution across ASEAN manufacturing hubs. Hunan Huacheng Biotech, Inc. dominates Chinese domestic cultivation with integrated leaf processing capabilities spanning Hunan province.
Stevia comprises sweet-tasting diterpene glycosides extracted primarily from Stevia rebaudiana leaves, with rebaudioside A and stevioside constituting the principal commercial compounds measured by purity percentage and sensory profile. The plant-derived sweetener delivers zero-calorie functionality for food and beverage applications requiring clean-label positioning. Stevia extract commands premium positioning among product type segments due to higher concentration thresholds and cleaner taste profiles compared to commodity powdered formats. Liquid stevia competes aggressively in beverage manufacturing channels where dissolution speed and batch consistency determine procurement decisions. Confectionery end users sustain specialized demand for granulated form factors that maintain crystalline structure in chocolate and hard candy production.
China's SAMR maintains evolving food additive standards under GB 2760 that specify permitted steviol glycoside categories and maximum usage levels across 14 food categories. India's FSSAI stevia notification under the Food Safety and Standards Regulations governs import purity requirements and domestic labeling protocols for tabletop and processed applications. Japan's Ministry of Health, Labour and Welfare operates a positive list system where stevia-derived additives require pre-market approval with specified specifications. Stakeholders must monitor pending glycoside specification expansions and evolving maximum permitted levels across national food codes to anticipate reformulation windows and procurement contract structures.
Market Dynamics
Sugar taxation regimes across Southeast Asian economies are compressing formulation windows for beverage manufacturers, forcing rapid stevia integration into existing production lines without full sensory optimization cycles.
Growth Catalysts
- China's SAMR glycoside expansion:Additional steviol glycoside specifications under GB 2760 are accelerating product registration timelines for reduced-sugar carbonated drinks.
- Urban processed food demand:India's FSSAI stevia notification governs import purity requirements, enabling tabletop sweetener penetration among metro consumers.
- Bioconversion technology maturation:Rare steviol glycoside extraction processes are unlocking cleaner taste profiles that displace bitter aftertaste in high-concentration applications.
Market Restraints
- Leaf supply concentration:Hunan province cultivation clusters create geographic vulnerability to climate-driven yield volatility.
- Sensory masking costs:Erythritol and monk fruit blends required for taste optimization inflate per-unit formulation expenses versus standalone stevia.
- Japan's positive list friction:Ministry of Health, Labour and Welfare pre-market approval requirements delay new glycoside introduction by 18-24 months.
Strategic Opportunities
- Vietnam and Indonesia underpenetration:Bottling operations in these markets lack technical stevia formulation expertise, creating first-mover service revenue potential.
- Confectionery crystalline demand:Granulated form factors for chocolate and hard candy production remain underserved versus liquid and extract formats.
- ASEAN harmonization momentum:Regional regulatory alignment initiatives could streamline multi-country product registration for multinational food manufacturers.
Industry Challenges
- Flavor chemist scarcity:Asia-Pacific food science programs produce insufficient specialists trained in stevia-sugar hybrid optimization.
- Batch consistency protocols:Dissolution speed variability between leaf harvests forces continuous recalibration of beverage manufacturing parameters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Stevia Market |
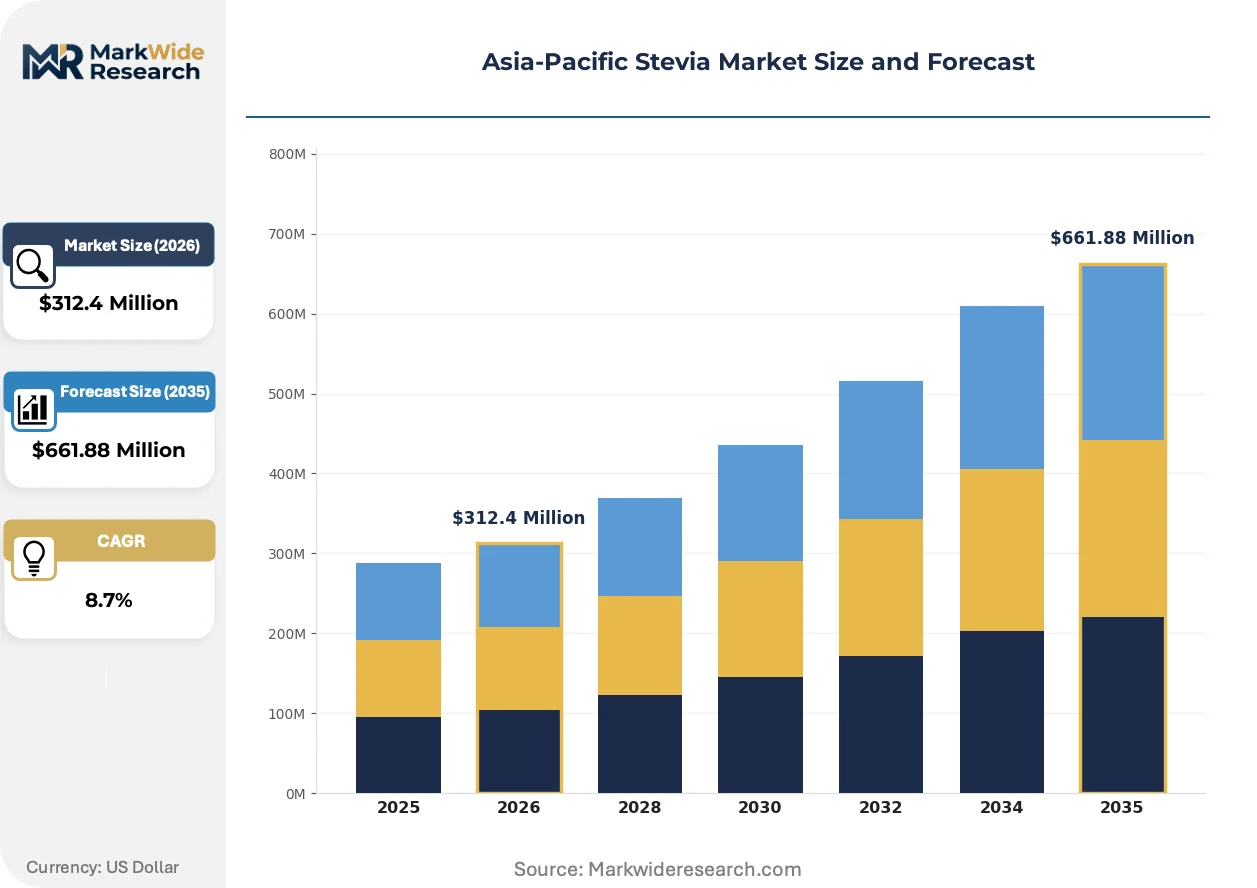
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stevia Extract, Liquid Stevia, Powdered Stevia, Blended Sweeteners End User: Beverages, Dairy Products, Bakery, Confectionery Form: Granulated, Liquid, Packets, Bulk Distribution Channel: Supermarkets, Online Retail, Health Stores, Food Service |
| Companies Covered | Cargill, Incorporated, Tate & Lyle PLC, Ingredion Incorporated, Archer Daniels Midland Company, PureCircle, Hunan Huacheng Biotech, Inc., GLG Life Tech Corp, Layn Corp., Sunwin Stevia International Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Stevia Market Emerging Trajectories
Enzymatic bioconversion and fermentation-based glycoside production are compressing traditional agricultural dependency, while regulatory specification expansions and procurement model evolution reshape competitive positioning across formulation channels.
Fermentation-derived steviol glycoside production is decentralizing supply chain control away from leaf cultivation geographies. Biotechnology firms in Singapore and South Korea are scaling precision fermentation platforms that bypass agricultural growing seasons. This technology is decentralizing raw material sourcing from Hunan and Paraguay toward distributed bioreactor networks.
China's SAMR maintains evolving GB 2760 standards that specify permitted steviol glycoside categories across 14 food categories. These specifications force multinational beverage manufacturers to maintain parallel formulation portfolios for domestic versus export production. Carbonated drink producers are responding by segregating China-bound product lines with dedicated glycoside blends.
Direct procurement contracts between extractors and bottling operations are displacing traditional ingredient distributor intermediaries. ASEAN beverage manufacturers now negotiate volume commitments with Hunan processors for rare glycoside supply security. This pattern concentrates most visibly in Thailand's ready-to-drink tea segment where dissolution speed requirements favor dedicated supply relationships over spot market purchasing.
Asia-Pacific Stevia Market Segmentation
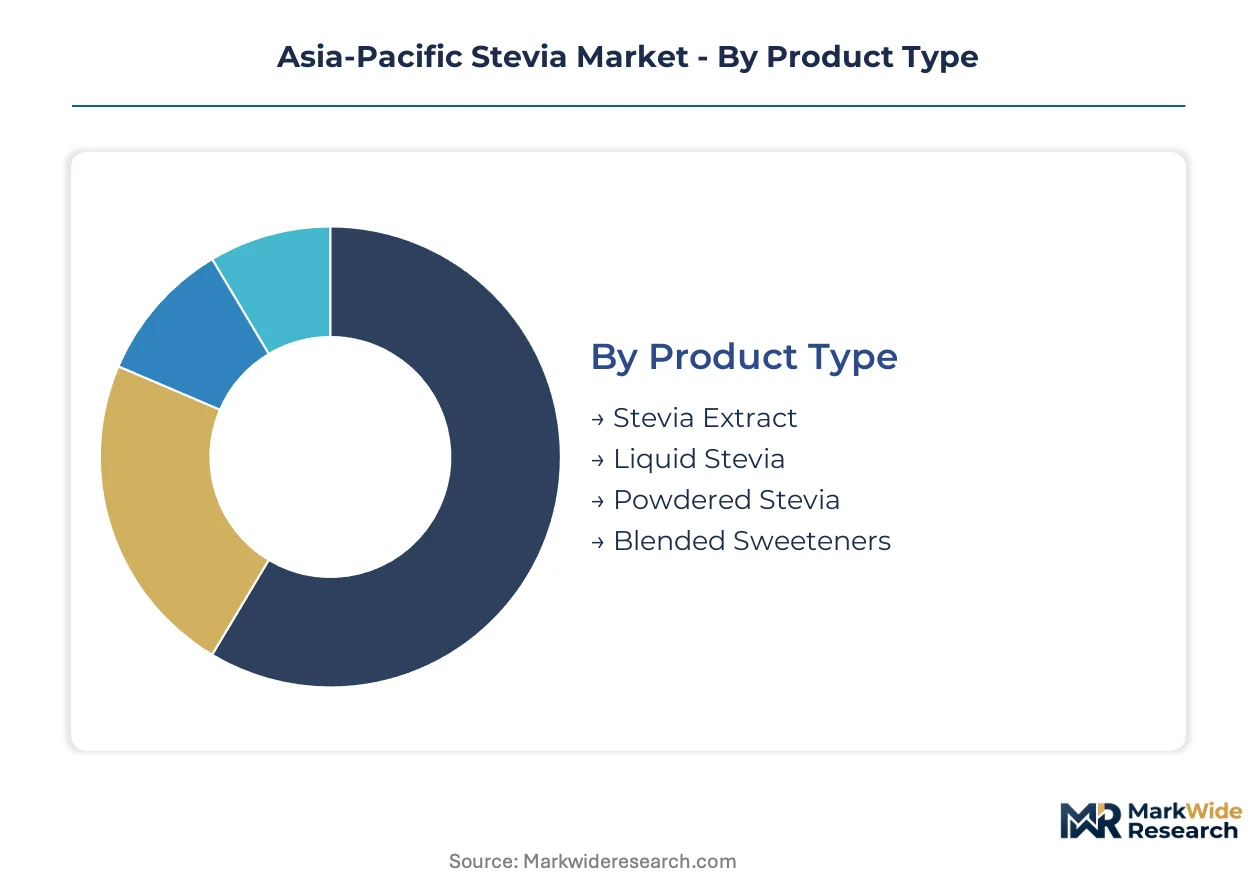
Stevia market segmentation in Asia-Pacific reflects divergent technical requirements across extraction methods, formulation chemistry, and procurement channels. Manufacturers optimize procurement decisions around dissolution speed, purity thresholds, and regulatory compliance across national food codes.
Product Type:
Extraction technology and glycoside concentration define competitive positioning across stevia formats.
- Stevia Extract:High-purity rebaudioside A and steviol glycoside concentrates deliver zero-calorie functionality for clean-label positioning. Beverage manufacturers in Thailand's ready-to-drink tea segment prioritize extract grades for batch consistency and rapid dissolution.
- Liquid Stevia:Pre-dissolved glycoside solutions eliminate hydration variability in high-speed bottling operations. China's carbonated drink producers favor liquid formats for reduced-sugar reformulation under SAMR's evolving GB 2760 standards.
- Powdered Stevia:Commodity-grade leaf-derived powders serve cost-sensitive tabletop applications across Indian metro households.
- Blended Sweeteners:Erythritol and monk fruit combinations mask bitter aftertaste in high-concentration confectionery applications.
Stevia extract leads on scale; liquid stevia climbs the fastest as bottling operations accelerate formulation integration.
End User:
Application-specific sensory requirements drive glycoside selection and supplier relationships.
- Beverages:Carbonated drinks and ready-to-drink teas dominate procurement volumes across ASEAN manufacturing hubs. Dissolution speed requirements favor dedicated supply contracts over spot purchasing in Thailand and Vietnam.
- Confectionery:Chocolate and hard candy production demands granulated form factors that maintain crystalline structure under thermal processing.
- Dairy Products:Yogurt and flavored milk applications require glycoside stability across pH ranges and refrigerated shelf life.
- Bakery:Heat-stable steviol glycoside specifications support reduced-sugar bread and pastry formulations in urban Chinese markets.
Beverages anchor volume procurement; confectionery commands premium positioning through specialized form factor requirements.
Form:
Physical presentation determines handling economics and end-use accessibility across consumer and industrial channels.
- Liquid:Industrial-scale totes and drums serve beverage manufacturing with metered dosing precision. ASEAN bottling operations specify liquid for dissolution speed consistency.
- Granulated:Crystalline structures replicate sugar mouthfeel in chocolate production and tabletop sweetener applications across Japanese retail.
- Packets:Single-serve sachets dominate food service and hospitality channels throughout Southeast Asian urban centers.
- Bulk:Food manufacturers in India procure unpackaged powder for in-house blending and private-label tabletop products.
Liquid form dominates industrial procurement; granulated formats gain share fastest through confectionery demand expansion.
Distribution Channel:
Channel selection reflects customer scale, technical service requirements, and regulatory documentation needs.
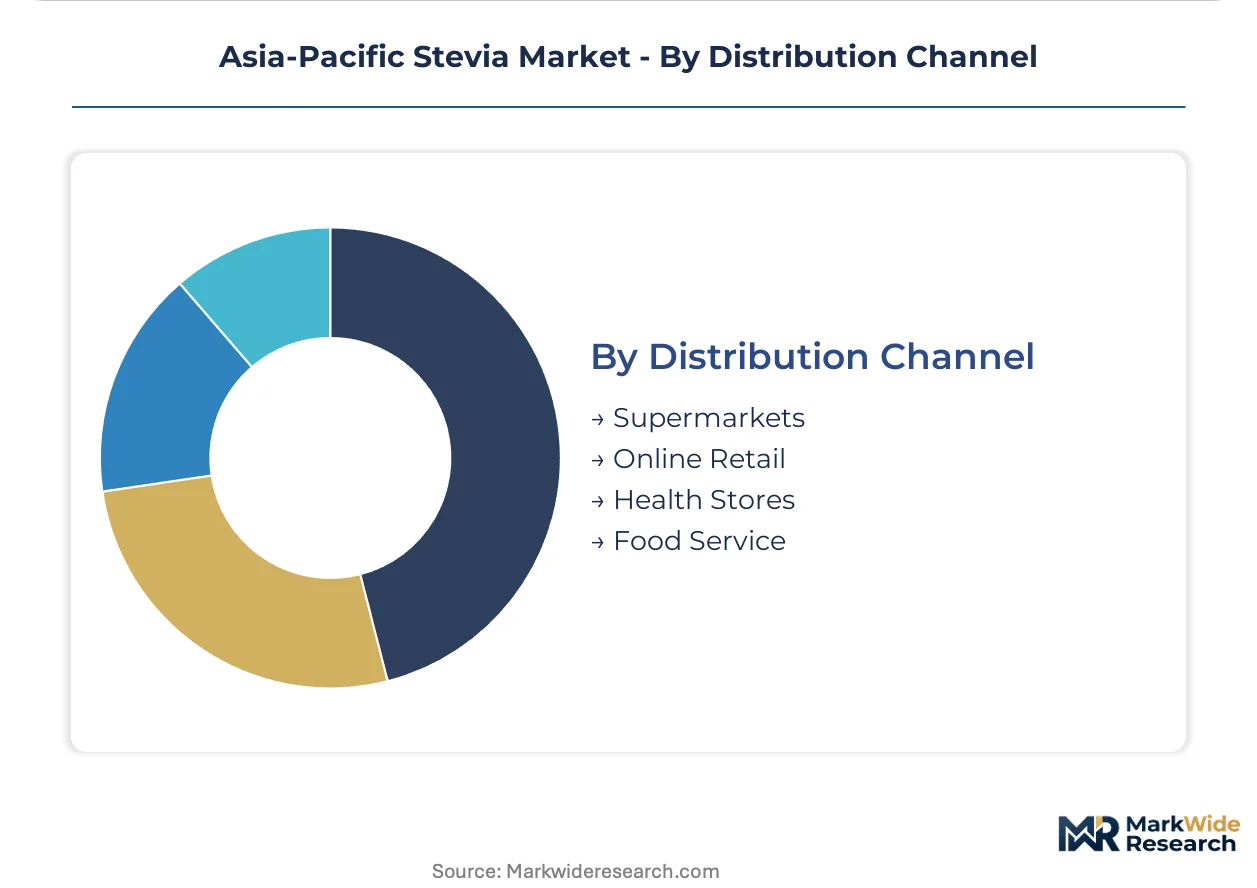
- Food Service:Direct procurement contracts between extractors and bottling operations displace traditional distributors in Thailand's ready-to-drink tea segment. Volume commitments secure rare glycoside supply security.
- Supermarkets:Mass retail placement of tabletop sweeteners concentrates in Chinese and Indian urban markets amid tightening sugar taxation.
- Online Retail:E-commerce platforms enable specialty glycoside access for small-batch confectioners and health-conscious consumers across Indonesia.
- Health Stores:Premium positioning of organic and non-GMO certified stevia serves niche demand in Australian and Japanese markets.
Food service leads on contract value; online retail expands most quickly through underpenetrated Southeast Asian markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hunan province cultivation clusters anchor regional supply security for Asia-Pacific stevia processors. Urban processed food demand across Southeast Asian metros is compressing formulation timelines for natural sweetener integration. National regulatory divergence under China's SAMR, India's FSSAI, and Japan's MHLW is fragmenting compliance architectures.
China
Carbonated drink manufacturers in Shanghai and Guangzhou are accelerating reduced-sugar reformulation ahead of provincial sugar taxation expansion. SAMR's evolving GB 2760 standards specify permitted steviol glycoside categories across 14 food categories, forcing parallel domestic and export formulation portfolios. Hunan province's integrated leaf processing capabilities dominate upstream supply, with Zhumadian and Changsha clusters handling extraction and purification.
India
Metro households in Mumbai and Delhi are driving tabletop sweetener penetration amid tightening state-level sugar levies. FSSAI stevia notifications govern import purity requirements and domestic labeling protocols for processed applications. Gujarat and Maharashtra food manufacturers are expanding private-label stevia procurement for bakery and dairy reformulation.
Japan
Confectionery producers in Osaka and Nagoya are demanding granulated form factors that maintain crystalline structure under thermal processing. MHLW's positive list system requires pre-market approval for new glycoside specifications, delaying introduction by 18-24 months. Tokyo-based retail channels sustain premium positioning for organic-certified stevia variants.
Thailand
Ready-to-drink tea bottlers in Bangkok and Pathum Thani are negotiating direct procurement contracts with extractors for rare glycoside supply security. Dissolution speed requirements favor dedicated supply relationships over spot market purchasing. Samut Sakhon industrial estates concentrate beverage manufacturing infrastructure requiring metered liquid stevia dosing precision.
Vietnam
Ho Chi Minh City and Hanoi bottling operations lack technical stevia formulation expertise, creating first-mover service revenue potential for ingredient suppliers. Provincial food safety departments are aligning domestic additive standards with ASEAN harmonization initiatives. Dong Nai province manufacturing zones are attracting regional sweetener distributors establishing technical service capabilities.
Asia-Pacific Stevia Market Vendor Landscape
Capacity expansion dominates the current landscape as extraction technology maturation compresses agricultural dependency. The vendor base stratifies across three tiers: multinational ingredient conglomerates with regional distribution infrastructure, Chinese domestic cultivators with integrated processing capabilities, and biotechnology specialists scaling fermentation platforms. Strategic archetypes include agricultural-integrated extractors, fermentation-based technology disruptors, and formulation service providers. M&A activity concentrates on rare glycoside patent portfolios, while vertical integration into leaf cultivation secures supply continuity against climate volatility.
Among multinational ingredient suppliers, Cargill, Incorporated and Tate & Lyle PLC occupy positions anchored by ASEAN manufacturing hub distribution networks. Within the Chinese domestic tier, Hunan Huacheng Biotech, Inc. exemplifies agricultural-integrated extraction with provincial cultivation control. PureCircle represents the technology-specialist archetype through proprietary bioconversion capabilities for rare steviol glycosides. These three entities collectively illustrate competitive positioning across scale-driven, geography-captive, and innovation-led vectors.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Tate & Lyle PLC |
| Ingredion Incorporated |
| Archer Daniels Midland Company |
| PureCircle |
| Hunan Huacheng Biotech, Inc. |
| GLG Life Tech Corp |
| Layn Corp. |
| Sunwin Stevia International Inc. |
| Others |
Supply Flow & Price Mechanics
Flavor chemist concentration in Thailand's Samut Sakhon industrial corridor creates labor-cost differentials that widen pricing spreads between premium glycoside formulations and commodity stevia extracts.
Pricing Analysis
Input-cost pass-through from Hunan province leaf harvests determines contract pricing for rare steviol glycoside supply agreements. Three-tier pricing structure across premium, standard, and economy levels separates bioconversion-derived Reb M from conventional Reb A extracts and commodity leaf powders. Pricing pressure stems from erythritol blending requirements for taste optimization in high-concentration applications. Beverage manufacturers in Vietnam exhibit highest price sensitivity due to technical formulation gaps, while Japanese confectionery producers accept premium positioning for crystalline granulated formats.
Supply Chain Analysis
Certification under China's GB 2760 and Japan's MHLW positive list gates market access for glycoside specifications across Asia-Pacific bottling operations. Raw material sourcing draws from Hunan province cultivation clusters, Paraguay leaf imports, and Singapore fermentation bioreactors. Supply chain risk centers on climate-driven yield volatility in concentrated Hunan growing regions. Distribution runs through direct procurement contracts between extractors and ASEAN beverage manufacturers, displacing traditional ingredient distributor intermediaries in Thailand's ready-to-drink tea segment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific stevia demand is maturing toward premium specifications as Japanese confectionery producers and Chinese carbonated drink manufacturers prioritize rare glycoside purity over commodity leaf-derived alternatives.
For Market Incumbents: Acquire rare glycoside patent portfolios to consolidate extraction technology leadership against fermentation-based disruptors. Secure backward integration into Hunan province cultivation through equity stakes in provincial processing clusters. Expand technical service capabilities in Vietnam's Dong Nai manufacturing zones to preempt formulation expertise gaps from emerging entrants. For New Entrants and Emerging Players: Enter via white-label formulation services for Vietnam and Indonesia bottling operations lacking stevia integration expertise. Target Indonesia's underpenetrated ready-to-drink tea segment through dissolved glycoside solutions that eliminate hydration variability. Build go-to-market positioning around ASEAN regulatory harmonization momentum for multi-country product registration efficiency. For Investors and Strategic Acquirers: Multinational ingredient conglomerates are the most active acquirer in this space, consolidating fermentation technology platforms and rare glycoside extraction capabilities. Long-term viability rests on biotechnology patent moats rather than agricultural land control. Watch for SAMR glycoside specification expansions as inflection indicators for reformulation-driven procurement surges.| Strategic Initiative | Industry Significance |
|---|---|
| Rare Glycoside Patent Acquisition | Bioconversion capabilities for Reb M and Reb D unlock premium pricing in Japanese confectionery channels. |
| Fermentation Platform Scale-Up | Singapore and South Korean bioreactor networks reduce dependency on Hunan province climate cycles. |
| Direct Procurement Contracting | Volume commitments with ASEAN bottlers secure dissolution-speed-consistent supply for ready-to-drink tea. |
| Technical Service Expansion | Formulation expertise deployment in Vietnam addresses capability scarcity among Ho Chi Minh City bottlers. |
| Regulatory Harmonization Lobbying | ASEAN alignment initiatives streamline multi-country GB 2760 and FSSAI compliance for multinational manufacturers. |
Methodological Framework
Multiple input streams — regulatory filing analysis, customs and trade flow data, and primary stakeholder interviews — were reconciled to construct market estimates across the Asia-Pacific stevia value chain. Beverage formulation chemists, FSSAI compliance officers, Hunan province leaf processors, and ASEAN bottling procurement managers provided operational validation. Secondary sources included SAMR GB 2760 amendment notices, Japan MHLW positive list updates, Thai FDA additive registrations, and trade databases tracking glycoside import volumes. Bottom-up procurement modeling and top-down sweetener substitution trend analysis were cross-validated.
Data-stream reconciliation across extraction technology maturation curves, regulatory approval timelines, and end-use substitution elasticities informed the analytical framework. Segmentation dimensions modeled encompass product type, end-use application, physical form, and distribution channel, with additional granularity on national food code compliance clusters. CAGRs were derived from glycoside specification expansion trajectories and processed food manufacturer reformulation commitments. Forecast inputs incorporated sugar taxation regime tightening schedules and urban household tabletop sweetener penetration patterns.
Inputs from SAMR and MHLW regulatory filings were available through the study window; gaps in provincial-level cultivation yield data introduce uncertainty bands around Hunan supply projections. Forecasts reflect assumptions on bioconversion technology cost curves and ASEAN harmonization implementation pace. A model refresh is warranted upon material change in China's GB 2760 glycoside category expansions or Japan's positive list approval timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Africa and Middle East Sugarcane Syrup Market
Sweeteners
China Allulose Market
Sweeteners
United States Xylitol Market
Sweeteners
Natural Sweeteners Market
Sweeteners
Global Low Intensity Sweeteners Market
Sweeteners
Clarified Rice Syrup Market
Sweeteners
Glucose-Fructose Syrup (GFS) Market
Sweeteners
Oligofructose Market
Sweeteners
China Saccharin Market
Sweeteners
Glucose Syrup Market
Sweeteners
Rice Syrup Market
Sweeteners
Organic Palm Sugar Market
Sweeteners
Europe Stevia Market
Sweeteners
D Psicose Market
Sweeteners
Mexico Food Sweetener Market
Sweeteners
Japan Food Sweetener Market