
 Global Polybenzimidazoles (PBI) Market | 2026-2036
Global Polybenzimidazoles (PBI) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polybenzimidazoles (PBI) Market Foresight
Aftermarket service revenue for PBI component refurbishment is reshaping margin distribution across the value chain. PBI Performance Products, Inc. dominates North American resin supply through captive polymerization capacity. Mitsubishi Chemical Advanced Materials leverages its Asian manufacturing footprint to anchor regional fiber distribution. Solvay specializes in aerospace-grade formulations that command premium positioning among defense contractors.
Polybenzimidazoles constitute a class of heterocyclic aromatic polymers synthesized through condensation of tetraaminobiphenyl and diphenyl isophthalate, exhibiting continuous service temperatures exceeding 400°C and inherent flame resistance with limiting oxygen indices above 40%. These thermal and chemical stability properties position PBI materials for extreme-environment applications including jet engine insulation, firefighter protective barriers, and proton exchange membrane substrates. The resin segment leads value generation due to downstream formulation flexibility across coating and composite intermediates, while fiber applications in protective gear sustain the fastest volume trajectory driven by defense procurement cycles. Membrane applications for electrochemical devices represent an emerging margin pool as hydrogen infrastructure scales.
The EPA governs emissions standards affecting PBI manufacturing facilities in the United States, while REACH and RoHS frameworks in Europe restrict hazardous substance content in polymer formulations destined for electronics and automotive supply chains. The EU F-Gas Regulation indirectly elevates PBI relevance by constraining conventional fluoropolymer alternatives in sealing and insulation roles. Stakeholders must monitor evolving chemical substance restrictions across multiple jurisdictions and assess backward integration into monomer supply as a strategic hedge against feedstock volatility.
Market Dynamics
Jet engine OEMs are consolidating thermal barrier specifications around single-supplier PBI resin platforms, compressing formulation diversity while amplifying volume commitments to qualified polymerization facilities.
Growth Catalysts
- REACH and RoHS frameworks:European electronics and automotive supply chains face hazardous substance restrictions that disqualify conventional fluoropolymer alternatives, redirecting specification engineers toward PBI formulations for high-temperature insulation.
- Defense procurement cycles:Military protective gear programs in the United States and Germany are accelerating fiber volume commitments for firefighter and combat apparel, creating sustained offtake agreements with spinners.
- Hydrogen infrastructure scaling:Proton exchange membrane developers are qualifying PBI substrates for electrolyzer and fuel cell stacks, opening membrane-grade resin demand from electrochemical device manufacturers.
Market Restraints
- Tetraaminobiphenyl feedstock volatility:The specialized diamine monomer relies on limited aromatic chemical production clusters, exposing resin converters to input cost swings without viable substitute chemistry.
- Polymerization capacity concentration:Captive resin production in North American and German chemical parks creates supply vulnerability for Asian compounders lacking backward integration into monomer supply.
- Processing temperature thresholds:PBI's extreme melt viscosity demands specialized extrusion and compression molding equipment, restricting fabrication to toll processors with capital-intensive thermal processing lines.
Strategic Opportunities
- India's specialty chemicals expansion:Government production-linked incentive schemes for advanced materials are attracting PBI compounders to establish formulation facilities serving domestic aerospace and defense contractors.
- Membrane-electrode assembly convergence:Integration of PBI substrates with catalyst-coated membranes is enabling next-generation electrolyzer designs that compress stack size while elevating operating temperature windows.
- EU F-Gas Regulation phase-down:Accelerated restriction of hydrofluorocarbon blowing agents and sealants is forcing HVAC and refrigeration OEMs to specify PBI foams and gaskets in equipment redesigns.
Industry Challenges
- High-temperature polymer processing expertise:The limited population of technicians trained in PBI rheology and thermal stabilization creates bottlenecks for capacity expansion at compounder facilities.
- Aerospace material qualification timelines:FAA and EASA certification protocols for jet engine components demand multi-year thermal cycling and flame-resistance validation, compressing revenue realization for new resin grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polybenzimidazoles (PBI) Market |
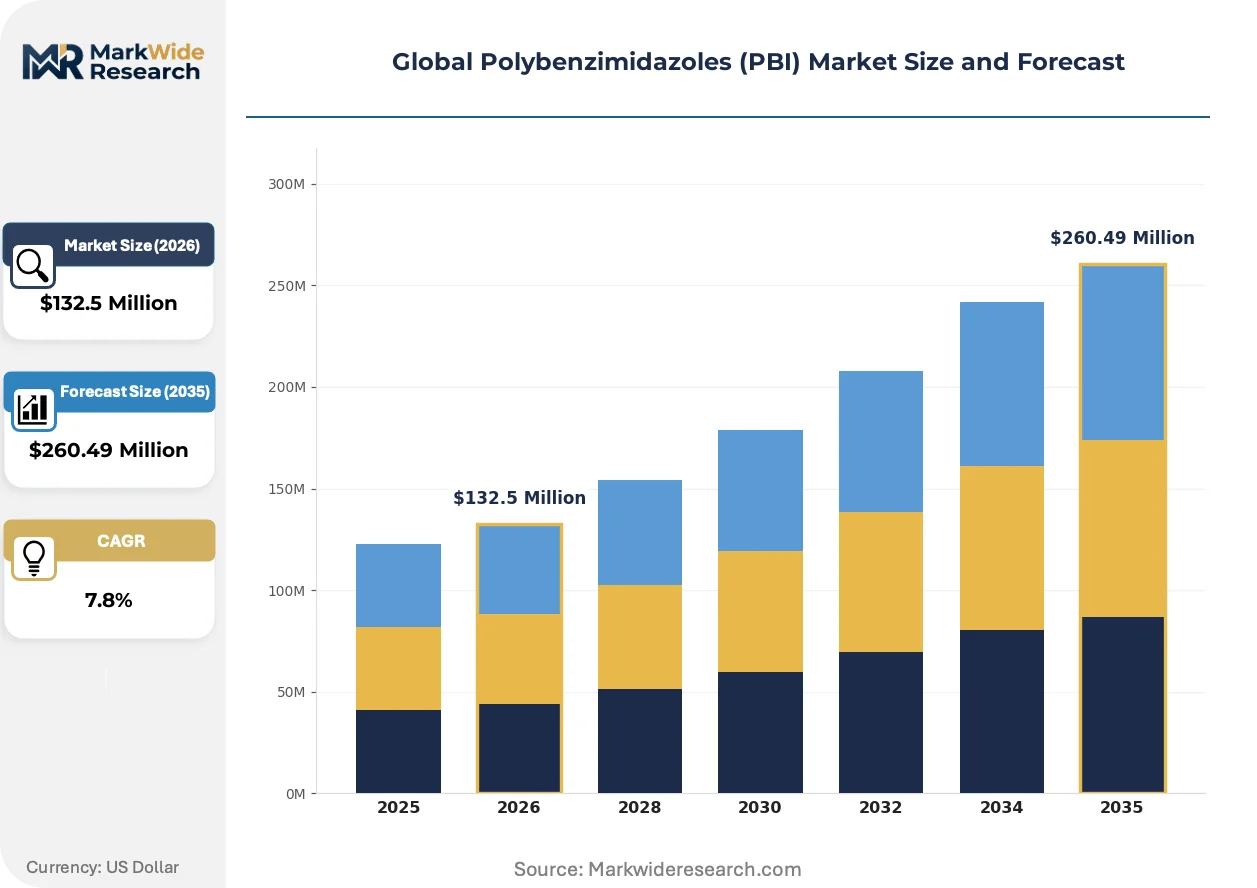
| Market Size in 2026 | $132.5 Million |
| Market Size in 2035 | $260.49 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber, Resin, Film, Coating, Composite Application: Aerospace Components, Protective Gear, Membranes, Electronics, Automotive Parts End User Industry: Defense Contractors, Electronics Manufacturers, Chemical Processing, Power Generation, Textiles Form: Powder, Pellet, Sheet, Granule, Rod |
| Companies Covered | PBI Performance Products, Inc., Mitsubishi Chemical Advanced Materials, Polymics, Ltd., Bally Ribbon Mills, Atkins & Pearce, Celanese Corporation, Solvay, Gharda Chemicals Ltd., HOS Technik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polybenzimidazoles (PBI) Market Shifts & Advancements
Formulation chemistry is pivoting toward membrane-grade purity standards while fiber spinning technology advances denier control for protective apparel. These technical trajectories are reshaping capital allocation across polymerization, compounding, and fabrication stages.
Solvent-cast PBI membrane technology is migrating from laboratory-scale electrochemical research toward commercial electrolyzer manufacturing. Hydrogen equipment builders in Germany and Japan are qualifying these substrates for 80°C-plus operating environments. This migration is compressing the competitive window for perfluorinated sulfonic acid membranes in heavy-duty fuel cell applications.
The EU F-Gas Regulation's accelerated phase-down schedule is forcing refrigeration OEMs to abandon hydrofluorocarbon insulation foams by 2030. Equipment redesigns in Germany and France are specifying PBI-based thermal barriers for commercial cold-chain infrastructure. Compressor manufacturers are responding by pre-qualifying resin formulations that maintain performance across expanded temperature differentials.
Aftermarket refurbishment contracts are unbundling from original component sales in aerospace thermal protection systems. MRO providers in the United States and United Kingdom are negotiating standalone service agreements for PBI insulation blanket inspection and replacement. This unbundling is visible most acutely in narrow-body engine programs where fleet utilization rates drive compressed turnaround schedules.
Global Polybenzimidazoles (PBI) Market Segmentation
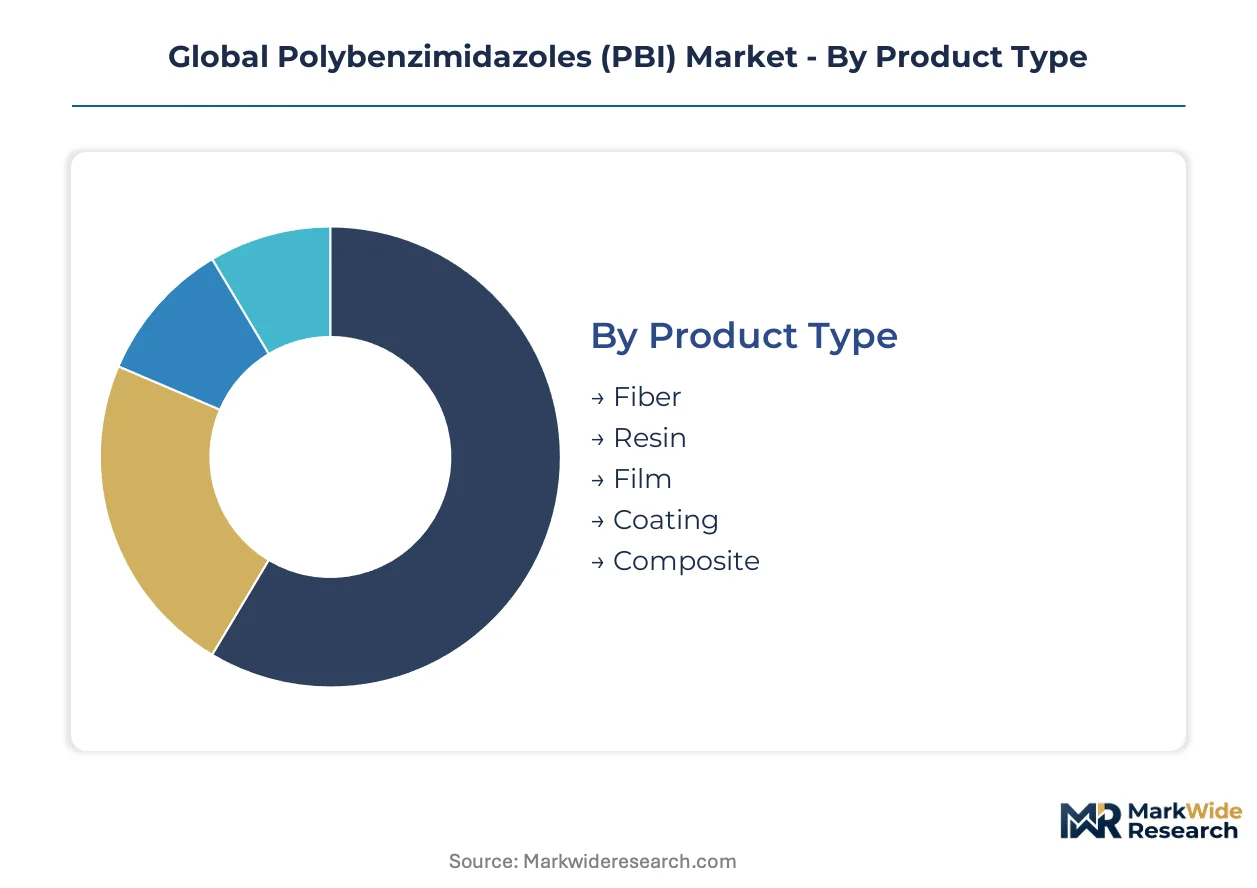
PBI materials fragment across distinct physical forms and end-use specifications that dictate polymerization chemistry, processing equipment, and qualification protocols. Each segment commands specialized supply chain configurations from monomer sourcing through fabrication.
Product Type:
Fiber, resin, film, coating, and composite formats span protective apparel, thermal barriers, electrochemical substrates, and structural components with divergent purity and viscosity requirements.
- Fiber:Continuous filament and staple forms spun from high-molecular-weight polymer solutions exhibit denier control critical for firefighter turnout gear and combat apparel. Defense procurement cycles in Germany and the United States sustain volume commitments to qualified spinners with FAA-EASA dual certification.
- Resin:Powder and pellet intermediates enable downstream formulation flexibility across coating systems, composite matrices, and membrane casting solutions. Jet engine OEMs in the United States consolidate thermal barrier specifications around single-supplier resin platforms, compressing formulation diversity while amplifying volume commitments.
- Film:Solvent-cast and extruded sheet formats serve gasketing and electrical insulation applications with thickness tolerances down to 25 microns. Electronics manufacturers in Japan qualify film grades for flexible circuit substrates under JIS standards.
- Coating:Dispersion and powder formulations provide corrosion protection and thermal resistance for chemical processing equipment. Application requires specialized spray systems handling extreme viscosity.
- Composite:Prepregs and molding compounds integrate PBI resin with carbon or glass fiber reinforcements for aerospace structural components. Qualification timelines extend across multi-year thermal cycling protocols.
Established volume favors resin; emerging adoption favors fiber.
Application:
Cost tiers stratify from aerospace qualification premiums through membrane-grade purity standards to industrial coating commodity positioning.
- Aerospace Components:Thermal protection systems for jet engines and re-entry vehicles demand the highest purity grades with continuous service temperature ratings exceeding 400°C. FAA and EASA certification protocols compress supplier pools to polymerization facilities with captive monomer supply.
- Protective Gear:Firefighter and military apparel exploit inherent flame resistance with limiting oxygen indices above 40. Volume trajectories climb fastest as defense procurement cycles accelerate fiber commitments.
- Membranes:Proton exchange substrates for electrolyzers and fuel cells require membrane-grade purity with ionic conductivity optimization. German and Japanese hydrogen equipment builders qualify PBI substrates for 80°C-plus operating environments.
- Electronics:Flexible circuit insulation and connector housings substitute for fluoropolymer alternatives under REACH and RoHS constraints.
- Automotive Parts:Thermal barriers and electrical components serve electric vehicle battery enclosures and charging infrastructure.
Premium pricing anchors aerospace; steepest expansion trajectory sits with membranes.
End User Industry:
Customer concentration varies from consolidated defense primes through fragmented electronics contract manufacturers.
- Defense Contractors:Integrated platform manufacturers in the United States and Germany drive protective gear and aerospace thermal protection specifications with multi-year offtake agreements.
- Electronics Manufacturers:OEMs and EMS providers specify PBI for high-temperature insulation under EU hazardous substance restrictions.
- Chemical Processing:Petrochemical and specialty chemical operators deploy PBI gaskets, seals, and linings for aggressive media exposure.
- Power Generation:Gas turbine and nuclear operators utilize thermal barriers for extreme-environment components.
- Textiles:Industrial fabric producers blend PBI fiber with aramids for flame-resistant workwear.
Procurement concentration favors defense; specification influence favors electronics.
Form:
Processing geometry dictates thermal history and molecular weight distribution with direct impact on fabrication yield.
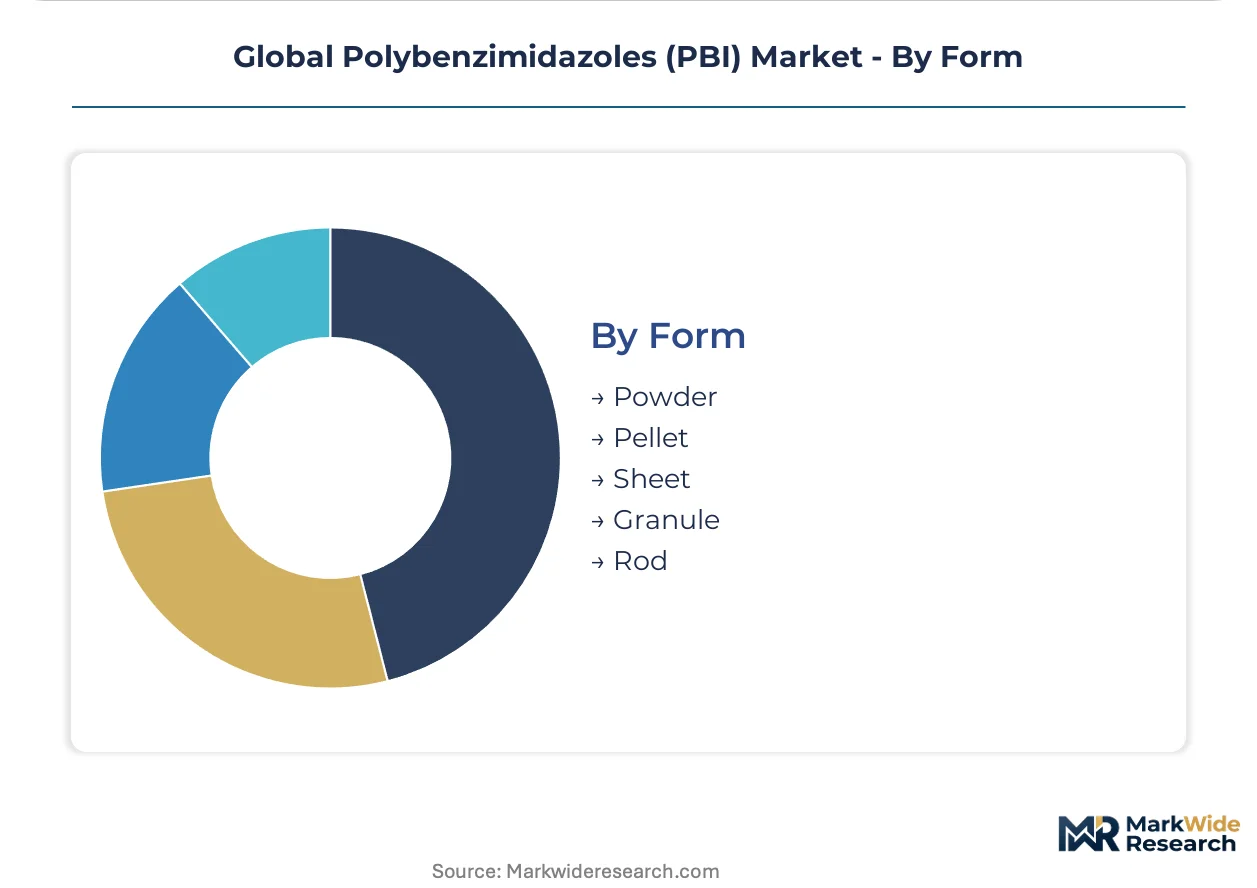
- Powder:Spray-dried particulate enables compression molding and coating dispersion with controlled particle size distribution.
- Pellet:Extruded and cut granules feed injection molding and extrusion lines with reduced dust handling.
- Sheet:Calendered and compression-molded plates provide machining stock for gaskets and electrical insulators.
- Granule:Intermediate sizing for specialty compounding operations requiring precise feed control.
- Rod:Extruded and sintered bar stock for precision machining of seals and bearings.
Processing flexibility favors pellet; machining applications favor rod.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States consume PBI primarily for aerospace thermal barriers and defense protective gear, while Japan and India concentrate procurement toward membrane-grade resins for hydrogen infrastructure and specialty chemical processing respectively.
United States
Jet engine OEMs in Connecticut and Ohio consolidate thermal barrier specifications around captive resin platforms, compressing supplier pools. EPA emissions standards govern polymerization facilities in Gulf Coast chemical parks. Defense procurement cycles sustain fiber volume commitments to qualified spinners serving firefighter and combat apparel programs.
Germany
Chemical processing clusters in North Rhine-Westphalia drive specialty resin consumption for gaskets and seals in aggressive media exposure. REACH compliance protocols and the EU F-Gas Regulation tighten material specifications, redirecting specification engineers from fluoropolymer alternatives. Hydrogen equipment builders in Bavaria qualify PBI substrates for electrolyzer stacks operating above 80°C.
Japan
Electronics manufacturers under JIS standards specify PBI film grades for flexible circuit substrates, substituting for restricted fluoropolymers. METI industrial policy supports domestic polymerization capacity for membrane-grade purity. Osaka-based fabricators anchor regional distribution of high-temperature insulation materials.
India
Government production-linked incentive schemes for advanced materials attract PBI compounders to establish formulation facilities. BIS standards govern polymer specifications for domestic aerospace and defense contractors. Gujarat and Maharashtra chemical parks concentrate new compounding capacity serving specialty resin demand.
United Kingdom
MRO providers negotiate standalone service agreements for PBI insulation blanket inspection and replacement in narrow-body engine programs. EASA certification protocols compress supplier qualification timelines. Aerospace clusters in the Midlands sustain aftermarket refurbishment revenue streams.
Global Polybenzimidazoles (PBI) Market Competitive Landscape
Capability concentration sits with resin specialists possessing captive monomer supply; scale advantage sits with diversified chemical conglomerates with multi-regional distribution networks. The vendor base separates into three tiers: integrated polymerization facilities with backward control over tetraaminobiphenyl feedstock, toll compounders serving regional fabrication demand, and specialized fiber spinners with defense qualification credentials. Dominant competitive moves include capacity expansion in German and US chemical parks and strategic partnerships between resin suppliers and hydrogen equipment builders.
Among North American resin specialists, PBI Performance Products, Inc. exemplifies the integrated polymerization archetype with captive supply chain configuration. Mitsubishi Chemical Advanced Materials represents the Asia-Pacific distribution anchor, leveraging regional manufacturing footprint to serve membrane and fiber demand. Solvay occupies a position within the diversified formulation tier, specializing in aerospace-grade specifications that command premium positioning among defense contractors.
| Leading Market Players |
|---|
| PBI Performance Products, Inc. |
| Mitsubishi Chemical Advanced Materials |
| Polymics, Ltd. |
| Bally Ribbon Mills |
| Atkins & Pearce |
| Celanese Corporation |
| Solvay |
| Gharda Chemicals Ltd. |
| HOS Technik |
| Others |
Supply & Pricing Matrix
Undercapacity in German polymerization facilities is amplifying pricing power for qualified resin suppliers while compressing margin buffers for Asian compounders lacking captive tetraaminobiphenyl supply. Jet engine OEMs in Connecticut and Ohio absorb cost pass-throughs through multi-year offtake structures, whereas electronics contract manufacturers in Japan face spot-market volatility for membrane-grade purity tiers.
Pricing Analysis
Long-term offtake contracts dominate aerospace procurement, locking in volume commitments across multi-year thermal barrier programs while spot transactions serve electronics and chemical processing buyers with shorter lead-time requirements. Price differentiation hinges on FAA-EASA dual certification status and membrane-grade ionic conductivity specifications. Cost compression in standard industrial resin tiers is intensifying because Asian compounders are bidding aggressively for European automotive qualification slots. Defense contractors exhibit the lowest price sensitivity due to mission-critical specification requirements, whereas HVAC OEMs responding to EU F-Gas Regulation phase-downs negotiate aggressively on thermal barrier foam pricing.
Supply Chain Analysis
Tariff exposure between the United States and China is disrupting established resin distribution patterns for Asian compounders serving North American aerospace Tier 1 suppliers. Captive production concentrates in the United States, Germany, and Japan, with emerging formulation capacity clustering in Gujarat and Maharashtra chemical parks under Indian PLI schemes. The supply chain draws from specialized aromatic chemical production clusters for tetraaminobiphenyl monomer, with limited alternative sourcing creating single-source vulnerability for non-integrated converters. Distribution runs through qualified polymerization facilities with direct OEM relationships, bypassing traditional chemical distributor networks for aerospace and defense qualification tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating around consolidated jet engine OEMs and defense primes, compressing supplier pools to polymerization facilities with captive monomer supply and dual-certification credentials.
For Market Incumbents: Insulate resin margin structures through backward integration into tetraaminobiphenyl production, eliminating feedstock volatility exposure that erodes compounder profitability. Expand polymerization capacity in North Rhine-Westphalia to capture EU F-Gas Regulation-driven demand from refrigeration OEMs abandoning hydrofluorocarbon alternatives. Accelerate membrane-grade purity certification with German hydrogen equipment builders to preempt perfluorinated sulfonic acid membrane displacement. For New Entrants and Emerging Players: Build out formulation facilities in Indian chemical parks under production-linked incentive schemes, targeting domestic aerospace and defense contractors with BIS-standard resin supply. The most penetrable white space sits with membrane-electrode assembly convergence for electrolyzer stacks, where qualification timelines remain open to new substrate suppliers. Pursue joint development agreements with Osaka-based fabricators to anchor regional distribution credibility under JIS standards. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across membrane-grade polymerization lines as hydrogen infrastructure scaling demands specialized purity infrastructure. Long-term viability favors integrated facilities with captive monomer supply and defense qualification credentials over toll compounders exposed to feedstock volatility. Acquisition target archetypes include German chemical processing specialists with REACH-compliant formulation expertise and established hydrogen equipment builder relationships. Monitor qualification timeline compression at FAA and EASA as the inflection signal for revenue realization acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Supply | Captive tetraaminobiphenyl production eliminates feedstock volatility exposure for resin converters. |
| Membrane-Grade Purity Certification | German hydrogen equipment builders qualify PBI substrates for 80°C-plus electrolyzer operating environments. |
| Capacity Expansion in German Chemical Parks | North Rhine-Westphalia clusters capture EU F-Gas Regulation-driven thermal barrier demand from refrigeration OEMs. |
| Long-term Defense Procurement Agreements | Multi-year offtake structures with U.S. and German military sustain fiber volume commitments to qualified spinners. |
| Joint Venture with Hydrogen Equipment Builders | Integration with Bavarian electrolyzer manufacturers compresses competitive windows for perfluorinated membrane alternatives. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, customs and trade data, ACC and Cefic industry reports, and REACH regulatory filings. Primary interviews engaged polymerization plant managers, procurement leads at jet engine OEMs, distribution channel partners, technical R&D directors at resin compounders, and defense contractor specification engineers. Bottom-up volume modeling across fiber, resin, film, coating, and composite formats triangulates against top-down value projections derived from aerospace thermal barrier program disclosures and hydrogen infrastructure investment announcements.
Forecast inputs include grade tier segmentation across aerospace qualification, membrane-grade purity, and industrial coating specifications; end-use industry clustering around defense, electronics, chemical processing, and power generation; and regional production hub differentiation between captive polymerization facilities and toll compounders. CAGRs were derived from elasticity-adjusted demand curves incorporating REACH and RoHS regulatory displacement effects, EU F-Gas Regulation phase-down schedules, and defense procurement cycle visibility. Industry-specific inputs capture membrane-electrode assembly convergence timelines and aftermarket refurbishment contract unbundling patterns in narrow-body engine programs.
Stress conditions across tetraaminobiphenyl feedstock availability, polymerization capacity utilization thresholds, and aerospace material qualification timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding sustained defense procurement commitments, hydrogen infrastructure scaling trajectories, and regulatory enforcement consistency across EU member states. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
EMI and RFI Shielding Materials Market
Specialty Materials
Global Cellulose Esters Market
Specialty Materials
Polyester Medical Films Market
Specialty Materials
Global Consumer Foam Market
Specialty Materials
Marine Mineral Complexes from Mediterranean Shells Market
Specialty Materials
Solar Backsheet Films Market
Specialty Materials
Gutta-Percha Market
Specialty Materials
Glass Ionomer Cement Market
Specialty Materials
Recyclable Thermosets Market
Specialty Materials
ePTFE Electronic Film Market
Specialty Materials
Medical Grade Silicone Market
Specialty Materials
Conductive Fluted Sheets Market
Specialty Materials
Absorbent Booms and Socks Market
Specialty Materials
Electroactive Polymers (EAP) Market
Specialty Materials
Asia-Pacific Polyether Ether Ketone (Peek) Market
Specialty Materials
Cellulose Gel Market