
 Sulphur Bentonite Market | 2026-2036
Sulphur Bentonite Market Size, Share, and Industry Trends Forecast 2026-2036
Sulphur Bentonite Market Outlook
Direct-to-farm distribution is rewriting how sulphur bentonite reaches end users, with agronomy cooperatives and input retailers consolidating procurement power across major growing regions. Tiger-Sul Products LLC leverages its North American production network to sustain supply continuity for bulk agricultural buyers. Coromandel International anchors its position through deep backward integration into sulphur sourcing and bentonite processing. ICL Group competes on specialized granular formulations tailored to precision application equipment.
Sulphur bentonite consists of elemental sulphur blended with bentonite clay, typically containing 90% sulphur and 10% swelling clay that fractures the sulphur matrix upon soil moisture contact, enabling gradual oxidation to plant-available sulphate. The material serves primarily as a soil amendment correcting sulphur deficiency in high-yield cropping systems where atmospheric deposition no longer meets crop removal rates. Granular and pellet product types dominate volume due to compatibility with mechanized spreading equipment, while powder forms occupy niche horticultural segments requiring rapid dissolution. Soil amendment applications lead end-use demand, though fertilizer additive blending is gaining traction as compound manufacturers seek sulphur delivery in bulk nutrient formulations.
EPA guidelines on sulphur emissions and OSHA workplace exposure standards shape manufacturing facility design and product handling protocols across the United States. India's Fertilizer Control Order under the Ministry of Agriculture mandates micronutrient content labeling and quality certification, directly influencing import and domestic production specifications. REACH registration requirements in Europe govern bentonite sourcing and sulphur purity thresholds for imported formulations. Stakeholders must monitor evolving sulphur recovery regulations from petroleum refining and natural gas processing, as these determine feedstock availability and cost structures for bentonite sulphur production.
Market Dynamics
Direct-to-farm distribution networks are consolidating procurement power across major agricultural regions, compressing traditional wholesale margins and forcing manufacturers to reconfigure supply relationships around cooperative buying structures.
Growth Catalysts
- EU F-Gas Regulation:Stringent fluorinated gas controls are redirecting agricultural investment toward sulphur-based soil amendments as growers seek compliant nutrient management pathways.
- Precision application equipment:Mechanized spreading technology adoption in Brazil's Cerrado region is accelerating granular sulphur bentonite uptake for large-scale soybean operations.
- Oilseed cultivation expansion:Canadian prairie growers are addressing chronic sulphur deficiency in canola rotations through systematic bentonite sulphur application programs.
Market Restraints
- Petroleum refinery sulphur supply concentration:Feedstock availability depends on sour crude processing volumes at Gulf Coast and Middle Eastern facilities, creating input cost volatility.
- REACH registration complexity:European bentonite sourcing requirements impose multi-year compliance timelines and purity verification burdens on imported formulations.
- Alternative sulphate fertilizers:Ammonium sulphate and gypsum products compete directly on immediate nutrient availability, pressuring slow-release sulphur bentonite positioning.
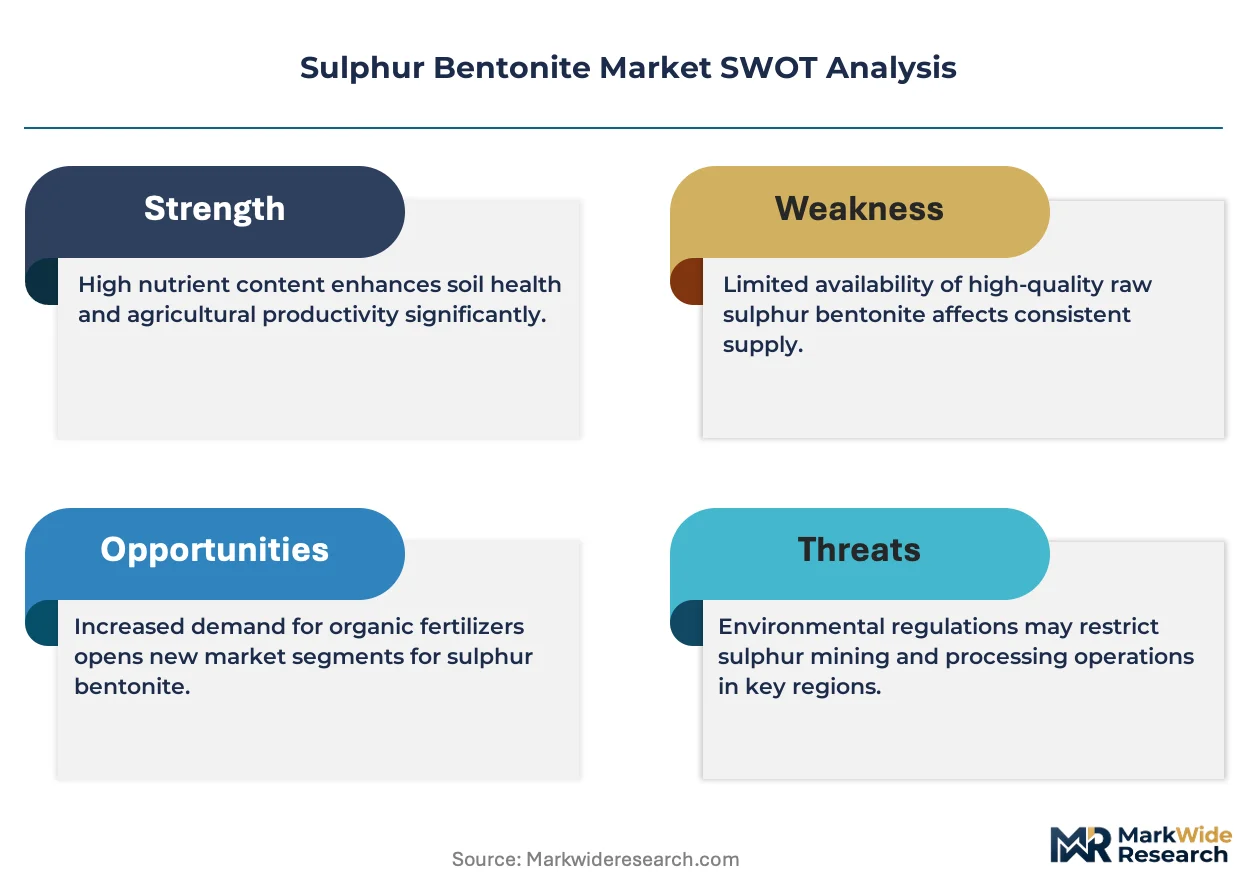
Strategic Opportunities
- Compound fertilizer blending:Bulk nutrient manufacturers are integrating sulphur bentonite into NPK formulations, opening industrial offtake channels beyond direct farm sales.
- India's Fertilizer Control Order:Micronutrient labeling mandates are creating certified product premiums for quality-verified domestic and imported sulphur bentonite.
- Horticultural powder segments:Rapid-dissolution formulations for specialty crop applications remain underdeveloped relative to dominant granular agricultural grades.
Industry Challenges
- OSHA workplace exposure compliance:Sulphur dust handling protocols require capital-intensive facility ventilation and personal protective equipment programs at manufacturing sites.
- Application equipment calibration:Variable-rate spreading technology demands agronomic expertise that input retailers struggle to staff across dispersed farm territories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sulphur Bentonite Market |
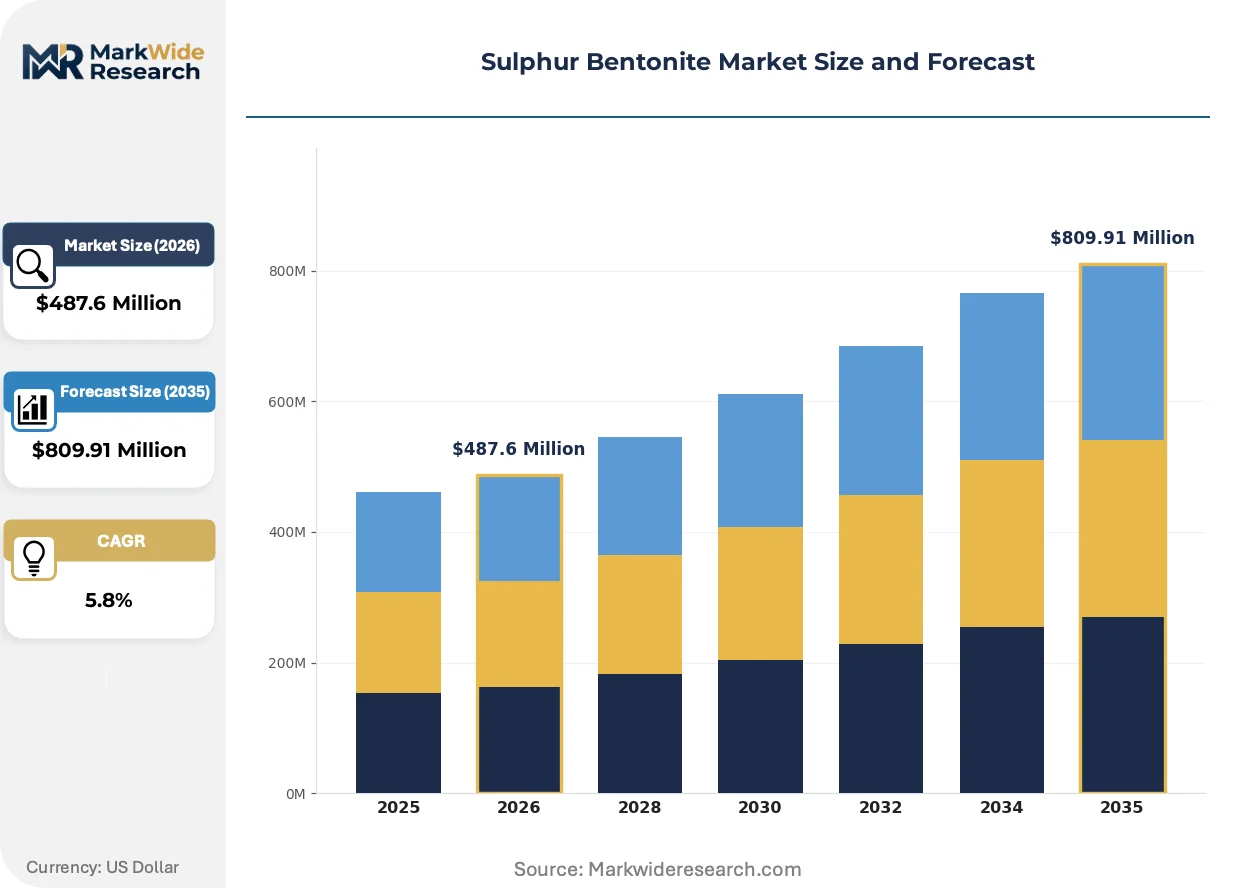
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Pellets, Tablets End User: Agriculture, Horticulture, Forestry, Turf Management Application: Soil Amendment, Fertilizer Additive, Pesticide, Plant Nutrient Packaging Type: Bags, Bulk Containers, Drums, Pallets |
| Companies Covered | Tiger-Sul Products LLC, Coromandel International, National Fertilizers Limited, Devco Australia, Coogee Chemicals, Indian Farmers Fertiliser Cooperative, ICL Group, H Sulphur Corp., Deepak Fertilisers and Petrochemicals Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sulphur Bentonite Market Strategic Shifts
Product formulation and distribution models are converging around precision agriculture requirements, with technology-enabled application and regulatory compliance emerging as the primary axes of competitive differentiation.
Controlled-release coating technology is hybridizing elemental sulphur with polymer and bentonite matrices to modulate oxidation rates across varying soil moisture conditions. Large-scale grain operations in the US Corn Belt are piloting these formulations to match sulphate availability with peak crop uptake windows. The technology is compressing the performance gap between immediate sulphate fertilizers and traditional bentonite sulphur.
EPA sulphur emissions guidelines are tightening facility-level reporting thresholds for bentonite processing operations. Manufacturing sites in Texas and Louisiana are retrofitting scrubbing systems to capture sulphur dioxide releases during granular production. The regulatory burden falls heaviest on mid-scale producers lacking integrated refining feedstock access.
Agronomy cooperatives are consolidating input procurement decisions across multi-county membership bases. Independent farm supply dealers in Saskatchewan and Manitoba are losing share to cooperative buying groups that negotiate direct manufacturer relationships. This concentration is most pronounced in regions with large-scale canola and wheat operations where sulphur deficiency correction has become standard practice.
Sulphur Bentonite Market Segmentation
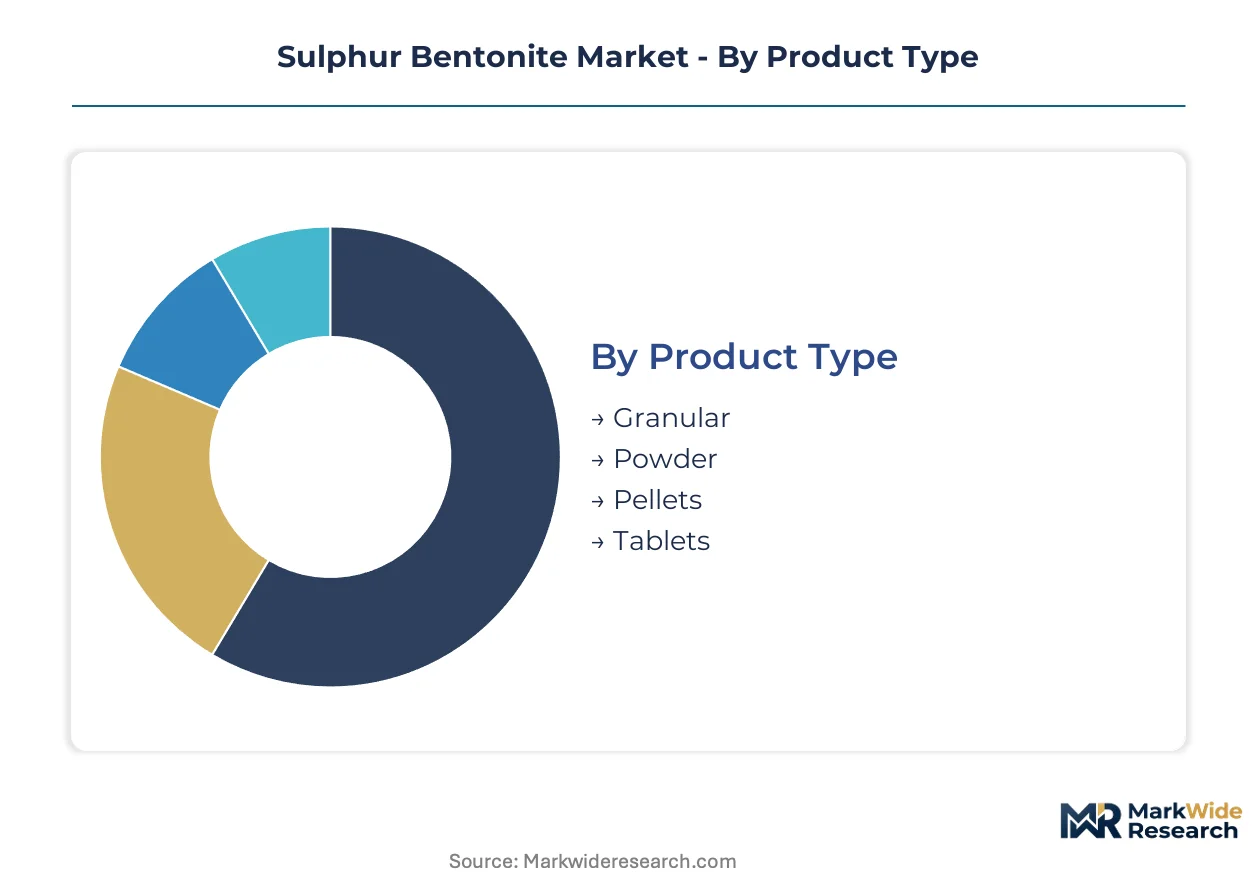
Sulphur bentonite markets fragment across product physics, end-use intensity, and supply chain logistics. Each segmentation axis carries distinct margin profiles and regulatory exposure that shape procurement decisions across agricultural and industrial channels.
Product Type:
Mature granular formats dominate commercial volumes while emerging tablet technologies target precision dosing requirements.
- Granular:Elemental sulphur particles bound with bentonite clay at 90:10 ratio, engineered for mechanized broadcast spreading across broadacre cropping. Canadian prairie canola operations and Brazilian Cerrado soybean farms drive sustained procurement of this format for sulphur deficiency correction in high-yield rotations.
- Pellets:Compressed spherical formulations with higher structural integrity than standard granular grades, designed for aerial application and reduced wind drift during spreading. US Corn Belt grain operations and Australian wheat belts concentrate demand where precision placement equipment requires uniform particle sizing.
- Powder:Fine-milled sulphur-bentonite blends for rapid soil incorporation in horticultural and greenhouse settings where immediate oxidation kinetics outweigh handling inconvenience.
- Tablets:Molded compressed units for spot application around tree crops and vineyard rows, enabling controlled sulphate release without broadcast equipment.
Granular handles the majority of throughput; tablets are the fastest mover on share.
End User:
Cost tier differentiation separates commodity agricultural buyers from premium horticultural and specialty turf segments.
- Agriculture:Broadacre cereal, oilseed, and pulse producers addressing chronic sulphur depletion in intensive cropping systems. Canadian canola growers and Brazilian soybean farmers anchor volume demand through systematic pre-plant and in-season application programs.
- Horticulture:Vegetable, fruit, and greenhouse operations requiring rapid-dissolution formulations for high-value produce where micronutrient precision affects marketable yield quality.
- Forestry:Plantation timber and pulpwood managers applying sulphur amendments to accelerate biomass accumulation on nutrient-poor sites, particularly in Scandinavian and Southeast Asian plantation estates.
- Turf Management:Golf course superintendents and sports field managers balancing visual turf quality with sulphur nutrition for root zone health in high-traffic surfaces.
Agriculture captures the dominant cost tier; horticulture commands the steepest expansion trajectory.
Application:
Volume concentration in soil amendment contrasts with margin concentration in fertilizer additive blending.
- Soil Amendment:Direct field application to correct sulphur deficiency in sulphate-depleted soils, representing the foundational use case for bentonite sulphur products across all major grain and oilseed regions.
- Fertilizer Additive:Integration into bulk NPK and compound fertilizer manufacturing, where compounders seek captive sulphur delivery without separate handling infrastructure.
- Plant Nutrient:Foliar and fertigation formulations for targeted sulphur delivery during critical crop growth stages, expanding in controlled-environment agriculture.
- Pesticide:Sulphur's fungicidal properties in organic and low-chemical production systems, particularly in European vineyard and orchard applications under EU Green Deal pesticide reduction targets.
Soil amendment moves the greatest volume; fertilizer additive blending is gaining share fastest.
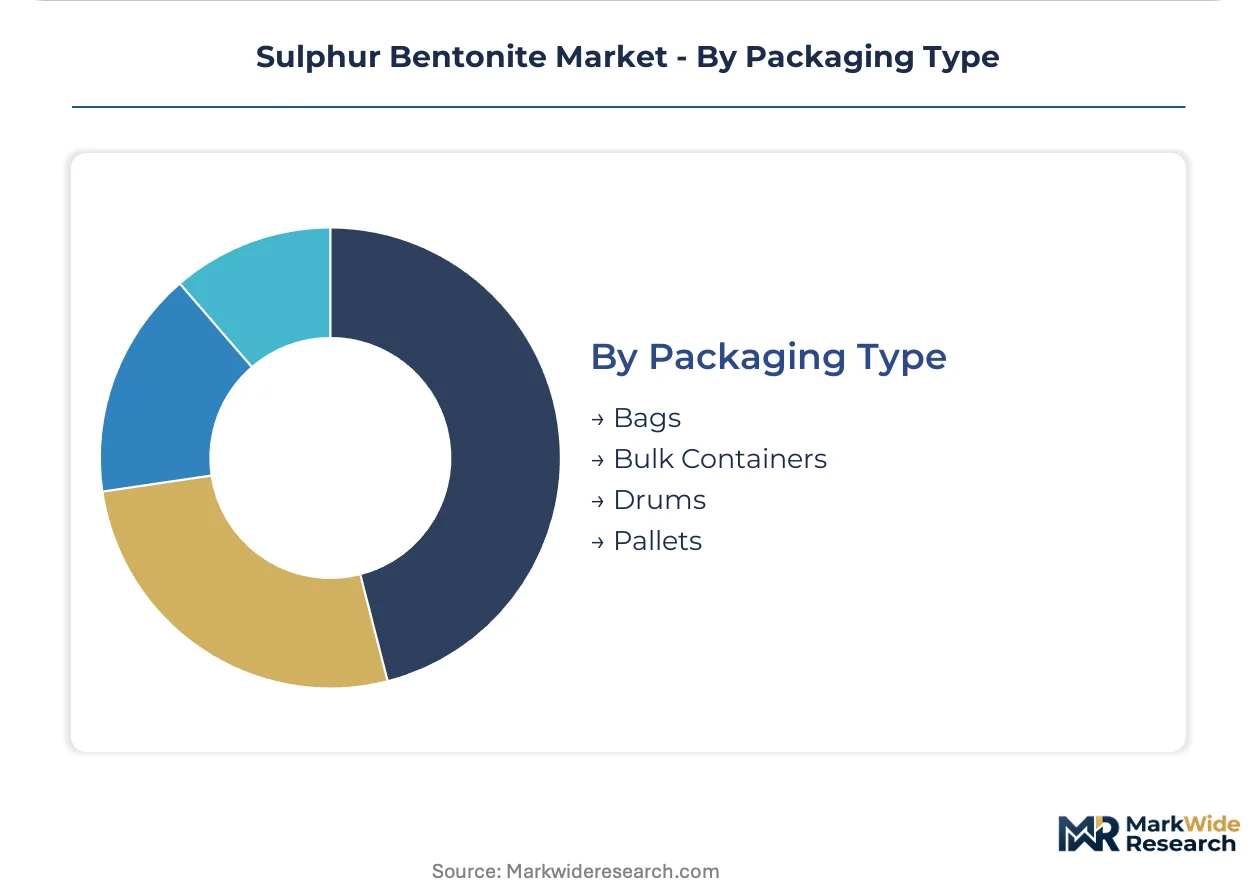
Packaging Type:
Supply chain configuration separates bulk container flows to industrial compounders from bagged retail channels serving dispersed farm operations.
- Bulk Containers:Tote and intermediate bulk container formats for compound fertilizer manufacturers and large cooperative buying groups with dedicated handling equipment.
- Bags:Standard 25-50kg woven polypropylene units for farm-gate delivery through agricultural retail networks, dominant in developing market smallholder channels.
- Drums:Sealed steel and fiber containers for moisture-sensitive powder grades and specialty horticultural formulations requiring extended storage stability.
- Pallets:Unitized load configurations for mechanized warehouse handling at agronomy cooperative distribution centers and large-scale farm supply depots.
Bulk containers serve industrial offtake; bags retain the broadest geographic penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Fertilizer Control Order under the Ministry of Agriculture is driving certified product premiums across multiple jurisdictions. Brazilian soybean expansion and Canadian canola intensification are redirecting procurement toward quality-verified sulphur bentonite formulations. Regulatory tightening in Europe and feedstock volatility in the Middle East are reshaping regional supply strategies.
Brazil
Precision application equipment adoption across Mato Grosso and Goiás is accelerating granular sulphur bentonite uptake for large-scale soybean operations. ANVISA's agricultural input registration requirements are extending compliance timelines for imported formulations. The Cerrado region concentrates demand where intensive farming drives sustained micronutrient investment.
Canada
Oilseed cultivation expansion across Saskatchewan and Manitoba is elevating sulphur bentonite consumption as growers address chronic deficiency in canola rotations. Health Canada's PMRA regulates product labeling and environmental release standards for soil amendments. Prairie cooperative buying groups are consolidating procurement power and compressing traditional wholesale margins.
India
Micronutrient labeling mandates under the Fertilizer Control Order are creating certified product premiums for quality-verified domestic and imported sulphur bentonite. The DGFT monitors import specifications for bentonite sourcing and sulphur purity thresholds. Gujarat and Maharashtra host compound fertilizer manufacturers integrating sulphur bentonite into NPK formulations.
United States
EPA guidelines on sulphur emissions and OSHA workplace exposure standards are shaping manufacturing facility design across Texas and Louisiana. The Corn Belt is piloting controlled-release formulations to match sulphate availability with peak crop uptake windows. Mid-scale producers lacking integrated refining feedstock access face the heaviest regulatory retrofit burden.
Germany
REACH registration requirements are imposing multi-year compliance timelines and purity verification burdens on imported bentonite formulations. The EU F-Gas Regulation is redirecting agricultural investment toward sulphur-based soil amendments as compliant nutrient management pathways. Industrial clusters in North Rhine-Westphalia concentrate blending operations serving Central European compound fertilizer demand.
Sulphur Bentonite Market Competitive Environment
On the supply side, the industry is moderately consolidated around integrated fertilizer conglomerates and specialized sulphur processors. Tiered competitive positioning separates multinational compound manufacturers with captive bentonite sourcing from regional blenders dependent on merchant sulphur markets. Three archetypes dominate: backward-integrated refiners with captive feedstock, agricultural cooperative networks with distribution control, and precision formulation specialists serving equipment-calibrated application. Capacity expansion and cooperative procurement consolidation represent the dominant competitive moves reshaping supply relationships.
Among North American and Australian processors, Tiger-Sul Products LLC exemplifies the production-network archetype sustaining supply continuity for bulk agricultural buyers. Coromandel International occupies a position representing deep upstream control over sulphur sourcing and bentonite processing. ICL Group sits within the specialization tier competing on formulation precision for mechanized spreading equipment. These three anchors illustrate how geographic feedstock access and distribution integration determine competitive positioning across the value chain.
| Leading Market Players |
|---|
| Tiger-Sul Products LLC |
| Coromandel International |
| National Fertilizers Limited |
| Devco Australia |
| Coogee Chemicals |
| Indian Farmers Fertiliser Cooperative |
| ICL Group |
| H Sulphur Corp. |
| Deepak Fertilisers and Petrochemicals Corporation |
| Others |
Value Chain & Pricing Dynamics
Gulf Coast petrochemical clusters in Texas and Louisiana concentrate elemental sulphur refining capacity, feeding bentonite processing operations whose output volumes directly determine regional pricing power for agricultural buyers. This geographic concentration of feedstock supply creates asymmetric leverage between integrated refiners and regional blenders dependent on merchant sulphur spot markets.
Pricing Analysis
Certification level under India's Fertilizer Control Order creates the primary spread between premium and standard grades, with quality-verified domestic production commanding sustained premiums over unlabeled imports. Volume scale differentiates cooperative procurement pricing from dispersed farm-gate retail, while after-sales agronomic support bundles compress price transparency. Cost compression in standard granular grades is intensifying because Brazilian and Canadian buyers are consolidating procurement through direct manufacturer relationships. Smallholder channels in developing markets exhibit the highest price sensitivity, whereas precision application equipment operators in Brazil's Cerrado demonstrate lowest sensitivity due to yield-linked return calculations.
Supply Chain Analysis
REACH registration requirements in Europe and India's DGFT import specifications function as de facto export controls, limiting formulation flows from non-compliant sourcing jurisdictions. Sulphur bentonite supply concentrates in the United States, India, and Australia, with production anchored in petroleum refining byproduct recovery and bentonite clay mining. Raw material dependencies rest on sour crude processing volumes, swelling clay grades from Wyoming and Gujarat deposits, and polymer coating inputs for controlled-release variants. Single-source vulnerability pervades the feedstock layer where Gulf Coast refinery maintenance cycles disrupt sulphur availability. Distribution runs through agronomy cooperative networks that are displacing traditional wholesale channels across North American prairie provinces and Brazilian soybean states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sulphur bentonite markets are entering a high-growth disruption phase as precision agriculture equipment and EU F-Gas Regulation compliance redirect agricultural investment toward sulphur-based soil amendments.
For Market Incumbents: Entrench position through backward integration into captive bentonite mining in Wyoming or Gujarat deposits, and accelerate certification investment under India's Fertilizer Control Order to defend against quality-verified domestic competition. Channel control represents the priority lever as cooperative buying groups compress wholesale margins across Canadian prairie provinces. For New Entrants and Emerging Players: Horticultural powder segments for greenhouse and specialty crop operations represent the most penetrable entry point, given underdeveloped supply relative to dominant granular agricultural grades. India's compound fertilizer blending channel offers secondary access, with go-to-market execution through technical partnerships with NPK manufacturers seeking captive sulphur delivery without separate handling infrastructure. For Investors and Strategic Acquirers: Long-term, this sits as a feedstock-integrated specialty chemicals play because sulphur recovery regulations from petroleum refining determine cost structures and competitive moats. Acquisition targets should prioritize mid-scale processors with existing REACH registration or Fertilizer Control Order certification. The signal to watch is sour crude processing volume trends at Gulf Coast and Middle Eastern facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bentonite Mining | Captive clay supply from Wyoming or Gujarat deposits insulates margin pressure from merchant mineral markets. |
| REACH Registration Investment | Multi-year compliance timelines create defensive barriers against non-European formulation imports. |
| Controlled-Release Coating Development | Polymer-bentonite hybrid formulations match sulphate availability with peak crop uptake windows in US Corn Belt operations. |
| Cooperative Distribution Partnerships | Direct relationships with Saskatchewan and Manitoba buying groups secure volume offtake bypassing wholesale intermediaries. |
| Fertilizer Control Order Certification | Quality-verified labeling under India's Ministry of Agriculture mandates unlocks premium pricing in micronutrient-deficient states. |
Study Parameters
Operator-level perspectives from agronomy cooperative procurement managers, compound fertilizer plant engineers, bentonite mining operations heads, and agricultural retail channel partners anchored the qualitative base. Primary field engagement combined with secondary validation from EPA emissions filings, Indian Fertilizer Control Order regulatory databases, customs trade records, and SEC disclosures from listed fertilizer conglomerates. Bottom-up volume estimates from regional application rates and top-down cross-checks against sulphur recovery data from petroleum refining operations were triangulated to establish market sizing.
Scenario-bracketing around regulatory enforcement intensity and precision agriculture equipment adoption rates bounded the projection range across the analysis window. Segmentation dimensions modeled include product physics (granular, pellet, powder, tablet), end-use intensity (agriculture, horticulture, forestry, turf), application mode (soil amendment, fertilizer additive, plant nutrient, pesticide), and packaging configuration (bulk, bagged, drum, pallet). CAGRs were derived from elasticity-adjusted demand curves incorporating oilseed cultivation expansion rates and sulphur deficiency correction penetration in intensive cropping systems.
Macroeconomic conditions sit as an overlay; deviation in crude oil price volatility, agricultural commodity cycles, or fertilizer subsidy policy would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory timeline adherence and equipment adoption curves. Cross-checking against bentonite trade flow data and regional sulphur recovery statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Marine Mineral Complexes from Mediterranean Shells Market
Specialty Materials
Semiconductor O-Rings Market
Specialty Materials
Glass Ionomer Cement Market
Specialty Materials
PVB Interlayers Market
Specialty Materials
Engineered Quartz Surface Market
Specialty Materials
Magnesium Fluoride Market
Specialty Materials
APAC Fluoroelastomer Market
Specialty Materials
Special Graphite Market
Specialty Materials
Lab Grown Diamonds Market
Specialty Materials
Global PU Films Market
Specialty Materials
Dysprosium Oxide Sputtering Target Market
Specialty Materials
Global Cellulose Esters Market
Specialty Materials
Africa Collagen Market
Specialty Materials
Polyetherimide (PEI) Market
Specialty Materials
Crusher Backing Materials Market
Specialty Materials
Absorbent Booms and Socks Market