
 Recyclable Thermosets Market | 2026-2036
Recyclable Thermosets Market Size, Share, and Industry Trends Forecast 2026-2036
Recyclable Thermosets Market Intelligence
Epoxy resin waste from wind turbine blades is decoupling from landfill-dependent disposal economics as recyclable formulations achieve cost parity with virgin materials. BASF SE leverages its integrated polyurethane recycling pilot in Ludwigshafen to anchor European supply chains for circular feedstocks. Covestro AG sustains technology leadership through its specialized chemical recycling process for rigid foams used in automotive seating. Huntsman Corporation dominates North American demand with its controlled distribution network serving aerospace Tier-1 suppliers in Wichita and Everett.
Recyclable thermosets constitute cross-linked polymer networks engineered with reversible covalent bonds or dynamic exchange chemistries, enabling depolymerization at temperatures between 150°C and 250°C without structural degradation. These materials serve industries requiring high thermal stability and dimensional rigidity where conventional thermoset disposal incurs escalating environmental penalties. Epoxy formulations lead product type revenue pools due to established aerospace qualification pathways, while chemical recycling technology captures the fastest expansion as pyrolysis and solvolysis methods mature at pilot scale. Polyurethane applications in automotive seating represent the most concentrated margin pool among end-user segments.
The EU Green Deal and REACH framework restrict persistent organic pollutants in virgin thermoset precursors, redirecting procurement budgets toward certified recyclable alternatives. EPA hazardous waste classifications in the United States elevate disposal costs for conventional thermoset scrap, strengthening the business case for closed-loop systems. China's MEE enforces dual carbon goals that penalize non-recyclable composite manufacturing in Jiangsu and Guangdong provinces. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate which recycling technology standards achieve cross-border harmonization first.
Market Dynamics
Chemical recycling infrastructure for cross-linked polymers is compressing the cost gap between virgin and circular thermoset feedstocks, forcing capital reallocation toward depolymerization assets.
Growth Catalysts
- EU Green Deal mandates:Binding carbon neutrality targets for 2050 redirect automotive and aerospace procurement toward certified recyclable epoxy systems. REACH chemical safety standards tighten precursor approval pathways.
- Wind blade decommissioning wave:First-generation offshore installations in the North Sea and Baltic reach end-of-life, generating concentrated feedstock volumes for chemical recycling pilots.
- Pyrolysis technology maturation:Continuous-flow reactor designs achieve throughput rates that support commercial-scale operations for aerospace composite scrap recovery.
Market Restraints
- Specialized catalyst cost volatility:Ruthenium and zinc-based depolymerization catalysts face supply concentration from South African and Chinese refiners, compressing processor margins.
- Technical limitation in fiber recovery:Glass and carbon fiber reinforcement damage during solvolysis reduces secondary fiber tensile strength by 15-30%, limiting closed-loop aerospace applications.
- Regulatory friction from EPA hazardous waste rules:Unclear classification of chemically recycled thermoset intermediates creates permitting delays for US-based processing facilities.
Strategic Opportunities
- Underpenetrated automotive seating in India:Domestic OEMs lack qualified suppliers for chemically recyclable polyurethane foam, creating first-mover advantage for technology licensors.
- Japan's METI circular economy subsidies:Funding pools for demonstration projects lower capex barriers for rigid foam recycling infrastructure in the Kansai manufacturing belt.
- Technology convergence of AI-sorting and near-infrared identification:Automated feedstock characterization improves batch consistency for mixed thermoset waste streams in European collection networks.
Industry Challenges
- Polymer chemist talent scarcity:Industrial expertise in dynamic covalent chemistry and reversible network design concentrates in academic laboratories, constraining process scale-up teams.
- Aerospace qualification timeline compression:OEMs require 3-5 year certification cycles for structural epoxy replacements, delaying revenue recognition for recycled formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recyclable Thermosets Market |
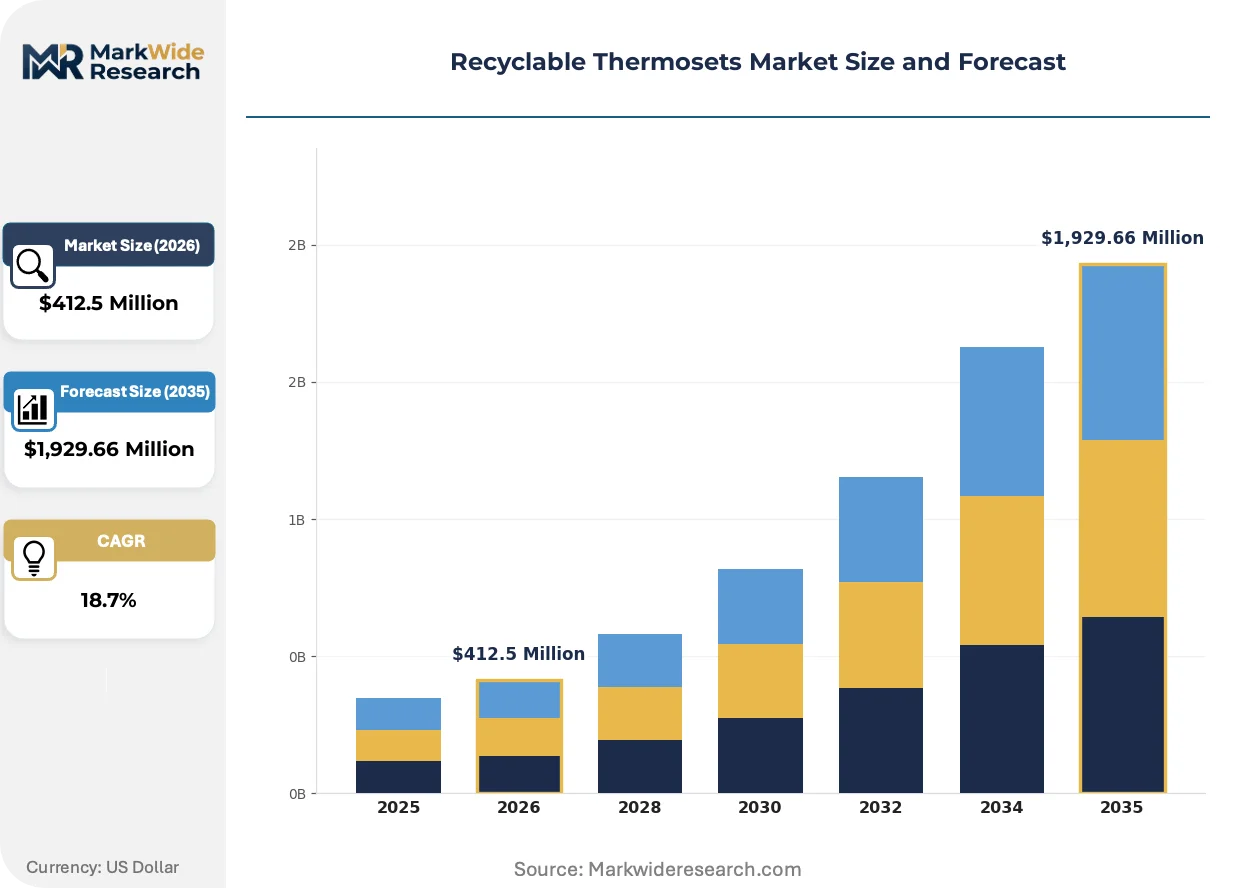
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,929.66 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phenolic, Epoxy, Polyurethane, Polyester Application: Aerospace, Automotive, Electronics, Construction End User: Manufacturers, OEMs, Tier-1 Suppliers, Startups Technology: Chemical Recycling, Mechanical Recycling, Energy Recovery, Biodegradable Thermosets |
| Companies Covered | BASF SE, Covestro AG, Aditya Birla Chemicals, Connora Technologies, Huntsman Corporation, Arkema, Hexcel Corporation, SABIC, Adesso Advanced Materials Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recyclable Thermosets Market Strategic Shifts & Innovations
Vitrimer chemistry is rewriting thermoset lifecycle economics by introducing bond exchange mechanisms that preserve mechanical properties through multiple reprocessing cycles.
Vitrimer formulations incorporating disulfide metathesis and transesterification chemistries enable reprocessing at moderate temperatures without irreversible cross-link degradation. Automotive Tier-1 suppliers in Germany and Japan are piloting these materials for interior structural components with 18-month qualification targets. This technology is consolidating supplier power around patent-holders who control catalyst and monomer supply chains.
REACH authorization procedures for persistent organic pollutants in bisphenol-based epoxy precursors are tightening feedstock approval windows. ECHA's restriction roadmap forces reformulation investments across European aerospace and wind energy supply chains. German composite manufacturers around Stuttgart are accelerating partnerships with chemical recyclers to secure compliant alternative feedstock pipelines.
Buyers in the wind energy sector are inserting circularity clauses into blade supply contracts, requiring OEMs to assume end-of-life recycling liability. Vestas and Siemens Gamesa procurement teams now specify recyclable resin systems for new offshore installations. This contractual shift is most pronounced in Danish and German North Sea developments where landfill bans on composite waste take effect by 2030.
Recyclable Thermosets Market Segmentation
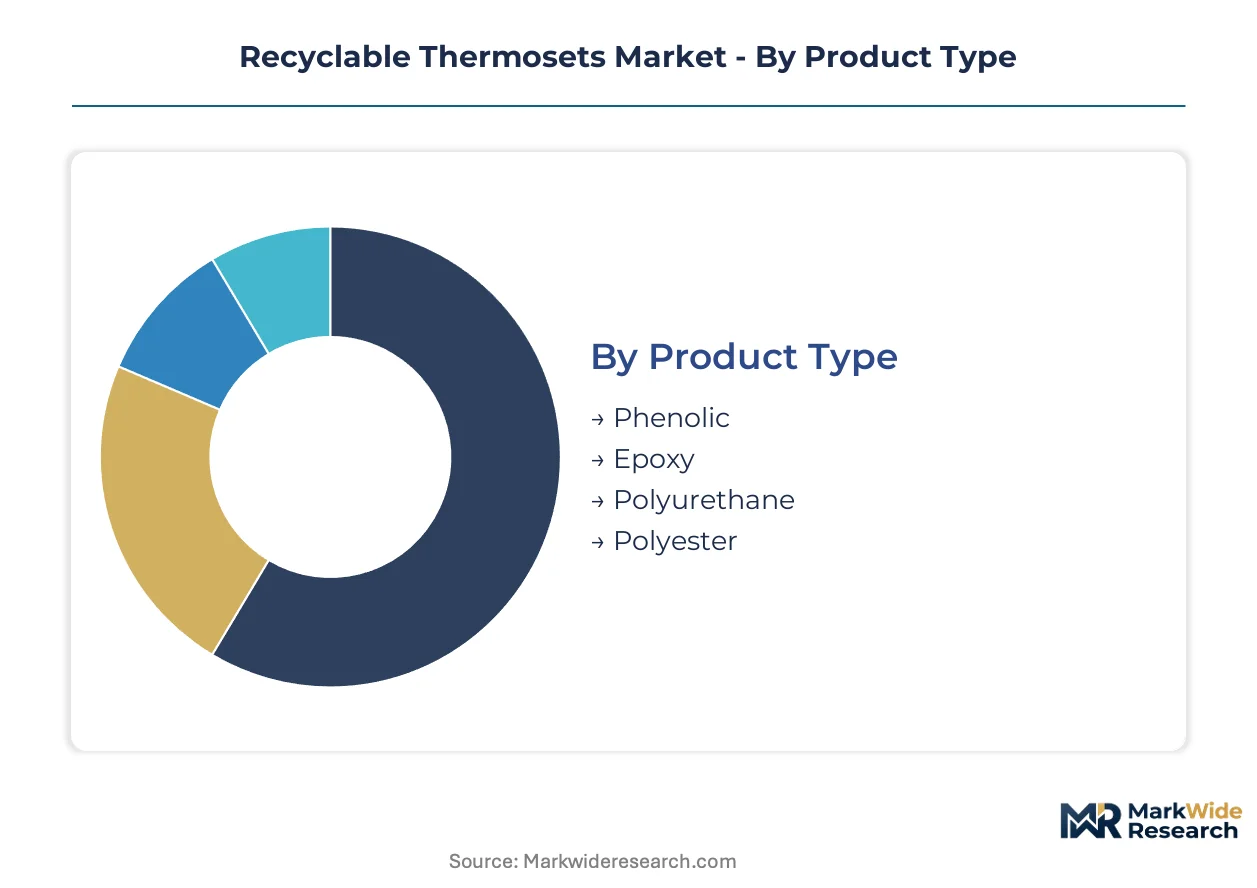
Segmentation in recyclable thermosets reveals where formulation chemistry, processing infrastructure, and regulatory pressure intersect. Each dimension exposes distinct margin pools and capital allocation priorities for processors and OEM procurement teams.
Product Type:
Standardization dominates commodity phenolic and polyester formulations, while epoxy and polyurethane command premium pricing through customized network architectures and reversible bond engineering.
- Epoxy:Cross-linked networks with dynamic covalent bonds enable depolymerization at 150-250°C without structural degradation. Aerospace qualification pathways in Germany and Japan concentrate procurement for structural composite applications under EU Green Deal mandates.
- Polyurethane:Rigid and flexible foam variants incorporate carbamate linkages cleavable through solvolysis methods. Automotive seating demand from Stuttgart and Wolfsburg manufacturing corridors drives chemical recycling pilot investments.
- Phenolic:Formaldehyde-based networks with limited reversibility suit electrical insulation and fire-resistant construction panels.
- Polyester:Unsaturated formulations serve cost-sensitive construction and marine applications with mechanical recycling as primary recovery route.
Most installed capacity flows through Epoxy. Expansion is steepest in Polyurethane.
Application:
Volume concentration separates mass-market construction from precision-driven aerospace and automotive segments where certification timelines and performance specifications dictate supplier selection.
- Aerospace:Primary structural components require FAA and EASA qualification cycles spanning 3-5 years for recycled epoxy formulations. Wichita and Everett Tier-1 suppliers source through controlled distribution networks with batch traceability mandates.
- Automotive:Lightweight structural components and interior panels accelerate adoption of chemically recycled systems. EU Green Deal binding targets redirect procurement budgets toward certified recyclable alternatives in German OEM supply chains.
- Electronics:Printed circuit board substrates and encapsulation materials face REACH restrictions on bisphenol-based precursors.
- Construction:Infrastructure composites and insulation panels operate under less stringent performance certification, prioritizing cost over circularity metrics.
Revenue concentrates in Aerospace. Volume expansion climbs fastest in Automotive.
End User:
Procurement sophistication varies from multinational OEMs with dedicated sustainability procurement officers to startups lacking qualified supplier relationships.
- OEMs:Volkswagen, Vestas, and Siemens Gamesa insert circularity clauses into supply contracts requiring end-of-life recycling liability assumption. North Sea and Baltic offshore wind developments specify recyclable resin systems with landfill bans effective by 2030.
- Tier-1 Suppliers:Mid-tier processors serving aerospace and automotive channels face compressed margins from catalyst cost volatility and fiber recovery technical limitations.
- Manufacturers:Compounders and composite fabricators source mixed thermoset waste streams requiring AI-sorting and near-infrared identification for batch consistency.
- Startups:Technology licensors in vitrimer chemistry and dynamic covalent network design concentrate in academic spinouts with limited production scale.
Contract volume concentrates with OEMs. Technology licensing growth is sharpest among Startups.
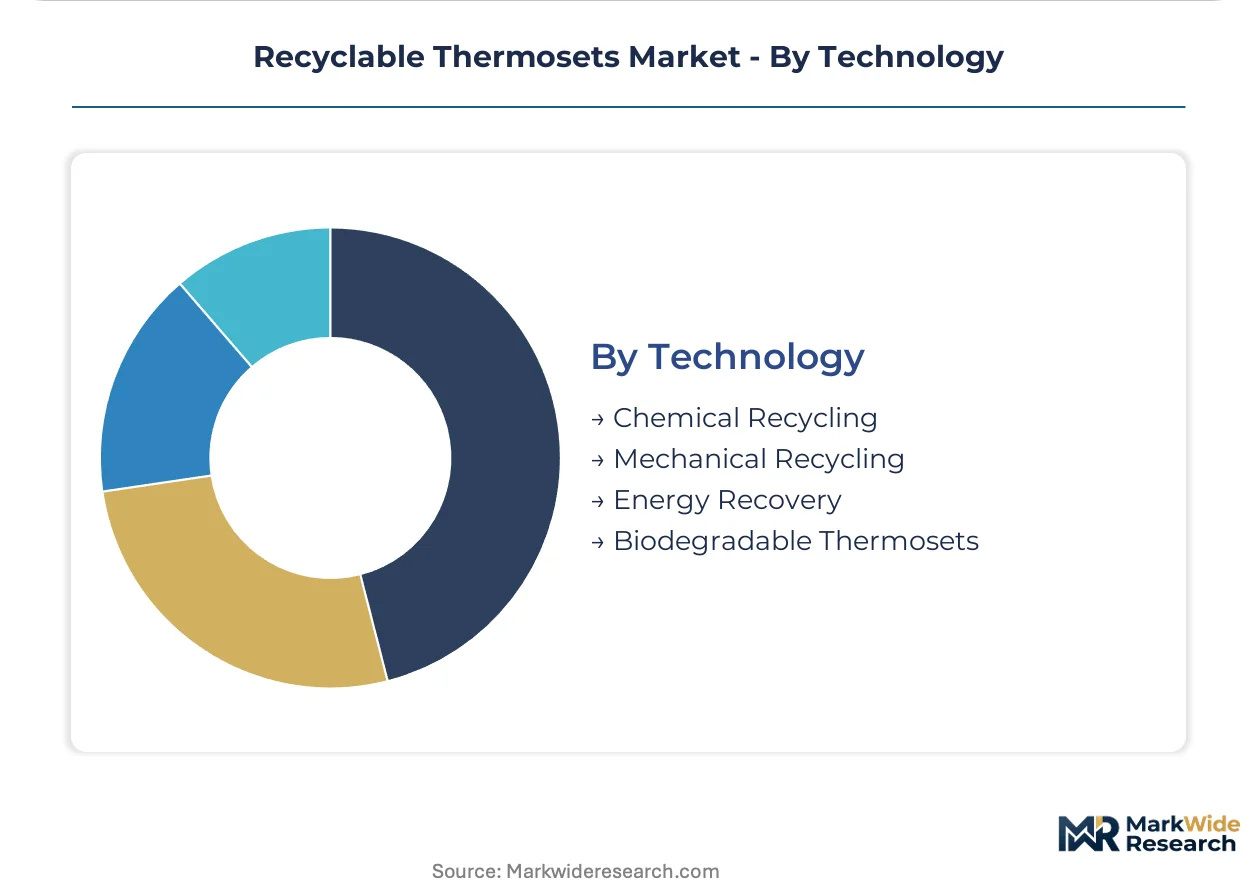
Technology:
Capital intensity and recovery yield separate mature mechanical methods from emerging chemical and biological pathways still at pilot scale.
- Chemical Recycling:Pyrolysis and solvolysis methods achieve commercial-scale throughput for aerospace composite scrap. Continuous-flow reactor designs mature at BASF's Ludwigshafen pilot and Covestro's rigid foam recovery operations.
- Mechanical Recycling:Grinding and remilling of thermoset waste serves construction and lower-specification automotive applications where fiber length degradation is acceptable.
- Energy Recovery:Incineration with energy capture faces regulatory pressure from EU Green Deal carbon neutrality targets and China's MEE dual carbon goals in Jiangsu and Guangdong.
- Biodegradable Thermosets:Emerging formulations with enzymatic degradation pathways remain pre-commercial, constrained by thermal stability limitations in structural applications.
Processing volume flows through Mechanical Recycling. Investment inflows target Chemical Recycling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive manufacturing corridor around Stuttgart and Wolfsburg commands the most concentrated demand for chemically recyclable thermoset systems, with EU Green Deal mandates redirecting procurement budgets toward certified circular alternatives.
Germany
Automotive OEMs in Stuttgart and Wolfsburg accelerate adoption of chemically recycled epoxy resins for lightweight structural components. REACH chemical safety standards tighten precursor approval pathways for conventional thermoset production. BASF SE anchors European supply chains through its integrated polyurethane recycling pilot in Ludwigshafen.
United States
Aerospace Tier-1 suppliers in Wichita and Everett drive qualification demand for recycled epoxy formulations with batch traceability mandates. EPA hazardous waste classifications elevate disposal costs for conventional thermoset scrap, strengthening closed-loop business cases. Huntsman Corporation dominates North American distribution networks serving these concentrated manufacturing clusters.
China
MEE dual carbon goals penalize non-recyclable composite manufacturing in Jiangsu and Guangdong provinces, redirecting investment toward chemical recycling infrastructure. Wind blade decommissioning generates concentrated feedstock volumes for pyrolysis pilots. Domestic compounders source mixed thermoset waste streams requiring automated characterization for batch consistency.
Japan
METI circular economy subsidies fund demonstration projects lowering capex barriers for rigid foam recycling infrastructure in the Kansai manufacturing belt. Automotive Tier-1 suppliers pilot vitrimer formulations for interior structural components with compressed qualification timelines. Technology licensors concentrate in academic spinouts around Osaka and Nagoya.
India
Domestic automotive OEMs lack qualified suppliers for chemically recyclable polyurethane foam, creating first-mover opportunities for technology licensors. BIS standards for sustainable materials gradually align with EU circularity frameworks. Manufacturing clusters in Maharashtra and Gujarat face procurement gaps in certified recyclable thermoset feedstocks.
Recyclable Thermosets Market Key Industry Players
Technology licensing dominates the current landscape as patent-holders consolidate control over catalyst and monomer supply chains for vitrimer chemistries. The vendor base spans multinational chemical conglomerates with integrated recycling pilots, mid-tier specialty resin producers, and academic spinouts commercializing dynamic covalent network designs. Two strategic archetypes predominate: integrated chemical majors leveraging backward control into circular feedstock production, and technology specialists licensing reversible bond platforms to Tier-1 processors. Capacity expansion and strategic partnerships represent the most visible competitive moves, with processors securing offtake agreements for decommissioned wind blade feedstocks.
Among European-based chemical majors, BASF SE and Covestro AG exemplify the integrated archetype through captive recycling infrastructure and specialized chemical recovery processes. Huntsman Corporation anchors the North American competitive vector through controlled distribution networks. These three entities represent distinct geographic and technological positioning strategies without overlapping operational footprints.
| Leading Market Players |
|---|
| BASF SE |
| Covestro AG |
| Aditya Birla Chemicals |
| Connora Technologies |
| Huntsman Corporation |
| Arkema |
| Hexcel Corporation |
| SABIC |
| Adesso Advanced Materials Inc. |
| Others |
Cost & Logistics Intelligence
Aerospace Tier-1 procurement teams in Wichita and Everett concentrate buying power for certified recyclable epoxy systems, anchoring contract-based long-term offtake pricing with volume-scale discounts and batch traceability premiums.
Pricing Analysis
Input-cost pass-through from ruthenium and zinc-based depolymerization catalysts compresses processor margins, forcing price adjustments downstream. Three-tier pricing structure across aerospace-qualified, automotive-certified, and industrial-grade levels separates segments by certification stringency. Cost compression in commodity phenolic tiers is intensifying because mechanical recycling alternatives undercut chemical recovery economics. Tier-1 suppliers exhibit lowest price sensitivity due to qualification lock-in, while construction end-users drive hardest bargaining on standard polyester formulations.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Stuttgart and Wolfsburg automotive clusters, while specialized distributors serve fragmented construction and electronics segments. Manufacturing concentration in Germany, China, and the United States shapes regional pricing benchmarks. Feedstock supply draws from decommissioned North Sea wind blades, aerospace composite scrap, and post-industrial polyurethane foam. Single-source vulnerability in South African ruthenium refining creates catalyst procurement risk. Distribution runs through controlled networks with batch documentation mandates for aerospace qualification pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH authorization timelines for bisphenol-based precursors lag EPA hazardous waste rulemaking in the United States, creating a 12-18 month regulatory arbitrage window for processors with dual-hemisphere qualification capabilities.
For Market Incumbents: To counter emerging vitrimer chemistry patent-holders, BASF and Covestro should deepen backward integration into circular feedstock production through captive wind blade offtake agreements. Securing exclusive catalyst supply contracts with South African refiners locks in cost position against margin compression. For New Entrants and Emerging Players: Launch via technology licensing to domestic automotive OEMs in Maharashtra and Gujarat, where BIS standards alignment with EU circularity frameworks creates first-mover advantage. India's underpenetrated polyurethane foam recycling infrastructure offers the most penetrable white space. Partner with academic spinouts in Osaka for vitrimer formulation transfer. For Investors and Strategic Acquirers: Chemical majors with integrated recycling pilots are the most active acquirers in this space, consolidating catalyst and monomer supply chain control. Long-term viability hinges on 5-10 year aerospace qualification pipeline visibility. Monitor ECHA restriction roadmap acceleration on bisphenol-A precursors as the inflection signal for recycled feedstock demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | BASF's Ludwigshafen pilot scaling enables European supply chain anchoring for circular polyurethane feedstocks. |
| Backward Integration | Covestro's rigid foam recovery operations secure captive supply from automotive seating waste streams. |
| Long-term Supply Agreement | Vestas circularity clauses with blade OEMs lock in end-of-life recycling liability assumptions by 2030. |
| Joint Venture | Japanese METI-funded demonstrations in Kansai lower capex barriers for vitrimer commercialization partnerships. |
| Technology Licensing | Academic spinouts around Nagoya monetize dynamic covalent chemistry patents through Tier-1 automotive supplier deals. |
Research Approach
Multiple input streams — primary interviews with polymer chemists and aerospace procurement directors, customs and trade data from EU and US customs authorities, and ECHA regulatory filings — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from ACC industry reports, SEC 10-K disclosures from listed chemical majors, and wind energy decommissioning databases. Conversations with plant managers at BASF Ludwigshafen and Covestro Leverkusen facilities informed capacity and yield assumptions.
Data-stream reconciliation across product type, application, end-user category, and recycling technology dimensions enabled segmentation-level modeling. CAGRs were derived from slope analysis of installed capacity expansion curves against regulatory mandate implementation timelines. Aerospace qualification pipeline data and automotive circular procurement contract volumes served as industry-specific forecast anchors across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under catalyst supply disruption or accelerated ECHA restriction timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Elastic Films Market
Specialty Materials
Advanced Green Septa Market
Specialty Materials
Polyphenylsulfone Market
Specialty Materials
Specialty Silicone Market
Specialty Materials
Methyl Silicone Market
Specialty Materials
Europe Textile Films Market
Specialty Materials
Silicone Solutions Market
Specialty Materials
Global PMMA Microspheres Market
Specialty Materials
Metalized Biaxially Oriented Polypropylene Films Market
Specialty Materials
Compostable Cotton Swab Market
Specialty Materials
Global Liquid Crystal Polymer (LCP) Films and Laminates Market
Specialty Materials
Polyimide Films Market
Specialty Materials
United States Microspheres Market
Specialty Materials
Silicone Film Market
Specialty Materials
Global Synthetic Zeolite Market
Specialty Materials
North America Solar Control Window Films Market