
 North America Smart Grid Market | 2026-2036
North America Smart Grid Market Size, Share, and Industry Trends Forecast 2026-2036
North America Smart Grid Market Analytics
Silicon carbide power electronics is repositioning converter economics across transmission and distribution systems. General Electric Company leverages its manufacturing scale to anchor domestic supply chains for grid-scale inverters. Siemens AG competes through technology leadership in digital twin platforms for substation automation. ABB Ltd specializes in high-voltage direct current interties that sustain cross-border power transfers between the United States and Canada.
North America smart grid denotes an electricity network integrating digital communication, advanced sensors, and automated control systems to enable bidirectional power flows and real-time demand-supply balancing, typically operating at frequencies of 60 Hz with latency requirements below 100 milliseconds for protection relaying. Advanced Metering Infrastructure occupies the largest technology position as utilities replace electromechanical meters with cellular-connected endpoints. Demand Response represents the fastest-expanding technology segment as wholesale markets in Texas and the Mid-Atlantic ISO integrate price-responsive load. Grid Automation commands concentrated margin pools where utilities require cyber-hardened control systems for critical infrastructure protection.
FERC Order 2222 and the North American Electric Reliability Corporation Critical Infrastructure Protection standards collectively reshape product requirements for cybersecurity and interoperability certification. The Environmental Protection Agency's power plant emissions rules indirectly stimulate grid modernization by accelerating renewable interconnection queues. Stakeholders must monitor how state-level public utility commission rulings on rate-base treatment of cloud-based deployment models alter vendor contracting structures.
Market Dynamics
FERC Order 2222 has fundamentally restructured electricity market participation rules, forcing utilities and technology vendors to rebuild interoperability standards around aggregated distributed energy resource bidding. This regulatory mandate cascades through procurement specifications, cybersecurity certification requirements, and vendor contracting timelines across the United States and Canada.
Growth Catalysts
- FERC Order 2222:The regulation mandates wholesale market access for aggregated DERs, compelling grid operators to develop new bidding platforms and settlement systems.
- Silicon carbide semiconductors:These wide-bandgap devices slash switching losses in power converters, enabling higher-density inverter deployments at substations.
- Texas ERCOT price volatility:Extreme weather-driven scarcity pricing creates direct economic returns for demand response aggregators and battery storage operators.
Market Restraints
- Cybersecurity compliance costs:NERC CIP standards impose mandatory audit cycles and encryption requirements that inflate project budgets by fifteen to twenty percent.
- Copper and rare earth supply concentration:Chinese processing dominance for neodymium and dysprosium creates input vulnerability for transformer and permanent magnet manufacturing.
- Interconnection queue delays:Regional transmission organizations face multi-year backlogs for renewable and storage projects, freezing capital deployment timelines.
Strategic Opportunities
- Canadian HVDC intertie expansion:Manitoba and Quebec hydroelectric surplus offers baseload balancing services for US Midwest and Northeast grids.
- Cloud-native SCADA platforms:Software-as-a-service delivery models reduce upfront capital barriers for municipal and cooperative utilities.
- Vehicle-to-grid integration:Bidirectional charging standards unlock mobile storage capacity from electric vehicle fleets in California and Texas.
Industry Challenges
- Cyber-physical systems engineering talent:The intersection of power systems expertise and information security certification remains severely understaffed across utilities.
- Multi-vendor interoperability testing:IEC 61850 implementation variations between suppliers create integration failures during commissioning.
- Rate-base treatment uncertainty:State public utility commissions issue inconsistent rulings on whether cloud-hosted control systems qualify for regulated cost recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Smart Grid Market |
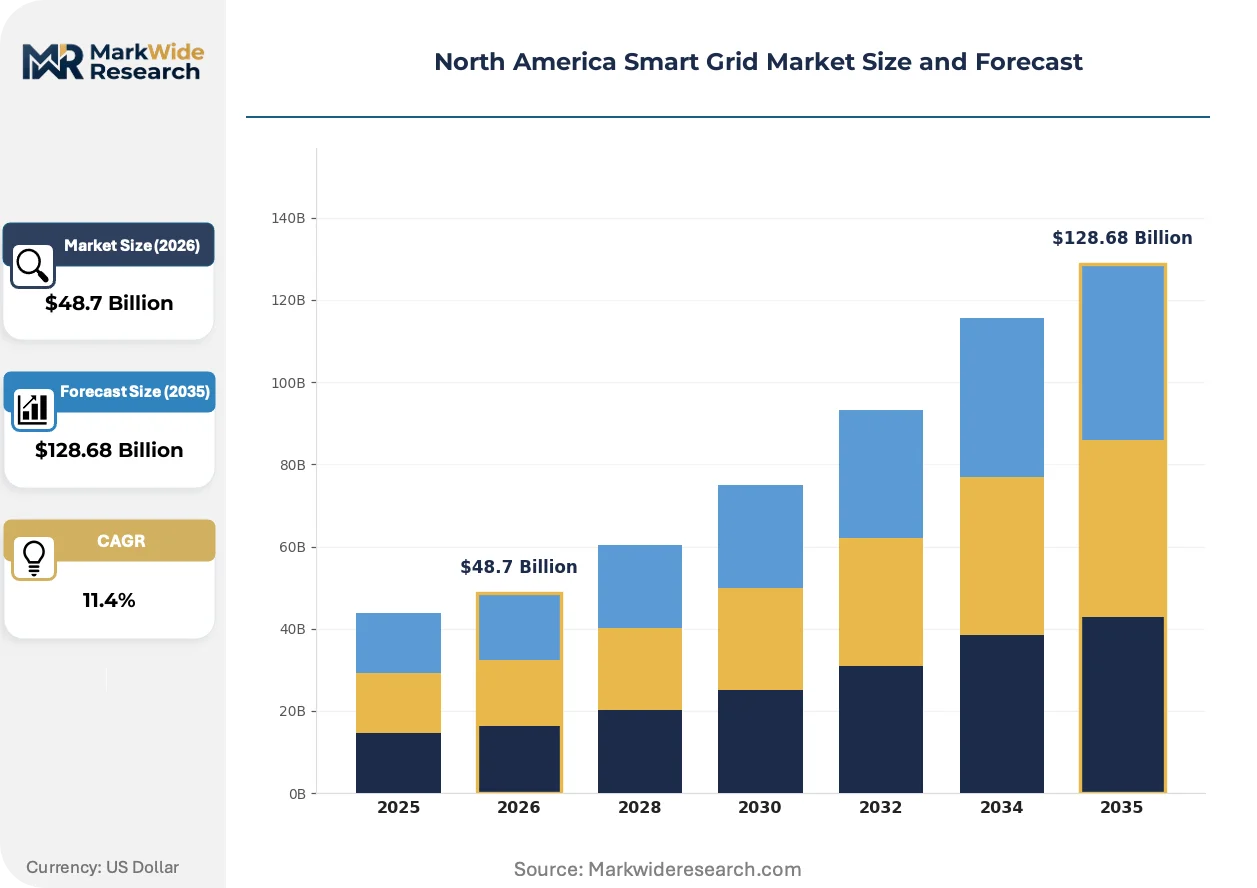
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $128.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Advanced Metering Infrastructure, SCADA, Demand Response, Distribution Management System Application: Energy Management, Grid Automation, Remote Monitoring, Electric Vehicle Integration End User: Utilities, Industrial Sector, Commercial Buildings, Residential Users Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Itron Inc., Schneider Electric, General Electric Company, Trilliant Holdings, Eaton Corporation plc, ABB Ltd, Honeywell International Inc., GE Vernova, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Smart Grid Market Evolving Landscape
Digitization of substation protection and control systems is compressing equipment replacement cycles while elevating software competence above hardware manufacturing scale as the primary competitive differentiator. Vendors now compete on firmware update velocity and threat intelligence integration rather than electromechanical relay reliability alone.
Silicon carbide power electronics is modularizing converter architectures across transmission and distribution systems. The material enables ten-kilohertz switching frequencies versus silicon's five-kilohertz ceiling, shrinking magnetic component volume by forty percent. Investor-owned utilities in Texas and California are deploying these converters for solar and battery integration. The technology is modularizing what were once centralized substation designs into distributed, containerized power conversion skids that utilities can stage and commission in weeks rather than months.
The Environmental Protection Agency's power plant emissions rules indirectly stimulate grid modernization by accelerating renewable interconnection queues. Coal and gas plant retirements trigger transmission upgrades to maintain voltage stability. ISO New England and PJM Interconnection are expanding dynamic line rating systems to extract capacity from existing corridors. The Mid-Atlantic and Northeast regions face the most acute pressure to reconductor and automate aging transmission infrastructure.
Buyer concentration among large investor-owned utilities is compressing vendor sales cycles and shifting contract structures toward performance guarantees. Duke Energy, Southern California Edison, and Dominion Energy now require cybersecurity incident response SLAs and software escrow provisions. Procurement teams in these utilities favor vendors with domestic manufacturing footprints to mitigate supply chain risk. Texas municipal utilities and electric cooperatives lag this consolidation, maintaining fragmented purchasing that sustains smaller regional system integrators.
North America Smart Grid Market Segmentation
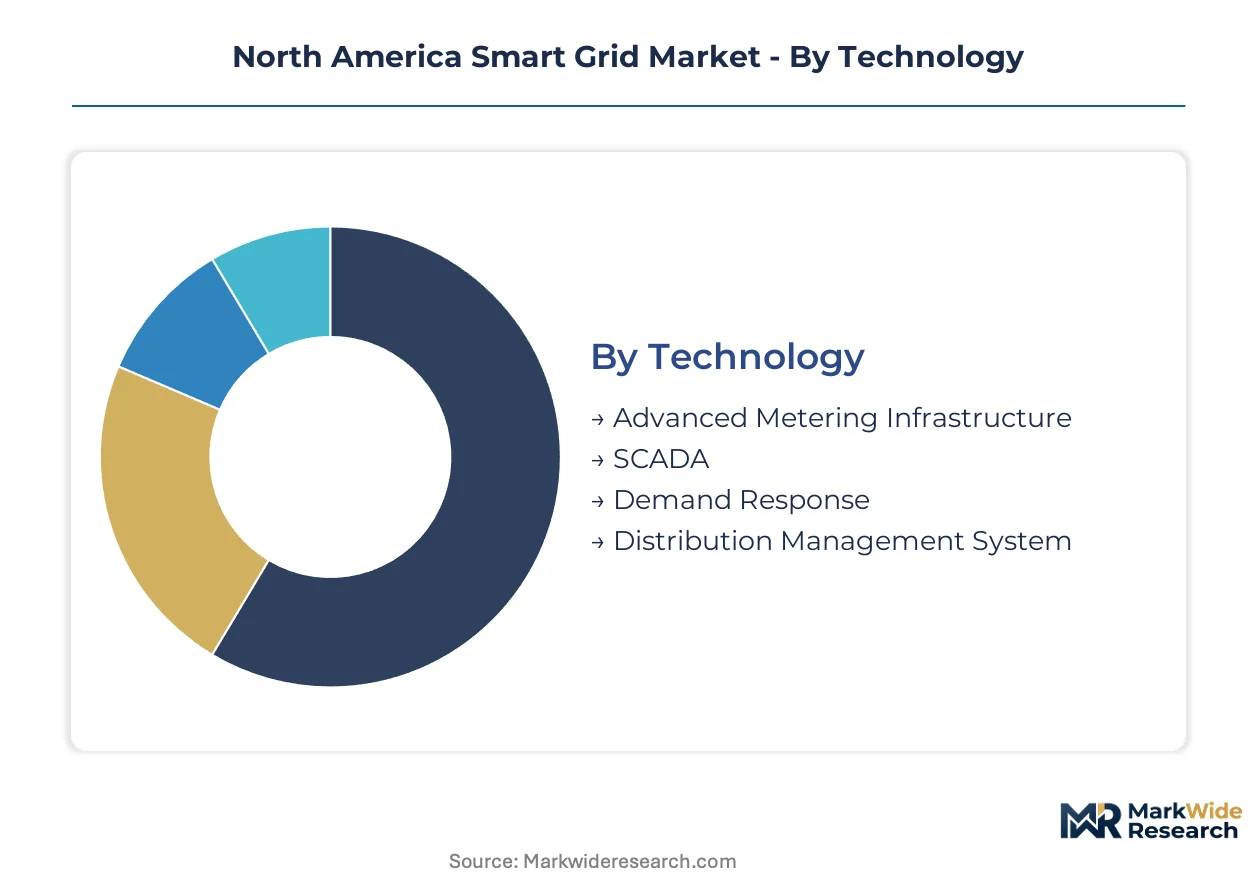
Technology heterogeneity across the North America Smart Grid Market creates distinct procurement patterns and vendor specialization zones. Each segmentation axis reveals where capital concentrates and which capabilities command pricing premiums.
Technology:
Silicon carbide semiconductors and cellular connectivity protocols are reshaping equipment specifications across all four technology segments.
- Advanced Metering Infrastructure:Cellular-connected endpoints replace electromechanical meters, with dual-band RF mesh and LTE-M radios dominating new deployments. Demand concentrates among Texas and California investor-owned utilities replacing twenty-year meter fleets, driven by FERC Order 2222 settlement data requirements.
- Demand Response:Aggregated load control platforms enable price-responsive bidding into ERCOT and PJM wholesale markets. Deployment concentrates in Texas municipal utilities and Mid-Atlantic ISO territories, propelled by scarcity pricing events and battery storage co-location economics.
- SCADA:Cyber-hardened control systems with IEC 61850 protocol stacks protect critical substation infrastructure.
- Distribution Management System:Outage management and volt-VAR optimization modules integrate DER forecasting for feeder-level balancing.
Mature deployment sits with Advanced Metering Infrastructure. Newer deployment is concentrated in Demand Response.
Application:
Application selection tracks utility organizational maturity and capital allocation discipline across operational domains.
- Grid Automation:Protection relaying and feeder automation systems operate below 100-millisecond latency thresholds. Procurement clusters at Duke Energy and Southern California Edison, compelled by NERC CIP audit cycles and cyber insurance underwriting requirements.
- Electric Vehicle Integration:Bidirectional charging controllers and fleet management platforms unlock mobile storage capacity. California IOUs and Texas cooperatives lead deployment, driven by state zero-emission vehicle mandates and vehicle-to-grid pilot programs.
- Energy Management:Commercial and industrial load forecasting tools optimize behind-the-meter consumption.
- Remote Monitoring:Transformer health sensors and dynamic line rating systems extract capacity from existing corridors.
Grid Automation commands the deepest capital commitment cycles. Electric Vehicle Integration is climbing the fastest as fleet electrification accelerates.
End User:
End user type determines contract structure, procurement timeline, and cybersecurity compliance burden.
- Utilities:Investor-owned utilities consolidate purchasing through master service agreements with performance guarantees and software escrow provisions. Rate-base treatment rulings by state public utility commissions shape cloud deployment appetite.
- Industrial Sector:C&I facilities with behind-the-meter solar and storage require private wire automation and islanding controls.
- Commercial Buildings:Smart building integration platforms aggregate HVAC and lighting loads for demand response participation.
- Residential Users:Home energy management systems and smart thermostat aggregators participate in wholesale markets through utility programs.
Utilities anchor procurement volume. Industrial Sector adoption is gaining share fastest as manufacturing reshoring intensifies reliability requirements.
Deployment:
Deployment architecture selection reflects risk tolerance for operational technology cybersecurity and data sovereignty constraints.
- Cloud-Based:SaaS-delivered SCADA and analytics platforms reduce upfront capital barriers for municipal and cooperative utilities. Adoption concentrates among Midwest and Northeast public power entities, driven by IT staffing constraints and subscription pricing preferences.
- Edge Computing:Containerized control systems process protection decisions locally with cloud telemetry backup. Texas and California utilities deploy at solar and battery sites, compelled by sub-cycle latency requirements and FERC interconnection standards.
- On-Premise:Air-gapped control systems remain mandatory for critical infrastructure protection compliance.
- Hybrid:Tiered architectures partition real-time control locally with analytics workloads in cloud instances.
On-Premise retains regulatory preference for protection systems. Edge Computing represents the steepest expansion trajectory as distributed resource penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States utilities drive the majority of capital deployment, with state-level regulatory variation creating distinct procurement clusters across the continent. Canadian provinces leverage hydroelectric surplus for cross-border balancing services. Mexican grid modernization accelerates through renewable interconnection mandates and industrial zone electrification.
United States
Texas and California utilities anchor demand through ERCOT scarcity pricing and CPUC renewable mandates. FERC Order 2222 compels grid operators to rebuild bidding platforms for aggregated DER participation. Silicon Valley and Austin metropolitan clusters concentrate software development for grid analytics and demand response aggregation platforms.
Canada
Manitoba and Quebec hydroelectric authorities pursue HVDC intertie expansion to export baseload balancing services. Provincial crown corporations dominate procurement through centralized capital programs. Toronto and Vancouver metropolitan areas host emerging clean technology clusters focused on grid-scale storage integration.
Mexico
Industrial manufacturing zones in Nuevo León and Baja California drive private wire automation and reliability investments. CRE regulatory reforms open wholesale market participation for distributed generation assets. Mexico City metropolitan utilities deploy smart metering to reduce non-technical losses in dense urban distribution networks.
North America Smart Grid Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with technology leadership and manufacturing scale commanding divergent margin pools. Grid automation and power electronics sectors consolidate around integrated solution providers, while metering and software layers sustain fragmented specialist competition. Two strategic archetypes dominate: diversified industrial conglomerates leveraging cross-divisional technology transfer, and pure-play grid technology vendors with concentrated R&D depth. Competitive moves center on silicon carbide supply chain anchoring and cloud-native platform partnerships with municipal utilities.
Within the diversified industrial tier, General Electric Company and Siemens AG exemplify scale-driven positioning through vertical manufacturing integration and digital twin platform development. ABB Ltd occupies a specialist position in high-voltage interconnection technology. These three anchors represent contrasting geographic origins and organizational structures while competing across overlapping procurement cycles at major investor-owned utilities.
| Leading Market Players |
|---|
| Itron Inc. |
| Schneider Electric |
| General Electric Company |
| Trilliant Holdings |
| Eaton Corporation plc |
| ABB Ltd |
| Honeywell International Inc. |
| GE Vernova |
| Siemens AG |
| Others |
Value Network & Pricing Analysis
Silicon carbide substrate costs cascade through converter manufacturing tiers, with six-inch wafer pricing separating premium grid-scale inverters from standard distribution-class units and economy-grade residential string converters downstream.
Pricing Analysis
Volume concentrates in cellular-connected meter endpoints while margins pool in cyber-hardened substation automation systems. Pricing stratifies across premium, standard, and economy tiers based on NERC CIP certification grade and domestic manufacturing footprint. Cost compression in AMI endpoints is intensifying because Chinese module suppliers are expanding LTE-M radio production capacity. Municipal utilities exhibit highest price sensitivity, while investor-owned utilities prioritize cybersecurity SLAs over unit economics.
Supply Chain Analysis
Domestic-content mandates in the Inflation Reduction Act are reshaping sourcing patterns for transformer core steel and power semiconductor packaging. Manufacturing concentrates in the United States, Mexico, and Vietnam for final assembly, while raw materials draw from Chilean copper mines and Australian rare earth processing facilities. Single-source vulnerability sits with Chinese neodymium refining for permanent magnet synchronous machines. Distribution runs through utility master service agreements and EPC contractor procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Smart Grid Market has become a vertical-integration race, with silicon carbide wafer production and cloud-native software stacks representing the decisive upstream and downstream levers players are pursuing to capture margin pools.
For Market Incumbents: Deepen backward integration into silicon carbide epitaxy and substrate manufacturing to offset Chinese rare earth processing dominance. Anchor domestic inverter assembly capacity in Texas and California to satisfy IRA content requirements. Counter emerging pure-play software vendors by accelerating firmware update velocity and threat intelligence integration. For New Entrants and Emerging Players: Launch via SaaS-delivered SCADA platforms targeting Midwest municipal utilities constrained by IT staffing shortages. Penetrate the cloud-based deployment segment where rate-base treatment uncertainty has slowed incumbent cloud migration. White-space exists in vehicle-to-grid aggregation software for Texas cooperative fleets. For Investors and Strategic Acquirers: FERC Order 2222 implementation timelines are the leading indicator that aggregated DER platform economics will mature within the next decade. Target acquisition candidates with IEC 61850 protocol expertise and established utility cybersecurity certifications. Monitor state public utility commission rulings on cloud-hosted control system rate-base eligibility as the inflection signal for SaaS vendor valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Chain Anchoring | Captures margin from Chinese wafer suppliers by securing domestic six-inch substrate capacity. |
| Cloud-Native SCADA Platform Launch | Unlocks municipal utility procurement cycles previously blocked by capital budget constraints. |
| Vehicle-to-Grid Integration Partnership | Positions aggregators to bid mobile storage into ERCOT scarcity pricing events. |
| HVDC Intertie Expansion Joint Venture | Enables Manitoba and Quebec hydroelectric surplus to balance US Midwest renewable variability. |
| Cybersecurity Certification Acceleration | Shortens sales cycles at Duke Energy and Southern California Edison through NERC CIP pre-qualification. |
Research Methodology
Multi-period observation of utility capital expenditure disclosures, renewable interconnection queue depths, and FERC docket filings anchored the trend analysis, supplemented by interviews with utility planning officers, grid automation procurement leads, substation automation engineers, and DER aggregation platform developers. Secondary validation drew from EIA Form 860 data, FERC Order 2222 implementation filings, NERC CIP audit summaries, and ISO New England interconnection statistics. Bottom-up equipment shipment tracking and top-down utility revenue requirement analysis were triangulated to constrain forecast variance.
Input-output matrices mapped technology adoption curves against regulatory compliance deadlines across the projection horizon. Segmentation dimensions modeled include deployment architecture, end-user utility type, technology maturity tier, and regional regulatory framework. CAGRs were derived from logistic diffusion curves fitted to historical smart meter deployment rates and silicon carbide inverter adoption patterns. Forecast inputs incorporated FERC Order 2222 settlement system timelines and state renewable portfolio standard acceleration clauses.
The model assumes a particular technology adoption path for silicon carbide power electronics; alternative pathways involving gallium nitride or silicon superjunction devices would alter the outlook for converter cost trajectories. Forecasts reflect assumptions regarding NERC CIP audit cycle intensity and state-level rate-base treatment consistency. Supply chain disruptions in Chinese rare earth processing or copper concentrate markets could revise capital deployment timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
Smart Grid Data Management Market
Smart Grid
China Smart Power Distribution Systems Market
Smart Grid
Automated Demand Response Management Systems Market
Smart Grid
Asia-Pacific Demand Response Management Systems Market
Smart Grid
Global Smart Grid Security Market
Smart Grid
Global Smart Grid Networking Market
Smart Grid
South and Central America Smart Grid Market
Smart Grid
Europe Smart Grid Network Market
Smart Grid
South Korea Smart Grid Network Market
Smart Grid
South Africa Smart Grid Market
Smart Grid
Microgrid Market
Smart Grid
Smart Grid Sensors Market
Smart Grid
UK Smart Grid Network Market
Smart Grid
Saudi Arabia Smart Grid Network Market
Smart Grid
Europe Automated Demand Response Market
Smart Grid
AC Grid Connected Microgrid Market