
 South Africa Smart Grid Market | 2026-2036
South Africa Smart Grid Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Smart Grid Market Analytics
Eskom's Just Energy Transition Partnership is pivoting capital allocation toward grid digitalization and distributed energy resource management. Siemens AG leverages its automation portfolio to anchor substation modernization contracts across South Africa's transmission network. ABB Ltd competes on power electronics specialization, particularly in high-voltage direct current links that stabilize intermittent renewable feed-in from the Northern Cape solar cluster.
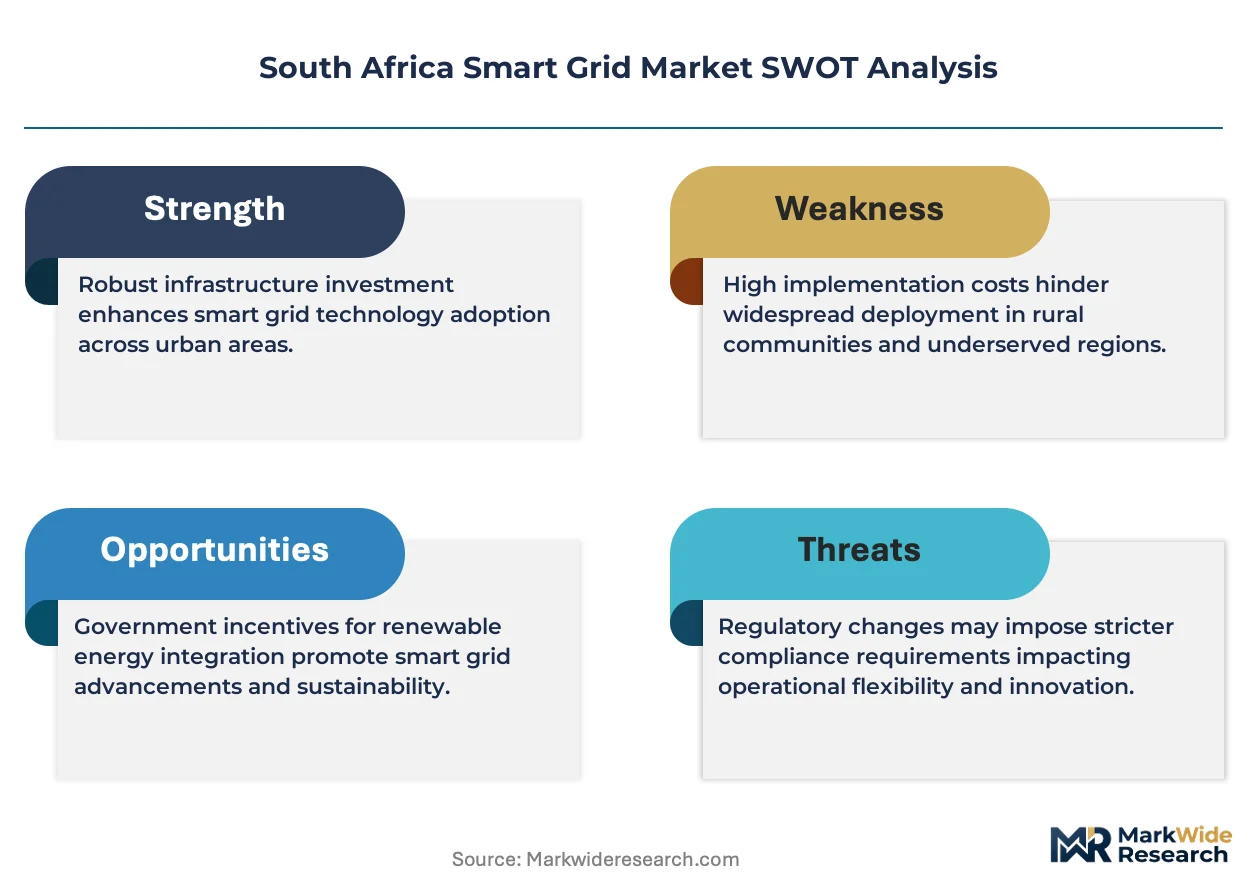
A smart grid integrates digital communications, advanced sensing, and automated control systems into electrical power infrastructure to enable bidirectional energy flows and real-time network optimization. The architecture typically incorporates phasor measurement units with sub-second sampling rates and IEC 61850 protocol interoperability for substation automation. Smart Meters dominate product type revenue by installation volume, though Grid Management Software captures disproportionate margin pools through recurring licensing and SaaS delivery models. Microgrid Technology within the technology dimension represents the fastest-expanding segment, driven by mining operations and commercial campuses seeking islanding capability during Eskom's persistent load-shedding events.
The National Energy Regulator of South Africa (NERSA) governs tariff structures and independent power producer licensing, while the South African Bureau of Standards (SBS) enforces grid interconnection codes that determine equipment certification requirements. The country's central bank, the South African Reserve Bank, influences infrastructure financing costs through monetary policy that affects utility capital expenditure cycles. Stakeholders must monitor NERSA's pending distributed generation licensing reforms and SBS's evolving cybersecurity standards for critical energy infrastructure.
Market Dynamics
Eskom's persistent load-shedding crisis is forcing municipal utilities and large industrial consumers to accelerate distributed energy resource deployment, fundamentally restructuring capital allocation toward grid-edge intelligence and islanding capability.
Growth Catalysts
- Just Energy Transition Partnership:International climate financing is unlocking dedicated capital streams for transmission digitalization and renewable integration infrastructure across the national grid.
- Mining sector electrification:Deep-level platinum and gold operations require advanced load management and microgrid redundancy to maintain production continuity during utility outages.
- NERSA distributed generation reforms:Pending licensing amendments for behind-the-meter generation are clearing regulatory pathways for commercial and industrial self-supply arrangements.
Market Restraints
- Foreign exchange volatility:Rand depreciation against the dollar and euro inflates imported hardware costs for switchgear, power electronics, and metering equipment.
- Concentrated equipment supply:High-voltage direct current converter stations and advanced metering infrastructure rely on a narrow base of European and East Asian original equipment manufacturers.
- Utility debt overhang:Eskom's financial distress constrains its ability to execute capital-intensive grid modernization programs without external guarantee structures.
Strategic Opportunities
- Northern Cape solar cluster integration:Utility-scale photovoltaic installations require grid stabilization services and energy storage co-location that create demand for power electronics and grid management software.
- Commercial campus microgrids:Shopping centers, hospitals, and data centers in Gauteng and Western Cape are procuring islanding-capable systems to ensure operational continuity.
- SBS cybersecurity standardization:Evolving critical infrastructure protection mandates are creating compliance-driven replacement cycles for legacy control systems and communication protocols.
Industry Challenges
- SCADA and substation automation expertise:Shortage of engineers proficient in IEC 61850 protocol implementation and phasor measurement unit deployment limits project execution velocity.
- Legacy meter integration:Heterogeneous installed base of mechanical and early electronic meters complicates AMI rollout and data platform consolidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Smart Grid Market |
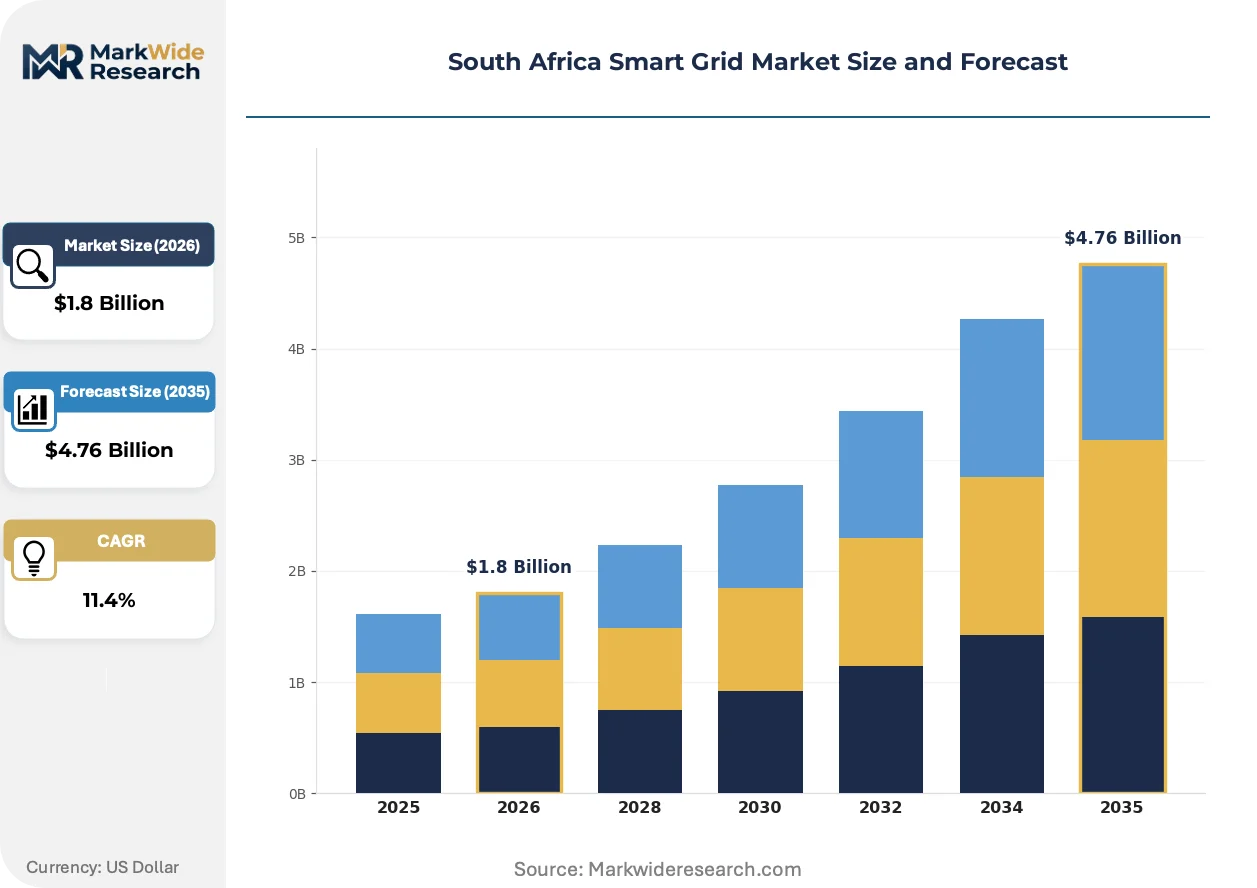
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Meters, Demand Response Systems, Grid Management Software, Advanced Sensors Technology: Communications Network, Distribution Automation, Energy Storage Solutions, Microgrid Technology End User: Utilities, Commercial Facilities, Industrial Plants, Residential Users Application: Energy Management, Load Forecasting, Renewable Integration, Outage Management |
| Companies Covered | Eskom Holdings SOC Ltd, General Electric Company, Siemens AG, Honeywell International Inc, Itron Inc, Schneider Electric SE, ABB Ltd, Landis+Gyr Group AG, Enel Green Power S.p.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Smart Grid Market Evolving Landscape
Digital twin technology and artificial intelligence-driven predictive maintenance are converging to transform how network operators manage aging transmission assets and intermittent renewable feed-in across South Africa's constrained grid.
Edge computing platforms with embedded machine learning inference engines are unifying real-time voltage regulation, fault detection, and demand response orchestration at the distribution transformer level. Mining houses in the Rustenburg platinum belt are piloting these systems to compress outage response times from hours to seconds. This architecture is unifying previously siloed operational technology and information technology domains, forcing traditional automation vendors to restructure their software licensing models.
NERSA's pending amendments to the Electricity Regulation Act will mandate time-of-use tariff structures for all large power users above one megawatt. Industrial consumers in the Sasolburg and Secunda chemical corridors are pre-emptively installing interval metering and energy management systems to optimize load scheduling. The regulatory shift is accelerating procurement of grid management software with native tariff optimization modules.
Power purchase agreements with embedded generation clauses are displacing traditional utility-only supply contracts for manufacturing facilities. Automotive component suppliers in the Eastern Cape are negotiating hybrid arrangements that blend Eskom baseload with on-site solar and battery storage. This contractual evolution is most visible in the Coega Industrial Development Zone, where new entrants require guaranteed power quality for precision manufacturing operations.
South Africa Smart Grid Market Segmentation
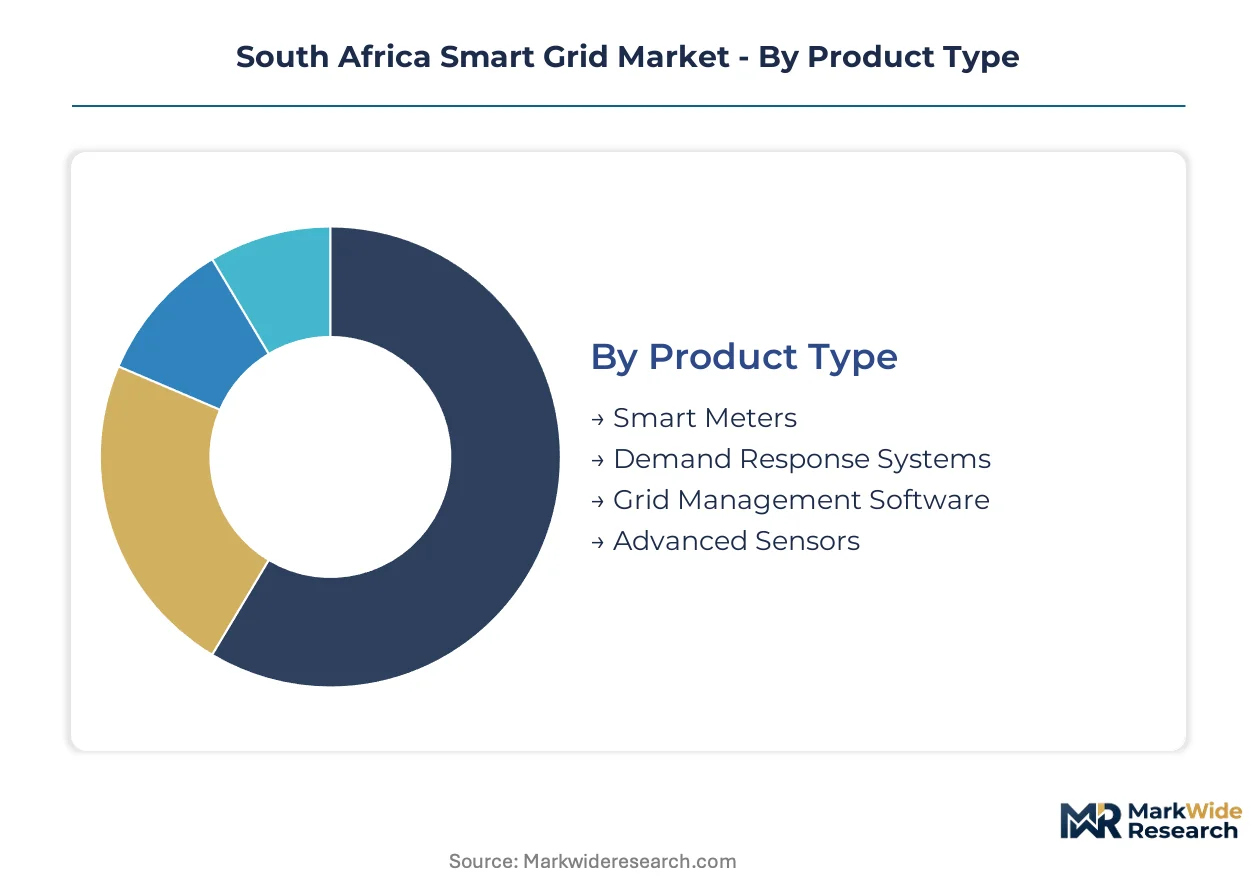
Smart grid deployment in South Africa exhibits distinct purchasing patterns across hardware, software, and service layers. Segmentation reveals where capital concentrates amid Eskom's financial constraints and municipal utilities' divergent procurement capacities.
Product Type:
Standalone metering hardware dominates procurement volumes, while embedded software systems capture recurring revenue streams through licensing and platform subscriptions.
- Smart Meters:Advanced metering infrastructure with two-way communication capability enables real-time consumption monitoring and remote disconnect functionality. Johannesburg and Cape Town municipal utilities are accelerating AMI rollout to reduce revenue leakage and enable time-of-use billing structures mandated by NERSA reforms.
- Grid Management Software:SaaS-delivered platforms unify SCADA integration, distributed energy resource orchestration, and predictive analytics for network operators. Mining houses in the Rustenburg platinum belt and Sasolburg chemical corridor are procuring these systems to optimize load scheduling and islanding protocols during Eskom load-shedding events.
- Demand Response Systems:Automated load curtailment platforms that integrate with industrial control systems to shed non-critical consumption during peak pricing periods.
- Advanced Sensors:Phasor measurement units and environmental monitoring devices providing sub-second grid state visibility for transmission stability applications.
Smart Meters leads volumes today; Grid Management Software is gaining share fastest.
Technology:
Cost tier stratification separates capital-intensive infrastructure investments from modular edge deployments that industrial consumers can self-finance.
- Microgrid Technology:Islanding-capable systems combining distributed generation, energy storage, and intelligent switching to maintain power quality during utility outages. Commercial campuses in Gauteng and data centers in the Western Cape are prioritizing these installations to ensure operational continuity amid persistent grid instability.
- Distribution Automation:Self-healing network architectures with automated fault detection, isolation, and restoration capabilities. Municipal utilities with constrained technical workforces are deploying these systems to compress outage response times without expanding field crew headcount.
- Communications Network:Private LTE, fiber optic, and powerline carrier infrastructure enabling secure data exchange between grid edge devices and central control systems.
- Energy Storage Solutions:Battery energy storage systems co-located with renewable generation or substations to provide frequency regulation and peak shaving services.
Distribution Automation commands the largest capital commitments; Microgrid Technology is expanding most quickly.
End User:
Customer type determines procurement authority—centralized utility purchasing contrasts with fragmented commercial and industrial decision-making across multiple sectors.
- Utilities:Eskom and municipal distributors responsible for transmission and distribution infrastructure modernization, tariff administration, and grid stability services.
- Industrial Plants:Energy-intensive mining, metals, and chemical operations with dedicated electrical engineering teams and capital autonomy to deploy behind-the-meter intelligence. Deep-level platinum and gold mines in the North West province require redundant power architectures to maintain ventilation and hoisting systems during utility failures.
- Commercial Facilities:Shopping centers, hospitals, and office complexes procuring islanding-capable microgrids to protect revenue-critical operations.
- Residential Users:Individual households adopting smart meters through utility-managed programs with limited direct technology selection influence.
Utilities dominate procurement value; Industrial Plants are driving the steepest expansion trajectory.
Application:
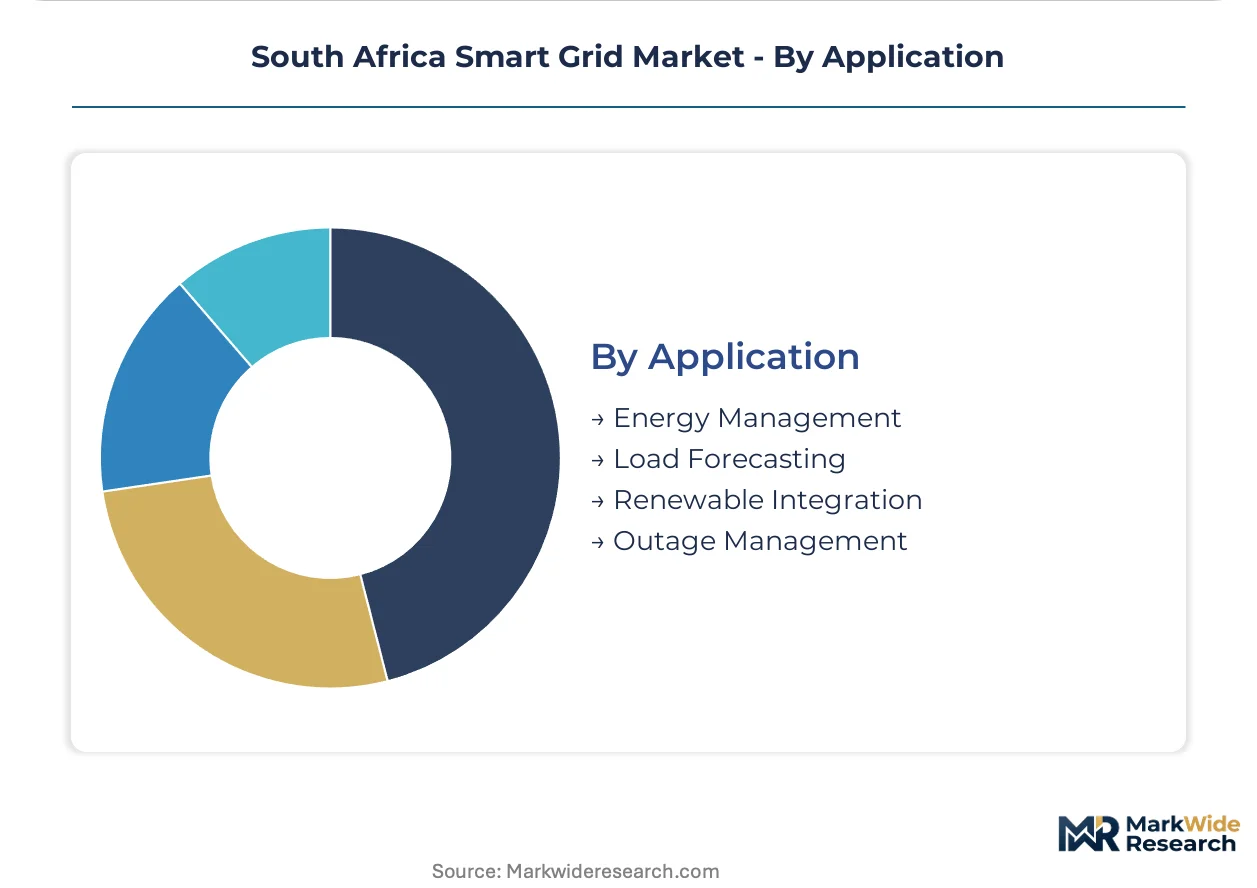
Maturity differentiation separates established operational functions from emerging use cases that require new data infrastructure and organizational capabilities.
- Energy Management:Real-time monitoring, benchmarking, and optimization of consumption patterns across facility portfolios. Industrial consumers in the Secunda petrochemical hub are deploying these systems to pre-empt NERSA's mandatory time-of-use tariff structures.
- Renewable Integration:Grid stabilization services, forecasting, and curtailment management for utility-scale solar and wind feed-in. The Northern Cape solar cluster requires advanced power electronics and grid management software to manage intermittency and voltage fluctuations.
- Load Forecasting:Machine learning-driven demand prediction enabling procurement optimization and maintenance scheduling for network operators.
- Outage Management:Geospatial tracking, crew dispatch optimization, and customer communication platforms for distribution utilities.
Energy Management anchors current deployment; Renewable Integration is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa's smart grid infrastructure traces its modernization lineage to post-apartheid electrification drives in the 1990s, which established the transmission backbone now undergoing digital retrofit. Municipal utilities and industrial consumers across the country's economic heartlands are deploying intelligent systems to manage chronic supply instability and integrate renewable generation clusters.
Gauteng Province
The Johannesburg and Pretoria metropolitan corridors anchor procurement volumes for advanced metering infrastructure and demand response platforms. The National Energy Regulator of South Africa governs tariff reforms that mandate time-of-use billing for large power users. Mining houses in the Rustenburg platinum belt are installing microgrid systems with islanding capability to sustain hoisting and ventilation during Eskom load-shedding events.
Western Cape
Cape Town's municipal utility leads sub-Saharan Africa in smart meter penetration rates and revenue protection systems. The South African Bureau of Standards enforces grid interconnection codes that determine equipment certification for distributed generation. Data centers and commercial campuses in the Stellenbosch-Paarl corridor are procuring redundant power architectures to ensure operational continuity.
Northern Cape
The Upington solar cluster generates the highest irradiation levels in the Southern Hemisphere, driving demand for grid stabilization services and HVDC transmission links. The Renewable Energy Independent Power Producer Procurement Programme channels international climate finance into utility-scale photovoltaic installations. Power electronics specialists are co-locating battery energy storage with substations to manage voltage fluctuations from intermittent solar feed-in.
KwaZulu-Natal
The Durban-Pinetown industrial corridor concentrates chemical and paper manufacturing operations requiring precise load scheduling. NERSA's pending distributed generation licensing amendments are clearing regulatory pathways for behind-the-meter self-supply arrangements. Automotive component suppliers in the Richards Bay industrial zone are negotiating hybrid power purchase agreements blending Eskom baseload with embedded solar generation.
Eastern Cape
The Coega Industrial Development Zone attracts precision manufacturing entrants demanding guaranteed power quality for automated production lines. The South African Reserve Bank's monetary policy influences utility capital expenditure cycles through infrastructure financing cost effects. New industrial tenants are mandating microgrid redundancy and interval metering as standard lease conditions.
South Africa Smart Grid Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the software-services divide, with recurring licensing platforms commanding superior economics to hardware-only suppliers. The market structure bifurcates between integrated automation conglomerates and specialized metering or power electronics pure-plays. Three archetypes dominate: transmission infrastructure modernizers, grid-edge intelligence providers, and distributed energy resource integrators. Competitive intensity centers on strategic partnerships with municipal utilities and technology licensing arrangements that accelerate deployment velocity.
Among European-based industrial conglomerates, Siemens AG and ABB Ltd occupy positions as transmission infrastructure modernizers, while Schneider Electric SE exemplifies the grid-edge intelligence archetype through its automation and software portfolio. General Electric Company anchors the North American contingent with power generation and grid integration capabilities. Honeywell International Inc and Itron Inc represent specialist positioning in metering and demand response domains, with Landis+Gyr Group AG occupying a Swiss-German niche in advanced metering infrastructure. Eskom Holdings SOC Ltd functions as the domestic anchor utility shaping procurement specifications and pilot program design across the national network.
| Leading Market Players |
|---|
| Eskom Holdings SOC Ltd |
| General Electric Company |
| Siemens AG |
| Honeywell International Inc |
| Itron Inc |
| Schneider Electric SE |
| ABB Ltd |
| Landis+Gyr Group AG |
| Enel Green Power S.p.A. |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between SBS-compliant grid equipment and non-certified imports creates divergent pricing corridors that reshape procurement patterns across municipal utilities and industrial self-supply projects. Premium-tier hardware commands substantial markups through guaranteed interoperability with Eskom's transmission protocols, while economy-tier alternatives attract price-sensitive mining contractors prioritizing rapid deployment over long-term service integration.
Pricing Analysis
Project-based contracting with embedded software licensing dominates procurement structures, separating capital-intensive infrastructure investments from recurring SaaS subscriptions for grid management platforms. Price differentiation rests on IEC 61850 protocol certification tier and after-sales technical support bundling. Cost compression in hardware tiers intensifies as rand depreciation inflates imported switchgear and power electronics. Municipal utilities exhibit acute price sensitivity due to constrained capital budgets, while mining houses prioritize uptime guarantees over upfront expenditure.
Supply Chain Analysis
SBS certification requirements for grid interconnection equipment gate market access, forcing suppliers to maintain testing relationships with accredited South African laboratories. Hardware sourcing concentrates in Germany, Switzerland, and China for HVDC converters, advanced metering infrastructure, and power electronics. Component dependencies span silicon carbide semiconductors, lithium-ion battery cells, and fiber-optic communication modules. Single-source vulnerability pervades specialized phasor measurement unit manufacturing. Distribution runs through engineering-procurement-construction contractors serving Eskom and municipal utility frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's smart grid market compounds steadily through persistent load-shedding that forces capital allocation toward resilience infrastructure regardless of macroeconomic cycles.
For Market Incumbents: Acquire specialized IEC 61850 protocol engineering teams to compress project delivery timelines and defend against emerging automation pure-plays. Consolidate substation automation contracts through bundled hardware-software-service offerings that raise switching costs for municipal utilities. Vertical integration into local meter manufacturing mitigates foreign exchange exposure on imported hardware. For New Entrants and Emerging Players: Mid-market pricing gaps between premium European automation systems and basic Chinese imports create entry corridors for certified-but-lower-cost power electronics. Target commercial campus microgrid installations in Gauteng and Western Cape where procurement authority fragments across facility managers rather than centralized utility purchasing. Pursue licensing partnerships with established EPC contractors to bypass direct Eskom qualification barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with grid-edge software platforms capturing recurring revenue from industrial load management and predictive maintenance applications. Long-term viability frames around NERSA's distributed generation reforms expanding addressable market for behind-the-meter intelligence. Monitor SBS cybersecurity standardization timelines as inflection triggers for legacy control system replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Local Meter Manufacturing | Rand hedging through domestic production reduces imported hardware cost volatility for municipal AMI rollouts. |
| IEC 61850 Protocol Certification Investment | SBS-mandated interoperability standards determine equipment eligibility for Eskom transmission contracts. |
| Grid Management Software Licensing Partnership | SaaS platforms capture recurring revenue from mining houses optimizing load scheduling during utility outages. |
| Microgrid Technology Joint Venture | Islanding capability addresses commercial campus demand for operational continuity amid persistent load-shedding. |
| Power Purchase Agreement Structuring | Hybrid contracts blending Eskom baseload with embedded generation attract precision manufacturing tenants in Coega IDZ. |
Research Methodology
Direct dialogue with utility planning officers, IPP project developers, EPC contractors, and grid operators grounded qualitative assessment in operational realities across transmission and distribution infrastructure. Secondary validation drew from NERSA regulatory filings, Eskom integrated reports, South African Reserve Bank monetary policy statements, and renewable energy procurement databases. Bottom-up project pipeline analysis triangulated with top-down macroeconomic modeling to anchor volume and value estimates.
Segmented outputs across product type, technology, end user, and application dimensions calibrated penetration rates and pricing trajectories over the projection horizon. CAGRs derived from econometric relationships between electricity demand growth, renewable capacity additions, and utility capital expenditure cycles. Forecast inputs incorporated NERSA tariff reform timelines, SBS standard evolution, and mining sector electrification intensity.
Caveats apply where NERSA distributed generation licensing amendments, SBS cybersecurity standardization delays, or sustained rand depreciation could materially shift the outlook. Deviation in Eskom's financial restructuring trajectory or international climate finance disbursement schedules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
United States Smart Grid Security Market
Smart Grid
Smart Grid Sensors Market
Smart Grid
Latin America Smart Grid Security Market
Smart Grid
Smart Microgrid Controller Market
Smart Grid
GCC Smart Grid Security Market
Smart Grid
Automated Demand Response Management Systems Market
Smart Grid
Smart Energy Switch Market
Smart Grid
Smart Grid Network Market
Smart Grid
Smart Grid Data Management Market
Smart Grid
Saudi Arabia Smart Grid Market
Smart Grid
Middle-East Smart Grid Network Market
Smart Grid
Smart Grid Technology Market
Smart Grid
China Smart Grid Network Market
Smart Grid
North America Microgrid Market
Smart Grid
UK Smart Grid Network Market
Smart Grid
Global Microgrid As a Service Market