
 Europe Automated Demand Response Market | 2026-2036
Europe Automated Demand Response Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automated Demand Response Market Foresight
Buyer concentration in the Europe Automated Demand Response Market is shifting from fragmented municipal utilities toward large integrated energy retailers. Schneider Electric SE leverages its building automation heritage to anchor software-led demand response portfolios. Siemens AG competes through industrial-grade control platforms that sustain long-term service contracts with German manufacturing clusters.
Automated demand response orchestrates electricity consumption through real-time telemetry, dispatch algorithms, and pre-programmed load curtailment protocols that stabilize grid frequency during supply constraints. The technology dimension splits across Direct Load Control, Dynamic Pricing, Real-Time Pricing, and Automated Control Systems, with Automated Control Systems capturing the deepest margin pools due to embedded software recurring revenues. End User segmentation spans Commercial Buildings, Industrial Facilities, Residential Consumers, and Utilities, where Industrial Facilities lead absolute spending because of penalty exposure under capacity market rules.
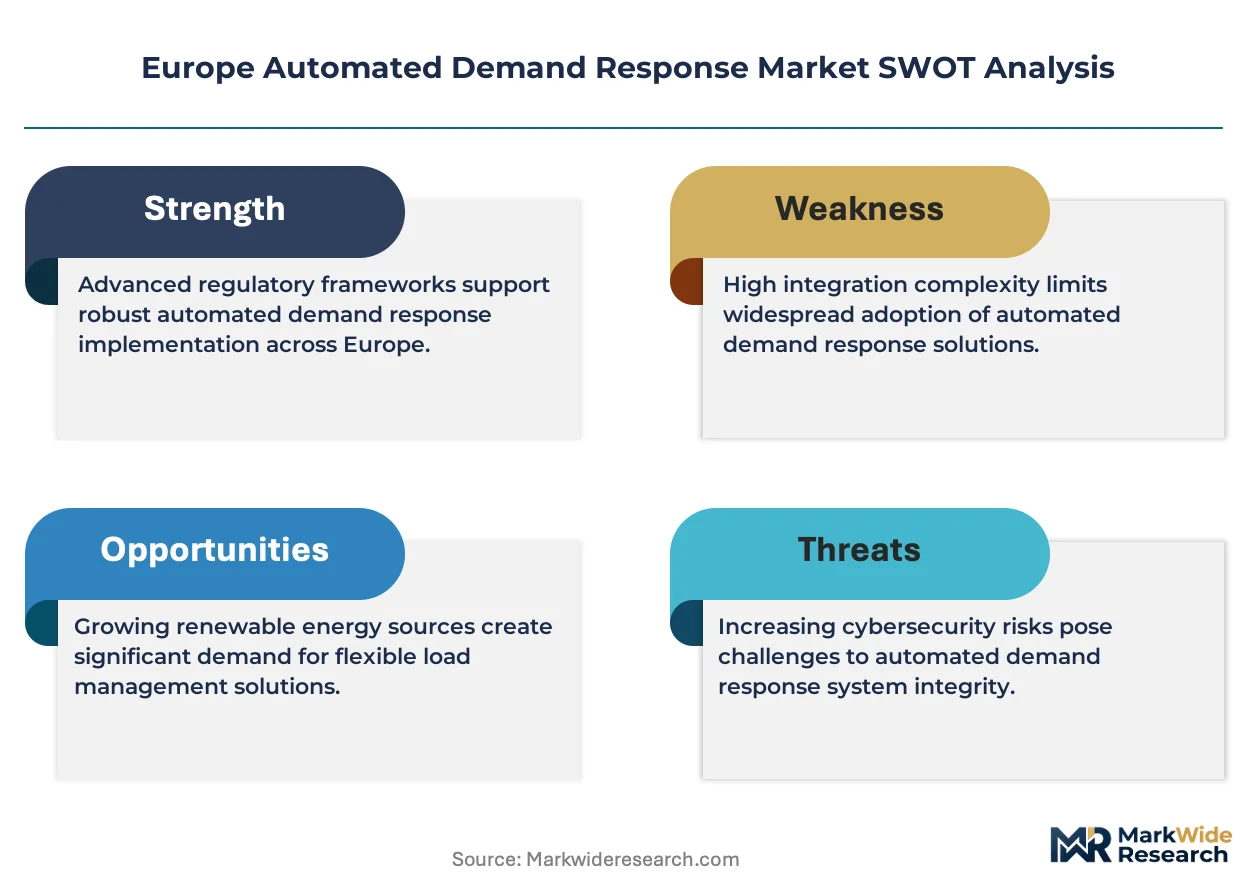
The EU Green Deal and F-Gas Regulation shape product efficiency standards, while national regulators in Germany and France enforce grid codes that mandate minimum response times for enrolled loads. EMA guidelines on cybersecurity for critical infrastructure and GDPR data handling requirements constrain how consumption telemetry flows across borders. Stakeholders must monitor how the EU AI Act classifies autonomous load dispatch algorithms before scaling cross-border platform deployments.
Market Dynamics
Grid code harmonization across EU member states is compressing response-time requirements for enrolled loads, forcing asset owners to upgrade telemetry infrastructure ahead of capacity market deadlines. This regulatory synchronization is reshaping procurement priorities for industrial energy managers.
Growth Catalysts
- EU Green Deal capacity mechanisms:Germany and France now penalize non-responsive industrial loads during system stress events, converting compliance costs into software investment.
- Electrolyzer clusters:Green hydrogen production facilities in the Netherlands and Spain require sub-second load modulation to stabilize renewable curtailment.
- F-Gas Regulation phase-down:Cooling-intensive pharmaceutical manufacturing in Italy faces refrigerant constraints that automated demand response alleviates through thermal load shifting.
Market Restraints
- Substation hardware concentration:Remote terminal units for telemetry depend on single-source semiconductor foundries in East Asia, exposing lead times to geopolitical friction.
- GDPR data localization:Cross-border telemetry flows require sovereign cloud infrastructure that fragments platform economics for multi-country operators.
- Legacy SCADA incompatibility:Brownfield industrial sites in Eastern Europe run proprietary protocols that resist API integration without costly middleware layers.
Strategic Opportunities
- Polish industrial corridor:Steel and chemical clusters near Katowice lack enrolled demand response capacity despite proximity to German balancing markets.
- EU AI Act algorithm classification:Autonomous load dispatch systems certified as limited-risk AI gain faster regulatory clearance for cross-border deployment.
- Building-to-grid aggregation:Commercial real estate in Nordic countries combines thermal inertia with battery storage for stacked revenue streams.
Industry Challenges
- Cyber-physical systems engineering:Utilities struggle to recruit specialists who bridge OT security and machine learning operations for critical infrastructure.
- Interoperability certification delays:Common Information Model compliance testing for new hardware vendors stretches 14-18 months, freezing procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automated Demand Response Market |
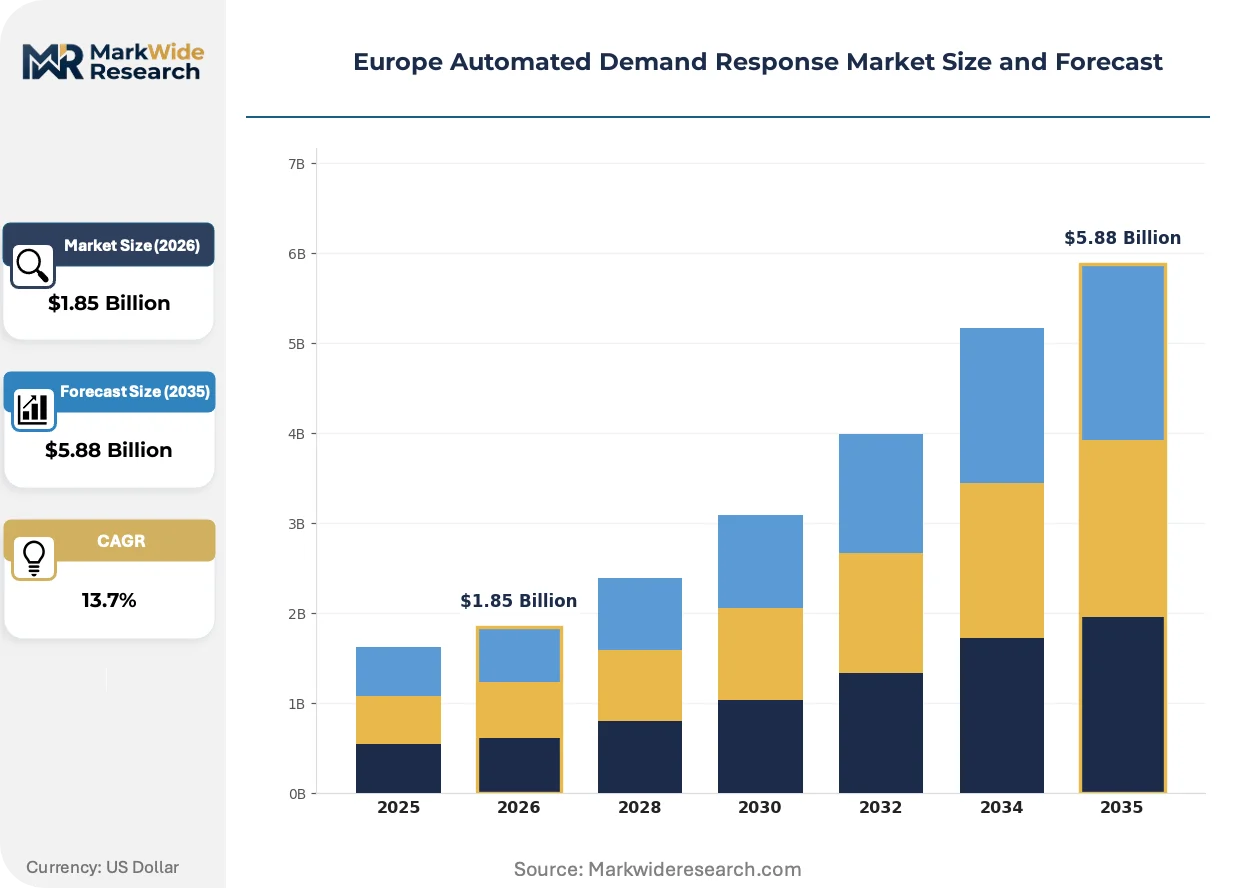
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Direct Load Control, Dynamic Pricing, Real-Time Pricing, Automated Control Systems End User: Commercial Buildings, Industrial Facilities, Residential Consumers, Utilities Application: Demand Management, Energy Optimization, Load Shifting, Peak Load Reduction Service Type: Consulting, Software Solutions, Implementation, Maintenance |
| Companies Covered | Itron Inc., General Electric Company, Eaton Corporation PLC, Mitsubishi Electric Corporation, Hitachi Ltd, Schneider Electric SE, Siemens AG, ABB Group, Enel S.p.A, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automated Demand Response Market Shifts & Advancements
Edge computing architectures are displacing centralized dispatch platforms, enabling millisecond response latencies that unlock new revenue streams for distributed energy resources. This infrastructure shift is redrawing competitive boundaries between automation vendors and grid operators.
Distributed energy resource management systems (DERMS) are unifying photovoltaic inverters, battery storage, and flexible loads under single control planes. German automotive suppliers now mandate DERMS compatibility for new facility construction. The technology is unifying previously siloed asset classes into fungible grid services that compete directly with peaking power plants.
France's national energy regulator has tightened frequency containment reserve requirements to 150 millisecond response windows. Industrial facilities must deploy local edge controllers or forfeit capacity payments. French chemical manufacturers are retrofitting programmable logic controllers with deterministic Ethernet to maintain enrollment eligibility.
Energy service contracts now bundle hardware, software, and performance guarantees into single ten-year agreements. Large retail property owners in the United Kingdom prefer this structure over capital expenditure ownership. This contracting evolution concentrates vendor risk while transferring operational complexity away from facility managers.
Europe Automated Demand Response Market Segmentation
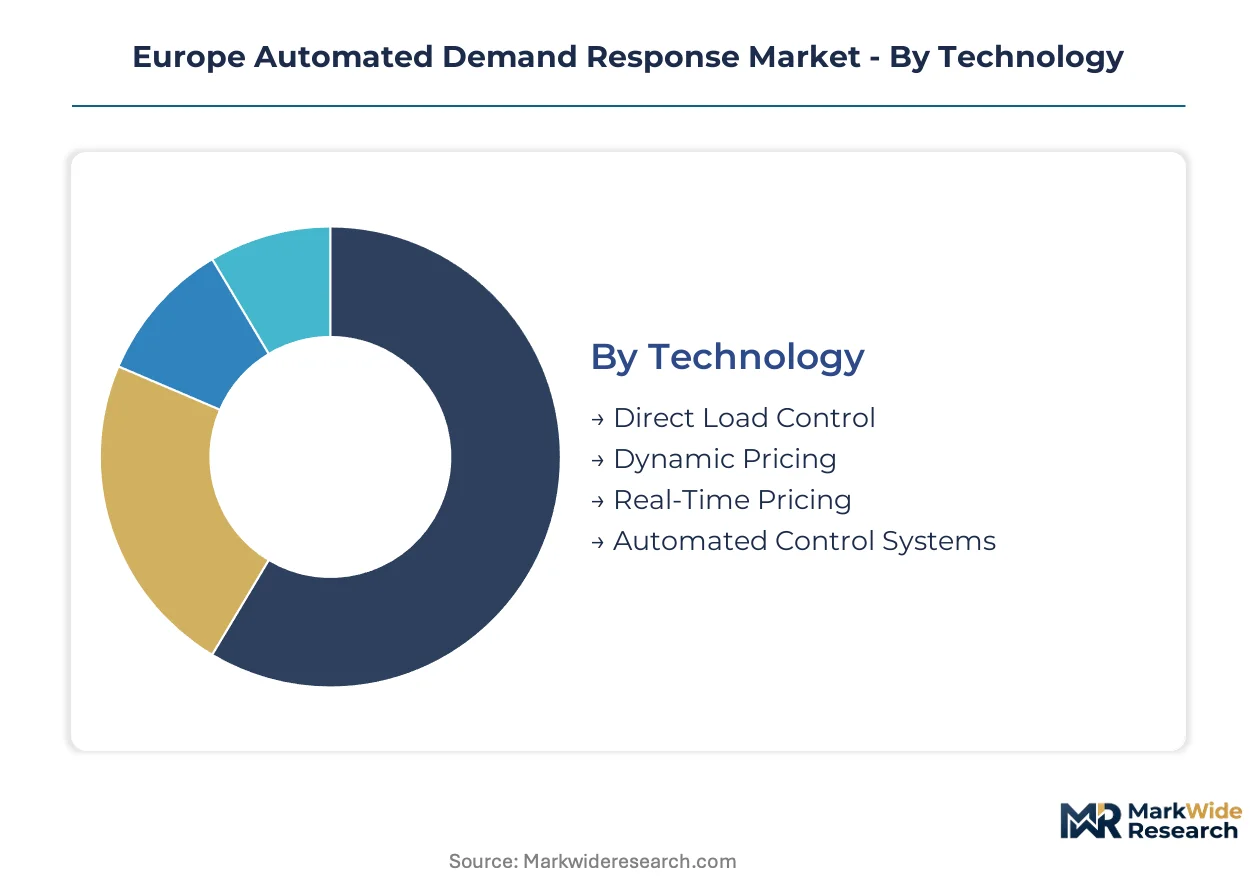
Automated demand response solutions diverge sharply across deployment contexts. Technology choices determine response latency capabilities, while end-user economics dictate contract structures and vendor selection criteria.
Technology:
Buyers differentiate primarily by integration depth and recurring software revenue exposure.
- Automated Control Systems:Embedded software platforms orchestrate load curtailment through pre-programmed protocols and real-time telemetry. German industrial clusters and French chemical manufacturers concentrate procurement here due to EU grid code mandates for sub-second response times. Recurring license revenues sustain vendor margins above hardware-centric alternatives.
- Direct Load Control:Utility-operated switches interrupt power to enrolled appliances during system stress events. Italian municipal utilities and Spanish distribution system operators favor this approach for residential and small commercial pools where capital expenditure minimization outweighs precision requirements.
- Dynamic Pricing:Time-varying rate structures signal economic incentives without automated intervention. Nordic retail energy providers deploy these schemes to commercial real estate with sufficient managerial bandwidth for manual response.
- Real-Time Pricing:Wholesale market indexation exposes end-users to volatile spot prices. Dutch electrolyzer operators and British industrial facilities with flexible process loads leverage this structure for arbitrage revenue.
Automated Control Systems leads volumes today; Real-Time Pricing is gaining share fastest among energy-intensive process industries.
End User:
Contract value scales with load size and penalty exposure under capacity market frameworks.
- Industrial Facilities:Steel, chemical, and automotive manufacturing sites face substantial imbalance penalties under German and French capacity mechanisms. Automated demand response converts compliance costs into grid service revenue streams. Siemens AG and Schneider Electric SE anchor long-term service relationships with Rhineland and Bavarian industrial clusters.
- Commercial Buildings:Retail property owners and office developers prioritize thermal inertia exploitation and battery stacking for ancillary service participation. British real estate investment trusts favor energy service contracts bundling hardware, software, and performance guarantees.
- Residential Consumers:Aggregated pools of smart thermostats and electric vehicle chargers participate through utility-managed programs. French and Italian regulators cap individual consumer exposure to protect vulnerable households.
- Utilities:Distribution system operators procure demand response as non-wires alternatives to substation upgrades. Polish and Romanian grid operators lag in enrollment capacity despite proximity to German balancing markets.
Industrial Facilities dominates absolute spending; Commercial Buildings is expanding most quickly through building-to-grid aggregation models.
Application:
Functional priorities vary by grid stress event type and asset flexibility characteristics.
- Peak Load Reduction:Synchronized curtailment during capacity scarcity events preserves system adequacy. Italian pharmaceutical manufacturers deploy thermal load shifting to maintain cold chain integrity while reducing coincident peak demand.
- Load Shifting:Temporal displacement of electricity consumption aligns industrial processes with renewable generation profiles. Spanish and Dutch electrolyzer clusters require sub-second modulation to stabilize solar and wind curtailment.
- Energy Optimization:Continuous algorithmic adjustment minimizes unit energy costs without grid service participation. German automotive suppliers mandate DERMS-compatible systems for new facility construction.
- Demand Management:Strategic load planning integrates procurement, on-site generation, and flexibility assets under unified control planes. French chemical manufacturers retrofit programmable logic controllers with deterministic Ethernet to maintain frequency containment reserve eligibility.
Peak Load Reduction anchors current deployment; Load Shifting shows steepest expansion trajectory with renewable integration mandates.
Service Type:
Procurement patterns split between capital ownership and performance-contracted outcomes.
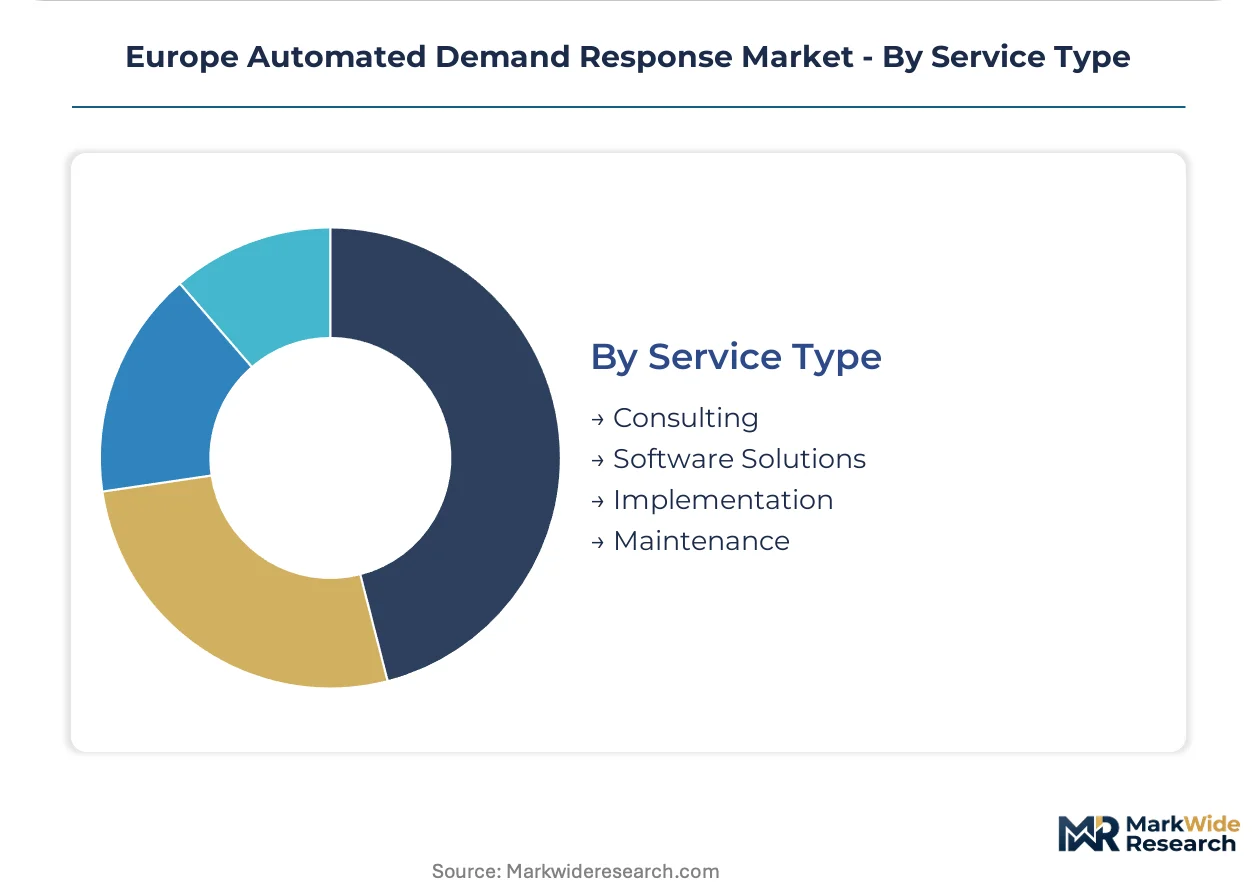
- Software Solutions:Cloud-based dispatch platforms and edge computing architectures enable millisecond response latencies. GDPR data localization requirements fragment platform economics for multi-country operators.
- Implementation:Hardware installation, system integration, and commissioning services bridge brownfield SCADA limitations. Eastern European industrial sites require costly middleware layers for proprietary protocol translation.
- Consulting:Regulatory navigation and grid code compliance advisory supports enrollment in capacity and balancing markets. EU AI Act algorithm classification uncertainty constrains autonomous dispatch system deployment.
- Maintenance:Long-term service contracts sustain telemetry infrastructure and cybersecurity patching. French and German regulators enforce minimum uptime requirements for enrolled loads.
Software Solutions captures the deepest margin pools; Implementation is climbing the fastest with brownfield retrofit acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grid flexibility specialists concentrate in German industrial corridors and French chemical clusters, where EU Green Deal mandates drive software investment. Talent pools in energy systems engineering and OT security sustain platform development across the continent.
Germany
Steel and automotive manufacturers in North Rhine-Westphalia and Bavaria face imbalance penalties under national capacity market rules. The Federal Network Agency enforces sub-second response requirements for enrolled industrial loads. Rhineland chemical clusters anchor Siemens AG service relationships spanning multi-year automation contracts.
France
Chemical manufacturers retrofit programmable logic controllers to maintain frequency containment reserve eligibility. ANSM and national energy regulators tightened response windows to 150 milliseconds for grid-stress events. Lyon and Marseille industrial zones deploy deterministic Ethernet infrastructure at scale.
Italy
Pharmaceutical manufacturers exploit thermal inertia for cold chain integrity during peak load reduction events. The F-Gas Regulation drives refrigerant constraint mitigation through automated load shifting. Milan and Turin cooling-intensive facilities concentrate procurement of Direct Load Control systems.
Netherlands
Electrolyzer operators require sub-second modulation to stabilize renewable curtailment from North Sea wind assets. National grid codes align with EU Green Deal hydrogen production targets. Rotterdam and Eindhoven green hydrogen clusters mandate DERMS-compatible control architectures.
Poland
Steel and chemical facilities near Katowice lack enrolled demand response capacity despite proximity to German balancing markets. National regulators lag in harmonizing grid codes with EU frequency response standards. Silesian industrial corridors represent underpenetrated territory for Automated Control Systems vendors.
Europe Automated Demand Response Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across software-led and hardware-centric market tiers. The vendor base clusters around three strategic archetypes: building automation heritage players, industrial control platform specialists, and utility-scale metering incumbents. Consolidation pressure intensifies as energy service contracts bundle decade-long performance guarantees. Dominant competitive moves include strategic partnerships for edge computing deployment and portfolio diversification into DERMS integration.
Among diversified industrial conglomerates, General Electric Company and Siemens AG occupy positions spanning power generation through grid-edge automation. Schneider Electric SE exemplifies the building automation heritage archetype with software-recurring revenue concentration. Itron Inc. represents the utility-scale metering incumbent tier, while ABB Group and Hitachi Ltd. sit within industrial robotics and power infrastructure crossovers. Mitsubishi Electric Corporation and Eaton Corporation PLC anchor diversified electrical equipment positions. Enel S.p.A. exemplifies the integrated utility operator expanding platform services beyond traditional rate-base structures.
| Leading Market Players |
|---|
| Itron Inc. |
| General Electric Company |
| Eaton Corporation PLC |
| Mitsubishi Electric Corporation |
| Hitachi Ltd |
| Schneider Electric SE |
| Siemens AG |
| ABB Group |
| Enel S.p.A |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between EU AI Act-compliant autonomous dispatch platforms and legacy control systems manifests in both margin structures and semiconductor sourcing strategies. Premium-tier vendors command recurring software revenues through deterministic Ethernet controllers, while commodity hardware providers compete on installation cost for municipal utility contracts.
Pricing Analysis
Capacity additions in German industrial automation corridors are reshaping price floors for Automated Control Systems. Three-tier pricing structure across premium, standard, and economy levels reflects response latency capabilities, with sub-150 millisecond certified platforms commanding service contract premiums. Price differentiation hinges on cybersecurity certification tier and edge computing integration depth. Pricing pressure stems from brownfield retrofit cost compression in Eastern European markets. Municipal utilities in Italy and Spain exhibit highest price sensitivity; German chemical manufacturers prioritize uptime guarantees over capital expenditure minimization.
Supply Chain Analysis
Semiconductor supply for telemetry infrastructure rests on Taiwanese and South Korean foundry capacity, with analog-to-digital converters and deterministic Ethernet chips drawing from concentrated East Asian sources. German and French system integrators source programmable logic controllers from regional assembly hubs. Single-source vulnerability in remote terminal unit chipsets exposes lead times to geopolitical friction. Distribution runs through authorized automation distributors with certified installer networks rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications are hardening as French frequency containment reserve mandates and German grid code deadlines shift procurement toward sub-second response platforms. Premium-tier demand now concentrates among industrial facilities facing penalty exposure under EU Green Deal capacity mechanisms.
For Market Incumbents: Cement long-term service relationships with Rhineland and Bavarian industrial clusters through multi-year automation contracts bundling hardware, software, and performance guarantees. Defend against pure-play DERMS specialists by deepening backward integration into edge computing silicon. Prioritize cybersecurity certification investment to maintain enrollment eligibility under tightening EU AI Act algorithm classification rules. For New Entrants and Emerging Players: Begin with Polish steel and chemical facilities near Katowice, where enrolled demand response capacity lags despite proximity to German balancing markets. Target commercial real estate in Nordic countries for building-to-grid aggregation models combining thermal inertia with battery storage. Pursue energy service contract structures that transfer operational complexity from facility managers to platform operators. For Investors and Strategic Acquirers: Consolidation pressure builds where energy service contracts bundle decade-long performance guarantees and concentrate vendor risk. Five-to-ten year viability favors software-recurring revenue models over hardware-centric installation businesses. Target acquisition archetype: DERMS platform specialists with deterministic Ethernet controller compatibility. Watch EU AI Act final implementing acts on autonomous load dispatch classification as inflection indicator for cross-border deployment scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Deployment | Deterministic Ethernet controllers unlock 150 millisecond frequency containment reserve eligibility under French ANSM mandates. |
| DERMS Platform Integration | Unified control planes for photovoltaic inverters, battery storage, and flexible loads compete directly with peaking power plants. |
| Cybersecurity Certification Program | GDPR-compliant sovereign cloud infrastructure resolves data localization constraints for multi-country operators. |
| Backward Integration into Silicon | In-house production of application-specific integrated circuits reduces exposure to East Asian foundry concentration risk. |
| Energy Service Contract Expansion | Ten-year performance guarantees transfer operational complexity from British retail property owners to automation vendors. |
Research Methodology
Coverage spans Western Europe, Central Europe, and Nordic markets, with primary inputs from each. The analysis combines structured interviews with utility planning officers, industrial energy managers, EPC contractors, and grid operators with secondary validation from FERC-style regulatory filings, IEA grid flexibility reports, and EU Green Deal implementation documents. Bottom-up facility-level enrollment data triangulates against top-down capacity market procurement statistics.
Granularity-level modeling disaggregates revenue across technology tiers, end-user segments, and service type categories throughout the forecast period. Segmentation dimensions include response latency requirements, grid code compliance tiers, and brownfield versus greenfield deployment contexts. CAGRs derive from installed base growth curves and capacity payment rate trajectories. Industry-specific inputs incorporate EU AI Act regulatory timelines and F-Gas Regulation phase-down schedules.
Several conditions sit outside the modeled scope, including unforeseen geopolitical disruptions to semiconductor supply chains and retroactive changes to national grid code harmonization deadlines. Forecasts reflect documented assumptions about regulatory implementation pacing and industrial load growth trajectories. A small set of named triggers warrants ongoing watch: EU AI Act algorithm classification finalization, East Asian foundry capacity allocation shifts, and Polish grid code synchronization with German balancing market standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
Smart Demand Response Market
Smart Grid
South Africa Smart Grid Market
Smart Grid
United States Smart Grid Security Market
Smart Grid
GCC Smart Grid Security Market
Smart Grid
South Korea Smart Grid Network Market
Smart Grid
Smart Grid Communications Market
Smart Grid
Europe Smart Grid Security Market
Smart Grid
Asia-Pacific Demand Response Management Systems Market
Smart Grid
Global Smart Grid Networking Market
Smart Grid
Smart Grid Market
Smart Grid
Smart Grid Network Market
Smart Grid
Microgrid Controller Market
Smart Grid
Smart Grid Home Area Network (HAN) Market
Smart Grid
Automated Demand Response Management Systems Market
Smart Grid
China Smart Power Distribution Systems Market
Smart Grid
Smart Microgrid Controller Market