
 North America Smart Meters Market | 2026-2036
North America Smart Meters Market Size, Share, and Industry Trends Forecast 2026-2036
North America Smart Meters Market Analytics
FERC Order 2222 is recalibrating the cost-of-entry calculus for metering vendors seeking to serve aggregated distributed energy resource markets. Itron leverages its AMI software stack to sustain platform dominance across large investor-owned utilities in the United States. Landis+Gyr anchors its position through integrated RF mesh deployments that extend from meter hardware to head-end systems. Schneider Electric differentiates via edge-computing capabilities embedded directly into smart meter chipsets.
Smart meters are electronic devices that measure and record energy, water, or gas consumption at intervals of an hour or less, communicating data via RF mesh, cellular, or power-line carrier networks to utility operators for billing, outage management, and demand response orchestration. Electric meters occupy the largest revenue pool given grid modernization mandates and vehicle-to-grid interoperability requirements, while AMI technology leads growth by replacing one-way AMR systems with two-way communication architectures that enable real-time pricing and remote disconnect functionality. Water meters represent a concentrated margin opportunity as aging municipal infrastructure across the United States drives precision metering adoption for leak detection and conservation compliance.
The Federal Energy Regulatory Commission shapes wholesale market participation rules for behind-the-meter assets, while state public utility commissions in California, Texas, and New York enforce specific AMI deployment timelines and cybersecurity standards that vendors must satisfy to qualify for procurement. The National Institute of Standards and Technology publishes interoperability frameworks that determine which communication protocols gain market traction. Stakeholders must monitor how state-level integrated resource plans reconcile accelerating electrification with meter upgrade budget cycles.
Market Dynamics
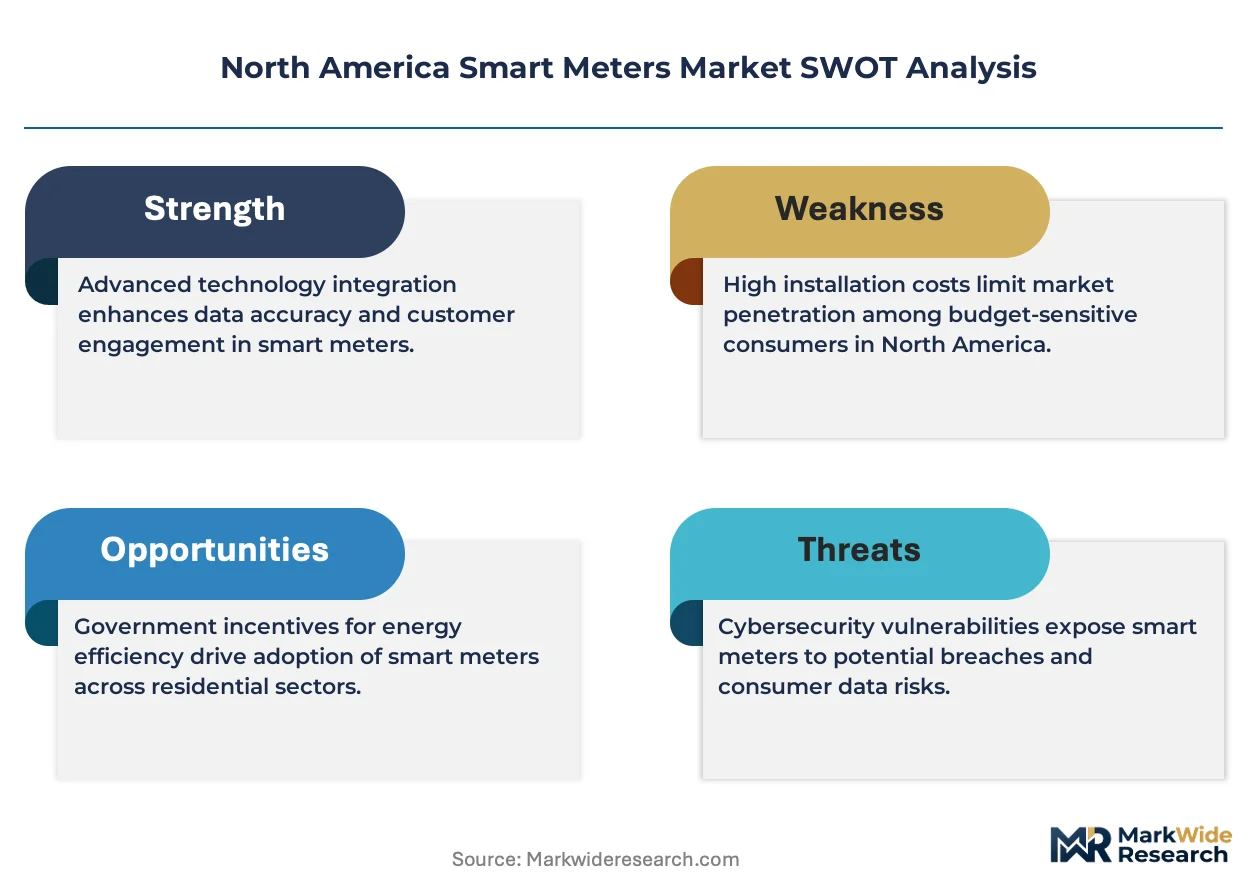
AMI infrastructure replacement cycles are compressing as state renewable mandates force utilities to retire one-way AMR systems before end-of-life, creating a structural demand pull that outpaces traditional capital planning horizons.
Growth Catalysts
- FERC Order 2222:The Federal Energy Regulatory Commission's wholesale market participation rules for aggregated distributed energy resources are mandating bidirectional metering capabilities across RTO territories.
- California's SB 100:The state's 100% clean electricity mandate is accelerating time-of-use rate structure deployment, requiring interval data collection infrastructure statewide.
- RF mesh technology maturation:Self-healing network architectures are reducing deployment costs for rural cooperative utilities previously priced out of AMI adoption.
Market Restraints
- Semiconductor supply concentration:RF transceiver and power management chip fabrication concentrates in Taiwan and South Korea, exposing meter OEMs to geopolitical disruption risk.
- Cybersecurity certification friction:NIST cybersecurity frameworks impose 18-24 month validation timelines that delay product launches and compress vendor margins.
- Copper and lithium pricing volatility:Meter housings and battery backup systems face input cost swings that utilities resist passing through in fixed-price procurement contracts.
Strategic Opportunities
- Texas municipal utility sector:Underpenetrated public power districts serving 4.2 million customers lack AMI coverage and present greenfield deployment potential.
- Water-AMI convergence:Municipal leak detection mandates are creating bundled electric-water meter procurement opportunities with shared network infrastructure.
- Inflation Reduction Act grid grants:Federal cost-sharing programs for disadvantaged communities are expanding addressable market for AMI vendors serving rural cooperatives.
Industry Challenges
- AMI-headend integration complexity:Utilities operating hybrid vendor environments face protocol translation failures between Itron, Landis+Gyr, and Sensus meter populations.
- Field technician skill scarcity:RF network optimization and edge-computing configuration require competencies absent from traditional meter installer workforces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Smart Meters Market |
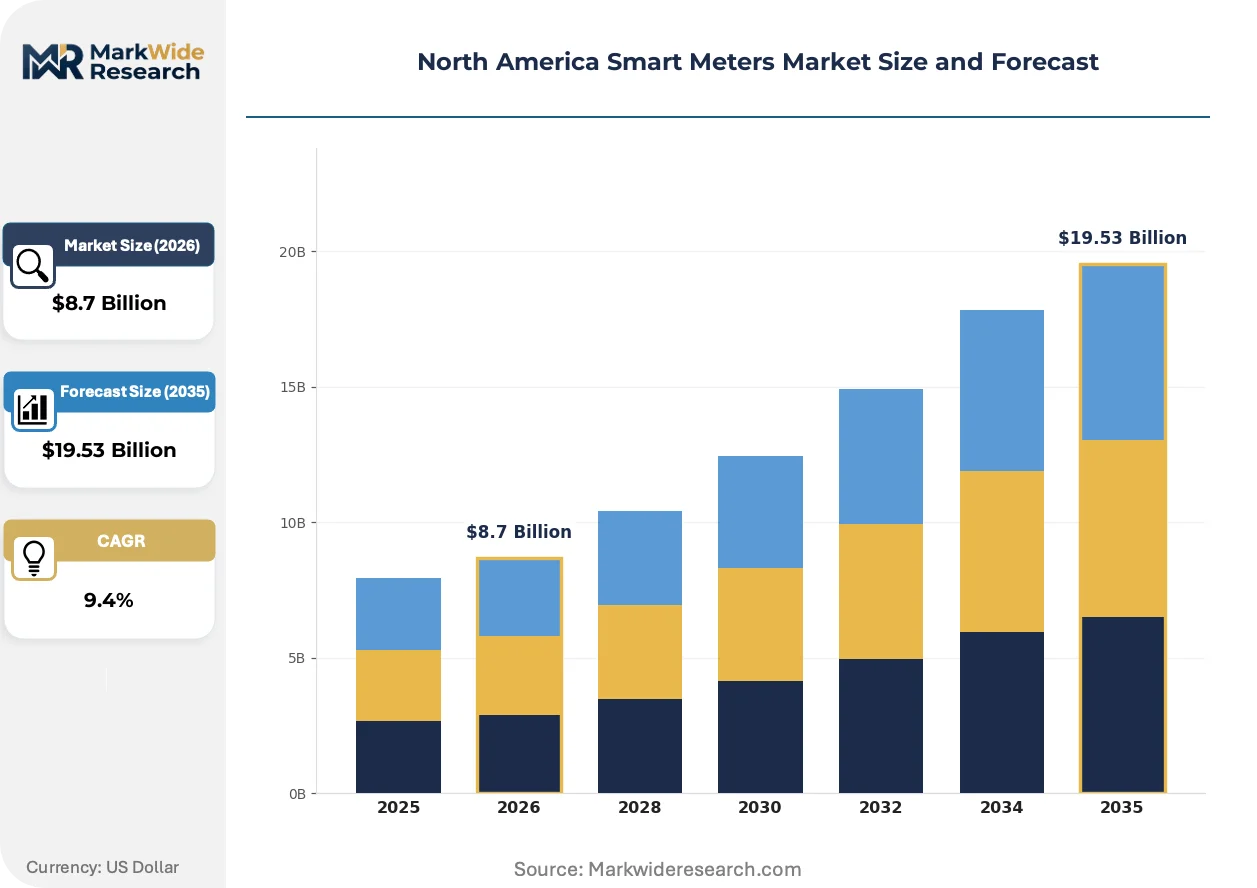
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Meters, Water Meters, Gas Meters, Heat Meters Technology: AMR, AMI, Digital, Analog End User: Utilities, Industries, Residential, Commercial Installation Type: Indoor, Outdoor, On-Grid, Off-Grid |
| Companies Covered | Landis+Gyr, Itron, Xylem (Sensus), Schneider Electric, Honeywell International, Badger Meter, ABB, General Electric, Aclara Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Smart Meters Market Evolving Landscape
Edge-native processing architectures are displacing centralized meter data management systems, compressing latency for real-time grid operations while complicating vendor software roadmaps.
Cellular LTE-M modules are electrifying last-mile connectivity for rural deployments previously dependent on power-line carrier limitations. Electric cooperatives in the Mountain West are adopting these modules at twice the pace of urban IOUs. The technology is electrifying competitive positioning for vendors lacking legacy RF mesh installed bases.
Texas PUC cybersecurity directives are mandating firmware signing and secure boot capabilities that force hardware refresh cycles ahead of functional obsolescence. Meter OEMs must redesign secure element architectures to comply. The residential AMI segment faces the steepest compliance cost absorption.
Performance-based service contracting is displacing traditional hardware procurement across large investor-owned utilities. Duke Energy and Southern California Edison now structure vendor payments around network uptime and data accuracy metrics rather than unit volumes. This shift is most visible in California where rate-case mechanisms accommodate operational expenditure treatment.
North America Smart Meters Market Segmentation
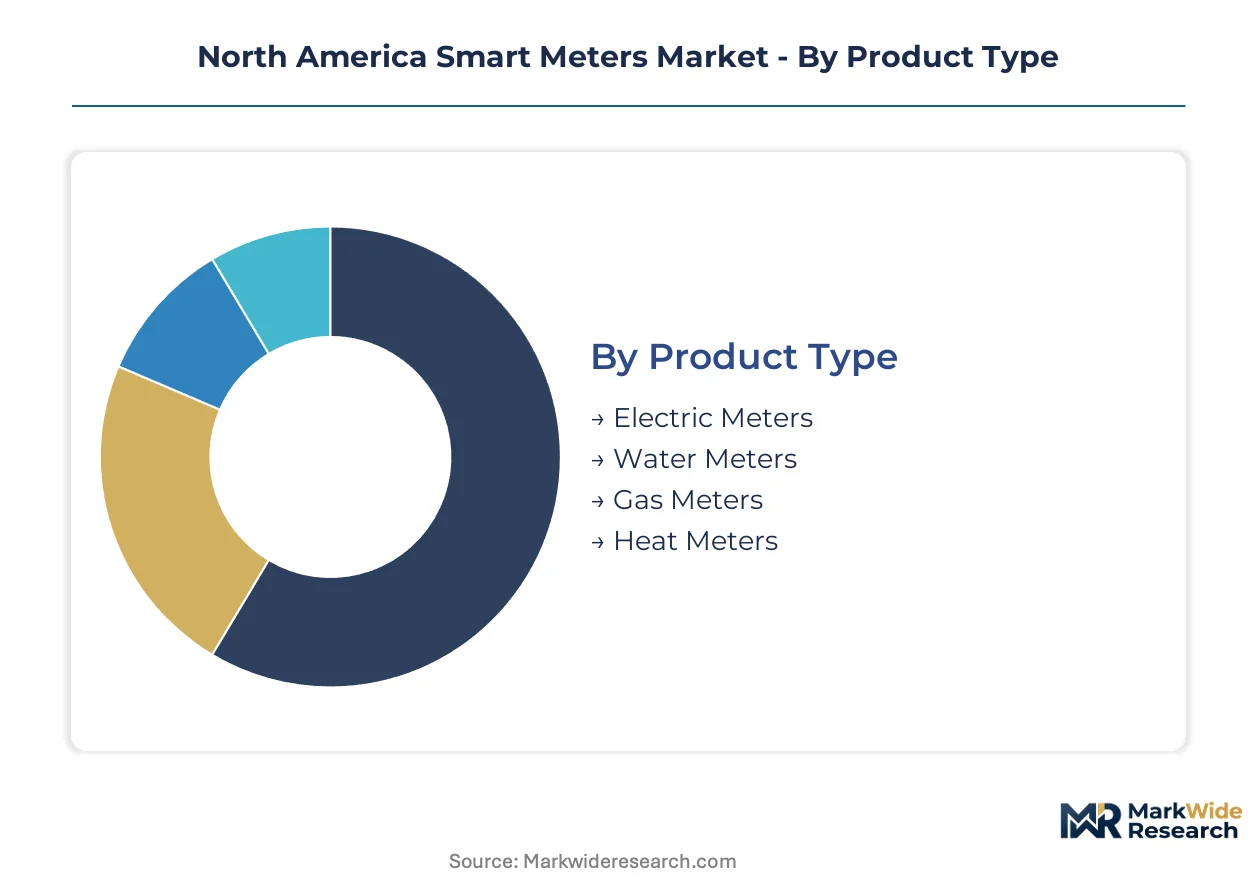
Smart meter procurement patterns diverge sharply across product types and deployment contexts, with utility-scale AMI rollouts commanding fundamentally different technical specifications than municipal water conservation programs. Understanding these segment boundaries clarifies where vendors must configure modular platforms versus purpose-built hardware.
Product Type:
Standardized form factors dominate electric meter deployments, while water and gas applications demand customized housings and sensor calibrations tailored to pressure differentials and flow chemistry.
- Electric Meters:These devices incorporate voltage and current transformers with 0.2% accuracy class measurement circuits, communicating via RF mesh or cellular modules to utility head-end systems. Demand concentrates with investor-owned utilities in California and Texas, where FERC Order 2222 compliance mandates bidirectional interval data collection for distributed solar and battery aggregation.
- Water Meters:Ultrasonic and electromagnetic flow sensors replace mechanical turbine designs, enabling leak detection sensitivity down to 0.1 gallons per minute. Municipal utilities across drought-prone western states drive procurement, with EPA conservation mandates forcing replacement of aging mechanical infrastructure.
- Gas Meters:Diaphragm and rotary displacement designs integrate temperature compensation and remote shutoff valves for safety events. Urban gas distribution utilities in the Northeast prioritize these units for corrosion-prone cast-iron pipeline networks.
- Heat Meters:Pairing temperature differential sensors with volumetric flow measurement, these units serve district heating systems and combined heat-and-power installations. University campuses and military bases in cold-climate states represent the concentrated addressable base.
Leading the category by volume: Electric Meters. Expanding most quickly: Water Meters.
Technology:
Cost tiers separate legacy one-way systems from two-way AMI architectures, with digital transitional designs occupying a narrowing middle band as utilities accelerate end-of-life replacements.
- AMI:Advanced Metering Infrastructure deploys RF mesh or cellular networks enabling real-time pricing signals, remote disconnect, and outage detection. Investor-owned utilities in Ontario and California structure procurement around network uptime guarantees rather than hardware unit costs.
- AMR:Automated Meter Reading systems transmit consumption data via drive-by or fixed-network one-way communication. Rural electric cooperatives in the Mountain West retain these systems where capital constraints delay full AMI conversion.
- Digital:Solid-state measurement without network connectivity serves as a transitional bridge technology. Small municipal utilities in Texas deploy these units where AMI funding cycles remain unfunded.
- Analog:Electromechanical dial meters persist in legacy installations and off-grid applications. Remote Alaskan communities and certain Native American tribal utilities maintain these units where electronic component reliability concerns dominate.
Dominating utility capital plans: AMI. Facing steepest decline: Analog.
End User:
Volume scale versus margin structure defines the customer landscape, with residential deployments offering unit economics that industrial applications cannot match despite higher per-meter pricing.
- Utilities:Vertically integrated generation, transmission, and distribution operators deploy AMI at scale across millions of endpoints. State renewable mandates in California and New York compress procurement timelines beyond traditional capital planning cycles.
- Residential:Single-family and multi-family dwellings represent the volume anchor, with time-of-use rate structures driving interval data requirements. Texas retail electric providers bundle smart meter deployment with competitive supply contracts.
- Commercial:Small-to-medium enterprises demand sub-metering granularity for tenant billing and demand charge management. Shopping malls and office complexes in Ontario prioritize these installations for LEED certification compliance.
- Industries:Heavy manufacturing and data center operations require power quality monitoring and harmonics measurement beyond standard consumption tracking. Petrochemical facilities along the Gulf Coast drive specifications for hazardous location certifications.
Capturing largest deployment volumes: Utilities. Commanding highest per-unit prices: Industries.
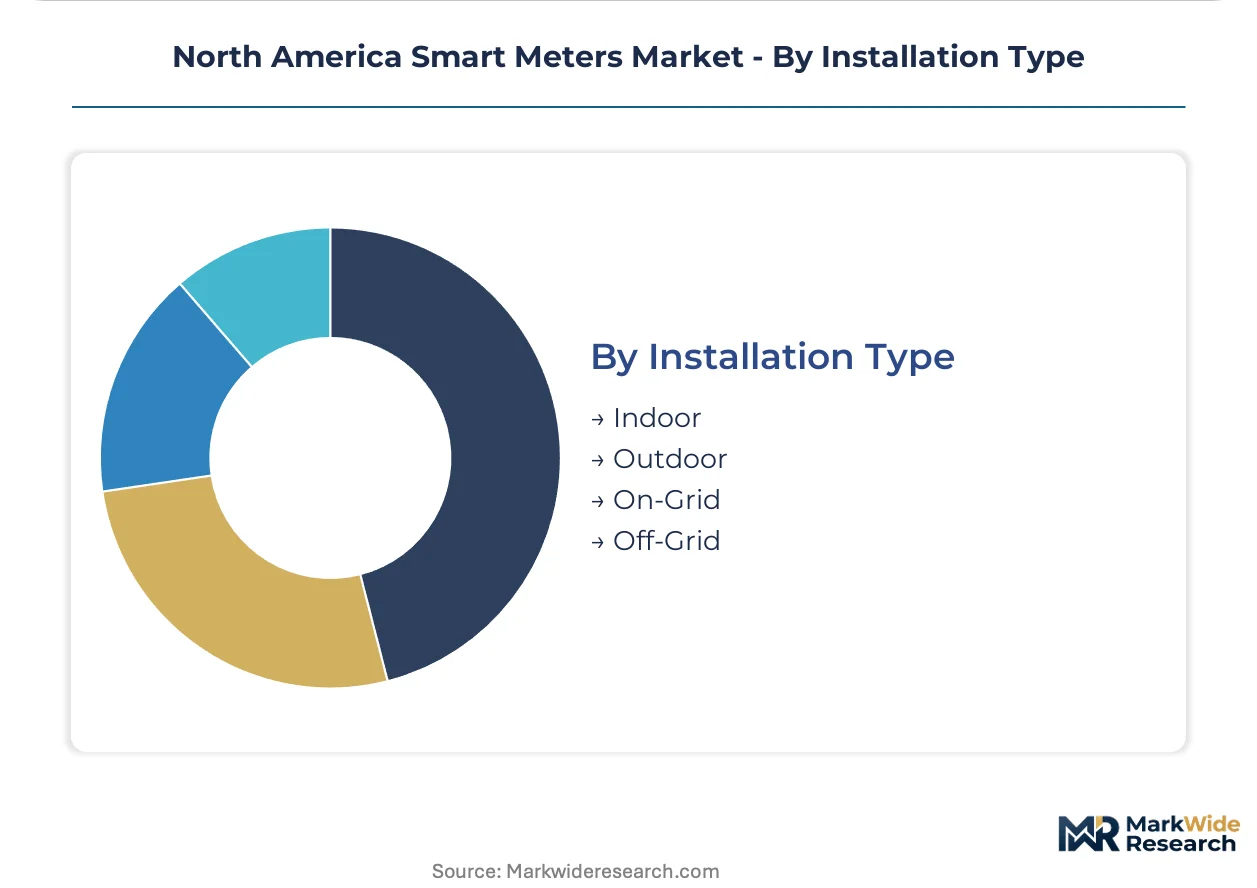
Installation Type:
Environmental exposure ratings and grid interconnection status determine housing specifications, with outdoor and on-grid configurations representing the procurement mainstream.
- Outdoor:NEMA 4X or IP68 enclosures withstand temperature extremes, moisture ingress, and UV degradation. Utilities across the Southwest specify these units for desert exposure and monsoon precipitation events.
- Indoor:Reduced environmental sealing requirements apply to basement, utility room, and meter closet installations. Multi-family residential buildings in dense urban cores concentrate this demand.
- On-Grid:Meters interconnect with centralized distribution infrastructure, requiring synchronization with utility voltage and frequency standards. The contiguous United States and Canadian provinces standardize around these configurations.
- Off-Grid:Standalone microgrid and remote cabin installations operate without utility interconnection, often pairing with solar-battery systems. Remote Alaska and northern Canadian territories present this specialized application.
Representing procurement majority: Outdoor. Narrowing to niche status: Off-Grid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Inflation Reduction Act's grid modernization tax credits are concentrating smart meter procurement across federally designated energy communities in the United States and Canada. FERC Order 2222 implementation timelines vary by regional transmission organization, creating asynchronous deployment waves across North American utilities.
United States
California's SB 100 clean electricity mandate and Texas PUC cybersecurity directives are compressing AMI replacement cycles ahead of functional end-of-life. FERC Order 2222 mandates bidirectional metering capabilities across RTO territories including PJM, ERCOT, and CAISO. The California-Texas corridor concentrates procurement volume, with investor-owned utilities in both states accelerating time-of-use rate infrastructure deployment.
Canada
Ontario's smart meter initiative and federal carbon pricing mechanisms are driving provincial utility capital plans toward two-way communication architectures. The Ontario Energy Board enforces specific AMI deployment timelines and data privacy standards that vendors must satisfy. Toronto and Ottawa metropolitan utilities are consolidating procurement to achieve scale economies in RF mesh network deployment.
Mexico
Comisión Federal de Electricidad modernization programs and distributed generation interconnection rules are creating demand for interval metering in industrial zones. The national energy regulator mandates smart metering for medium-voltage customers above specified consumption thresholds. Monterrey and Guadalajara manufacturing corridors are deploying AMI infrastructure to support industrial demand response programs.
North America Smart Meters Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware, software, and integrated system tiers. The vendor base organizes around three strategic archetypes: full-stack AMI platform providers, meter hardware specialists with RF mesh expertise, and edge-computing technology integrators. Market consolidation proceeds through strategic partnerships between meter OEMs and utility software vendors, alongside vertical integration into semiconductor sourcing.
Within the full-stack platform tier, Itron and Landis+Gyr exemplify integrated AMI providers spanning meter hardware through head-end software systems. Schneider Electric occupies a position at the technology convergence vector, embedding edge-computing capabilities directly into meter chipsets. These three companies represent distinct strategic postures: RF mesh network dominance, cellular module integration, and distributed intelligence architecture respectively.
| Leading Market Players |
|---|
| Landis+Gyr |
| Itron |
| Xylem (Sensus) |
| Schneider Electric |
| Honeywell International |
| Badger Meter |
| ABB |
| General Electric |
| Aclara Technologies |
| Others |
Value Network & Pricing Analysis
Copper futures on the COMEX exchange cascade through smart meter manufacturing costs, compressing margins for RF mesh module producers while utilities resist pass-through clauses in fixed-price procurement contracts. This commodity-price transmission mechanism stratifies vendor tiers based on their captive sourcing arrangements and contract hedging capabilities.
Pricing Analysis
Lead-time premiums of 30-45 days command pricing advantages for AMI vendors holding buffer inventory of RF transceivers and power management semiconductors. Three-tier pricing structure across NIST-certified premium, state-compliant standard, and municipal economy levels separates Itron and Landis+Gyr platform bundles from single-product competitors. Cost compression in the residential segment is intensifying because Texas PUC cybersecurity mandates force premature hardware refresh cycles. Rural electric cooperatives exhibit highest price sensitivity due to capital constraint structures, while investor-owned utilities in California prioritize network uptime guarantees over unit cost minimization.
Supply Chain Analysis
Direct-to-utility channels handle hyperscale deployments across California and Texas investor-owned utilities, while distribution partnerships serve municipal utilities and rural cooperatives with fragmented procurement authority. Taiwan and South Korea anchor semiconductor fabrication for RF transceivers and secure element chipsets, with Mexico and Vietnam housing final meter assembly operations. The supply chain draws from copper sheet for housings, lithium cells for battery backup systems, and epoxy resins for encapsulation. Single-source vulnerability concentrates in Taiwan-based foundries serving NIST cybersecurity-certified secure elements. Distribution runs through authorized utility distributors and direct OEM sales forces with long-term service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Smart Meters Market sits at an AMI-versus-AMR technology transition phase, with two-way communication architectures displacing one-way drive-by systems as FERC Order 2222 mandates bidirectional metering capabilities across RTO territories.
For Market Incumbents: Anticipate margin compression from cellular module specialists lacking legacy RF mesh bases by deepening backward integration into secure element semiconductor sourcing. Prioritize NIST cybersecurity certification pre-positioning ahead of Texas PUC and California CPUC rulemakings to defend procurement eligibility. Platform consolidation around integrated AMI software stacks represents the priority defensive lever against modular competitors. For New Entrants and Emerging Players: Enter via Texas municipal utility districts serving 4.2 million customers with underpenetrated AMI coverage, where incumbent platform switching costs remain immature. Target bundled electric-water meter procurement opportunities in drought-prone western states leveraging shared network infrastructure economics. A cellular LTE-M module specialization strategy bypasses RF mesh patent thickets while addressing rural cooperative connectivity gaps. For Investors and Strategic Acquirers: Distressed-cycle entries favor edge-computing technology integrators with firmware signing capabilities in California and Texas, where cybersecurity compliance premiums compress valuations for non-compliant vendors. Long-term viability across the projection horizon hinges on AMI-headend software integration depth rather than hardware unit scale. Watch FERC Order 2222 implementation timelines across PJM, ERCOT, and CAISO as inflection indicators for aggregated distributed energy resource metering demand.| Strategic Initiative | Industry Significance |
|---|---|
| RF Mesh Network Expansion | Landis+Gyr leverages self-healing architectures to reduce rural cooperative deployment costs below cellular alternatives. |
| Edge-Computing Chipset Integration | Schneider Electric embeds distributed intelligence directly into meter hardware, displacing centralized data management systems. |
| Cellular LTE-M Module Adoption | Electric cooperatives in the Mountain West adopt cellular modules at twice the pace of urban IOUs for last-mile connectivity. |
| Performance-Based Service Contracting | Duke Energy and Southern California Edison structure vendor payments around network uptime rather than hardware volumes. |
| Water-AMI Convergence Bundling | Municipal leak detection mandates create shared infrastructure opportunities for electric-water meter procurement combinations. |
Research Methodology
FERC Order 2222 dockets, EIA Form 861 utility data, and NIST cybersecurity framework publications formed the secondary backbone of this analysis, cross-referenced with primary interviews with utility planning officers, AMI procurement managers at investor-owned utilities, RF network engineers at rural cooperatives, and regulatory affairs leads at meter OEMs. Bottom-up and top-down triangulation validated deployment volume estimates against state integrated resource plan filings and federal infrastructure grant disclosures.
Bottom-up modeling anchored volume projections on utility-specific AMI deployment schedules across California, Texas, and Ontario, while top-down cross-checks assessed market size against federal grid modernization appropriations and state renewable mandate compliance timelines. Segmentation dimensions included product type, communication technology, end-user category, and installation environment. CAGRs were derived from regression analysis of historical replacement cycles against regulatory compliance deadlines. Key forecast inputs incorporated semiconductor lead time fluctuations and copper price volatility indices.
Revisions become necessary when Taiwan semiconductor foundry capacity constraints intensify, FERC Order 2222 implementation timelines shift across RTO territories, or state cybersecurity mandates accelerate beyond current hardware refresh cycles. Forecasts reflect assumptions about federal infrastructure funding continuity and state renewable mandate enforcement intensity. Periodic stress-testing of base assumptions against commodity price shocks and geopolitical supply disruptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Global Smart Energy Meters Market
Smart Meters
Industrial Power Monitoring System Market
Smart Meters
Europe Smart Water Meter Market
Smart Meters
AMI Smart Water Meter Market
Smart Meters
Smart Gas Metering Market
Smart Meters
Europe Water Meter Market
Smart Meters
Smart Water Metering Market
Smart Meters
North America Gas Meter Market
Smart Meters
United States (US) Water Meter Market
Smart Meters
Gas Meters Market
Smart Meters
Asia Pacific Water Meter Market
Smart Meters
Europe Smart Meters Market
Smart Meters
Commercial Non IC Card Gas Smart Meter Sales Market
Smart Meters
United States (US) Residential Smart Meters Market
Smart Meters
Middle East Distribution Meter Market
Smart Meters
Single-Phase Anti-Theft Meter Market