
 Asia-Pacific Demand Response Management Systems Market | 2026-2036
Asia-Pacific Demand Response Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Demand Response Management Systems Market Outlook
The capital-intensity divergence between cloud-native software providers and legacy hardware-integrated platforms is bifurcating competitive dynamics across the region. Schneider Electric leverages its integrated building-to-grid software stack to sustain premium positioning in Australia's commercial building segment. Siemens anchors its regional footprint through localized manufacturing partnerships that dominate utility-scale deployments in South Korea and Taiwan.
Demand Response Management Systems comprise software platforms, communication infrastructure, and control algorithms that enable utilities and grid operators to modulate electricity consumption in response to supply conditions, typically achieving load reductions within 15-minute dispatch intervals. These systems integrate real-time metering data with automated control signals to balance grid frequency and defer capacity investments. Smart Meters represent the most mature technology segment with established deployment pipelines, while Software Solutions capture expanding margin pools as utilities shift from hardware procurement to subscription-based analytics. The Industrial Sector end-user category generates the highest per-site revenue volumes, though Commercial Buildings offer faster deployment cycles due to standardized building management system interfaces.
Japan's METI enforces stringent grid stability standards that mandate demand response participation from large industrial consumers, while Australia's AEMO operates capacity markets with explicit demand-side bidding mechanisms. China's National Energy Administration implements provincial pilot programs that require state-owned utilities to procure third-party demand response services. Stakeholders must monitor how carbon border adjustment mechanisms and cross-border electricity trading protocols reshape procurement criteria for system integrators.
Market Dynamics
China's dual carbon goals and India's CEA mandates are compressing procurement timelines for automated demand response infrastructure across Southeast Asian utilities managing grid volatility from renewable intermittency.
Growth Catalysts
- CEA Mandates:India's Central Electricity Authority requires large industrial consumers to participate in demand response programs, forcing steel and cement plants to install automated load modulation systems.
- Industrial Manufacturing Clusters:Japan's automotive and electronics corridors require precise frequency balancing, creating concentrated demand for sub-15-minute dispatch interval capabilities.
- Smart Meter Pipelines:Australia's state-level rollout programs provide the metering backbone enabling real-time consumption visibility for commercial building demand response aggregation.
Market Restraints
- Silicon Supply Concentration:Communication chipset procurement depends on concentrated East Asian foundry capacity, exposing DRMS vendors to input cost volatility and allocation constraints.
- Legacy SCADA Integration:South Korean and Taiwanese utility-scale deployments face technical friction retrofitting 1990s-era control systems with cloud-native demand response platforms.
- Cross-Border Certification:Fragmented electromagnetic compatibility standards between ASEAN member states create regulatory friction for hardware-integrated platform vendors seeking regional scale.
Strategic Opportunities
- Vietnam Industrial Zones:Underpenetrated northern manufacturing corridors present white space for demand response providers as state utility EVN expands time-of-use pricing pilots.
- Building-to-Grid Convergence:Integration of HVAC control algorithms with battery storage dispatch logic creates new service revenue streams for commercial building aggregators.
- AEMO Capacity Markets:Australia's explicit demand-side bidding mechanisms provide regulatory tailwinds for virtual power plant operators seeking dispatch revenue streams.
Industry Challenges
- Cybersecurity Certification:IEC 62351 compliance timelines for critical infrastructure protection delay platform deployment approvals at Japanese utilities.
- Legacy Protocol Translation:Integration complexity with proprietary Modbus and DNP3 implementations in existing industrial control systems extends implementation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Demand Response Management Systems Market |
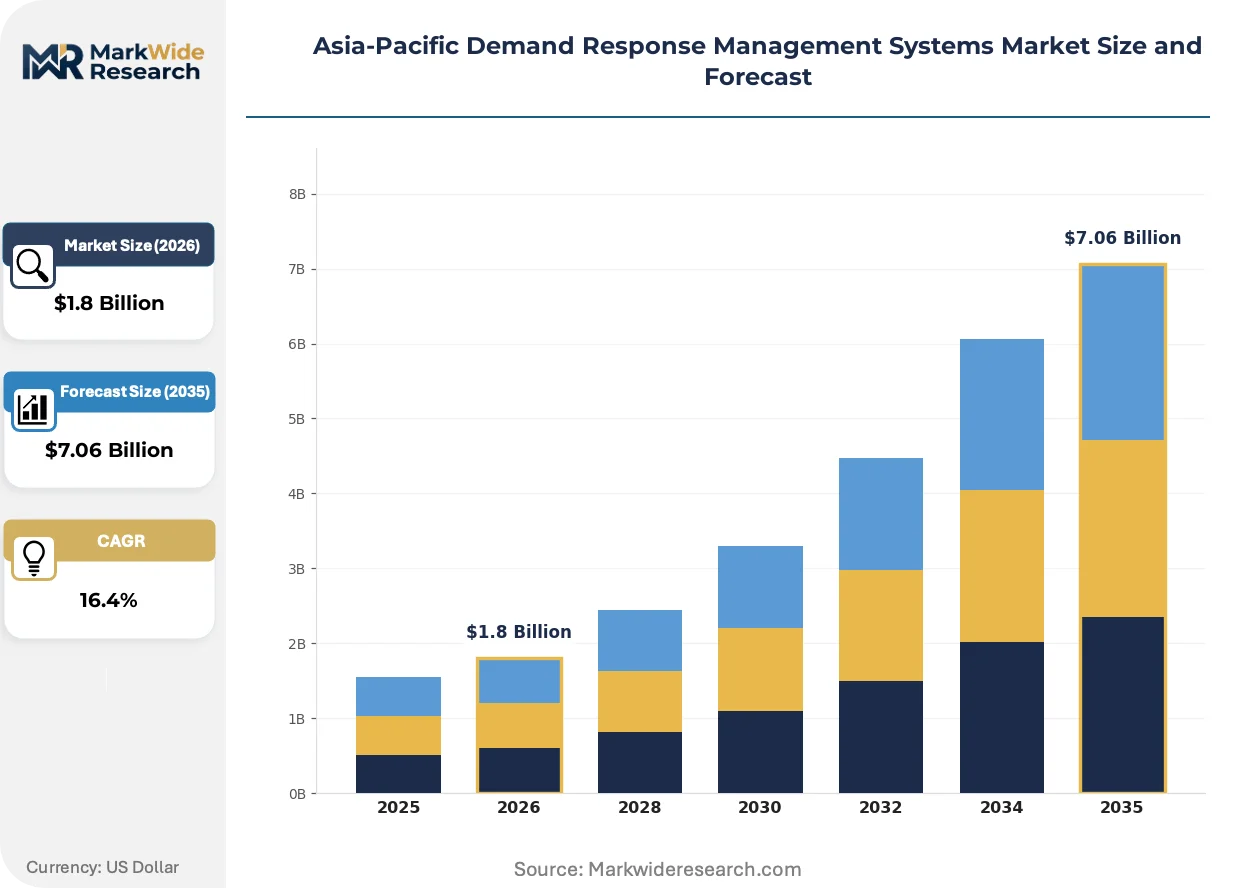
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Smart Meters, Automated Systems, Software Solutions, Demand Forecasting End User: Utilities, Industrial Sector, Commercial Buildings, Residential Users Service Type: Consulting Services, Implementation Services, Maintenance Services, Support Services Application: Demand Response, Load Management, Energy Efficiency, Peak Shaving |
| Companies Covered | Schneider Electric, Siemens AG, Hitachi Ltd, Mitsubishi Electric Corporation, General Electric Company, ABB, Eaton Corporation PLC, Honeywell International Inc., Johnson Controls International PLC, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Demand Response Management Systems Market Strategic Shifts
Cloud-native software architectures are displacing on-premise hardware stacks, while AI-driven load forecasting compresses dispatch preparation windows and regulatory carbon accounting tightens procurement criteria.
Edge computing nodes with embedded machine learning inference are decomposing centralized control architectures in industrial demand response deployments. Japanese steel mills and petrochemical complexes are adopting these distributed controllers to achieve sub-second response latency. This topology is decomposing traditional hub-and-spoke communication models, enabling peer-to-peer load coordination that reduces backhaul bandwidth requirements.
METI's grid stability standards now mandate cybersecurity certification for all demand response communication pathways serving critical infrastructure. Japanese utilities must demonstrate IEC 62351 compliance before commissioning new industrial load modulation contracts. Heavy manufacturing segments in the Keihin and Chukyo industrial belts are responding by consolidating vendor relationships with platforms pre-certified under the updated framework.
Subscription-based analytics procurement is displacing perpetual software licenses across Australian commercial building portfolios. Facility managers in Sydney and Melbourne now prioritize platforms with guaranteed forecasting accuracy SLAs over upfront capital expenditure models. This preference shift concentrates contract awards with vendors offering outcome-linked pricing structures.
Asia-Pacific Demand Response Management Systems Market Segmentation
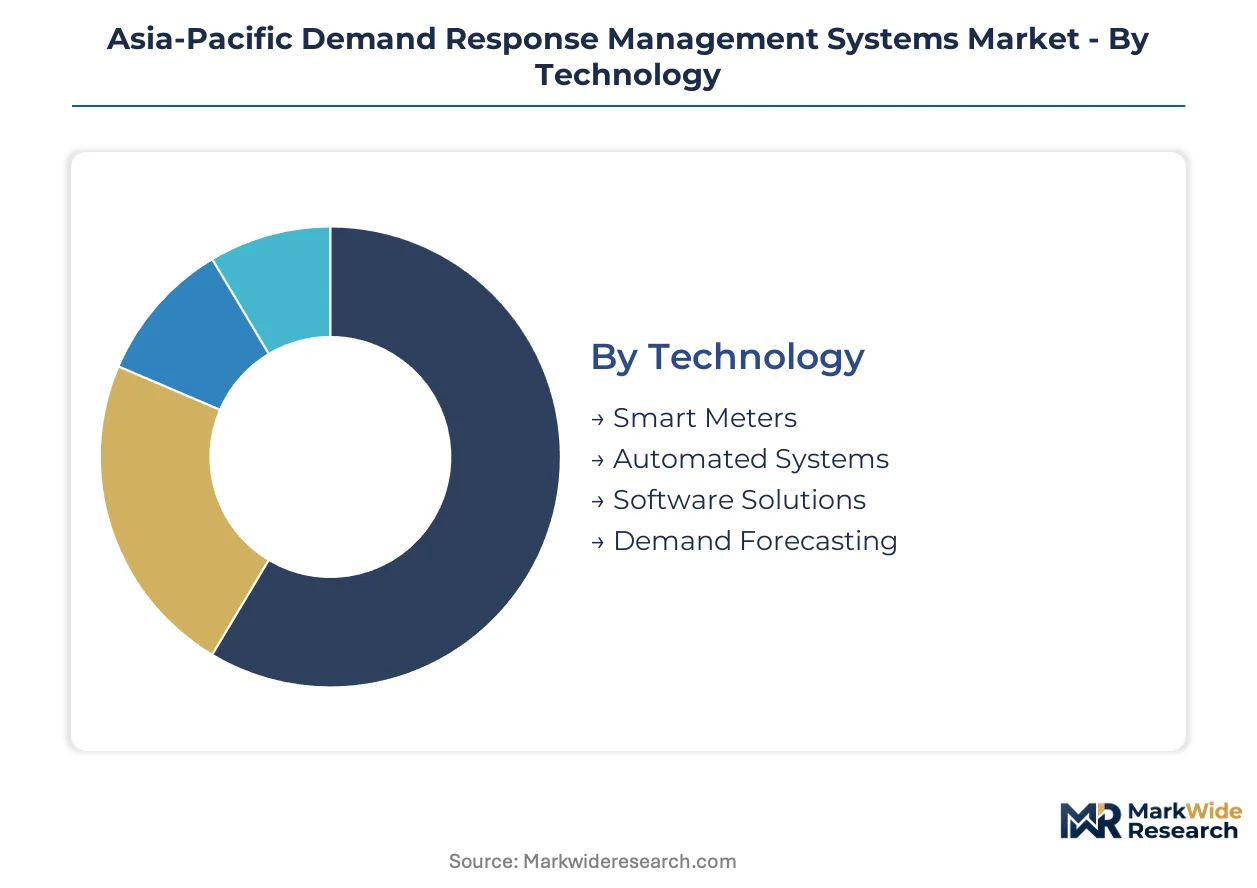
Segmentation reveals how procurement patterns diverge across the Asia-Pacific Demand Response Management Systems landscape. Technology choices determine capital deployment timelines, while end-user categories dictate service model preferences and margin structures.
Technology:
Smart Meters dominate procurement pipelines in Australia and Japan where state-mandated rollout programs create concentrated demand, while Software Solutions gain traction in India's industrial corridors as CEA compliance deadlines approach.
- Smart Meters:These devices capture real-time consumption data through advanced metering infrastructure, transmitting interval readings to utility control centers. Australian state governments in New South Wales and Victoria are accelerating deployment to enable time-of-use pricing for commercial aggregators.
- Software Solutions:Cloud-native platforms deliver predictive analytics and automated dispatch orchestration via subscription models. Japanese steel mills in the Keihin industrial belt prioritize these systems for sub-15-minute frequency response compliance under METI grid stability mandates.
- Automated Systems:Hardware-integrated controllers execute load modulation commands without human intervention.
- Demand Forecasting:Machine learning algorithms predict consumption patterns to optimize dispatch timing.
Smart Meters holds the largest share; momentum sits with Software Solutions.
End User:
Industrial Sector deployments generate the highest per-site revenue volumes due to complex integration requirements, while Commercial Buildings offer faster implementation cycles through standardized building management interfaces.
- Industrial Sector:Heavy manufacturing facilities require precise load modulation to maintain production continuity during grid events. Cement and steel plants across India's Maharashtra and Gujarat states face mandatory CEA participation rules forcing automated system investments.
- Commercial Buildings:Office towers and retail complexes aggregate HVAC and lighting loads for utility demand response programs. Sydney and Melbourne facility managers favor platforms with guaranteed forecasting accuracy SLAs over capital-intensive hardware procurement.
- Utilities:Grid operators procure DRMS to manage renewable intermittency and defer generation capacity investments.
- Residential Users:Single-family homes and apartment buildings participate through utility-managed thermostat and water heater programs.
Industrial Sector commands premium pricing; Commercial Buildings are climbing the fastest.
Service Type:
Implementation Services absorb the largest share of utility budgets as retrofit complexity drives professional integration demand, while Maintenance Services contracts lengthen as uptime guarantees become standard procurement criteria.
- Implementation Services:System integrators deploy hardware, configure software platforms, and establish communication pathways between utility control centers and end-user equipment. South Korean utility-scale projects require specialized expertise to bridge 1990s-era SCADA systems with cloud-native architectures.
- Consulting Services:Advisory firms assess facility load profiles and design participation strategies for wholesale electricity markets.
- Maintenance Services:Preventive and corrective support ensures continuous platform availability through firmware updates and hardware replacement.
- Support Services:Help desk and technical assistance resolve operational issues during demand response events.
Implementation Services captures the dominant revenue pool; Maintenance Services shows the steepest expansion trajectory.
Application:
Load Management applications concentrate in Taiwan and South Korea where utility-scale deployments prioritize grid stability, while Peak Shaving gains share in Australia's AEMO capacity markets where demand-side bidding creates explicit revenue streams.
- Load Management:Continuous modulation of electricity consumption maintains grid frequency within operational bands. Taiwan Power Company deploys these capabilities across semiconductor fabrication facilities to manage voltage fluctuations from renewable penetration.
- Peak Shaving:Temporary load reduction during highest-demand hours defers generation capacity investments. Australian virtual power plant operators aggregate commercial building loads to capture dispatch payments in AEMO's wholesale market.
- Demand Response:Event-based consumption reduction triggered by supply constraints or price signals.
- Energy Efficiency:Permanent load reduction through equipment upgrades and operational optimization.
Load Management retains the largest installed base; Peak Shaving is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japan's precision-manufacturing corridors where METI-mandated frequency response standards command system premiums, while cost-sensitive procurement across Vietnam's emerging industrial zones compresses margins for standardized hardware deployments.
Japan
Automotive and electronics manufacturing clusters in the Keihin and Chukyo industrial belts drive concentrated demand for sub-15-minute dispatch capabilities. METI enforces stringent IEC 62351 cybersecurity certification for all demand response pathways serving critical infrastructure. Heavy steel mills and petrochemical complexes in the Tokyo-Yokohama corridor are consolidating vendor relationships with pre-certified platforms.
China
State-owned utilities in coastal manufacturing provinces face procurement deadlines under the National Energy Administration's dual carbon implementation roadmap. Provincial pilot programs in Jiangsu and Guangdong require third-party demand response service procurement from industrial consumers. The Yangtze River Delta semiconductor fabrication corridor is deploying edge-computing controllers to manage renewable intermittency.
India
Steel and cement plants across Maharashtra and Gujarat states confront mandatory automated load modulation investments under Central Electricity Authority participation rules. State distribution companies in Tamil Nadu and Karnataka are expanding time-of-use pricing pilots to commercial building aggregators. The Delhi-Mumbai Industrial Corridor is emerging as a concentrated deployment zone for utility-scale demand response integration.
Australia
Commercial building portfolio managers in Sydney and Melbourne are prioritizing subscription-based analytics platforms with guaranteed forecasting accuracy SLAs. The Australian Energy Market Operator's capacity markets provide explicit demand-side bidding mechanisms for virtual power plant operators. State governments in New South Wales and Victoria are accelerating smart meter rollouts to enable real-time consumption visibility.
South Korea
Utility-scale deployments by Korea Electric Power Corporation face technical friction retrofitting 1990s-era SCADA systems with cloud-native architectures. The Busan-Ulsan petrochemical corridor requires specialized integration expertise for legacy control system bridges. Seoul Capital Area data centers are adopting automated demand response to manage grid frequency fluctuations from renewable penetration.
Asia-Pacific Demand Response Management Systems Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific Demand Response Management Systems landscape. Integrated European industrial conglomerates with building-to-grid software stacks command premium positioning in Australia's commercial building segment, while diversified automation specialists anchor utility-scale deployments through localized manufacturing partnerships. The competitive structure segments into three strategic archetypes: full-stack platform providers, hardware-integrated system integrators, and pure-play software analytics vendors. Dominant competitive moves include backward integration into communication chipset supply chains and geographic expansion through regional system integration partnerships.
Among the integrated European conglomerates, Schneider Electric and Siemens AG exemplify the full-stack platform archetype with cross-regional building-to-grid capabilities. Hitachi Ltd and Mitsubishi Electric Corporation represent Japan-based industrial electronics specialists with concentrated positioning in domestic manufacturing corridor deployments. These named entities occupy representative positions within their respective archetype tiers rather than defining exhaustive market coverage.
| Leading Market Players |
|---|
| Schneider Electric |
| Siemens AG |
| Hitachi Ltd |
| Mitsubishi Electric Corporation |
| General Electric Company |
| ABB |
| Eaton Corporation PLC |
| Honeywell International Inc. |
| Johnson Controls International PLC |
| Others |
Value Chain & Pricing Dynamics
Cloud-native software stacks are displacing on-premise hardware platforms across Asia-Pacific utilities, simultaneously shifting procurement geography toward Indian and Australian SaaS vendors while compressing capital expenditure pricing models into recurring subscription structures. This substitution dynamic redistributes margin capture from hardware-integrated system integrators toward analytics specialists with lower fixed asset requirements.
Pricing Analysis
The customization-premium spread separates IEC 62351-certified platforms for Japanese critical infrastructure from standardized deployments in Vietnam's emerging industrial zones. Subscription-based SaaS tiers dominate Australian commercial buildings, while project-based licensing persists in South Korean utility retrofits. Price differentiation rests on cybersecurity certification grade and after-sales service bundling. Cost compression in Vietnam's hardware tier is intensifying because of state utility procurement standardization. Commercial building aggregators in Sydney exhibit lowest price sensitivity; northern Vietnamese manufacturers show highest.
Supply Chain Analysis
Inventory lead times for communication chipsets have extended due to concentrated foundry capacity in Taiwan and South Korea. The DRMS supply chain draws from Japanese edge-computing controller production, Chinese smart meter manufacturing, and Australian software development. Raw material dependencies include silicon wafers, lithium-ion cells for battery-integrated systems, and rare earth elements for power electronics. Single-source vulnerability in East Asian semiconductor fabrication creates structural risk. Distribution runs through regional system integration partnerships anchored by localized manufacturing alliances.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Australian commercial building portfolio managers and Japanese industrial conglomerates, compressing vendor margins and forcing consolidation among mid-tier system integrators.
For Market Incumbents: Shield core revenue in Japan's Keihin industrial belt by accelerating IEC 62351 pre-certification investments before METI enforcement tightens. Deepen backward integration into communication chipset supply chains to mitigate Taiwan foundry allocation constraints. Prioritize channel control through exclusive distribution partnerships with South Korean SCADA retrofit specialists. For New Entrants and Emerging Players: Differentiate on outcome-linked pricing with guaranteed forecasting accuracy SLAs for Australian commercial building aggregators. Target Vietnam's underpenetrated northern manufacturing corridors as EVN expands time-of-use pilots. Pursue white-space in building-to-grid convergence integrating HVAC algorithms with battery dispatch logic. For Investors and Strategic Acquirers: The market sits at a regulatory-compliance acceleration phase that favors software analytics vendors with pre-certified cybersecurity frameworks. Long-term viability centers on subscription revenue durability and regional system integration partnerships. Acquisition target archetype: cloud-native platforms with proven AEMO market participation. Watch for carbon border adjustment mechanism implementation as demand-side procurement criteria inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Communication Chipsets | Mitigates Taiwan foundry concentration risk for DRMS vendors serving Japanese utilities. |
| IEC 62351 Pre-Certification Investment | Accelerates METI compliance timelines for platforms targeting Keihin industrial corridor steel mills. |
| Building-to-Grid Software Convergence | Creates new service revenue streams by integrating HVAC control with battery storage dispatch in Australian commercial portfolios. |
| Regional System Integration Partnership | Enables market entry into South Korean utility-scale deployments requiring 1990s SCADA bridge expertise. |
| Outcome-Linked Pricing Model | Aligns vendor incentives with Australian facility manager preferences for guaranteed forecasting accuracy SLAs. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, utility procurement databases, and industrial automation trade data. Primary interviews engaged utility planning officers, commercial building facility managers, DRMS platform engineers, and system integration specialists across Japan, Australia, India, South Korea, and Vietnam. Secondary validation drew from CEA mandate documentation, METI grid stability standards, AEMO market rule amendments, and smart meter rollout disclosures. Bottom-up deployment tracking triangulates against top-down utility capital expenditure analysis.
Segmentation dimensions modeled include technology type, end-user category, service delivery model, and application function across the projection horizon. CAGRs derive from regression analysis of historical procurement velocity against regulatory deadline compression and renewable penetration rates. Forecast inputs incorporate industrial electricity demand elasticity, cloud-native platform adoption curves, and cybersecurity certification pipeline timelines.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement or accelerated renewable intermittency would require recalibration. Forecasts reflect documented assumptions about compliance timeline adherence and foundry capacity allocation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
Smart Grid Network Market
Smart Grid
Global Self-Healing Grid Market
Smart Grid
South Africa Smart Grid Market
Smart Grid
North America Automated Demand Response Management System Market
Smart Grid
Smart Microgrid Controller Market
Smart Grid
Latin America Smart Grid Security Market
Smart Grid
Power Grid Market
Smart Grid
Smart Demand Response Market
Smart Grid
Renewable Energy Integration with Smart Grid Market
Smart Grid
Smart Grid Home Area Network (HAN) Market
Smart Grid
South Africa Smart Grid Network Market
Smart Grid
Smart Grid Sensors Market
Smart Grid
Smart Grid Technology Market
Smart Grid
North America Microgrid Market
Smart Grid
Smart Grid Market
Smart Grid
Middle-East Smart Grid Network Market