
 Europe Smart Grid Network Market | 2026-2036
Europe Smart Grid Network Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Smart Grid Network Market Foresight
Spain's Andalusian solar corridor is rewriting how southern European utilities balance intermittent generation with baseload stability. Siemens AG leverages its digital grid software portfolio to anchor large-scale distribution management deployments across Iberia. Schneider Electric SE competes through integrated microgrid controls that extend its reach into commercial and industrial behind-the-meter applications. ABB Ltd specializes in high-voltage direct current interconnection hardware that sustains cross-border electricity trading between France and Spain.
A smart grid network comprises digitally controlled transmission and distribution infrastructure that uses two-way communication, automated switching, and real-time sensor telemetry to optimize electricity flow from heterogeneous generation sources to geographically dispersed consumption points. These systems typically operate at frequencies of 50 Hz across Europe and incorporate IEC 61850 protocol standards for substation automation, enabling millisecond-level fault isolation and self-healing grid topologies. Advanced Metering Infrastructure leads technology investment as utilities replace electromechanical meters with IP-connected endpoints capable of time-of-use pricing and remote disconnect. Renewable Integration within the application dimension represents the fastest-expanding segment as grid codes in member states mandate ride-through capabilities and frequency response from distributed energy resources. Consulting and System Integration services capture disproportionate margin pools due to the bespoke engineering required to retrofit legacy SCADA architectures with cloud-native analytics platforms.
The European Commission's EU Green Deal and F-Gas Regulation together with national implementations of the Clean Energy Package are binding member states to binding electrification targets that directly shape smart grid procurement specifications. ECHA chemical restrictions and CE marking requirements under the MDR framework constrain component sourcing for switchgear and transformer monitoring equipment, favoring European-qualified suppliers. Germany's KBA and France's national energy regulator enforce grid compliance protocols that determine market access for foreign equipment vendors. Stakeholders must monitor how the EU AI Act's risk classification rules will apply to autonomous grid optimization algorithms before committing to fully automated control system architectures.
Market Dynamics
The EU Green Deal's binding electrification mandates are forcing transmission system operators across Germany, France, and Spain to accelerate digital substation deployments and retrofit legacy SCADA architectures with cloud-native control systems.
Growth Catalysts
- EU Green Deal targets:Binding national renewable integration deadlines in Germany and France mandate grid modernization investments that directly expand demand for IEC 61850-compliant automation hardware.
- Distributed solar proliferation:Spain's Andalusian solar corridor and similar clusters in Italy are driving two-way communication infrastructure deployment to manage bidirectional power flows.
- F-Gas Regulation phase-down:The European regulation restricting fluorinated greenhouse gases is accelerating replacement of sulfur hexafluoride switchgear with vacuum interrupter alternatives.
Market Restraints
- Copper and rare earth price volatility:Transformer core laminations and permanent magnet materials face input cost swings that compress equipment margins and delay utility procurement cycles.
- Legacy SCADA integration complexity:Proprietary protocols from 1980s-era control systems create technical debt that extends commissioning timelines for digital overlay deployments.
- CE marking and MDR compliance costs:European medical device regulation spillover effects increase certification burden for grid monitoring equipment with embedded sensors.
Strategic Opportunities
- Eastern European grid lag:Poland and Romania retain substantial electromechanical meter populations that present addressable white space for Advanced Metering Infrastructure vendors.
- Industrial microgrids:Behind-the-meter commercial and industrial applications in Spain and Italy offer higher-margin deployment opportunities outside regulated utility channels.
- EU AI Act pre-positioning:Early alignment of autonomous grid optimization algorithms with risk classification rules creates first-mover advantage before mandatory compliance deadlines.
Industry Challenges
- Cybersecurity engineering scarcity:Utilities compete with fintech and defense sectors for personnel qualified to implement IEC 62351 security standards across substation networks.
- Multi-vendor interoperability testing:Integration of Siemens, ABB, and Schneider Electric equipment within single control architectures demands extended factory acceptance testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Smart Grid Network Market |
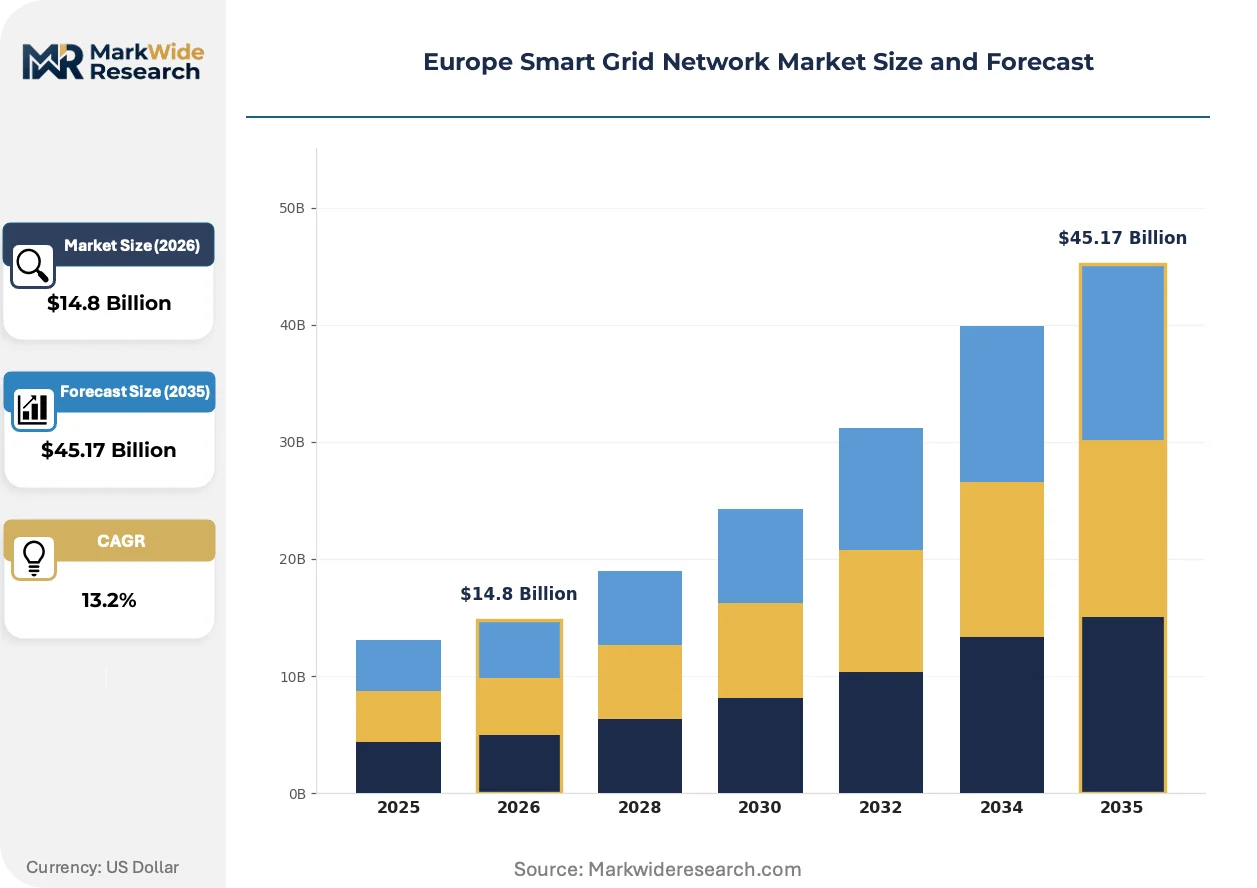
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $45.17 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Advanced Metering Infrastructure, Demand Response, Distribution Management System, Energy Management Systems End User: Utilities, Industrial Consumers, Commercial Buildings, Residential Users Application: Energy Storage, Renewable Integration, Grid Optimization, Fault Detection Service Type: Consulting, System Integration, Maintenance, Managed Services |
| Companies Covered | Schneider Electric SE, Siemens AG, Électricité de France SA, E.ON SE, SSE PLC, ABB Ltd, Landis+Gyr Group AG, General Electric Company, Itron, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Smart Grid Network Market Shifts & Advancements
Digital twin architectures and autonomous control algorithms are compressing fault response times from seconds to milliseconds, while procurement patterns shift toward performance-guaranteed service contracts rather than capital equipment purchases.
Digital twin simulation platforms replicate physical grid topology in real-time software environments, enabling predictive maintenance and scenario modeling before physical intervention. German transmission operators deploy these systems across high-voltage corridors to pre-validate switching sequences. The technology is rendering obsolete manual dispatch procedures that required on-site engineering presence for topology reconfiguration.
The EU AI Act's risk-based classification framework imposes documentation and human oversight requirements on autonomous grid optimization systems that make real-time switching decisions without operator confirmation. Equipment vendors must redesign control algorithms to maintain audit trails and explainability features. French and Spanish regulators are issuing interim guidance ahead of full enforcement, pushing utilities toward hybrid human-in-the-loop architectures.
Power purchase agreements with industrial offtakers now specify grid flexibility services as contract deliverables, not just energy volume. Large manufacturing facilities in Germany's Ruhr region negotiate demand response commitments directly with transmission system operators. This contractual innovation transfers balancing responsibility downstream and creates new revenue pools for behind-the-meter storage and load control vendors.
Europe Smart Grid Network Market Segmentation
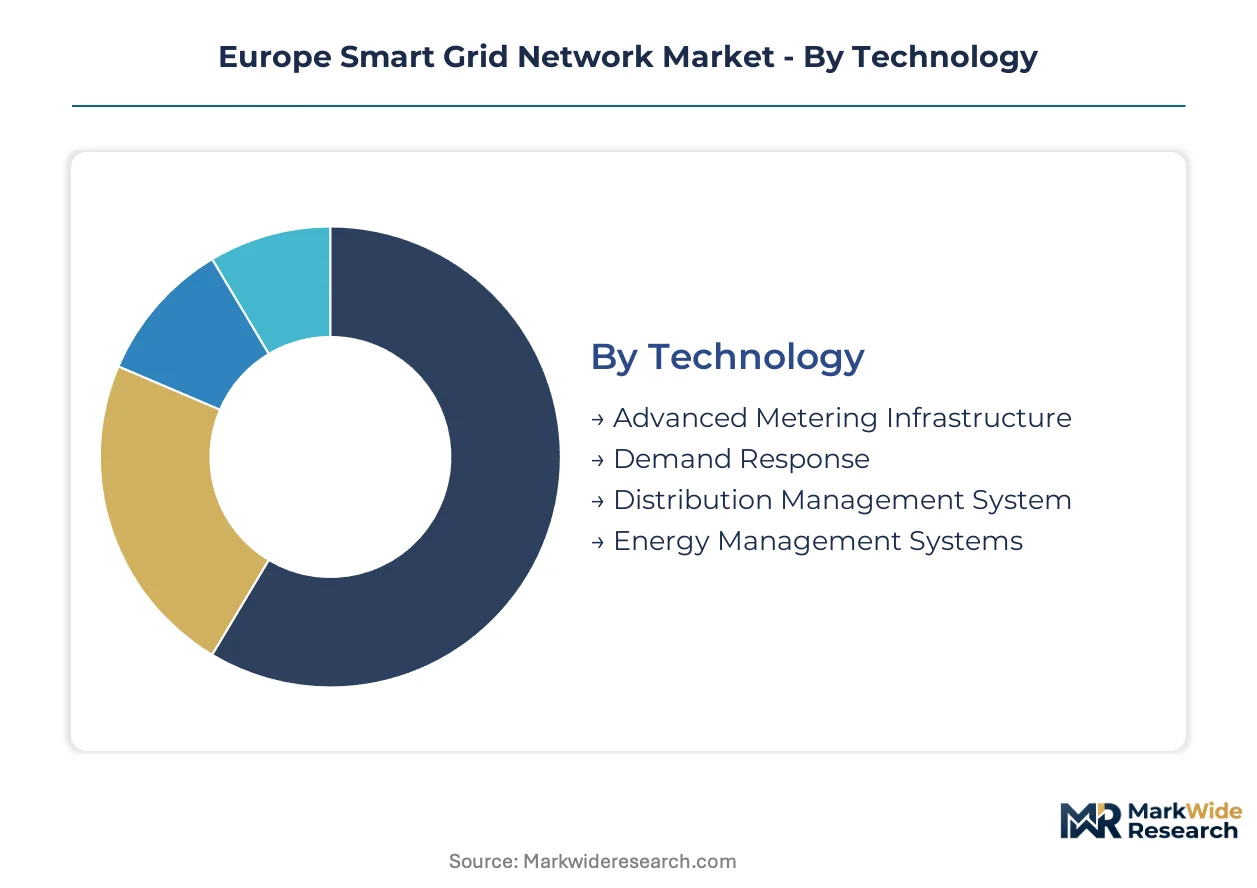
European smart grid procurement patterns diverge sharply across technology maturity and regulatory pressure. Segmentation reveals where capital concentrates versus where service margins expand.
Technology:
The use-case spectrum spans consumer-facing endpoints through utility-scale control platforms, with deployment urgency tied to renewable integration deadlines.
- Advanced Metering Infrastructure:IP-connected electromechanical meter replacements enable time-of-use pricing and remote disconnect capabilities. German and Spanish utilities drive replacement cycles under national electrification mandates, with Poland's electromechanical legacy creating substantial white space.
- Demand Response:Automated load curtailment systems integrate industrial offtakers into frequency regulation markets. German manufacturing facilities in the Ruhr region negotiate direct response commitments with transmission operators, transferring balancing responsibility downstream.
- Distribution Management System:Real-time feeder reconfiguration software optimizes power flow across meshed networks.
- Energy Management Systems:Behind-the-meter optimization platforms serve commercial building portfolios seeking utility bill reduction.
The dominant share belongs to Advanced Metering Infrastructure, while Demand Response is closing the gap fastest.
End User:
Customer type determines procurement channel structure and contract complexity, from regulated rate-base treatment to competitive commercial tenders.
- Utilities:Transmission and distribution operators deploy capital-intensive infrastructure under regulatory rate-of-return frameworks. France's national energy regulator and Germany's KBA enforce grid compliance protocols that constrain vendor selection and extend commissioning timelines.
- Industrial Consumers:Large manufacturing facilities procure behind-the-meter microgrids and storage systems outside regulated channels. Spain and Italy host the most active commercial deployments, with power purchase agreements now specifying flexibility services as contract deliverables.
- Commercial Buildings:Facility managers prioritize energy cost reduction through automated HVAC and lighting integration.
- Residential Users:Distributed solar adopters drive home energy management system attachment rates.
Utilities command the largest absolute spend, though Industrial Consumers are expanding most quickly.
Application:
Functional priority reflects grid stress points, from intermittent generation accommodation through reliability assurance.
- Renewable Integration:Grid code compliance systems enable distributed solar and wind ride-through capabilities and frequency response. Spain's Andalusian solar corridor and Italian clusters demand bidirectional power flow management infrastructure.
- Grid Optimization:Autonomous switching algorithms compress fault response times from seconds to milliseconds. German transmission operators deploy digital twin architectures across high-voltage corridors to pre-validate topology reconfiguration sequences.
- Energy Storage:Battery management systems coordinate charging cycles with wholesale price signals.
- Fault Detection:Sensor networks isolate distribution faults before cascading failures propagate.
Renewable Integration holds the steepest expansion trajectory, while Grid Optimization captures the highest per-project value.
Service Type:
Margin structure inverts between commoditized maintenance and bespoke engineering engagements.
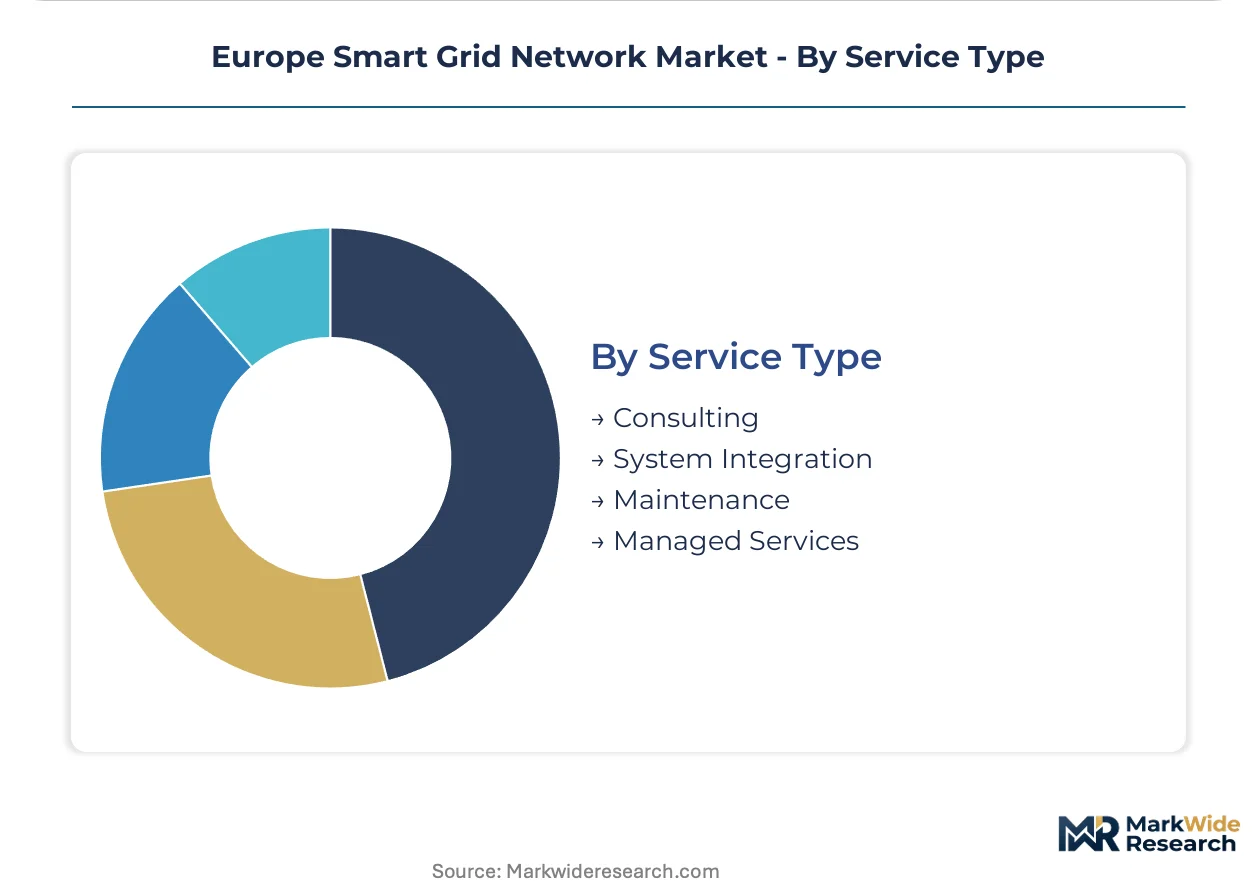
- Consulting:Grid modernization strategy and regulatory compliance advisory commands premium pricing due to scarce expertise. ECHA chemical restrictions and CE marking requirements under the MDR framework increase certification burden complexity.
- System Integration:Legacy SCADA retrofit with cloud-native analytics platforms requires extended factory acceptance testing. Multi-vendor interoperability between Siemens, ABB, and Schneider Electric equipment demands bespoke engineering protocols.
- Maintenance:Preventive service contracts on deployed infrastructure generate recurring revenue streams.
- Managed Services:Performance-guaranteed operational contracts transfer operational risk from utilities to vendors.
Consulting claims the highest margin pool, while System Integration is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing clusters concentrate in Germany, France, and Switzerland, while deployment velocity varies across southern and eastern Europe based on renewable integration deadlines and legacy infrastructure age.
Germany
Transmission system operators face binding renewable integration deadlines that mandate digital substation upgrades across high-voltage corridors. The KBA enforces grid compliance protocols that constrain foreign equipment vendor access and extend commissioning timelines. The Ruhr region's industrial load centers negotiate direct demand response commitments with transmission operators, transferring balancing responsibility downstream.
France
Électricité de France SA drives standardization of IEC 61850-compliant automation hardware through its procurement specifications. The national energy regulator enforces grid codes that determine market access for substation equipment vendors. The Île-de-France region hosts pilot deployments of autonomous grid optimization systems ahead of full EU AI Act enforcement.
Spain
The Andalusian solar corridor generates bidirectional power flows that demand two-way communication infrastructure across distribution networks. The EU Green Deal's electrification targets accelerate retrofit timelines for legacy SCADA architectures. Barcelona and Madrid utilities deploy integrated microgrid controls for commercial and industrial behind-the-meter applications.
United Kingdom
SSE PLC and other distribution network operators modernize aging infrastructure to accommodate offshore wind generation from North Sea clusters. Ofgem's regulatory frameworks shape rate-of-return calculations for capital-intensive smart meter deployments. The Midlands and northern England present substantial addressable white space for Advanced Metering Infrastructure vendors replacing electromechanical meter populations.
Poland
Electromechanical meter legacy creates substantial deployment opportunities for IP-connected endpoint vendors. The country's national energy regulator transposes EU Clean Energy Package directives into binding procurement specifications. Warsaw and Krakow distribution utilities lag western European digitalization timelines, extending replacement cycle visibility for automation hardware suppliers.
Europe Smart Grid Network Market Competitive Landscape
Integrated conglomerates and specialized automation houses split the market along capability depth versus portfolio breadth lines. Siemens AG and Schneider Electric SE anchor the consolidated tier through full-stack hardware-software integration, while mid-cap specialists capture niche margins in sensor telemetry and vacuum interrupter switchgear. Three archetypes dominate: European industrial conglomerates with captive utility relationships, North American technology vendors with cloud-native analytics platforms, and regional automation specialists with deep IEC protocol expertise. Competitive moves concentrate on strategic partnerships between equipment vendors and transmission system operators, plus portfolio diversification into behind-the-meter energy management systems.
Within the European conglomerate tier, Siemens AG, Schneider Electric SE, and ABB Ltd represent the dominant strategic archetypes. Siemens AG exemplifies the vertically integrated automation house with deep transmission system operator relationships. Schneider Electric SE occupies a position bridging utility-scale and commercial-industrial application domains. ABB Ltd anchors the high-voltage interconnection specialization segment. Électricité de France SA and E.ON SE demonstrate how incumbent utilities compete through captive procurement channels and standard-setting influence. Landis+Gyr Group AG sits within the meter-focused specialist tier alongside Itron, Inc., while General Electric Company represents the transatlantic technology vendor archetype seeking European market penetration through digital platform offerings.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Siemens AG |
| Électricité de France SA |
| E.ON SE |
| SSE PLC |
| ABB Ltd |
| Landis+Gyr Group AG |
| General Electric Company |
| Itron, Inc. |
| Others |
Supply & Pricing Matrix
The Rhine-Alpine freight corridor's volatile container rates amplify cost differentials between German-engineered automation hardware and Asian-sourced sensor components, compressing margins for mid-tier European suppliers while rewarding vertically integrated conglomerates with captive logistics networks.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure across European smart grid procurement, separating CE-marked IEC 61850-compliant systems from uncertified alternatives. Three-tier pricing stratifies across premium automation suites, standard distribution hardware, and economy-grade meter endpoints. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because Polish and Romanian utilities prioritize lowest-first-cost procurement. Industrial offtakers in Germany's Ruhr region exhibit the least price sensitivity, accepting performance-guaranteed contracts with embedded service premiums.
Supply Chain Analysis
Extended payment terms from transmission system operators are forcing component suppliers to draw from supply-chain finance facilities, concentrating working capital strain on mid-cap sensor vendors. Manufacturing concentrates in Germany, Switzerland, and France for high-voltage switchgear, while semiconductor components source from Taiwan and South Korea. Raw material dependencies span copper for transformer laminations, rare earth elements for permanent magnets, and silicon carbide for power electronics. Single-source vulnerability in ceramic substrate supply creates chokepoint exposure. Distribution runs through authorized system integrators holding IEC protocol expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across Eastern European electromechanical legacy and Southern European solar integration deadlines creates niche entry points for specialized vendors. The demand-side shift toward behind-the-meter industrial microgrids splinters procurement authority away from centralized utilities.
For Market Incumbents: Pre-empt cloud-native platform consolidation by acquiring middleware specialists with IEC 62351 cybersecurity credentials. Siemens AG and Schneider Electric SE should extend factory acceptance testing protocols to lock out mid-tier interoperability challengers. Backward integration into silicon carbide substrate supply would defend margin position against rare earth volatility. For New Entrants and Emerging Players: Poland's electromechanical meter legacy offers immediate addressable volume for IP-connected endpoint vendors with CE marking capabilities. Romanian distribution utilities lag digitalization timelines by half a decade, creating extended replacement cycle visibility. Target industrial microgrid controls in Spain's Andalusian solar corridor through direct engineering sales to commercial offtakers bypassing utility channels. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate automation divisions seeking portfolio simplification. Five-to-ten year viability favors specialists with captive IEC protocol expertise over hardware-commoditized generalists. Monitor EU AI Act enforcement timing as inflection indicator for autonomous control algorithm valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Substation Retrofit | German transmission operators deploy IEC 61850 automation to meet binding renewable integration deadlines. |
| Cloud-Native SCADA Migration | Legacy protocol translation creates recurring integration revenue for system engineering specialists. |
| Vacuum Interrupter Scale-Up | F-Gas Regulation phase-down accelerates SF6 switchgear replacement across French and Spanish utilities. |
| Behind-the-Meter Microgrid Deployment | Spanish industrial parks negotiate flexibility services directly with transmission system operators. |
| Cybersecurity Certification Investment | IEC 62351 compliance becomes table stakes for substation network access under EU AI Act guidance. |
Research Methodology
Initial hypotheses were tested against primary input from transmission system planning officers, substation automation engineers, regulatory compliance leads at national energy regulators, and procurement managers at distribution utilities, then refined through secondary validation against EIA grid modernization databases, IEA renewable integration reports, FERC interconnection filings, and EU Clean Energy Package implementation tracking. Bottom-up equipment shipment data and top-down utility capital expenditure disclosures were triangulated to reconcile volume and value estimates.
Demand-supply balance modeling anchored projections across the analysis window, with segmentation by technology tier, end-user category, application priority, and service type. CAGRs were derived from utility procurement pipeline visibility and regulatory deadline enforcement schedules. Forecast inputs incorporated renewable capacity addition trajectories, grid code amendment timelines, and industrial load growth patterns specific to the Ruhr and Andalusian corridors.
The forecast holds incumbent behavior within observed patterns; aggressive moves by North American cloud-platform vendors or Chinese state-backed equipment suppliers would shift outcomes. Macroeconomic deviation in copper and rare earth pricing, regulatory acceleration of EU AI Act enforcement, or technological breakthrough in solid-state transformer topology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
UK Smart Grid Network Market
Smart Grid
Europe Microgrid Market
Smart Grid
Smart Grid Network Market
Smart Grid
Microgrid Controller Market
Smart Grid
Smart Grid Sensors Market
Smart Grid
China Smart Grid Network Market
Smart Grid
Global Smart Grid Security Market
Smart Grid
Automated Demand Response Management Systems Market
Smart Grid
Global Smart Grid Networking Market
Smart Grid
Saudi Arabia Smart Grid Market
Smart Grid
Smart Microgrid Controller Market
Smart Grid
Smart Demand Response Market
Smart Grid
Smart Grid Data Management Market
Smart Grid
Demand Response Market
Smart Grid
North America Smart Grid Market
Smart Grid
Middle-East Smart Grid Network Market