
 Smart Grid Sensors Market | 2026-2036
Smart Grid Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Grid Sensors Market Analysis
Multi-source procurement for advanced metering components is broadening as utilities reduce dependency on single-vendor architectures. ABB Ltd. leverages its integrated power automation portfolio to anchor large-scale European deployments. General Electric Company competes through its digital energy platform that extends across transmission and distribution networks. Siemens AG specializes in IoT-enabled sensor arrays for predictive grid maintenance, sustaining technical leadership in fault detection systems.
Smart grid sensors are electromechanical and solid-state devices that measure voltage, current, temperature, and power quality parameters across distribution networks, transmitting data via wireless, wired, or hybrid communication protocols to centralized control systems for real-time operational decisions. These instruments typically operate within IEC 61850 communication frameworks and withstand temperature ranges from minus forty to plus eighty-five degrees Celsius for outdoor substation installations. Wireless technology leads deployment volume due to lower retrofit costs in aging infrastructure, while IoT-enabled architectures represent the fastest-expanding category as utilities integrate edge computing for sub-second fault localization. The application segment for fault detection commands concentrated margin pools because downtime avoidance delivers quantifiable economic returns to grid operators.
The Federal Energy Regulatory Commission in the United States mandates transmission reliability standards that directly stimulate sensor investments for grid monitoring compliance. The European Union's CE marking and IEC 61850 interoperability requirements shape product design specifications and determine market access for equipment vendors serving continental utilities. China's GB standards and dual carbon goals from the Ministry of Ecology and Environment are restructuring procurement criteria for state grid operators. Stakeholders must monitor evolving cybersecurity certification requirements as grid digitization expands attack surfaces for critical infrastructure.
Market Dynamics
Grid digitization mandates are compressing deployment timelines as utilities replace electromechanical relays with solid-state sensing arrays capable of sub-cycle fault detection.
Growth Catalysts
- FERC Order 693:US transmission reliability standards mandate continuous thermal monitoring of critical corridors, forcing capital allocation toward distributed temperature sensing.
- EU F-Gas Regulation:Phase-down of sulfur hexafluoride in switchgear accelerates demand for optical partial discharge sensors as non-gaseous alternatives.
- Edge computing convergence:On-device inference engines reduce telemetry latency from seconds to milliseconds, enabling autonomous sectionalizing without centralized SCADA dependency.
Market Restraints
- Semiconductor supply concentration:Analog-to-digital converter and MEMS foundry capacity clusters in Taiwan create procurement bottlenecks for sensor module vendors.
- Legacy protocol fragmentation:DNP3, Modbus, and proprietary SCADA interfaces persist in brownfield substations, complicating interoperability with IEC 61850-native devices.
- Copper and rare earth volatility:Neodymium and dysprosium price swings for magnetic sensing cores compress margin stability for manufacturers without long-term offtake agreements.
Strategic Opportunities
- India's Revamped Distribution Sector Scheme:Central government capital subsidies for smart metering create entry pathways for fault passage indicator vendors in state discom tenders.
- Vehicle-to-grid integration:Bidirectional EV charging infrastructure requires power quality sensors capable of harmonic detection at residential transformers, opening residential-scale deployment.
- Digital twin convergence:Physics-based grid modeling platforms seek real-time sensor feeds for calibration, creating subscription revenue streams beyond hardware sales.
Industry Challenges
- Cybersecurity certification timelines:IEC 62351 compliance testing for encrypted sensor communications extends product launch cycles by 8-14 months in regulated markets.
- Field workforce skill gaps:Deployment of optical fiber current sensors requires technicians trained in fusion splicing and OTDR diagnostics, capabilities scarce outside transmission utilities.
- Multi-vendor integration complexity:Utilities operating hybrid fleets from ABB, Siemens, and GE face protocol mediation costs when harmonizing event timestamps across sensor arrays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Grid Sensors Market |
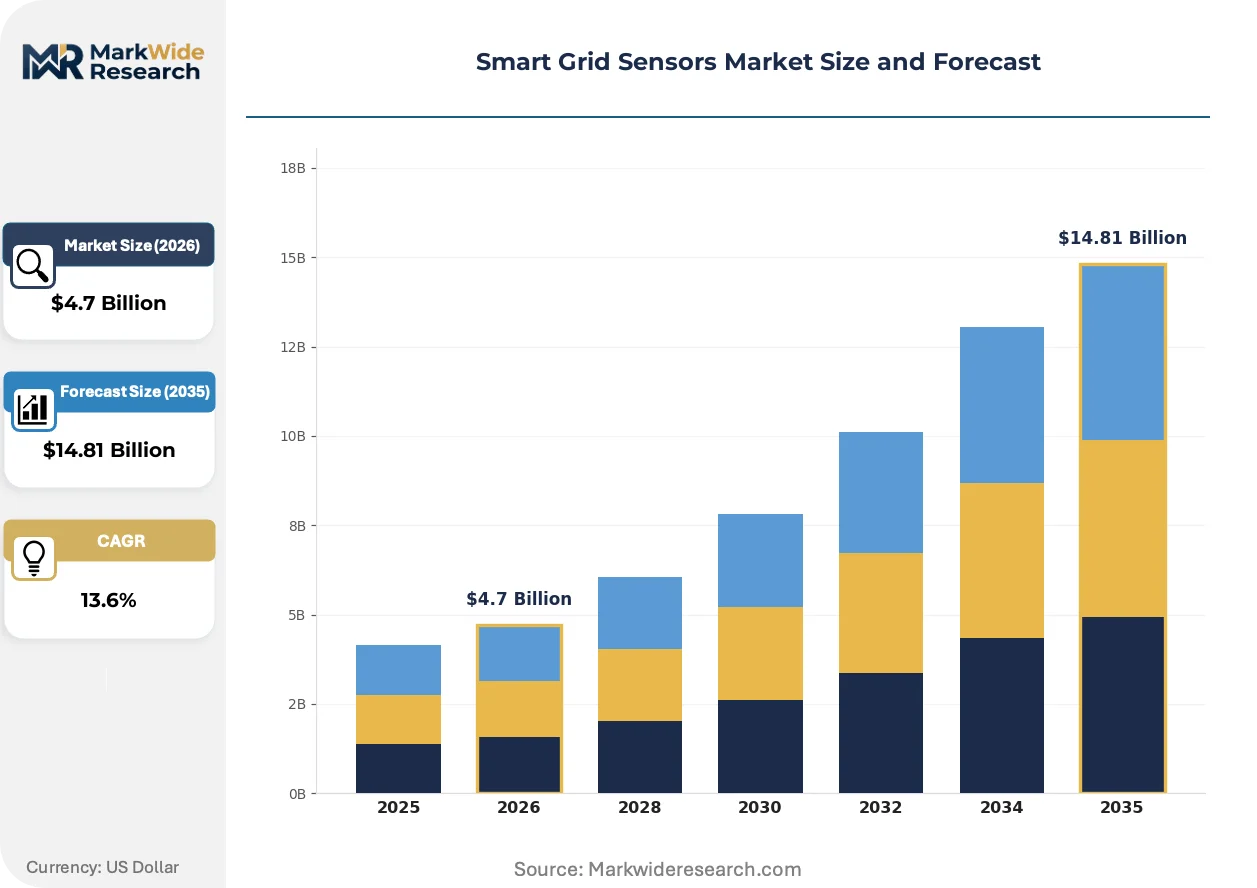
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $14.81 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Wireless, Wired, Hybrid, IoT-enabled Component: Transducers, Meters, Data Loggers, Actuators Application: Energy Management, Demand Response, Fault Detection, Asset Monitoring End User: Utilities, Industrial, Commercial, Residential |
| Companies Covered | ABB Ltd., General Electric Company, Siemens AG, Honeywell International Inc., Eaton Corporation, Aclara Technologies LLC, Itron Inc., Schneider Electric, Landis+Gyr Group AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Grid Sensors Market Emerging Trajectories
Silicon carbide power electronics and optical sensing modalities are collapsing the size and power budgets of grid monitoring equipment, enabling pad-mounted and pole-top installations previously infeasible with conventional instrument transformers.
Optical voltage transducers based on Pockels cell and Kerr effect principles are electrifying medium-voltage distribution monitoring by eliminating magnetic saturation and ferroresonance risks inherent in iron-core potential transformers. European DSOs in Germany and the Netherlands are piloting these devices at 20-36 kV levels, with procurement volumes expanding as type-test certifications accumulate. The technology is compressing substation footprints and enabling underground vault deployments where oil-filled units posed fire hazards.
The EU AI Act's risk classification framework for critical infrastructure is reshaping sensor firmware development cycles, requiring algorithmic transparency documentation for machine-learning-based fault classification models. Vendors serving continental utilities must now maintain model cards and bias audit trails alongside hardware certifications. German TSOs and French DSOs are incorporating these requirements into technical specifications, effectively filtering out suppliers lacking embedded AI governance capabilities.
Performance-based service agreements are displacing traditional equipment procurement in North American utility budgets, with sensor vendors assuming uptime risk and earning fees tied to avoided outage minutes. This model transfers capital burden from rate-base-constrained municipals to technology providers, concentrating vendor selection among firms with balance-sheet capacity to underwrite long-term contracts. The shift is most pronounced in California and Texas, where wildfire and storm resilience mandates intensify downtime cost calculations.
Smart Grid Sensors Market Segmentation
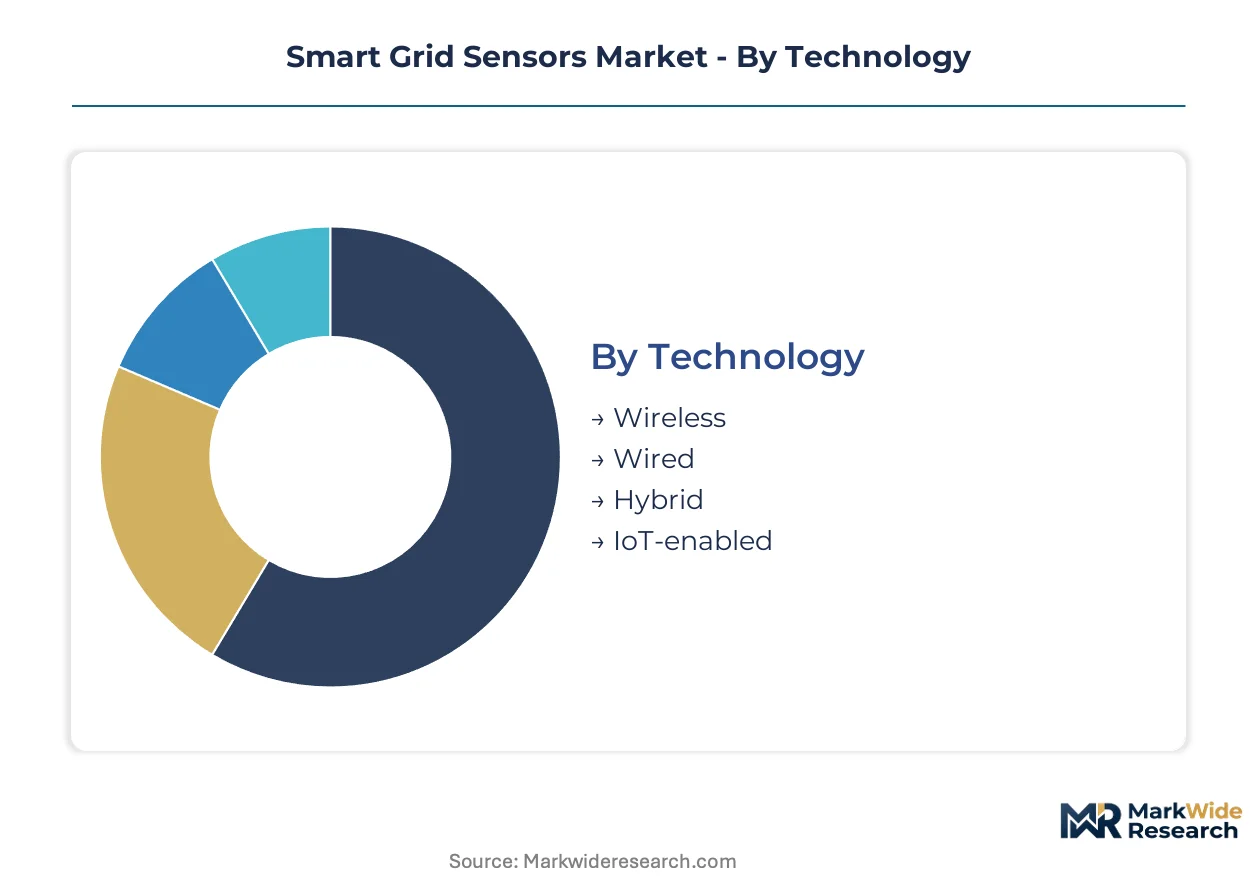
Technology heterogeneity in smart grid sensors creates distinct procurement pathways for utilities retrofitting aging infrastructure versus greenfield deployments. Component selection and application focus determine integration complexity, capital intensity, and recurring revenue potential for equipment vendors.
Technology:
Standardization pressures from IEC 61850 compliance compete with customization demands for brownfield protocol adaptation across this category.
- Wireless:Radio frequency and mesh network architectures eliminate trenching costs in urban distribution retrofit projects. Deployment concentrates in Germany and the United States where aging underground cable networks resist physical sensor installation.
- IoT-enabled:Edge computing modules with on-device inference engines process voltage sag data locally before cloud transmission. Demand clusters among California municipal utilities seeking sub-second fault localization for wildfire prevention mandates.
- Wired:Fiber optic and Ethernet-based installations deliver deterministic latency for transmission-level protection schemes.
- Hybrid:Dual-mode devices switch between wireless backup and primary wired connectivity based on network availability.
Leading the category by volume: Wireless. Growing fastest: IoT-enabled.
Component:
Margin concentration follows the data value chain from raw measurement through actionable control signals.
- Transducers:Current and voltage conversion elements using Rogowski coils or optical Pockels cells translate physical grid parameters into processable signals. Optical variants gain traction in Netherlands medium-voltage substations eliminating SF6 insulation dependencies under EU F-Gas Regulation.
- Data Loggers:Time-synchronized recording devices with GPS-disciplined clocks enable post-disturbance analysis for regulatory compliance. Procurement accelerates among Japanese regional utilities integrating tsunami-resilient monitoring under METI grid hardening directives.
- Meters:Revenue-grade measurement instruments certified to IEC 62053 accuracy classes.
- Actuators:Motorized switch controllers executing sectionalizing commands from centralized protection logic.
Highest margin capture: Data Loggers. Steepest expansion trajectory: Transducers.
Application:
Operational criticality determines budget allocation priority across grid operator planning cycles.
- Fault Detection:Traveling wave and impedance-based algorithms identify line-to-ground faults within quarter-cycle timeframes. Investment concentrates in Texas and Australia where storm-induced outage costs drive performance-based contracting for avoided interruption minutes.
- Asset Monitoring:Thermal and dissolved gas analysis sensors track transformer health degradation. Deployment expands in Japan and France for aging EHV substation fleets requiring predictive replacement scheduling.
- Energy Management:Power flow optimization sensors enable volt-VAR control for loss reduction.
- Demand Response:Load signaturing devices detect appliance-level consumption patterns for time-of-use tariff enforcement.
Dominant budget share: Fault Detection. Gaining share fastest: Asset Monitoring.
End User:
Procurement sophistication and capital access separate volume buyers from emerging niche adopters.
- Utilities:Vertically integrated transmission and distribution operators specify enterprise-grade sensor platforms with multi-decade service life requirements. Spending concentrates among German TSOs and US investor-owned utilities with rate-base-supported modernization programs.
- Industrial:Cogeneration facilities and microgrid operators deploy power quality monitors for harmonic compliance and islanding detection. Adoption accelerates in South Korean semiconductor fabs under KEPCO industrial tariff structures penalizing reactive power draw.
- Commercial:Retail and office building operators install sub-metering for LEED certification and tenant billing.
- Residential:Smart home energy monitors with circuit-level granularity remain nascent outside vehicle-to-grid pilot programs.
Primary volume driver: Utilities. Expanding most quickly: Industrial.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility capital allocation for grid modernization concentrates in Germany, the United States, and Japan, where regulatory mandates and infrastructure age drive sensor procurement volumes. These three markets absorb the dominant share of electromechanical-to-solid-state replacement cycles and first-time IoT deployments.
Germany
Distribution system operators in North Rhine-Westphalia and Bavaria deploy optical voltage transducers to eliminate SF6 dependencies under EU F-Gas Regulation phase-down schedules. The Bundesnetzagentur enforces grid stability standards that mandate real-time thermal monitoring of transformer assets. Siemens AG anchors large-scale deployments from its Munich engineering base, supplying fault detection arrays to TenneT and 50Hertz transmission zones.
United States
California municipal utilities and Texas grid operators lead wildfire prevention and storm resilience investments, procuring sub-second fault localization systems. FERC Order 693 mandates continuous thermal monitoring of critical transmission corridors, compelling capital flows toward distributed temperature sensing. Pacific Gas and Electric and CenterPoint Energy concentrate deployment in high-risk fire and hurricane corridors where downtime costs justify performance-based contracting.
Japan
Regional utilities integrate tsunami-resilient monitoring under METI grid hardening directives following 2011 infrastructure vulnerabilities. Tokyo Electric Power and Chubu Electric deploy data loggers with GPS-disciplined clocks for post-disturbance regulatory compliance. The Kanto and Chubu regions concentrate investment in aging EHV substation predictive maintenance systems.
China
State Grid Corporation procurement restructuring under Ministry of Ecology and Environment dual carbon goals accelerates optical sensor adoption for SF6-free switchgear. GB standards compliance shapes product specifications for domestic vendors serving 20-36 kV distribution networks. Yangtze River Delta utilities pilot edge computing architectures for autonomous sectionalizing without centralized SCADA dependency.
Netherlands
Enexis and Stedin distribution operators pilot optical voltage transducers at medium-voltage levels, expanding procurement as type-test certifications accumulate. EU Green Deal electrification targets compress deployment timelines for underground vault installations where oil-filled units posed fire hazards. The Randstad corridor concentrates smart meter and sensor integration for volt-VAR optimization.
Smart Grid Sensors Market Vendor Landscape
Portfolio diversification dominates the current landscape as industrial conglomerates leverage power automation heritage to anchor enterprise-scale utility contracts. The vendor base stratifies across three tiers: integrated multinationals with multi-decade service platforms, specialized sensor manufacturers with protocol-specific expertise, and emerging IoT-native entrants with edge computing capabilities. Two strategic archetypes prevail: full-stack automation providers bundling sensors with SCADA integration, and component specialists supplying transducer modules to third-party system integrators. M&A activity concentrates on cybersecurity capabilities and AI governance tooling, while capacity expansion targets semiconductor-adjacent foundry partnerships for MEMS and analog-to-digital converter supply security.
Within the integrated multinational tier, ABB Ltd., General Electric Company, and Siemens AG occupy positions shaped by geographic engineering heritage and automation portfolio breadth. ABB Ltd. leverages its Zurich-based power automation lineage to anchor European deployments. General Electric Company represents the digital energy platform archetype spanning transmission and distribution networks. Siemens AG exemplifies IoT-enabled sensor specialization for predictive maintenance applications. These three conglomerates sit within a competitive structure where technical leadership in fault detection systems and IEC 61850 interoperability determines vendor selection for rate-base-supported modernization programs.
| Leading Market Players |
|---|
| ABB Ltd. |
| General Electric Company |
| Siemens AG |
| Honeywell International Inc. |
| Eaton Corporation |
| Aclara Technologies LLC |
| Itron Inc. |
| Schneider Electric |
| Landis+Gyr Group AG |
| Others |
Supply Flow & Price Mechanics
Neodymium and dysprosium price swings for magnetic sensing cores cascade through three distinct equipment tiers, with foundry capacity constraints in Taiwan amplifying procurement premiums for utilities seeking IEC 61850-certified modules.
Pricing Analysis
High-volume wireless sensor deployments capture thin margins through standardized transducer modules, while IoT-enabled edge computing arrays with embedded AI governance command premium positioning. Price differentiation rests on IEC 62351 cybersecurity certification tier and after-sales service bundling. Pricing pressure stems from semiconductor supply concentration, compressing margins for vendors without long-term foundry agreements. Municipal utilities in rate-base-constrained jurisdictions exhibit highest price sensitivity; German TSOs with grid stability mandates show lowest.
Supply Chain Analysis
India's domestic-content thresholds for smart metering tenders and China's GB standards compliance requirements are redirecting component sourcing toward local assembly partnerships. Analog-to-digital converter and MEMS foundry capacity clusters in Taiwan, South Korea, and Japan. Raw material dependencies span neodymium and dysprosium for magnetic cores, silicon carbide substrates for power electronics, and optical-grade lithium niobate for Pockels cell transducers. Single-source vulnerability concentrates in Taiwan semiconductor fabrication. Distribution runs through authorized system integrators with SCADA deployment capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vendors with balance-sheet capacity to underwrite performance-based service agreements, forcing capital-constrained specialists toward acquisition or exit.
For Market Incumbents: Acquire cybersecurity certification capabilities to compress IEC 62351 compliance timelines that currently extend product launches. Anchor defensive positioning through backward integration into MEMS foundry partnerships, mitigating Taiwan supply concentration. Lock in multi-decade service contracts with California and Texas utilities where wildfire and storm resilience mandates intensify downtime cost calculations.
For New Entrants and Emerging Players: Cloud-native distribution platforms bypass incumbent field service networks to reach India's state discom tenders under Revamped Distribution Sector Scheme subsidies. Target vehicle-to-grid residential transformer monitoring where harmonic detection requirements outpace established vendor roadmap priorities. Lead with subscription revenue models tied to digital twin calibration feeds rather than capital equipment sales.
For Investors and Strategic Acquirers: FERC Order 693 thermal monitoring mandate expansion is the leading indicator that transmission-grade sensor demand will outpace distribution retrofit cycles. Position for five-to-ten year holding periods around vendors with embedded AI governance tooling compliant with EU AI Act risk classification frameworks. Watch for optical voltage transducer type-test certification accumulation in Netherlands and Germany as signal of SF6-free switchgear procurement inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Investment | IEC 62351 compliance accelerates market access in FERC-regulated US transmission corridors. |
| Optical Sensing Technology Licensing | Pockels cell voltage transducers eliminate SF6 dependencies under EU F-Gas Regulation schedules. |
| Edge Computing Module Development | On-device inference enables California municipal utilities to meet sub-second wildfire fault localization mandates. |
| Performance-Based Service Agreement | Uptime risk transfer unlocks rate-base-constrained municipal procurement in Texas storm corridors. |
| Domestic Content Partnership | India's RDSS scheme subsidies require local assembly for state discom tender eligibility. |
Methodological Framework
Document review covered FERC reliability standards filings, EU CE marking directives, and State Grid Corporation procurement databases, complemented by interviews with utility planning officers, grid automation engineers, and EPC contractors specializing in substation retrofit. Secondary validation drew from IEC technical committee publications, EIA transmission infrastructure reports, and customs data on sensor module trade flows. Bottom-up unit deployment estimates triangulated against top-down utility capital expenditure projections.
Cross-referencing historical deployment velocity against utility panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include technology architecture, component value chain position, application criticality, and end-user procurement sophistication. CAGRs were derived from regression analysis of regulatory mandate timelines and infrastructure replacement cycles, incorporating edge computing adoption curves and optical sensor certification trajectories as industry-specific inputs.
The model holds under stable regulatory enforcement of FERC Order 693 and EU F-Gas Regulation phase-down schedules; deviation in semiconductor supply availability or cybersecurity certification timeline extensions would shift deployment trajectories. Forecasts reflect these documented assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
South and Central America Smart Grid Market
Smart Grid
Europe Smart Grid Security Market
Smart Grid
South Africa Smart Grid Market
Smart Grid
India Smart Grid Network Market
Smart Grid
North America Automated Demand Response Management System Market
Smart Grid
Microgrid Market
Smart Grid
Global Smart Grid Security Market
Smart Grid
Smart Grid Data Management Market
Smart Grid
United Arab Emirates Smart Grid Market
Smart Grid
North America Smart Grid Market
Smart Grid
Smart Grid Adoption Market
Smart Grid
South Korea Smart Grid Network Market
Smart Grid
China Smart Grid Network Market
Smart Grid
Smart Grid Home Area Network (HAN) Market
Smart Grid
Saudi Arabia Smart Grid Network Market
Smart Grid
Smart Grid Communications Market