
 Albinism Drugs Market | 2026-2036
Albinism Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Albinism Drugs Market Analysis
Specialty clinics is rebalancing toward integrated dermatology-ophthalmology care models for albinism patients, while homecare settings contract as complex photoprotection regimens require professional oversight. AbbVie Inc. leverages its immunology R&D infrastructure to explore anti-inflammatory pathways in oculocutaneous albinism. Novartis AG anchors its rare disease portfolio through partnerships with European reference networks for congenital melanin disorders. Clinuvel Pharmaceuticals Limited specializes in melanocortin receptor agonist development, positioning its photoprotection technology for erythropoietic protoporphyria as a platform extensible to albinism-related UV sensitivity.
Albinism drugs comprise pharmaceutical and device-based interventions targeting melanin deficiency across ocular, cutaneous, and systemic manifestations, with topical formulations typically incorporating titanium dioxide or zinc oxide barriers exceeding SPF 50+ and oral agents modulating melanocyte-stimulating hormone pathways. These therapeutics serve to reduce photodamage risk, correct refractive errors, and prevent skin malignancy in patients with tyrosinase-negative or tyrosinase-positive oculocutaneous variants. Genetic therapies represent the fastest-growing segment as CRISPR-based melanin restoration approaches advance through preclinical validation, while topical treatments retain the largest margin pool due to recurring prescription patterns and established reimbursement. Oral medications occupy a transitional position, with sustained-release nitisinone analogs showing promise in modifying pigmentary phenotype.
FDA orphan drug designation and EMA's Committee for Orphan Medicinal Products shape clinical development incentives, compressing trial timelines and reducing regulatory fees for sponsors addressing populations below 200,000 in the United States. ISO 14155 good clinical practice standards govern multinational trial conduct, while national health technology assessment bodies in Germany and France determine market access for novel genetic therapies. Stakeholders must monitor how payer evidence requirements for gene therapy durability will reshape investment priorities across small-molecule and biologic platforms.
Market Dynamics
Genetic therapy pipelines are compressing development timelines for melanin restoration, forcing incumbent topical manufacturers to defend recurring revenue models against potentially curative interventions. This structural tension between chronic management and disease modification is reallocating R&D budgets across the competitive landscape.
Growth Catalysts
- FDA Orphan Drug Incentives:Tax credits and waived user fees for sponsors addressing populations below 200,000 patients accelerate clinical trial initiation for oculocutaneous albinism candidates.
- European Reference Networks:Cross-border healthcare coordination for congenital melanin disorders pools patient data and streamlines recruitment for multinational studies.
- Photoprotection Technology:Advances in melanocortin receptor agonist formulation are expanding addressable UV sensitivity beyond erythropoietic protoporphyria into albinism-related indications.
Market Restraints
- Tyrosinase Enzyme Instability:Topical melanin precursors degrade rapidly under ambient light and temperature, requiring cold-chain distribution that elevates pharmacy fulfillment costs.
- Specialist Concentration:Dermatology-ophthalmology dual certification remains concentrated in academic medical centers across Germany, Japan, and the United States, limiting patient access in secondary markets.
- Gene Therapy Manufacturing:Viral vector production capacity constraints at contract development organizations create enrollment bottlenecks for CRISPR-based pigment restoration trials.
Strategic Opportunities
- India's Rare Disease Policy:Center-funded treatment cost coverage for notified conditions creates reimbursement infrastructure applicable to albinism drug categories.
- Telemedicine Integration:Remote dermatoscopy and refraction monitoring enable rural patient management without travel to specialty clinics.
- Japan's Sakigake Designation:Priority review vouchers for regenerative medicine products accelerate melanocyte stem cell therapy timelines.
Industry Challenges
- Genetic Counselor Shortage:Oculocutaneous albinism variant interpretation requires specialized expertise unavailable in most community hospitals.
- Multi-Site Trial Coordination:ISO 14155 compliance across FDA, EMA, and PMDA jurisdictions demands redundant quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Albinism Drugs Market |
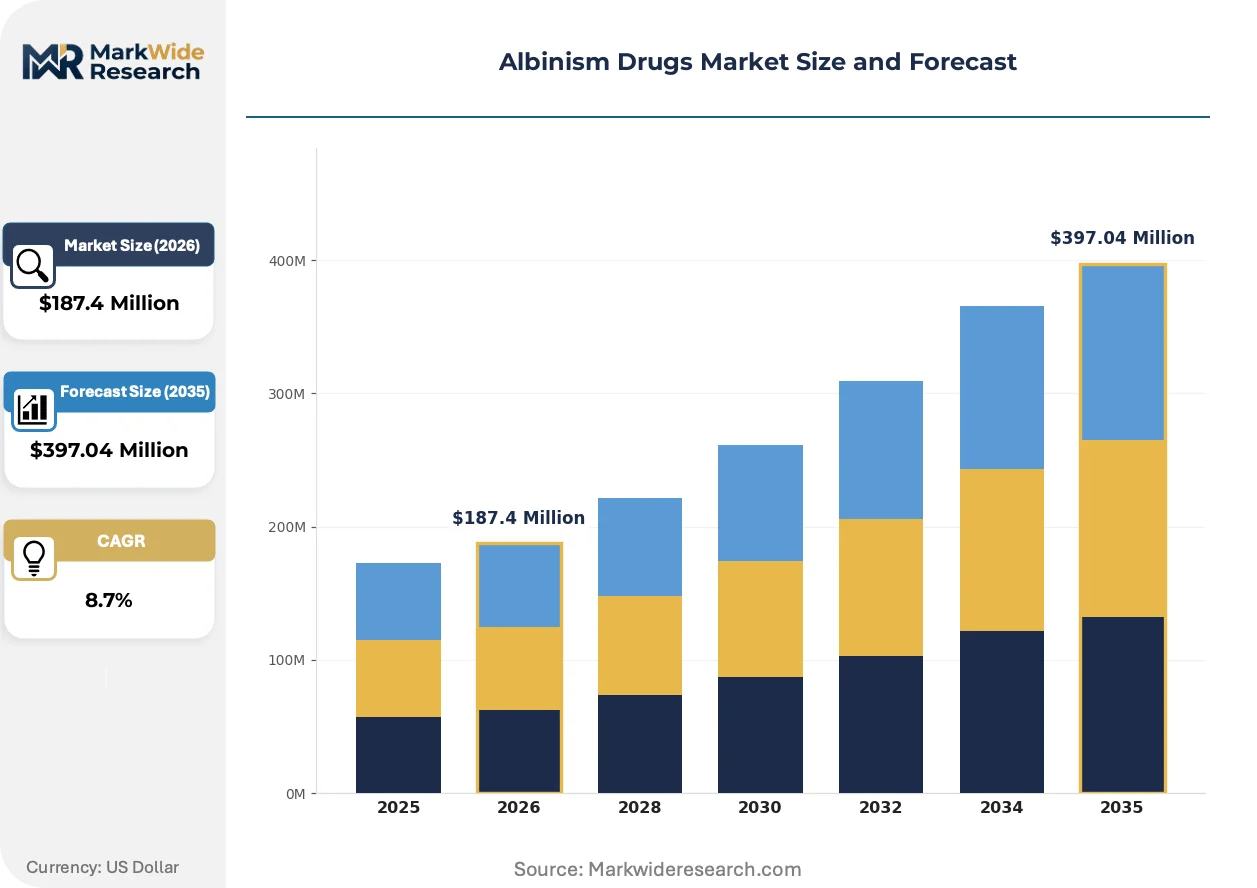
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Treatments, Oral Medications, Light Filters, Genetic Therapies End User: Hospitals, Specialty Clinics, Homecare Settings, Pharmacies Application: Cosmetic Treatments, Vision Correction, Skin Protection, Preventative Care Distribution Channel: Direct Sales, Online Pharmacies, Retail Drugstores, Wholesalers |
| Companies Covered | AbbVie Inc., Novartis AG, Pfizer Inc., Merck & Co., Inc., Johnson & Johnson Services, Inc., Clinuvel Pharmaceuticals Limited, Roche Holding AG, Sanofi S.A., Takeda Pharmaceutical Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Albinism Drugs Market Emerging Trajectories
CRISPR-based melanin restoration is advancing through preclinical validation, while topical barrier formulations incorporate bioadhesive polymers to extend photoprotection duration. These parallel tracks are fragmenting the therapeutic paradigm between chronic management and potential disease modification.
Gene editing platforms targeting TYR, OCA2, and TYRP1 mutations are integrating lipid nanoparticle delivery systems to improve melanocyte transfection efficiency. Academic medical centers in Boston and Rotterdam are adopting these constructs for investigator-initiated trials. The technology is integrating viral vector manufacturing constraints into early-phase protocol design, compressing dose-escalation timelines.
EMA's Committee for Orphan Medicinal Products has streamlined scientific advice procedures for congenital melanin disorders, reducing pre-submission meeting intervals from 90 to 60 days. This regulatory acceleration enables parallel protocol development across US and European sites. Small-molecule sponsors are responding by front-loading pediatric investigation plans to align with EMA's early engagement pathways.
Patient advocacy organizations are consolidating procurement influence through centralized registry databases in the United States and Germany. These platforms are displacing fragmented individual physician prescribing by directing members to clinical trial networks and approved therapy access programs. The concentration is most visible in national albinism associations negotiating formulary placement directly with pharmacy benefit managers.
Albinism Drugs Market Segmentation
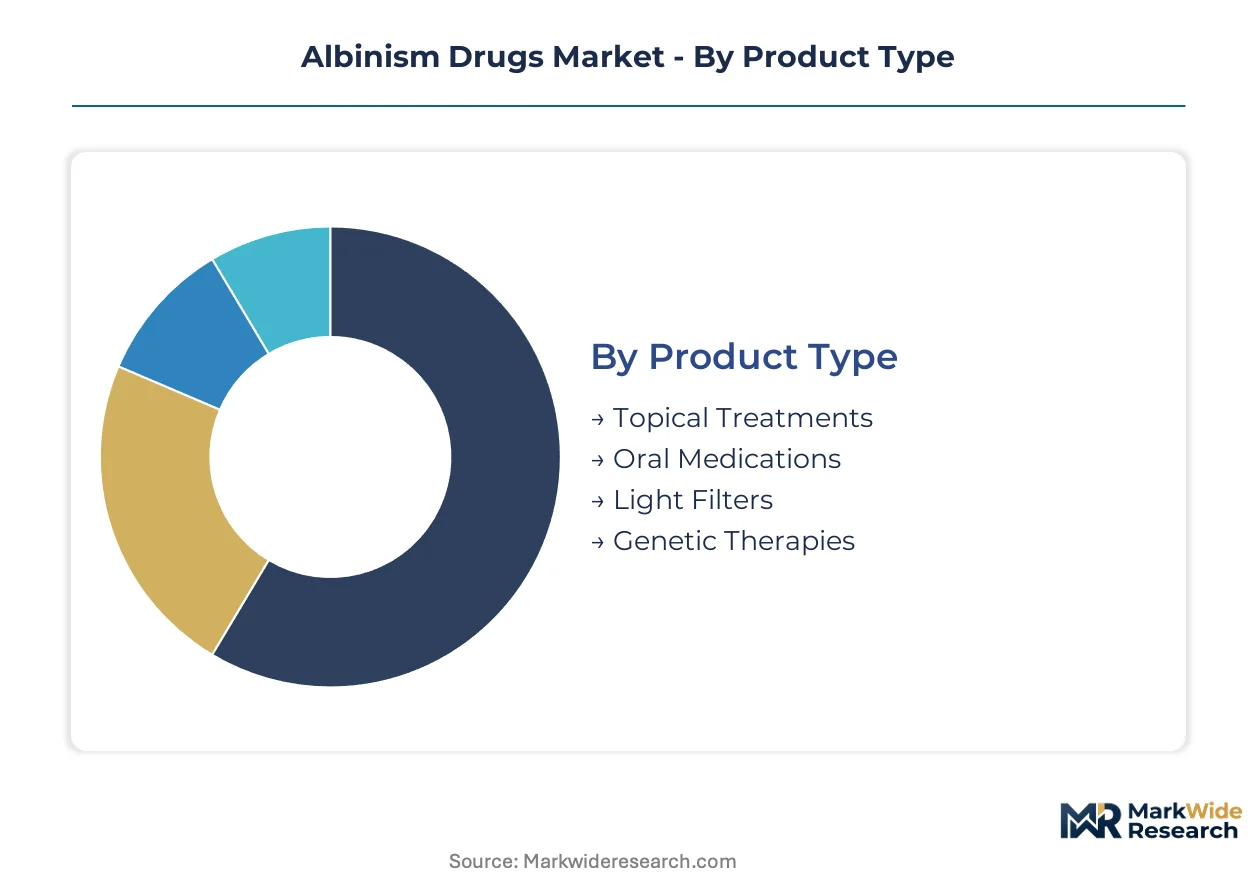
Albinism therapeutics fragment across intervention intensity and care setting, with genetic therapies disrupting chronic management models while topical barriers defend recurring revenue streams. Treatment selection hinges on phenotype severity, photodamage history, and access to specialized dermatology-ophthalmology coordination.
Product Type:
Prescriber choice pivots on curative intent versus symptom control, with reimbursement durability and manufacturing scalability determining commercial viability across modalities.
- Topical Treatments:Formulations incorporate titanium dioxide or zinc oxide barriers exceeding SPF 50+ alongside bioadhesive polymers to extend photoprotection duration. Demand clusters in Germany and the United States where specialty clinics manage complex hypopigmentation regimens requiring professional oversight rather than self-administration.
- Genetic Therapies:CRISPR-based melanin restoration approaches advance through preclinical validation, targeting TYR, OCA2, and TYRP1 mutations via lipid nanoparticle delivery systems. Academic medical centers in Boston and Rotterdam are adopting these constructs for investigator-initiated trials, compressing dose-escalation timelines despite viral vector manufacturing constraints at contract development organizations.
- Oral Medications:Sustained-release nitisinone analogs show promise in modifying pigmentary phenotype, occupying a transitional position between chronic and curative paradigms.
- Light Filters:Device-based interventions reduce photodamage risk through spectral modification, serving patients with tyrosinase-negative or tyrosinase-positive oculocutaneous variants.
Volume sits with topical treatments; growth tilts toward genetic therapies.
End User:
Care delivery is rebalancing toward integrated service lines as home-based management contracts for complex cases.
- Specialty Clinics:Dermatology-ophthalmology dual certification concentrates in academic medical centers across Germany, Japan, and the United States, creating access bottlenecks that elevate per-patient revenue but limit addressable population.
- Hospitals:Tertiary centers anchor genetic therapy administration and surgical vision correction, drawing referrals from national patient registries in markets with structured rare disease pathways.
- Homecare Settings:Simple photoprotection regimens sustain residual volume, though professional oversight requirements are compressing this segment.
- Pharmacies:Dispensing functions consolidate as patient advocacy organizations direct members to clinical trial networks and approved therapy access programs.
Revenue concentrates in specialty clinics; patient flow is shifting toward hospital-based genetic therapy administration.
Application:
Clinical priority sequences interventions by malignancy risk and functional impairment severity.
- Skin Protection:Photodamage prevention dominates prescription volume, with barrier formulations requiring cold-chain distribution that elevates pharmacy fulfillment costs due to tyrosinase enzyme instability under ambient conditions.
- Vision Correction:Refractive error management and nystagmus intervention drive ophthalmology service line expansion, particularly in Japan where national screening programs identify pediatric cases early.
- Preventative Care:Skin malignancy surveillance protocols create recurring consultation demand, especially in Australia and South Africa with high ambient UV exposure.
- Cosmetic Treatments:Pigmentation restoration for psychosocial outcomes occupies a niche position, with limited reimbursement outside private pay markets.
Prescription frequency peaks in skin protection; therapeutic innovation is concentrating in vision correction.
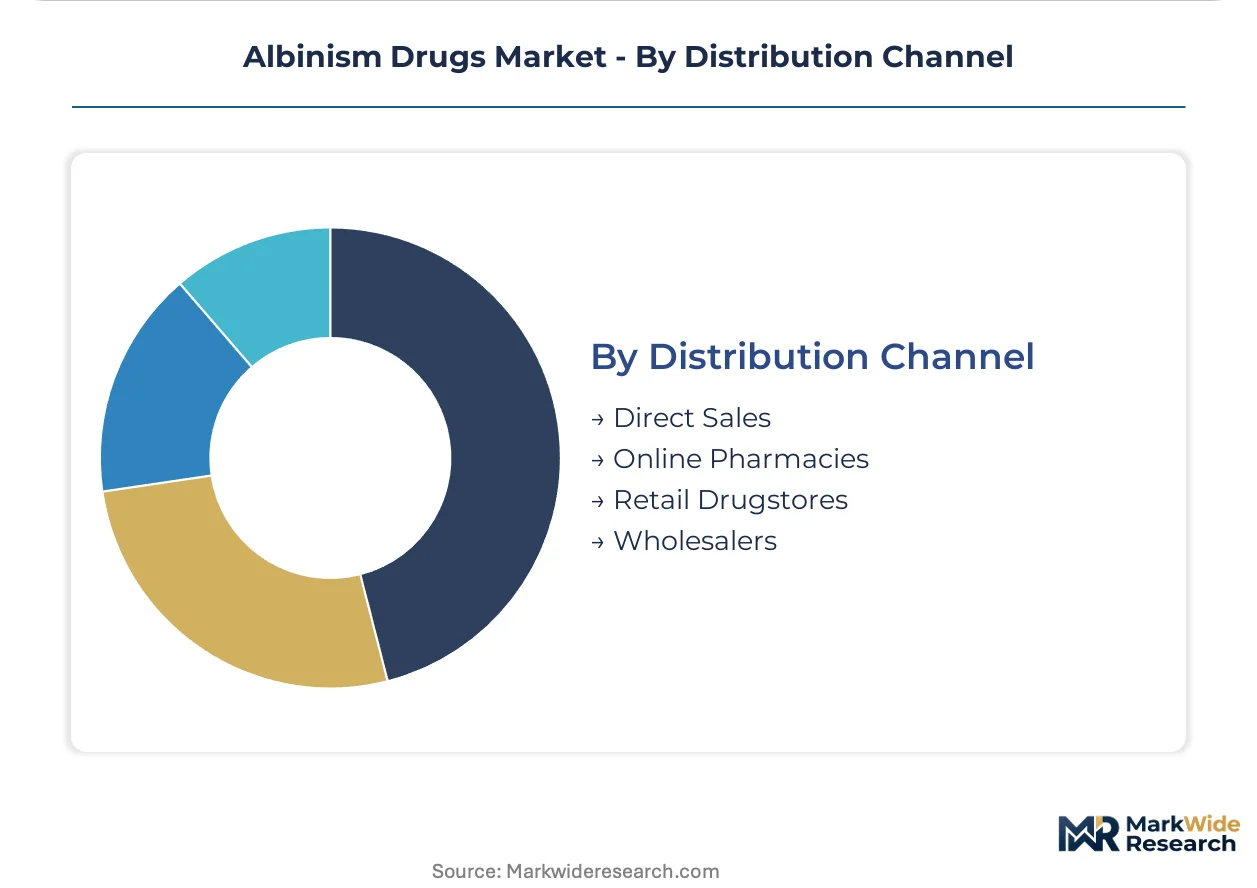
Distribution Channel:
Channel selection reflects product temperature sensitivity, prescriber concentration, and patient mobility constraints.
- Direct Sales:Manufacturer-to-clinic relationships dominate genetic therapy and specialty device distribution, bypassing wholesale markup for high-value, low-volume therapeutics.
- Online Pharmacies:Telemedicine integration is expanding rural access to photoprotection refills, though cold-chain requirements limit applicable product categories.
- Retail Drugstores:Standard SPF formulations sustain foot traffic in markets with established albinism prevalence and patient registry penetration.
- Wholesalers:Inventory aggregation functions persist for oral medications with ambient storage profiles and broader prescriber bases.
Margin capture favors direct sales; volume expansion is tilting toward online pharmacies with telemedicine integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty pharmaceutical zones in Massachusetts and Basel-Stadt concentrate melanin-therapeutics R&D, with tax-advantaged research parks anchoring clinical trial infrastructure for rare dermatological conditions.
United States
Academic medical centers in Boston and Philadelphia drive genetic therapy development for oculocutaneous albinism variants. FDA orphan drug tax credits reduce sponsor costs for trials enrolling below 200,000 patients. The Massachusetts biotechnology corridor houses contract development organizations specializing in viral vector manufacturing for CRISPR-based pigment restoration studies.
Germany
Dermatology-ophthalmology dual certification concentrates in university hospitals across Munich and Heidelberg, creating referral bottlenecks that elevate per-patient revenue. EMA's Committee for Orphan Medicinal Products compresses scientific advice timelines from 90 to 60 days for congenital melanin disorders. The Rhine-Main metropolitan region anchors European reference network coordination for cross-border rare disease data pooling.
Japan
National pediatric screening programs in Tokyo and Osaka identify oculocutaneous cases early, channeling patients toward specialized refractive correction services. METI's Sakigake designation accelerates priority review for regenerative medicine products including melanocyte stem cell therapies. The Kansai region's pharmaceutical manufacturing base supports photoprotection formulation production for Asia-Pacific distribution.
India
Center-funded rare disease treatment cost coverage under the National Policy for Rare Diseases creates reimbursement infrastructure applicable to albinism drug categories. CDSCO streamlined approval pathways for orphan indications reduce sponsor regulatory burden. Hyderabad's active pharmaceutical ingredient cluster supplies tyrosinase-stabilizing excipients for topical barrier formulations.
Australia
High ambient UV exposure in Queensland and Western Australia drives demand for skin malignancy surveillance protocols and photodamage prevention regimens. TGA priority review vouchers for rare disease therapeutics accelerate market entry timelines. Sydney's dermatology research institutes coordinate multicenter studies on melanocortin receptor agonist applications beyond erythropoietic protoporphyria.
Albinism Drugs Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated pharmaceutical conglomerates controlling genetic therapy pipelines while regional formulators dominate topical photoprotection supply. Market structure tilts toward consolidation at the innovation-intensive end, where viral vector manufacturing constraints limit viable sponsors to capitalized entities. Three archetypes populate the competitive terrain: immunology-platform diversifiers extending into anti-inflammatory pigment pathways, rare-disease pure-plays leveraging orphan regulatory incentives, and dermatology-device hybrid operators. Dominant competitive moves include strategic partnerships with European reference networks for patient recruitment and backward integration into lipid nanoparticle delivery system production.
Among Swiss-based rare disease specialists, Novartis AG and Roche Holding AG exemplify the diversified pharmaceutical archetype, anchoring positions through congenital melanin disorder portfolio breadth. Clinuvel Pharmaceuticals Limited, an Australian limited company, occupies a distinct niche within photoprotection technology development, representing the single-indication specialist model.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Novartis AG |
| Pfizer Inc. |
| Merck & Co., Inc. |
| Johnson & Johnson Services, Inc. |
| Clinuvel Pharmaceuticals Limited |
| Roche Holding AG |
| Sanofi S.A. |
| Takeda Pharmaceutical Company Limited |
| Others |
Supply Flow & Price Mechanics
Lipid nanoparticle delivery system manufacturing is compressing production economics for genetic therapy developers while concentrating supply leverage among viral vector contract development organizations with validated GMP suites. This technological transition simultaneously elevates cold-chain fulfillment costs for topical melanin precursors and creates dual-tier pricing power between curative and chronic management paradigms.
Pricing Analysis
Premium pricing attaches to short-lead-time viral vector slots at contract manufacturing organizations, while spot inventory of tyrosinase-stabilizing excipients trades at discounts. Three-tier pricing structure across premium genetic therapy, standard oral analogs, and economy topical barriers reflects certification grade and cold-chain compliance. Cost compression in economy barriers is intensifying because Indian API suppliers are scaling tyrosinase-stabilizing excipient production. Hospital procurement committees show highest price sensitivity for chronic photoprotection regimens; academic medical centers accept premium positioning for investigator-initiated genetic therapy trials.
Supply Chain Analysis
Specialized viral vector production workforce availability concentrates in Massachusetts, Basel-Stadt, and the Kansai region, creating recruitment bottlenecks that elevate contract manufacturing rates. Manufacturing draws from lipid nanoparticle feedstocks, GMP-grade plasmid DNA, and temperature-stabilized zinc oxide barriers. Single-source vulnerability runs through European reference network-coordinated patient recruitment for multinational trials. Distribution runs through direct manufacturer-to-specialty-clinic relationships for genetic therapies, bypassing wholesale markup.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
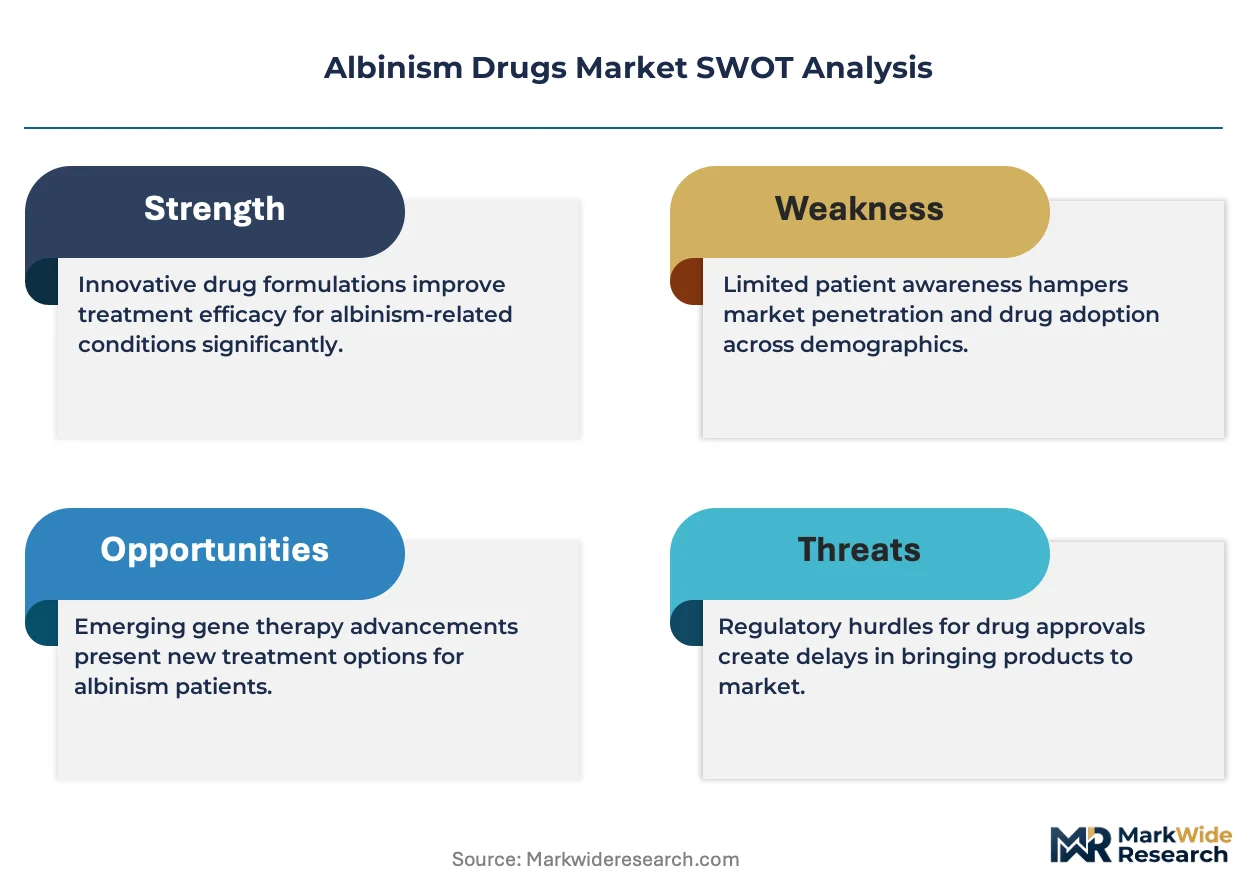
FDA orphan drug tax credits and EMA's Committee for Orphan Medicinal Products fee waivers erect a cost-of-compliance moat that favors capitalized sponsors with established regulatory affairs infrastructure over underfunded entrants.
For Market Incumbents: Lock in backward integration into lipid nanoparticle production to secure supply continuity against viral vector manufacturing bottlenecks. Secure exclusive partnerships with European reference networks for congenital melanin disorders to preempt competitor patient recruitment. Defend recurring revenue streams in topical photoprotection by extending bioadhesive polymer patent estates against CRISPR-based melanin restoration substitution. For New Entrants and Emerging Players: Specialty clinics with dermatology-ophthalmology dual certification represent the most penetrable channel partner type for novel genetic therapy administration. Target India's center-funded rare disease reimbursement infrastructure as a white-space geography with established cost-coverage mechanisms. Pursue telemedicine-integrated photoprotection refill services as a go-to-market angle to bypass specialist concentration bottlenecks in secondary markets. For Investors and Strategic Acquirers: Exit pathways concentrate in rare-disease pure-plays with validated orphan regulatory incentives and Phase II genetic therapy assets. Long-term viability hinges on durability of gene editing efficacy data across the projection horizon. Acquisition target archetype: Australian or Swiss photoprotection specialists with melanocortin receptor agonist platforms extensible to albinism indications. Monitor EMA scientific advice timeline compression as an inflection signal for regulatory acceleration momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA tax credits and waived user fees compress clinical trial initiation costs for sponsors. |
| European Reference Network Partnership | Cross-border patient data pooling streamlines recruitment for multinational melanin restoration studies. |
| Lipid Nanoparticle Manufacturing Scale-Up | In-house production of delivery vectors reduces dependency on constrained contract development organization capacity. |
| Telemedicine Platform Integration | Remote dermatoscopy and refraction monitoring expands rural access beyond specialist clinic concentration. |
| Pediatric Investigation Plan Front-Loading | Early EMA engagement aligns development timelines with accelerated scientific advice pathways. |
Methodological Framework
Independent corroboration across regulatory affairs specialists at FDA and EMA, drug development executives at rare-disease pure-plays, and formulary directors at German statutory health insurers underwrites the qualitative findings. Primary interviews with hospital procurement managers, payer access specialists, and European reference network coordinators combined with secondary validation from FDA orphan drug designations, EMA Committee for Orphan Medicinal Products opinions, ClinicalTrials.gov albinism protocol registrations, and national patient registry disclosures. Bottom-up patient flow modeling and top-down pharmaceutical expenditure triangulation anchored volume estimates.
Rate-of-change decomposition across treatment modality, care setting, and regional regulatory cluster enabled segment-level CAGR derivation. The analytical framework projects adoption curves for genetic therapies against erosion of chronic management revenue streams throughout the forecast period. Modeled inputs include viral vector manufacturing capacity expansion timelines, EMA scientific advice procedural acceleration effects, and India's rare disease policy reimbursement infrastructure maturation.
Caveats apply where gene therapy durability data from early-phase trials, viral vector manufacturing scale-up bottlenecks, or payer evidence requirements for one-time curative interventions could materially shift the outlook. Forecasts reflect assumptions about regulatory pathway stability and manufacturing capacity expansion without guaranteed realization. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Rosuvastatin Market
Pharmaceuticals
Global Lifestyle Drugs Market
Pharmaceuticals
Focal Segmental Glomerulosclerosis (FSGS) Therapeutics Market
Pharmaceuticals
US Over the Counter Drugs Market
Pharmaceuticals
API Contract Manufacturing Market
Pharmaceuticals
Cryoprecipitated Antihemophilic Factor Market
Pharmaceuticals
India Opioids Market
Pharmaceuticals
Global Basal Insulin Market
Pharmaceuticals
Global Interleukin Inhibitors Market
Pharmaceuticals
Global Alteplase Market
Pharmaceuticals
Naproxen Market
Pharmaceuticals
Oral Antibiotics Market
Pharmaceuticals
Peptide Therapeutics Market
Pharmaceuticals
Iceland Pharmaceutical Market
Pharmaceuticals
Ebola Drug and Vaccine Market
Pharmaceuticals
Allergic Rhinitis Drugs Market