
 Global Hepatitis B Vaccines Market | 2026-2036
Global Hepatitis B Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hepatitis B Vaccines Market Foresight
Market Context
Subscription-based procurement models for multi-dose vaccine series is consolidating purchasing power among national immunization programs. GSK plc leverages its recombinant platform dominance across European tender systems. Sanofi anchors supply security through long-term agreements with UNICEF and Gavi. Serum Institute of India Pvt. Ltd. competes aggressively on cost per dose in emerging markets.
Technical Definition and Structural Segments
Hepatitis B vaccines are sterile suspensions containing purified hepatitis B surface antigen (HBsAg) produced through recombinant DNA technology in yeast or mammalian cell substrates, formulated to induce protective anti-HBs antibody titers exceeding 10 mIU/mL. Recombinant vaccines occupy the core volume position due to manufacturing scalability and safety profile advantages over plasma-derived alternatives. Adjuvanted formulations capture premium positioning where rapid seroprotection is clinically prioritized, while combination vaccines containing DTP-HepB-Hib components dominate public program procurement by reducing cold chain complexity and injection burden.
Regulatory Framework and Outlook
FDA batch release protocols, WHO prequalification standards, and EMA centralized marketing authorizations collectively gate market access and shape formulation requirements across jurisdictions. India's CDSCO and China's NMPA enforce localized clinical bridging studies that extend registration timelines but protect domestic manufacturers. Stakeholders must monitor evolving WHO policy shifts on birth-dose timing and adult booster recommendations to align R&D pipelines with procurement criteria.
Market Dynamics
WHO prequalification standards are consolidating procurement authority among national immunization programs, forcing manufacturers to reformulate for thermostability and single-dose presentation to qualify for Gavi and UNICEF tenders.
Growth Catalysts
- Brazilian pediatric expansion:Routine infant immunization schedules at pediatric centers are extending birth-dose coverage into underserved municipalities, creating new volume anchors in Latin America.
- WHO birth-dose policy:Accelerated timing recommendations for neonatal administration are compressing the window between delivery and seroprotection, favoring single-dose adjuvanted formulations.
- Southeast Asian adult campaigns:National immunization programs in Vietnam, Indonesia, and Thailand are scaling catch-up vaccination for unimmunized adults, opening demographic expansion beyond pediatric baselines.
Market Restraints
- Yeast substrate concentration:Recombinant HBsAg production depends on Saccharomyces cerevisiae fermentation capacity concentrated in three manufacturing clusters, creating input bottlenecks during demand surges.
- CDSCO bridging requirements:India's localized clinical study mandates add 18-24 months to registration timelines, delaying market entry for foreign recombinant platforms.
- Plasma-derived substitution ceiling:Regional preference for traditional vaccines in parts of Eastern Europe and Central Asia caps recombinant penetration despite superior safety profiles.
Strategic Opportunities
- Hexavalent combination convergence:DTP-HepB-Hib-IPV-HepA formulations are capturing premium positioning in European tender systems by reducing injection burden and cold chain complexity.
- Nigerian birth-dose integration:Underpenetrated maternal-child health infrastructure presents white space for single-dose thermostable presentations delivered through community health workers.
- EMA centralized pathways:Mutual recognition procedures are streamlining multi-country access for adjuvanted adult boosters, compressing time-to-revenue for novel formulations.
Industry Challenges
- Bioprocess engineering talent scarcity:Recombinant yeast fermentation and downstream purification require specialized expertise concentrated at legacy plasma fractionation facilities, constraining capacity expansion.
- Prequalification documentation burden:WHO stability and potency dossier requirements demand 24-36 month lead times, freezing formulation innovation cycles.
- Cold chain reconfiguration friction:Transitioning from multi-dose vials to single-dose presentations disrupts existing distribution infrastructure in low-income countries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hepatitis B Vaccines Market |
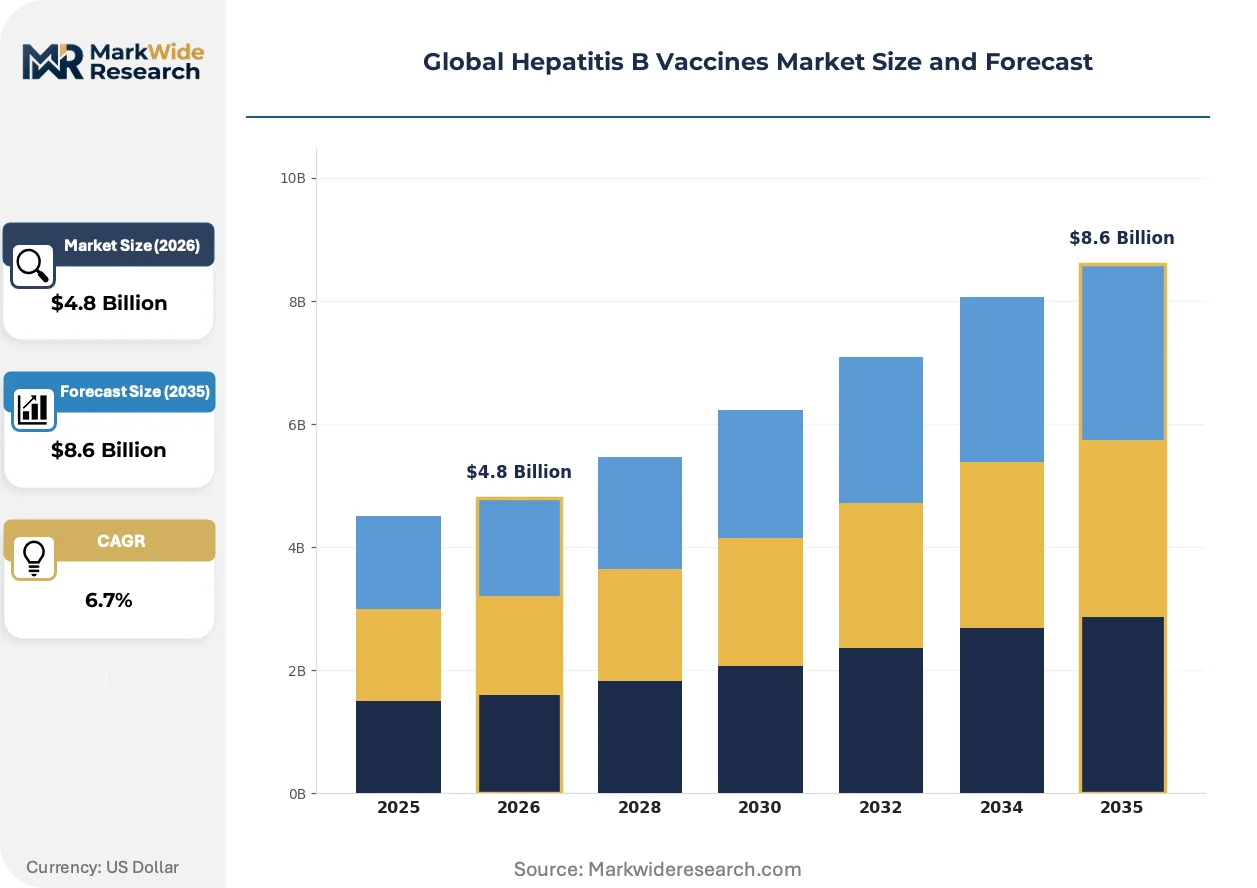
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Recombinant, Plasma-Derived, Combination, Adjuvanted Administration Route: Intramuscular, Intradermal, Subcutaneous, Oral End User: Public Health Programs, Immunization Clinics, Pediatric Centers, Occupational Health Services Application: Infant Immunization, Adult Immunization, High-Risk Groups, Post-Exposure Prophylaxis |
| Companies Covered | GSK plc, Sanofi, Merck & Co., Inc., Dynavax Technologies Corporation, VBI Vaccines Inc., Gilead Sciences, Inc., Beijing Minhai Biological Technology Co., Ltd., Serum Institute of India Pvt. Ltd., LG Chem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hepatitis B Vaccines Market Shifts & Advancements
Recombinant platform maturation is converging with thermostable formulation science to reshape competitive positioning across temperature-variable distribution environments.
RNA-amplified recombinant platforms are expanding into birth-dose applications through improved immunogenicity at lower antigen loads. UNICEF and Gavi procurement officers are accelerating qualification timelines for these candidates. Thermostable presentations are compressing cold chain requirements, enabling last-mile delivery through community health worker networks.
EMA centralized marketing authorizations are harmonizing stability requirements across member states, forcing manufacturers to standardize on 2-8°C profiles with heat-stable backup claims. This regulatory convergence is elevating documentation costs for smaller plasma-derived producers. Adjuvanted formulations targeting rapid seroprotection are absorbing the most significant compliance burden.
Subscription-based tender structures are consolidating purchasing power among national immunization programs, displacing spot-market procurement for multi-dose series. European and Southeast Asian ministries of health are locking in 3-5 year supply agreements with penalty clauses for stockout events. This behavioral shift is compressing supplier margins while securing volume commitments for qualified manufacturers.
Global Hepatitis B Vaccines Market Segmentation
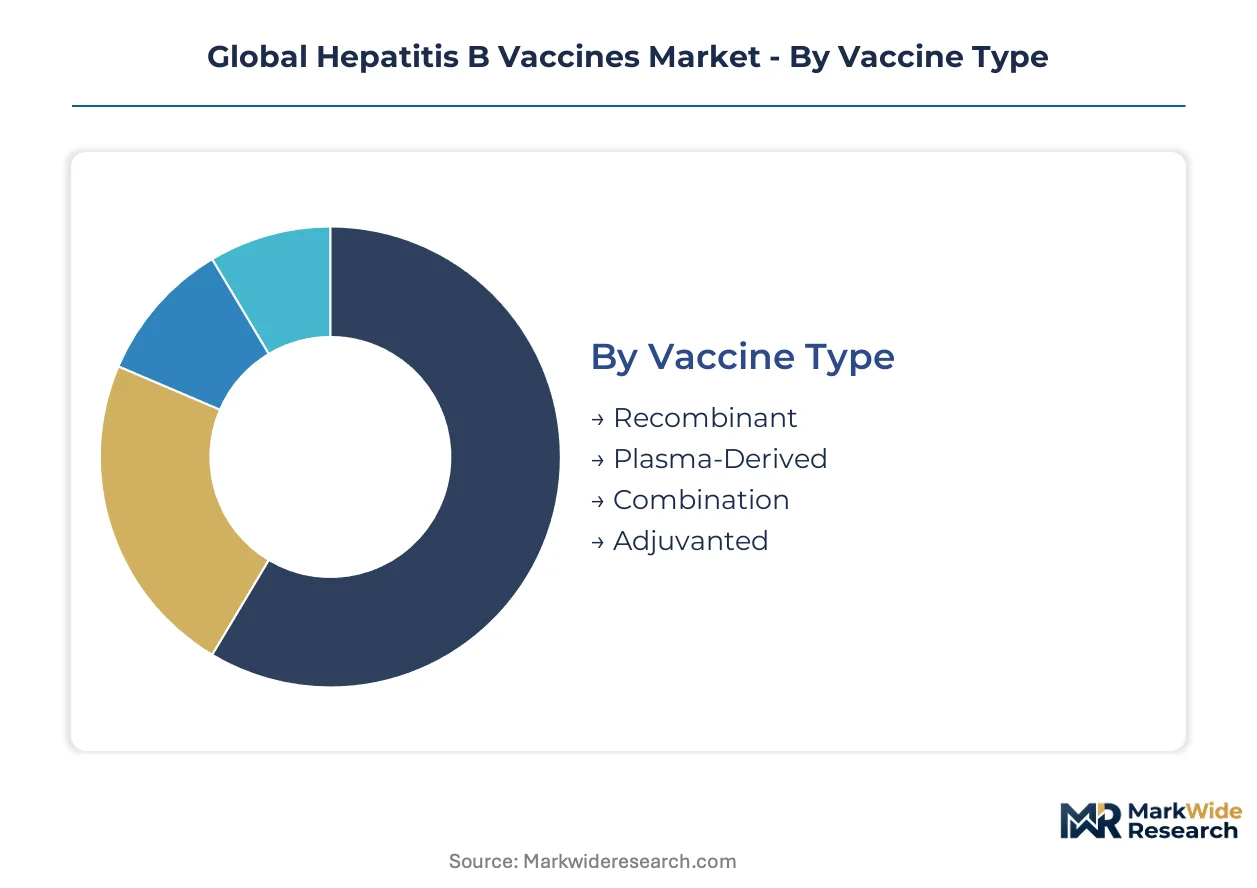
Segmentation in hepatitis B vaccines reveals how procurement criteria diverge between public tenders and private channels. Manufacturers must align formulation choices with the temperature stability, dosing schedules, and presentation formats demanded by each buyer type.
Vaccine Type:
Volume production concentrates in recombinant platforms, while premium positioning attaches to specialized formulations requiring advanced adjuvant science or combination engineering.
- Recombinant:Yeast-based HBsAg expression dominates manufacturing throughput due to Saccharomyces cerevisiae fermentation scalability. Demand anchors in Gavi-eligible countries where WHO prequalification requirements favor recombinant safety profiles over legacy alternatives.
- Combination:DTP-HepB-Hib and hexavalent formulations reduce cold chain burden through consolidated antigen delivery. European tender systems and Southeast Asian national programs are scaling procurement of these presentations to minimize injection visits.
- Plasma-Derived:Regional preference persists in Eastern Europe and Central Asia despite safety advantages of recombinant alternatives. Limited new capacity investment reflects declining procurement interest from major international buyers.
- Adjuvanted:Rapid seroprotection requirements in dialysis patients and immunocompromised populations sustain niche premium positioning. EMA centralized pathways are streamlining multi-country access for novel adjuvant platforms.
Mature deployment sits with recombinant platforms. Newer deployment is concentrated in combination and adjuvanted segments.
Administration Route:
Route selection trades immunogenicity optimization against cold chain infrastructure and healthcare worker training requirements.
- Intramuscular:Deltoid or anterolateral thigh delivery remains standard for neonatal and adult dosing across all major procurement systems. WHO birth-dose timing recommendations assume intramuscular administration within 24 hours of delivery.
- Intradermal:Reduced antigen volume per dose enables cost efficiency in resource-constrained settings. India's national program has scaled intradermal delivery for adult catch-up campaigns in selected states.
- Subcutaneous:Limited application in specific patient populations with bleeding disorders. Not a priority route for manufacturer formulation development.
- Oral:Experimental platforms in early clinical evaluation face significant immunological barriers to HBsAg gut absorption. No near-term procurement relevance.
Established practice centers on intramuscular delivery. Alternative routes are gaining traction fastest in cost-sensitive public programs.
End User:
Buyer concentration shapes pricing architecture and contract structures across the value chain.
- Public Health Programs:National immunization programs and Gavi-eligible country tenders drive volume through multi-year supply agreements. UNICEF procurement officers enforce strict prequalification standards that filter supplier participation.
- Pediatric Centers:Birth-dose administration within 24 hours of delivery requires cold chain proximity to maternity wards. Brazilian municipalities are expanding pediatric center coverage into underserved regions.
- Immunization Clinics:Adult catch-up vaccination and occupational health compliance sustain outpatient demand. Vietnam and Thailand are scaling clinic-based adult campaigns.
- Occupational Health Services:Healthcare worker and laboratory personnel vaccination mandates generate predictable recurring demand. Employer-paid procurement operates outside tender systems.
Volume leadership rests with public health programs. Margin expansion concentrates in occupational health and specialized clinic channels.
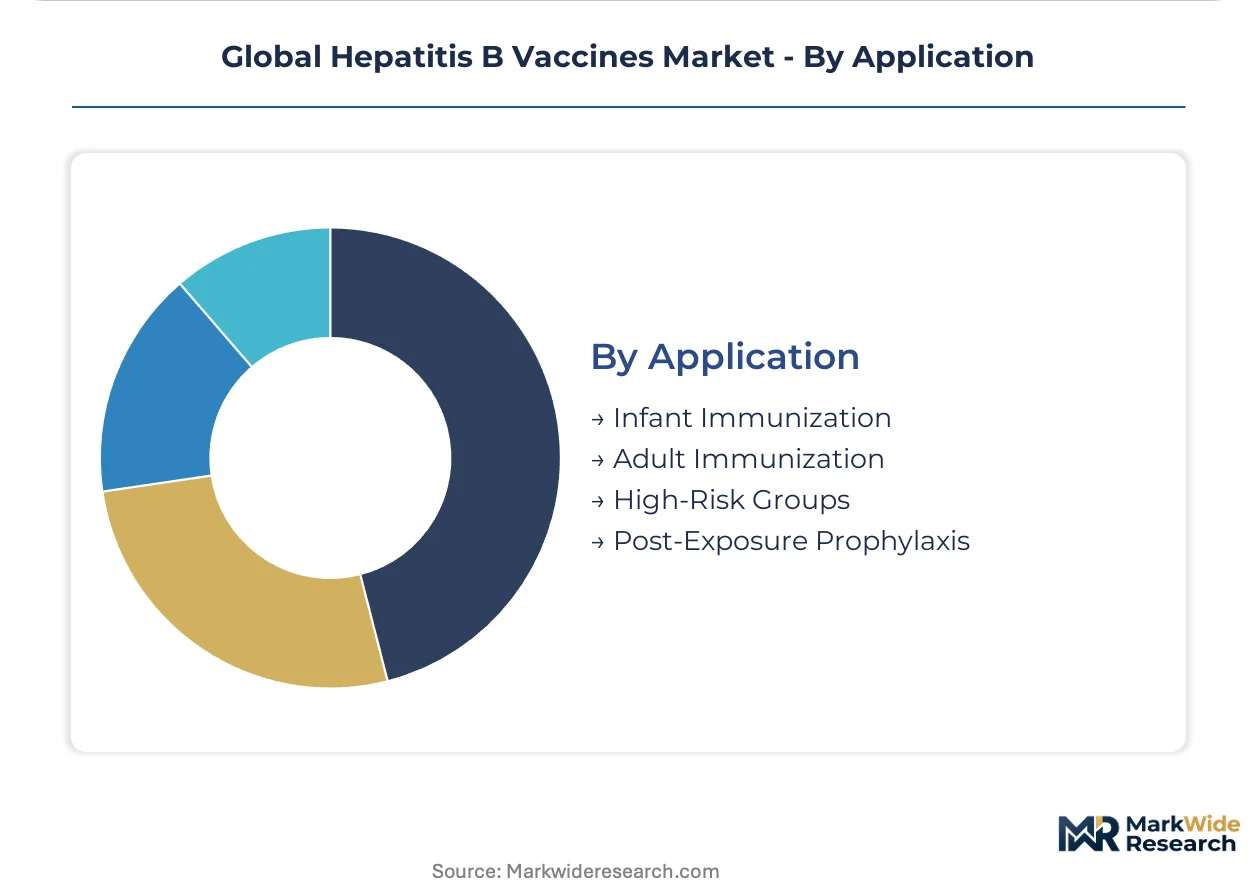
Application:
Demographic targeting determines antigen dose, schedule compression, and adjuvant requirements.
- Infant Immunization:Birth-dose within 24 hours followed by primary series completion defines the volume base. WHO policy shifts on accelerated timing are compressing the window between delivery and seroprotection.
- Adult Immunization:Catch-up campaigns for unimmunized populations are expanding in Vietnam, Indonesia, and Thailand. Two-dose schedules for healthy adults reduce completion burden versus pediatric three-dose regimens.
- High-Risk Groups:Dialysis patients, HIV-positive individuals, and injection drug users require higher antigen doses or adjuvanted formulations. CDSCO bridging study requirements complicate registration of specialized products for Indian high-risk populations.
- Post-Exposure Prophylaxis:Hepatitis B immunoglobulin co-administration with accelerated vaccine schedules follows needlestick and sexual exposure protocols. Hospital procurement systems manage this application separately from routine immunization.
Pediatric birth-dose capture represents the most mature application. Adult expansion and high-risk specialization are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing clusters in India and China supply the bulk of global Hepatitis B vaccine volume, while demand concentrates in Southeast Asian national immunization programs and Brazilian pediatric networks. Consumption patterns diverge sharply between Gavi-eligible countries prioritizing cost per dose and European tender systems favoring combination formulations.
United States
FDA batch release protocols govern recombinant platform distribution through occupational health mandates and dialysis center procurement. CDC immunization schedules drive adult catch-up vaccination in clinic settings. Boston and San Francisco biotech corridors host adjuvant formulation R&D for rapid seroprotection applications.
India
CDSCO bridging study requirements extend registration timelines for foreign recombinant platforms while protecting domestic yeast-fermentation capacity. Serum Institute of India Pvt. Ltd. anchors supply to UNICEF through Pune-based manufacturing. Intradermal delivery pilots in Maharashtra and Tamil Nadu reduce antigen volume for adult campaigns.
Brazil
ANVISA regulatory pathways align with WHO prequalification for Gavi-eligible procurement. Municipal pediatric centers in São Paulo and Minas Gerais extend birth-dose coverage into underserved regions. Federal immunization program expansion targets zero-dose children in Amazon basin municipalities.
China
NMPA localized clinical requirements shield domestic recombinant manufacturers from foreign competition. Beijing-Tianjin-Hebei corridor concentrates yeast fermentation capacity for HBsAg production. National immunization program procurement prioritizes thermostable presentations for western province distribution.
Germany
EMA centralized marketing authorizations streamline multi-country access for adjuvanted adult boosters. Bavarian and North Rhine-Westphalia tender systems consolidate purchasing power through multi-year supply agreements. Hexavalent combination vaccines capture premium positioning in pediatric clinic procurement.
Global Hepatitis B Vaccines Market Competitive Landscape
Top-tier vendors anchor European and North American tender systems, while mid-scale recombinant specialists compete on cost per dose in Gavi-eligible markets. The competitive terrain splits between plasma-derived heritage producers defending Eastern European share and yeast-fermentation platforms scaling thermostable formulations. Three archetypes dominate: multinational pharmaceutical conglomerates with recombinant platform dominance, emerging market volume manufacturers with integrated fermentation capacity, and adjuvant technology specialists targeting rapid seroprotection niches. Capacity expansion and WHO prequalification documentation are the primary competitive levers.
Among the multinational tier, GSK plc and Sanofi occupy positions defined by recombinant platform maturity and long-term UNICEF supply agreements. Serum Institute of India Pvt. Ltd. exemplifies the emerging market volume archetype through cost-optimized manufacturing and Gavi procurement penetration. Beijing Minhai Biological Technology Co., Ltd. represents the China-based recombinant specialist segment serving domestic NMPA pathways and select export markets.
| Leading Market Players |
|---|
| GSK plc |
| Sanofi |
| Merck & Co., Inc. |
| Dynavax Technologies Corporation |
| VBI Vaccines Inc. |
| Gilead Sciences, Inc. |
| Beijing Minhai Biological Technology Co., Ltd. |
| Serum Institute of India Pvt. Ltd. |
| LG Chem |
| Others |
Supply & Pricing Matrix
Specialized bioprocess engineering talent concentrated in Bavaria and North Rhine-Westphalia feeds into labor-cost differentials that widen pricing-tier spreads between premium adjuvanted formulations and economy recombinant doses. Yeast-fermentation expertise scarcity in legacy plasma fractionation hubs compresses margins at the standard tier while elevating premium capture for thermostable specialists.
Pricing Analysis
Margin tightening in standard recombinant tiers reflects Gavi procurement consolidation and UNICEF tender compression. Three-tier pricing structure across premium adjuvanted, standard recombinant, and economy bulk-purchase levels separates buyers by immunogenicity urgency and cold-chain capability. Certification grade—WHO prequalification versus national-only registration—drives the widest price spreads. Cost-down pressure on standard formulations accelerates because Brazilian and Southeast Asian national programs are consolidating multi-year supply agreements with penalty clauses. Public health programs exhibit highest price sensitivity; occupational health services and dialysis center procurement show lowest sensitivity due to clinical urgency.
Supply Chain Analysis
India's PLI scheme for domestic biopharmaceutical manufacturing and China's NMPA localized clinical requirements are reshaping sourcing patterns toward captive fermentation capacity. Supply concentrates in India, China, and Germany, with Pune, Beijing-Tianjin-Hebei, and Bavarian corridors anchoring HBsAg production. Saccharomyces cerevisiae fermentation substrates, downstream purification resins, and single-dose presentation materials constitute critical input dependencies. Single-source vulnerability in yeast substrate supply creates structural risk during demand surges. Distribution runs through UNICEF and Gavi central procurement for low-income countries, direct national immunization program tenders for middle-income markets, and hospital procurement systems for occupational health channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Control over recombinant yeast fermentation capacity has become the decisive upstream lever as WHO prequalification timelines stretch and substrate bottlenecks tighten.
For Market Incumbents: Anticipate RNA-amplified platform disruption by locking in thermostable formulation IP and expanding Pune or Bavarian fermentation capacity ahead of competitor qualification cycles. Defend position by securing 5-year supply agreements with Southeast Asian national immunization programs before subscription-based tender structures fully consolidate. Prioritize backward integration into yeast substrate production to insulate margins from Saccharomyces cerevisiae supply volatility. For New Entrants and Emerging Players: Begin with intradermal delivery pilots in Indian states as the most penetrable entry point, leveraging Maharashtra and Tamil Nadu adult campaign infrastructure to demonstrate cost efficiency. Target Nigerian birth-dose integration as white-space geography where maternal-child health infrastructure gaps favor community health worker-deployable thermostable presentations. Pursue CDSCO fast-track pathways for specialized adjuvanted formulations in high-risk group applications where bridging study requirements deter foreign competitors. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale recombinant specialists possessing integrated fermentation capacity and pending WHO prequalification, given Gavi procurement consolidation and tender volume concentration. Long-term viability over the 5-10 year window favors manufacturers with documented thermostability profiles and single-dose presentation capabilities aligned with birth-dose policy shifts. Watch EMA centralized marketing authorization timelines for adjuvanted adult boosters as the inflection signal for premium-tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Expands Saccharomyces cerevisiae fermentation capacity to meet Gavi and UNICEF tender volume commitments. |
| Regulatory Approval Pathway | EMA centralized authorization streamlines multi-country access for novel adjuvanted formulations across member states. |
| Backward Integration | In-house yeast substrate production reduces dependency on concentrated fermentation input suppliers during demand surges. |
| Pipeline Diversification | RNA-amplified recombinant platforms improve immunogenicity at lower antigen loads for birth-dose applications. |
| Long-term Supply Agreement | Multi-year contracts with Brazilian federal immunization programs secure volume anchors in expanding pediatric networks. |
Research Methodology
Multi-period observation of WHO prequalification timelines, Gavi procurement volumes, and national immunization program tender awards anchored the trend analysis, supplemented by interviews with vaccine development executives, regulatory affairs leads at EMA and CDSCO, UNICEF procurement officers, and hospital pharmacy directors. Secondary validation drew from FDA batch release protocols, WHO prequalification dossiers, ClinicalTrials.gov entries, and EMA centralized marketing authorization records. Bottom-up segment sizing and top-down macroeconomic triangulation cross-checked volume and value estimates.
Segment-weighting across vaccine type, administration route, end user, and application dimensions shaped the analytical framework over the projection horizon. Recombinant, combination, plasma-derived, and adjuvanted platform shares were modeled against birth-dose policy evolution and adult campaign scaling. CAGRs derived from regression analysis of historical procurement volumes and elasticity-adjusted demand projections. Forecast inputs incorporated CDSCO and NMPA registration timeline assumptions, thermostable formulation adoption curves, and hexavalent combination tender penetration rates.
Regulatory pathway delays, yeast substrate supply disruptions, and WHO birth-dose policy reversals are the dominant revision risks that could alter trajectory assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Canagliflozin Market
Pharmaceuticals
Esophageal Achalasia Drug Market
Pharmaceuticals
Global Varicella Vaccine Market
Pharmaceuticals
Dental Medication Market
Pharmaceuticals
Global Cancer Vaccines Drug Pipeline Market
Pharmaceuticals
Cytomegalovirus Treatment Market
Pharmaceuticals
Europe Pharmaceutical Contract Manufacturing Market
Pharmaceuticals
In-Silico Drug Discovery Market
Pharmaceuticals
Leukotriene Modifiers Market
Pharmaceuticals
Motilium Market
Pharmaceuticals
Candidiasis Drug Market
Pharmaceuticals
Global Bendamustine Injection Market
Pharmaceuticals
Pharmaceutical Contract Development and Manufacturing Organization (CDMO) Market
Pharmaceuticals
Oral Contraceptive Pills Market
Pharmaceuticals
Nicotine Replacement Product Market
Pharmaceuticals
Decongestants Market