
 Global Anti-Neoplastic Agents Market | 2026-2036
Global Anti-Neoplastic Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anti-Neoplastic Agents Market Foresight
The EU Green Deal's pharmaceutical sustainability requirements are shifting procurement criteria across European hospital networks. F. Hoffmann-La Roche Ltd. anchors its position through in-house production of monoclonal antibody platforms. Novartis AG differentiates via CAR-T cell therapy manufacturing scale. Bristol-Myers Squibb Company leads in checkpoint inhibitor commercialization across major oncology indications.
Anti-neoplastic agents comprise synthetic and biologic compounds designed to inhibit malignant cell proliferation through DNA interference, metabolic disruption, or immune system modulation, typically administered via intravenous infusion or oral dosing regimens with narrow therapeutic indices requiring therapeutic drug monitoring. These agents serve primarily to extend progression-free survival in hematologic and solid tumor malignancies within institutional and outpatient oncology settings. Targeted therapy commands significant investment focus as kinase inhibitors demonstrate superior efficacy profiles in genomically defined patient subsets. Immunotherapy represents the fastest-expanding category as PD-1/PD-L1 inhibitors secure front-line approvals across multiple tumor types. Alkylating agents constitute a mature segment where generic competition has compressed margins despite sustained clinical utility in combination regimens.
FDA breakthrough therapy designation, EMA priority medicines scheme, and NMPA conditional approval pathways collectively compress development timelines while elevating evidence standards for anti-neoplastic agents seeking market access. China's GB standards for biologic manufacturing and India's CDSCO biosimilar guidelines further shape regional competitive dynamics through quality benchmarks and local production incentives. Stakeholders must monitor evolving reimbursement negotiations for cell and gene therapies as payors develop novel outcome-based contracting frameworks.
Market Dynamics
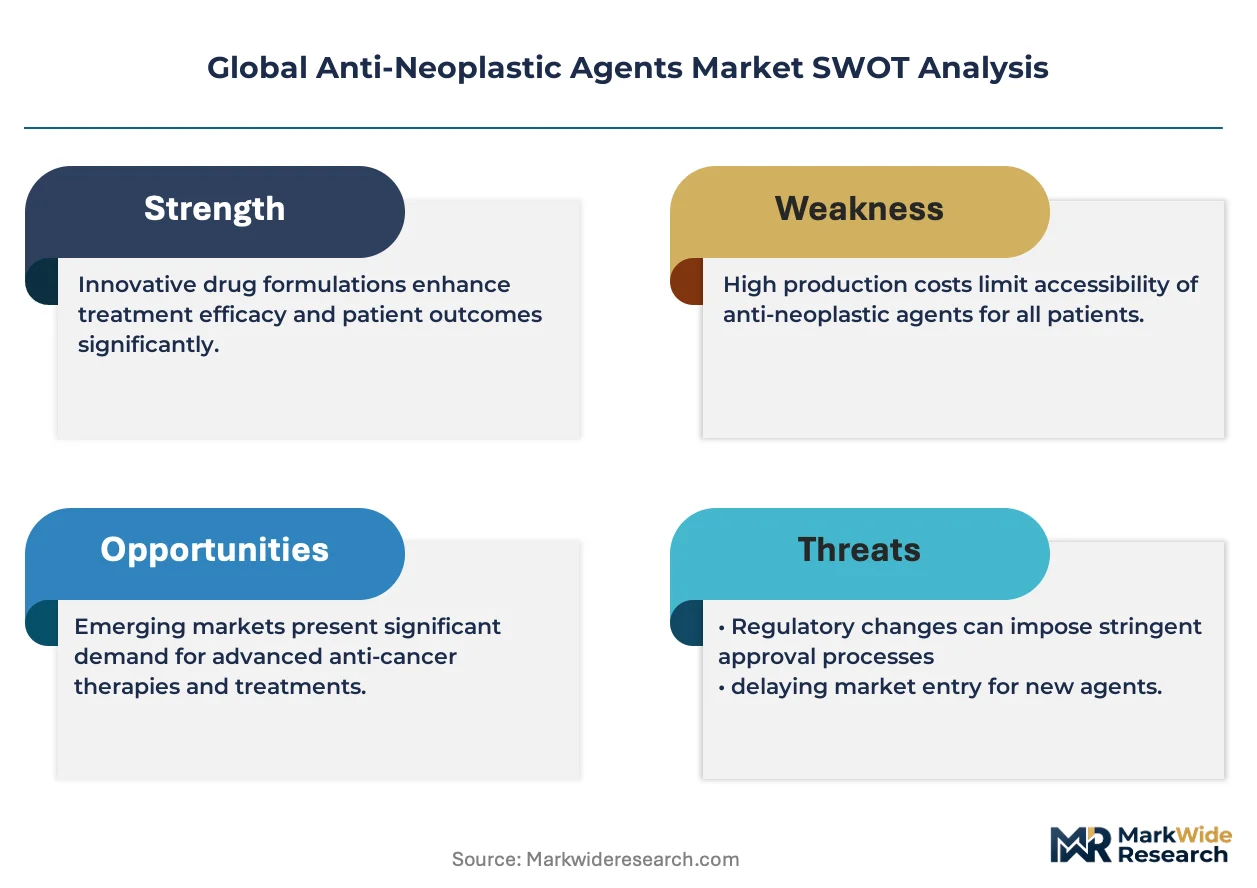
FDA breakthrough therapy designation and EMA priority medicines scheme are compressing development timelines for anti-neoplastic agents while simultaneously elevating evidence requirements, forcing manufacturers to accelerate clinical data generation without compromising safety protocols.
Growth Catalysts
- Accelerated approval pathways:FDA breakthrough therapy designation and EMA priority medicines scheme compress development timelines while maintaining rigorous efficacy standards for novel oncology therapeutics.
- Precision medicine infrastructure:United States, China, and Germany are expanding genomic sequencing capabilities and biomarker-driven patient stratification protocols across tertiary hospital networks.
- CAR-T manufacturing scale:Automated cell processing platforms and closed-system bioreactors are reducing per-dose production costs for autologous immunotherapy products.
Market Restraints
- Plasmid DNA supply concentration:Contract manufacturing organizations in North America and Europe control critical raw material inputs for viral vector production, creating single-source vulnerabilities.
- Narrow therapeutic indices:Cytotoxic alkylating agents require intensive therapeutic drug monitoring and specialized pharmacy infrastructure, limiting administration to certified oncology centers.
- Reimbursement compression:Medicare and commercial payors in the United States are implementing indication-specific value frameworks that restrict coverage for off-label uses of high-cost targeted therapies.
Strategic Opportunities
- Biosimilar substitution mandates:India's CDSCO biosimilar guidelines and European reference pricing systems are creating procurement advantages for domestically manufactured monoclonal antibody alternatives.
- Radioligand therapy expansion:Lutetium-177 based theranostics are penetrating metastatic castration-resistant prostate cancer and neuroendocrine tumor indications previously served by chemotherapy alone.
- Outpatient infusion networks:Community oncology clinics in Germany and community health centers in China are building capacity for biologic administration outside tertiary hospital settings.
Industry Challenges
- Cell therapy logistics complexity:Cryogenic cold chain requirements for CAR-T products demand specialized courier networks and vein-to-vein tracking systems that exceed conventional pharmaceutical distribution capabilities.
- Companion diagnostic co-development:Synchronized FDA approval of PD-L1 expression assays and checkpoint inhibitors requires parallel clinical validation timelines that extend regulatory submission preparation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anti-Neoplastic Agents Market |
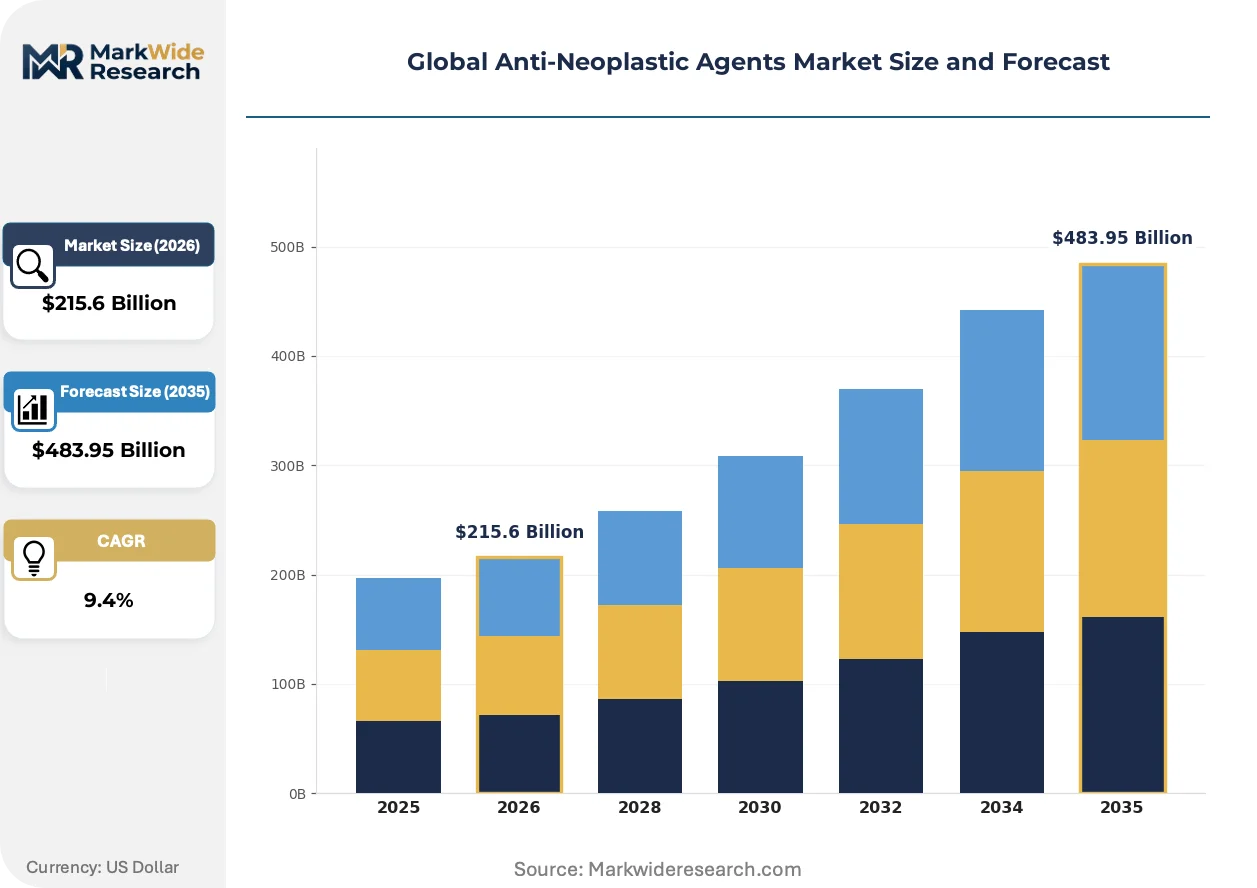
| Market Size in 2026 | $215.6 Billion |
| Market Size in 2035 | $483.95 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkylating Agents, Antimetabolites, Hormonal Therapy, Targeted Therapy, Immunotherapy, Biologic Response Modifiers Therapy Area: Breast Cancer, Lung Cancer, Colorectal Cancer, Leukemia, Lymphoma, Melanoma End User: Hospitals, Specialty Clinics, Cancer Research Institutes, Ambulatory Surgical Centers, Diagnostic Laboratories Delivery Mode: Intravenous, Oral, Topical, Subcutaneous, Intramuscular |
| Companies Covered | Bayer AG, Bristol-Myers Squibb Company, Pfizer Inc., Takeda Pharmaceutical Company Limited, AstraZeneca PLC, F. Hoffmann-La Roche Ltd., Novartis AG, Teva Pharmaceutical Industries Ltd., Merck & Co. Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anti-Neoplastic Agents Market Shifts & Advancements
Biologic manufacturing platforms and regulatory science advances are converging to transform how anti-neoplastic agents reach patients, with automation and real-world evidence frameworks displacing legacy development paradigms.
Antibody-drug conjugate technology is unifying cytotoxic potency with tumor-specific targeting through cleavable linker chemistry and payload optimization. Oncology departments in tertiary hospitals are adopting ADC protocols for HER2-low breast cancer and urothelial carcinoma indications previously managed with conventional chemotherapy. This unifying architecture is compressing the historical separation between targeted therapy and cytotoxic treatment categories, enabling single-agent efficacy in heterogeneous tumor populations.
EU Green Deal pharmaceutical sustainability requirements are mandating carbon footprint disclosure and waste reduction targets across European hospital procurement networks. Manufacturers must now document environmental impact across active pharmaceutical ingredient synthesis, packaging, and reverse logistics. German hospital networks and French public health institutions are prioritizing suppliers with validated lifecycle assessments for monoclonal antibody products.
Buyers are consolidating purchasing decisions through integrated delivery networks and group purchasing organizations that negotiate indication-based contracts rather than per-unit pricing. United States oncology practices affiliated with hospital systems are ceding formulary control to centralized pharmacy committees that evaluate total cost of care across lines of therapy. This concentration is visible most acutely in Medicare Advantage populations where risk-bearing entities directly manage oncology drug spend.
Global Anti-Neoplastic Agents Market Segmentation
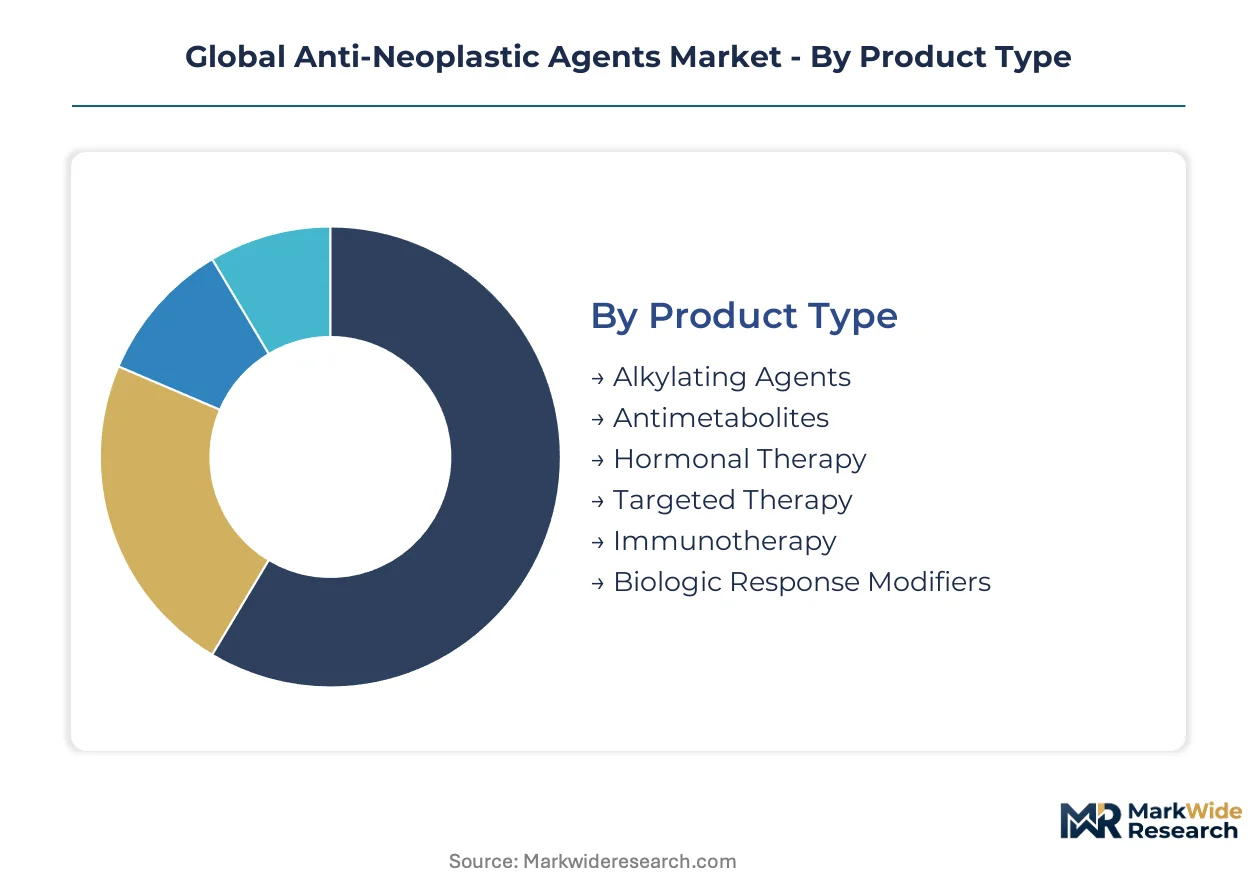
Anti-neoplastic agents exhibit pronounced heterogeneity across therapeutic modalities, cancer indications, and care settings. Segmentation reveals how reimbursement frameworks, manufacturing complexity, and clinical evidence requirements differentially shape commercial viability across product categories.
Product Type:
Buyer differentiation hinges on whether procurement committees prioritize mature generic availability or premium-priced biologic innovation.
- Targeted Therapy:Kinase inhibitors and monoclonal antibodies engineered against tumor-specific molecular markers. United States oncology practices affiliated with hospital systems are consolidating formulary decisions around these agents as Medicare Advantage risk-bearing entities manage total cost of care across lines of therapy.
- Immunotherapy:Checkpoint inhibitors modulating PD-1/PD-L1 pathways to restore anti-tumor immune responses. China's tertiary hospital networks are expanding genomic sequencing infrastructure to identify patients eligible for front-line pembrolizumab and nivolumab protocols.
- Alkylating Agents:DNA-crosslinking cytotoxics with established efficacy in combination regimens.
- Antimetabolites:Folate and pyrimidine pathway antagonists disrupting nucleic acid synthesis.
- Hormonal Therapy:Androgen and estrogen receptor modulators for prostate and breast malignancies.
- Biologic Response Modifiers:Cytokine and growth factor therapies augmenting host immune surveillance.
Alkylating agents lead volumes today; immunotherapy is gaining share fastest.
Therapy Area:
Clinical trial success rates and addressable patient populations determine where pharmaceutical R&D investment concentrates.
- Lung Cancer:Non-small cell and small cell carcinomas representing the leading cause of cancer mortality worldwide. German hospital networks are prioritizing PD-L1 expression testing infrastructure to stratify patients for immunotherapy versus chemotherapy-first protocols.
- Breast Cancer:Hormone receptor-positive, HER2-positive, and triple-negative subtypes with divergent treatment algorithms. Antibody-drug conjugates targeting HER2-low expression are displacing conventional chemotherapy in United States community oncology practices.
- Colorectal Cancer:Microsatellite instability-high subsets driving immunotherapy penetration.
- Leukemia:Hematologic malignancies where CAR-T cell therapies are transforming relapsed/refractory treatment paradigms.
- Lymphoma:Hodgkin and non-Hodgkin subtypes with established CD20-directed monoclonal antibody protocols.
- Melanoma:BRAF-mutant and checkpoint inhibitor-responsive disease with durable survival improvements.
Lung cancer commands the largest absolute spend; breast cancer demonstrates the steepest expansion trajectory from ADC adoption.
End User:
Administrative complexity and reimbursement mechanics fragment purchasing authority across institutional settings.
- Hospitals:Tertiary academic medical centers with integrated pharmacy committees managing oncology formularies. China's GB standards for biologic manufacturing are elevating quality benchmarks for monoclonal antibody procurement across provincial hospital networks.
- Specialty Clinics:Community-based oncology practices with direct physician influence over treatment selection. United States independent practices are ceding autonomy to hospital system-affiliated centralized pharmacy committees.
- Cancer Research Institutes:Early-phase clinical trial sites with investigator-initiated protocol flexibility.
- Ambulatory Surgical Centers:Limited oncology service scope concentrated in diagnostic and minor procedures.
- Diagnostic Laboratories:Companion diagnostic providers enabling biomarker-driven patient stratification.
Hospitals retain dominant purchasing volume; specialty clinics are consolidating fastest through acquisition by health systems.
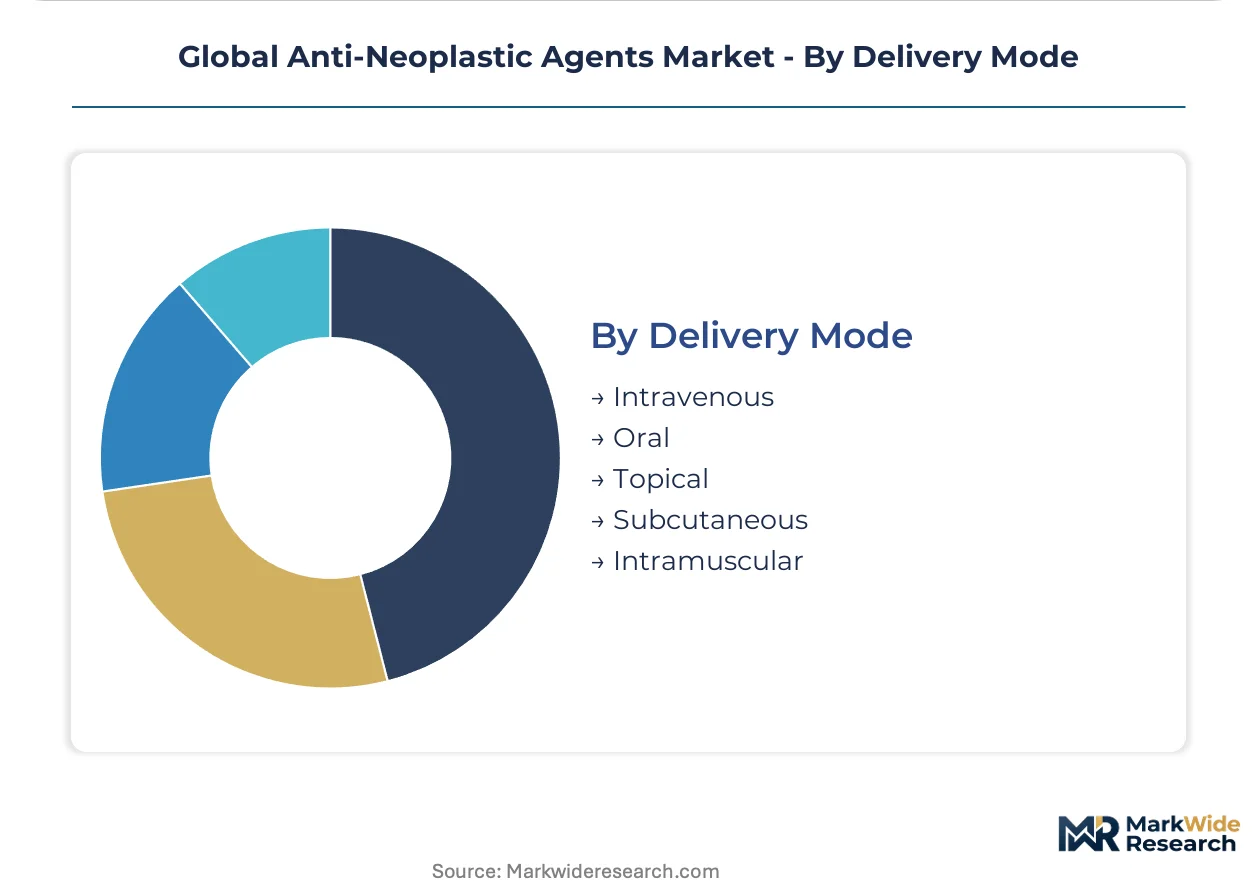
Delivery Mode:
Route of administration determines cold chain requirements, pharmacy infrastructure investment, and patient convenience trade-offs.
- Intravenous:Infusion-based delivery of cytotoxics and biologics requiring certified oncology pharmacy infrastructure. Germany's community oncology clinics are building capacity for biologic administration outside tertiary hospital settings.
- Oral:Small molecule kinase inhibitors enabling outpatient self-administration with therapeutic drug monitoring. India's CDSCO biosimilar guidelines are creating procurement advantages for domestically manufactured oral oncology alternatives.
- Subcutaneous:Monoclonal antibody formulations reducing infusion center burden.
- Topical:Limited application to superficial skin malignancies and palliative lesions.
- Intramuscular:Hormonal depot formulations for prostate and breast cancer maintenance therapy.
Intravenous dominates current administration volumes; oral formulations are climbing the fastest as fixed-dose combinations simplify regimens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modern oncology therapeutics trace their industrial origins to German chemical synthesis laboratories and Swiss pharmaceutical research institutes that pioneered alkylating agents and hormonal therapies during the mid-twentieth century. These foundational discoveries established the regulatory and manufacturing frameworks that now govern precision medicine deployment across major hospital networks.
United States
FDA breakthrough therapy designation compresses development timelines for novel checkpoint inhibitors while Medicare Advantage risk-bearing entities consolidate oncology drug procurement through centralized pharmacy committees. The National Cancer Institute's Cancer Centers Program funds genomic sequencing infrastructure across tertiary academic medical centers. Boston's Longwood Medical Area and Houston's Texas Medical Center anchor CAR-T cell therapy manufacturing and early-phase clinical trial operations.
China
NMPA conditional approval pathways accelerate market access for domestically manufactured monoclonal antibodies as provincial hospital networks expand biologic response modifier protocols. GB standards for biologic manufacturing elevate quality benchmarks for monoclonal antibody procurement across tertiary oncology departments. Shanghai's Zhangjiang Hi-Tech Park and Beijing's Zhongguancun Life Science Park concentrate cell therapy research facilities and automated manufacturing platforms.
Germany
EMA priority medicines scheme elevates evidence requirements for anti-neoplastic agents while EU Green Deal pharmaceutical sustainability mandates reshape hospital procurement criteria toward carbon footprint disclosure. Germany's reference pricing systems for biosimilars create procurement advantages for domestically manufactured monoclonal antibody alternatives. Munich's biotechnology cluster and Heidelberg's university hospital network lead radioligand therapy expansion for metastatic prostate cancer indications.
India
CDSCO biosimilar guidelines establish quality benchmarks for domestically manufactured oral oncology alternatives as contract manufacturing organizations scale production of active pharmaceutical ingredients. India's PLI scheme for pharmaceuticals incentivizes local production of critical raw material inputs for viral vector manufacturing. Hyderabad's Genome Valley and Ahmedabad's pharmaceutical manufacturing corridor concentrate biologic production capacity and export-oriented formulation facilities.
Japan
PMDA's sakigake designation system accelerates regulatory review for innovative oncology therapeutics while METI's healthcare industry strategy promotes precision medicine infrastructure development. Japan's national health insurance system maintains indication-specific reimbursement frameworks that restrict coverage for off-label uses of high-cost targeted therapies. Tokyo's Koto Ward biocluster and Osaka's pharmaceutical research corridor anchor antibody-drug conjugate development and companion diagnostic co-validation programs.
Global Anti-Neoplastic Agents Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the anti-neoplastic agents landscape, with integrated pharmaceutical conglomerates maintaining captive biologic manufacturing capacity while specialized biotechnology firms rely on contract manufacturing organizations for viral vector and cell therapy production. The market structure concentrates around three strategic archetypes: diversified conglomerates with in-house monoclonal antibody platforms, cell therapy specialists with automated manufacturing systems, and generic manufacturers scaling biosimilar substitution. Competitive dynamics center on backward integration into plasmid DNA supply and strategic partnerships for companion diagnostic co-development.
Within the diversified conglomerate tier, F. Hoffmann-La Roche Ltd., Novartis AG, and Bristol-Myers Squibb Company exemplify contrasting strategic positions. The Basel-based Roche anchors its market presence through captive monoclonal antibody production infrastructure. Novartis AG occupies a position emphasizing cell therapy manufacturing scale across Swiss and United States facilities. Bristol-Myers Squibb Company represents the checkpoint inhibitor commercialization archetype with established protocols across major oncology indications.
| Leading Market Players |
|---|
| Bayer AG |
| Bristol-Myers Squibb Company |
| Pfizer Inc. |
| Takeda Pharmaceutical Company Limited |
| AstraZeneca PLC |
| F. Hoffmann-La Roche Ltd. |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd. |
| Merck & Co. Inc. |
| Others |
Supply & Pricing Matrix
Bioprocess engineering talent concentration in Switzerland and Massachusetts creates labor-cost differentials that widen pricing spreads between premium monoclonal antibody products and economy-tier biosimilars. CDSCO guidelines in India and EMA reference pricing in Europe compress margins for manufacturers lacking captive production infrastructure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the anti-neoplastic agents landscape. Price differentiation hinges on FDA breakthrough therapy designation status and manufacturing origin—Swiss and US-sourced biologics command substantial premiums over Indian and Chinese biosimilars. Cost compression in the economy tier intensifies because CDSCO biosimilar guidelines in India accelerate domestic substitution. Hospital procurement committees exhibit highest price sensitivity for alkylating agents and antimetabolites, while oncology practices affiliated with health systems show lowest sensitivity for CAR-T cell therapies where clinical outcomes dominate purchasing decisions.
Supply Chain Analysis
Reverse logistics for temperature-sensitive biologics—including cryogenic returns of expired CAR-T products and monoclonal antibody vials—demands specialized cold-chain couriers exceeding conventional pharmaceutical distribution capabilities. Manufacturing concentrates in Switzerland, the United States, and India for monoclonal antibodies, with China expanding bioreactor capacity for biosimilar production. Plasmid DNA supply draws from contract manufacturing organizations in North America and Europe, creating single-source vulnerabilities for viral vector production. Tariff exposure on Chinese-sourced active pharmaceutical ingredients threatens cost structures for oral kinase inhibitors. Distribution runs through hospital system-affiliated specialty distributors and group purchasing organizations consolidating oncology drug procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anti-neoplastic agents market functions as a regulatory compounder where FDA breakthrough therapy designation and EMA priority medicines scheme accelerate demand for novel immunotherapies. These accelerated approval pathways compress development timelines while elevating evidence standards, rewarding manufacturers with robust clinical data generation capabilities.
For Market Incumbents: Hedge against biosimilar substitution by securing backward integration into plasmid DNA supply and expanding automated cell processing platforms for CAR-T manufacturing. F. Hoffmann-La Roche Ltd. and Novartis AG demonstrate defensive positioning through captive monoclonal antibody production infrastructure and Swiss-US cell therapy manufacturing scale. Invest in companion diagnostic co-development capabilities to synchronize FDA approvals and extend formulary protection. For New Entrants and Emerging Players: NMPA conditional approval pathways in China open a window for domestically manufactured checkpoint inhibitors targeting provincial hospital networks expanding genomic sequencing infrastructure. White-space targets include radioligand therapy expansion for metastatic prostate cancer and community oncology clinic capacity for biologic administration outside tertiary settings. Pursue licensing agreements with established contract manufacturing organizations to bypass capital-intensive bioreactor construction. For Investors and Strategic Acquirers: Diversified pharmaceutical conglomerates are the most active acquirers in this space, seeking cell therapy specialists with automated manufacturing systems and companion diagnostic platforms. Long-term viability centers on backward integration into critical raw materials and outcome-based contracting capabilities for payor negotiations. Acquisition target archetypes include biosimilar manufacturers with validated GB standards compliance and radioligand therapy developers with Lutetium-177 supply agreements. Monitor EMA priority medicines scheme designations and NMPA conditional approvals as inflection indicators for portfolio repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses development timelines for novel checkpoint inhibitors. |
| Manufacturing Scale-Up | Automated cell processing platforms reduce per-dose production costs for autologous CAR-T products. |
| Backward Integration | Captive plasmid DNA production insulates against single-source vulnerabilities in viral vector supply. |
| Companion Diagnostic Co-Development | Synchronized FDA approval of PD-L1 assays and checkpoint inhibitors extends formulary protection. |
| Licensing Agreement | Technology transfers enable rapid entry into NMPA conditional approval pathways for Chinese hospital networks. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down pharmaceutical expenditure analysis were triangulated to anchor market size estimates.
Historical reference periods spanning pre-pandemic baseline through recent regulatory milestone years anchored the forecast window across the projection horizon. The analytical framework modeled segmentation dimensions including therapeutic modality, cancer indication, administration route, treatment line, and regional regulatory cluster. CAGRs were derived from patent expiration timelines, biosimilar entry curves, and clinical trial success rate differentials by tumor type. Forecast inputs incorporated plasmid DNA supply constraints and EU Green Deal sustainability mandates reshaping procurement criteria.
Revisions become necessary when accelerated approval withdrawals, manufacturing quality enforcement actions, or payor coverage restrictions materialize. Forecasts reflect documented assumptions regarding clinical trial readout timing and regulatory review duration. Practitioners should monitor FDA advisory committee outcomes, EMA CHMP opinions, and CMS national coverage determinations for early signals of forecast deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Exocrine Pancreatic Insufficiency Therapeutics Market
Pharmaceuticals
Antiepilepsy Drugs Market
Pharmaceuticals
Xerostomia Therapeutics Market
Pharmaceuticals
Nuclear Medicines Radioisotopes Market
Pharmaceuticals
Critical Care Drugs Market
Pharmaceuticals
Cortisone Market
Pharmaceuticals
Japan Diabetes Drugs Market
Pharmaceuticals
Dopamine and Norepinephrine Reuptake Inhibitor Market
Pharmaceuticals
Italy Opioids Market
Pharmaceuticals
Antispasmodics Drugs Market
Pharmaceuticals
Asia-Pacific Gastrointestinal Drugs Market
Pharmaceuticals
Global Loperamide Hcl Market
Pharmaceuticals
Second Generation Cephalosporins Market
Pharmaceuticals
Sinus Therapeutic Drugs Market
Pharmaceuticals
Europe Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Global Lipid Disorder Treatment Market