
 Rupatadine Fumarate API Market | 2026-2036
Rupatadine Fumarate API Market Size, Share, and Industry Trends Forecast 2026-2036
Rupatadine Fumarate API Market Insights
Buyer concentration among pharmaceutical manufacturers is rebalancing as large Indian and Chinese formulators absorb volume previously fragmented across mid-tier buyers. Biophore India Pharmaceuticals leverages backward integration into API synthesis to secure margin control. Tagoor Laboratories anchors its position through dedicated manufacturing blocks for antihistamine chemistry. LGM Pharma sustains North American supply relationships through dedicated regulatory dossier support.
Rupatadine fumarate is a second-generation histamine H1-receptor antagonist with platelet-activating factor inhibitory properties, synthesized through multi-step organic chemistry involving condensation and salt formation to achieve fumarate salt purity above 99.5 percent for pharmaceutical use. Bulk API commands the dominant volume position due to in-house formulation capabilities at major buyers, while oral delivery mode leads value generation because tablet and capsule formulations represent the primary commercial dosage forms for allergic rhinitis and chronic urticaria indications. The intermediate segment competes on specialized contract synthesis for innovators seeking to outsource early-stage manufacturing steps.
CDSCO in India enforces Schedule M compliance for domestic API facilities, while FDA inspections of overseas manufacturers determine market access for exports to the United States. ICH Q7 guidelines establish the universal quality benchmark that shapes batch release protocols and supplier audit frequencies across all major sourcing geographies. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and IP standards to anticipate specification drift that could disqualify existing inventory or trigger reformulation costs.
Market Dynamics
FDA inspection intensity at overseas API facilities is compressing supplier qualification timelines and forcing pharmaceutical manufacturers to consolidate purchase orders among pre-qualified vendors with established regulatory dossiers.
Growth Catalysts
- Allergic rhinitis prevalence:Rising diagnosis rates across South Asian populations are expanding prescription volumes for second-generation antihistamine formulations.
- ICH Q7 harmonization:Universal adoption of good manufacturing practice guidelines is streamlining cross-border batch release protocols for contract manufacturers.
- Chronic urticaria protocols:Updated treatment guidelines in dermatology practices are extending duration of therapy and API consumption per patient.
Market Restraints
- KSM supply concentration:Critical starting materials for rupatadine synthesis originate from a narrow base of Chinese chemical intermediates suppliers.
- FDA inspection backlog:Delayed facility approvals at Indian API manufacturers are freezing export capacity expansion timelines.
- Generics substitution:Patent-expired loratadine and cetirizine formulations compete on price in reimbursement-sensitive markets.
Strategic Opportunities
- Pediatric formulation development:Orally disintegrating tablet formats for rupatadine remain underdeveloped relative to adult dosage strengths.
- CDSCO export incentives:Indian PLI scheme allocations for API manufacturing are reducing capital cost barriers for domestic capacity expansion.
- Continuous flow chemistry:Adoption of microreactor technology is enabling process intensification and yield improvements at synthesis stage.
Industry Challenges
- Analytical method transfer:Validation of impurity profiling methods between sponsor and contract laboratories extends timeline to commercial supply.
- Multipurpose equipment scheduling:Antihistamine API campaigns compete for reactor time against high-margin oncology intermediates at CDMO facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rupatadine Fumarate API Market |
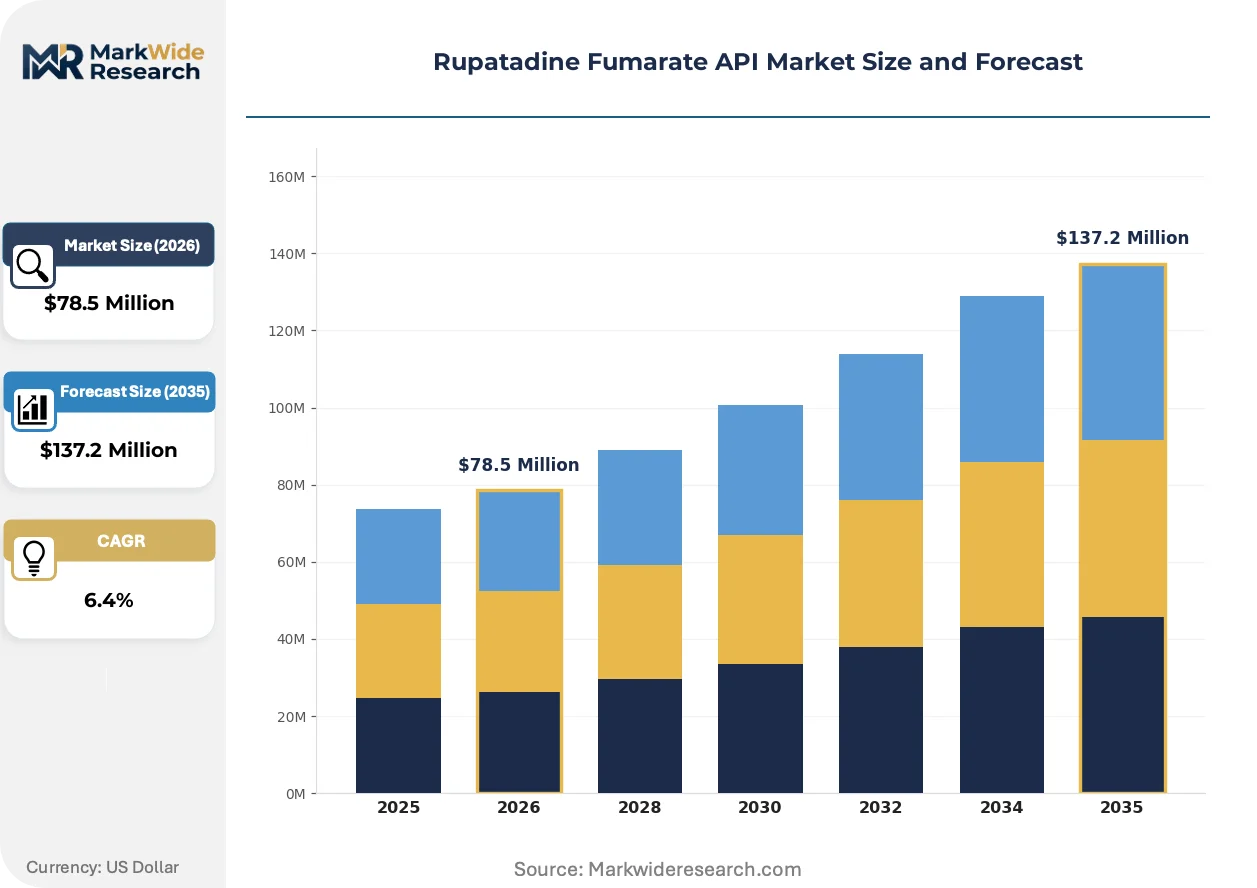
| Market Size in 2026 | $78.5 Million |
| Market Size in 2035 | $137.2 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulk API, Formulated Product, Intermediate, Excipients End User: Pharmaceutical Manufacturers, Contract Manufacturers, Research Institutions, Specialty Clinics Delivery Mode: Injectable, Oral, Topical, Inhalation Indication: Allergic Rhinitis, Chronic Urticaria, Asthma, Others |
| Companies Covered | Biophore India Pharmaceuticals Pvt Ltd, Tagoor Laboratories, Inabata France S.A.S, LGM Pharma, Hunan Huateng Pharmaceutical, Yangtze River Pharmaceutical Group, Cadila Pharmaceuticals, Hetero Drugs, Tyche Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rupatadine Fumarate API Market Trends and Innovations
Process analytical technology is penetrating rupatadine synthesis operations, enabling real-time release testing that reduces quarantine inventory and accelerates batch disposition for oral tablet manufacturers.
Continuous manufacturing equipment is absorbing quality control functions previously performed offline. Mid-scale Indian API producers are retrofitting existing batch plants with in-line PAT sensors for fumarate salt crystallization monitoring. This convergence is compressing the specification-setting window between synthesis and final API release.
REACH authorization requirements for residual solvent classification are forcing reformulation of purification protocols across European supply chains. Manufacturers serving EMA-regulated markets are substituting dichloromethane recovery systems with ethyl acetate alternatives. The transition is absorbing capital allocation that might otherwise expand nameplate capacity.
Long-term offtake agreements are displacing spot market purchasing among North American generic pharmaceutical companies. Buyers with internal formulation capabilities are contracting directly with Indian API facilities for multi-year supply commitments. This pattern is most visible among mid-tier formulators seeking regulatory dossier continuity for chronic urticaria indications.
Rupatadine Fumarate API Market Segmentation
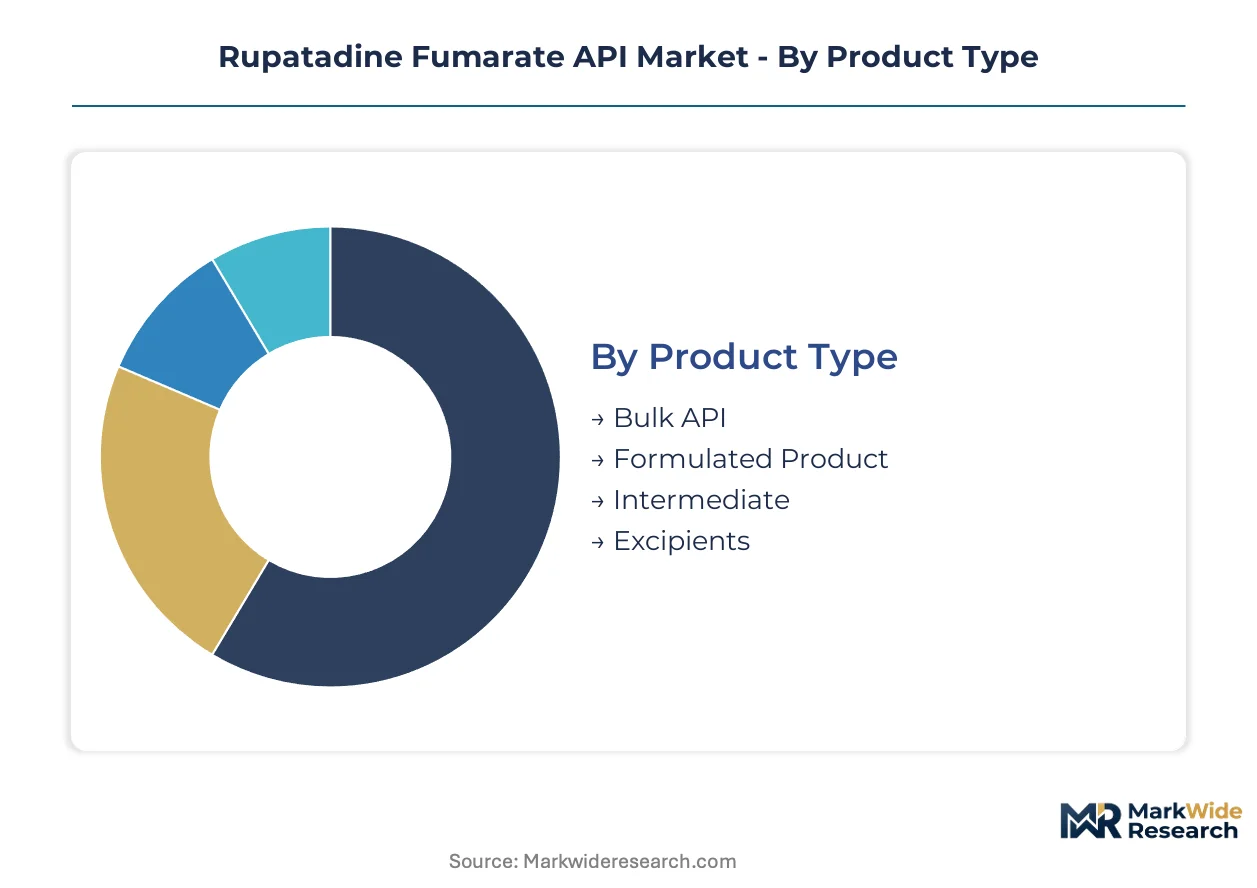
Segmentation in rupatadine fumarate API markets reveals how supply chain configuration shapes procurement patterns across pharmaceutical value chains. Each dimension exposes distinct concentration dynamics that determine vendor selection criteria and margin distribution.
Product Type:
Supply concentration among Indian and Chinese manufacturers favors bulk material procurement over finished formulations for buyers with in-house tableting capabilities.
- Bulk API:Crystalline fumarate salt meeting USP/EP/IP pharmacopeial standards commands dominant procurement volumes. Major Indian formulators at Hyderabad and Ahmedabad clusters source directly for captive tablet production, compressing intermediate trading margins.
- Intermediate:Advanced synthetic intermediates for late-stage rupatadine coupling reactions attract specialized contract demand. European innovators outsource these steps to Indian CDMOs seeking to avoid capital-intensive hydrogenation infrastructure.
- Formulated Product:Ready-to-fill granules and pre-compression blends serve smaller pharmaceutical manufacturers lacking formulation expertise. CDSCO registration requirements limit supplier pools for domestic Indian buyers.
- Excipients:Co-processed diluents and disintegrants optimized for rupatadine's hygroscopic profile complete delivery system specifications. Mannitol and croscarmellose sodium blends from Roquette and DFE Pharma dominate supplier nominations.
Today's leader: Bulk API. Tomorrow's challenger: Intermediate contract synthesis for innovator pipelines.
End User:
Procurement scale separates large-volume pharmaceutical manufacturers from fragmented research and clinical buyers with divergent specification tolerances.
- Pharmaceutical Manufacturers:Integrated formulators with dedicated antihistamine production lines drive annual offtake commitments. Dr. Reddy's and Cipla negotiate multi-year supply agreements with API houses for loratadine-adjacent portfolio continuity.
- Contract Manufacturers:CDMOs serving North American generic sponsors require pre-qualified supplier dossiers for ANDA submissions. LGM Pharma and Patheon facilities source through audited Indian API channels with established FDA inspection histories.
- Research Institutions:Gram-scale purchases for pharmacokinetic studies and formulation development command premium pricing. Academic buyers tolerate broader specification ranges than commercial manufacturers.
- Specialty Clinics:Compounding pharmacies in dermatology and allergy practices procure micro-batches for personalized chronic urticaria protocols. USP 795 and 797 compliance requirements constrain vendor selection.
Volume concentrates with pharmaceutical manufacturers. Margin capture shifts toward contract manufacturers with regulatory dossier capabilities.
Delivery Mode:
Patient compliance requirements and manufacturing infrastructure investments determine route selection across allergic rhinitis and chronic urticaria indications.
- Oral:Immediate-release and modified-release tablets dominate commercial volumes. Film-coated formulations from Aurobindo and Zydus Cadila anchor prescription volumes across South Asian and North American markets.
- Injectable:Hospital-administered presentations for acute allergic emergencies occupy niche positioning. Sterile manufacturing requirements and pyrogen testing protocols limit supplier participation.
- Topical:Transdermal gel formulations for localized urticaria remain developmental. Permeation enhancement challenges constrain bioequivalence achievement versus oral references.
- Inhalation:Dry powder and metered-dose presentations for allergic rhinitis nasal delivery attract formulation R&D investment. Particle engineering requirements for regional lung deposition extend development timelines.
Oral delivery sustains volume leadership. Inhalation presentations claim the steepest expansion trajectory among emerging formats.
Indication:
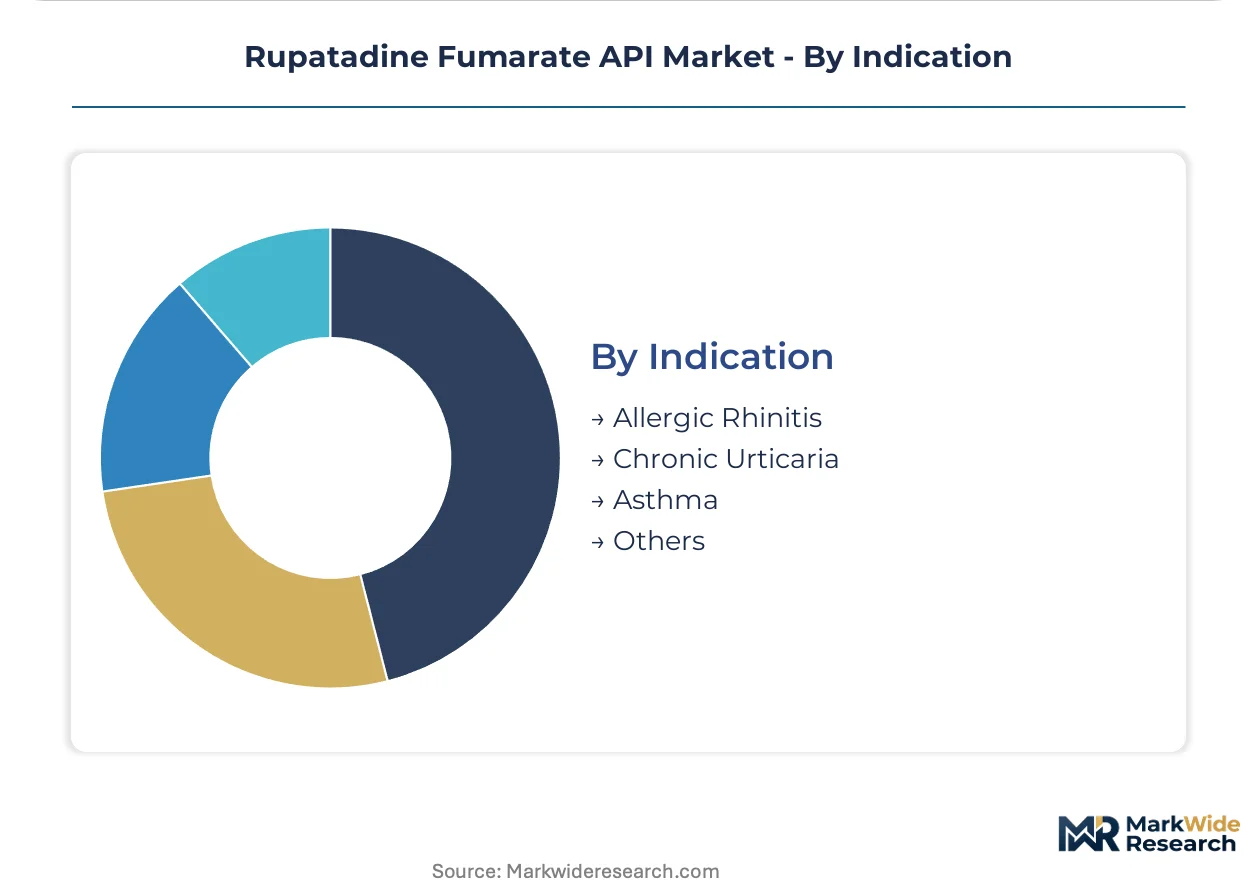
Treatment guideline updates and diagnosis rate variations across geographies reshape demand composition for rupatadine prescribing.
- Allergic Rhinitis:Seasonal and perennial presentations drive baseline prescription volumes. Indian pulmonologists and ENT specialists favor second-generation antihistamines over first-generation alternatives for sedation avoidance.
- Chronic Urticaria:Refractory cases requiring extended therapy duration expand per-patient API consumption. Updated EAACI/GA2LEN guidelines position rupatadine as second-line after H1-antihistamine dose escalation failures.
- Asthma:Adjunctive antihistamine therapy for allergic asthma phenotypes occupies exploratory positioning. Clinical trial enrollment for this indication determines future label expansion potential.
- Others:Off-label applications in atopic dermatitis and mast cell disorders generate sporadic demand. Case report accumulation supports investigator-initiated studies without formal indication expansion.
Allergic rhinitis anchors current volumes. Chronic urticaria protocols are gaining share fastest through extended duration prescribing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India and China dominate rupatadine fumarate API manufacturing capacity, yet the United States and Germany anchor formulation demand through distinct regulatory pathways and patient access models.
United States
FDA inspections of overseas API facilities determine import eligibility for generic tablet manufacturers serving allergic rhinitis patients. The agency's data integrity enforcement at Indian and Chinese sites compresses supplier qualification timelines. North American formulators in New Jersey and North Carolina clusters increasingly contract directly with pre-qualified API houses for multi-year supply security.
India
CDSCO enforces Schedule M compliance for domestic API production while the PLI scheme reduces capital barriers for capacity expansion. Hyderabad and Ahmedabad pharmaceutical clusters concentrate backward-integrated manufacturers with captive rupatadine synthesis capabilities. FDA inspection backlogs at Visakhapatnam and Baddi facilities occasionally freeze export capacity timelines.
China
NMPA oversight of chemical intermediate production shapes starting material availability for downstream API synthesis. Yangtze River Delta chemical parks host hydrogenation and salt formation infrastructure supporting fumarate purity specifications. REACH authorization pressures are forcing solvent recovery system upgrades at European-facing export facilities.
Germany
EMA pharmacopeial harmonization requirements between USP, EP and IP standards influence specification-setting for imported APIs. Frankfurt and Ludwigshafen chemical trading hubs intermediate between Asian manufacturers and European formulators. BfArM guidance on chronic urticaria treatment protocols extends per-patient API consumption through second-line positioning.
Japan
PMDA GMP inspections of overseas API suppliers determine market access for domestic generic entrants. Osaka and Tokyo formulation clusters source rupatadine through audited Indian channels with established MFDS-equivalent quality systems. An aging patient population expands prescription volumes for sedating-antihistamine-free allergic rhinitis therapies.
Rupatadine Fumarate API Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across rupatadine fumarate API supply tiers. Market structure tilts toward consolidation as FDA inspection intensity forces pharmaceutical manufacturers to narrow vendor pools to pre-qualified suppliers with established regulatory dossiers. Three archetypes dominate: backward-integrated Indian formulators with captive API production, dedicated antihistamine chemistry specialists operating contract manufacturing blocks, and North American distributors sustaining relationships through regulatory documentation support. Capacity expansion and long-term offtake agreements represent the dominant competitive moves as spot market purchasing declines.
Within the Indian manufacturing tier, Biophore India Pharmaceuticals and Tagoor Laboratories exemplify distinct strategic positioning approaches. LGM Pharma occupies a position bridging North American formulation demand with Asian supply capacity. These three entities represent the spectrum from integrated production to regulatory-focused distribution, with each archetype capturing margin through different value chain control points.
| Leading Market Players |
|---|
| Biophore India Pharmaceuticals Pvt Ltd |
| Tagoor Laboratories |
| Inabata France S.A.S |
| LGM Pharma |
| Hunan Huateng Pharmaceutical |
| Yangtze River Pharmaceutical Group |
| Cadila Pharmaceuticals |
| Hetero Drugs |
| Tyche Industries Ltd |
| Others |
Pricing and Supply Chain Analysis
Starting material costs for 3-(4-piperidinyl)-1H-benzimidazol-2-one derivatives flow through Yangtze River Delta chemical intermediates suppliers into Indian API manufacturers, stratifying across premium fumarate salt grades for FDA-inspected facilities versus standard IP-grade material for domestic Indian formulators.
Pricing Analysis
Capacity additions in Gujarat and Telangana are reshaping price floors for standard-grade rupatadine fumarate as backward-integrated formulators absorb captive volumes. Three-tier pricing structure across premium, standard, and economy levels separates FDA-inspected USP-grade material from CDSCO-registered IP-grade and unregistered technical-grade supplies. Cost compression in the economy tier is intensifying because Chinese KSM suppliers are consolidating hydrogenation capacity. Contract manufacturers serving North American ANDA sponsors exhibit lowest price sensitivity, while domestic Indian formulators without export ambitions drive hardest bargain negotiations.
Supply Chain Analysis
Chemical engineering talent availability in Hyderabad and Ahmedabad pharmaceutical clusters anchors fumarate salt formation capacity expansion. Supply concentrates in India and China, with starting material dependencies on piperidine derivatives, benzimidazolone cores, and maleic acid for salt conversion. Single-source vulnerability runs through hydrogenation catalyst suppliers in the Yangtze River Delta. Distribution runs through audited API houses with established regulatory dossiers rather than spot-market traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rupatadine fumarate API market functions as a geographic-arbitrage play where CDSCO's PLI scheme subsidies in India offset FDA inspection compliance costs that Chinese competitors face for US market access.
For Market Incumbents: Cement dossier continuity through multi-year offtake agreements with North American generic sponsors before FDA inspection backlogs at Visakhapatnam facilities clear. Deepen backward integration into piperidine starting material synthesis to offset KSM supply concentration risk from Yangtze River Delta suppliers. Prioritize continuous flow chemistry retrofit investments at Hyderabad manufacturing blocks to defend yield advantages against emerging microreactor specialists. For New Entrants and Emerging Players: The price-point gap between premium FDA-inspected grades and domestic Indian IP-grade material creates entry space for mid-tier API houses with partial regulatory qualification. Target pediatric formulation development for orally disintegrating tablets as the most penetrable white-space segment. Pursue CDSCO export incentive qualification under PLI scheme allocations to compress capital barriers for initial capacity installation. For Investors and Strategic Acquirers: Consolidation pressure builds where FDA inspection histories determine supplier qualification timelines and pharmaceutical manufacturers narrow vendor pools. Focus acquisition screening on Indian API facilities with established ANDA submission support capabilities and clean FDA inspection records. Watch for inflection when chronic urticaria treatment guideline updates in European markets extend per-patient API consumption through second-line positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Chemistry Adoption | Microreactor technology at Indian API houses compresses fumarate salt crystallization cycles and raises yield above batch benchmarks. |
| Backward Integration into KSM Synthesis | Captive piperidine derivative production insulates margin from Yangtze River Delta intermediate supplier consolidation. |
| Regulatory Dossier Expansion | EMA and PMDA filing investments open formulation supply relationships beyond FDA-dependent North American sponsors. |
| Pediatric Formulation Development | Orally disintegrating tablet formats address compliance gaps in allergy therapy for children under twelve. |
| Long-term Supply Agreement Structuring | Multi-year offtake commitments with CDMOs secure volume visibility against spot market purchasing decline. |
Research Methodology
Bottom-up pharmaceutical manufacturer procurement modeling reconciled against top-down API production capacity tracking forms the analytical core of this study. Primary interviews with regulatory affairs directors at Indian API houses, formulation development leads at contract manufacturers, and procurement managers at North American generic sponsors combined with secondary validation through FDA inspection database records, CDSCO manufacturing license registries, and EMA active substance master file submissions. Cross-reference against customs export data from DGFT and US import manifests anchored volume estimates.
Historical volume trendlines across the analysis window established baseline growth patterns segmented by product grade tier, end-user manufacturer type, delivery mode, and regional regulatory cluster. CAGRs were derived from slope analysis of annual procurement trajectories adjusted for patent expiry impacts and treatment guideline revision effects. Forecast inputs incorporated ICH Q7 compliance cost inflation, PLI scheme subsidy phase-out schedules, and chronic urticaria protocol adoption rates across dermatology practices.
Caveats apply where FDA inspection backlog resolution timelines or REACH authorization requirement changes for residual solvent classification could materially shift the outlook. Forecasts embed assumptions regarding pharmacopeial harmonization stability between USP, EP and IP standards. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Gemcitabine Hydrochloride Market
Pharmaceuticals
Asia-Pacific Aneurysmal Subarachnoid Hemorrhage Drugs Market
Pharmaceuticals
Gardasil (HPV Vaccine) Market
Pharmaceuticals
Dopamine and Norepinephrine Reuptake Inhibitor Market
Pharmaceuticals
Gastrointestinal OTC Drugs Market
Pharmaceuticals
Teriflunomide Market
Pharmaceuticals
Global Non-Alcoholic Fatty Liver Disease (NAFLD) Drug Market
Pharmaceuticals
Global Hepatitis B Vaccines Market
Pharmaceuticals
Asia-Pacific Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Endocarditis Drugs Market
Pharmaceuticals
Dystonia Drugs Market
Pharmaceuticals
New Zealand Diabetes Drugs Market
Pharmaceuticals
Antiplatelet Drugs Market
Pharmaceuticals
Penicillin Market
Pharmaceuticals
Europe Heparin Market
Pharmaceuticals
Metaxalone Market