
 Anti-Infective Vaccines Market | 2026-2036
Anti-Infective Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Infective Vaccines Market Analysis
Software-defined antigen design and computational epitope mapping is broadening what vaccine developers can license as recurring subscription services rather than one-off products. Pfizer leverages its manufacturing scale to anchor mRNA capacity across multiple therapeutic areas. Merck & Co. sustains competitive positioning through long-standing dominance in pediatric combination vaccines.
Anti-infective vaccines are biologic preparations containing attenuated, inactivated, or subunit antigenic components that stimulate adaptive immunity against pathogenic microorganisms, typically requiring cold-chain distribution at two to eight degrees Celsius to preserve molecular integrity. Their primary commercial purpose is preventing infectious disease morbidity in population-level immunization programs. Live attenuated formats occupy the highest margin pools due to durable cellular immunity and reduced booster requirements, while intranasal administration routes represent the fastest-growing delivery segment as mucosal vaccination gains clinical traction. Viral infection vaccines lead therapy area demand, though bacterial infection targets are deepening R&D pipelines.
FDA, EMA, and WHO prequalification standards shape product registration pathways, with WHO PQ determining access to Gavi-eligible country procurement. The EU Green Deal and FDA's enhanced manufacturing inspection protocols are tightening environmental and quality compliance costs. Stakeholders must monitor how regional regulator divergence on accelerated approval pathways affects portfolio prioritization and geographic launch sequencing.
Market Dynamics
The mRNA platform transition from COVID-19 toward broader infectious disease targets is compressing manufacturing timelines while forcing asset reallocation across multi-product facilities. This technological pivot demands that developers rebuild antigen design workflows around software-defined epitope mapping rather than traditional empirical screening.
Growth Catalysts
- Pediatric combination schedules:National immunization programs in India and Nigeria are expanding pentavalent and hexavalent coverage, creating sustained procurement volumes for combination vaccine suppliers.
- WHO prequalification pathways:The PQ acceleration framework is shortening registration timelines for Gavi-eligible countries, unlocking pooled procurement access for manufacturers meeting stability and cold-chain documentation standards.
- Intranasal delivery platforms:Mucosal administration routes are gaining clinical validation for respiratory pathogens, reducing cold-chain dependency and enabling community-based administration.
Market Restraints
- API supply concentration:Adjuvant manufacturing clusters in Belgium and the Netherlands create single-source vulnerability for aluminum-based formulations used in pediatric combinations.
- EMA environmental compliance:The EU Green Deal's manufacturing emission caps are raising facility retrofit costs for European production sites serving WHO PQ markets.
- Fill-finish capacity scarcity:Sterile injectable finishing lines are concentrated among contract manufacturers, creating queue bottlenecks during pandemic surge scenarios.
Strategic Opportunities
- India PLI scheme localization:Production-linked incentives for vaccine manufacturing are attracting fill-finish investments to serve Southeast Asian and African procurement.
- Thermostable formulation R&D:Lyophilization and novel stabilizer chemistries are enabling ambient distribution, opening last-mile delivery in cold-chain-deficient regions.
- Computational epitope licensing:Software-defined antigen design tools are shifting revenue models toward recurring platform subscriptions rather than per-product transactions.
Industry Challenges
- Bioprocess engineering talent scarcity:mRNA manufacturing scale-up requires specialized lipid nanoparticle formulation expertise that outpaces current training pipeline output.
- WHO PQ documentation burden:Stability protocol harmonization across FDA, EMA, and WHO standards demands redundant clinical lot testing, extending registration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Infective Vaccines Market |
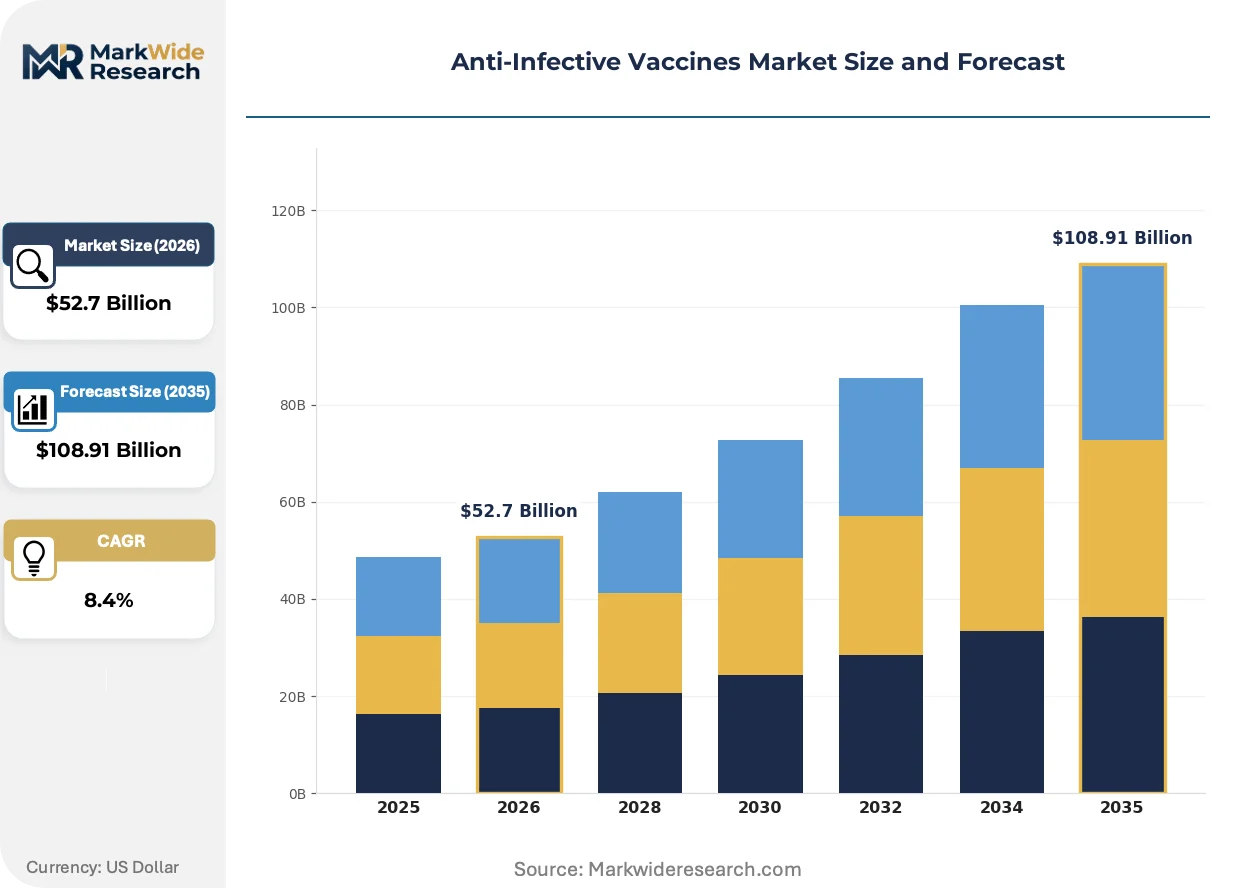
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $108.91 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Live Attenuated, Inactivated, Subunit, Toxoid Therapy Area: Viral Infections, Bacterial Infections, Fungal Infections, Protozoal Infections Administration Route: Intramuscular, Subcutaneous, Oral, Intranasal End User: Hospitals, Clinics, Research Institutions, Pharmacies |
| Companies Covered | Pfizer, Merck & Co., GlaxoSmithKline, Sanofi, AstraZeneca, Moderna, Novavax, Serum Institute of India, Bharat Biotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Infective Vaccines Market Emerging Trajectories
Antigen discovery workflows are migrating from empirical screening toward structure-guided computational design, compressing preclinical timelines while raising the bar for bioinformatics infrastructure investment. This shift is redrawing competitive boundaries between platform technology owners and traditional empirical developers.
Structure-guided antigen design is unifying previously separate computational biology and wet-lab validation workflows into continuous digital-physical loops. Mid-size developers lacking in-house structural biology capabilities are licensing AI-driven epitope prediction platforms from specialized software vendors. This convergence is compressing lead identification timelines while concentrating competitive advantage among firms with integrated computational-cGMP capabilities.
EMA's enhanced manufacturing inspection protocols under the EU Green Deal are tightening environmental release standards for solvent-intensive purification steps. Facilities operating legacy chromatography suites face capital-intensive retrofit requirements to meet volatile organic compound emission thresholds. European manufacturers serving Gavi markets are responding by consolidating production at newer greenfield sites with integrated waste recovery systems.
National stockpiling mandates are fragmenting procurement from centralized UN mechanisms toward bilateral sovereign contracts with local production requirements. Brazil's ANVISA and India's CDSCO are conditioning emergency use authorizations on domestic fill-finish commitments, displacing traditional UNICEF pooled purchasing for pandemic preparedness. This geographic demand rotation is forcing manufacturers to replicate quality systems across multiple regulatory jurisdictions rather than optimizing for single-source WHO PQ compliance.
Anti-Infective Vaccines Market Segmentation
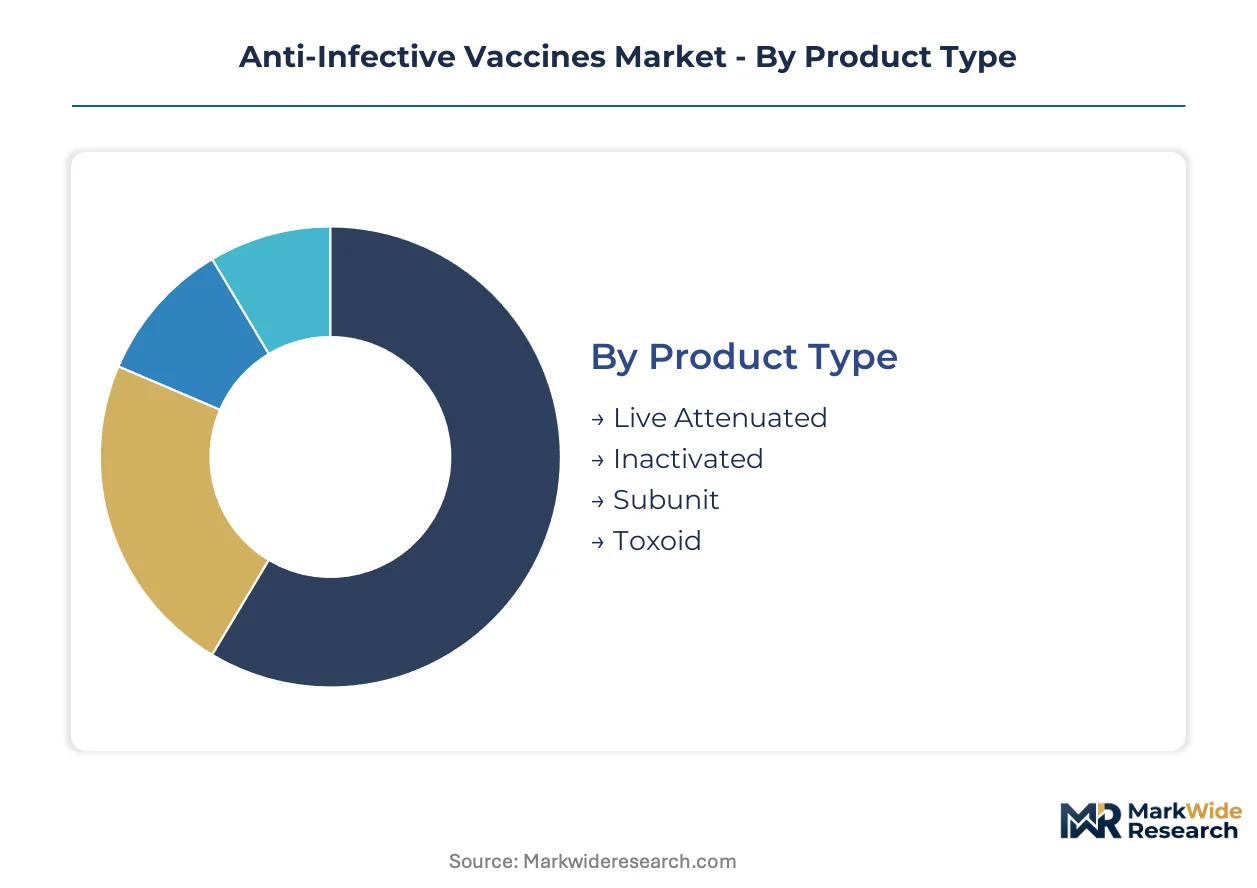
Segmentation in anti-infective vaccines reveals divergent margin structures across manufacturing complexity tiers. Product format and administration route determine cold-chain infrastructure requirements, while therapy area specialization shapes regulatory pathway investments.
Product Type:
Volume production concentrates in formats with established fill-finish infrastructure, while premium margins accrue to formats requiring complex bioprocess engineering.
- Live Attenuated:These formulations contain weakened pathogenic organisms that replicate minimally in host tissue to elicit durable cellular immunity. Demand clusters in pediatric combination programs across India and Nigeria, where single-dose efficacy reduces cold-chain distribution costs. Mature deployment sits with Live Attenuated. Newer deployment is concentrated in Subunit.
- Inactivated:Whole-pathogen preparations destroyed by heat or chemicals retain immunogenicity without replication risk. Procurement volumes from national stockpiling programs in the United States and China favor this format for pandemic preparedness due to established safety profiles.
- Subunit:Purified antigen components—proteins or polysaccharides—deliver targeted immune response without whole-cell complexity. mRNA platform expansion is accelerating recombinant subunit development timelines.
- Toxoid:Bacterial exotoxins inactivated by formalin retain immunogenicity for toxin-mediated diseases. Tetanus and diphtheria toxoids anchor WHO prequalified pediatric combination schedules.
Established formats dominate procurement volumes, while recombinant subunit approaches capture platform licensing revenue.
Therapy Area:
Application urgency and population burden determine R&D prioritization across infectious disease targets.
- Viral Infections:Respiratory and vector-borne pathogens command the deepest clinical pipelines, with mRNA manufacturing capacity reorienting from COVID-19 toward influenza and RSV candidates. Hospital systems in the United States and China drive procurement for adult immunization programs.
- Bacterial Infections:Pneumococcal and meningococcal polysaccharide conjugates sustain combination vaccine franchises. Gavi-eligible countries in sub-Saharan Africa concentrate demand for pentavalent and hexavalent formulations.
- Fungal Infections:Candida and Aspergillus vaccines target immunocompromised populations in oncology and transplant centers. Limited commercial infrastructure constrains manufacturing scale.
- Protozoal Infections:Malaria and leishmaniasis candidates address tropical disease burden through WHO and Gates Foundation funding mechanisms. RTS,S malaria vaccine distribution in Ghana and Kenya establishes proof-of-concept for parasite-targeting platforms.
Respiratory viral targets absorb the majority of platform technology investment. Bacterial combinations sustain procurement predictability through national immunization schedules.
Administration Route:
Delivery modality shapes distribution economics and last-mile access constraints.
- Intramuscular:Deltoid or vastus lateralis injection remains standard for aluminum-adjuvanted formulations requiring deep tissue depot formation. Clinics and hospitals across India and Brazil maintain refrigerated storage for routine pediatric administration.
- Subcutaneous:Upper arm or thigh injection suits live attenuated formats with smaller fluid volumes. Measles-mumps-rubella combinations deploy through this route in community health worker programs.
- Oral:Enteric-coated capsules or liquid suspensions eliminate cold-chain dependency for thermostable formulations. Typhoid and cholera vaccines in Bangladesh and Pakistan demonstrate field stability advantages.
- Intranasal:Mucosal spray delivery generates IgA-mediated respiratory protection without systemic injection. Clinical validation for influenza and COVID-19 candidates is expanding fastest among administration modalities.
Injectable formats retain manufacturing dominance. Intranasal platforms are climbing fastest as mucosal immunization gains regulatory traction.
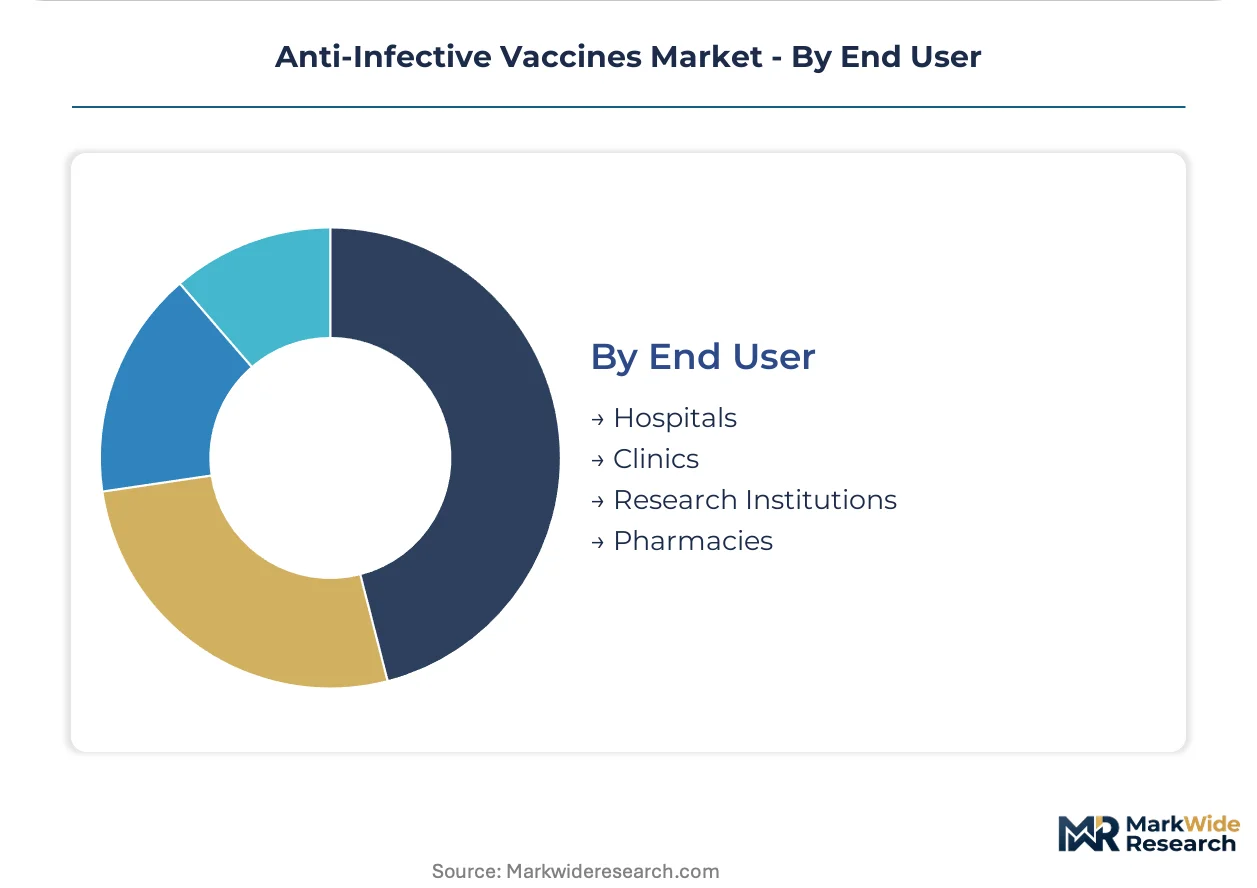
End User:
Procurement authority and patient volume determine contract structure and pricing negotiation leverage.
- Hospitals:Acute care systems manage adult immunization for influenza, pneumococcal, and shingles vaccines through centralized pharmacy operations. The United States and Germany concentrate demand for high-dose formulations in aging populations.
- Clinics:Primary care and community health centers administer routine pediatric schedules and travel medicine. India's Universal Immunization Program channels pentavalent and rotavirus doses through this tier.
- Research Institutions:Academic medical centers and contract research organizations conduct Phase I-III trials and post-market surveillance. FDA and EMA inspection protocols govern site qualification for global studies.
- Pharmacies:Retail and independent dispensers expand access for adult boosters and seasonal campaigns. Brazil's expanded pharmacy vaccination authority increases point-of-care availability.
Institutional procurement dominates volume contracting. Pharmacy channel expansion is broadening access most rapidly for adult immunization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity concentrates in Belgium, the Netherlands, and Switzerland, while procurement demand clusters in the United States, China, and India. Cold-chain distribution networks and pediatric immunization programs shape regional consumption patterns.
United States
FDA accelerated approval pathways and BARDA stockpiling contracts drive procurement for pandemic preparedness. The Biomedical Advanced Research and Development Authority maintains strategic reserves of influenza and smallpox vaccines. Boston and Research Triangle Park anchor mRNA manufacturing clusters with integrated lipid nanoparticle formulation capabilities.
China
NMPA conditional approval frameworks and dual carbon manufacturing mandates reshape local production requirements. CDSCO-equivalent pathways prioritize domestic fill-finish commitments for emergency use authorizations. Beijing and Shanghai concentrate bulk antigen manufacturing with expanding lyophilization capacity for thermostable formulations.
India
PLI scheme production-linked incentives attract fill-finish investments for Southeast Asian and African export markets. CDSCO manufacturing license requirements condition market access on local stability testing protocols. Hyderabad and Pune anchor recombinant subunit and viral vector manufacturing with WHO prequalified facilities.
Germany
EMA enhanced manufacturing inspection protocols under the EU Green Deal tighten volatile organic compound emission thresholds for solvent-intensive purification. REACH compliance documentation burdens extend registration timelines for Gavi-eligible country access. Marburg and Idar-Oberstein concentrate legacy adjuvant manufacturing with greenfield retrofit investments.
Brazil
ANVISA emergency use authorization requirements mandate domestic fill-finish commitments for pandemic vaccine access. National immunization program expansion drives pentavalent and rotavirus procurement through SUS public health channels. São Paulo and Rio de Janeiro anchor fill-finish partnerships with multinational technology transfer agreements.
Anti-Infective Vaccines Market Vendor Landscape
Top-tier vendors anchor platform technology licensing, while mid-tier developers compete on regional manufacturing scale and WHO prequalification speed. The vendor base stratifies across integrated mRNA platform owners, established pediatric combination suppliers, and emerging fill-finish specialists. Two strategic archetypes dominate: computational antigen design licensors and multi-product cGMP facility operators. Competitive moves concentrate on bioprocess engineering talent acquisition and thermostable formulation patent positioning.
Within the platform technology tier, Pfizer and Moderna exemplify mRNA manufacturing scale deployment across infectious disease targets. Merck & Co. occupies a position in pediatric combination vaccine franchises with established cold-chain distribution networks. Serum Institute of India represents the emerging market archetype, anchoring high-volume fill-finish capacity for WHO prequalified export markets.
| Leading Market Players |
|---|
| Pfizer |
| Merck & Co. |
| GlaxoSmithKline |
| Sanofi |
| AstraZeneca |
| Moderna |
| Novavax |
| Serum Institute of India |
| Bharat Biotech |
| Others |
Supply Flow & Price Mechanics
The EU Green Deal's manufacturing emission caps are gating qualified supply for European production sites while simultaneously filtering premium-tier pricing access to sponsors with greenfield facility investments. Buyers in Gavi-eligible markets face bifurcated procurement: WHO PQ-compliant manufacturers command contract premiums while legacy facilities absorb margin compression from retrofit compliance costs.
Pricing Analysis
Margin tightening in standard-tier live attenuated vaccines reflects aluminum adjuvant supply concentration in Belgium and the Netherlands. Pricing stratifies across premium, standard, and economy tiers based on WHO PQ certification status and cold-chain documentation completeness. Cost-down pressure on economy-tier pentavalent combinations accelerates because Indian PLI scheme entrants are undercutting legacy suppliers with localized fill-finish. Government procurement offices in Nigeria and Bangladesh exhibit highest price sensitivity, while BARDA stockpiling contracts in the United States show lowest sensitivity to unit cost.
Supply Chain Analysis
Regional distribution centers in Hyderabad, Pune, and São Paulo anchor hub-and-spoke patterns for last-mile delivery to sub-Saharan Africa and Southeast Asia. Bulk antigen manufacturing draws from Belgium, the Netherlands, and Switzerland, with fill-finish capacity expanding in India and Brazil under technology transfer agreements. Single-source vulnerability in lipid nanoparticle formulation expertise creates supply chain risk for mRNA platform scale-up. Distribution runs through UNICEF's Copenhagen hub for Gavi-eligible markets, while bilateral sovereign contracts increasingly bypass pooled procurement mechanisms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anti-infective vaccines market operates as a cost-of-compliance story where EMA enhanced manufacturing inspection protocols under the EU Green Deal erect barrier-to-entry moats favoring sponsors with integrated waste recovery systems and greenfield facility investments.
For Market Incumbents: Anchor competitive positioning through bioprocess engineering talent acquisition in lipid nanoparticle formulation, the scarcest capability as mRNA manufacturing scales beyond COVID-19. Defend against emerging fill-finish specialists in India by consolidating WHO PQ documentation capabilities across multiple regulatory jurisdictions rather than optimizing for single-source compliance. Prioritize thermostable formulation patent positioning to capture ambient distribution premiums in cold-chain-deficient regions.
For New Entrants and Emerging Players: Launch via pharmacy channel partnerships in Brazil's expanded vaccination authority markets, bypassing institutional procurement bottlenecks. Target intranasal delivery platform white space where mucosal immunization validation is climbing fastest among administration modalities. Enter through computational epitope licensing subscriptions rather than per-product transactions, capturing recurring revenue from mid-size developers lacking in-house structural biology capabilities.
For Investors and Strategic Acquirers: WHO PQ acceleration framework shortening registration timelines for Gavi-eligible countries is the leading indicator that fill-finish capacity scarcity will deepen competitive moats for prequalified manufacturers. Long-term viability over the next decade rests on platform technology ownership rather than single-product franchises. Acquisition targets should profile as integrated computational-cGMP operators with software-defined antigen design tools. Watch for thermostable formulation breakthroughs as the signal that last-mile delivery economics are shifting toward ambient distribution models.
| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Unlocks Gavi pooled procurement access for manufacturers meeting stability documentation standards. |
| mRNA Manufacturing Scale-Up | Rebuilds antigen design workflows around software-defined epitope mapping across multi-product facilities. |
| Thermostable Formulation R&D | Enables ambient distribution in cold-chain-deficient regions through lyophilization advances. |
| Computational Epitope Licensing | Shifts revenue models toward recurring platform subscriptions from specialized software vendors. |
| Fill-Finish Capacity Expansion | Addresses sterile injectable bottlenecks under India's PLI scheme for Southeast Asian export markets. |
Methodological Framework
Document review covered FDA filings, EMA submissions, ClinicalTrials.gov records, and WHO prequalification databases, complemented by interviews with vaccine development executives, regulatory affairs leads, formulary directors at hospital systems, and procurement managers at national immunization programs. Primary fieldwork across the United States, India, Germany, and Brazil validated secondary data on manufacturing capacity and pricing dynamics. Bottom-up modeling of product-level volumes triangulated against top-down market sizing from trade data and sponsor disclosures.
Cross-referencing historical WHO PQ approval timelines with expert panel input on mRNA platform transition dynamics shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, therapy area, administration route, end-user procurement channel, and regional regulatory cluster. CAGRs were derived from growth driver elasticity analysis and scenario-weighted probability assessments. Forecast inputs incorporated bioprocess engineering talent pipeline constraints and EMA environmental compliance cost trajectories.
Regulatory divergence on accelerated approval pathways, API supply concentration disruptions, and fill-finish capacity bottlenecks are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumptions on technology adoption curves and procurement localization mandates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Marburg Virus Disease Therapeutics Market
Pharmaceuticals
Asia-Pacific Fatty Bases for Suppositories Market
Pharmaceuticals
Opium Tincture Market
Pharmaceuticals
Meperidine Drugs Market
Pharmaceuticals
Intravenous Solution Compounders Market
Pharmaceuticals
Dyslipidemia Therapeutics Market
Pharmaceuticals
Global Preventive Vaccines Market
Pharmaceuticals
North America Dipeptide Peptidase 4 (Dpp-4) Inhibitors Market
Pharmaceuticals
Erectile Dysfunction Market
Pharmaceuticals
Global Tetanus Toxoid Vaccine Market
Pharmaceuticals
US Pharmaceutical CMO Market
Pharmaceuticals
Cough Oral Solution Market
Pharmaceuticals
Antiepileptic Drugs (AED) Market
Pharmaceuticals
Tuberculosis Vaccine Treatment Market
Pharmaceuticals
Europe Novel Drug Delivery System (NDDS) Market
Pharmaceuticals
Anastrozole Tablets Market