
 Japan Semiconductor Device Market | 2026-2036
Japan Semiconductor Device Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Semiconductor Device Market Insights
Advanced-node specification tiers is rotating capital toward automotive-grade and power-device reliability standards. Renesas Electronics Corp anchors domestic automotive MCU supply through in-house fabrication and foundry partnerships. Shinko Electric Industries Co. Ltd specializes in high-density organic substrates for advanced packaging. TOWA Corp dominates precision mold equipment for epoxy resin encapsulation, a critical step in automotive device qualification.
A semiconductor device is an electronic component fabricated from crystalline silicon, compound semiconductors such as gallium nitride or silicon carbide, or epitaxial layers thereof, engineered to control electron flow through doped p-n junctions, gate oxides, or heterostructures for switching, amplification, or signal processing functions. Discrete Devices and power-oriented Integrated Circuits command the deepest margin pools in Japan's supplier base, reflecting automotive and industrial voltage-handling requirements. SiC and GaN technology segments are expanding fastest as METI-backed foundry investments mature, while CMOS retains volume leadership in consumer and telecommunications applications.
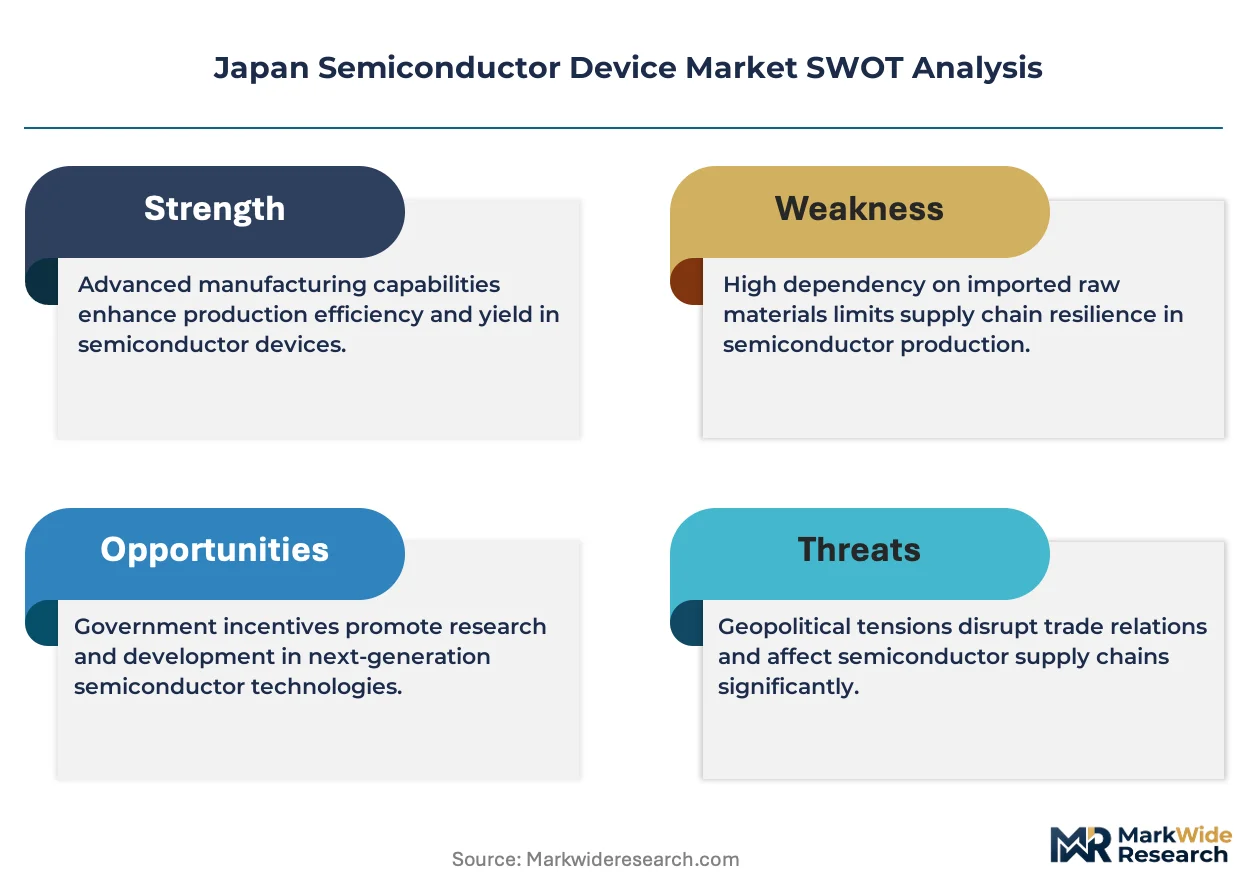
METI's subsidy frameworks, JIS quality standards, and PMDA-adjacent medical-device semiconductor rules collectively elevate entry barriers for non-compliant suppliers. PMDA traceability requirements for implantable and diagnostic equipment extend design-cycle demands on domestic device makers. Stakeholders must monitor subsidy allocation timing and foundry utilization rates to calibrate capacity commitments against actual automotive program ramps.
Market Dynamics
METI's semiconductor revitalization subsidies are redirecting domestic capital toward automotive-grade silicon carbide and gallium nitride production, compressing investment timelines for power-device qualification.
Growth Catalysts
- Automotive electrification mandates:Domestic OEMs are expanding MCU procurement for battery management and inverter systems, pulling demand toward Kyushu's foundry cluster.
- METI subsidy frameworks:The ministry's production capacity incentives are de-risking capital commitments for 200mm SiC wafer expansion.
- Silicon carbide epitaxy:Epitaxial layer deposition techniques are maturing for 1200V automotive traction applications, narrowing the performance gap with silicon IGBTs.
Market Restraints
- Equipment import dependency:Lithography and ion implantation tools concentrate among Dutch and American suppliers, exposing buildout schedules to export control friction.
- Substrate cost structure:SiC boule slicing yields remain below silicon equivalents, inflating die costs for mid-voltage industrial drives.
- JIS certification timelines:Automotive-grade reliability testing under JIS standards extends qualification cycles by 18-24 months versus consumer CMOS.
Strategic Opportunities
- Medical-device semiconductors:PMDA traceability requirements for implantable electronics are creating captive demand for domestic foundry capacity with full lot documentation.
- Advanced packaging substrates:High-density organic interposers for chiplets represent underdeveloped capacity within Japan's materials ecosystem.
- GaN-on-silicon convergence:Consumer power adapter and data center PSU segments are adopting gallium nitride for 650V applications below SiC cost thresholds.
Industry Challenges
- Compound semiconductor process engineering:SiC and GaN device physics require distinct doping profiles and thermal management expertise scarce in legacy silicon CMOS talent pools.
- Automotive program integration:Tier-1 suppliers demand synchronous qualification across multiple wafer sources, complicating foundry allocation for fabless designers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Semiconductor Device Market |
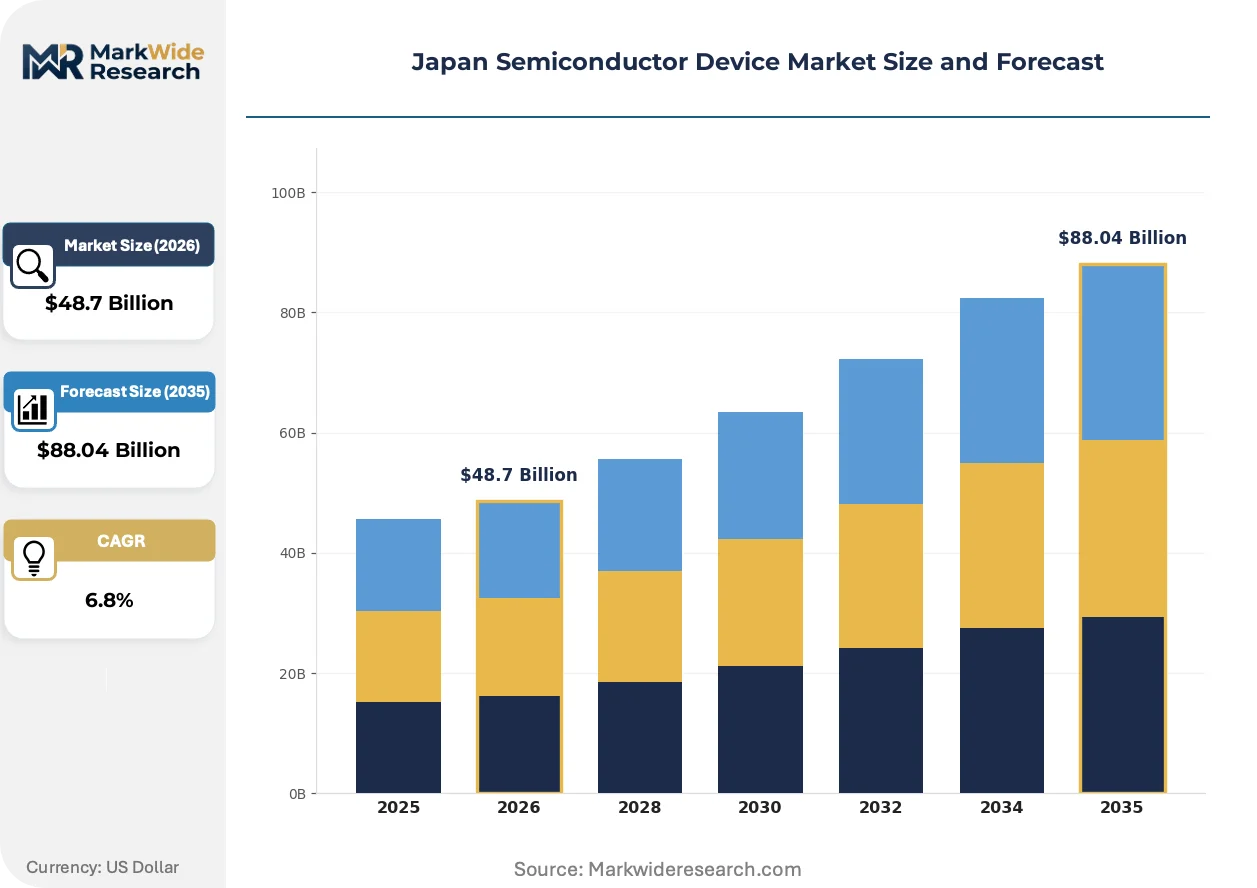
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Discrete Devices, Integrated Circuits, Optoelectronics, Sensors Technology: CMOS, BiCMOS, GaN, SiC End User: Telecommunications, Consumer Electronics, Automotive, Industrial Application: Power Management, Signal Processing, Data Conversion, Communication |
| Companies Covered | Shinko Electric Industries Co. Ltd, Ferrotec Holdings Corp, Renesas Electronics Corp, TOWA Corp, JAPAN MATERIAL Co. Ltd, SCREEN Holdings Co. Ltd, Tokyo Seimitsu Co. Ltd, Mitsui High-tec, Inc., ROHM Co. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Semiconductor Device Market Trends and Innovations
Process-node diversification and packaging architecture evolution are redistributing value capture across Japan's device supply base, with power electronics and automotive reliability standards commanding priority.
Silicon carbide MOSFET technology is fragmenting the insulated-gate bipolar transistor's historical lock on electric vehicle traction inverters. Automotive OEMs in Japan are qualifying 800V SiC architectures for next-generation battery platforms ahead of 2026 model introductions. This voltage-class migration is compressing silicon IGBT procurement forecasts while expanding demand for SiC epitaxial wafer and module packaging capacity.
METI's semiconductor production subsidies are accelerating domestic 200mm SiC substrate qualification. The ministry's cost-sharing framework requires recipient foundries to reserve capacity for automotive and industrial customers, reshaping allocation priorities away from consumer electronics. Kyushu-based fabrication clusters are capturing the bulk of these incentives, consolidating power-device production geography.
Automotive procurement departments are consolidating supplier panels around vertically integrated device makers with in-house packaging and test capabilities. Tier-1 inverter manufacturers are narrowing qualified vendor lists to three or fewer sources per voltage class, replacing the historical six-to-eight supplier dispersion. This concentration is most pronounced in 750V-1200V automotive traction applications, where reliability documentation requirements favor established Japanese suppliers with JIS-certified quality systems.
Japan Semiconductor Device Market Segmentation
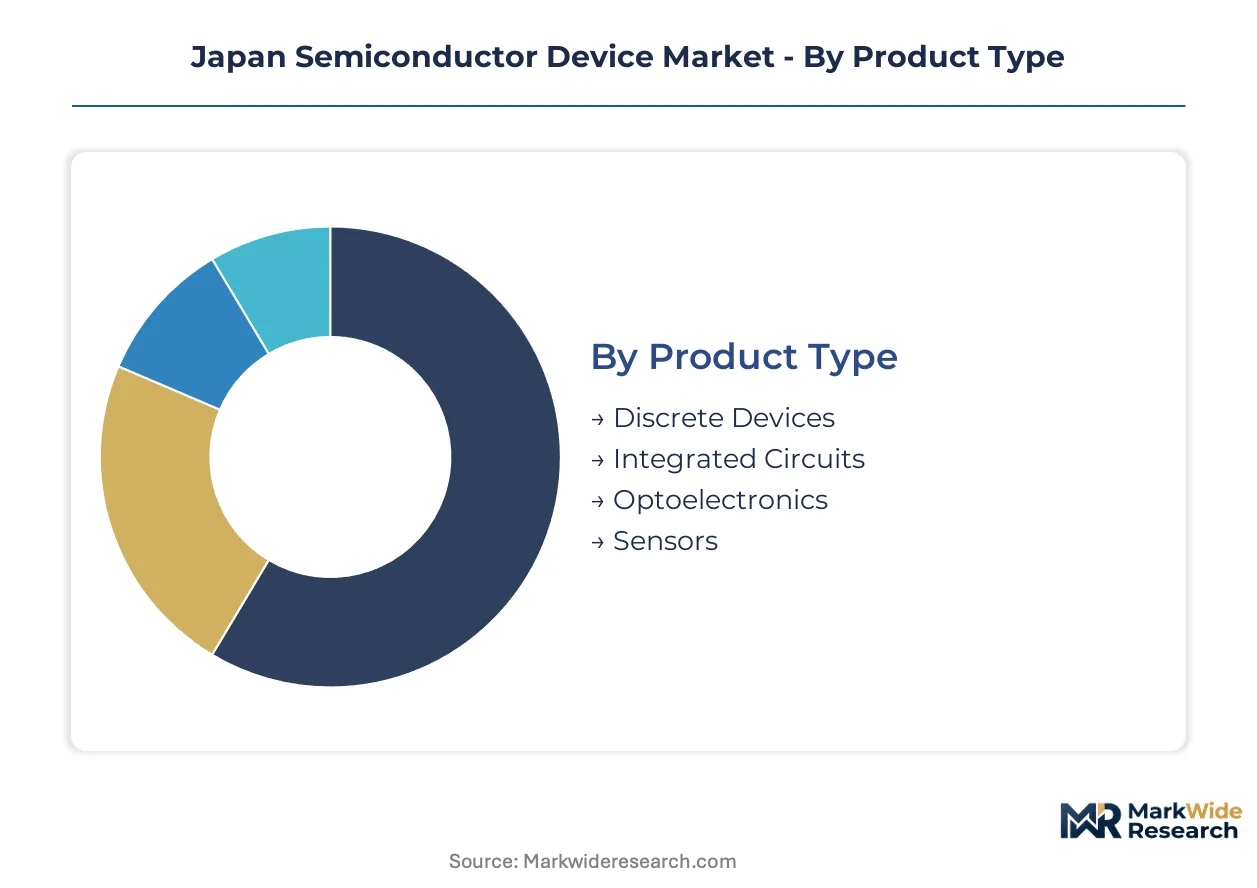
Japan's semiconductor device market fragments across four analytical dimensions that govern capital allocation and foundry scheduling. Product type and technology classifications determine margin capture, while end-user and application segments dictate qualification timelines under METI subsidy frameworks.
Product Type:
Discrete Devices and power-oriented Integrated Circuits command the deepest margin pools, reflecting automotive voltage-handling requirements and JIS certification premiums.
- Discrete Devices:Individual semiconductor components including diodes, transistors, and thyristors fabricated from silicon or compound substrates. Automotive inverter manufacturers in Kyushu's silicon island cluster source 1200V SiC discrete units for traction systems, with METI subsidies de-risking 200mm wafer expansion commitments.
- Integrated Circuits:Monolithic assemblies of transistors, resistors, and capacitors on single substrates performing complex functions. MCU procurement from domestic OEMs concentrates around Renesas Electronics' in-house fabrication and foundry partnerships for battery management systems.
- Optoelectronics:Light-emitting and light-detecting devices spanning LEDs, photodiodes, and laser diodes. Industrial automation lines in Osaka and Nagoya prefectures drive demand for high-speed optical isolators.
- Sensors:Transducers converting physical parameters into electrical signals, including MEMS accelerometers and pressure transducers. PMDA traceability requirements for implantable medical electronics extend design-cycle demands on domestic MEMS foundries.
Discrete Devices holds installed capacity. Integrated Circuits is rotating up the share rankings.
Technology:
Silicon carbide and gallium nitride segments attract subsidy-weighted investment flows, while CMOS retains volume leadership through consumer and telecommunications applications.
- CMOS:Complementary metal-oxide-semiconductor technology pairing p-type and n-type MOSFETs for low static power consumption. Consumer electronics assembly in Tokyo and Osaka metropolitan areas sustains 40-90nm node demand for smartphones and tablets.
- SiC:Silicon carbide wide-bandgap semiconductor enabling high-temperature, high-voltage operation. 800V automotive traction inverters from domestic OEMs are narrowing qualified vendor lists to three or fewer sources per voltage class.
- GaN:Gallium nitride heterostructure devices delivering superior electron mobility for RF and power conversion. Data center PSU segments below SiC cost thresholds are adopting 650V GaN-on-silicon for efficiency gains.
- BiCMOS:Bipolar-CMOS integration combining high-speed bipolar transistors with low-power CMOS logic. Telecommunications infrastructure in Greater Tokyo maintains demand for mixed-signal BiCMOS RF front-ends.
SiC captures subsidy-allocated capacity. GaN is climbing the fastest.
End User:
Automotive procurement departments consolidate supplier panels around vertically integrated device makers, compressing historical six-to-eight vendor dispersion.
- Automotive:Tier-1 inverter and battery management system manufacturers. Kyushu-based foundry clusters reserve capacity for automotive customers under METI's cost-sharing framework, reshaping allocation priorities away from consumer electronics.
- Industrial:Factory automation, motor drives, and power supply manufacturers. Mid-voltage industrial drives face SiC substrate cost inflation from boule slicing yields below silicon equivalents.
- Telecommunications:Base station infrastructure and optical network equipment providers. 5G deployment timelines in Tokyo, Osaka, and Nagoya sustain demand for GaN RF power amplifiers.
- Consumer Electronics:Smartphone, tablet, and wearable device OEMs. Premium segment concentration in domestic brands maintains 7nm and below CMOS orders despite foundry allocation shifts.
Automotive holds qualification priority. Industrial is gaining share fastest.
Application:
Power Management commands capital rotation toward wide-bandgap devices, while Signal Processing retains silicon CMOS dominance.
- Power Management:Voltage regulation, battery charging, and energy conversion circuits. SiC MOSFET technology fragments the IGBT's historical lock on electric vehicle traction inverters ahead of next-generation battery platform introductions.
- Signal Processing:Analog-to-digital conversion, filtering, and amplification functions. Consumer and telecommunications CMOS applications sustain 40-90nm node utilization despite automotive allocation pressures.
- Data Conversion:ADC and DAC interfaces bridging analog sensors with digital processors. Medical-device semiconductor rules from PMDA extend lot documentation requirements for diagnostic equipment.
- Communication:RF transceivers, modems, and protocol controllers. 5G base station rollouts in Japan's three major metropolitan areas stabilize BiCMOS and GaN RF component demand.
Power Management holds technology investment. Signal Processing maintains volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's semiconductor device trade balance tilts toward specialized component exports while importing lithography and ion implantation equipment from Dutch and American suppliers. Domestic production concentrates in Kyushu's silicon island cluster and the Tokyo-Osaka industrial corridor. METI's subsidy frameworks are reshaping regional investment flows toward automotive-grade capacity.
Kyushu
Automotive MCU and power-device demand from domestic OEMs anchors wafer fabrication in this southern island cluster. METI's production capacity incentives require recipient foundries to reserve output for automotive customers. Kumamoto and Kagoshima prefectures co-locate epitaxial wafer growth, device fabrication, and module packaging operations under unified subsidy frameworks.
Kanto
Tokyo and surrounding prefectures sustain CMOS demand for consumer electronics and telecommunications infrastructure. JIS quality standards and PMDA-adjacent medical-device rules elevate entry barriers for non-compliant suppliers in this administrative center. Yokohama and Tsukuba host MEMS foundries serving implantable electronics with full lot documentation requirements.
Kansai
Osaka prefecture drives industrial automation demand for high-speed optical isolators and factory motor drives. Shinko Electric Industries anchors high-density organic substrate supply from this region. Kyoto-based equipment specialists serve precision mold operations for epoxy resin encapsulation critical to automotive qualification.
Chubu
Nagoya's automotive supply chain integration pulls discrete device procurement toward Tier-1 inverter manufacturers. Toyota and Honda procurement departments consolidate supplier panels around vertically integrated device makers with in-house packaging capabilities. Aichi prefecture foundries face synchronous qualification demands across multiple wafer sources.
Tohoku
Sendai and surrounding cities support silicon wafer and materials production feeding Kyushu fabrication clusters. Substrate cost pressures from SiC boule slicing yields below silicon equivalents affect regional materials economics. Miyagi prefecture suppliers coordinate with METI-backed 200mm SiC expansion timelines.
Japan Semiconductor Device Market Competitive Landscape
Listed leaders compete with private specialists across fabrication, materials, and equipment verticals. The vendor base spans vertically integrated device makers, precision equipment specialists, and substrate manufacturers with varying exposure to automotive qualification cycles. Three archetypes dominate: automotive-grade MCU suppliers with in-house fabrication, precision mold and packaging equipment specialists, and compound semiconductor materials providers. Capacity reservation agreements under METI subsidies and JIS certification investments constitute the primary competitive moves.
Among Tokyo-listed fabricators, Renesas Electronics Corp and ROHM Co. Ltd occupy positions within the automotive-grade integrated device manufacturer tier. TOWA Corp represents the precision equipment specialist archetype serving epoxy resin encapsulation requirements. These three companies exemplify the geographic and functional segmentation across Kyushu fabrication, Kanto equipment supply, and Kansai materials ecosystems.
| Leading Market Players |
|---|
| Shinko Electric Industries Co. Ltd |
| Ferrotec Holdings Corp |
| Renesas Electronics Corp |
| TOWA Corp |
| JAPAN MATERIAL Co. Ltd |
| SCREEN Holdings Co. Ltd |
| Tokyo Seimitsu Co. Ltd |
| Mitsui High-tec, Inc. |
| ROHM Co. Ltd |
| Others |
Pricing and Supply Chain Analysis
Silicon carbide MOSFET substitution for silicon IGBTs in automotive traction inverters simultaneously concentrates supply geography around Kyushu's METI-subsidized foundry cluster and compresses pricing premiums for legacy silicon power devices. This displacement dynamic feeds back into procurement strategies as Tier-1 suppliers consolidate vendor panels around three or fewer qualified sources per voltage class.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with pricing stratifying across automotive-grade JIS certification tiers, volume scale commitments, and vertical integration depth. Price differentiation reflects reliability documentation burdens and foundry allocation priority under METI subsidy frameworks. Cost compression in mid-voltage industrial SiC tiers intensifies because substrate slicing yields trail silicon equivalents, while automotive procurement departments show least price sensitivity due to synchronous qualification requirements across multiple wafer sources.
Supply Chain Analysis
Inbound logistics costs from Dutch lithography equipment suppliers and American ion implantation tool vendors expose buildout schedules to export control friction at Yokohama and Kobe port gateways. Wafer fabrication concentrates in Japan's Kyushu cluster, with epitaxial materials sourcing from Tohoku suppliers and precision mold equipment from Kansai-based specialists. The supply chain rests on SiC boule growth, photoresist chemicals, and high-purity gases as critical inputs. Single-source vulnerability in extreme ultraviolet lithography systems dominates risk exposure. Distribution runs through Tier-1 inverter manufacturers with synchronous qualification demands across multiple foundry sources.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat environment where METI subsidy allocation rights and JIS certification investments create regulatory entrenchment that elevates switching costs for automotive OEM procurement departments.
For Market Incumbents: Compound JIS-certified quality system investments with capacity reservation agreements under METI's cost-sharing framework to deepen captive supply relationships with domestic automotive OEMs. Defend against GaN-on-silicon substitution in 650V consumer adapter segments by accelerating 800V SiC platform qualification timelines. Prioritize backward integration into epitaxial wafer growth to secure substrate allocation priority.
For New Entrants and Emerging Players: Medical-device semiconductor traceability services represent a service-layer gap where incumbents under-serve PMDA documentation requirements for implantable electronics. Target MEMS foundry capacity in Greater Tokyo with full lot documentation capabilities as the most penetrable white-space segment. Pursue partnership-based go-to-market positioning with Yokohama and Tsukuba biomedical engineering clusters to bypass JIS automotive certification barriers.
For Investors and Strategic Acquirers: The market sits at a subsidy-deployment phase that favors compound semiconductor materials specialists with 200mm SiC substrate qualification progress. Long-term viability across the next decade hinges on METI allocation continuity and automotive electrification mandate durability. Acquisition target archetypes include precision mold equipment specialists serving epoxy resin encapsulation and high-density organic substrate manufacturers. Monitor foundry utilization rate divergence from automotive program ramp schedules as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| 200mm SiC Wafer Capacity Expansion | METI subsidy frameworks de-risk capital commitments while mandating automotive customer reservation. |
| JIS Certification Investment | Automotive-grade reliability testing extends qualification cycles and elevates entry barriers for non-compliant suppliers. |
| Epitaxial Layer Integration | In-house SiC epitaxy capability secures substrate allocation priority under synchronous qualification demands. |
| Medical-Device Foundry Documentation | PMDA traceability requirements for implantable electronics create captive demand with full lot documentation. |
| GaN-on-Silicon Process Development | 650V consumer power adapter adoption below SiC cost thresholds opens data center PSU segments. |
Research Methodology
The analysis maps discrete devices, integrated circuits, optoelectronics, and sensors, each validated through semiconductor device engineering directors, foundry operations managers, automotive Tier-1 procurement leads, and METI subsidy program administrators. Primary interview insights combined with secondary validation from SEC 10-K filings, Japan Customs trade statistics, JIS standard documentation, and PMDA medical-device registration databases. Bottom-up capacity and utilization estimates triangulated against top-down subsidy allocation and automotive production forecasts.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled technology segments, product types, end-user industries, and application categories with regional production cluster differentiation. CAGRs derived from segment-level growth rate reconciliation with aggregate market scaling. Forecast inputs incorporated foundry utilization rates, automotive platform introduction timelines, and SiC epitaxy yield maturation curves without year-specific anchoring.
Forecasts assume regulatory continuity in METI subsidy regimes and PMDA medical-device traceability rules; material policy shifts would require re-modeling. Substrate cost inflation from boule slicing yield gaps and export control friction on lithography equipment constitute specific revision risks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
China MLCC Market
Semiconductor Devices
Americas Power Transistor Market
Semiconductor Devices
Wttx Market
Semiconductor Devices
Global Gan Semiconductor Device Market
Semiconductor Devices
5G Automotive Grade Product Market
Semiconductor Devices
Power Supply in Package (Psip) and Power Supply on Chip (Pwrsoc) Market
Semiconductor Devices
North America Silicon Carbide Wafers Market
Semiconductor Devices
Japan MCU Market
Semiconductor Devices
Gan and Sic Power Semiconductor Market
Semiconductor Devices
Ferroelectric FET Market
Semiconductor Devices
Analog to Digital Converter Market
Semiconductor Devices
IGCT Market
Semiconductor Devices
High Voltage Diodes Market
Semiconductor Devices
High Electron Mobility Transistor Market
Semiconductor Devices
Silicon Epitaxial Wafer Market
Semiconductor Devices
FPGA Market