
 Padlock Smart Lock Market | 2026-2036
Padlock Smart Lock Market Size, Share, and Industry Trends Forecast 2026-2036
Padlock Smart Lock Market Analysis
The padlock smart lock category is restructuring around a widening gap between premium biometric systems and commodity Bluetooth-enabled units. ASSA ABLOY leverages its door hardware heritage to dominate European commercial channels. Master Lock Company LLC anchors the North American portable segment through retail distribution density. Samsung competes on mobile ecosystem integration, extending its smartphone authentication stack into physical security hardware.
A padlock smart lock is an electromechanical locking device retaining the traditional shackle-and-body form factor while incorporating digital authentication mechanisms such as capacitive fingerprint sensors, Bluetooth Low Energy transceivers, or Wi-Fi connectivity modules for remote management; these devices secure gates, storage units, lockers, and equipment enclosures where hardwired power is unavailable. Fingerprint lock units command the highest margins due to semiconductor sensor costs and liveness-detection firmware requirements. Bluetooth lock volumes lead in residential DIY channels where smartphone pairing replaces key management. Cloud-based technology platforms are capturing recurring revenue through subscription access logs and temporary credential issuance.
FCC certification governs radio frequency emissions for Wi-Fi and Bluetooth variants sold in the United States, while CE marking and the EU AI Act impose conformity requirements on biometric data processing for fingerprint-enabled models in Europe. China's MIIT regulates wireless transmission protocols and SAMR oversees product quality certification under GB standards, shaping which foreign brands achieve market access. Stakeholders must monitor evolving biometric data privacy frameworks as jurisdictions diverge on consent requirements and cross-border data localization mandates.
Market Dynamics
Bluetooth Low Energy transceivers and fingerprint-on-card modules are bifurcating the padlock smart lock market into premium biometric systems and mass-market smartphone-paired units, with semiconductor sensor costs determining margin architecture.
Growth Catalysts
- Smart city infrastructure mandates:Municipal investments in China, Germany, and the United States are accelerating perimeter access control deployments for public utilities and transportation hubs.
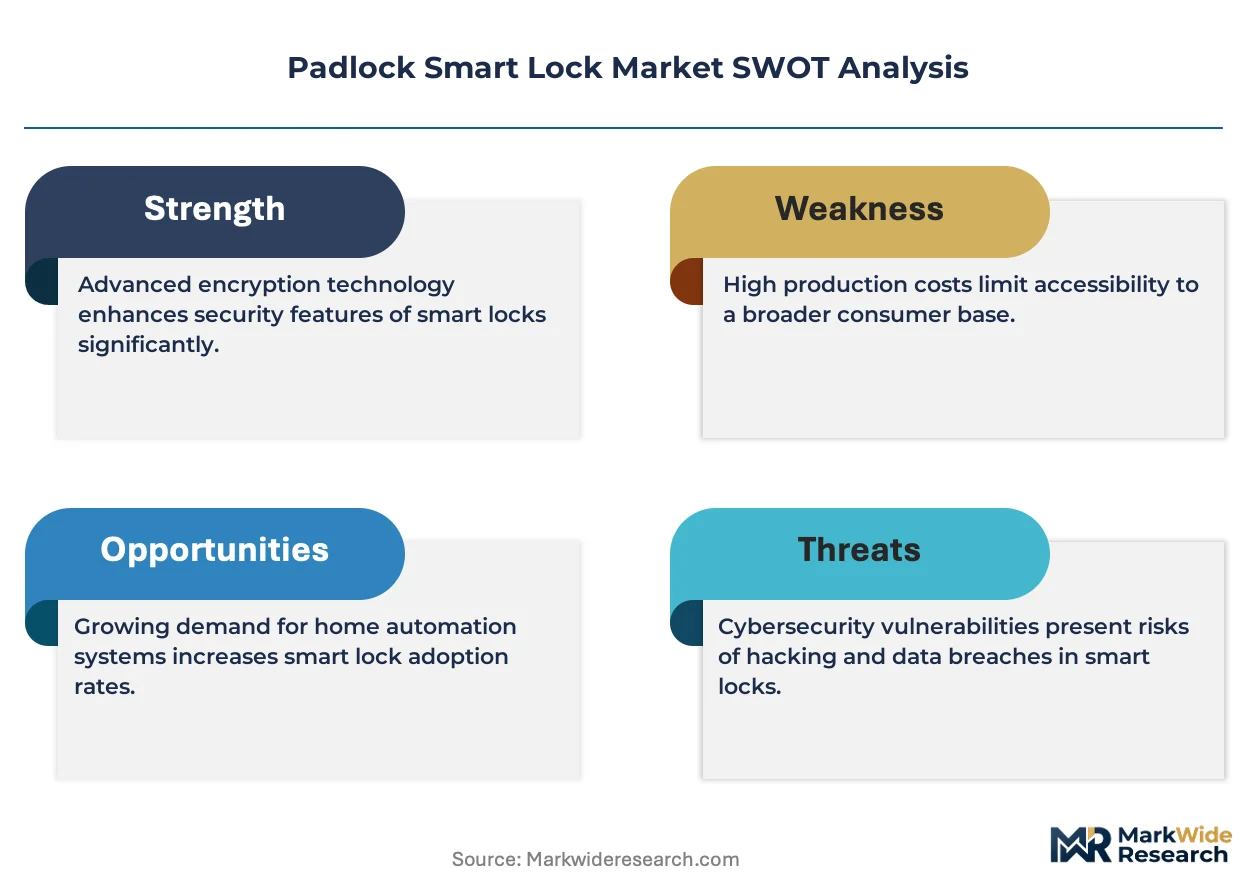
- EU AI Act biometric compliance:European commercial real estate operators are replacing legacy key systems with liveness-detection-enabled fingerprint padlocks to satisfy data processing requirements.
- Remote credential issuance:Cloud-based platforms are capturing recurring revenue through subscription temporary access logs for logistics and shared workspace operators.
Market Restraints
- Capacitive sensor cost volatility:Fingerprint module semiconductor pricing constrains margin expansion for biometric padlock manufacturers.
- Supply concentration in East Asian foundries:BLE chipset fabrication depends on a narrow supplier base concentrated in Taiwan and South Korea.
- Wi-Fi power consumption limitations:Battery-operated padlock form factors cannot sustain continuous cloud connectivity without unacceptable cell replacement cycles.
Strategic Opportunities
- India BIS certification pathway:Domestic manufacturing incentives and quality mark requirements are opening import substitution opportunities for compliant foreign suppliers.
- Outdoor equipment rental vertical:Construction and agricultural machinery sharing platforms require ruggedized biometric padlocks with offline audit trails.
- Convergence of NFC and biometric sensors:Dual-authentication padlocks are penetrating enterprise fleet management where smartphone-plus-fingerprint redundancy reduces credential fraud.
Industry Challenges
- FCC Part 15 certification timelines:Radio frequency emission testing for Wi-Fi and Bluetooth variants delays product launches by four to six months.
- Firmware security engineering scarcity:Liveness-detection algorithm development requires specialized computer vision talent concentrated in limited geographic clusters.
- Legacy mechanical lock integration:Retrofit installations demand custom mounting adapters for non-standard gate and enclosure geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Padlock Smart Lock Market |
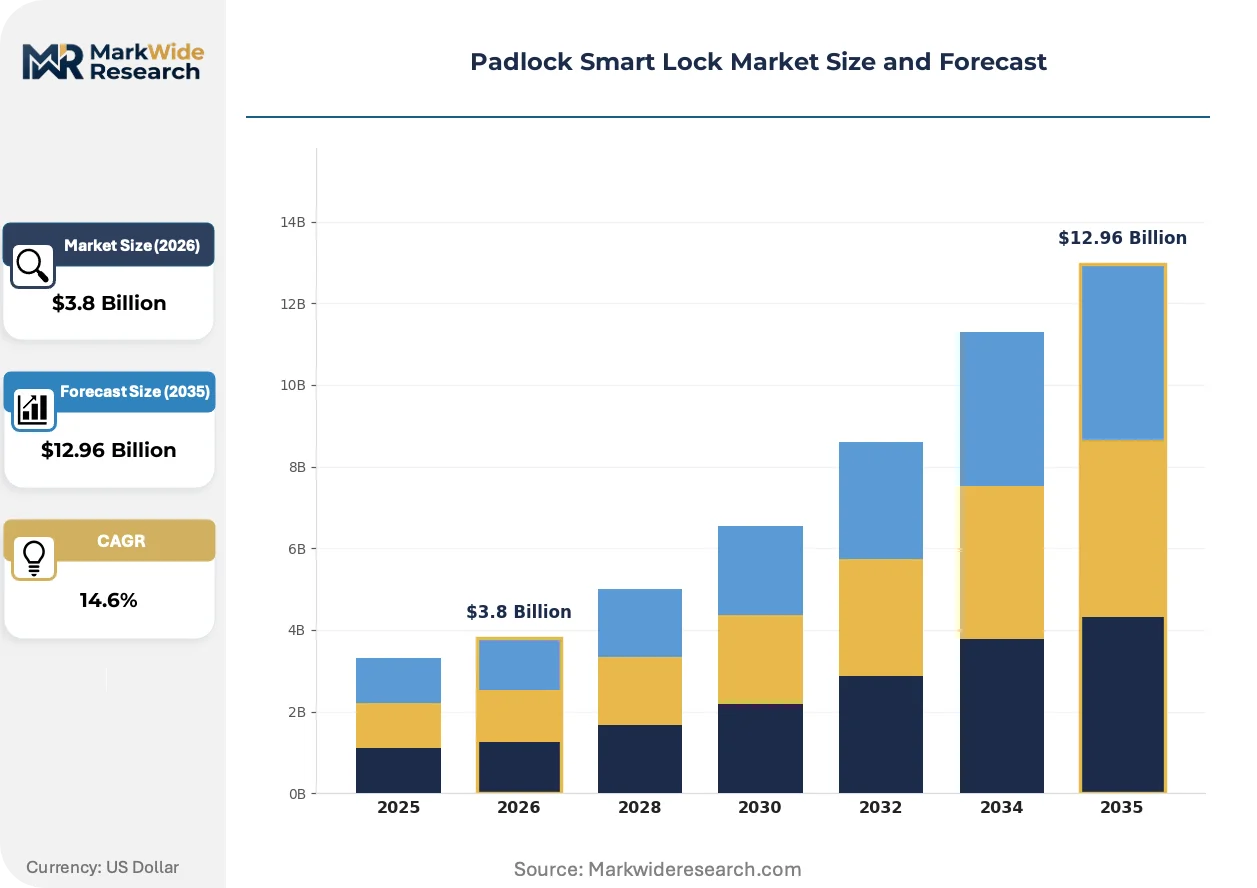
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bluetooth Lock, Keypad Lock, Fingerprint Lock, Wi-Fi Lock Technology: Biometric, Wireless, Mobile App, Cloud-Based End User: Residential, Commercial, Industrial, Institutional Installation: Wall-Mounted, Portable, Smart Home Integration, DIY |
| Companies Covered | ASSA ABLOY, Allegion plc, dormakaba Group, Spectrum Brands Holdings, Inc., Salto Systems S.L., Master Lock Company LLC, Samsung, Dahua Technology Co., Ltd, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Padlock Smart Lock Market Emerging Trajectories
Product architecture is fragmenting around authentication modality, with hardware designers optimizing for either smartphone-dependent or standalone biometric user journeys rather than hybrid compromise designs.
Fingerprint-on-card modules are modularizing padlock smart lock electronics by separating the biometric sensor from the locking mechanism control board. Commercial fleet operators in logistics yards are adopting these units for driver-specific equipment access without smartphone dependency. This architecture is compressing repair costs and enabling field-swappable authentication upgrades without full device replacement.
China's MIIT wireless transmission protocol regulations are tightening Type Approval requirements for BLE frequency hopping algorithms. Foreign manufacturers must redesign radio stacks to satisfy updated GB standards before SAMR quality certification. European and North American suppliers are responding by establishing in-country testing partnerships to accelerate market entry timelines.
Facility managers are consolidating vendor relationships through integrated physical security platforms that unify padlock, door, and gate access logs. Industrial warehousing and cold storage operators are displacing standalone lock purchases with subscription-managed device fleets. Germany's logistics corridor demonstrates the strongest concentration of this procurement consolidation pattern.
Padlock Smart Lock Market Segmentation
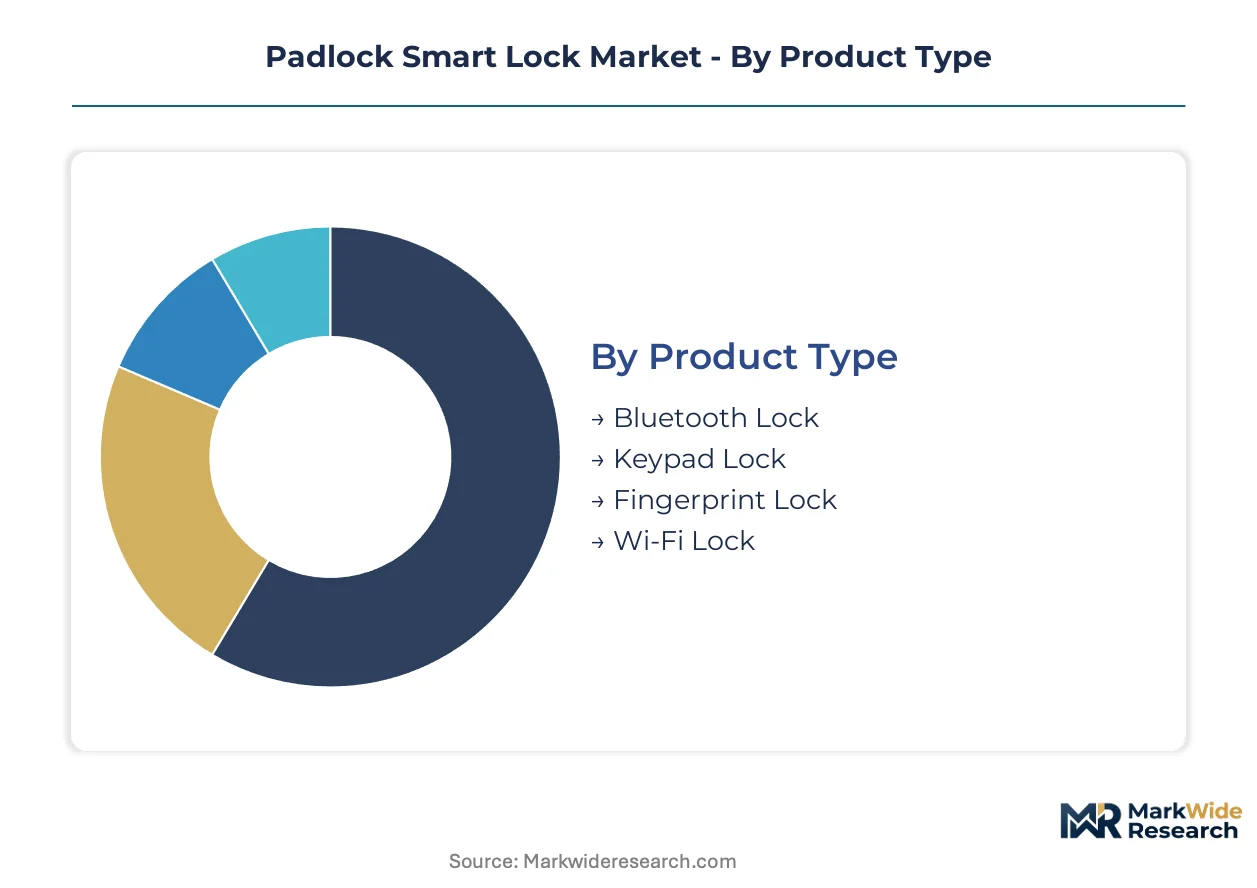
Padlock smart lock segmentation reveals how authentication modality and installation context determine semiconductor requirements, battery architecture, and certification pathways. Product type and technology categories drive the steepest capital allocation differences, while end-user and installation segments shape channel strategy and margin structure.
Product Type:
Fingerprint locks demand the heaviest upfront investment due to capacitive sensor modules and liveness-detection firmware development. Bluetooth locks require minimal semiconductor customization beyond standard BLE transceivers.
- Fingerprint Lock:Capacitive semiconductor sensors paired with spoof-detection algorithms authenticate users through ridge pattern recognition. Commercial real estate operators in Germany are deploying these for perimeter access control to satisfy EU AI Act biometric compliance requirements. Liveness-detection firmware development consumes the largest R&D allocation across all product types.
- Bluetooth Lock:BLE transceivers enable smartphone-paired authentication without dedicated biometric hardware. Residential DIY channels in the United States concentrate demand where smartphone pairing replaces mechanical key management. Semiconductor costs remain lowest here, enabling mass-market pricing.
- Keypad Lock:Physical PIN entry through capacitive touch matrices offers standalone operation without smartphone dependency. Construction equipment rental yards favor these for driver access in remote locations lacking cellular coverage.
- Wi-Fi Lock:Continuous cloud connectivity modules enable remote management and real-time audit logging. Battery constraints limit deployment to applications with accessible power or acceptable cell replacement cycles.
Most installed capacity flows through Bluetooth Lock. Expansion is steepest in Fingerprint Lock.
Technology:
Biometric systems command premium pricing through specialized sensor procurement, while cloud platforms capture recurring revenue through subscription access management.
- Biometric:Fingerprint and emerging iris recognition modules integrate capacitive or optical sensors with onboard template storage. Logistics fleet operators in China are adopting these for driver-specific equipment access without credential sharing vulnerabilities.
- Wireless:BLE, Zigbee, and proprietary RF protocols enable device-to-device and device-to-gateway communication. Frequency hopping algorithm redesigns for MIIT Type Approval in China are extending certification timelines for foreign suppliers.
- Mobile App:Smartphone applications handle credential issuance, temporary access sharing, and audit log visualization. Shared workspace operators rely on these for visitor management without physical key handoff.
- Cloud-Based:Centralized platforms manage device fleets, firmware updates, and subscription billing. Industrial warehousing operators in Germany are consolidating vendor relationships through these integrated physical security platforms.
Biometric technology captures the highest revenue per unit. Cloud-Based platforms are gaining share fastest through recurring revenue attachment.
End User:
Industrial deployments require ruggedized enclosures and offline audit trails, while residential demand prioritizes smartphone integration and retail availability.
- Commercial:Office buildings, retail storefronts, and hospitality properties demand centralized access management with temporary credential issuance. Property management platforms in the United States are displacing standalone lock purchases with subscription-managed device fleets.
- Residential:Homeowners and renters prioritize DIY installation and smartphone ecosystem compatibility. Retail distribution density determines competitive positioning in North American mass-market channels.
- Industrial:Manufacturing facilities, logistics yards, and utility infrastructure require IP-rated enclosures and extreme temperature tolerance. Cold storage operators specify these for freezer compartment access control.
- Institutional:Schools, healthcare facilities, and government buildings mandate compliance with sector-specific security protocols. EU AI Act biometric processing requirements are accelerating fingerprint padlock adoption in European educational institutions.
Commercial end users represent the largest installed base. Industrial applications are expanding most quickly through equipment rental platform demand.
Installation:
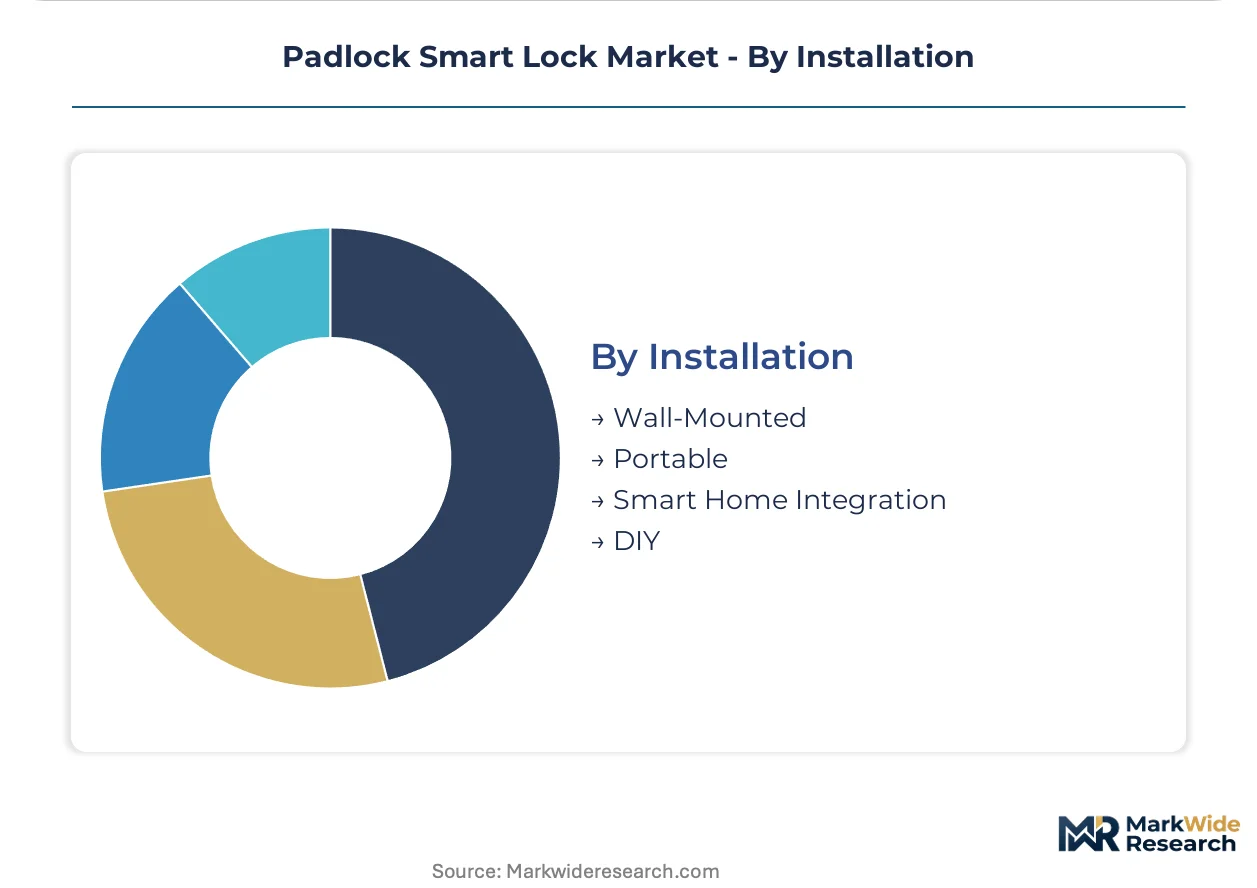
Portable form factors dominate unit volumes, while smart home integration requires protocol compatibility investments that raise development costs.
- Portable:Self-contained battery-powered units secure gates, storage units, and equipment without fixed mounting. Master Lock Company LLC anchors this segment through North American retail distribution density.
- DIY:Consumer-installed products prioritize tool-free mounting and smartphone-guided setup instructions. Big-box retail channels in the United States concentrate demand for these entry-level configurations.
- Wall-Mounted:Fixed installations on gates, doors, and enclosures require weatherproofing and tamper-resistant hardware. Commercial perimeter access control in China specifies these for public utility infrastructure.
- Smart Home Integration:Protocol compatibility with Alexa, Google Home, and Apple HomeKit enables voice control and automation triggers. Samsung competes here by extending its smartphone authentication stack into physical security hardware.
Portable installation accounts for the highest unit volumes. Smart Home Integration is climbing the fastest as ecosystem vendors bundle physical security into platform subscriptions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Embedded systems engineers and semiconductor firmware specialists cluster in Shenzhen, Munich, and Austin, anchoring design and certification workflows for biometric padlock platforms.
China
MIIT Type Approval requirements for BLE frequency hopping algorithms are extending certification timelines for foreign manufacturers seeking SAMR quality marks under updated GB standards. Shenzhen's electronics corridor hosts the densest concentration of fingerprint sensor module integrators serving logistics fleet operators.
Germany
EU AI Act biometric compliance mandates are accelerating replacement of mechanical perimeter locks with liveness-detection-enabled units in commercial real estate. Berlin and Hamburg logistics hubs demonstrate the strongest procurement consolidation toward subscription-managed device fleets.
United States
FCC Part 15 certification timelines delay Wi-Fi and Bluetooth variant launches by four to six months, constraining product refresh cycles. Austin's embedded security engineering cluster supplies firmware talent for spoof-detection algorithm development.
India
BIS certification pathways and domestic manufacturing incentives under PLI schemes are opening import substitution opportunities for compliant foreign suppliers. Maharashtra's industrial corridor is absorbing initial deployments for construction equipment rental platforms.
South Korea
BLE chipset fabrication concentration in Seoul-Incheon foundries creates supply vulnerability for battery-operated padlock manufacturers. MFDS-equivalent quality frameworks for biometric data processing are shaping enterprise adoption patterns in logistics yards.
Padlock Smart Lock Market Vendor Landscape
Top-tier vendors anchor European commercial channels through door hardware heritage, while Asian electronics conglomerates and North American portable security specialists occupy differentiated tiers. The vendor base stratifies across three strategic archetypes: diversified industrial conglomerates with mobile ecosystem integration capabilities, heritage lock manufacturers leveraging retail distribution density, and pure-play access control specialists. Competitive positioning hardens through M&A activity consolidating cloud platform capabilities and strategic partnerships bridging semiconductor supply gaps.
Among diversified industrial conglomerates, Samsung exemplifies mobile-first ecosystem extension into physical security hardware. ASSA ABLOY and Master Lock Company LLC occupy positions on opposite ends of the channel spectrum—heritage European commercial infrastructure versus North American retail portable density. These three anchors represent the dominant competitive vectors: smartphone authentication stack integration, legacy hardware distribution leverage, and vertical specialization in biometric sensor integration.
| Leading Market Players |
|---|
| ASSA ABLOY |
| Allegion plc |
| dormakaba Group |
| Spectrum Brands Holdings, Inc. |
| Salto Systems S.L. |
| Master Lock Company LLC |
| Samsung |
| Dahua Technology Co., Ltd |
| Honeywell International Inc. |
| Others |
Supply Flow & Price Mechanics
Capacitive fingerprint sensor module pricing cascades through three distinct tiers, with semiconductor cost volatility compressing margins on biometric units while BLE chipset commoditization sustains mass-market affordability.
Pricing Analysis
Bundled subscription services versus unbundled hardware-only sales split the market into recurring-revenue platforms and transactional retail channels. Three-tier pricing structure across premium biometric, standard Bluetooth, and economy keypad levels reflects certification grade and liveness-detection firmware investment. Pricing pressure stems from Taiwan foundry capacity constraints on fingerprint sensors. Residential DIY buyers exhibit highest price sensitivity, while German logistics operators accept premium positioning for EU AI Act compliance.
Supply Chain Analysis
Trans-Pacific freight cost fluctuations ripple through Shenzhen assembly corridors before landing in North American retail distribution. Semiconductor fabrication concentrates in Taiwan, South Korea, and mainland China. Raw material dependencies span capacitive sensor wafers, BLE radio chipsets, and lithium-polymer cells. Single-source vulnerability on fingerprint-on-card modules from Seoul-Incheon suppliers creates chokepoint exposure. Distribution runs through electronics wholesale channels in Shenzhen, direct-to-retail in the United States, and systems integrator networks in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EU AI Act biometric processing mandates forcing hardware refresh cycles across European commercial real estate portfolios.
For Market Incumbents: Deploy firmware security engineering teams to harden liveness-detection algorithms against emerging spoofing techniques from low-cost Asian entrants. Deepen backward integration into capacitive sensor supply through captive partnerships with Taiwan foundries. Channel control through property management platform APIs defends against cloud-platform disintermediation. For New Entrants and Emerging Players: BIS certification pathways in India open a window for import substitution plays targeting Maharashtra construction equipment rental platforms. White-space concentration sits with ruggedized biometric padlocks for cold storage operators lacking smartphone coverage. Go-to-market leverage runs through domestic manufacturing incentives under PLI schemes rather than direct import competition. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play access control specialists possessing cloud-platform subscription revenue and MIIT Type Approval expertise for China entry. Long-term viability favors vendors bridging semiconductor supply gaps through strategic foundry relationships. Watch for FCC Part 15 certification timeline compression as signal of regulatory arbitrage capability.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Security Hardening | Liveness-detection algorithm investment defends biometric padlock premium positioning against spoofing threats. |
| Foundry Partnership Lock-in | Captive capacitive sensor supply from Taiwan secures margin architecture for fingerprint-enabled units. |
| Platform API Integration | Property management software connectivity captures subscription revenue from US commercial real estate operators. |
| MIIT Type Approval Acceleration | In-country testing partnerships compress China market entry timelines for foreign BLE padlock suppliers. |
| India PLI Manufacturing Setup | Domestic production qualification unlocks BIS certification for construction equipment rental vertical penetration. |
Methodological Framework
Bottom-up logistics fleet operator modeling reconciled against top-down semiconductor shipment tracking forms the analytical core of this study. Primary interviews with embedded systems engineers, commercial property managers, cold storage operators, and BLE chipset procurement leads combined with secondary validation from FCC equipment authorization databases, MIIT Type Approval registries, EU AI Act implementation guidance, and SAMR quality certification lists. Triangulation across supply-side foundry utilization data and demand-side access control procurement patterns ensures coverage integrity.
Historical trendline analysis on authentication modality adoption rates informed projection frameworks across the analysis window. Segmentation dimensions span product type, technology stack, end-use vertical, and installation context, with regional regulatory cluster as an additional modeled variable. CAGRs derive from fitted growth curves on biometric sensor cost decline trajectories and BLE penetration saturation patterns. Forecast inputs include cloud-platform subscription attach rates and smart city infrastructure procurement pipeline visibility.
Revisions become necessary when semiconductor foundry capacity allocations shift, biometric data privacy frameworks diverge across jurisdictions, or wireless transmission protocol regulations tighten unexpectedly. Forecasts reflect documented assumptions on sensor cost decline curves and certification timeline stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Japan Access Control Market
Access Control Systems
Smart Entry System Market
Access Control Systems
North America Keyless Vehicle Access Control System Market
Access Control Systems
North America Safety Connection Devices Market
Access Control Systems
North America Pin-Based Access Control Market
Access Control Systems
Border Security System Market
Access Control Systems
Global Industrial Security Systems Market
Access Control Systems
Global Fingerprint Access Control Systems Market
Access Control Systems
Latin America Pin-Based Access Control Market
Access Control Systems
Global Keyless Vehicle Access Control Systems Market
Access Control Systems
Mechanical Locks Market
Access Control Systems
United Kingdom Access Control Market
Access Control Systems
United States Smart Lock Market
Access Control Systems
US Restricted Access Barrier System Market
Access Control Systems
Smart Locker Locks Market
Access Control Systems
Facial Recognition Access Control Solution Market