
 North America Access Control Software Market | 2026-2036
North America Access Control Software Market Size, Share, and Industry Trends Forecast 2026-2036
North America Access Control Software Market Insights
System integrator channels across the United States and Canada are reconfiguring around subscription-based credential management. Johnson Controls leverages its building automation footprint to bundle access control with HVAC and fire safety contracts. Genetec Inc. anchors its position through unified security platforms that merge video management with access analytics. Honeywell International Inc. competes by sustaining deep relationships with federal contracting officers through FedRAMP-authorized cloud deployments.
North America access control software comprises applications that authenticate identities, manage credential lifecycles, and enforce physical entry permissions across secured perimeters, typically operating through encrypted communications protocols with millisecond-level door-release latency. The technology serves commercial, institutional, and critical infrastructure operators seeking to replace mechanical keys with auditable, remotely manageable electronic systems. Cloud-based solutions represent the fastest-expanding deployment mode as multi-tenant architectures reduce capital burdens for mid-sized organizations. Biometric systems command premium pricing due to liveness detection requirements and template encryption standards, while card-based systems retain volume leadership in retrofit-heavy government facilities. Mobile access segments are capturing share fastest among technology and financial services campuses prioritizing smartphone-native user experiences.
The Federal Risk and Authorization Management Program shapes cloud deployment decisions by mandating standardized security assessments for federal agency adoption. State biometric privacy statutes, notably Illinois BIPA and emerging California analogues, impose consent and retention rules that elevate software compliance costs. The Payment Card Industry Data Security Standard indirectly pressures commercial building operators to harden physical access around cardholder data environments. Stakeholders must monitor whether proposed federal identity verification mandates will force interoperability standards that reshape vendor competitive moats.
Market Dynamics
Enterprise campuses across the United States and Canada are dismantling legacy card reader infrastructure in favor of mobile credential platforms that merge physical access with identity lifecycle management. This hardware-to-software transition compresses capital deployment timelines while elevating cybersecurity compliance requirements across critical infrastructure verticals.
Growth Catalysts
- Biometric Privacy Statutes:Illinois BIPA and emerging California analogues mandate consent frameworks and retention limits that force facility operators toward auditable software solutions with encrypted template storage.
- Data Center Construction:The Texas Triangle metro corridor is outpacing national facility build rates, driving concentrated procurement of multi-tenant access management systems for hyperscale and colocation campuses.
- FedRAMP Authorization:Standardized cloud security assessments for federal agency adoption accelerate procurement cycles among system integrators serving government and defense end-uses.
Market Restraints
- Input Cost Volatility:Semiconductor shortages and specialty sensor pricing instability inflate hardware component costs for biometric enrollment terminals and edge controllers.
- Supply Concentration Risk:Cloud infrastructure for access management concentrates among three hyperscale providers, creating single-point vulnerability for multi-tenant deployments.
- Interoperability Friction:Proprietary credential formats and non-standard API architectures lock facilities into vendor ecosystems that resist integration with third-party security stacks.
Strategic Opportunities
- Healthcare Vertical Expansion:Hospital systems in Ontario and Quebec are underpenetrated relative to US enterprise adoption, presenting whitespace for HIPAA-aligned physical access platforms.
- Zero Trust Convergence:Integration between physical access software and IT identity providers collapses the boundary between building entry and network authentication, opening unified security procurement.
- Subscription Channel Migration:Value-added resellers are pivoting from perpetual license sales to recurring credential management services, capturing lifetime customer value.
Industry Challenges
- Cybersecurity Skill Scarcity:Facility security teams lack personnel trained in encrypted protocol management and liveness detection calibration for biometric deployments.
- Legacy System Integration:Decades-old Wiegand wiring and proprietary controller firmware resist seamless migration to IP-native architectures without full infrastructure replacement.
- Compliance Timeline Compression:State-level biometric law enactment windows provide insufficient runway for software vendors to reengineer consent workflows and data retention engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Access Control Software Market |
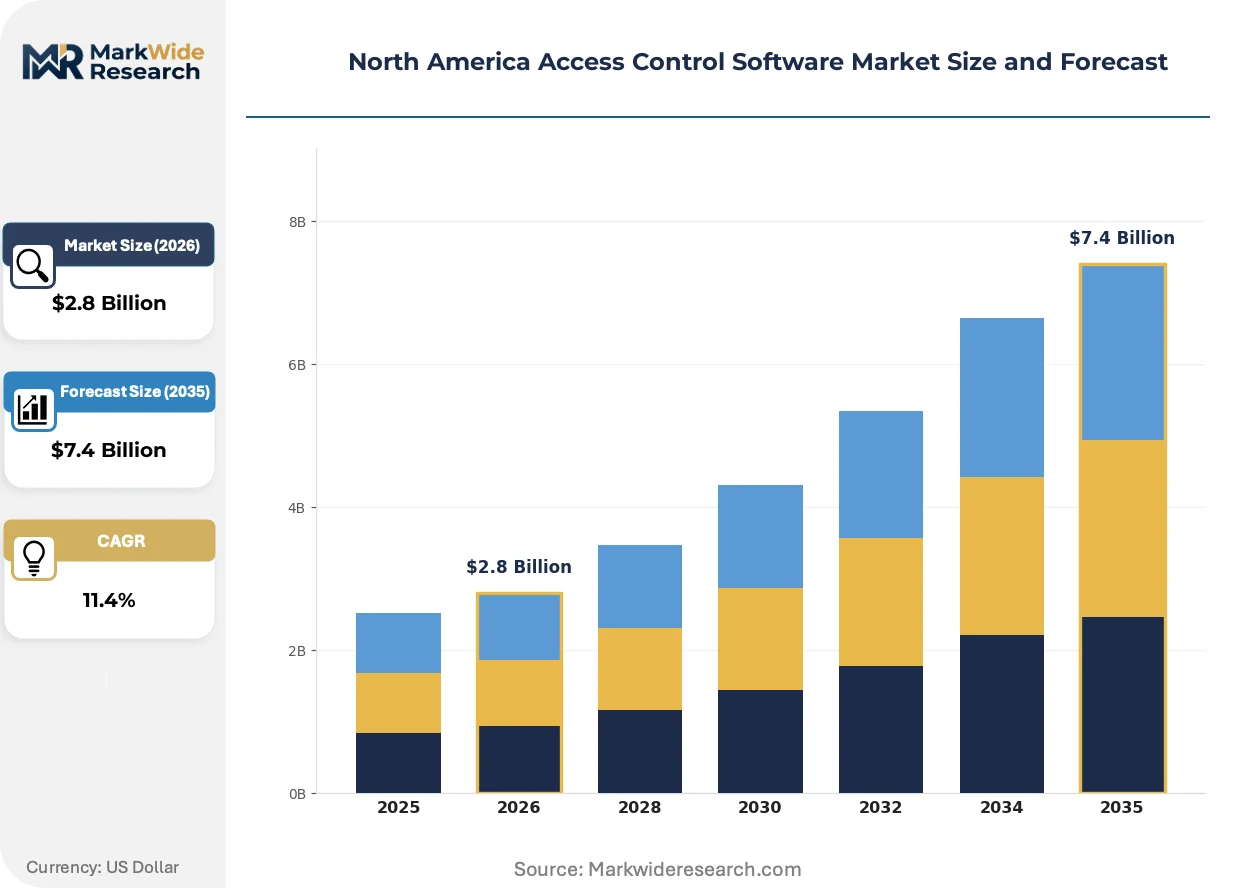
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biometric Systems, Card-Based Systems, Mobile Access, Cloud-Based Solutions Deployment: On-Premises, Cloud, Hybrid, Managed Services End User: Commercial Buildings, Government Facilities, Educational Institutions, Residential Areas Integration Level: Standalone Systems, Integrated Systems, Custom Solutions, Others |
| Companies Covered | Bosch Security and Safety Systems, Johnson Controls, Genetec Inc., Honeywell International Inc., Axis Communications AB, Securitas Technology, Allegion plc, ASSA ABLOY, dormakaba, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Access Control Software Market Trends and Innovations
Mobile credential platforms are collapsing the distinction between physical access credentials and enterprise identity management, forcing a rearchitecture of how facilities authenticate and authorize entry. Three convergent developments are compressing deployment timelines and reshaping competitive positioning.
Bluetooth Low Energy and ultra-wideband positioning is collapsing the functional separation between smartphone-based credentials and traditional proximity cards. Financial services campuses in Manhattan and Chicago are piloting gesture-free entry systems that eliminate tap-and-hold friction. This convergence is collapsing hardware refresh cycles from seven-year replacement schedules to continuous software updates.
NIST cybersecurity frameworks and state biometric privacy statutes are elevating software compliance costs while accelerating procurement among risk-averse institutional buyers. The Federal Risk and Authorization Management Program mandates standardized security assessments that filter vendor eligibility for federal contracts. Critical infrastructure operators in energy and data center verticals are responding by demanding FedRAMP-authorized cloud deployments as table stakes.
System integrators across the United States are unbundling hardware installation from ongoing credential lifecycle management, creating recurring revenue streams that displace one-time license transactions. Mid-sized commercial building operators in secondary metros are adopting subscription access management to avoid capital deployment. This pattern is most visible in Austin, Denver, and Toronto technology corridors where facility management outsourcing concentrates.
North America Access Control Software Market Segmentation
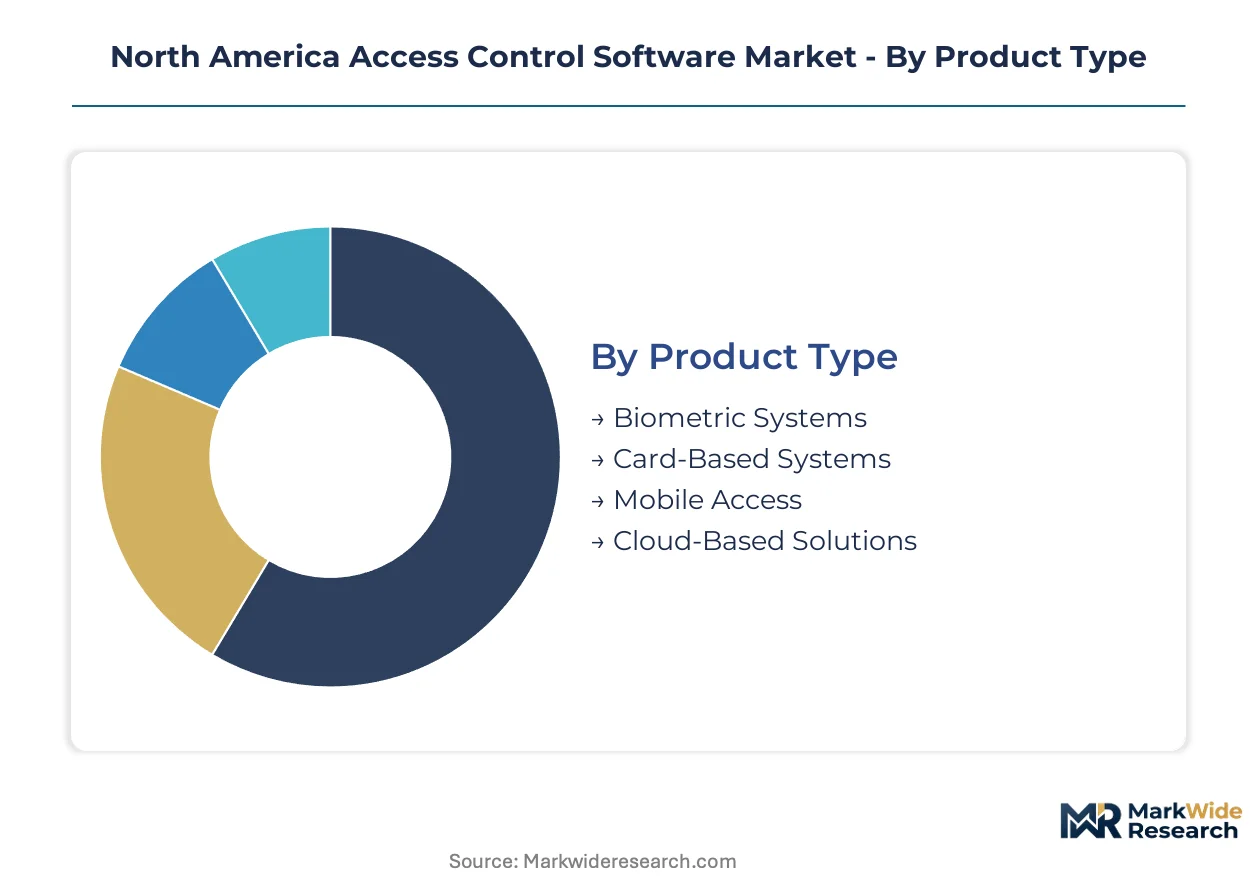
Segmentation in North America access control software reveals diverging replacement cycles across credential technologies. Product refresh timelines stretch from continuous software updates for cloud platforms to decade-long hardware lifecycles for embedded biometric terminals.
Product Type:
Replacement velocity varies dramatically across credential technologies, with smartphone-native platforms enabling monthly feature releases while biometric enrollment hardware locks facilities into seven-year depreciation schedules.
- Biometric Systems:Liveness detection algorithms and encrypted template storage distinguish enterprise-grade deployments. Demand concentrates in Texas Triangle data centers where NIST cybersecurity frameworks mandate multi-factor authentication for critical infrastructure perimeters.
- Mobile Access:Bluetooth Low Energy and ultra-wideband positioning enable gesture-free entry without tap-and-hold friction. Financial services campuses in Manhattan and Chicago are piloting these platforms to collapse the boundary between physical credentials and enterprise identity management.
- Card-Based Systems:Wiegand and proximity formats retain dominance in government retrofit projects where legacy wiring resists full infrastructure replacement.
- Cloud-Based Solutions:Multi-tenant architectures reduce capital burdens for mid-sized commercial operators in secondary metros.
Card-based systems anchor the volume base while mobile access gains share at the steepest rate.
Deployment:
Capital commitment intensity separates deployment modes, with subscription models shifting balance sheet treatment from capital expenditure to operating expense.
- Cloud:FedRAMP-authorized architectures accelerate procurement cycles among federal contracting officers. System integrators bundle these deployments with ongoing credential lifecycle management to capture recurring revenue streams.
- Managed Services:Third-party operation of enrollment, provisioning, and deactivation workflows appeals to facility management outsourcing concentrations in Austin, Denver, and Toronto technology corridors.
- On-Premises:Air-gapped installations persist in defense and intelligence facilities where data sovereignty requirements block external network connectivity.
- Hybrid:Edge controllers with cloud management planes bridge compliance-sensitive organizations seeking local authentication with centralized audit capabilities.
On-premises deployments retain the installed base while managed services climb the fastest.
End User:
Procurement sophistication and compliance burden intensity diverge sharply across facility types, with critical infrastructure operators demanding FedRAMP authorization as table stakes.
- Government Facilities:Federal Risk and Authorization Management Program mandates filter vendor eligibility for national security and civilian agency contracts. Illinois BIPA and emerging California biometric privacy statutes impose consent frameworks that elevate software compliance costs.
- Commercial Buildings:PCI DSS requirements indirectly pressure operators to harden physical access around cardholder data environments. Mid-sized organizations in secondary metros favor subscription models to avoid capital deployment.
- Educational Institutions:Campus-wide credential provisioning for transient student populations favors automated lifecycle management with semester-aligned activation and deactivation workflows.
- Residential Areas:Multi-tenant property managers prioritize smartphone-native experiences for amenity access and visitor management.
Commercial buildings command the revenue base while government facilities expand most quickly.
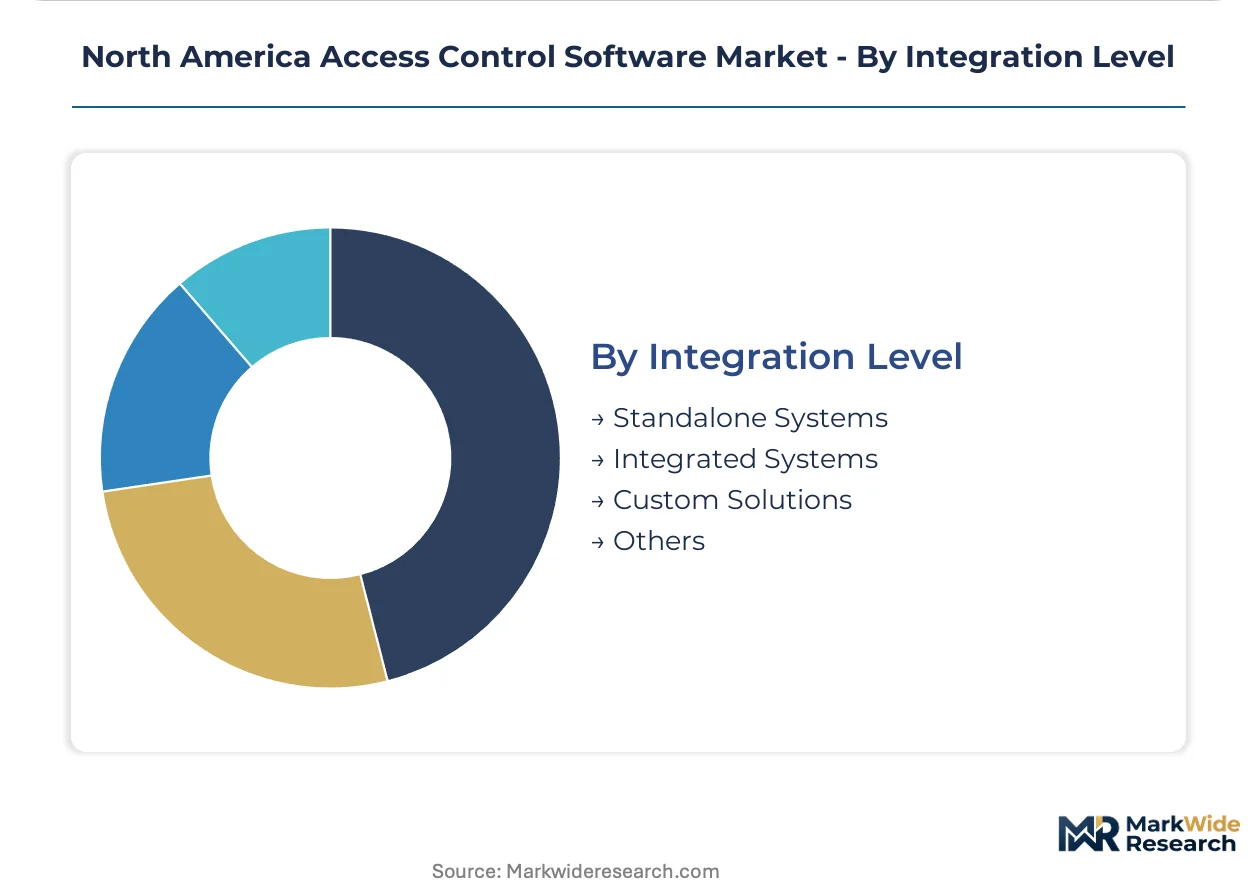
Integration Level:
System architecture choices determine interoperability with broader security stacks and IT identity providers, with unified platforms commanding premium positioning.
- Integrated Systems:Video management convergence with access analytics enables correlation between credential events and surveillance footage. Genetec anchors positioning through unified security platforms serving enterprise campuses.
- Custom Solutions:Proprietary API architectures and non-standard credential formats lock facilities into vendor ecosystems that resist third-party integration without middleware development.
- Standalone Systems:Single-purpose controllers persist in small commercial deployments where capital constraints block full security stack replacement.
- Others:Emerging zero-trust convergence models collapse the boundary between building entry and network authentication through IT identity provider federation.
Standalone systems retain volume leadership while integrated systems capture the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while Canadian procurement cycles compress under provincial privacy mandates. The United States commands premium positioning through federal compliance requirements that filter vendor eligibility.
United States
Texas Triangle data center construction and Manhattan financial services campuses drive concentrated procurement of mobile credential platforms. FedRAMP authorization mandates from federal contracting officers accelerate cloud deployment decisions. Austin and Denver technology corridors witness facility management outsourcing that favors subscription access management over capital-intensive hardware.
Canada
Hospital systems in Ontario and Quebec present underpenetrated whitespace for HIPAA-aligned physical access platforms. Provincial privacy commissioners enforce consent frameworks that elevate software compliance costs relative to US benchmarks. Toronto's technology corridor concentrates multi-tenant property managers prioritizing smartphone-native amenity access.
Mexico
Manufacturing campuses in Nuevo León and the Bajío Region demand audit-ready electronic systems as foreign direct investment intensifies. The national data protection authority imposes retention rules that push facilities toward encrypted template storage. Mexico City metro corridor leads commercial building modernization with PCI DSS-aligned physical access hardening.
North America Access Control Software Market Competitive Landscape
Building automation conglomerates and pure-play security software developers split the market into distinct competitive spheres. The vendor base organizes around three strategic archetypes: diversified industrial technology groups, specialized physical security platforms, and subscription-native credential management services. Consolidation pressure intensifies as system integrators pivot from perpetual licenses to recurring revenue streams. Strategic partnerships between cloud infrastructure providers and hardware manufacturers reshape distribution economics.
Within the diversified technology tier, Johnson Controls leverages building automation footprints while Honeywell International Inc. sustains federal contracting relationships through FedRAMP-authorized deployments. Genetec Inc. occupies a position exemplifying unified security platform convergence. These three anchors represent distinct pathways for collapsing the boundary between physical access and enterprise identity management.
| Leading Market Players |
|---|
| Bosch Security and Safety Systems |
| Johnson Controls |
| Genetec Inc. |
| Honeywell International Inc. |
| Axis Communications AB |
| Securitas Technology |
| Allegion plc |
| ASSA ABLOY |
| dormakaba |
| Others |
Pricing and Supply Chain Analysis
The Texas Triangle metro corridor anchors North American manufacturing capacity for biometric enrollment terminals and edge controllers, with local assembly operations feeding hyperscale data center construction across Dallas-Fort Worth, Houston, and Austin. This geographic concentration of production capacity amplifies pricing power for domestic integrators serving federal compliance mandates while exposing downstream buyers to semiconductor input volatility.
Pricing Analysis
Configured-to-order deployments command 40-60% premiums over standard SaaS tiers due to FedRAMP authorization requirements and custom API development for legacy system bridges. Subscription pricing stratifies across premium, standard, and economy tiers based on credential volume tiers and liveness detection algorithm sophistication. Cost compression in the standard tier intensifies as mid-sized commercial operators in secondary metros migrate from perpetual licenses to recurring models. Government facilities exhibit lowest price sensitivity due to compliance-driven procurement timelines, while multi-tenant property managers in residential verticals negotiate aggressively on per-door economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for biometric sensor modules and specialty semiconductors used in liveness detection hardware. Component sourcing draws from Taiwan for advanced image sensors, South Korea for memory modules, and domestic foundries for encryption chip fabrication. Single-source vulnerability concentrates in BLE and UWB positioning chipsets where Qualcomm and Apple silicon architectures dominate smartphone credential ecosystems. Distribution runs through system integrator channels that bundle hardware installation with ongoing credential lifecycle management, displacing direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America access control software market sits in early-cycle recovery as enterprise campuses accelerate hardware-to-software transitions and federal compliance mandates compress procurement timelines. Data center construction velocity in the Texas Triangle and Manhattan financial services pilot programs signal sustained replacement demand through the projection horizon.
For Market Incumbents: Pre-empt cloud-native entrants by acquiring subscription-native credential management platforms before they achieve critical mass in the Austin and Denver technology corridors. Fortify FedRAMP authorization moats through accelerated re-certification cycles that filter vendor eligibility for defense and intelligence contracts. Deepen vertical integration into liveness detection algorithm development to reduce dependency on third-party biometric SDK providers facing Illinois BIPA compliance re-engineering costs. For New Entrants and Emerging Players: Establish a beachhead in Canadian hospital systems across Ontario and Quebec where HIPAA-aligned physical access platforms remain underpenetrated relative to US enterprise adoption. Target multi-tenant property managers in Toronto's technology corridor with smartphone-native amenity access solutions that bypass legacy Wiegand infrastructure entirely. Lead with zero-trust convergence positioning that collapses physical entry authentication with IT identity provider federation, capturing procurement budgets from CISOs rather than facilities managers. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-utility play because biometric privacy statutes and NIST cybersecurity frameworks create durable procurement tailwinds independent of macroeconomic cyclicality. Acquisition targets should display FedRAMP authorization progress, recurring revenue concentration above 60%, and vertical penetration in data center or healthcare verticals. The signal to watch is state-level biometric law enactment velocity in California and New York, which would force vendor consolidation as compliance engineering costs outrun mid-cap balance sheets.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Acceleration | Filters vendor eligibility for federal agency contracts through standardized cloud security assessments. |
| Zero-Trust Platform Integration | Collapses physical access and network authentication boundaries through IT identity provider federation. |
| Biometric SDK Acquisition | Captures liveness detection IP to reduce Illinois BIPA compliance re-engineering dependency on third parties. |
| Canadian Healthcare Vertical Expansion | Addresses underpenetrated whitespace in Ontario and Quebec hospital systems relative to US adoption. |
| Subscription Channel Migration | Pivots system integrators from perpetual licenses to recurring credential lifecycle management revenue. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, and state legislative databases. Primary interviews engaged CTOs at financial services campuses, federal contracting officers, system integrator channel partners, and facility management outsourcing executives across Austin, Denver, and Toronto corridors. Secondary validation drew from NIST cybersecurity framework documentation, FedRAMP authorization manifests, and Illinois BIPA enforcement records. Bottom-up credential volume modeling triangulated against top-down IT security spending allocation surveys.
Forecast inputs span deployment model migration curves, vertical adoption saturation thresholds, and compliance timeline compression effects across the projection horizon. Segmentation dimensions modeled include credential technology type, cloud architecture authorization status, end-user vertical, integration complexity tier, and regional regulatory cluster. CAGRs derive from logistic diffusion curves fitted to mobile credential adoption patterns and hardware replacement cycle compression observed in enterprise campus deployments. Industry-specific inputs incorporate data center construction permits and state biometric privacy statute enactment pipelines.
Stress conditions across semiconductor availability, FedRAMP authorization delays, and state-level compliance timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding enterprise campus refresh cycles and federal procurement acceleration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Modular Biometric Access Control Terminals Market
Access Control Systems
Australia Industrial Barrier Systems Market
Access Control Systems
Latin America Card-Based Access Control Market
Access Control Systems
North America Pin-Based Access Control Market
Access Control Systems
Japan Access Control Market
Access Control Systems
Digital Security Control Market
Access Control Systems
Italy Access Control Market
Access Control Systems
Mobile Turnstile Market
Access Control Systems
South Korea Access Control Market
Access Control Systems
Border Security System Market
Access Control Systems
Asia-Pacific Proximity Access Control Market
Access Control Systems
North America Home Security System Market
Access Control Systems
GCC Home Security Systems Market
Access Control Systems
Access Control and Authentication Market
Access Control Systems
Acousto-Magnetic (AM) Security Systems Market
Access Control Systems
Network Access Control Market