
 North America Process Safety Services Market | 2026-2036
North America Process Safety Services Market Size, Share, and Industry Trends Forecast 2026-2036
North America Process Safety Services Market Analytics
Refinery investment in digital safety layers is consolidating procurement toward full-service providers. Honeywell International Inc. leverages its distributed control systems footprint to bundle process safety consulting with automation retrofits. Emerson Electric Co. sustains deep relationships with Gulf Coast petrochemical complexes through its safety instrumented systems expertise. Bureau Veritas competes aggressively on third-party auditing credentials across Canadian energy corridors.
Process Safety Services encompass engineering consulting, hazard analysis, compliance verification, and operational risk management designed to prevent catastrophic releases of toxic, reactive, flammable, or explosive chemicals in industrial facilities. These services typically integrate quantitative risk assessment methodologies, layers of protection analysis, and safety integrity level calculations to establish defensible safeguards for high-hazard processes. Consulting and auditing services command the largest revenue share due to recurring regulatory inspection cycles, while safety management systems integration represents the fastest-expanding category as operators seek unified platforms spanning hazard identification through incident investigation. Training services occupy a mature position with stable renewal rates tied to OSHA PSM refresher mandates.
OSHA Process Safety Management standards and EPA Risk Management Program requirements create baseline demand for compliance auditing across US chemical and refining facilities. Health Canada and provincial regulators in Alberta enforce parallel frameworks through the Canadian Environmental Protection Act and occupational health statutes, shaping cross-border service standardization. DNV GL AS anchors offshore safety certification in the Gulf of Mexico, while ABS Consulting dominates maritime and midstream risk quantification. Stakeholders must weigh the trade-off between specialized boutique analysts and integrated automation vendors as facility owners consolidate vendor relationships.
Market Dynamics
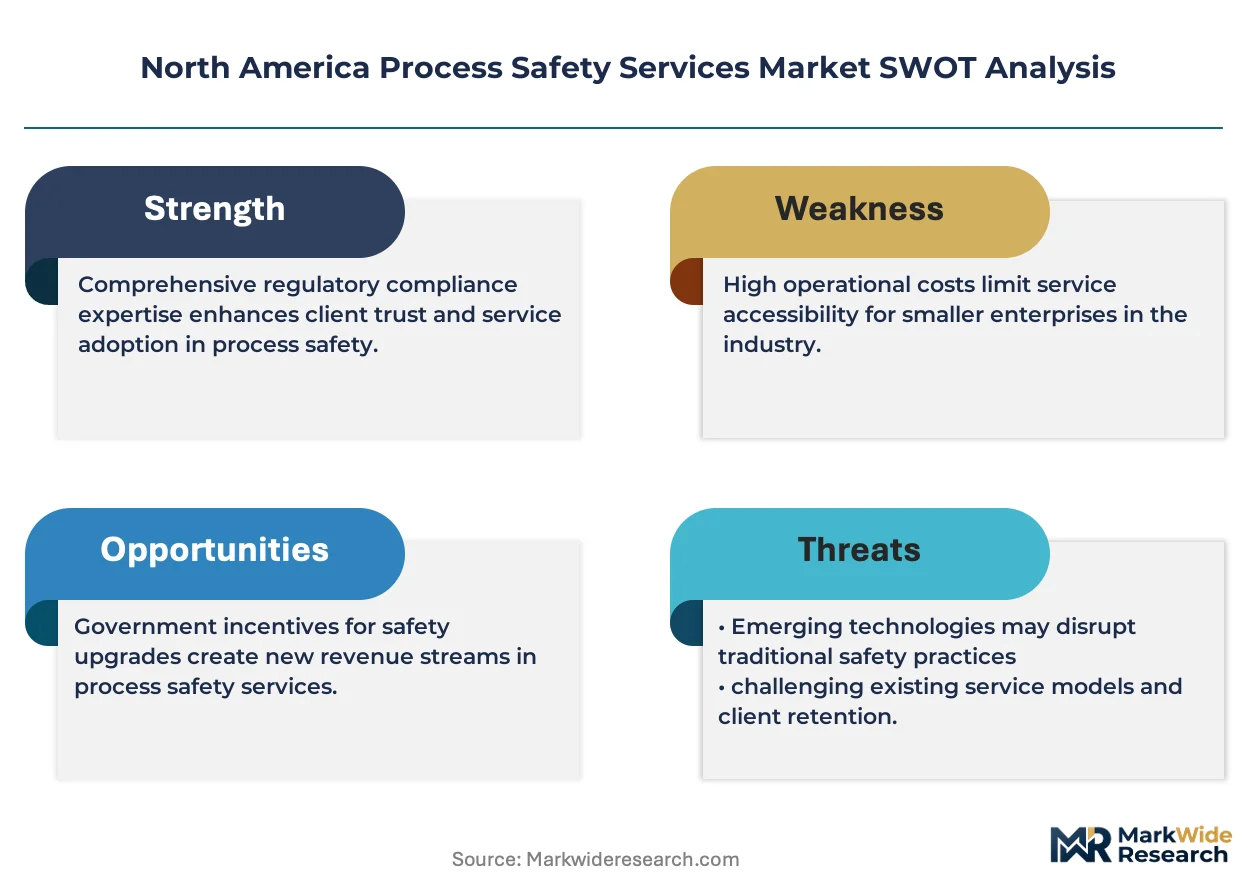
OSHA's tightening enforcement posture on Process Safety Management violations is compressing procurement cycles, forcing Gulf Coast refineries and Appalachian shale processors to accelerate third-party auditing engagements and digital safety layer upgrades ahead of anticipated penalty escalations.
Growth Catalysts
- EPA Risk Management Program amendments:Proposed chemical disaster prevention rules are compelling US petrochemical facilities to expand quantitative risk assessment budgets and layers of protection analysis scope.
- Alberta oil sands expansion:Provincial mandates for integrated safety management systems are driving Canadian operators toward unified hazard identification platforms spanning upstream through midstream operations.
- Digital twin adoption:Process simulation technologies are embedding safety instrumented system validation into engineering workflows, creating recurring consulting demand for model calibration and verification.
Market Restraints
- Specialized engineering labor scarcity:North American universities produce insufficient process safety engineering graduates to match Gulf Coast and Alberta facility expansion timelines.
- Third-party auditor concentration:A handful of credentialed firms dominate offshore platform certification in the Gulf of Mexico, creating bottlenecks for midstream operators seeking expedited compliance verification.
- Legacy system interoperability:Decades-old distributed control systems in Texas and Louisiana refineries resist seamless integration with modern safety integrity level calculation software.
Strategic Opportunities
- Mexican energy reform implementation:Pemex downstream modernization and private refinery licensing are creating first-mover openings for safety management systems integration in Veracruz and Tamaulipas corridors.
- Hydrogen hub development:US Department of Energy-funded regional clean hydrogen projects in the Gulf Coast require novel hazard analysis methodologies for ammonia and liquid hydrogen handling.
- Remote auditing platforms:Cloud-based inspection tools are enabling real-time compliance monitoring across geographically dispersed Canadian oil sands and US shale extraction sites.
Industry Challenges
- Functional safety certification timelines:TÜV Rheinland and exida credentialing for safety instrumented system engineers extends 18-24 months, constraining project staffing flexibility.
- Multi-vendor system integration:Facilities combining Honeywell, Emerson, and Yokogawa automation layers face complex safety requirement harmonization during layered protection verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Process Safety Services Market |
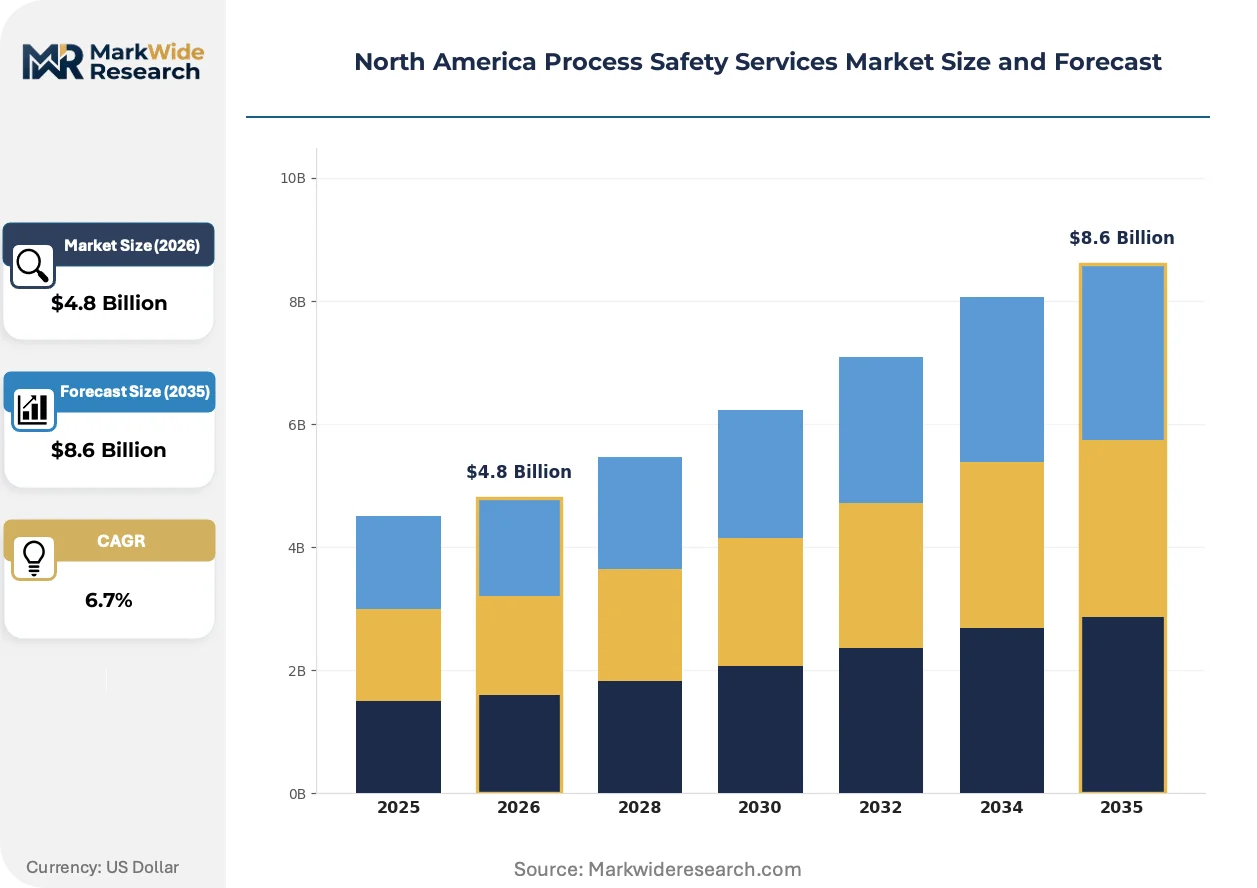
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Training, Auditing, Compliance Industry Vertical: Oil & Gas, Chemical, Pharmaceutical, Energy Technology: Risk Assessment, Safety Management Systems, Automation, Incident Investigation End User: Manufacturers, Refineries, Utilities, Contractors |
| Companies Covered | Honeywell International Inc., Emerson Electric Co., Rockwell Automation, ABB Group, General Electric Company, Bureau Veritas, DNV GL AS, DEKRA Process Safety, ABS Consulting, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Process Safety Services Market Evolving Landscape
Artificial intelligence is penetrating hazard identification workflows, compressing the timeline between incident precursor detection and safeguard activation while reshaping how process safety engineers allocate analytical attention across operating units.
Machine learning-based predictive maintenance is electrifying traditional safety instrumented system testing protocols. US Gulf Coast refineries are deploying neural network models to forecast sensor degradation and valve failure probabilities. This capability is compressing proof-test intervals and reducing unplanned shutdown frequency in high-consequence hydrocracker and alkylation units.
OSHA's forthcoming updates to the Process Safety Management standard are mandating root cause analysis depth for near-miss events. Chemical manufacturers in Texas and Louisiana are restructuring incident investigation teams and expanding training budgets for systematic failure mode identification. The consulting segment is responding with packaged investigation facilitation services and software-enabled cause mapping tools.
Buyer consolidation among supermajor refiners is reshaping vendor relationship structures. ExxonMobil, Chevron, and Phillips 66 are narrowing preferred provider lists for process safety services, demanding bundled offerings spanning hazard analysis through safety management systems integration. This concentration is squeezing boutique specialists and favoring automation-origin consultancies with captive engineering resources.
North America Process Safety Services Market Segmentation
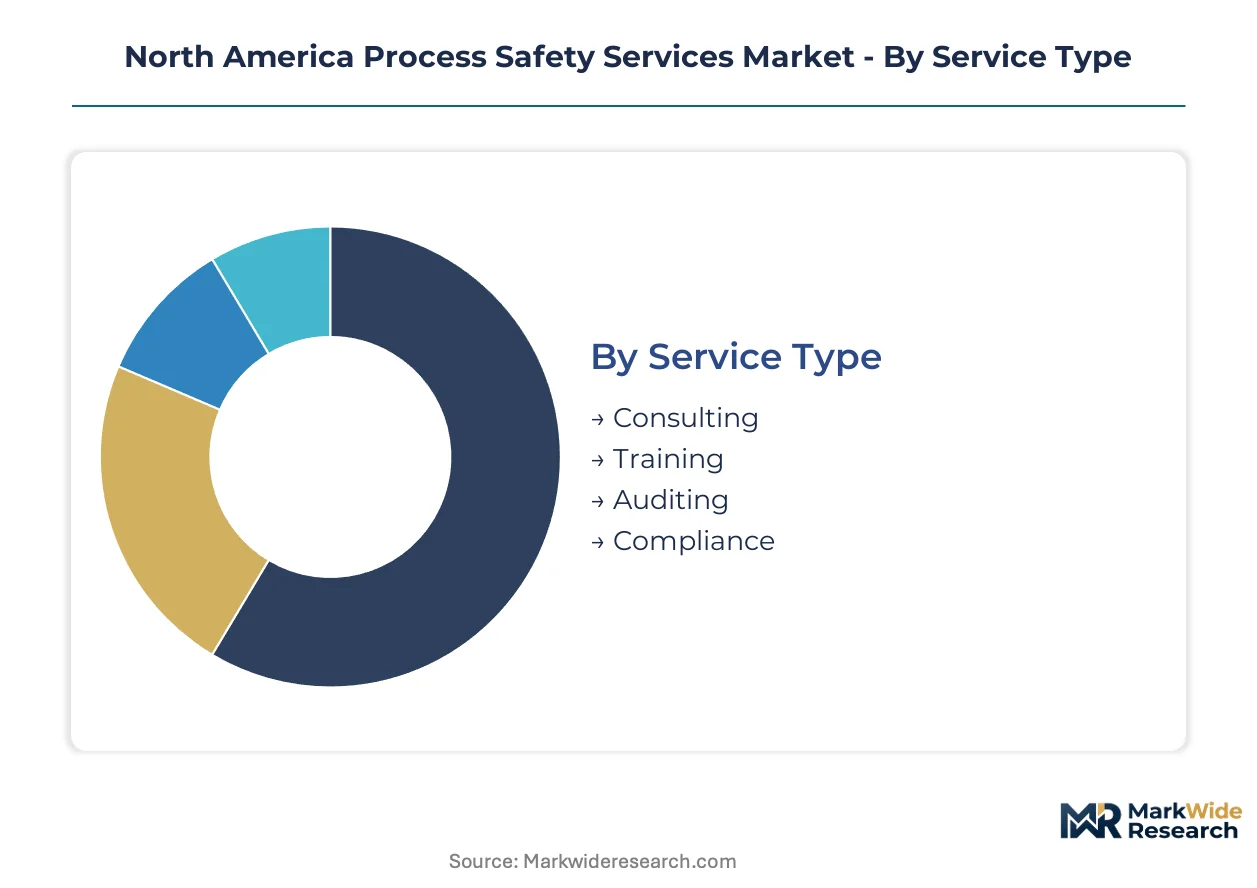
Process safety services fragment across service delivery modes, industry applications, and technological platforms. Procurement patterns differ sharply between compliance-driven renewals and capital-intensive system overhauls. Understanding these segment boundaries clarifies where vendor consolidation pressures concentrate versus where specialized boutiques retain defensible positions.
Service Type:
Facility upgrade cycles and regulatory inspection calendars determine renewal velocity across service categories. Operators facing OSHA enforcement tightening prioritize accelerated auditing engagements over extended consulting retainers.
- Consulting:Engineering advisory spans hazard analysis, layers of protection design, and quantitative risk assessment for new capital projects and major modifications. Gulf Coast petrochemical complexes drive sustained demand for process safety management program development ahead of anticipated EPA Risk Management Program amendments. Procurement is consolidating toward automation-origin consultancies with captive engineering benches.
- Auditing:Third-party compliance verification and management system assessments address OSHA PSM and EPA RMP inspection requirements. Texas and Louisiana refineries anchor the highest concentration of external audit services in the region, with compressed procurement cycles reflecting enforcement anxiety. Credential scarcity among certified lead auditors creates scheduling bottlenecks for midstream operators.
- Training:Workforce certification and refresher instruction satisfies OSHA PSM employee participation mandates and operator competency requirements. Stable renewal rates reflect regulatory minimums rather than discretionary expansion budgets.
- Compliance:Documentation management, regulatory filing support, and permit maintenance services reduce administrative burden on facility safety managers. Canadian oil sands operators leverage these services to navigate Alberta provincial regulator mandates.
Volume placements concentrate in Auditing; the faster expansion belongs to Consulting.
Industry Vertical:
End-use concentration shapes service customization requirements and pricing power distribution across verticals. Capital intensity and catastrophic release consequences determine willingness to fund premium advisory versus commoditized compliance checking.
- Oil & Gas:Upstream through downstream operations require integrated safety management systems spanning drilling, processing, and distribution hazards. Alberta oil sands expansion and Appalachian shale processing drive Canadian and US demand respectively for unified hazard identification platforms.
- Chemical:Specialty and commodity chemical manufacturers face acute OSHA PSM enforcement pressure, particularly in Gulf Coast clusters. Proposed EPA chemical disaster prevention rules are compelling expanded quantitative risk assessment budgets.
- Pharmaceutical:Batch processing facilities and active pharmaceutical ingredient manufacturing impose stringent containment and reaction hazard controls. FDA process validation requirements intersect with OSHA standards for hybrid compliance frameworks.
- Energy:Power generation and renewable fuel projects introduce novel hazard profiles for hydrogen handling and ammonia infrastructure. US Department of Energy-funded regional clean hydrogen initiatives require specialized methodology development.
Revenue concentration sits with Oil & Gas; Chemical verticals are climbing the fastest as enforcement intensity escalates.
Technology:
Technology platform selection determines integration complexity and recurring calibration revenue potential. Legacy system interoperability constraints favor vendors with proven migration pathways from decades-old distributed control architectures.
- Risk Assessment:Quantitative methodologies including fault tree analysis, event tree modeling, and consequence modeling establish defensible safeguard specifications. Gulf Coast refineries embed these services into front-end engineering design for hydrocracker and alkylation unit modifications.
- Safety Management Systems:Unified software platforms integrating hazard identification through incident investigation represent the steepest expansion trajectory. Canadian provincial mandates are accelerating adoption across Alberta oil sands corridors.
- Automation:Safety instrumented system design, validation, and lifecycle management services tie to distributed control system retrofit cycles. Proof-test interval compression through predictive analytics is reshaping maintenance economics.
- Incident Investigation:Root cause analysis facilitation and systematic failure mode identification address OSHA's forthcoming near-miss event depth requirements. Texas and Louisiana chemical manufacturers are restructuring investigation team capabilities.
Deployment scale favors Risk Assessment; Safety Management Systems are gaining share fastest through platform consolidation.
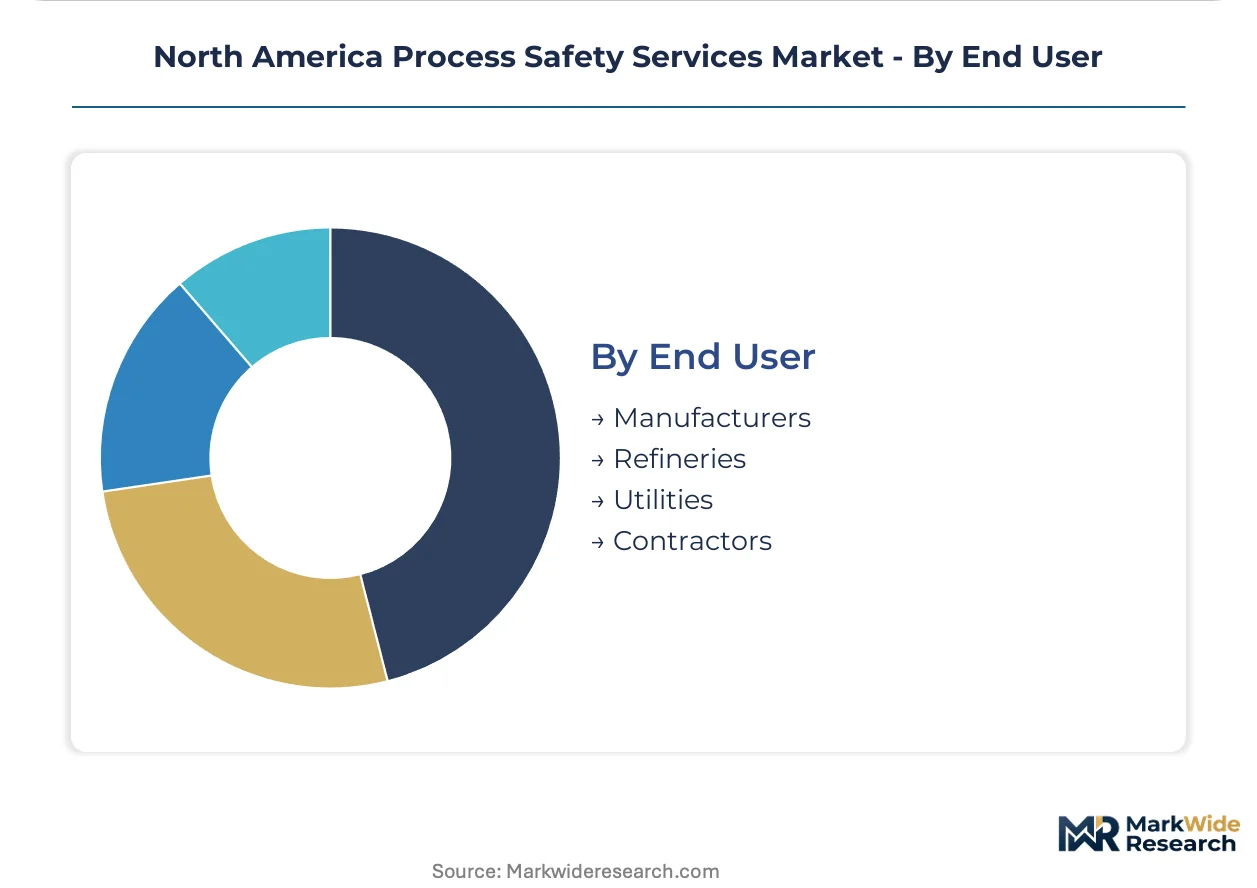
End User:
Customer organizational structure dictates procurement centralization versus site-level autonomy. Supermajor consolidation into preferred provider lists is squeezing relationship diversity.
- Refineries:Integrated downstream complexes with high-consequence hydroprocessing units anchor premium service demand. ExxonMobil, Chevron, and Phillips 66 procurement consolidation is narrowing vendor access.
- Manufacturers:Chemical and pharmaceutical production facilities balance compliance minimums against capital project safety integration. Specialty chemical producers retain more boutique advisory relationships than commodity operators.
- Utilities:Power generation and grid infrastructure operators are emerging as process safety service buyers as hydrogen and ammonia handling enters their hazard portfolios.
- Contractors:Engineering, procurement, and construction firms embed safety services into turnkey project delivery, creating channel conflict with direct facility relationships.
Contractor channel volume dominates project-phase activity; direct Refinery relationships are expanding fastest through operational phase retainers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes the dominant share of process safety services while Canada anchors specialized demand tied to oil sands extraction. Mexico's energy reform is opening new procurement channels for integrated safety management systems.
United States
Gulf Coast refineries and Appalachian shale processors drive concentrated demand for third-party auditing and digital safety layer upgrades. OSHA's tightening enforcement posture on Process Safety Management violations compresses procurement cycles ahead of anticipated penalty escalations. Texas and Louisiana host the highest concentration of external audit services, with Houston-area petrochemical complexes expanding quantitative risk assessment budgets.
Canada
Alberta oil sands operators are accelerating adoption of unified hazard identification platforms spanning upstream through midstream operations. Provincial mandates for integrated safety management systems reshape procurement toward full-service providers with safety instrumented systems expertise. Calgary and Fort McMurray anchor the densest clustering of compliance verification services tied to Canadian Environmental Protection Act enforcement.
Mexico
Pemex downstream modernization and private refinery licensing create first-mover openings for safety management systems integration. Federal energy reform implementation demands novel hazard analysis methodologies for new processing capacity in Veracruz and Tamaulipas corridors. The Salina Cruz and Tula refinery modernization programs are embedding process safety consulting into front-end engineering design.
North America Process Safety Services Market Competitive Landscape
Top-tier vendors anchor automation-integrated consulting, while mid-tier specialists compete on credential scarcity and geographic focus. The vendor base stratifies across three tiers: full-service automation-origin consultancies with captive engineering benches, boutique hazard analysis specialists with TÜV Rheinland or exida certifications, and third-party auditing firms competing on regulatory credentials. Consolidation pressures favor bundled offerings spanning hazard analysis through safety management systems integration. Preferred provider list narrowing by supermajor refiners squeezes relationship diversity for smaller specialists.
Among automation-origin consultancies, Honeywell International Inc., Emerson Electric Co., and Rockwell Automation exemplify the full-service archetype bundling distributed control systems with process safety advisory. These firms occupy positions shaped by installed base leverage and retrofit cycle timing rather than pure consulting differentiation. Bureau Veritas and DNV GL AS represent the credential-driven tier competing on third-party auditing authority across Canadian energy corridors and Gulf of Mexico offshore platforms.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Emerson Electric Co. |
| Rockwell Automation |
| ABB Group |
| General Electric Company |
| Bureau Veritas |
| DNV GL AS |
| DEKRA Process Safety |
| ABS Consulting |
| Others |
Value Network & Pricing Analysis
Certified process safety engineers concentrated along the US Gulf Coast and Alberta corridors command premium billing rates that compress pricing-tier spreads between boutique specialists and integrated automation vendors. Labor-cost differentials between TÜV Rheinland-credentialed consultants and uncertified analysts shape three distinct service tiers.
Pricing Analysis
Margin tightening in mid-tier auditing reflects credential scarcity among certified lead auditors and compressed procurement cycles ahead of OSHA enforcement escalation. Project-based pricing dominates consulting engagements, while subscription models gain traction for safety management systems integration. Price differentiation hinges on certification grade—exida or TÜV Rheinland functional safety credentials—and vertical integration with distributed control system footprints. Cost-down pressure on commoditized compliance documentation accelerates as facility owners consolidate vendor relationships. Supermajor refiners exhibit lowest price sensitivity; midstream shale operators show highest.
Supply Chain Analysis
Dual-sourcing requirements for critical safety instrumented system components mandate multi-vendor qualification across Honeywell, Emerson, and Yokogawa automation layers. Engineering talent concentrates in the United States, Canada, and select Mexican technical institutes. Raw material dependencies span specialized sensors, fail-safe valve actuators, and proprietary software licenses. Single-source vulnerability in functional safety certification—TÜV Rheinland and exida dominate credentialed engineer pipelines—creates project staffing bottlenecks. Distribution runs through direct facility relationships and engineering-procurement-construction contractor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Process safety services are becoming a vertical-integration race. Automation vendors with captive engineering benches are pulling upstream into consulting advisory to capture retrofit cycle economics.
For Market Incumbents: Anchor market position through backward integration into TÜV Rheinland certification pipelines and safety instrumented system manufacturing partnerships. Consolidate procurement influence by bundling hazard analysis with distributed control system lifecycle services. Defend against boutique specialist displacement by embedding predictive analytics capabilities into proof-test protocols. For New Entrants and Emerging Players: Launch via cloud-based remote auditing platforms targeting geographically dispersed Canadian oil sands and Appalachian shale extraction sites. White-space concentration sits with hydrogen hub hazard methodology development and Mexican refinery modernization programs. Pursue regulatory technology positioning to automate compliance documentation workflows for midstream operators. For Investors and Strategic Acquirers: The window for entry favors automation-origin consultancies with installed base leverage and captive engineering resources. Long-term viability centers on platform consolidation economics spanning hazard identification through incident investigation. Watch for OSHA Process Safety Management standard finalization as inflection signal for accelerated procurement compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certification Pipelines | TÜV Rheinland and exida credential scarcity constrains project staffing flexibility across Gulf Coast expansions. |
| Platform Integration of Safety Management Systems | Unified hazard identification through incident investigation platforms address Alberta provincial regulator mandates. |
| Geographic Expansion into Mexican Energy Corridors | Pemex downstream modernization and private refinery licensing create first-mover openings in Veracruz and Tamaulipas. |
| Strategic Partnership for Hydrogen Hub Methodology | US Department of Energy-funded regional clean hydrogen projects require novel ammonia and liquid hydrogen hazard analysis. |
| Acquisition of Specialist Incident Investigation Firms | OSHA's forthcoming near-miss event depth requirements restructure Texas and Louisiana chemical manufacturer capabilities. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with process safety directors, plant managers at Gulf Coast petrochemical complexes, procurement leads at supermajor refiners, and Alberta oil sands operations executives combined with OSHA enforcement databases, EPA Risk Management Program filings, and Canadian Environmental Protection Act compliance records. Bottom-up service category sizing triangulated against top-down regional market estimates.
Segment-level modeling applied service type, industry vertical, technology platform, and end-user organizational structure dimensions across the projection horizon. Consulting, auditing, training, and compliance service categories were modeled separately. CAGRs derived from regulatory inspection cycle frequencies, capital project pipelines, and enforcement intensity trajectories. Safety instrumented system retrofit cycles and digital twin adoption curves informed technology platform growth allocations.
OSHA enforcement posture shifts, EPA Risk Management Program amendment timing, and functional safety engineer graduation rates are the dominant revision risks. Deviation in credential pipeline expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Intrinsically Safe Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Goggles Market
Safety Equipment and Personal Protective Equipment (PPE)
US Safety Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
US Safety Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Non-Powered Air Purifying Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
Panic Exit Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Bulletproof Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Fall Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
US Conducted Energy Weapons Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Spill Kits Market
Safety Equipment and Personal Protective Equipment (PPE)
Biodegradable Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Surgical Mask and Respirators Market