
 Cylindrical Door Lock Market | 2026-2036
Cylindrical Door Lock Market Size, Share, and Industry Trends Forecast 2026-2036
Cylindrical Door Lock Market Outlook
Grade 2 and Grade 3 ANSI/BHMA certification tiers is rotating toward the center of procurement specifications across North American commercial real estate. ASSA ABLOY leverages its captive foundry network to control brass and zinc alloy supply costs. Yale anchors retail channel presence through locksmith and hardware cooperative networks. Mottura specializes in high-security European profile cylinders for banking and government verticals.
A cylindrical door lock employs a rotating plug mechanism housed within a circular barrel that aligns driver pins with corresponding key bitting to permit latch retraction; typical specifications include 5-pin or 6-pin tumbler configurations with plug diameters of 18–22 mm for residential and light commercial duty cycles. The device serves as the primary access control interface for interior and exterior door assemblies across single-family homes, apartment units, and small-to-mid commercial facilities. Keyless cylinder and smart lock installation types command expanding margin pools as electrification and mobile credentialing displace mechanical master key systems. Brass and stainless steel material segments retain volume leadership in institutional and industrial end-user categories where durability specifications and corrosion resistance requirements remain stringent.
UL 437 burglary-resistant cylinder listings and ANSI/BHMA A156.5 operational cycle standards govern product eligibility for commercial insurance and facility management contracts in the United States. The EU's Construction Products Regulation and CE marking requirements for panic exit devices and fire-rated door hardware shape cross-border market access for cylinder manufacturers exporting from Asia-Pacific production bases. Stakeholders must monitor the divergence between mechanical cylinder upgrade cycles and connected lock platform refresh timelines as interoperability standards for commercial access control networks crystallize.
Market Dynamics
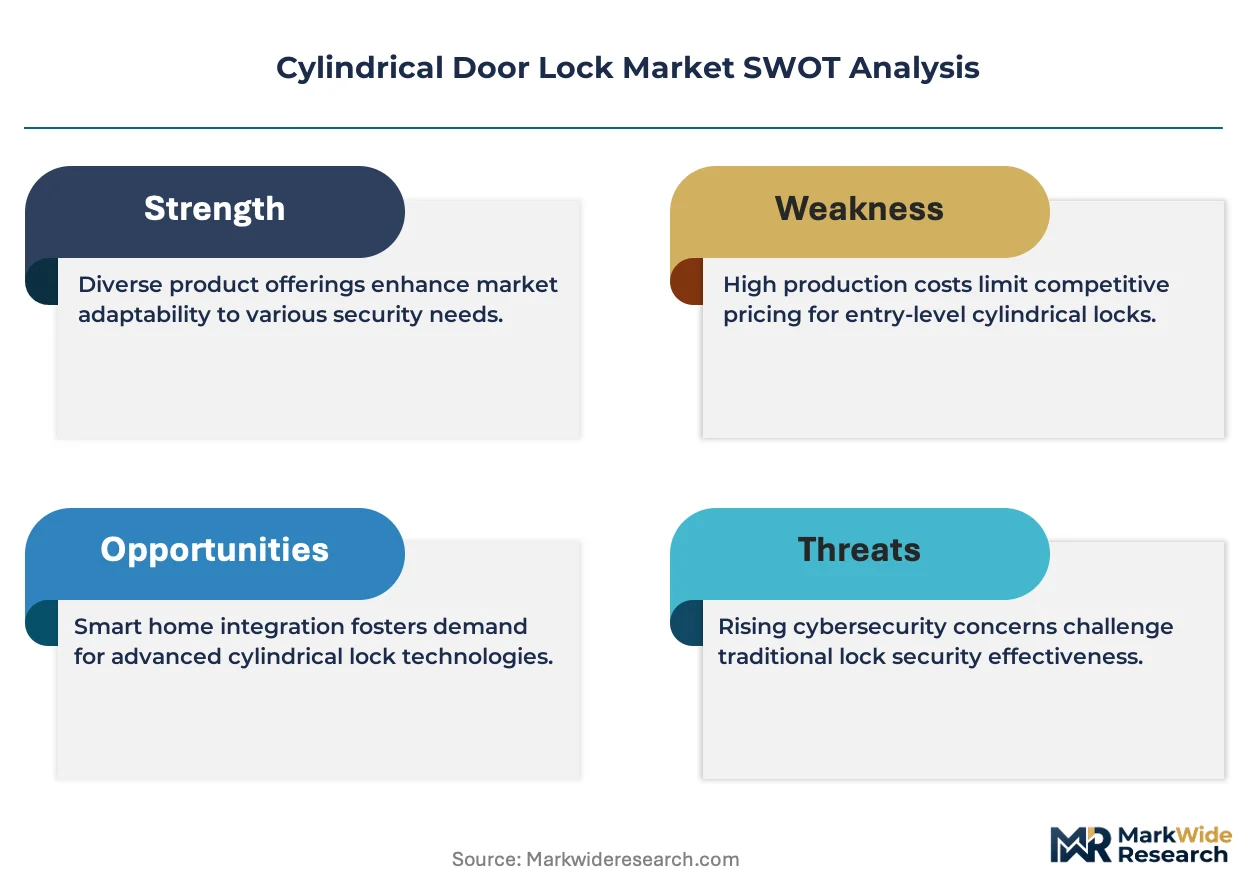
Electrification of credentialing systems is fragmenting the cylindrical lock value chain, forcing mechanical manufacturers to absorb firmware development costs while maintaining brass foundry operations for institutional grade hardware.
Growth Catalysts
- ANSI/BHMA Grade 2 Certification:Commercial real estate developers in the United States now mandate this tier for mid-rise office and retail fit-outs, compressing replacement cycles from fifteen to eight years.
- ETSI EN 303 645:The EU's baseline cybersecurity requirements for consumer IoT devices is creating compliant product categories that unlock insurance premium reductions for multi-family housing operators.
- Mobile Credential Convergence:Hospitality chains are retrofitting Bluetooth Low Energy modules into existing cylinder housings to bypass front-desk key distribution labor costs.
Market Restraints
- Brass Alloy Volatility:Copper and zinc price swings from Chilean and Peruvian concentrate supply disruptions compress foundry margins on institutional-grade cylinders.
- Zhejiang Component Concentration:Over sixty percent of electronic lock motor and sensor subassemblies originate from a three-city radius around Ningbo, creating single-point vulnerability.
- Mechanical-to-Digital Skill Gap:Master locksmiths lack training in credential provisioning and over-the-air firmware updates, slowing smart retrofit penetration in small commercial accounts.
Strategic Opportunities
- German Building Renovation Wave:Hamburg and Munich smart building mandates are accelerating replacement of DIN-standard cylinders in pre-2010 commercial stock.
- Insurance-Driven Specification:Underwriters in the United Kingdom are introducing premium discounts for UL 437-listed cylinders in high-value residential construction.
- Cooperative Distribution:Hardware buying groups and locksmith associations are consolidating procurement power, creating private-label opportunities for mid-tier manufacturers.
Industry Challenges
- Dual Certification Timelines:Manufacturers pursuing simultaneous ANSI/BHMA A156.5 and CE marking for fire-rated panic hardware face eighteen-month approval queues.
- Interoperability Fragmentation:Proprietary access control protocols from major commercial real estate technology vendors force cylinder OEMs to maintain multiple firmware branches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cylindrical Door Lock Market |
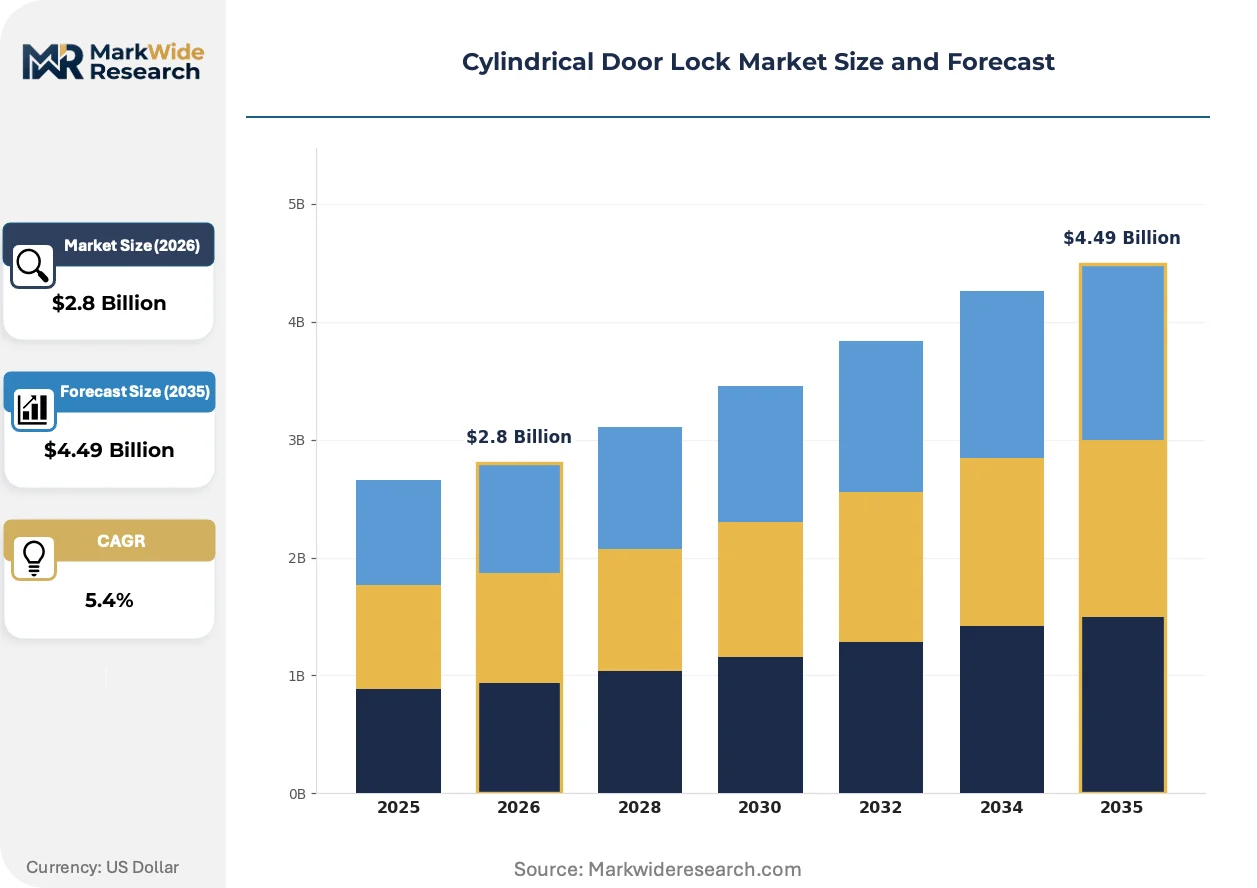
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cylinder, Double Cylinder, Keyless Cylinder, Deadbolt Material: Brass, Stainless Steel, Aluminum, Zinc Alloy End User: Residential, Commercial, Institutional, Industrial Installation Type: Surface-Mounted, Mortise, Insert, Smart Lock |
| Companies Covered | ERA, Mottura, ASSA ABLOY, Cisa, Kale, Ultion (Brisant), M&C, Pfaffenhain, Yale, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cylindrical Door Lock Market Strategic Shifts
Three distinct vectors are restructuring how cylindrical locks are specified, manufactured, and monetized across residential and commercial channels.
Bluetooth-enabled passive entry modules are decomposing the traditional separation between mechanical hardware and access control electronics. Multi-family developers in Texas and Florida are specifying these retrofits for Class B apartment repositioning projects. The technology is compressing installation labor costs by eliminating separate low-voltage wiring runs to door positions.
REACH restrictions on lead and cadmium in metal alloys are forcing brass foundries to reformulate cylinder housings and plug components. German manufacturers serving banking and government verticals have shifted to bismuth and silicon bronze alternatives ahead of enforcement timelines. The regulatory pressure is concentrating high-security cylinder production among foundries with metallurgical R&D capabilities.
Property technology procurement teams are consolidating vendor relationships around integrated platform providers rather than discrete hardware suppliers. Facility managers in the United States are bundling lock hardware with energy management and visitor management systems under single-source contracts. This behavior is most visible in the build-to-rent residential sector, where national operators standardize on credential systems across fifty-plus unit portfolios.
Cylindrical Door Lock Market Segmentation
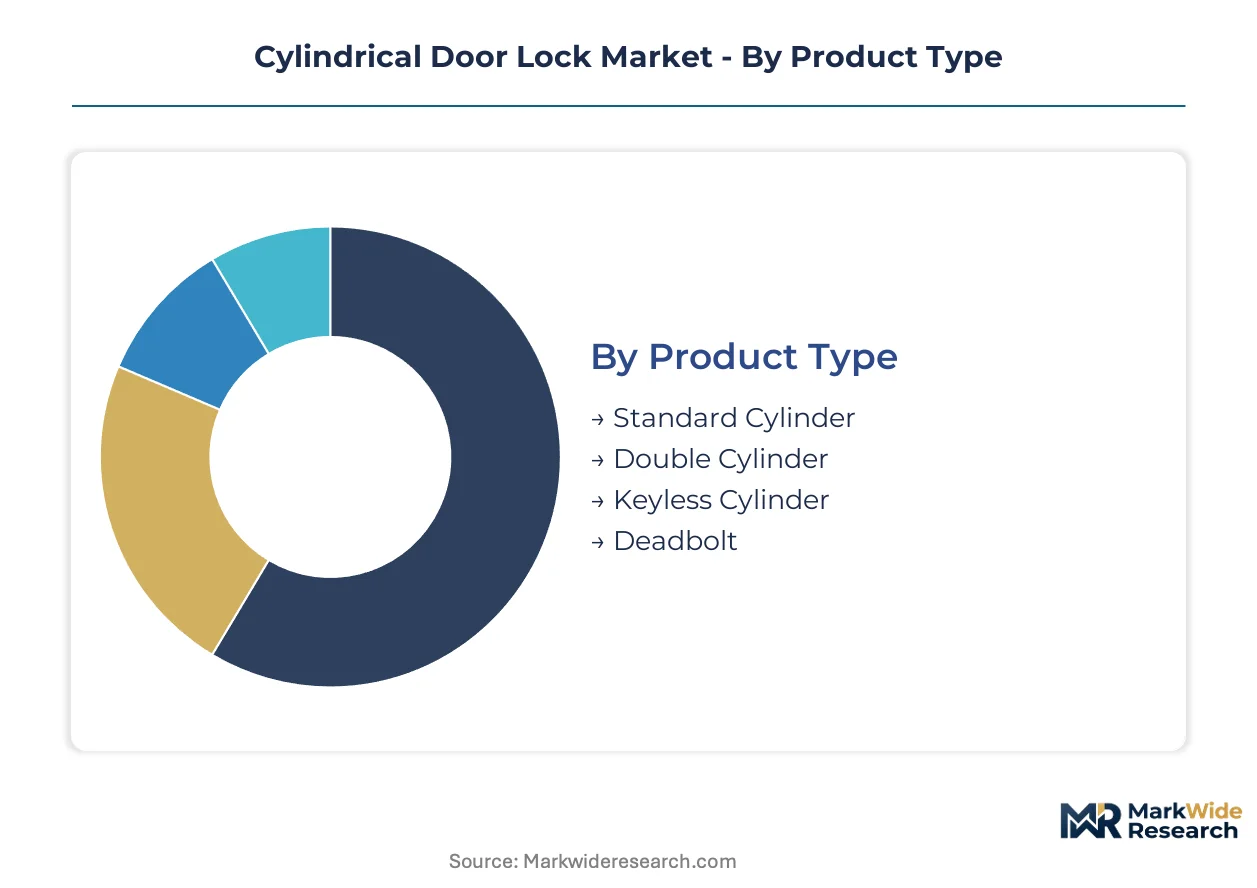
Cylindrical door lock procurement channels diverge sharply by segment, with mechanical grades flowing through locksmith cooperatives and smart variants concentrating in direct specification by property technology platforms. Understanding these channel dynamics reveals where margin pools concentrate and which certification tiers command pricing power.
Product Type:
Channel mix varies dramatically across product types, with standard mechanical cylinders dominating wholesale distribution while keyless variants bypass traditional hardware cooperatives entirely.
- Standard Cylinder:Five-pin or six-pin tumbler configurations with 18–22 mm plug diameters constitute the volume foundation. Demand concentrates in North American residential replacement cycles and German commercial renovation mandates, driven by ANSI/BHMA Grade 2 procurement specifications compressing replacement intervals from fifteen to eight years.
- Keyless Cylinder:Bluetooth Low Energy and NFC-enabled housings retrofit existing door preparations without wiring runs. Hospitality chains in Texas and Florida specify these for Class B apartment repositioning, bypassing front-desk key distribution labor costs entirely.
- Double Cylinder:Key-required operation on both sides of the door assembly, common in European DIN-standard installations.
- Deadbolt:Independent locking bolt mechanism providing supplemental security to primary latch systems.
Standard cylinder dominates installed base. Keyless cylinder is where expansion concentrates.
Material:
Cost tier alignment shapes material selection, with premium alloys commanding specification in institutional verticals while mid-tier metals serve volume residential channels.
- Brass:Copper-zinc alloys deliver machinability and corrosion resistance for institutional duty cycles. Foundry concentration in Ningbo and Dongguan creates supply vulnerability, with copper price volatility from Chilean concentrate disruptions compressing margins on ANSI/BHMA Grade 2 and Grade 3 certifications.
- Stainless Steel:Austenitic grades provide salt-spray resistance for coastal commercial applications. German banking and government verticals specify these for high-security European profile cylinders, with Hamburg and Munich smart building mandates accelerating specification.
- Aluminum:Lightweight die-cast housings for residential and light commercial duty cycles where cost sensitivity dominates.
- Zinc Alloy:Zamak formulations for economy-tier residential products in price-sensitive developing markets.
Brass retains volume leadership. Stainless steel is gaining share fastest in premium specification.
End User:
Application requirements dictate certification complexity, with institutional and industrial segments demanding multi-standard compliance while residential tolerates single-tier listing.
- Commercial:Mid-rise office and retail fit-outs mandate ANSI/BHMA Grade 2 certification for insurance eligibility. United States commercial real estate developers now embed this tier in standard specifications, with ETSI EN 303 645 cybersecurity compliance unlocking premium reductions for multi-family housing operators in EU markets.
- Residential:Single-family and multi-family units drive volume through retail and locksmith channels. Build-to-rent national operators in the United States consolidate procurement around integrated platform providers, bundling lock hardware with energy and visitor management systems.
- Institutional:Schools, hospitals, and government facilities requiring fire-rated and panic exit compatibility.
- Industrial:Heavy-duty cycle environments with corrosion resistance and vandalism protection requirements.
Residential commands unit volume. Commercial is where margin expansion concentrates.
Installation Type:
Customer technical sophistication determines installation type selection, with professional channels handling complex mortise preparations while consumer-direct channels capture smart lock growth.
- Smart Lock:Electrified cylindrical housings with credential provisioning and over-the-air firmware update capability. Master locksmiths in small commercial accounts lack training in these systems, slowing retrofit penetration and creating opportunity for manufacturer-direct service models.
- Mortise:Recessed cavity preparation requiring professional installation, dominant in commercial and institutional new construction.
- Surface-Mounted:Rim cylinder applications for retrofit and auxiliary locking scenarios.
- Insert:Drop-in replacements for existing cylindrical preparations without door modification.
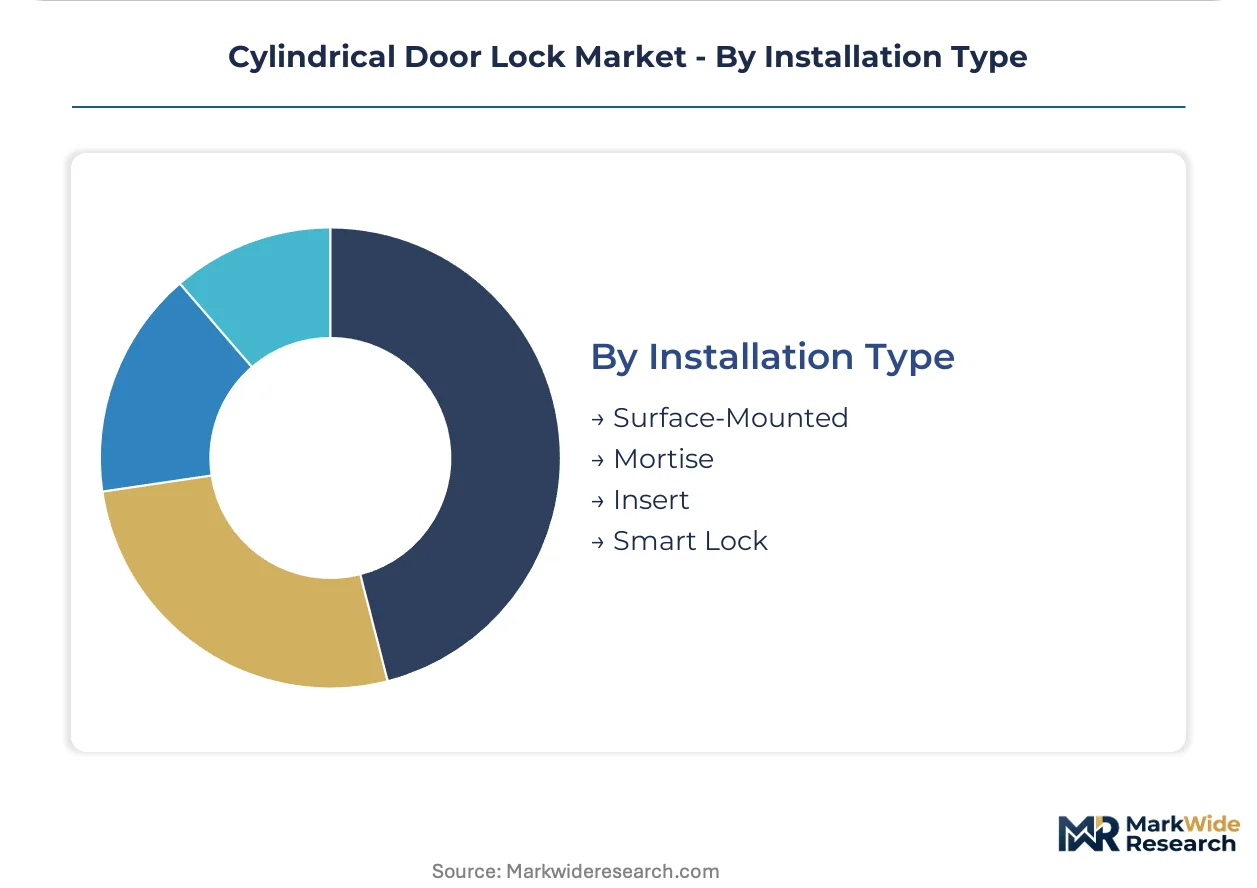
Mortise dominates commercial new build. Smart lock is where technology refresh concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brass foundry capacity clusters in China's Yangtze River Delta and Pearl River Delta, with Ningbo and Dongguan supplying over sixty percent of electronic lock motor assemblies. This concentration creates vulnerability when Chilean copper concentrate disruptions ripple through alloy pricing.
United States
Commercial real estate developers mandate ANSI/BHMA Grade 2 certification for mid-rise office fit-outs, compressing replacement cycles from fifteen to eight years. OSHA workplace safety standards and insurance underwriting requirements shape procurement specifications. Texas and Florida Class B apartment repositioning projects concentrate Bluetooth retrofit demand in Dallas-Fort Worth and Miami-Dade submarkets.
Germany
Hamburg and Munich smart building mandates accelerate DIN-standard cylinder replacement in pre-2010 commercial stock. The EU's Cybersecurity Act and ETSI EN 303 645 standards reshape product certification timelines for connected devices. Bavaria's banking and government verticals specify high-security European profile cylinders from foundries with metallurgical R&D capabilities.
China
Ningbo's three-city radius dominates electronic lock motor and sensor subassembly production for export markets. MIIT national standards and GB certification requirements govern domestic product eligibility. Dongguan die-casting clusters supply zamak and aluminum housings for economy-tier residential exports to Southeast Asian markets.
United Kingdom
Insurance underwriters introduce premium discounts for UL 437-listed cylinders in high-value residential construction. Building regulations and fire safety codes from the Ministry of Housing shape panic exit device specifications. Locksmith cooperatives in Greater London and the Midlands consolidate procurement power for private-label hardware programs.
Italy
European profile cylinder demand concentrates in Lombardy and Veneto for banking and government security applications. CE marking requirements under the EU Construction Products Regulation govern cross-border market access. Emilia-Romagna's precision machining clusters supply high-tolerance plug components to German and French OEMs.
Cylindrical Door Lock Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Mechanical specialists with captive foundry operations compete on alloy formulation and cycle durability, while electronics integrators compete on firmware development and platform interoperability. Three archetypes dominate: vertically integrated hardware manufacturers with brass foundry control, smart lock platform providers with mobile credential ecosystems, and cooperative-aligned brands serving locksmith distribution networks. Competitive moves concentrate on M&A for electronic capability acquisition and strategic partnerships for access control protocol integration.
Among European specialists, Mottura and Cisa exemplify the high-security mechanical archetype, with Mottura representing Italian precision machining for banking and government verticals. ASSA ABLOY anchors the integrated multinational tier, its structure spanning captive foundry networks and electronic platform development. Yale occupies the cooperative distribution channel, its position reflecting locksmith and hardware buying group alignment rather than direct specification capture. These three illustrate how geographic origin and organizational structure map to competitive positioning in fragmented procurement channels.
| Leading Market Players |
|---|
| ERA |
| Mottura |
| ASSA ABLOY |
| Cisa |
| Kale |
| Ultion (Brisant) |
| M&C |
| Pfaffenhain |
| Yale |
| Others |
Value Chain & Pricing Dynamics
ANSI/BHMA Grade 2 certification gates both supply qualification and price differentiation simultaneously, compressing replacement cycles from fifteen to eight years while creating tiered margin pools across institutional and residential channels. Brass alloy volatility from Chilean concentrate disruptions feeds directly into foundry pricing power, with captive supply networks commanding premium positioning against spot-market dependent competitors.
Pricing Analysis
ANSI/BHMA A156.5 dictates the pricing tier structure across mechanical and electrified product lines. Three-tier pricing structure across premium, standard, and economy levels separates Grade 1 fire-rated hardware from Grade 2 commercial fit-outs and Grade 3 residential replacements. Price differentiation rests on certification level and after-sales service bundling, with cybersecurity-compliant connected locks commanding positioning above mechanical equivalents. Cost compression in standard mechanical tiers is intensifying because copper-zinc alloy volatility compresses foundry margins. Small commercial accounts exhibit highest price sensitivity, while institutional buyers prioritize duty-cycle durability over unit cost.
Supply Chain Analysis
Inventory buffers for electronic motor assemblies stretch to twelve-week lead times during concentrate supply disruptions. Production gravity centers on China, Italy, and Germany, with Ningbo's three-city radius supplying over sixty percent of BLE module and sensor subassemblies. Raw material dependencies span Chilean copper concentrate, Peruvian zinc, and rare-earth magnets for motor actuation. Single-source vulnerability concentrates in Zhejiang electronic component clusters. Distribution runs through locksmith cooperatives and hardware buying groups for mechanical grades, while smart variants bypass traditional channels for direct property technology platform specification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cylindrical door lock penetration sits at early-cycle expansion, with mobile credential convergence in hospitality and multi-family residential unlocking retrofit demand ahead of greenfield construction.
For Market Incumbents: Secure captive brass foundry capacity against concentrate price volatility while accelerating firmware development partnerships with commercial real estate technology vendors. Bluetooth Low Energy module integration threatens mechanical specialists lacking electronic capability; backward integration into credential provisioning platforms represents the critical defensive lever. For New Entrants and Emerging Players: Lead with cybersecurity-compliant SKUs targeting German smart building mandates in Hamburg and Munich, where DIN-standard replacement cycles concentrate demand ahead of enforcement timelines. Cooperative distribution channels through locksmith associations offer the most penetrable go-to-market angle against entrenched retail brands. For Investors and Strategic Acquirers: ETSI EN 303 645 certification requirements reshape the acquisition landscape toward foundries with metallurgical R&D capabilities and existing CE marking pathways. Long-term viability favors targets with dual mechanical-electronic competency spanning institutional duty cycles and connected platform refresh timelines. Watch ANSI/BHMA Grade 2 procurement specification penetration in United States commercial real estate as the inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Expansion | Captive brass supply insulates margins from Chilean concentrate volatility for institutional-grade production. |
| Cybersecurity Certification Investment | ETSI EN 303 645 compliance unlocks insurance premium reductions for multi-family housing operators. |
| Cooperative Distribution Partnership | Hardware buying group alignment secures private-label shelf space against direct-to-platform competitors. |
| Firmware Platform Integration | Bluetooth Low Energy module convergence with existing cylinder housings eliminates separate wiring installation costs. |
| Metallurgical Alloy Reformulation | REACH-compliant bismuth and silicon bronze alternatives concentrate high-security production among R&D-capable foundries. |
Study Parameters
A spread of perspectives from hardware cooperative procurement managers, commercial real estate technology directors, master locksmiths, and brass foundry operations heads converged on the working assumptions. Primary interviews combined with secondary validation against ANSI/BHMA certification databases, EU Construction Products Regulation filings, and customs trade records for copper-zinc alloy shipments. Bottom-up unit economics triangulated against top-down construction spending and building renovation cycle data.
Segmentation dimensions modeled include product type, material grade, end-user vertical, and installation complexity across the projection horizon. CAGRs derived from replacement cycle compression rates, smart building mandate adoption curves, and credential system refresh timelines. Forecast inputs incorporated copper price volatility scenarios and cybersecurity compliance penetration rates by regional regulatory cluster.
The analysis sits within stated boundaries; outcomes outside sustained Chilean concentrate supply stability or accelerated ETSI EN 303 645 enforcement timelines would require recalibration. Forecasts reflect documented assumptions regarding replacement cycle compression and platform interoperability crystallization. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Middle East and Africa Pin-Based Access Control Market
Access Control Systems
Card-Based Electronic Access Control Systems Market
Access Control Systems
Global Keyless Vehicle Access Control Systems Market
Access Control Systems
Global Industrial Safety Gates Market
Access Control Systems
Restricted Access Barrier System (RABS) Market
Access Control Systems
Europe Access Control Hardware Market
Access Control Systems
Pedestrian Entrance Control System Market
Access Control Systems
Indoor Electromagnetic Lock Market
Access Control Systems
North America Access Control Market
Access Control Systems
GCC Home Security Systems Market
Access Control Systems
Smart Door Lock Market
Access Control Systems
Residential Smart Lock Market
Access Control Systems
Access Control and Authentication Market
Access Control Systems
Automated Barriers and Bollards Market
Access Control Systems
Perimeter Intrusion Detection Systems Market
Access Control Systems
Global Automated Border Control Market