
 Anesthetic Gas Masks Market | 2026-2036
Anesthetic Gas Masks Market Size, Share, and Industry Trends Forecast 2026-2036
Anesthetic Gas Masks Market Analysis
Asian medical device manufacturing is shifting toward higher-grade polymer processing for anesthetic delivery systems. Medtronic plc leverages captive silicone compounding capabilities across its production footprint. Drägerwerk AG & Co. KGaA anchors European anesthesia workstation supply with integrated mask portfolios. Intersurgical Ltd. specializes in single-use airway consumables for high-throughput surgical environments.
Anesthetic gas masks are sealed patient interfaces designed to deliver volatile anesthetics and oxygen mixtures during controlled sedation, typically molded from medical-grade silicone or PVC with 22-millimeter ISO-standard connectors for circuit compatibility. Disposable masks dominate hospital procurement due to cross-contamination protocols, while pediatric configurations represent the fastest-expanding subset as neonatal surgery protocols advance. Material selection stratifies across silicone for extended procedures, PVC for cost-sensitive bulk purchasing, and polyurethane for latex-allergic patient populations.
FDA 510(k) clearance requirements govern mask biocompatibility and gas leakage thresholds in the United States, while the EU MDR mandates clinical evidence for reusable device classifications across European member states. China's NMPA enforces GB standard compliance for imported anesthesia accessories, creating tiered market access timelines. Stakeholders must monitor regulatory divergence between single-use and reusable device pathways as sustainability pressures intensify.
Market Dynamics
Single-use silicone mask procurement is tightening around ambulatory surgical center networks, compressing purchasing cycles and forcing manufacturers toward captive compounding capabilities that eliminate external polymer dependency.
Growth Catalysts
- Outpatient volume expansion:Ambulatory surgical centers in the United States, Germany, and China are scaling procedure throughput, creating sustained demand for disposable airway interfaces that minimize cross-contamination risk.
- FDA 510(k) pathway efficiency:Expedited clearance timelines for predicate-device submissions are accelerating product iteration cycles for silicone mask manufacturers targeting the US hospital segment.
- Neonatal protocol advancement:Pediatric anesthesia specialization is requiring purpose-built mask geometries with dead-space reduction, opening configuration-specific procurement channels.
Market Restraints
- Medical-grade silicone price volatility:Petrochemical feedstock fluctuations and semiconductor-grade silicone diversion are compressing gross margins on extended-use mask categories.
- EU MDR clinical evidence burden:Reusable device classifications now require post-market surveillance documentation, extending time-to-revenue for European market entrants by 18-24 months.
- Single-use plastic restriction momentum:France's AGEC law and similar extended producer responsibility frameworks are creating compliance friction for PVC-dominant mask portfolios.
Strategic Opportunities
- India ambulatory surgery penetration:Underdeveloped day-surgery infrastructure in tier-2 cities creates first-mover positioning for disposable mask suppliers establishing CDSCO-compliant distribution.
- Latex-allergic patient segmentation:Polyurethane mask alternatives command pricing premiums in pediatric and immunocompromised settings where PVC sensitivity protocols apply.
- Integrated workstation bundling:Anesthesia machine OEMs are consolidating supplier bases, creating captive channel access for mask manufacturers with ISO 80369-7 connector compatibility.
Industry Challenges
- Polymer processing talent scarcity:Medical-grade silicone molding expertise concentrates in Germany, the United States, and Japan, constraining geographic diversification of production assets.
- Dual regulatory track complexity:Manufacturers maintaining both single-use and reusable mask lines face divergent biocompatibility testing protocols under FDA and EU MDR frameworks.
- Legacy circuit integration:22-millimeter ISO-standard connector specifications limit form-factor innovation without anesthesia machine OEM cooperation on port redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anesthetic Gas Masks Market |
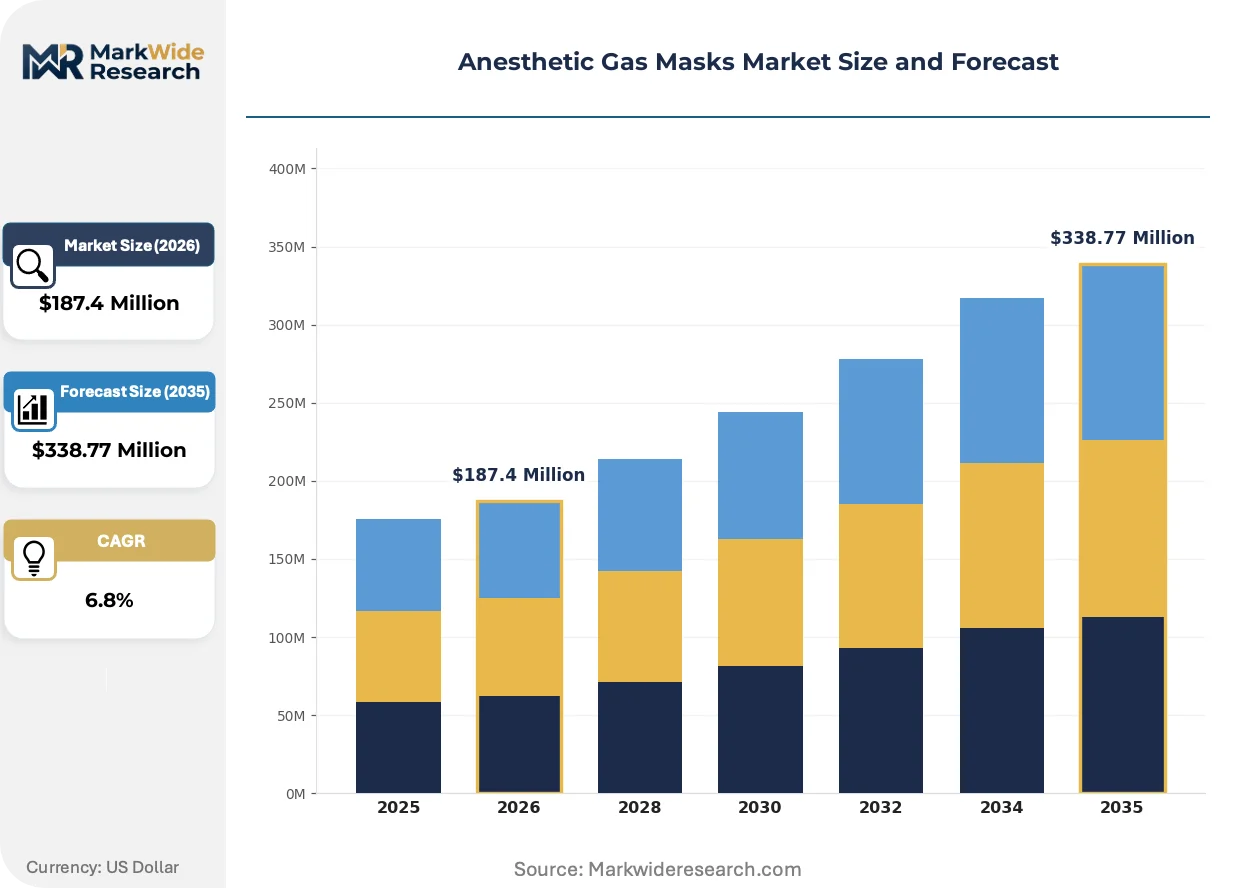
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable Masks, Disposable Masks, Pediatric Masks, High-Performance Masks Material: Silicone, PVC, Rubber, Polyurethane Application: Surgery, Anesthesia, Emergency Care, Veterinary Use End User: Hospitals, Clinics, Ambulance Services, Veterinary Clinics |
| Companies Covered | Ambu A/S, Intersurgical Ltd., Teleflex Incorporated, Medtronic plc, Smiths Medical, Drägerwerk AG & Co. KGaA, Cardinal Health Inc., GE HealthCare Technologies Inc., Medline Industries LP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anesthetic Gas Masks Market Emerging Trajectories
Silicone compounding automation and regulatory harmonization pressures are converging to reshape how anesthetic gas mask manufacturers structure production assets and certification timelines.
Closed-loop silicone injection molding with real-time viscosity monitoring is automating defect detection in high-throughput mask production. Tier-1 suppliers in Germany and the United States are deploying these systems to compress lot-release testing cycles. The technology is automating quality assurance labor out of extended-procedure mask categories where thickness uniformity directly impacts seal integrity.
EU MDR Article 10 clinical evaluation requirements are mandating post-market performance data for reusable mask classifications. Manufacturers with legacy CE-marked portfolios face retrospective documentation gaps that delay renewal approvals. Pediatric configurations with limited predicate-device histories are experiencing the most severe timeline compression as notified bodies demand prospective clinical evidence.
Hospital procurement departments are consolidating anesthesia consumables into single-source contracts with integrated workstation vendors. Independent mask distributors in the United States are losing shelf space as IDN-level agreements preference bundled supply. This concentration is most visible in multi-hospital systems across Texas and Florida where ambulatory expansion is driving standardized circuit procurement.
Anesthetic Gas Masks Market Segmentation
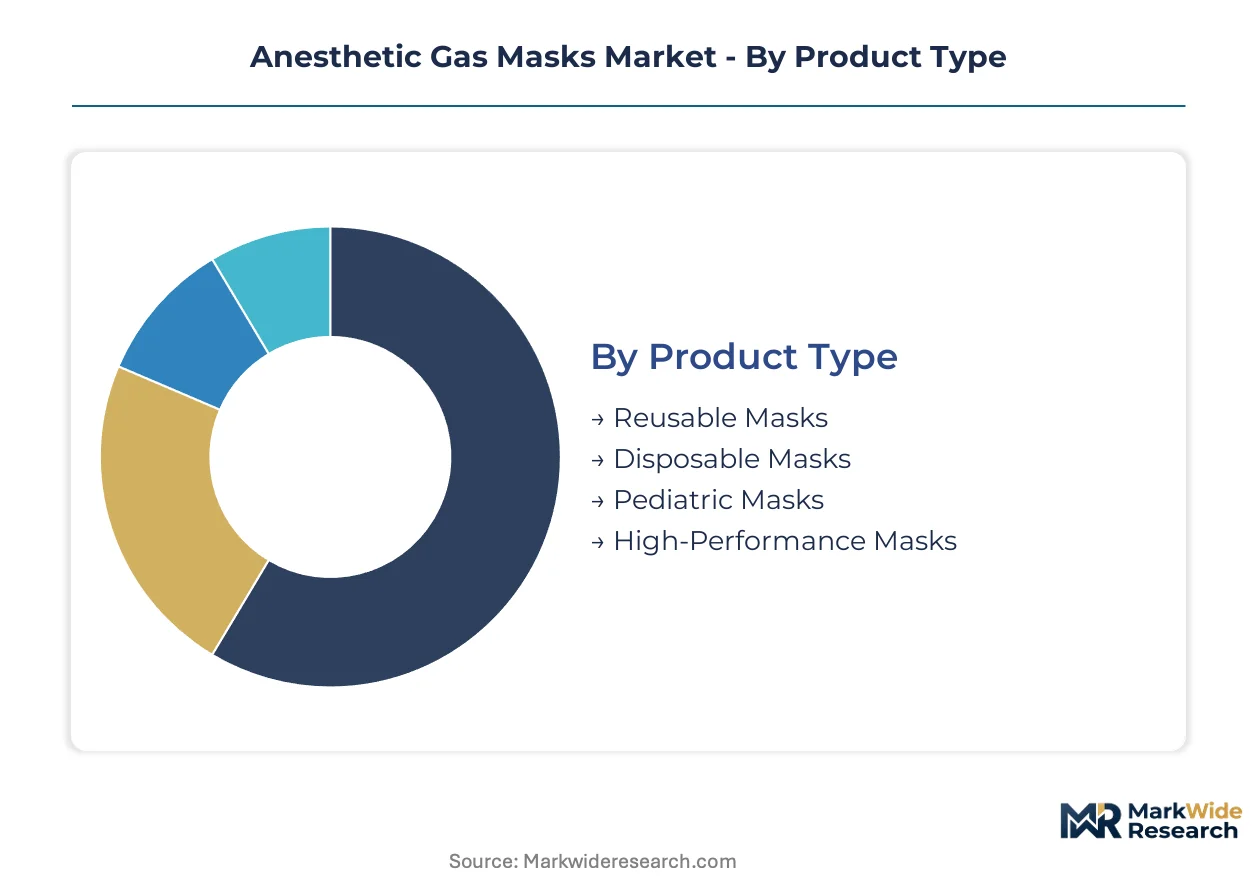
Anesthetic gas mask procurement stratifies sharply across durability tiers and patient risk profiles, with material selection and regulatory classification creating distinct margin architectures. Manufacturers must align production assets to either high-volume disposable workflows or precision-molded reusable categories with diverging certification burdens.
Product Type:
Disposable masks command volume leadership in ambulatory networks while reusable configurations retain premium positioning in academic medical centers with sterilization infrastructure.
- Disposable Masks:Single-use silicone or PVC constructions with 22-millimeter ISO connectors dominate hospital procurement due to cross-contamination protocols. Demand concentrates in United States ambulatory surgical centers where throughput maximization overrides per-unit cost sensitivity.
- Reusable Masks:Medical-grade silicone shells designed for 100+ autoclave cycles serve academic medical centers in Germany and Japan with captive sterilization departments. EU MDR clinical evidence requirements are extending renewal timelines for these classifications.
- Pediatric Masks:Dead-space minimized geometries for neonatal patients.
- High-Performance Masks:Integrated pressure monitoring ports for complex anesthesia workstations.
Today's leader: Disposable Masks. Tomorrow's challenger: Pediatric Masks.
Material:
Silicone anchors premium production while PVC serves cost-optimized bulk purchasing; alternative polymers capture niche allergic-patient segments.
- Silicone:Medical-grade platinum-cured formulations deliver biocompatibility and thermal stability for extended procedures. German and United States manufacturers maintain captive compounding to secure supply against semiconductor-grade silicone diversion.
- PVC:Plasticized polyvinyl chloride dominates high-volume procurement in China and India where per-procedure cost minimization governs purchasing. France's AGEC extended producer responsibility framework is creating compliance friction for PVC-dominant portfolios.
- Rubber:Latex-based constructions for legacy equipment compatibility.
- Polyurethane:Hypoallergenic alternative commanding pricing premiums in pediatric settings.
Silicone retains margin leadership. Polyurethane shows steepest expansion trajectory in allergy-protocol environments.
Application:
Surgical anesthesia generates baseline demand while emergency and veterinary channels diversify revenue exposure.
- Surgery:Controlled inhalation induction in operating theaters requires seal-optimized masks with pressure-limited ventilation compatibility. United States hospital surgical departments are standardizing on single-source contracts with integrated workstation vendors.
- Anesthesia:Pre-operative sedation and maintenance delivery in induction rooms.
- Emergency Care:Rapid-sequence intubation support in ambulance and trauma settings.
- Veterinary Use:Species-adapted geometries for companion animal and livestock procedures.
Surgery commands procurement volume. Emergency Care is gaining share fastest through pre-hospital network expansion.
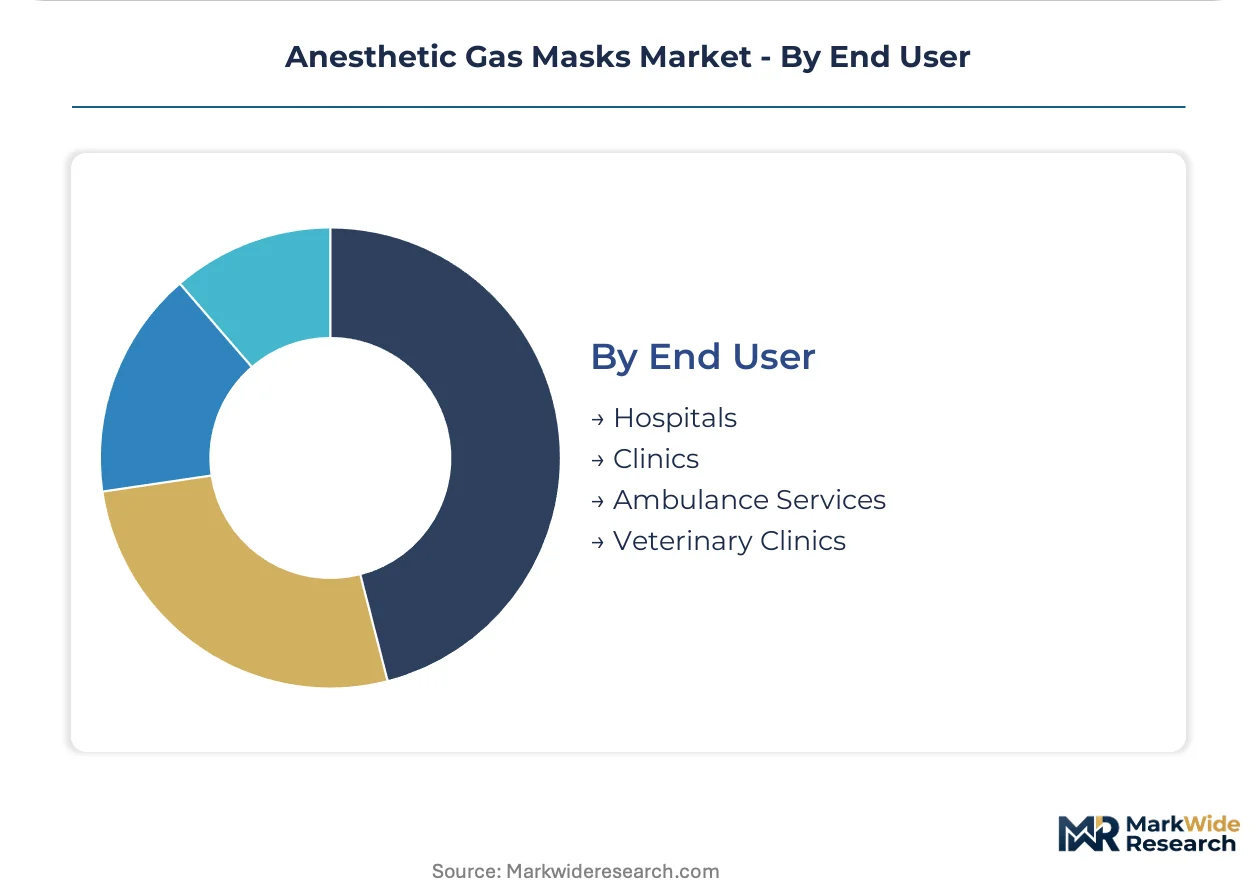
End User:
Hospital IDNs consolidate purchasing power while ambulatory and pre-hospital channels fragment procurement across regional distributors.
- Hospitals:Integrated delivery networks in Texas and Florida are bundling anesthesia consumables into workstation supply agreements, compressing independent distributor shelf space. Multi-hospital systems preference ISO 80369-7 connector compatibility for circuit standardization.
- Clinics:Outpatient procedure centers with limited sterilization capacity.
- Ambulance Services:Mobile emergency units requiring compact disposable inventories.
- Veterinary Clinics:Specialized practices with species-specific mask requirements.
Hospitals anchor contract value. Ambulance Services represent the most dispersed procurement challenge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling production toward jurisdictions with streamlined device clearance pathways, while mature markets impose heavier post-market surveillance burdens that extend commercialization timelines.
United States
FDA 510(k) clearance efficiency attracts manufacturers targeting hospital IDN procurement consolidation in Texas and Florida. The agency's predicate-device pathway compresses time-to-revenue for silicone mask submissions. Minneapolis and Boston anchor domestic production clusters serving integrated delivery networks with standardized circuit requirements.
Germany
EU MDR clinical evidence mandates extend renewal timelines for reusable mask classifications, favoring established players with retrospective documentation. Drägerwerk AG anchors European anesthesia workstation supply from Lübeck, integrating captive mask portfolios. Bavaria and Baden-Württemberg concentrate medical-grade silicone molding expertise.
China
NMPA GB standard compliance creates tiered market access timelines for imported anesthesia accessories. Domestic ambulatory surgical center expansion in Shanghai and Guangzhou drives disposable mask procurement. Yangtze River Delta manufacturers are upgrading polymer processing capabilities for higher-grade anesthetic delivery systems.
India
CDSCO regulatory alignment efforts are streamlining device import pathways for disposable mask suppliers. Underdeveloped day-surgery infrastructure in tier-2 cities creates first-mover positioning opportunities. Maharashtra and Gujarat medical device clusters are scaling ISO 13485-certified production for regional distribution.
Japan
PMDA quality management system requirements maintain high barriers for foreign mask manufacturers. Academic medical centers in Tokyo and Osaka retain preference for reusable silicone configurations with captive sterilization. Kanto region production assets serve domestic demand with limited export orientation.
Anesthetic Gas Masks Market Vendor Landscape
United States producers anchor one tier; European specialists hold integrated workstation positions; Asian fabricators compete on polymer processing scale. The vendor base stratifies across anesthesia machine OEMs with captive mask portfolios, independent disposable specialists, and regional distributors losing shelf space to IDN-level bundling. Three archetypes dominate: integrated workstation suppliers, single-use consumables specialists, and polymer-compounding manufacturers with backward integration. M&A activity concentrates on anesthesia machine OEMs consolidating supplier bases, while capacity expansion targets captive silicone compounding to eliminate external polymer dependency.
Among diversified medical technology conglomerates, Medtronic plc and GE HealthCare Technologies Inc. represent the integrated workstation tier with captive anesthesia delivery system portfolios. Drägerwerk AG & Co. KGaA exemplifies European specialization in integrated workstation supply. Intersurgical Ltd. occupies the independent disposable consumables position serving high-throughput surgical environments. These three anchors illustrate how competitive positioning stratifies between bundled system vendors and standalone mask suppliers.
| Leading Market Players |
|---|
| Ambu A/S |
| Intersurgical Ltd. |
| Teleflex Incorporated |
| Medtronic plc |
| Smiths Medical |
| Drägerwerk AG & Co. KGaA |
| Cardinal Health Inc. |
| GE HealthCare Technologies Inc. |
| Medline Industries LP |
| Others |
Supply Flow & Price Mechanics
Captive silicone compounding anchors both supply security and margin protection for manufacturers serving United States hospital IDNs, insulating them from petrochemical feedstock volatility while compressing procurement cycles for ambulatory surgical center networks.
Pricing Analysis
Distributor margin compression runs through independent mask suppliers as hospital IDNs consolidate anesthesia consumables into single-source workstation contracts. Contract-based long-term offtake dominates procurement between integrated workstation vendors and multi-hospital systems, while per-unit transactional pricing persists for regional ambulatory centers. Price differentiation hinges on ISO 80369-7 connector certification and captive polymer compounding capabilities. Cost compression in PVC-dominant portfolios intensifies because France's AGEC extended producer responsibility framework adds compliance overhead. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers with captive sterilization departments show lowest.
Supply Chain Analysis
Medical-grade silicone molding expertise concentrates in Germany, the United States, and Japan, constraining geographic diversification of production assets and tethering capacity expansion to these three manufacturing clusters. Raw material dependencies center on platinum-cured silicone formulations, semiconductor-grade polymer feedstocks, and 22-millimeter ISO-standard connector components. Single-source vulnerability persists for specialized molding equipment sourced from Bavaria and Baden-Württemberg. Distribution runs through integrated anesthesia workstation OEMs consolidating supplier bases, with independent distributors losing shelf space to IDN-level bundling agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where CDSCO regulatory alignment in India offers faster market access timelines against EU MDR clinical evidence burdens that extend European commercialization by 18-24 months.
For Market Incumbents: Cement captive silicone compounding capabilities to eliminate external polymer dependency against semiconductor-grade silicone diversion. Defend channel position by securing ISO 80369-7 connector compatibility with anesthesia machine OEMs consolidating supplier bases. Prioritize backward integration into medical-grade polymer processing to compress lot-release testing cycles and protect gross margins.
For New Entrants and Emerging Players: Ambulatory surgical center distributors in India's tier-2 cities represent the most penetrable channel partner type for first-mover positioning. Target CDSCO-compliant distribution partnerships in Maharashtra and Gujarat medical device clusters. Pursue polyurethane mask alternatives for pediatric and immunocompromised segments where latex-allergic protocols command pricing premiums.
For Investors and Strategic Acquirers: Roll-up economics work for independent disposable mask specialists because hospital IDN procurement consolidation is compressing independent distributor shelf space and creating captive channel access premiums. Target manufacturers with FDA 510(k) predicate-device histories and EU MDR technical documentation gaps requiring capital infusion. Watch NMPA GB standard compliance timelines for imported anesthesia accessories as inflection indicator for China market access velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Silicone Compounding | Eliminates semiconductor-grade polymer diversion risk for United States manufacturers. |
| FDA 510(k) Predicate Pathway | Compresses clearance timelines for silicone mask submissions targeting hospital IDNs. |
| EU MDR Technical Documentation | Extends renewal timelines for reusable classifications, favoring established players. |
| ISO 80369-7 Connector Compatibility | Secures bundled supply agreements with anesthesia workstation OEMs consolidating vendors. |
| CDSCO Distribution Partnership | Unlocks first-mover positioning in India's underdeveloped tier-2 ambulatory surgery infrastructure. |
Methodological Framework
Multiple input streams — primary interviews with anesthesia department heads, biomedical engineers, and GPO contracts managers; secondary validation through FDA 510(k) filings, EU MDR notified body documentation, and hospital procurement databases; plus customs records and medical device trade flows — were reconciled through bottom-up and top-down triangulation across the analysis window.
Historical shipment data cross-referenced against panel input from silicone compounding specialists and anesthesia workstation OEMs anchored the forecast framework. Segmentation dimensions modeled include product durability tier, material grade, patient risk profile, and regional regulatory cluster. CAGRs were derived from procedure volume trajectories and ambulatory surgical center expansion patterns across United States, German, and Chinese markets.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR clinical evidence burden evolution and NMPA GB standard enforcement intensity. Forecasts reflect assumptions about outpatient procedure volume continuity and polymer feedstock supply stability. Material deviation in semiconductor-grade silicone diversion rates or IDN procurement consolidation velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Global Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Motorcycle Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Chemical Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Respiratory Protection Equipment (RPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Seat Belt System Market
Safety Equipment and Personal Protective Equipment (PPE)
China Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Hearing Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Spill Kits Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Equipment Packaging Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Mirrors Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Eye Wash Stations Market
Safety Equipment and Personal Protective Equipment (PPE)
Hazardous Disposal Bag Market
Safety Equipment and Personal Protective Equipment (PPE)
Household Smart Safe Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Fall Protection Market