
 Europe Smart Lock Market | 2026-2036
Europe Smart Lock Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Smart Lock Market Insights
The EU Green Deal is repositioning smart lock procurement across European commercial real estate, as building owners retrofit properties to meet tightening energy and carbon benchmarks. Assa Abloy leverages its extensive patent portfolio to dominate premium integrated access systems for Nordic hospitality chains. Dormakaba anchors its position through deep channel control across German commercial distribution networks. Yale Locks competes aggressively in the UK residential retrofit segment with installer-friendly form factors.
A smart lock is an electromechanical locking device that authenticates users through wireless protocols—Bluetooth Low Energy, Wi-Fi, Z-Wave, or Zigbee—and motorized deadbolt actuation, typically operating on battery power with 6- to 12-month lifecycles depending on cycle frequency and radio configuration. Its primary commercial purpose is to replace mechanical key systems with credential-based entry logging, remote authorization, and integration with building management platforms. Deadbolt configurations currently occupy the largest installed base across European residential retrofits, while Z-Wave and Zigbee radios are gaining fastest in new commercial construction due to mesh-network reliability requirements and compatibility with existing building automation backbones. Bluetooth dominates the standalone consumer channel where smartphone-native credentialing eliminates hub infrastructure costs.
CE marking under the EU Radio Equipment Directive and cybersecurity certification emerging from ETSI EN 303 645 shape product compliance costs and market access timelines for non-European suppliers. The EU AI Act and GDPR intersect with smart lock deployments where biometric authentication or facial recognition handles entry credentialing, forcing explicit consent architectures and data localization provisions. Stakeholders must monitor whether the European Commission extends cybersecurity labeling mandates to IoT access hardware, as this would fragment certification requirements across member states and reshape competitive economics for mid-tier vendors.
Market Dynamics
The EU Green Deal is compressing procurement timelines for connected access hardware as commercial property owners face binding carbon reduction mandates and energy performance certificate upgrades. This regulatory pressure is cascading through hospitality, multifamily residential, and office retrofit channels, restructuring how building automation vendors specify locking infrastructure.
Growth Catalysts
- ETSI EN 303 645 certification:Emerging cybersecurity standards for IoT devices are creating procurement preference for pre-certified hardware, accelerating replacement cycles in German commercial real estate.
- Hospitality access automation:Nordic hotel chains are deploying integrated credential systems to eliminate front-desk bottlenecks and reduce staffing costs across seasonal demand fluctuations.
- Bluetooth Low Energy credentialing:Smartphone-native authentication is eliminating hub infrastructure requirements in UK residential retrofits, lowering total cost of ownership for installer networks.
Market Restraints
- Battery supply concentration:Lithium cell sourcing from East Asian suppliers creates input cost volatility and extended lead times for European assembly operations.
- CE marking complexity:The EU Radio Equipment Directive's evolving testing protocols extend certification timelines for new market entrants unfamiliar with notified body procedures.
- Mechanical key persistence:Fail-safe requirements in fire safety regulations mandate redundant mechanical override systems, limiting full-electronic penetration in heritage buildings.
Strategic Opportunities
- Polish multifamily housing:EU cohesion fund financing for building modernization is unlocking smart lock retrofits in Warsaw and Krakow residential towers.
- GDPR-compliant biometric integration:Facial recognition entry systems with explicit consent architectures are opening premium segments in Dutch corporate campuses.
- Z-Wave/Zigbee mesh convergence:Interoperability with existing building automation backbones is expanding addressable market for new commercial construction in France.
Industry Challenges
- Cybersecurity engineering talent:Shortage of embedded security specialists familiar with ETSI standards is constraining firmware development velocity for mid-tier vendors.
- Legacy access system integration:Proprietary protocols in installed building management platforms require custom middleware development, extending deployment timelines.
- Cross-border data localization:GDPR requirements for credential storage are forcing cloud architecture redesigns for vendors with centralized US-based infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Smart Lock Market |
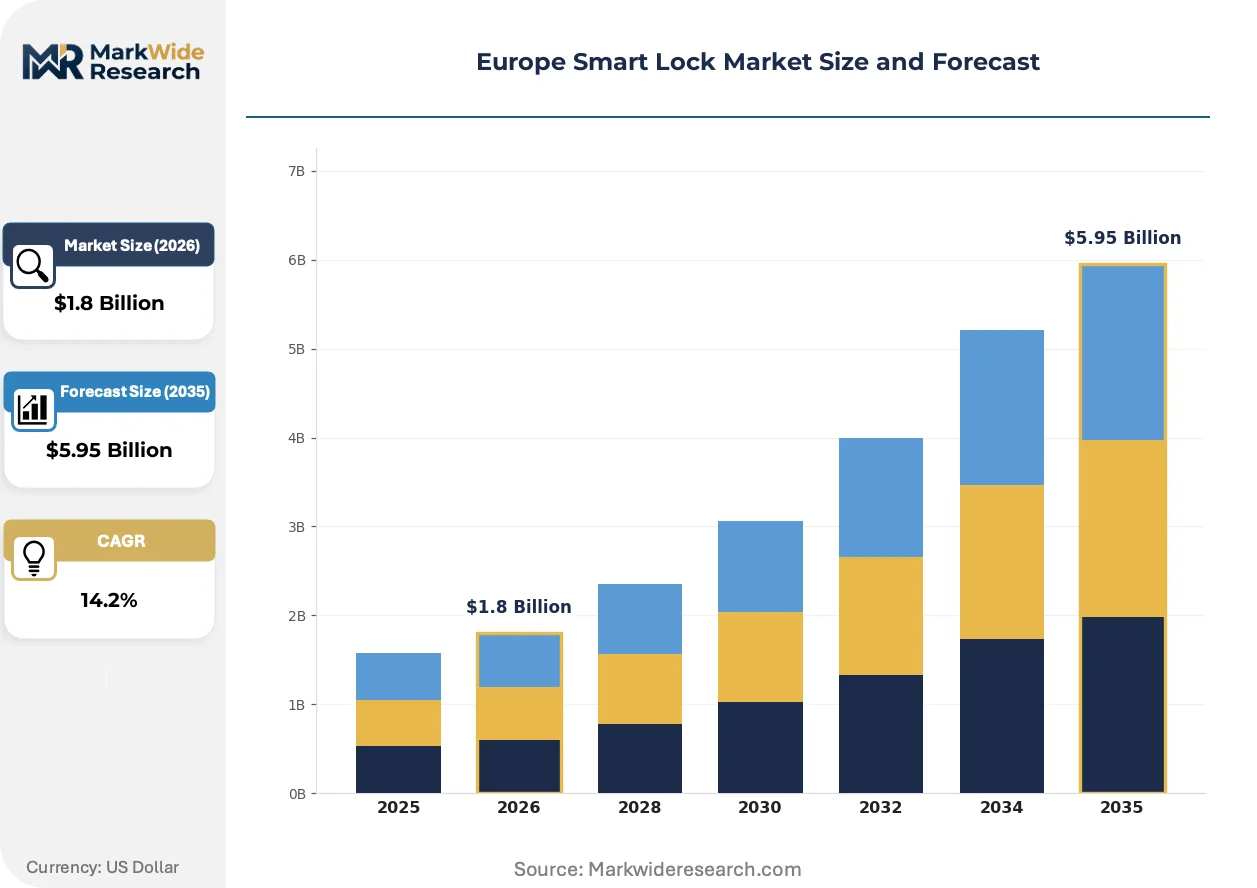
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Deadbolt, Lever Handle, Smart Knob, Padlock Technology: Bluetooth, Wi-Fi, Z-Wave, Zigbee End User: Residential, Commercial, Industrial, Retail Installation Type: New, Retrofit, Integrated, Standalone |
| Companies Covered | Salto Systems, Yale Locks, Assa Abloy, Spectrum Brands, Honeywell International, Dormakaba, Nuki Home Solutions, Master Lock Company, Allegion, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Smart Lock Market Trends and Innovations
Radio protocol diversification and cybersecurity certification are converging to reshape product architectures and procurement criteria across European access control channels.
Matter protocol support is expanding into smart lock firmware as a unifying layer above Bluetooth, Z-Wave, and Zigbee transports. Dutch smart home integrators are specifying Matter-compatible hardware to reduce interoperability service calls. This convergence is compressing vendor differentiation around proprietary ecosystems and forcing standardization investments.
The EU AI Act is imposing algorithmic transparency requirements on biometric authentication systems, forcing vendors to document training data provenance and decision logic. Systems deploying facial recognition must now maintain audit trails and enable human review of access denials. French commercial real estate developers are prioritizing vendors with pre-submitted conformity assessments to avoid construction timeline delays.
Building management platform unbundling is fragmenting procurement authority between facilities managers and IT security departments. German enterprise tenants are negotiating direct smart lock contracts separate from landlord-provided base building systems, creating channel conflict between hardware OEMs and system integrators. This organizational tension is most acute in Frankfurt and Munich flex-office deployments.
Europe Smart Lock Market Segmentation
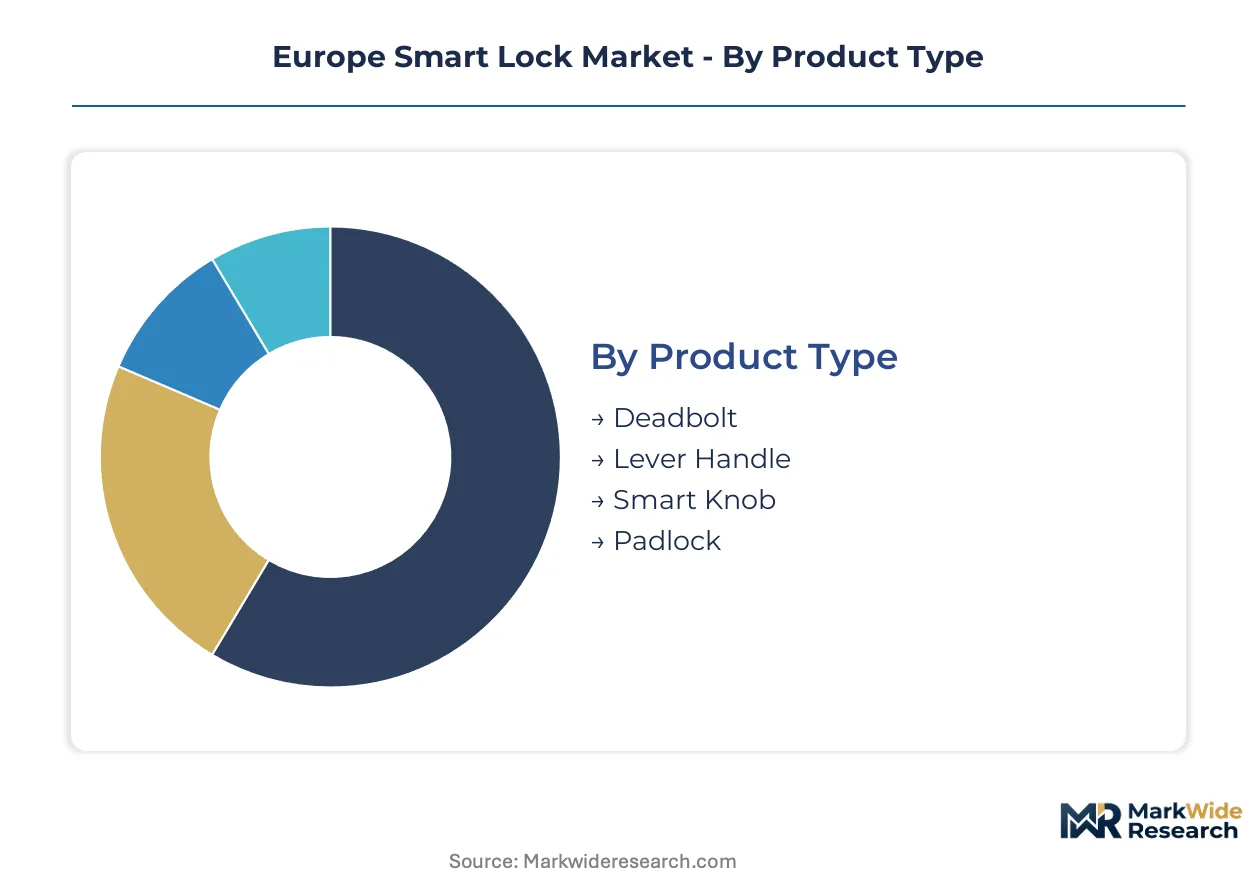
Smart lock procurement patterns diverge sharply across credentialing protocols, mounting configurations, and building automation integration requirements. European buyers prioritize radio compatibility with existing infrastructure over standalone feature sets, reshaping how vendors structure product portfolios.
Product Type:
Mechanical form factor determines retrofit feasibility, fire safety compliance, and aesthetic integration with European door standards.
- Deadbolt:Motorized single-point locking with hardened steel throw bolts dominates residential retrofits across Germany and France. CE marking under construction product regulations and compatibility with multi-point door systems drive specification in multifamily housing upgrades.
- Lever Handle:Integrated clutch mechanisms with ANSI/BHMA Grade 2 durability standards capture commercial office demand in London and Frankfurt. Facilities managers specify lever formats for ADA-equivalent accessibility compliance and high-traffic durability.
- Smart Knob:Cylindrical locksets with embedded credential readers serve interior residential doors and hospitality suites where space constraints limit deadbolt depth.
- Padlock:Weatherized battery compartments and shrouded shackles address utility infrastructure, construction sites, and outdoor storage applications across Nordic climates.
Deadbolt leads on scale; lever handle leads on momentum.
Technology:
Radio selection cascades through hub requirements, power budgets, and building automation compatibility matrices.
- Bluetooth:Low Energy 5.0 stacks with smartphone-native credentialing eliminate gateway infrastructure in UK residential installer networks. Battery lifecycles extend to 12 months with typical residential cycle frequencies, reducing service call costs.
- Wi-Fi:Direct IP connectivity enables cloud-managed access logging without intermediary hubs, though power consumption constrains battery size and cycle frequency in high-traffic commercial deployments.
- Z-Wave:Sub-GHz mesh networking with 100-meter range specifications integrates with existing building automation backbones in French new commercial construction. S2 security frameworks address ETSI cybersecurity certification requirements.
- Zigbee:2.4 GHz mesh protocols with Thread interoperability emerging align with Dutch smart home integrator specifications for unified lighting and access control platforms.
Bluetooth dominates volume; Z-Wave climbs the fastest on commercial construction specifications.
End User:
Procurement authority and compliance obligations fragment across owner-occupied, tenant-facing, and operational technology contexts.
- Residential:Single-family and multifamily owner-occupiers prioritize smartphone credentialing and temporary access sharing for service providers across UK retrofit channels.
- Commercial:Corporate real estate operators in Frankfurt and Munich negotiate direct smart lock contracts separate from landlord base building systems, creating channel conflict.
- Industrial:Manufacturing facilities and logistics hubs specify IP65 environmental ratings and audit-trail integration with workforce management platforms.
- Retail:Franchise operators and high-street chains deploy centralized access management across dispersed locations with time-based credentialing for shift workers.
Residential commands absolute volume; commercial expands most quickly on flex-office automation.
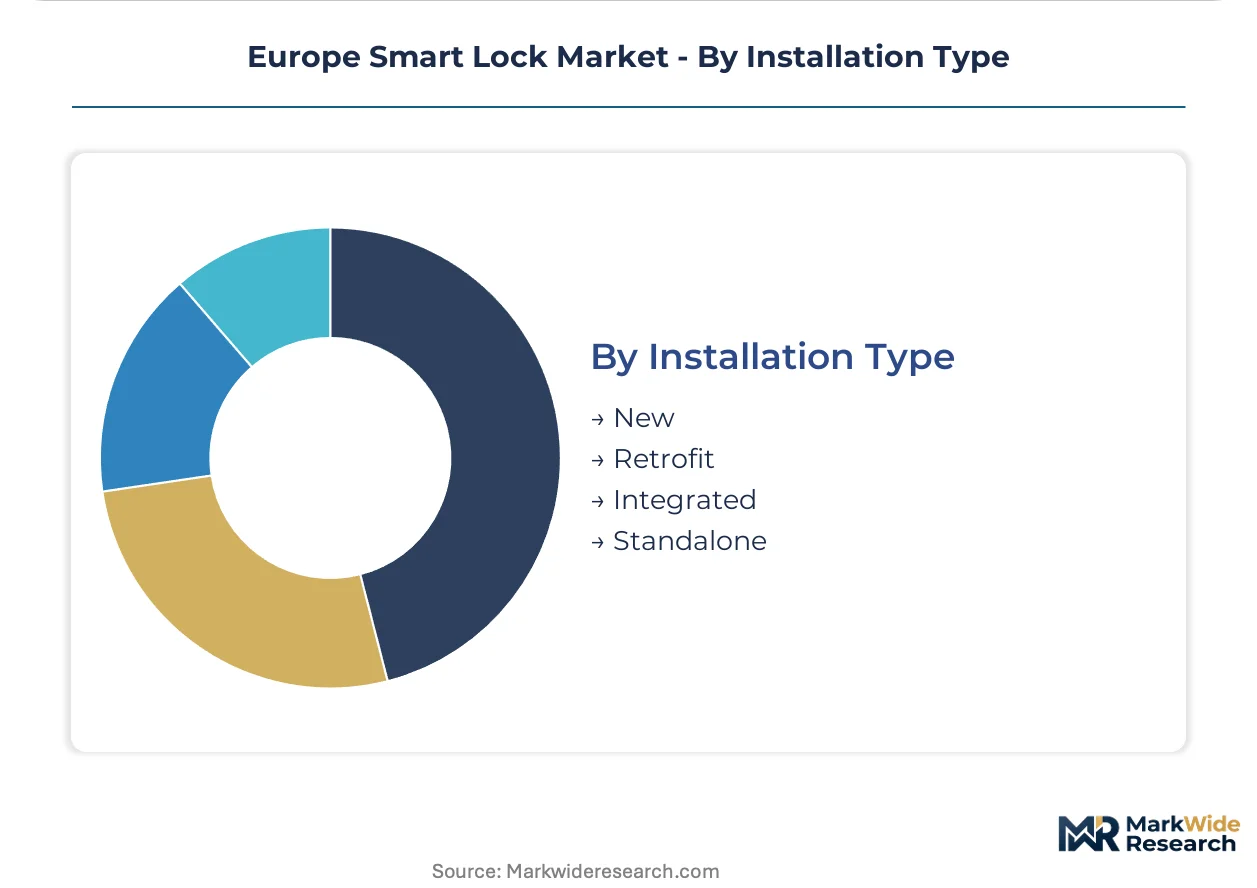
Installation Type:
Deployment context determines mechanical compatibility requirements, electrical integration scope, and procurement stakeholder alignment.
- New:Greenfield construction specifications in France and Germany embed smart locks during door fabrication, enabling concealed wiring and power-over-Ethernet options.
- Retrofit:Battery-powered deadbolt replacements dominate European residential aftermarket, constrained by existing cylinder formats and fire door certification retention.
- Integrated:Hardwired connections to building management platforms serve enterprise campuses and hospitality chains with unified HVAC, lighting, and access control.
- Standalone:Hub-independent operation with local credential storage addresses GDPR data localization requirements and connectivity-uncertain environments.
Retrofit anchors current volume; integrated gains share fastest on EU Green Deal building automation mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Embedded firmware engineers and IoT security specialists cluster in southern Germany and the Netherlands, anchoring European smart lock development capacity. This talent concentration shapes regional competitive advantages in cybersecurity certification and building automation integration. National regulatory frameworks and urban construction cycles then determine deployment velocity across member states.
Germany
Frankfurt and Munich flex-office operators negotiate direct smart lock contracts separate from landlord base building systems. CE marking under the EU Radio Equipment Directive extends certification timelines for hardware unfamiliar with notified body procedures. Bavarian industrial zones host assembly operations constrained by lithium cell sourcing volatility from East Asian suppliers.
United Kingdom
Residential installer networks prioritize Bluetooth Low Energy credentialing to eliminate hub infrastructure costs. GDPR requirements for credential storage force cloud architecture redesigns for vendors with centralized infrastructure. London commercial real estate channels demand lever-handle formats for ADA-equivalent accessibility compliance in high-traffic deployments.
France
New commercial construction specifications embed Z-Wave mesh networking for compatibility with existing building automation backbones. The EU AI Act imposes algorithmic transparency requirements on biometric authentication systems deployed in corporate campuses. Paris and Lyon developers prioritize vendors with pre-submitted conformity assessments to avoid construction timeline delays.
Netherlands
Dutch smart home integrators specify Matter-compatible hardware to reduce interoperability service calls. Facial recognition entry systems with explicit consent architectures open premium segments in corporate campuses under GDPR. Eindhoven and Randstad regions concentrate firmware development talent for S2 security framework implementation.
Poland
EU cohesion fund financing for building modernization unlocks smart lock retrofits in Warsaw and Krakow residential towers. Battery-powered deadbolt replacements dominate the aftermarket constrained by existing cylinder formats. Polish assembly operations benefit from proximity to German distribution networks while managing extended lead times for lithium cell inputs.
Europe Smart Lock Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the European smart lock landscape. Assa Abloy and Dormakaba anchor the premium integrated access segment through deep channel control and patent portfolios. Mid-tier vendors concentrate on installer-friendly form factors for residential retrofit channels. Strategic moves center on cybersecurity certification pre-emption and Matter protocol standardization investments.
Among Nordic-origin access control specialists, Salto Systems exemplifies the hospitality automation archetype through integrated credential systems. Yale Locks occupies a position within the UK residential retrofit tier, while Nuki Home Solutions represents the standalone consumer channel where smartphone-native credentialing eliminates hub infrastructure. Dormakaba anchors the German commercial distribution network tier. Allegion and Spectrum Brands sit within the multinational hardware conglomerate archetype competing across multiple European jurisdictions.
| Leading Market Players |
|---|
| Salto Systems |
| Yale Locks |
| Assa Abloy |
| Spectrum Brands |
| Honeywell International |
| Dormakaba |
| Nuki Home Solutions |
| Master Lock Company |
| Allegion |
| Others |
Pricing and Supply Chain Analysis
Lithium cell costs from East Asian suppliers cascade through European assembly operations into tiered hardware pricing, with battery chemistry grade and cybersecurity certification tier separating premium integrated systems from standalone residential units.
Pricing Analysis
Bundled subscription models for cloud-managed access logging command recurring revenue streams from hospitality chains and corporate campuses, while unbundled transactional hardware sales dominate UK residential installer networks. Price differentiation hinges on ETSI EN 303 645 certification status and Matter protocol compatibility, with pre-certified hardware capturing procurement preference in German commercial real estate. Cost compression in the mid-tier segment intensifies as Polish assembly operations compete on proximity to German distribution networks. Residential retrofit buyers exhibit highest price sensitivity, while Dutch corporate campuses prioritize GDPR-compliant biometric integration regardless of premium positioning.
Supply Chain Analysis
CE marking under the EU Radio Equipment Directive gates market access for non-European suppliers, extending certification timelines and concentrating procurement among pre-qualified vendors. Manufacturing draws from East Asian lithium cell suppliers, German precision motor fabricators, and Nordic firmware development clusters. Single-source vulnerability persists in battery chemistry supply, with concentrated East Asian production exposing European assemblers to input cost volatility. Distribution runs through German commercial distribution networks for integrated systems and UK installer channels for standalone residential units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Smart Lock Market operates as a regulatory compounder, with EU Green Deal carbon reduction mandates and ETSI cybersecurity certification requirements continuously restructuring procurement criteria and replacement cycles.
For Market Incumbents: Extend patent portfolio leverage into Matter protocol standardization investments to defend against proprietary ecosystem compression. Deepen channel control across German commercial distribution networks to counter enterprise tenants negotiating direct contracts. Prioritize ETSI EN 303 645 pre-certification to accelerate replacement cycles in carbon-mandated retrofit channels. For New Entrants and Emerging Players: Launch via Polish assembly partnerships targeting EU cohesion fund-financed residential tower retrofits in Warsaw and Krakow. Penetrate the UK installer network tier with Bluetooth-native credentialing that eliminates hub infrastructure costs. White-space opportunity concentrates in GDPR-compliant standalone systems for connectivity-uncertain environments. For Investors and Strategic Acquirers: Roll-up economics work for cybersecurity-certified firmware specialists because ETSI standards scarcity constrains mid-tier vendor development velocity. Five-to-ten-year viability favors vendors with pre-submitted EU AI Act conformity assessments for biometric systems. Watch for European Commission extension of cybersecurity labeling mandates to IoT access hardware as inflection trigger.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Integration | Dutch smart home integrators specify unified hardware to reduce interoperability service calls. |
| ETSI Certification Pre-emption | German commercial real estate procurement preference accelerates replacement cycles for pre-certified vendors. |
| GDPR-Compliant Biometric Development | Explicit consent architectures open premium segments in Dutch corporate campuses under AI Act transparency requirements. |
| Polish Assembly Footprint Expansion | Proximity to German distribution networks captures EU cohesion fund residential modernization financing. |
| Channel Control Deepening | Direct enterprise tenant contracts in Frankfurt flex-offices counter landlord base building system fragmentation. |
Research Methodology
Bottom-up building automation specification modeling reconciled against top-down radio protocol shipment tracking forms the analytical core of this study. Primary interviews with facilities managers, smart home integrators, embedded firmware engineers, and commercial distribution channel heads combined with secondary validation against CE marking databases, ETSI certification registries, EU funding disbursement records, and building energy performance certificate upgrade timelines. Cross-referencing against customs data for lithium cell imports and Z-Wave Alliance membership directories enabled triangulation between demand-side procurement patterns and supply-side manufacturing concentration.
Input-output matrices map credentialing protocol adoption rates through installation type segments across the projection horizon. Segmentation dimensions modeled include radio technology, mechanical form factor, end-user category, and building automation integration depth. CAGRs derive from regression analysis of replacement cycle acceleration under regulatory mandate pressure, with EU Green Deal compliance timelines and ETSI certification penetration curves as primary forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended CE marking timeline revisions or lithium supply disruption scenarios. Model assumptions reflect documented regulatory milestone schedules and notified body capacity constraints. A model refresh is warranted upon material change in European Commission cybersecurity labeling mandate scope or EU AI Act biometric enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Latin America Proximity Access Control Market
Access Control Systems
Global Fingerprint Access Control Systems Market
Access Control Systems
Latin America Pin-Based Access Control Market
Access Control Systems
North America Access Control Market
Access Control Systems
Facial Recognition Access Control Solution Market
Access Control Systems
Middle East and Africa Proximity Access Control Market
Access Control Systems
South Korea Access Control Market
Access Control Systems
Canada Access Control Market
Access Control Systems
GPS Smart Locks Market
Access Control Systems
APAC Home Security System Market
Access Control Systems
Network Access Control Market
Access Control Systems
Asia-Pacific Proximity Access Control Market
Access Control Systems
Global Digital Door Lock Systems Market
Access Control Systems
Door Controller Systems Market
Access Control Systems
Middle-East and Africa Airport Passenger Screening Systems Market
Access Control Systems
Indoor Electromagnetic Lock Market