
 Europe Safety Instrumented Systems Market | 2026-2036
Europe Safety Instrumented Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Safety Instrumented Systems Market Foresight
Silicon carbide-based safety sensor substrates is shifting from niche aerospace applications into mainstream European process industries, cutting failure rates under high-temperature conditions. Siemens AG leverages vertical integration across sensor fabrication and safety controller assembly to dominate German chemical corridor procurement. ABB Ltd anchors its position through IEC 61511-certified engineering centers in Switzerland and Sweden. HIMA Paul Hildebrandt GmbH specializes in SIL 3-certified platforms for offshore North Sea installations, competing on functional safety depth rather than portfolio breadth.
Safety instrumented systems comprise sensor-to-actuator loops engineered to achieve specified safety integrity levels, with architectures rated SIL 1 through SIL 4 per IEC 61508 depending on probability of dangerous failure thresholds. These systems execute automatic protective responses when process variables exceed safe operating limits, preventing catastrophic releases in hazardous facilities. Safety controllers capture the largest margin pool among product categories due to firmware complexity and recertification barriers. Wireless technology segments are expanding fastest as Norwegian and UK North Sea operators retrofit aging platforms without pulling new cable through congested conduit. Integrated solutions spanning sensors, logic solvers, and final control elements concentrate R&D investment at Schneider Electric SE and Emerson Electric Co.
EU Seveso III Directive enforcement through national competent authorities in Germany, France, and the Netherlands mandates systematic safety management for upper-tier establishments, directly driving SIS expenditure. IEC 61511 second edition compliance requirements, interpreted by DEKRA and TÜV Rheinland as notified bodies, shape product design specifications and market access conditions across member states. ECHA REACH restrictions on legacy flame retardants in cable insulation are forcing material transitions with recertification timelines. Stakeholders must monitor the EU Cyber Resilience Act's emerging conformity framework, as safety controllers with embedded connectivity face overlapping functional safety and cybersecurity compliance obligations.
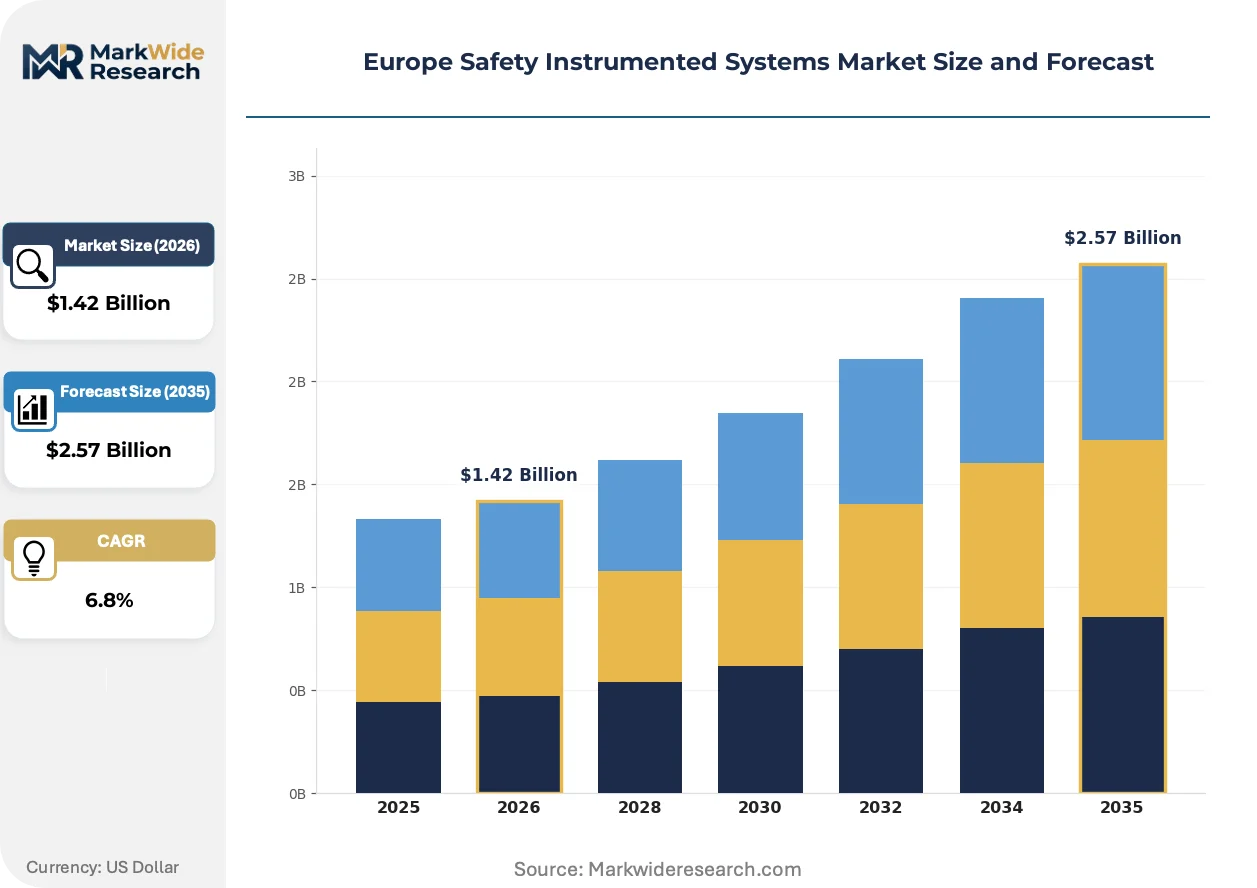
Market Dynamics
Wireless safety sensor architectures are compressing retrofit timelines across Europe's congested brownfield installations, eliminating cable pulls through saturated conduit systems while forcing incumbent hardwired suppliers to recertify wireless-native platforms.
Growth Catalysts
- EU Seveso III Directive enforcement:National competent authorities in Germany, France, and the Netherlands mandate systematic safety management for upper-tier establishments, directly accelerating SIS procurement cycles in chemical processing and hydrocarbon storage.
- Silicon carbide substrate adoption:High-temperature process environments in refineries and petrochemical crackers are migrating to SiC-based sensors, cutting dangerous failure rates under thermal stress that degrades conventional silicon alternatives.
- North Sea platform aging:Norwegian and UK offshore operators face escalating maintenance burdens on legacy hardwired systems, creating replacement demand that bypasses traditional cable infrastructure entirely.
Market Restraints
- Copper and rare earth price volatility:Sensor coil windings and magnet assemblies depend on lanthanide concentrates primarily processed through Chinese refining complexes, exposing European fabricators to input cost swings without contractual hedging mechanisms.
- TÜV Rheinland and DEKRA certification bottlenecks:IEC 61508 and IEC 61511 recertification queues for modified safety controllers extend twelve to eighteen months, freezing product releases and compressing vendor revenue recognition windows.
- Functional safety-cybersecurity overlap:The EU Cyber Resilience Act's emerging conformity framework imposes dual compliance obligations on connected safety controllers, multiplying engineering validation costs without harmonized testing protocols.
Strategic Opportunities
- Polish and Romanian chemical corridor expansion:EU cohesion fund investments in Central European petrochemical clusters are greenlighting new-build facilities without legacy system baggage, favoring integrated wireless-native SIS architectures from project inception.
- Carbon capture integration:Amine-based CO2 capture skids at refineries and cement plants require dedicated safety loops for toxic release prevention, opening application-specific sensor and valve configurations absent from standard hydrocarbon portfolios.
- Outcome-based maintenance contracting:UK North Sea operators are piloting availability-guarantee agreements where SIS vendors assume operational responsibility, shifting revenue from hardware shipment to performance-based service fees.
Industry Challenges
- SIL 3 firmware engineering scarcity:Embedded systems developers with dual competence in functional safety mathematics and real-time operating systems command premium compensation, constraining vendor R&D throughput and platform refresh cadence.
- Legacy system integration complexity:Brownfield installations running 1990s-era proprietary safety buses resist seamless migration to IEC 62443-compliant Ethernet architectures, forcing costly gateway development or complete loop replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Safety Instrumented Systems Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Safety Sensors, Safety Controllers, Safety Actuators, Software End User: Oil & Gas, Chemical, Power Generation, Pharmaceutical Technology: Hardwired, Software-based, Wireless, Integrated Solutions Installation Type: Onshore, Offshore, Industrial Facility, Residential Facility |
| Companies Covered | Siemens AG, ABB Ltd, Schneider Electric SE, Emerson Electric Co, Honeywell International, Rockwell Automation, Yokogawa Electric Corporation, OMRON Corporation, HIMA Paul Hildebrandt GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Safety Instrumented Systems Market Shifts & Advancements
Three intersecting developments are compressing product lifecycles and rewiring competitive advantage: materials science breakthroughs in extreme-environment sensing, regulatory frameworks forcing cybersecurity-functional safety convergence, and procurement models that transfer operational risk to equipment vendors.
Silicon carbide-based sensor substrates are rewriting the thermal performance envelope for European process industries. These ceramic semiconductor platforms maintain signal integrity above 600°C where silicon devices fail catastrophically. German chemical manufacturers operating high-temperature crackers and reformers are specifying SiC sensors for SIL 2 and SIL 3 loops, compressing the addressable market for conventional sapphire and platinum-rhodium alternatives that dominated prior decades.
REACH restrictions on legacy halogenated flame retardants in cable insulation are forcing material transitions with cascading recertification obligations. ECHA's sunset dates for decaBDE and HBCDD compounds are compelling cable suppliers to validate phosphate-ester and metal-hydroxide alternatives under IEC 61508 fire-resistance protocols. Safety controller vendors with captive cable manufacturing are absorbing these timeline impacts internally, while pure-play logic solver suppliers face supplier qualification delays that freeze platform releases.
Integrated safety-IT convergence is fragmenting traditional procurement channels. End-users are consolidating vendor relationships around platforms that unify process safety, asset performance management, and cybersecurity under single-pane dashboards. Norwegian offshore operators are leading this consolidation, specifying IEC 62443-3-3 SL3-certified safety controllers with embedded OPC UA connectivity that feeds directly into digital twin environments, bypassing the systems integrators that historically mediated safety and automation procurement decisions.
Europe Safety Instrumented Systems Market Segmentation
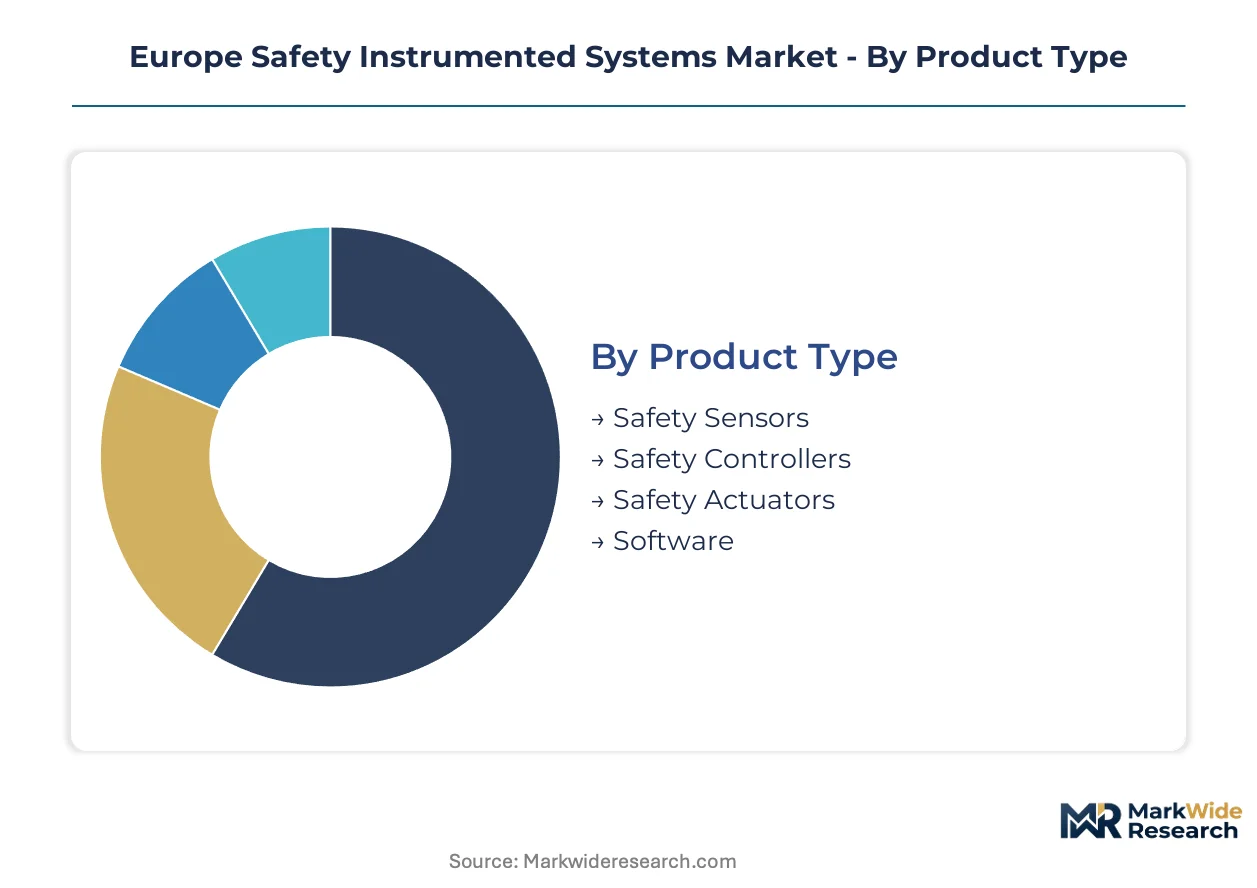
Segmentation in European safety instrumented systems reveals distinct procurement patterns across product architectures, end-use risk profiles, and installation constraints. Buyers prioritize certification depth over feature breadth in high-consequence applications, while retrofit economics reshape technology preferences in brownfield corridors.
Product Type:
Procurement economics diverge sharply between component buyers seeking interoperability and integrated platform purchasers optimizing for single-vendor accountability.
- Safety Sensors:Devices detect process deviations through pressure, temperature, level, and flow measurement, converting physical variables into safety-critical signals. German chemical manufacturers specify silicon carbide substrates for high-temperature crackers above 600°C, where conventional silicon fails thermally. Volume sits with safety sensors; growth tilts toward wireless-native architectures.
- Safety Controllers:Logic solvers execute voting algorithms and output commands to final control elements, with firmware complexity creating recertification barriers that protect incumbent positions. Norwegian North Sea operators demand IEC 62443-3-3 SL3 certification with embedded OPC UA connectivity for digital twin integration.
- Safety Actuators:Final control elements including emergency shutdown valves and trip systems physically terminate hazardous conditions upon controller command.
- Software:Configuration, diagnostics, and proof-testing applications reduce manual validation labor while introducing cybersecurity exposure under EU Cyber Resilience Act conformity frameworks.
Margin capture concentrates in safety controllers; sensor commoditization accelerates among wireless entrants.
End User:
Risk tolerance and regulatory scrutiny intensity separate buyers, with upper-tier Seveso III establishments facing mandatory systematic safety management.
- Oil & Gas:Upstream, midstream, and downstream operations deploy SIL 3 loops for blowout prevention and overpressure protection. UK and Norwegian offshore operators drive wireless retrofit demand to bypass cable replacement in congested platform infrastructure. Procurement scale favors integrated platform vendors over component specialists.
- Chemical:Process plants handling toxic, flammable, or explosive materials anchor European SIS demand under Seveso III enforcement through German, French, and Dutch competent authorities. German chemical corridor procurement concentrates around vertically integrated suppliers with captive sensor fabrication.
- Power Generation:Conventional and nuclear facilities require safety loops for turbine protection and reactor trip systems, with nuclear applications demanding additional national regulatory approvals beyond IEC 61508 baseline.
- Pharmaceutical:Batch processing and sterile manufacturing applications prioritize contamination prevention alongside personnel safety, with PAT (Process Analytical Technology) integration creating hybrid quality-safety system requirements.
Revenue concentration rests with oil and gas; chemical sector procurement expands most quickly under tightening Seveso III interpretations.
Technology:
Architecture selection hinges on installation constraints, with brownfield congestion forcing technology transitions that greenfield projects avoid.
- Hardwired:Traditional copper-cable architectures dominate legacy installations but face REACH-driven material transitions as ECHA sunset dates eliminate decaBDE and HBCDD flame retardants.
- Software-based:Programmable safety platforms enable flexible logic modification without hardware replacement, though firmware recertification through TÜV Rheinland and DEKRA extends twelve to eighteen months.
- Wireless:ISA100.11a and WirelessHART safety protocols eliminate cable pulls through saturated conduit, compressing North Sea platform retrofit timelines. Norwegian and UK operators specify wireless-native platforms for aging infrastructure replacement.
- Integrated Solutions:Unified sensor-controller-actuator platforms with embedded cybersecurity consolidate vendor relationships and reduce systems integrator mediation. Schneider Electric and Emerson Electric concentrate R&D investment here.
Installed base remains hardwired; wireless and integrated solutions climb the fastest.
Installation Type:
Physical environment severity and accessibility constraints determine technology durability requirements and maintenance economics.
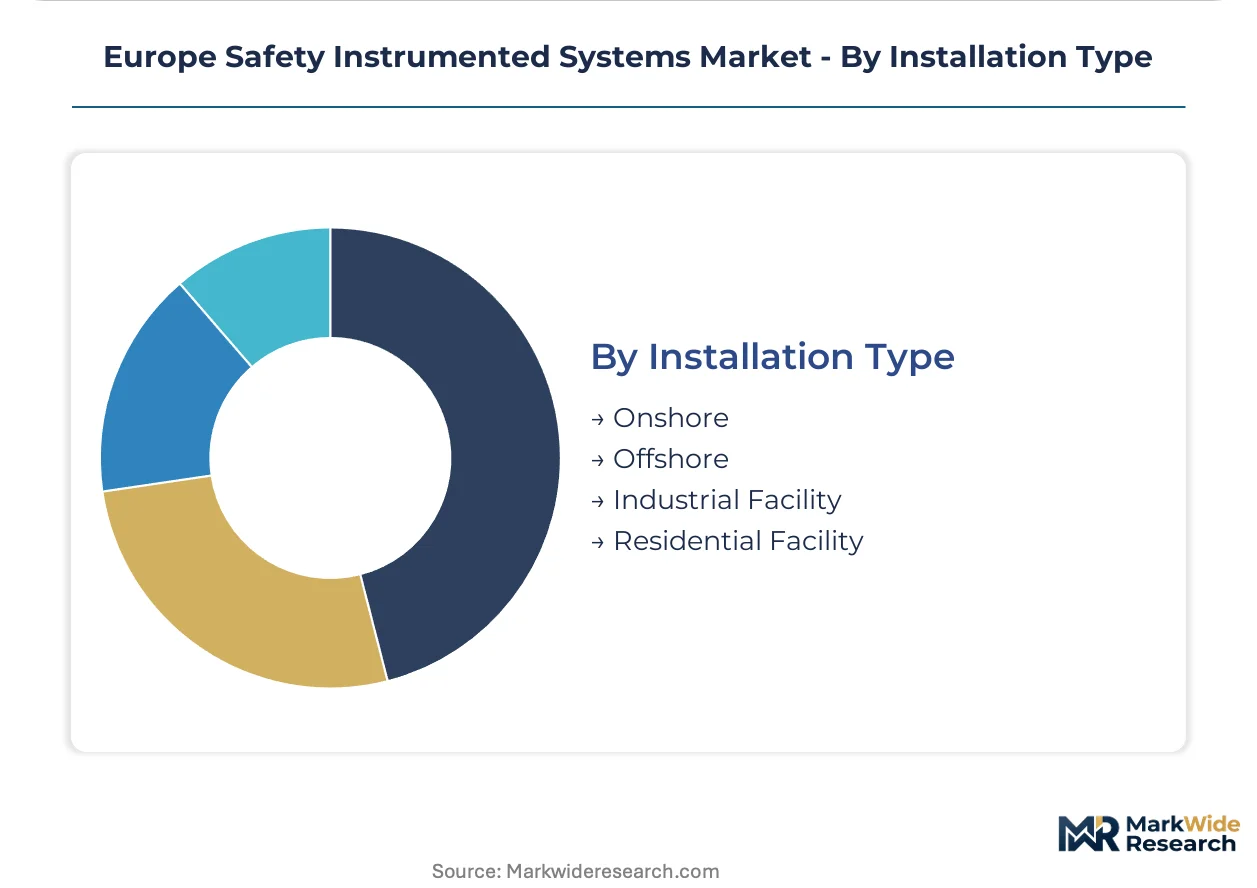
- Onshore:Refineries, chemical plants, and manufacturing facilities with controlled environments favor standard industrial enclosures and scheduled maintenance access.
- Offshore:North Sea platforms expose equipment to salt spray, vibration, and limited logistics windows, demanding marine-grade enclosures and remote diagnostics capability. HIMA Paul Hildebrandt specializes in SIL 3 platforms for these installations.
- Industrial Facility:Broad category encompassing manufacturing, warehousing, and processing operations with varying hazard classifications and safety integrity requirements.
- Residential Facility:Building automation and district heating applications with lower SIL requirements but growing cybersecurity exposure under EU Cyber Resilience Act scope expansion.
Complexity and margin pool center on offshore; standardization pressures compress pricing in onshore industrial facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European SIS procurement concentrates in the chemical corridor stretching from the Netherlands through Germany to Switzerland, with North Sea offshore operations generating specialized demand for marine-certified platforms.
Germany
Ludwigshafen and Leverkusen chemical clusters anchor continental demand for SIL 3-certified systems in high-temperature crackers. The Federal Ministry for the Environment enforces Seveso III through state-level authorities, mandating systematic safety management for upper-tier establishments. Bavarian sensor fabricators supply silicon carbide substrates that cut failure rates above 600°C.
United Kingdom
Aberdeen and the wider Scottish offshore sector drive wireless retrofit demand as aging North Sea platforms bypass cable replacement. The Health and Safety Executive interprets Seveso III through the Control of Major Accident Hazards Regulations, shaping procurement specifications for hydrocarbon facilities. Thames Corridor refineries are integrating carbon capture skids with dedicated safety loops for toxic release prevention.
Netherlands
Rotterdam's petrochemical complex generates concentrated demand for integrated safety-IT platforms with embedded cybersecurity. The Ministry of Infrastructure and Water Management coordinates Seveso III enforcement through the Environment and Transport Inspectorate, accelerating SIS expenditure in storage and processing terminals. Eindhoven-region engineering centers specialize in ISA100.11a wireless protocol implementation for brownfield congestion.
Norway
Stavanger and Oslofjord offshore operators pioneer availability-guarantee contracting models that shift operational risk to equipment vendors. The Petroleum Safety Authority mandates functional safety compliance through national regulations aligned with IEC 61511, driving replacement of 1990s-era proprietary safety buses. Integrated solutions with OPC UA connectivity for digital twin environments dominate new procurement.
France
Lyon and Normandy chemical manufacturers face tightening interpretations of Seveso III through the Ministry of Ecological Transition's regional directorates. The Autorité de Sûreté Nucléaire imposes additional certification layers on safety systems serving nuclear-adjacent industrial facilities. Paris Basin pharmaceutical processors are specifying hybrid quality-safety systems for PAT integration in sterile manufacturing.
Europe Safety Instrumented Systems Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform vendors capturing premium positions in greenfield projects while component specialists defend retrofit niches. The vendor base organizes around three strategic archetypes: vertically integrated industrial conglomerates with captive sensor fabrication, pure-play functional safety specialists competing on certification depth, and automation generalists leveraging cross-selling from process control portfolios. Dominant competitive moves include backward integration into semiconductor substrates and strategic partnerships to compress IEC 61508 recertification timelines.
Among German-based fabricators, Siemens AG and HIMA Paul Hildebrandt GmbH occupy distinct positioning within the safety controller segment. Swiss-Swedish ABB Ltd exemplifies the automation generalist archetype, leveraging IEC 61511-certified engineering centers to anchor regional procurement decisions. These three entities represent the primary competitive anchors against which specialized entrants and integrated challengers must differentiate.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd |
| Schneider Electric SE |
| Emerson Electric Co |
| Honeywell International |
| Rockwell Automation |
| Yokogawa Electric Corporation |
| OMRON Corporation |
| HIMA Paul Hildebrandt GmbH |
| Others |
Supply & Pricing Matrix
Silicon carbide substrate migration from aerospace into European process industries is compressing cost curves for high-temperature safety sensors while concentrating fabrication capability among Bavarian semiconductor specialists. This materials transition simultaneously elevates performance premiums for SiC-certified loops and reduces supplier diversity as legacy silicon sensor vendors exit thermal-extreme segments.
Pricing Analysis
Volume concentrates in safety sensors while margin capture tilts toward safety controllers with firmware complexity barriers. Three-tier pricing structure across SIL 4 premium, SIL 3 standard, and SIL 2 economy certification levels separates German chemical corridor procurement from budget-constrained Eastern European retrofits. Pricing pressure stems from wireless-native entrants compressing hardware premiums in North Sea brownfield projects. Chemical manufacturers show lowest price sensitivity given Seveso III compliance mandates; residential facility buyers exhibit highest elasticity.
Supply Chain Analysis
Refurbishment flows for legacy safety controllers extend product lifecycles in UK North Sea installations, creating secondary parts markets that compete with new equipment vendors. German sensor fabrication, Swiss controller assembly, and Chinese rare earth processing anchor upstream concentration. Lanthanide concentrates for magnet assemblies, silicon carbide wafers, and REACH-compliant cable compounds constitute critical input dependencies. Single-source vulnerability runs through Chinese rare earth refining complexes. Distribution runs through systems integrators and EPC contractors serving hydrocarbon and chemical end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireless safety architectures are displacing hardwired installations across Europe's brownfield infrastructure, creating a generational transition window where competitive positions remain unsettled.
For Market Incumbents: Anticipate certification bottlenecks at TÜV Rheinland and DEKRA by pre-positioning SIL 3 firmware submissions eighteen months ahead of platform refresh cycles. Backward integration into silicon carbide sensor substrates protects margin erosion from wireless commoditization. Prioritize captive cable manufacturing to absorb REACH-driven material transition timelines internally rather than freezing releases through supplier qualification delays. For New Entrants and Emerging Players: Launch via outcome-based maintenance contracting with UK North Sea operators piloting availability-guarantee agreements. Polish and Romanian chemical corridor greenfield projects offer the most penetrable entry points absent legacy system integration burdens. Target carbon capture skid integration at refineries and cement plants where application-specific safety loops lack incumbent standard portfolios. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to automation conglomerates seeking functional safety depth. Long-term viability favors vendors with dual competence in IEC 61508 certification and IEC 62443 cybersecurity integration. Monitor EU Cyber Resilience Act implementation timelines as the inflection signal determining which safety controller platforms face compliance multiplication versus harmonized testing pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Substrates | Bavarian sensor fabricators capture thermal-extreme premiums from German chemical crackers. |
| Wireless-Native Platform Certification | ISA100.11a and WirelessHART protocols unlock North Sea retrofit demand without cable pulls. |
| Cybersecurity-Functional Safety Convergence | IEC 62443-3-3 SL3 certification with OPC UA connectivity consolidates Norwegian procurement decisions. |
| Outcome-Based Maintenance Contracting | Availability-guarantee agreements shift UK North Sea revenue from hardware to performance fees. |
| Carbon Capture Safety Loop Development | Amine-based CO2 capture skids at Thames Corridor refineries require toxic release prevention architectures. |
Research Methodology
Multi-period observation of wireless protocol adoption rates, IEC 61508 recertification queue lengths, and silicon carbide sensor specification trends anchored the trend analysis, supplemented by interviews with safety system engineering directors at German chemical manufacturers, procurement leads at Norwegian offshore operators, TÜV Rheinland certification auditors, and EPC contractors serving Rotterdam petrochemical terminals. Secondary validation drew from EU Seveso III enforcement reports, ECHA REACH substance restriction timelines, IEC standard revision drafts, and petroleum safety authority incident databases. Bottom-up sensor-controller-actuator shipment estimates triangulated against top-down chemical and hydrocarbon capital expenditure disclosures.
Input-output matrices mapped safety integrity level requirements across installation types, technology architectures, and end-use risk profiles to generate segment-level demand projections across the analysis window. Modeled dimensions encompassed product type, end user industry, technology architecture, and installation environment severity. CAGRs derived from regression analysis of historical procurement cycles against regulatory enforcement intensity and brownfield age distribution. Forecast inputs incorporated EU Cyber Resilience Act scope expansion assumptions and North Sea platform decommissioning schedules.
The model assumes a particular technology adoption path; alternative pathways for wireless safety protocol standardization would alter the outlook if ISA100.11a and WirelessHART convergence stalls. Forecasts reflect fixed assumptions regarding Seveso III enforcement continuity and rare earth supply chain stability. Practitioners should monitor EU Cyber Resilience Act delegated act publication and Chinese export license changes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Laser Safety Glasses Market
Safety Equipment and Personal Protective Equipment (PPE)
Anti-Static Safety Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Bicycle Safety Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Sports Gun Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Law Enforcement and Military Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Self-Contained Breathing Apparatus Market
Safety Equipment and Personal Protective Equipment (PPE)
Eye Wash Stations Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Ballistic Floatation Vest Market
Safety Equipment and Personal Protective Equipment (PPE)
Cargo Security Seals Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Connection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Germany Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia Pacific Gas Detector Market