
 GPS Smart Locks Market | 2026-2036
GPS Smart Locks Market Size, Share, and Industry Trends Forecast 2026-2036
GPS Smart Locks Market Insights
MIL-STD-810G durability certification is redrawing competitive boundaries in the GPS smart locks sector. Assa Abloy leverages its Nordic manufacturing footprint to sustain supply continuity for high-specification padlocks. Samsung SDS anchors its position through captive semiconductor sourcing for GPS modules. Allegion differentiates via professional installation partnerships across European commercial real estate portfolios.
GPS smart locks are electromechanical locking devices integrating satellite positioning receivers, cellular or short-range wireless transceivers, and tamper-resistant housings to enable remote access control, real-time location tracking, and unauthorized-movement alerts for mobile and fixed assets. Bluetooth-enabled units dominate residential retrofit volumes due to minimal power draw and smartphone-native pairing, while Wi-Fi-connected systems command commercial hospitality deployments where cloud-based audit trails are mandatory. Keyless entry systems represent the fastest-growing product category as fleet operators replace mechanical seals with programmable electronic alternatives.
FCC equipment authorization governs radio-frequency emissions for GPS smart locks sold in the United States, while CE marking under the EU Radio Equipment Directive governs market access across European member states. The EU AI Act's risk-classification framework will soon subject autonomous anomaly-detection algorithms in smart locks to conformity assessment protocols. Stakeholders must weigh backward integration into GPS module sourcing against the flexibility of multi-vendor chip architectures as supply conditions evolve.
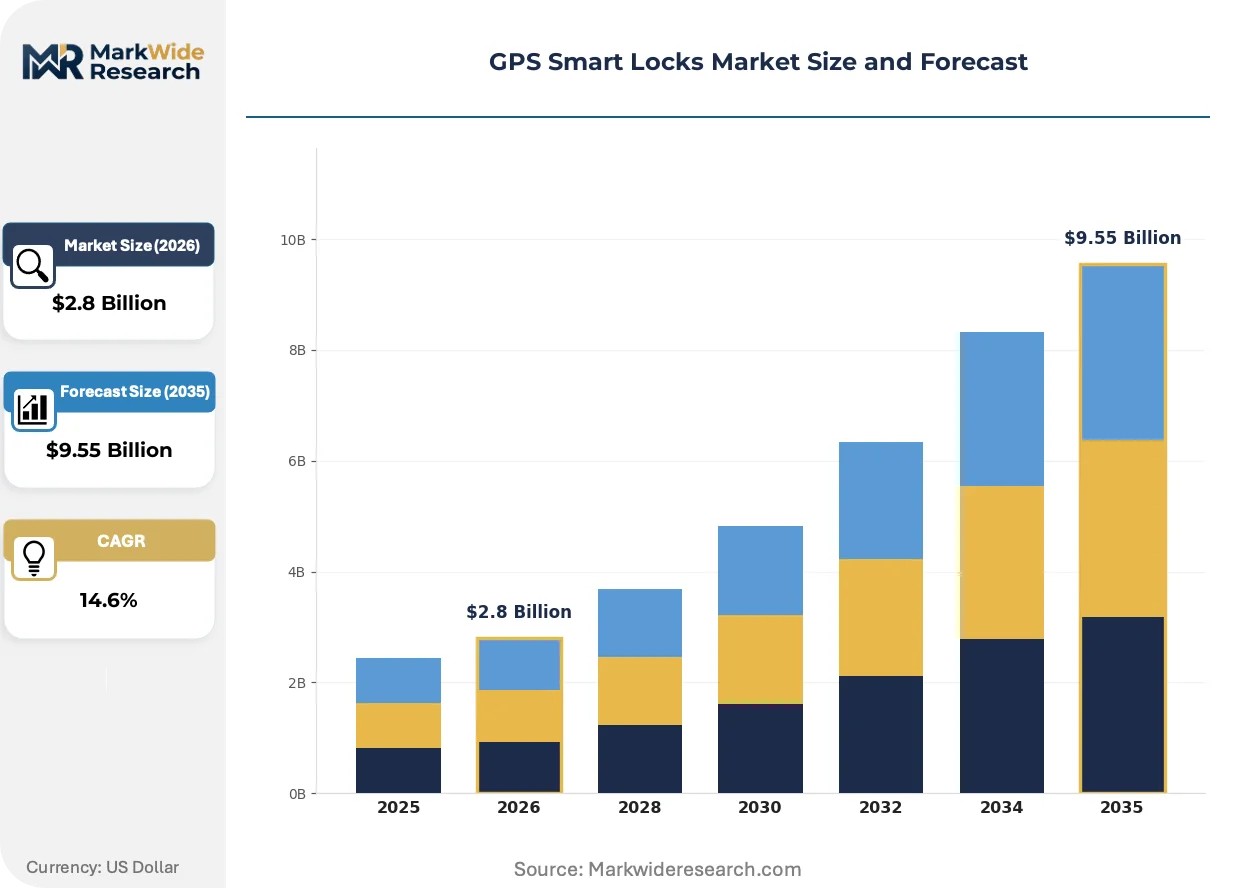
Market Dynamics
Fleet operators' replacement of mechanical seals with programmable electronic alternatives is compressing procurement cycles and forcing hardware suppliers to embed cellular connectivity as a baseline specification rather than a premium upgrade.
Growth Catalysts
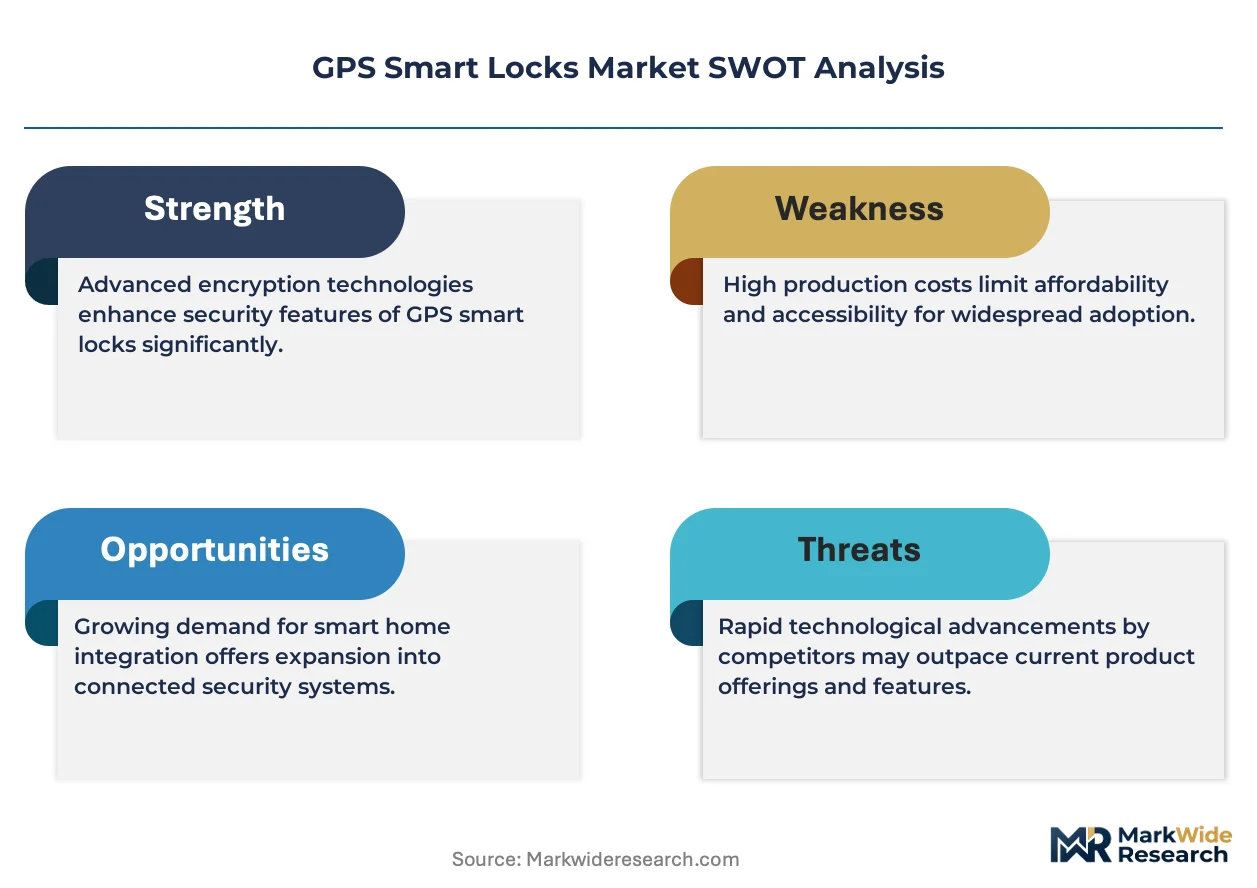
- FCC Equipment Authorization:Tightening radio-frequency emission standards for wireless locking devices sold in the United States is accelerating R&D investment in compliant antenna designs and filtering architectures.
- Connected Vehicle Platforms:Automotive OEMs in Germany are mandating GPS-enabled lock integration into telematics stacks, creating captive demand for satellite-receiver modules with automotive-grade temperature tolerance.
- Keyless Entry Systems:Trailer and container fleet logistics operators across North America are replacing physical key management with smartphone-credential systems to reduce driver idle time and seal-verification labor.
Market Restraints
- Semiconductor Supply Concentration:GPS module fabrication concentrates among a limited set of foundry operators in East Asia, exposing lock manufacturers to allocation volatility for multi-constellation receiver chips.
- Cellular Subscription Burden:Recurring connectivity fees for NB-IoT or LTE-M data plans add operational cost layers that mechanical locking alternatives avoid entirely.
- RoHS Compliance Friction:Lead-free solder requirements for tamper-resistant housings complicate thermal management design for high-current solenoid actuators.
Strategic Opportunities
- EU AI Act Conformity:Autonomous anomaly-detection algorithms in smart locks will soon require formal risk-classification assessment, creating first-mover advantage for vendors with pre-certified machine-learning stacks.
- Residential Retrofit Channels:Bluetooth-native padlocks with smartphone pairing are penetrating home security segments previously served by mechanical combination locks, opening volume markets with lower certification barriers.
- Cloud Audit Trail Mandates:Commercial hospitality operators are specifying Wi-Fi-connected systems with immutable access logs to satisfy insurer requirements for high-value asset protection.
Industry Challenges
- MIL-STD-810G Certification Timelines:Durability testing for shock, vibration, and temperature cycling extends product development cycles by 8-14 months for vendors targeting defense-adjacent logistics contracts.
- Legacy Fleet Management Integration:API compatibility with incumbent telematics platforms requires custom middleware development that fragments engineering resources across customer-specific deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GPS Smart Locks Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Deadbolts, Smart Knob Locks, Keyless Entry Systems, Smart Padlocks Technology: Bluetooth, Wi-Fi, Z-Wave, NFC End User: Residential, Commercial, Hospitality, Automotive Installation Type: DIY, Professional, Retrofit, New Construction |
| Companies Covered | Assa Abloy, Allegion, Kwikset, Yale, August Home, Schlage, Honeywell, Samsung SDS, Godrej Locks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GPS Smart Locks Market Trends and Innovations
Hardware-software convergence is redefining value capture in asset security, with data-analytics subscriptions and firmware-update services displacing traditional equipment-margin models as primary revenue streams.
Ultra-wideband (UWB) ranging chips are supplanting Bluetooth Low Energy for proximity-based unlock authentication in high-security commercial deployments. Financial services and pharmaceutical distribution centers are specifying UWB-enabled locks to achieve centimeter-grade spatial verification that prevents relay attacks. This precision-layer requirement is compressing addressable market share for legacy Bluetooth-only architectures.
CE marking under the EU Radio Equipment Directive is tightening electromagnetic compatibility thresholds for GPS smart locks entering European member states. Manufacturers must now demonstrate coexistence performance with 5G NR base stations and Wi-Fi 6E access points in dense urban RF environments. German industrial logistics operators are responding by demanding pre-certified module platforms rather than discrete component sourcing.
Buying committees at large fleet operators are unbundling hardware procurement from connectivity and software subscriptions, forcing vendors to compete on transparent lifecycle cost models rather than upfront equipment pricing. This decomposition is most visible in North American trucking and intermodal container segments, where total-cost-of-ownership spreadsheets now dominate vendor selection over technical specification checklists.
GPS Smart Locks Market Segmentation
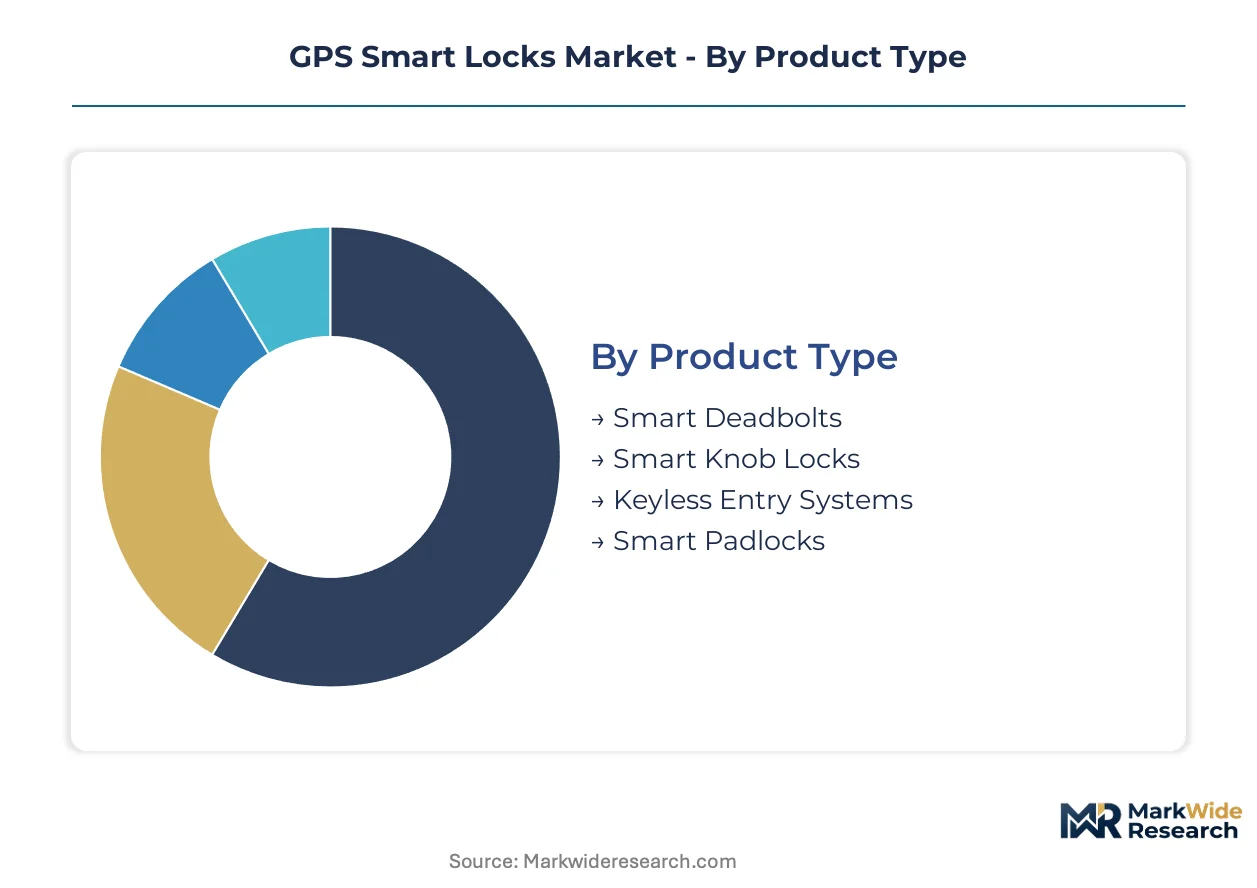
Product architecture in GPS smart locks diverges sharply between consumer convenience and enterprise-grade security requirements. Technology choices cascade through installation complexity, connectivity costs, and regulatory compliance burdens. Understanding these segment boundaries clarifies where vendors must specialize versus where scale economies apply.
Product Type:
Smart deadbolts and knob locks dominate residential retrofit demand in the United States, while keyless entry systems anchor fleet logistics procurement in Germany and export-led supply chains from Nordic manufacturing hubs.
- Smart Deadbolts:Electromechanical locking mechanisms with integrated GPS receivers and cellular modems for remote access management. Demand concentrates in single-family residential upgrades across the United States, where FCC equipment authorization compliance adds certification overhead that domestic suppliers absorb more efficiently than importers.
- Keyless Entry Systems:Programmable electronic alternatives to mechanical seals with smartphone-credential authentication and real-time location tracking. Fleet logistics operators in Germany and intermodal container handlers across North American port corridors are replacing physical key management to reduce driver idle time and labor verification costs.
- Smart Knob Locks:Cylindrical locksets with embedded satellite positioning for interior door applications in multi-tenant commercial buildings.
- Smart Padlocks:Portable tamper-resistant housings with Bluetooth-native pairing for construction site equipment and shared mobility fleets.
Smart deadbolts command the established base. The steepest expansion runs through keyless entry systems.
Technology:
Bluetooth-enabled units minimize power draw for battery-constrained residential deployments, while Wi-Fi and Z-Wave architectures serve commercial hospitality operators requiring cloud-based audit trails and building automation integration.
- Bluetooth:Short-range wireless protocol with smartphone-native pairing and minimal energy consumption. Residential retrofit volumes in the United States and Germany favor this technology for its compatibility with existing mobile device ecosystems and lower hardware cost structures.
- Wi-Fi:Direct internet connectivity enabling real-time status monitoring and over-the-air firmware updates. Commercial hospitality operators in France and the United Kingdom specify Wi-Fi-connected systems to satisfy insurer requirements for immutable access logs on high-value asset protection.
- Z-Wave:Mesh networking protocol optimized for smart home hub integration and extended range through repeater nodes.
- NFC:Near-field communication for tap-to-unlock authentication in enterprise access control and payment-integrated deployments.
Bluetooth retains volume leadership in unit shipments. Wi-Fi is gaining share fastest in value terms through commercial specification upgrades.
End User:
Residential and commercial segments split between DIY installation channels and professional integration services, while automotive OEM demand in Germany creates captive supply relationships with module vendors.
- Residential:Individual homeowners and rental property managers purchasing through retail and e-commerce channels. The United States and Germany represent the largest addressable markets, with demand concentrating in smart home ecosystem adopters replacing mechanical combination locks.
- Commercial:Facility managers and security directors specifying integrated access control for office buildings, warehouses, and industrial sites. German industrial logistics operators are demanding pre-certified module platforms under tightened CE marking electromagnetic compatibility thresholds.
- Hospitality:Hotels and short-term rental operators requiring guest credential management and housekeeping audit trails.
- Automotive:Vehicle manufacturers integrating GPS-enabled locks into connected telematics stacks for fleet management and asset tracking.
Commercial installations command the established base. The steepest expansion runs through automotive platform integration.
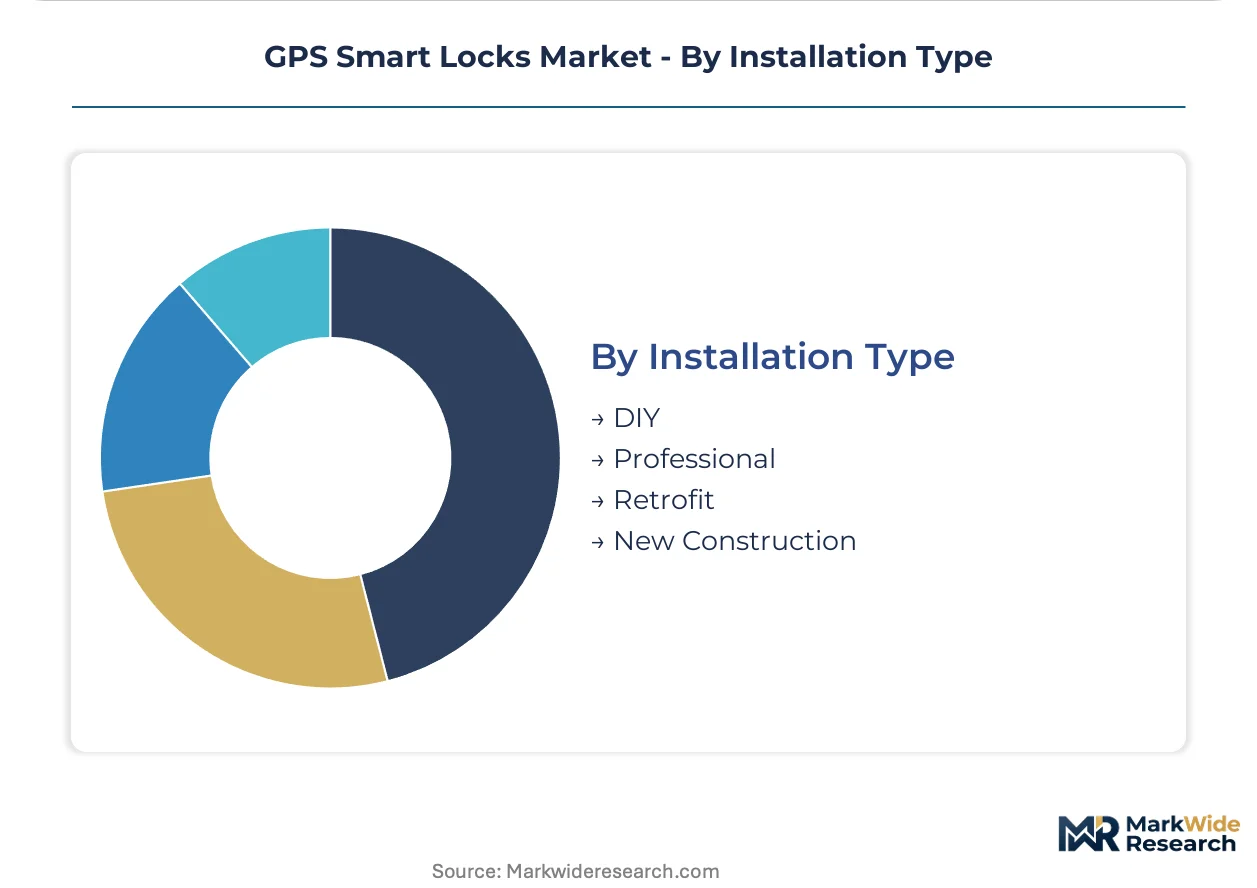
Installation Type:
DIY and retrofit channels minimize labor costs for residential adopters, while professional installation and new construction specifications dominate commercial real estate and hospitality deployments requiring warranty coverage and code compliance.
- DIY:Consumer self-installation of battery-powered units without hardwired power or network infrastructure. Retail channels in the United States and United Kingdom move the highest volumes, though return rates spike when smartphone pairing fails or door preparation requires unanticipated modifications.
- Professional:Certified technician deployment with hardwired power integration, network configuration, and ongoing maintenance contracts. European commercial real estate portfolios, particularly in France and Germany, specify professional installation partnerships to ensure CE marking compliance and insurer validation.
- Retrofit:Replacement of existing mechanical locks without door or frame modification, preserving original hardware mounting dimensions.
- New Construction:Specification during building design phase with embedded wiring, network drops, and integrated security system architecture.
Professional installation commands the established base. The steepest expansion runs through DIY channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity for multi-constellation GPS receiver chips concentrates in Taiwan and South Korea, while lock assembly and firmware development clusters in Germany, the United States, and China. This geographic split shapes procurement risk profiles and certification pathway choices for vendors.
United States
Fleet logistics operators across California and Texas are replacing mechanical seals with smartphone-credential systems to cut driver idle time. FCC equipment authorization governs radio-frequency emissions for wireless locking devices, tightening antenna design standards. Chicago and Detroit industrial corridors anchor demand from intermodal container handlers requiring cloud-based audit trails.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg mandate GPS-enabled lock integration into connected vehicle telematics stacks. CE marking under the EU Radio Equipment Directive enforces electromagnetic compatibility with 5G NR base stations. Stuttgart's industrial logistics operators demand pre-certified module platforms rather than discrete component sourcing.
China
Shared mobility fleets in Shenzhen and Shanghai specify Bluetooth-native padlocks with minimal power draw for bicycle and scooter deployments. MIIT certification requirements govern cellular modem integration for NB-IoT connectivity. Yangtze River Delta manufacturing hubs supply tamper-resistant housings to export markets.
Japan
Commercial hospitality operators in Tokyo and Osaka specify Wi-Fi-connected systems with immutable access logs for insurer compliance. METI standards guide smart home device interoperability. Kanto region facility managers prioritize professional installation partnerships for building automation integration.
United Kingdom
Residential retrofit demand in Greater London and the Southeast favors DIY battery-powered units with smartphone-native pairing. GDPR compliance shapes data handling for cloud-based access logs. Manchester and Birmingham commercial real estate portfolios specify Z-Wave mesh networking for extended range through repeater nodes.
GPS Smart Locks Market Competitive Landscape
Concentration sits with diversified security conglomerates and captive electronics divisions of industrial groups. The vendor base spans three tiers: heritage lock manufacturers with Nordic supply footprints, semiconductor-anchored conglomerates with in-house GPS module sourcing, and specialist smart home entrants with direct-to-consumer distribution. Strategic moves center on MIL-STD-810G durability certification for defense-adjacent logistics contracts and professional installation partnerships across European commercial real estate.
Within the diversified security tier, Assa Abloy and Allegion exemplify heritage manufacturers leveraging manufacturing scale and certification expertise. Samsung SDS occupies a position representing captive electronics integration. These three anchors illustrate divergent sourcing strategies: Nordic supply continuity, European installation networks, and semiconductor backward integration.
| Leading Market Players |
|---|
| Assa Abloy |
| Allegion |
| Kwikset |
| Yale |
| August Home |
| Schlage |
| Honeywell |
| Samsung SDS |
| Godrej Locks |
| Others |
Pricing and Supply Chain Analysis
Foundry utilization rates above 85% in Taiwan and South Korea compress margin recovery for GPS module-dependent lock manufacturers while simultaneously elevating price floors for multi-constellation receiver chips. This capacity tightness cascades through contract manufacturing networks in China and Vietnam, forcing hardware vendors to absorb component premiums or pass through selective increases to fleet operators with multi-year procurement agreements.
Pricing Analysis
FCC equipment authorization dictates the pricing tier structure for wireless locking devices sold in the United States, separating certified premium units from uncertified economy alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects MIL-STD-810G durability certification, automotive-grade temperature tolerance, and residential Bluetooth-native convenience tiers. Cost compression in the standard tier is intensifying because cellular subscription bundling now dominates fleet procurement evaluations. Small residential retrofit buyers exhibit highest price sensitivity; defense-adjacent logistics contractors demonstrate lowest sensitivity due to specification rigidity.
Supply Chain Analysis
Container availability constraints on the Shanghai-Long Beach trade lane elevate inbound logistics costs for tamper-resistant housing suppliers sourcing from Yangtze River Delta manufacturing hubs. GPS smart lock production draws from Taiwan and South Korea for multi-constellation receiver chips, China for die-cast housings and solenoid actuators, and Germany for automotive-grade firmware development. Single-source vulnerability concentrates in East Asian foundry capacity for NB-IoT modem silicon. Distribution runs through direct OEM supply agreements for automotive platform integration and security distributor networks for commercial facility management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechanical seal substitution by programmable electronic alternatives threatens incumbent hardware margins while opening subscription revenue streams that favor software-capable entrants. Incumbents must navigate this technology transition without cannibalizing established product lines.
For Market Incumbents: Consolidate professional installation partnerships across European commercial real estate portfolios to lock in recurring service revenue streams. Deepen backward integration into GPS module sourcing through captive semiconductor relationships, mirroring Samsung SDS's supply continuity model. Defend against Bluetooth-native specialist entrants by embedding cellular connectivity as baseline specification rather than premium upgrade tier.
For New Entrants and Emerging Players: Lead with UWB-enabled proximity authentication targeting financial services and pharmaceutical distribution centers where centimeter-grade spatial verification commands specification priority. Target residential retrofit channels in the United Kingdom and United States where DIY battery-powered units with smartphone-native pairing face lower certification barriers than commercial hospitality deployments. Pursue direct-to-consumer e-commerce positioning with video-guided installation support to minimize return rates from pairing failures.
For Investors and Strategic Acquirers: Specialist firmware developers with pre-certified machine-learning stacks for EU AI Act conformity represent priority acquisition targets as autonomous anomaly-detection algorithms face formal risk-classification assessment. Long-term viability hinges on recurring data-analytics subscription revenue displacing equipment-margin dependence. Watch for unbundling of hardware procurement from connectivity subscriptions at large North American fleet operators as inflection signal for transparent lifecycle cost model dominance.
| Strategic Initiative | Industry Significance |
|---|---|
| MIL-STD-810G Certification Investment | Unlocks defense-adjacent logistics contracts with 8-14 month development timeline premiums. |
| Cellular Connectivity Baseline Integration | Aligns hardware specifications with fleet operator procurement cycle compression. |
| EU AI Act Pre-Certification | Captures first-mover advantage in autonomous anomaly-detection algorithm compliance. |
| Professional Installation Partnership Expansion | Secures CE marking compliance and insurer validation across European commercial portfolios. |
| UWB Ranging Chip Architecture Migration | Prevents relay attacks in high-security financial and pharmaceutical deployments. |
Research Methodology
The analysis maps smart deadbolt, keyless entry system, and smart padlock sub-sectors, each validated through fleet logistics procurement directors, commercial facility security managers, automotive OEM telematics engineers, and residential smart home ecosystem adopters. Primary interview intelligence triangulates against FCC equipment authorization filings, CE marking documentation under EU Radio Equipment Directive, MIIT certification records, customs trade data for GPS module imports, and SEC 10-K disclosures from diversified security conglomerates. Bottom-up unit shipment estimates reconcile with top-down addressable market sizing across technology, end user, and installation type dimensions.
Consistency checks validate volume and value outputs against external benchmarks including automotive telematics integration forecasts, commercial real estate security spend patterns, and fleet operator capital expenditure surveys. The analytical framework models product type, connectivity protocol, end-user vertical, and installation complexity segments across the projection horizon. CAGRs derive from regression analysis of historical adoption curves adjusted for regulatory inflection points and technology substitution elasticities. Forecast inputs incorporate cellular subscription pricing trajectories, semiconductor foundry capacity expansion announcements, and electromagnetic compatibility threshold evolution under 5G NR coexistence requirements.
The analysis sits within stated boundaries; outcomes outside FCC equipment authorization timeline stability, East Asian foundry allocation continuity, or EU AI Act implementation sequencing would require recalibration. Forecasts reflect documented assumptions regarding fleet operator replacement rates, residential DIY installation success rates, and automotive platform integration cadence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Home Control and Security Systems Market
Access Control Systems
Japan Access Control Market
Access Control Systems
Border Security System Market
Access Control Systems
Programmable Safety Systems Market
Access Control Systems
North America Keyless Vehicle Access Control System Market
Access Control Systems
France Access Control Market
Access Control Systems
Latin America Smart Lock Market
Access Control Systems
Global Fingerprint Access Control Systems Market
Access Control Systems
Europe Home Security System Market
Access Control Systems
Europe Access Control Software Market
Access Control Systems
Global Home Security Systems Market
Access Control Systems
Automatic Gate and Door Opening System Market
Access Control Systems
Pedestrian Access Control System Market
Access Control Systems
Pedestrian Entrance Control System Market
Access Control Systems
Europe Proximity Access Control Market
Access Control Systems
United Kingdom Access Control Market