
 Plant-Based Bacon Market | 2026-2036
Plant-Based Bacon Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Bacon Market Insights
Buyer concentration across the foodservice sector is broadening as independent restaurants and regional chains join national quick-service operators in sourcing plant-based bacon alternatives. Beyond Meat Inc. anchors supply relationships with large-scale distributors, while Impossible Foods Inc. leverages direct-to-foodservice technical support to sustain kitchen adoption. Tofurky competes through established vegetarian retail channels that extend its shelf presence in conventional supermarkets.
Plant-based bacon comprises protein-lipid matrices formulated to replicate the crisp texture, umami profile, and visual appearance of cured pork bacon, typically manufactured through extrusion or shear-cell processing to align fibers and create bite resistance. The ingredient dimension shows pea protein formulations leading volume due to clean-label positioning, while coconut oil variants capture premium margin pools through superior fat-crystallization behavior that mimics pork fat rendering. Distribution through supermarkets still occupies the largest revenue share, though online retail is accelerating fastest as subscription models reduce customer acquisition costs for emerging brands.
FDA oversight of alternative protein labeling and USDA engagement on meat-term usage shape product nomenclature and packaging claims in the United States, directly influencing consumer trial rates and retail placement negotiations. EFSA and national regulators across Europe enforce novel-food authorization pathways for emerging protein sources, creating staggered market entry timelines that favor established ingredient suppliers with dossier experience. Stakeholders must monitor evolving enforcement postures on protein descriptor terminology, as regulatory clarity on "bacon" equivalency claims will determine permissible marketing architecture and channel expansion feasibility.
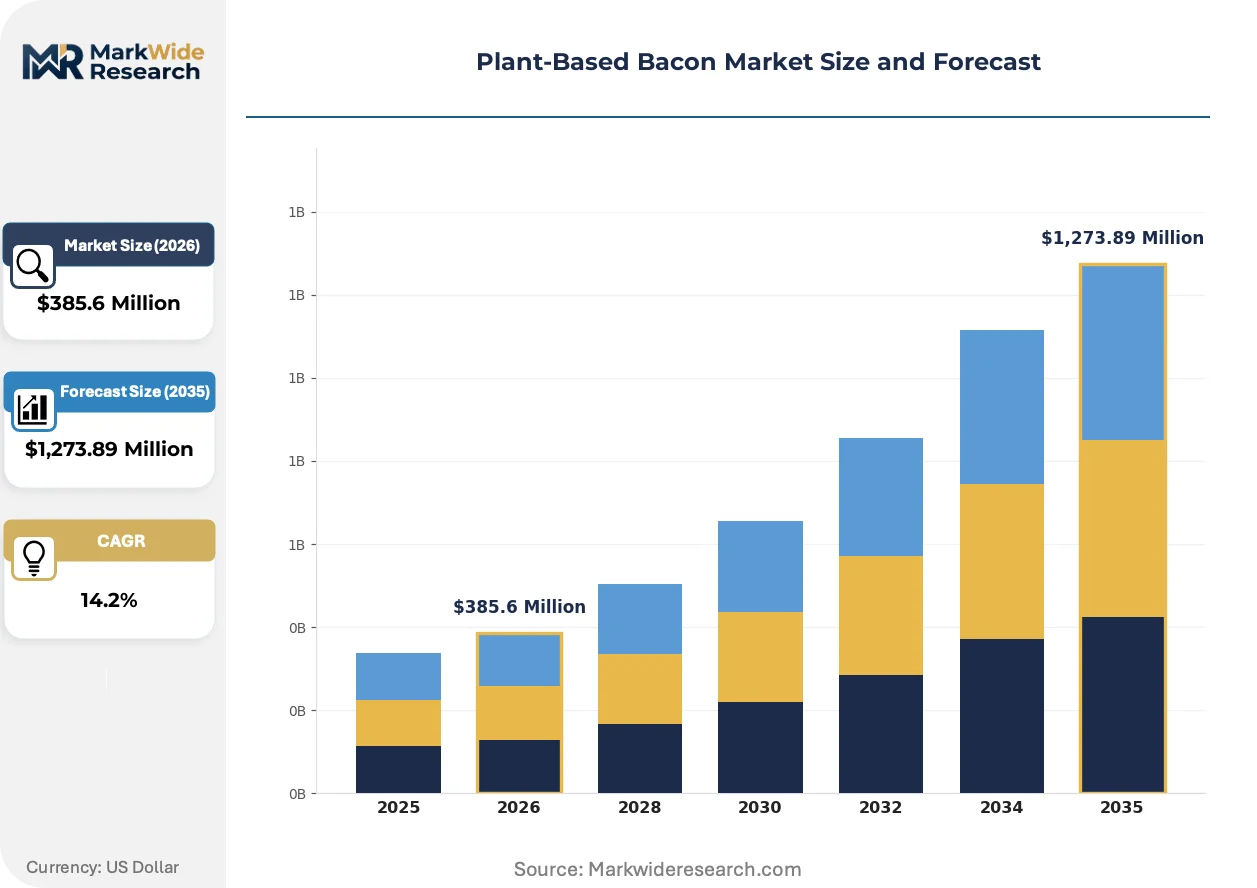
Market Dynamics
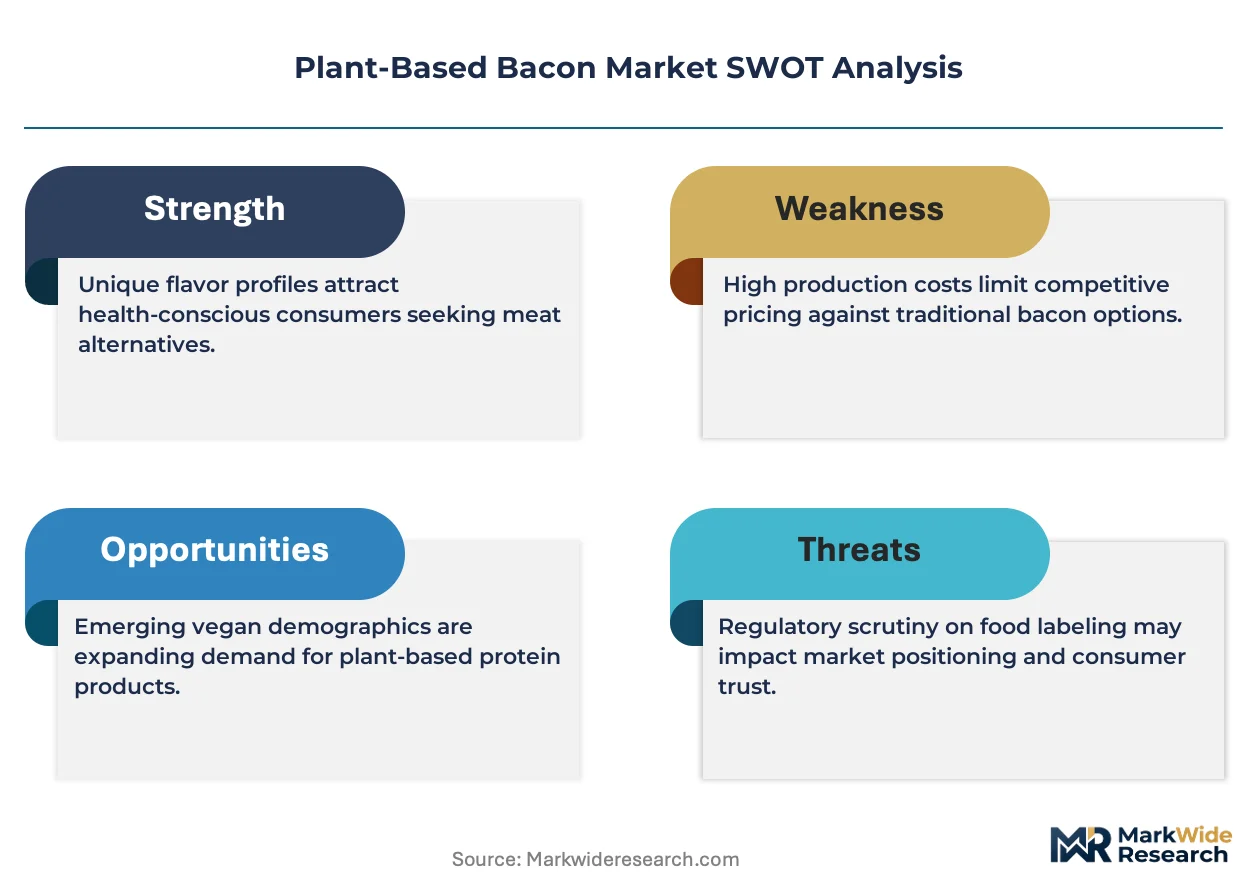
Shear-cell processing technology is compressing production costs for plant-based bacon manufacturers while FDA labeling clarity on alternative protein descriptors unlocks retail shelf placement negotiations previously blocked by nomenclature disputes.
Growth Catalysts
- Flexitarian household penetration:United States households reducing meat frequency without eliminating animal products drive repeat purchases across retail and foodservice channels, expanding the addressable consumer base beyond committed vegetarians.
- Quick-service restaurant menu expansion:National chains and regional operators accelerate plant-based breakfast sandwich placements as kitchen equipment compatibility with existing bacon warmers reduces operational friction.
- Extrusion technology maturation:High-moisture extrusion systems now achieve fiber alignment and bite resistance comparable to cured pork bacon at production scales viable for mass-market pricing.
Market Restraints
- Pea protein supply concentration:North American and European ingredient processing capacity limits constrain formulation flexibility when crop yields fluctuate or contract negotiations tighten.
- Fat crystallization performance gaps:Coconut oil and shea butter blends fail to replicate pork fat's rendering behavior at lower temperatures, producing texture inconsistencies in home cooking applications.
- USDA meat-term enforcement uncertainty:Pending determinations on "bacon" descriptor permissibility create packaging claim hesitation that delays marketing investment and retail expansion timelines.
Strategic Opportunities
- Subscription direct-to-consumer models:Emerging brands bypass slotting fee barriers in conventional retail by building recurring revenue through frozen product delivery networks.
- Clean-label ingredient positioning:Formulations eliminating methylcellulose and artificial smoke flavors capture premium positioning as EFSA and FDA scrutiny intensifies on processed alternative protein additive panels.
- Shear-cell processing adoption:This emerging technology converges with precision fermentation-derived fats to enable whole-muscle structure replication without extrusion equipment capital requirements.
Industry Challenges
- Food technologist talent scarcity:Formulation expertise spanning protein chemistry, lipid science, and sensory evaluation remains concentrated at established ingredient suppliers, constraining R&D velocity at mid-scale manufacturers.
- Novel-food authorization timelines:EFSA dossier preparation for emerging protein sources stretches 18-36 months, staggering European market entry and favoring incumbents with regulatory affairs infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Bacon Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,273.89 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Strips, Crumbles, Chunks, Ribbons Ingredients: Pea Protein, Soy Protein, Wheat Gluten, Coconut Oil Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Restaurants Customer Type: Vegetarians, Vegans, Flexitarians, Meat Reducers |
| Companies Covered | Beyond Meat Inc., Cool Foods Inc., Hooray Foods, Tofurky, Impossible Foods Inc., Conagra Inc., Kellanova, Umaro Foods, Prime Roots, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Bacon Market Trends and Innovations
Ingredient diversification and processing technology maturation are compressing the quality gap between plant-based and conventional bacon while regulatory frameworks crystallize around labeling permissibility.
Precision fermentation-derived fats are rewriting fat-phase functionality in plant-based bacon formulations. Early-stage suppliers now provide tailored lipid profiles that crystallize and render with pork-like behavior. Quick-service restaurant chains pilot these ingredients in limited regional launches. This technology is rewriting margin structures by reducing coconut oil dependency and its associated commodity price volatility.
EFSA novel-food authorization pathways are tightening entry requirements for emerging protein sources across European markets. Dossier requirements now mandate extended toxicology and allergenicity data sets that extend approval timelines. Startups lacking regulatory affairs specialization face capital runway compression. Protein ingredient suppliers with established EFSA relationships capture first-mover positioning in bacon applications.
Foodservice procurement teams now specify performance-based acceptance criteria rather than ingredient-origin specifications. Operators demand sensory parity benchmarks against pork bacon in blind testing protocols. This shift compresses supplier qualification timelines while raising technical performance thresholds. United States quick-service chains lead this specification evolution, with regional chains adopting similar protocols within 12-18 month lags.
Plant-Based Bacon Market Segmentation
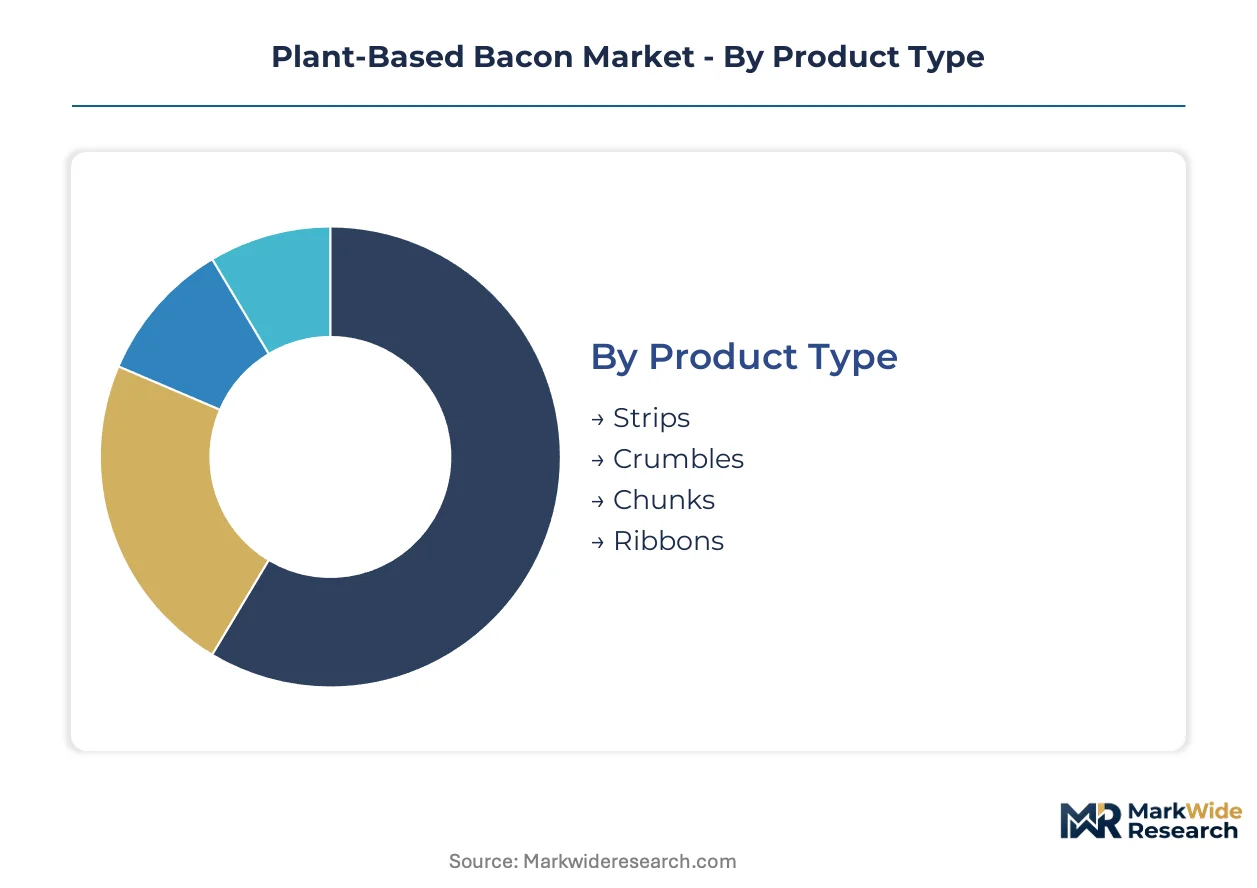
Plant-based bacon manufacturers configure product portfolios across four intersecting dimensions that determine pricing architecture and channel access. Each segmentation layer carries distinct technical specifications, regulatory exposure, and margin profiles that shape competitive positioning.
Product Type:
Standardization dominates strip formats while crumble and chunk variants accommodate more customization in portion control and recipe integration.
- Strips:Extruded protein-lipid matrices cut to uniform dimensions replicate pork bacon's visual and textural signatures for direct breakfast plate substitution. Quick-service restaurants in the United States specify strip formats for breakfast sandwich compatibility, driving volume concentration through national chain procurement.
- Crumbles:Smaller particulate sizing enables salad topping and pizza applications where bacon bits traditionally scatter. Foodservice operators specify crumble formats for recipe cost control and reduced kitchen labor.
- Chunks:Larger irregular pieces target home cooking applications requiring renderable fat pockets and chew resistance. Premium positioning in health food stores supports higher unit economics.
- Ribbons:Thin continuous sheets suit food processor integration and industrial ingredient supply. Limited retail presence concentrates in commercial bakery and prepared meal channels.
Most installed capacity flows through strips. Expansion is steepest in crumbles.
Ingredients:
Cost tier separation between commodity protein sources and premium lipid systems defines formulation strategy across price-positioned product lines.
- Pea Protein:Clean-label positioning and neutral flavor profiles support mainstream retail placement. North American crop processing infrastructure constrains supply flexibility during contract negotiation periods.
- Soy Protein:Mature supply chains and established extrusion parameters enable cost-competitive formulations. Allergen labeling requirements limit school and institutional foodservice penetration.
- Wheat Gluten:Seitan-derived textures achieve pronounced fibrous bite resistance in premium positioning. European formulation preferences favor wheat gluten for traditional meat alternative heritage.
- Coconut Oil:Superior fat crystallization behavior commands premium pricing through pork-like rendering performance. Commodity price volatility compresses margin stability for mid-tier brands.
Pea protein formulations command the largest production volume. Coconut oil variants gain share fastest in premium positioning.
Distribution Channel:
Customer acquisition economics diverge sharply between high-slotting-fee retail and lower-friction direct channels.
- Supermarkets:Conventional grocery placement requires slotting fee investment and refrigerated supply chain compliance. National retail banners in the United States consolidate category management decisions at headquarters level.
- Online Retail:Subscription models reduce customer acquisition costs for frozen product delivery. Direct-to-consumer fulfillment bypasses retail margin stacking.
- Health Food Stores:Specialty retail placement targets committed vegetarian and vegan consumer bases. Smaller format stores limit SKU breadth and frozen storage capacity.
- Restaurants:Foodservice distribution through broadline operators requires technical kitchen support and equipment compatibility verification. Quick-service chain adoption drives volume scaling.
Supermarkets absorb the majority of shipment volume. Online retail climbs the fastest in emerging brand penetration.
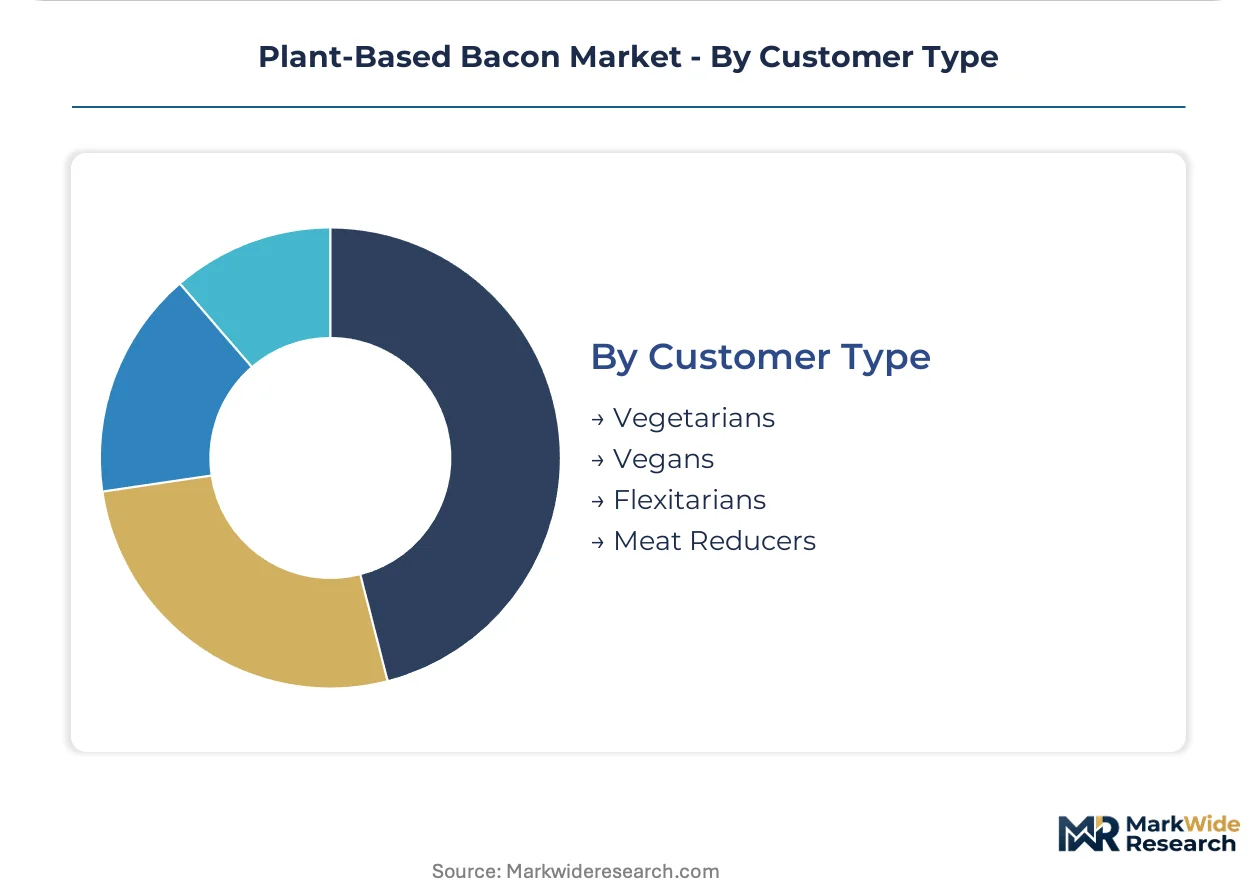
Customer Type:
Dietary commitment level determines repeat purchase frequency and price sensitivity across consumption occasions.
- Flexitarians:Households reducing meat frequency without eliminating animal products drive mainstream market expansion. United States demographic concentration supports retail and foodservice channel development.
- Meat Reducers:Health-motivated purchase behavior prioritizes nutritional labeling and ingredient transparency. Physician recommendation channels influence trial conversion.
- Vegetarians:Longstanding category adoption sustains baseline demand through established retail placement. Lower price sensitivity supports premium product trial.
- Vegans:Strict exclusion criteria require certification verification and cross-contamination controls. Smaller addressable base limits dedicated product development investment.
Flexitarian households represent the largest addressable base. Meat reducers show the steepest expansion trajectory in new customer acquisition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands retail velocity through flexitarian household penetration, while Germany builds European momentum through clean-label formulation preferences and established meat-alternative retail infrastructure.
United States
Quick-service restaurant chains drive volume concentration through breakfast sandwich placements requiring equipment compatibility with existing bacon warmers. FDA labeling guidelines on alternative protein descriptors clarify composition standards for retail packaging claims. California and Pacific Northwest metropolitan clusters anchor foodservice procurement teams specifying sensory parity benchmarks against pork bacon in blind testing protocols.
Germany
Established vegetarian retail heritage sustains baseline demand through conventional supermarket placement and discount channel penetration. EFSA novel-food authorization pathways enforce extended toxicology requirements for emerging protein sources entering European markets. Bavaria and North Rhine-Westphalia host ingredient processing infrastructure supporting wheat gluten formulation preferences in premium positioning.
United Kingdom
Supermarket private-label expansion compresses branded shelf space while flexitarian demographic growth broadens addressable consumer bases beyond committed vegetarians. FSA enforcement on protein descriptor terminology shapes permissible marketing architecture for bacon-equivalency claims. London and Southeast England concentrate foodservice distributor headquarters consolidating category management decisions for national chain procurement.
Canada
Health Canada and PMRA oversight on novel food ingredients creates staggered approval timelines favoring established suppliers with regulatory dossier experience. Cross-border supply chain integration with United States processing infrastructure reduces formulation cost differentials. Ontario and Quebec metropolitan corridors anchor retail banner consolidation driving slotting fee negotiations for refrigerated alternative protein placement.
Australia
TGA novel food regulations and state-level food safety enforcement create multi-layer compliance requirements for imported ingredient formulations. Subscription direct-to-consumer models reduce customer acquisition costs for frozen product delivery networks bypassing conventional retail margin stacking. New South Wales and Victoria host foodservice operator clusters piloting precision fermentation-derived fats in limited regional launches.
Plant-Based Bacon Market Competitive Landscape
United States producers anchor one tier; European specialists hold formulation heritage positioning in clean-label segments. The vendor base distributes across consolidated national brand portfolios and emerging regional challengers with subscription-driven direct channels. Three strategic archetypes dominate: scale-driven extrusion manufacturers, precision fermentation fat suppliers, and direct-to-consumer subscription specialists. Competitive moves concentrate on shear-cell processing technology licensing and backward integration into pea protein processing infrastructure.
Within the scale-driven tier, Beyond Meat Inc. and Impossible Foods Inc. occupy positions exemplifying national distribution anchorage through broadline foodservice relationships and retail banner penetration. Tofurky represents the established vegetarian heritage archetype with conventional supermarket shelf presence extending through decades of category participation. These three entities illustrate the competitive structure without exhausting its full composition.
| Leading Market Players |
|---|
| Beyond Meat Inc. |
| Cool Foods Inc. |
| Hooray Foods |
| Tofurky |
| Impossible Foods Inc. |
| Conagra Inc. |
| Kellanova |
| Umaro Foods |
| Prime Roots |
| Others |
Pricing and Supply Chain Analysis
Captive pea protein processing in Canada and the United States anchors supply positioning and pricing power for plant-based bacon manufacturers, with backward integration into extrusion infrastructure compressing unit economics while insulating against commodity volatility in coconut oil feedstocks.
Pricing Analysis
Capacity additions in the United States are reshaping price floors as extrusion equipment deployments reach commercial scale. Three-tier pricing structure across premium, standard, and economy levels separates precision fermentation-fat formulations from coconut oil variants and commodity soy protein lines. Price differentiation hinges on clean-label certification status and shear-cell processing adoption. Cost compression in economy tiers is intensifying because pea protein contract negotiations tighten during harvest cycles. Quick-service restaurant procurement teams exhibit lowest price sensitivity; independent foodservice operators face highest margin pressure.
Supply Chain Analysis
Single-source vulnerability sits with North American pea protein isolate suppliers concentrated in Manitoba and the Dakotas. Manufacturing draws from Canadian crop processing, United States extrusion equipment, and Southeast Asian coconut oil refining. Raw material dependencies span pea protein isolate, coconut oil fractions, and methylcellulose binders. Tariff exposure on Southeast Asian lipid imports threatens margin stability for mid-tier brands. Distribution runs through broadline foodservice operators and refrigerated retail networks with slotting fee barriers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant-based bacon manufacturing operates as a geographic-arbitrage play: EFSA novel-food authorization timelines in Europe stretch 18-36 months while FDA labeling clarity in the United States accelerates market entry, creating cost and timing differentials favoring North American production placement.
For Market Incumbents: Acquire shear-cell processing technology licenses to defend against precision fermentation-fat entrants disrupting texture parity benchmarks. Secure captive pea protein processing capacity in Manitoba or the Dakotas to offset supply concentration risk from crop yield volatility. Lock long-term offtake agreements with quick-service restaurant chains before emerging brands achieve sensory parity in blind testing protocols. For New Entrants and Emerging Players: Capture subscription direct-to-consumer channels in Australia and Canada where retail slotting fees and refrigerated supply chain compliance create barriers for conventional distribution. Target flexitarian households in Pacific Northwest metropolitan clusters with clean-label formulations eliminating methylcellulose. Lead with frozen product delivery networks bypassing supermarket margin stacking. For Investors and Strategic Acquirers: Consolidation pressure builds where food technologist talent scarcity constrains R&D velocity at mid-scale manufacturers lacking regulatory affairs infrastructure. Five-to-ten-year viability favors precision fermentation-fat suppliers achieving pork-like rendering behavior and extrusion manufacturers with backward integration into protein processing. Watch EFSA enforcement postures on protein descriptor terminology as inflection indicator for European market entry feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Shear-Cell Processing Licensing | Enables whole-muscle structure replication without extrusion capital requirements, compressing production costs for emerging entrants. |
| Backward Integration into Pea Protein | Captive supply of North American crop processing insulates margin stability from contract negotiation tightening during harvest cycles. |
| Precision Fermentation Fat Partnerships | Access to tailored lipid profiles crystallizing with pork-like behavior reduces coconut oil dependency and commodity price exposure. |
| Subscription Direct-to-Consumer Launch | Frozen product delivery networks in Australia and Canada bypass retail slotting fees and recurring revenue builds customer lifetime value. |
| Clean-Label Certification Investment | EFSA and FDA scrutiny on methylcellulose and artificial smoke flavors creates premium positioning for additive-free formulations. |
Research Methodology
Multiple input streams — executive interviews with plant-based protein R&D directors, procurement leads at broadline foodservice distributors, regulatory affairs specialists at ingredient suppliers, and category buyers at national retail banners — were reconciled against FDA labeling guideline documents, EFSA novel-food authorization dossiers, SEC filings from publicly traded alternative protein companies, and trade data on pea protein isolate imports. Bottom-up volume estimates from extrusion capacity installations and top-down expenditure tracking from quick-service restaurant menu expansion programs were cross-validated.
Historical capacity deployment patterns were cross-referenced against panel input from food technologists and supply chain planners to build the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, protein source, lipid system, distribution channel, and customer dietary commitment level. CAGRs were derived from installed equipment scaling curves and repeat purchase velocity in flexitarian household panels. Forecast inputs incorporated shear-cell processing adoption rates and precision fermentation-fat commercialization timelines.
Regulatory enforcement shifts on protein descriptor terminology, crop yield volatility in North American pea production, and precision fermentation-fat cost curves are the dominant revision risks to modeled outputs. Forecasts reflect assumptions on FDA and EFSA labeling clarity trajectories without certainty on timing or scope. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Vegan Diet Market
Plant Based Food
Europe Tofu Market
Plant Based Food
United Kingdom Soy Protein Market
Plant Based Food
United Kingdom Plant Protein Market
Plant Based Food
India Plant Based Milk Market
Plant Based Food
Plant Based Eggs Market
Plant Based Food
Plant Based Cheese Market
Plant Based Food
West Africa Plant Based Product Market
Plant Based Food
Middle East and Africa Plant-Based Egg Market
Plant Based Food
United States Meat Substitutes Market
Plant Based Food
Burdock Root Extract Market
Plant Based Food
Plant-Based Diet Market
Plant Based Food
Vegan Spaghetti Market
Plant Based Food
Plant-Based Chicken Market
Plant Based Food
South America Meat Substitute Market
Plant Based Food
Meatless Meat Market