
 Middle East and Africa Plant-Based Meat and Dairy Products Market | 2026-2036
Middle East and Africa Plant-Based Meat and Dairy Products Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Plant-Based Meat and Dairy Products Market Foresight
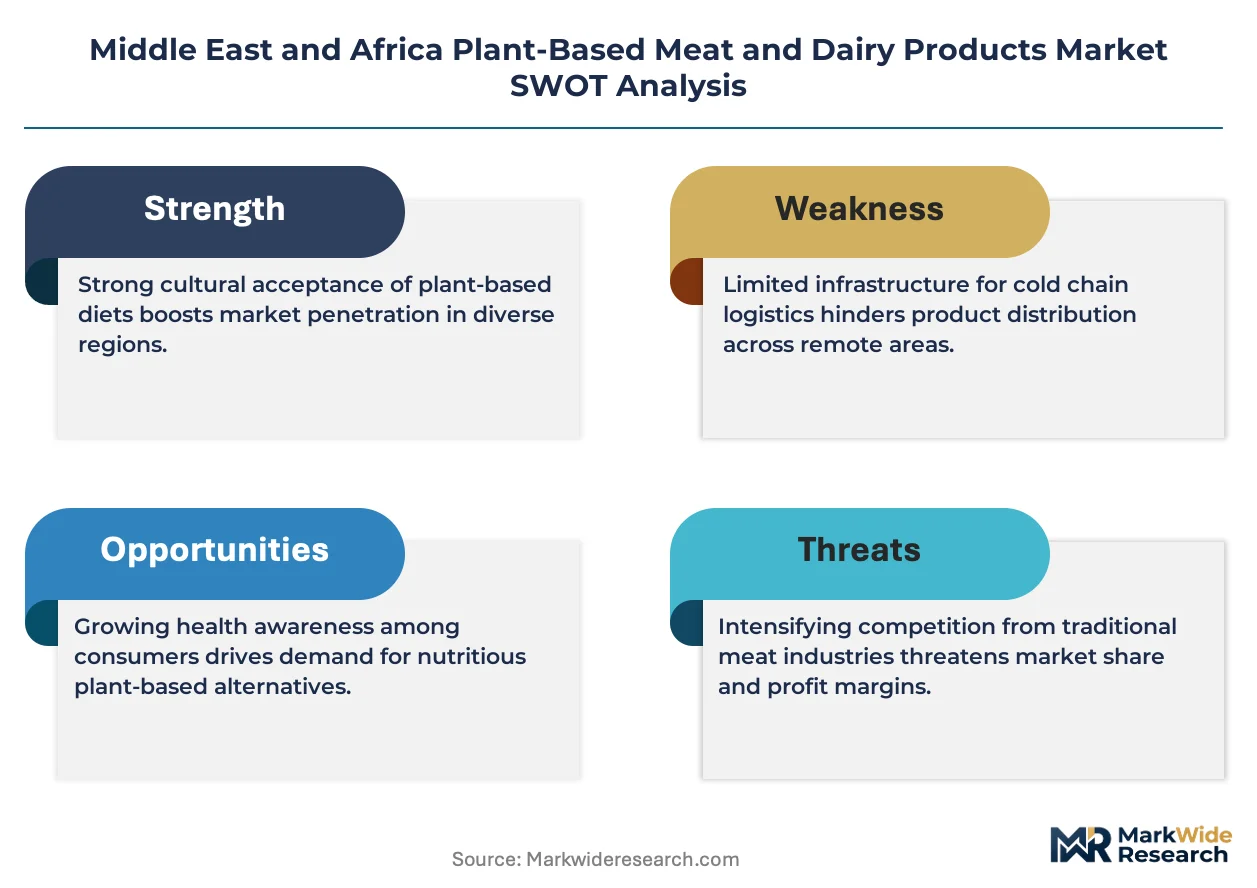
The capital-intensity divergence between multinational manufacturers and regional specialists is redrawing competitive boundaries in the Middle East and Africa plant-based protein space. Beyond Meat Inc leverages its extrusion technology leadership to supply foodservice operators across Gulf markets. Al Islami Foods anchors its position through deep halal supply chain integration and familiar brand equity in Middle Eastern retail channels.
Plant-based meat and dairy products encompass formulated foodstuffs derived from isolated proteins, texturized vegetable matter, and fermented plant extracts designed to replicate the sensory and nutritional profiles of conventional animal products. These items typically contain protein concentrations between ten and twenty grams per serving, achieved through high-moisture extrusion or precision fermentation, and serve commercial kitchens and retail shelves seeking alternatives compliant with religious dietary laws and allergen restrictions. Plant-based milk leads volume across distribution channels given its established shelf presence and lower price point relative to emerging categories. Pea protein represents the fastest-growing ingredient type as manufacturers seek to differentiate from legacy soy formulations and address allergen-sensitive consumers.
South Africa's Department of Health food labeling standards, Saudi FDA nutritional claims guidelines, and UAE MOHAP import registration requirements collectively shape product development timelines and market access pathways for new entrants. Halal certification bodies in Malaysia and Indonesia provide additional compliance layers for brands targeting Muslim-majority populations across the region. Stakeholders must monitor evolving protein sourcing regulations and certification reciprocity agreements to sustain commercial momentum.
Market Dynamics
Halal certification reciprocity between Malaysia, Indonesia, and Gulf Cooperation Council states is compressing product registration timelines and reshaping which manufacturers can achieve rapid multi-market deployment across the Middle East and Africa.
Growth Catalysts
- FSSAI-aligned food safety protocols:India's food safety standards are being adopted as reference frameworks by several African national regulators, reducing reformulation burdens for entrants already compliant with these rules.
- Foodservice channel expansion:Hotel and restaurant operators in Dubai, Riyadh, and Johannesburg are adding dedicated plant-based menu sections, creating pull-through demand for bulk-formatted products.
- Pea protein extraction advances:Wet-fractionation improvements are lowering isolate production costs and enabling cleaner taste profiles that satisfy Middle Eastern sensory preferences.
Market Restraints
- Import dependency for protein isolates:Regional manufacturers rely on North American and European suppliers for textured pea and fava protein, exposing margins to currency volatility and shipping disruptions.
- Shelf-stable formulation limitations:Current high-moisture extrusion systems struggle to achieve ambient-stable textures without refrigeration, constraining distribution reach in areas with cold-chain gaps.
- Dual certification requirements:Products targeting Muslim-majority populations must secure both national food safety approvals and halal body endorsements, extending time-to-market by four to eight months.
Strategic Opportunities
- Underpenetrated East African markets:Kenya, Ethiopia, and Tanzania present whitespace where urbanization and diaspora influence are creating early adopter clusters for plant-based dairy alternatives.
- Precision fermentation convergence:Combining microbial protein production with traditional fermentation techniques could yield novel ingredients that satisfy both halal requirements and clean-label demands.
- Direct-to-hospitality distribution:Bypassing traditional retail and supplying institutional kitchens directly reduces margin erosion and builds brand equity with influential chefs.
Industry Challenges
- Halal supply chain verification:Maintaining certified status requires continuous auditing of every input supplier, creating administrative overhead that smaller regional players struggle to resource.
- Extrusion equipment capex intensity:Commercial-scale high-moisture extrusion lines require seven-figure capital commitments, favoring well-capitalized entrants over local startups.
- Cross-border labeling harmonization:Divergent nutritional claim standards between Saudi FDA and South African Department of Health force portfolio fragmentation or lowest-common-denominator formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Plant-Based Meat and Dairy Products Market |
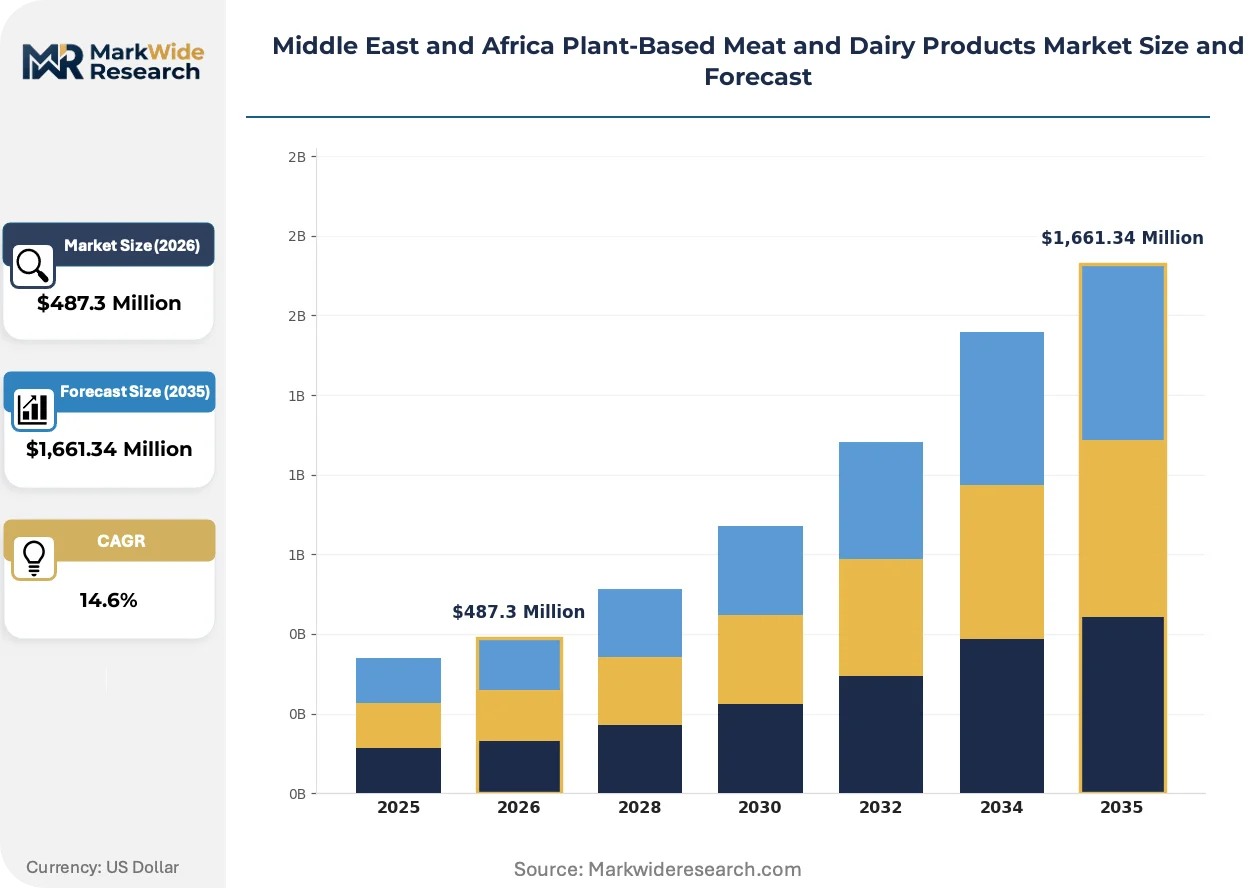
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,661.34 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plant-Based Meat, Plant-Based Milk, Plant-Based Cheese, Plant-Based Yogurt Ingredient Type: Soy, Pea Protein, Wheat Gluten, Almond End User: Households, Restaurants, Retail Chains, Food Service Providers Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Specialty Stores |
| Companies Covered | Danone SA, Beyond Meat Inc, Upfield Holdings B.V., Al Islami Foods, Silk, Alpro, The Hain Celestial Group, Inc., Koita FZE, Impossible Foods, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Plant-Based Meat and Dairy Products Market Shifts & Advancements
Product formulation and certification pathways are diverging as manufacturers prioritize either premium foodservice positioning or mass-market retail accessibility, with technology choices locking in divergent cost structures.
High-moisture extrusion is bifurcating the competitive landscape between capital-intensive multinational suppliers and regional specialists. Gulf-based hotel chains and fine-dining groups are adopting these textures for premium menu placements at accelerated procurement cycles. The technology is bifurcating market tiers—those with extrusion capability capture foodservice margins while non-integrated competitors remain confined to commoditized retail segments.
SFDA nutritional claims guidelines and UAE MOHAP import registration requirements are tightening evidentiary standards for protein content and allergen labeling. Manufacturers must now submit third-party analytical certificates for every production batch, elevating quality assurance costs. Dairy-alternative beverages face the strictest scrutiny, with several brands reformulating to reduce additive counts and simplify ingredient declarations.
Buyer concentration among large-format retail chains in South Africa and the UAE is compressing supplier negotiation cycles and demanding exclusive product variants. Private-label plant-based ranges at Pick n Pay and Spinneys are displacing branded shelf space, forcing national brand owners to invest in direct consumer education and recipe content. This concentration is most visible in Johannesburg and Cape Town, where two retailers control over sixty percent of plant-based milk distribution.
Middle East and Africa Plant-Based Meat and Dairy Products Market Segmentation
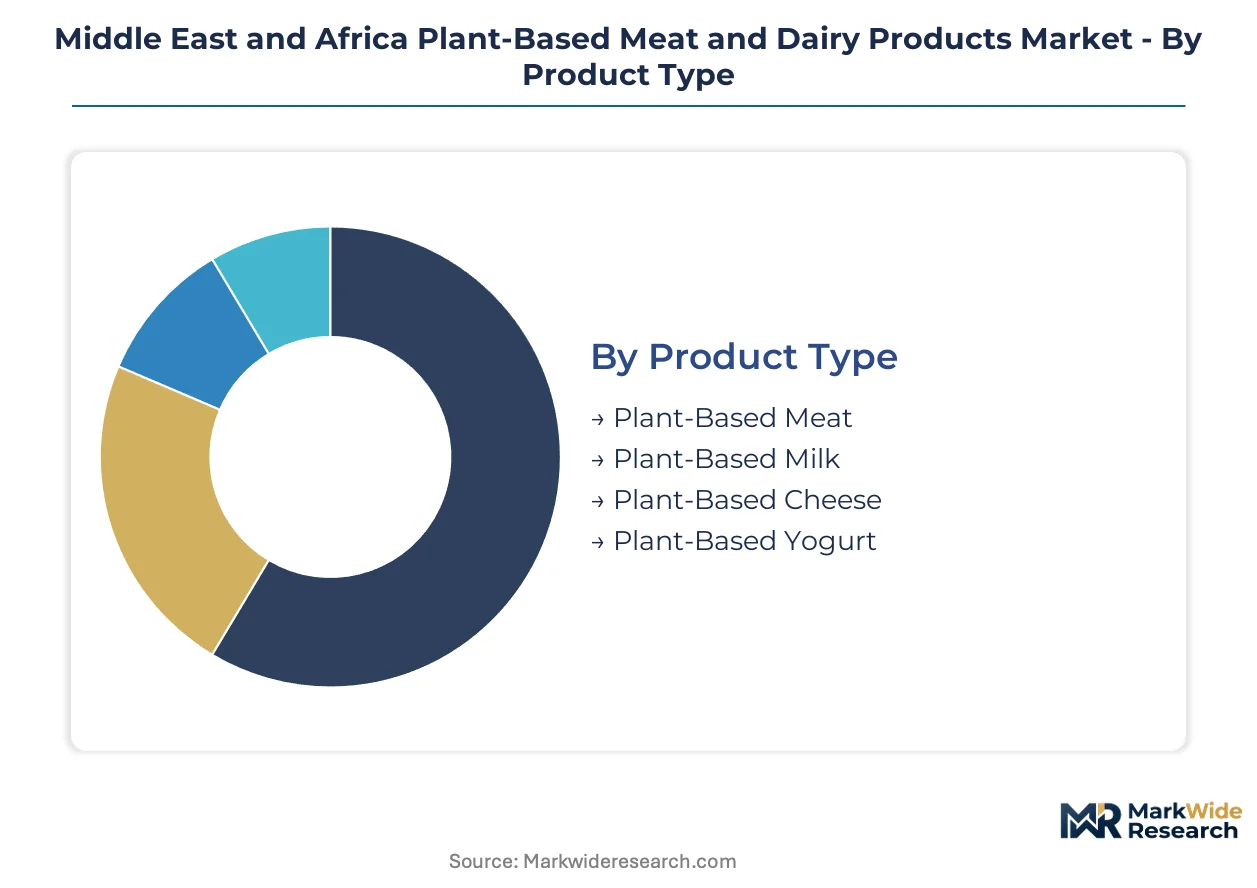
Segmentation in the Middle East and Africa plant-based protein space reveals divergent margin architectures across product formats and channel structures. Manufacturers must align extrusion capabilities, halal certification pathways, and cold-chain reach to specific segment requirements or risk margin erosion.
Product Type:
Margin pools concentrate in ambient-stable formats that bypass refrigeration constraints across the region's fragmented cold-chain infrastructure.
- Plant-Based Meat:High-moisture extrusion creates fibrous textures replicating beef and poultry cuts. Dubai and Riyadh hotel chains are pulling premium burger and kebab formats for dedicated menu sections, though ambient stability limitations constrain distribution beyond urban clusters.
- Plant-Based Milk:Barista-grade oat and almond formulations command price premiums in UAE and South African café channels. Pick n Pay and Spinneys private-label ranges are compressing branded margins, forcing national players toward direct hospitality supply relationships.
- Plant-Based Cheese:Fermented cashew and coconut oil bases target pizza and sandwich applications in Johannesburg and Cape Town foodservice.
- Plant-Based Yogurt:Probiotic coconut and soy formulations serve breakfast and smoothie channels in Kenyan and Tanzanian urban retail.
Plant-Based Milk holds installed capacity. Plant-Based Meat is rotating up the share rankings.
Ingredient Type:
Cost tier differentiation separates commodity soy isolates from premium allergen-free alternatives commanding formulation premiums.
- Soy:Legacy protein base with established supply chains and lowest per-kilogram input costs. South African manufacturers leverage domestic crushing infrastructure, though consumer perception shifts in Gulf markets are forcing portfolio diversification.
- Pea Protein:Wet-fractionation advances are lowering isolate production costs and enabling cleaner taste profiles. Wet-fractionation improvements are lowering isolate production costs and enabling cleaner taste profiles that satisfy Middle Eastern sensory preferences, with wet-fractionation improvements lowering isolate production costs and enabling cleaner taste profiles that satisfy Middle Eastern sensory preferences.
- Wheat Gluten:Seitan-based formats serve cost-sensitive retail segments in Egyptian and Moroccan markets.
- Almond:California-sourced bases dominate premium beverage positioning in UAE and Saudi Arabian retail.
Soy maintains volume leadership. Pea Protein is climbing the fastest as manufacturers reformulate for allergen-sensitive positioning.
End User:
Application concentration determines whether procurement flows through consolidated retail buyers or fragmented foodservice operators.
- Restaurants:Hotel and fine-dining operators in Dubai, Riyadh, and Johannesburg are accelerating procurement cycles for premium extruded formats. Direct supply relationships bypass retail margin stacking and build chef-level brand equity.
- Households:South African urban consumers drive repeat purchase frequency in plant-based milk through established supermarket presence. Price sensitivity constrains experimentation with emerging meat alternatives outside promotional windows.
- Retail Chains:Pick n Pay and Spinneys buyer concentration demands exclusive SKUs and slotting fee commitments.
- Food Service Providers:Institutional catering contracts in Saudi Arabian healthcare and education sectors require bulk pricing and halal audit documentation.
Restaurants capture premium margin pools. Households anchor volume throughput.
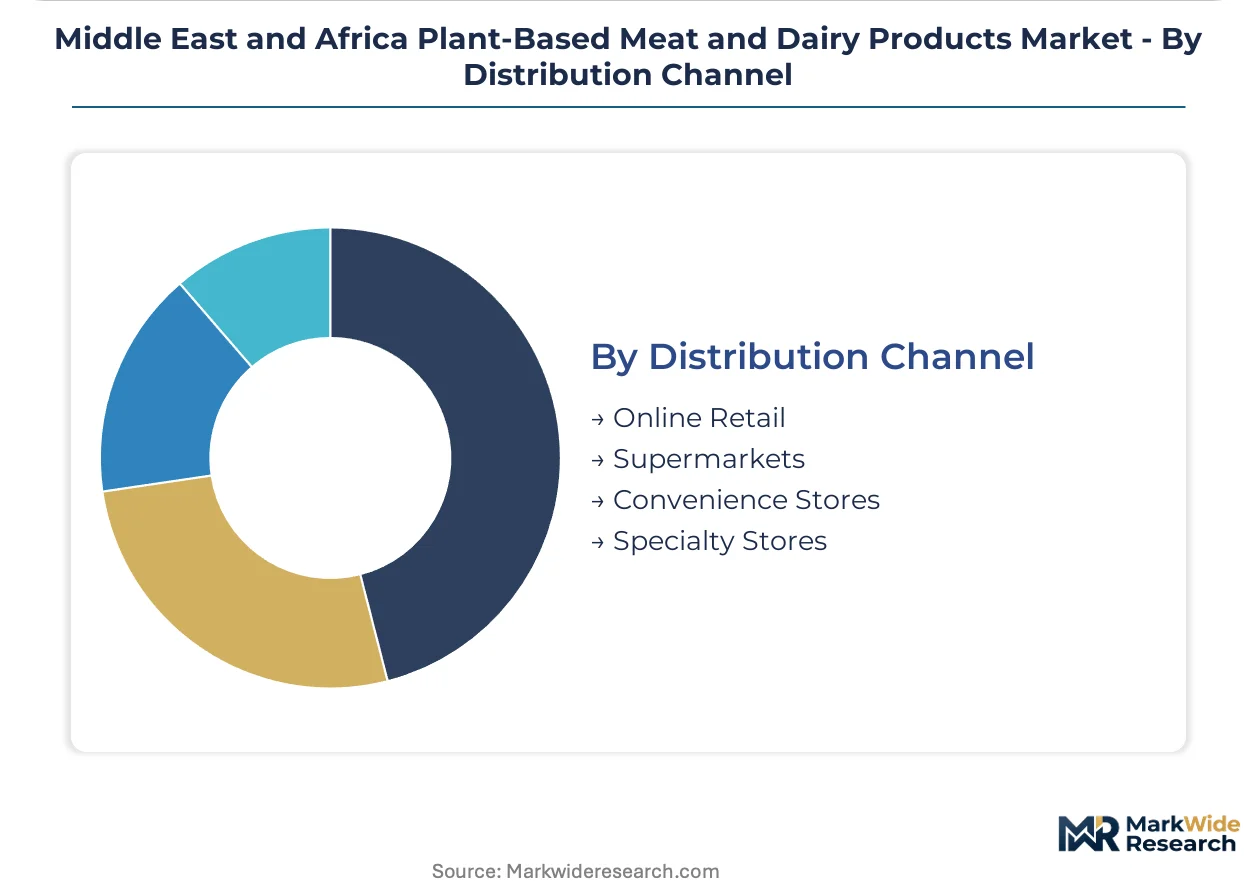
Distribution Channel:
Channel selection dictates refrigeration requirements, certification documentation burdens, and working capital intensity.
- Supermarkets:South African and UAE large-format chains control shelf placement and promotional calendars. Private-label expansion at Pick n Pay and Spinneys is displacing branded space, forcing supplier investment in consumer education and recipe content.
- Online Retail:Subscription models and direct-to-consumer platforms are gaining traction in Nairobi and Lagos urban clusters. Cold-chain gaps limit perishable meat alternatives to ambient-stable dairy formats.
- Convenience Stores:Grab-and-go plant-based milk single-serve formats target commuter traffic in Johannesburg and Cape Town.
- Specialty Stores:Health-focused independents in Dubai and Riyadh serve expatriate and wellness-oriented local consumers.
Supermarkets dominate current throughput. Online Retail is gaining share fastest as logistics infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Middle East and Africa plant-based protein sector runs a structural trade deficit in protein isolates, with regional manufacturers importing textured pea and fava inputs from North American and European suppliers. This dependency shapes margin structures and exposes local processors to currency volatility and shipping disruptions across key consumption clusters.
United Arab Emirates
Dubai's hospitality sector drives premium demand for high-moisture extruded formats, with hotel chains accelerating procurement cycles for dedicated plant-based menu sections. MOHAP import registration requirements enforce third-party analytical certificates for every production batch, elevating quality assurance costs. Abu Dhabi's retail infrastructure supports ambient-stable dairy alternatives through Spinneys and large-format supermarket chains.
Saudi Arabia
Riyadh's foodservice operators are expanding dedicated plant-based sections to capture shifting consumer preferences in the Kingdom's urban centers. SFDA nutritional claims guidelines tighten evidentiary standards for protein content and allergen labeling, forcing reformulation investments. The Eastern Province's institutional catering contracts in healthcare and education sectors require bulk pricing and comprehensive halal audit documentation.
South Africa
Johannesburg and Cape Town anchor regional volume through established supermarket infrastructure, with Pick n Pay controlling significant shelf placement for plant-based milk categories. The Department of Health food labeling standards mandate specific nutritional disclosure formats that extend product development timelines. Private-label expansion at major retailers is displacing branded space, forcing national players toward direct hospitality supply relationships.
Egypt
Cairo's cost-sensitive retail segments sustain demand for wheat gluten-based seitan formats at accessible price points. The country's national food safety regulator maintains import inspection protocols that delay product registration for international entrants. Alexandria's processing infrastructure supports domestic soy crushing operations that supply legacy protein bases for local manufacturers.
Kenya
Nairobi's urban clusters present whitespace opportunity where urbanization and diaspora influence are creating early adopter segments for plant-based dairy alternatives. National regulators are adopting FSSAI-aligned food safety protocols as reference frameworks, reducing reformulation burdens for compliant entrants. Mombasa's logistics infrastructure enables distribution reach into Tanzanian and Ethiopian markets with emerging retail modernization.
Middle East and Africa Plant-Based Meat and Dairy Products Market Competitive Landscape
Concentration sits with multinational extrusion-technology leaders and deep-halal-integrated regional specialists. The vendor base splits between capital-intensive suppliers capable of high-moisture extrusion at commercial scale and smaller regional players confined to commoditized retail segments. Two strategic archetypes dominate: technology-licensing multinationals supplying foodservice operators across Gulf markets, and halal-certification-anchored specialists leveraging familiar brand equity in Middle Eastern retail channels. Competitive moves center on direct-to-hospitality distribution partnerships and portfolio diversification away from legacy soy formulations toward allergen-free alternatives.
Within the multinational technology tier, Beyond Meat Inc represents extrusion-capable supply to foodservice operators, while Danone SA exemplifies dairy-alternative beverage positioning through established retail channels. Among regional halal-integrated specialists, Al Islami Foods occupies a position anchored in deep supply chain certification and familiar brand equity across Middle Eastern retail. These three entities illustrate the competitive bifurcation between capital-intensive extrusion leadership and certification-driven regional penetration.
| Leading Market Players |
|---|
| Danone SA |
| Beyond Meat Inc |
| Upfield Holdings B.V. |
| Al Islami Foods |
| Silk |
| Alpro |
| The Hain Celestial Group, Inc. |
| Koita FZE |
| Impossible Foods |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between South African retailers and European protein isolate suppliers lock in both supply access and price visibility across the Middle East and Africa plant-based protein market. These arrangements insulate Pick n Pay and Spinneys procurement teams from spot-market volatility in pea and fava protein inputs while constraining margin flexibility for regional manufacturers lacking equivalent purchasing scale.
Pricing Analysis
Industrial OEM buyers anchor contract-based pricing structures that stratify across premium, standard, and economy tiers based on halal certification grade and volume scale. Foodservice operators in Dubai and Riyadh command favorable terms through bulk commitments and direct supply relationships, while smaller retail distributors face price erosion from private-label competition and slotting fee burdens. Cost compression in economy-tier soy-based formulations is intensifying because Egyptian and Moroccan manufacturers compete on accessible price points. Household consumers in South Africa demonstrate highest price sensitivity, whereas Gulf hotel chains exhibit lowest sensitivity due to menu premiumization strategies.
Supply Chain Analysis
Inventory buffers at Jebel Ali and Durban ports extend lead times for North American and European protein isolate shipments, exposing regional formulators to working capital pressure. Supply concentrates in Canada and France for textured pea protein, the Netherlands for precision fermentation inputs, and India for soy isolate processing. Raw material dependencies on imported protein isolates, fermentation feedstocks, and halal-certified emulsifiers create single-source vulnerability when shipping disruptions affect Red Sea transit routes. Distribution runs through consolidated supermarket chains in Johannesburg and Cape Town, with direct-to-hospitality bypass emerging in Gulf markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa plant-based protein market functions as a defensive-moat story where regulatory entrenchment through halal certification reciprocity creates durable barriers against unqualified entrants. Network effects concentrate in foodservice procurement relationships where chef-level brand equity compounds through repeat menu placements.
For Market Incumbents: Compound halal supply chain integration advantages by deepening audit documentation capabilities and securing multi-year institutional catering contracts in Saudi Arabian healthcare and education sectors. Threat from precision fermentation startups demands accelerated R&D investment in microbial protein applications that satisfy both clean-label and religious compliance requirements. Capacity addition in UAE extrusion facilities represents the priority lever for capturing premium foodservice margins before competitor technology licensing reaches commercial scale. For New Entrants and Emerging Players: Direct-to-hospitality service layers where incumbents under-serve present whitespace opportunity for agile suppliers willing to bypass retail margin stacking. East African urban clusters in Nairobi and Mombasa offer the most penetrable geography where FSSAI-aligned regulatory familiarity reduces compliance burdens for prepared entrants. Go-to-market execution should prioritize subscription-based online retail models that circumvent cold-chain gaps limiting perishable meat alternative distribution. For Investors and Strategic Acquirers: Regional halal-certification specialists with established UAE and Saudi retail presence represent the acquisition target archetype most likely to compound value through regulatory moat expansion. Long-term viability over the coming decade hinges on portfolio diversification away from legacy soy formulations toward allergen-free pea and fava protein positioning. The signal to watch is reciprocity agreement expansion between Malaysian, Indonesian, and Gulf Cooperation Council halal bodies, which would compress multi-market deployment timelines for certified acquirers.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Reciprocity Expansion | Multi-market deployment timelines compress when Malaysian and Indonesian bodies recognize Gulf Cooperation Council standards. |
| Direct-to-Hospitality Distribution Buildout | Bypassing retail margin stacking captures premium foodservice pricing in Dubai and Riyadh hotel chains. |
| Pea Protein Wet-Fractionation Investment | Cleaner taste profiles from improved isolate production satisfy Middle Eastern sensory preferences and enable allergen-free positioning. |
| Precision Fermentation Capability Addition | Microbial protein production converges with traditional fermentation to yield novel ingredients satisfying halal and clean-label demands. |
| East African Market Entry Programming | Nairobi and Mombasa urban clusters present whitespace where FSSAI-aligned protocols reduce reformulation burdens. |
Research Methodology
A standing panel of foodservice procurement directors, halal certification auditors, retail category buyers, and plant-based R&D formulators provided ongoing calibration across primary data collection. The analysis combined structured interviews with these industry stakeholders against secondary validation from SFDA nutritional claims filings, UAE MOHAP import registration databases, South African Department of Health labeling standards, and FSSAI-aligned protocol documentation. Customs records for protein isolate shipments through Jebel Ali and Durban ports supplemented trade flow analysis. Bottom-up demand modeling and top-down supply capacity assessment were triangulated to converge on market size estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product type, ingredient source, end-user application, and distribution channel structure. CAGRs were derived from fitted growth curves applied to base-year estimates and checked against historical expansion patterns in comparable protein substitute markets. Industry-specific forecast inputs incorporated extrusion technology adoption curves and halal certification reciprocity agreement timelines.
Forecasts assume regulatory continuity in SFDA, UAE MOHAP, and South African Department of Health regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant Based Pasta Market
Plant Based Food
Japan Plant Protein Market
Plant Based Food
Plant-Based Natural Flavor Market
Plant Based Food
Plant-Based Nuggets Market
Plant Based Food
Germany Plant Protein Market
Plant Based Food
Fermented Plant Extracts Market
Plant Based Food
Plant-Based Beef Market
Plant Based Food
Middle East and Africa Meat Substitute Market
Plant Based Food
Italy Plant Protein Market
Plant Based Food
Vegan Steak Market
Plant Based Food
South America Meat Substitute Market
Plant Based Food
Vegan Dips Market
Plant Based Food
Global Plant Based Milk Market
Plant Based Food
Plant-Based Flour Market
Plant Based Food
Plant Based Cheese Market
Plant Based Food
Vegan Marshmallows Market