
 Plant Based Meat Market | 2026-2036
Plant Based Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Based Meat Market Analysis
Ingredient sourcing margins is narrowing as protein isolate suppliers consolidate upstream positions. Beyond Meat leverages vertical integration into pea-protein extraction to protect formulation costs. Impossible Foods Inc. anchors its position through heme-fermentation technology leadership and patent depth. Maple Leaf Foods Inc. sustains geographic dominance in Canadian retail channels through its Lightlife and Field Roast brand portfolio.
Plant-based meat comprises extruded or sheared protein matrices, typically containing 15-25% protein content, formulated with oils, binders, and flavor precursors to replicate animal muscle tissue texture and umami chemistry. The category serves commercial foodservice and retail consumers seeking protein alternatives with reduced saturated fat and no cholesterol. Pea Protein dominates source-based segmentation due to allergen-friendly positioning against soy and superior emulsion stability in high-moisture extrusion. Wheat Protein retains cost advantages in European and Asian applications where gluten tolerance meets established supply chains. Flexitarians represent the fastest-growing end-user segment, outpacing committed vegetarians and vegans in absolute purchase volume across supermarket and restaurant channels.
The USDA and FDA share jurisdiction over plant-based meat labeling and safety standards in the United States, with ongoing rulemaking on "meat" terminology restricting market access for certain product descriptors. The European Food Safety Authority evaluates novel protein ingredients under EU Novel Food regulations, creating pre-market approval barriers for emerging fermentation-derived proteins. China's National Health Commission and SAMR administer GB standards for plant-based foods, with recent draft rules addressing protein content claims and additive limits. Stakeholders must monitor how evolving label-integrity enforcement and protein-content thresholds reshape competitive positioning in priority markets.
Market Dynamics
Pea-protein supply consolidation upstream is compressing formulation margins and forcing downstream brands to secure captive extraction capacity or accept input cost volatility. This concentration dynamic now determines competitive viability more than consumer demand fluctuations.
Growth Catalysts
- EU Farm to Fork strategy:Binding sustainability benchmarks for protein alternatives are mandating procurement shifts across European foodservice operators, accelerating certified product placement.
- Flexitarian purchase volume:Supermarket and restaurant channels report this segment outpacing committed vegetarians in absolute unit sales, expanding addressable base beyond niche positioning.
- High-moisture extrusion advances:Equipment refinements are reducing texture variance between batches, enabling QSR chains to standardize plant-based patties as permanent menu fixtures.
Market Restraints
- Pea-protein isolate concentration:Three suppliers control majority North American extraction capacity, creating price-setting power and allocation risk during crop shortfalls.
- USDA-FDA label jurisdiction overlap:Ongoing rulemaking on "meat" terminology restricts product descriptor options, forcing costly packaging redesigns and market access delays.
- Heme-fermentation scale barriers:Novel protein production requires bioreactor infrastructure that few contract manufacturers possess, limiting capacity expansion for precision fermentation entrants.
Strategic Opportunities
- Brazilian retail penetration:Supermarket chains in São Paulo and Rio de Janeiro are expanding shelf space for pea-protein formulations faster than any Latin American market.
- Hybrid meat-plant blends:Foodservice operators are testing 70/30 animal-plant ratios to reduce saturated fat claims while maintaining familiar taste profiles for mainstream consumers.
- China GB standards finalization:Draft protein content claims and additive limits from SAMR will clarify compliance pathways, reducing regulatory uncertainty for entrants.
Industry Challenges
- Extrusion technician scarcity:High-moisture extrusion operation requires specialized knowledge of shear rate and moisture control that existing food manufacturing workforces rarely possess.
- EU Novel Food approval timelines:EFSA evaluation periods for emerging fermentation-derived proteins extend 18-24 months, consuming working capital before revenue generation.
- Patent thickets around heme precursors:Licensing complexity for soy leghemoglobin production is forcing second movers to pursue alternative iron-carrying molecules with unproven sensory performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Based Meat Market |
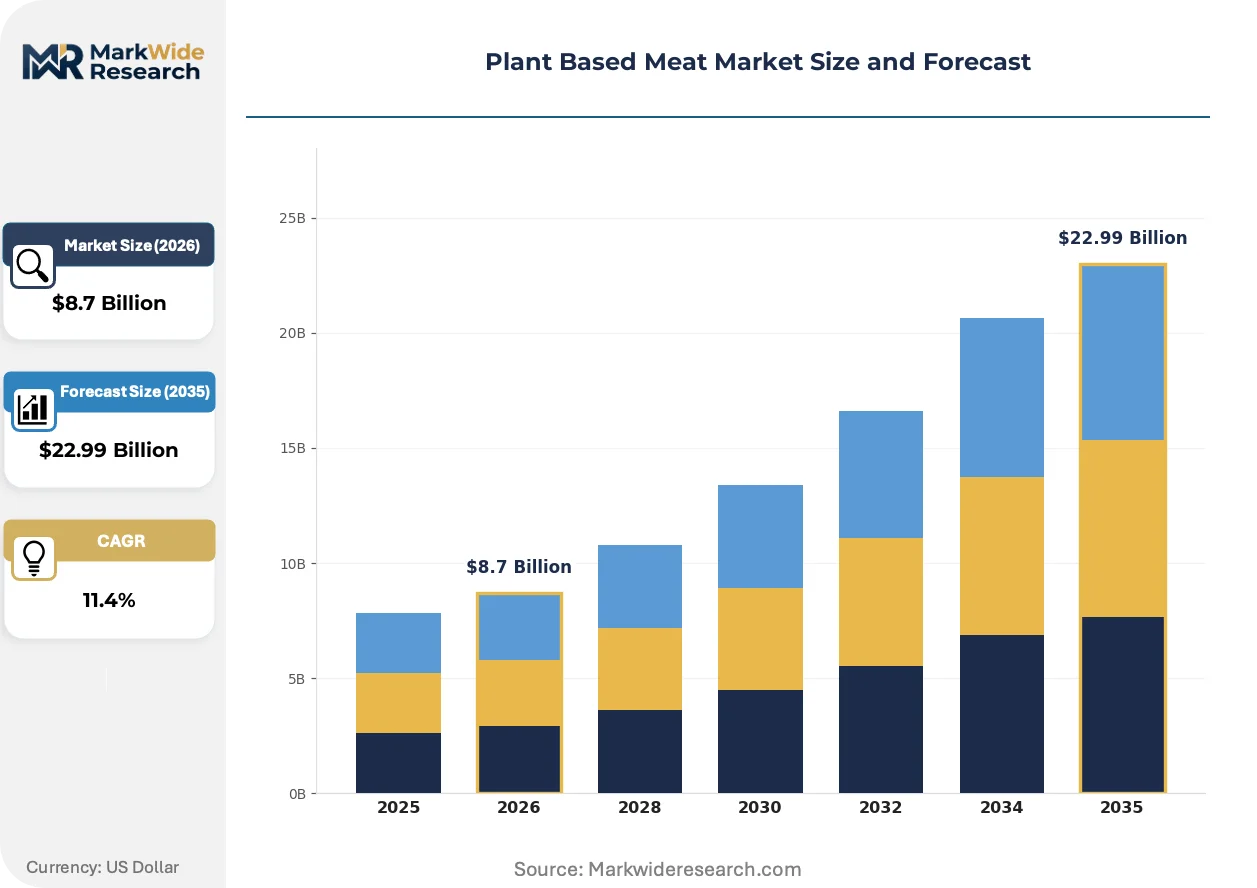
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Veggie Burgers, Plant Sausages, Meatballs, Nuggets Source: Pea Protein, Soy Protein, Wheat Protein, Lentil Protein Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Restaurants End User: Vegetarians, Vegans, Flexitarians, Health Conscious Consumers |
| Companies Covered | Beyond Meat, Impossible Foods Inc., Quorn Foods, Maple Leaf Foods Inc., Tofurky, Amy's Kitchen Inc., Conagra Brands, Inc., The Vegetarian Butcher, VBites Foods Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Based Meat Market Emerging Trajectories
Shear-cell technology is collapsing the cost gap between plant-based texture replication and conventional extrusion methods. Three interconnected developments are compressing production economics and reshaping competitive entry barriers.
Shear-cell processing is collapsing the capital intensity barrier that previously separated pilot-scale from industrial-volume texture formation. European equipment manufacturers are installing units at mid-cap food companies within twelve-month commissioning cycles. This compression is enabling regional brands to achieve fibrous muscle-tissue analogs without the extruder infrastructure that anchored incumbents.
REACH authorization requirements for novel protein processing aids are tightening purity documentation standards for European market entry. Industrial consequence includes mandatory supply chain audits back to agricultural input sources. Fermentation-derived ingredient suppliers are responding by integrating in-house analytical chemistry capabilities to preempt regulatory rejection.
Direct-to-foodservice distribution is displacing traditional broker networks for plant-based protein procurement. Large contract caterers and institutional buyers are establishing preferred supplier agreements that bypass wholesale distributors entirely. This channel compression is most visible in German and US hospital and university feeding systems where volume concentration justifies dedicated logistics arrangements.
Plant Based Meat Market Segmentation
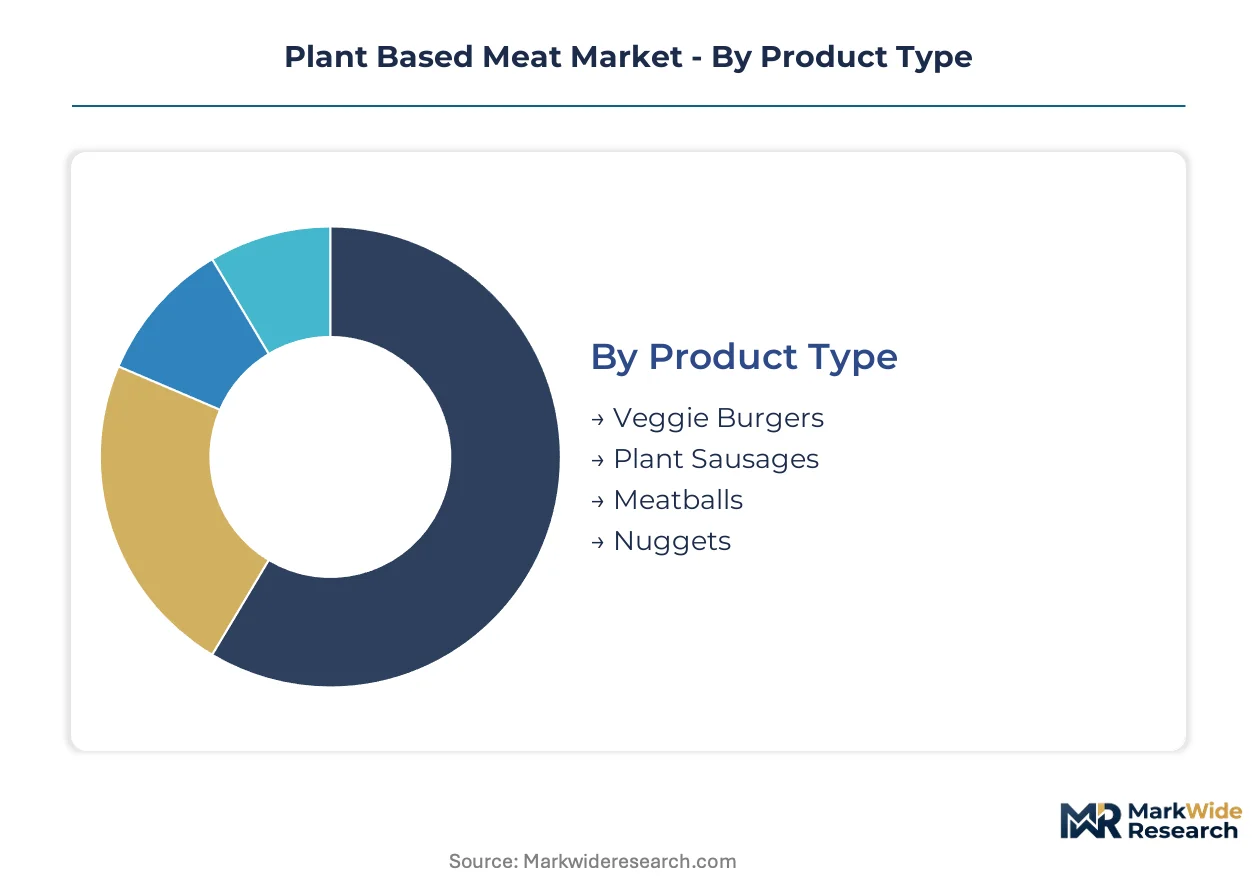
Segmentation in plant-based meat reveals how formulation choices, protein sourcing, and channel access determine margin capture. Each dimension exposes distinct technical barriers and regulatory exposure that shape competitive entry.
Product Type:
Mature formats dominate volume while emerging formats reshape texture benchmarks.
- Veggie Burgers:Extruded or sheared protein matrices at 15-25% protein content, formulated with oils and binders to replicate ground beef texture. Quick-service restaurant chains in the United States and Germany standardize these as permanent menu fixtures, driving procurement consolidation.
- Plant Sausages:Emulsion-based systems requiring precise fat-protein binding and casing integrity. Health Food Stores and specialty retailers in European markets prioritize certified organic variants, creating premium positioning opportunities.
- Meatballs:Spherical extrudates with breadcrumb analogs for binding; common in foodservice pre-portioned formats.
- Nuggets:Battered and breaded bite-sized pieces targeting child-oriented menu placements and retail frozen aisles.
Veggie Burgers handle the majority of throughput; Nuggets are gaining share fastest among younger demographics.
Source:
Cost tiers separate allergen-friendly premium positioning from commodity protein economics.
- Pea Protein:Isolate with superior emulsion stability in high-moisture extrusion and hypoallergenic positioning against soy. China and Brazil concentrate the fastest-growing demand outside North America and Europe as local suppliers scale extraction capacity.
- Soy Protein:Established isolate and concentrate infrastructure with cost advantages; faces allergen labeling requirements in multiple jurisdictions.
- Wheat Protein:Gluten-based texturizing agent retaining cost advantages in European and Asian applications where supply chains are mature.
- Lentil Protein:Emerging isolate with favorable amino acid profiles; limited commercial scale restricts current formulation penetration.
Pea Protein handles the majority of throughput; Lentil Protein is expanding most quickly on share as extraction technology matures.
Distribution Channel:
Volume concentration shifts toward direct institutional procurement, bypassing traditional intermediaries.
- Supermarkets:Primary retail access point with dedicated plant-based sections; shelf-space allocation determines brand visibility.
- Online Retail:Direct-to-consumer subscription models and marketplace platforms capturing trial purchases.
- Health Food Stores:Curated assortments emphasizing certified organic and clean-label positioning.
- Restaurants:Foodservice operators including quick-service chains and contract caterers establishing preferred supplier agreements.
Supermarkets handle the majority of throughput; Restaurants are climbing the fastest on share through direct procurement.
End User:
Customer type stratification reveals that dietary commitment correlates inversely with absolute purchase volume.
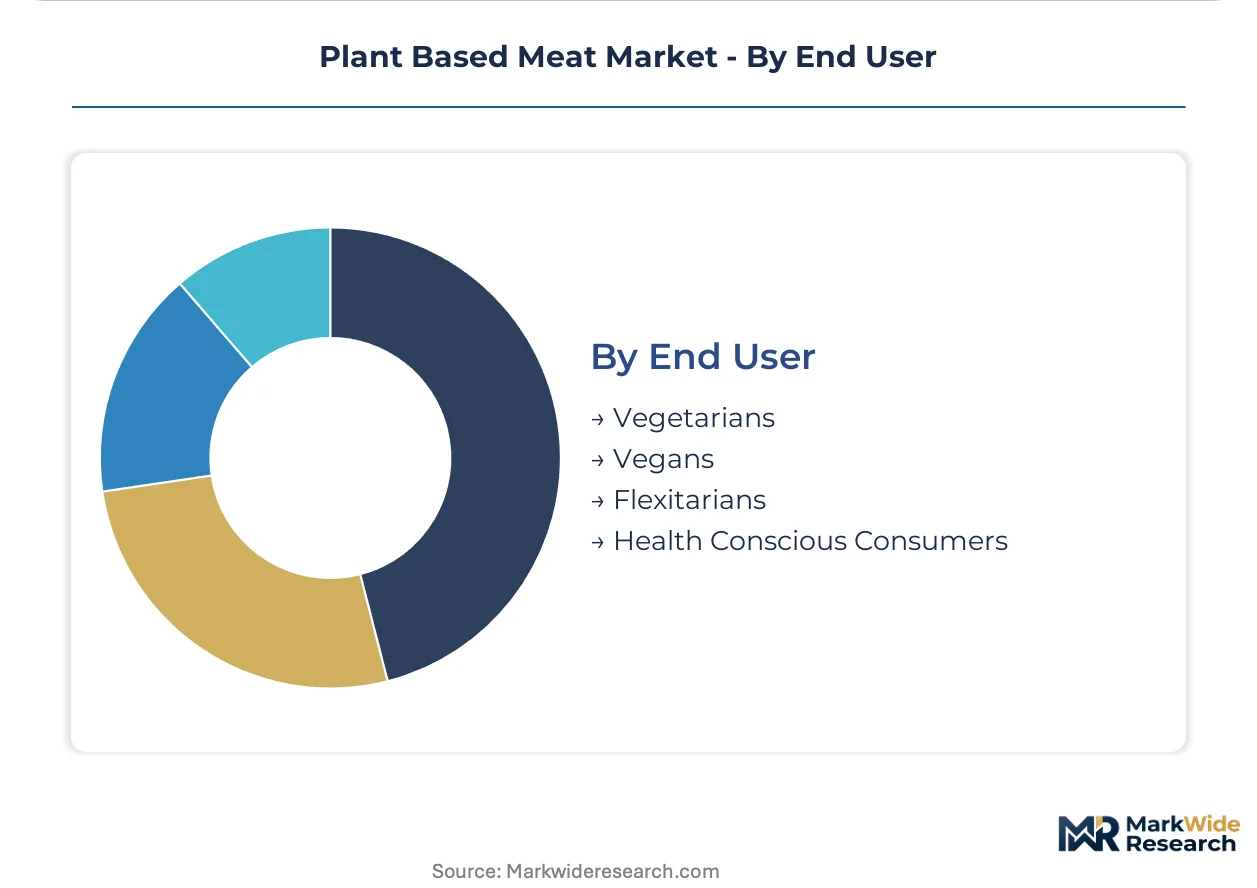
- Flexitarians:Consumers reducing animal protein without eliminating it; this segment outpaces committed vegetarians and vegans in absolute purchase volume across supermarket and restaurant channels.
- Health Conscious Consumers:Buyers prioritizing reduced saturated fat and zero cholesterol claims; responsive to nutritional labeling and physician recommendations.
- Vegetarians:Long-term abstainers from meat consumption; established demand base with stable purchasing patterns.
- Vegans:Strictest dietary exclusion; smallest absolute segment but highest per-unit willingness to pay for certified products.
Flexitarians handle the majority of throughput; Health Conscious Consumers are gaining share fastest as clinical nutrition guidance evolves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Quick-service restaurant chains in the United States and Germany stock plant-based patties as standard menu items, while China and Brazil concentrate the fastest-growing demand for pea-protein formulations outside established Western markets.
United States
Quick-service restaurant procurement drives volume concentration, with chains standardizing plant-based patties as permanent menu fixtures. The USDA and FDA share jurisdiction over labeling and safety standards, with ongoing rulemaking on "meat" terminology restricting product descriptors. Chicago and Los Angeles anchor foodservice testing corridors where contract caterers establish preferred supplier agreements bypassing traditional distribution.
Germany
European foodservice operators accelerate certified product placement under binding sustainability benchmarks. The EU's Farm to Fork strategy mandates procurement shifts across institutional feeding systems. Berlin and Hamburg concentrate direct-to-foodservice distribution where hospital and university buyers negotiate dedicated logistics arrangements.
China
Local suppliers scale pea-protein extraction capacity to meet surging formulation demand from domestic brands. The National Health Commission and SAMR administer GB standards for plant-based foods, with draft rules addressing protein content claims and additive limits. Shanghai and Shenzhen anchor manufacturing clusters where mid-cap food companies commission shear-cell processing units within compressed timelines.
Brazil
Supermarket chains in São Paulo and Rio de Janeiro expand shelf space for pea-protein formulations faster than any Latin American market. ANVISA regulates novel protein ingredients under pre-market approval frameworks similar to EU structures. The São Paulo metropolitan corridor concentrates retail distribution infrastructure serving flexitarian consumers reducing animal protein without eliminating it.
United Kingdom
Health food stores and specialty retailers prioritize certified organic variants, creating premium positioning opportunities distinct from mass-market penetration. The Food Standards Agency enforces allergen labeling requirements that favor pea-protein positioning against soy. London and Manchester anchor curated retail assortments where clean-label positioning commands price premiums.
Plant Based Meat Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another. Three suppliers control majority North American pea-protein extraction capacity, creating price-setting power that determines downstream competitive viability. Strategic archetypes include vertically integrated ingredient-to-brand operators, precision fermentation technology specialists, and multi-brand portfolio owners leveraging geographic channel dominance. Dominant competitive moves center on captive extraction capacity acquisition and direct-to-foodservice distribution bypassing wholesale intermediaries.
Within the vertically integrated tier, Beyond Meat exemplifies backward integration into upstream pea-protein extraction to protect formulation cost structures. Impossible Foods Inc. occupies a position anchored by heme-fermentation technology leadership and patent depth around iron-carrying molecules. Maple Leaf Foods Inc. represents the multi-brand portfolio archetype, sustaining retail channel presence through consolidated brand ownership.
| Leading Market Players |
|---|
| Beyond Meat |
| Impossible Foods Inc. |
| Quorn Foods |
| Maple Leaf Foods Inc. |
| Tofurky |
| Amy's Kitchen Inc. |
| Conagra Brands, Inc. |
| The Vegetarian Butcher |
| VBites Foods Limited |
| Others |
Supply Flow & Price Mechanics
Three North American pea-protein isolate suppliers command majority extraction capacity, anchoring price-setting power that compresses downstream formulation margins and forces brand operators toward captive supply arrangements or cost volatility absorption.
Pricing Analysis
Long-term offtake contracts dominate procurement between pea-protein extractors and brand manufacturers, though spot purchases persist for formulation flexibility. Price differentiation rests on certification grade and volume scale, with organic-certified isolates commanding premiums and bulk commitments securing preferential rates. Cost compression in mid-tier formulations is intensifying because upstream consolidation limits supplier alternatives. Foodservice operators exhibit highest price sensitivity due to thin menu-margin structures, while health food retailers show least sensitivity given clean-label positioning premiums.
Supply Chain Analysis
Contract manufacturing capacity for high-moisture extrusion concentrates in the United States, Germany, and China, with European equipment manufacturers expanding installation timelines for mid-cap food companies. Raw material dependencies center on yellow pea cultivation, protein isolate processing, and heme-fermentation precursors. Single-source vulnerability runs through the three dominant North American pea-protein extractors. Distribution feeds from direct-to-foodservice arrangements bypassing wholesale intermediaries, particularly visible in German hospital systems and US university feeding contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-moisture extrusion advances are disrupting competitive entry barriers, compressing capital requirements for texture replication and enabling regional brand formation outside incumbent strongholds.
For Market Incumbents: Entrench formulation cost advantages through backward integration into pea-protein extraction capacity or binding long-term offtake agreements with isolate suppliers. Defend QSR channel positioning against shear-cell technology entrants by accelerating equipment refresh cycles and locking permanent menu placements. Patent depth around iron-carrying molecules represents a critical lever for heme-fermentation specialists facing second-mover competition.
For New Entrants and Emerging Players: Brazilian retail expansion in São Paulo and Rio de Janeiro represents the most penetrable entry point for pea-protein formulations seeking shelf-space growth outside saturated North American and European markets. Chinese GB standards finalization creates regulatory clarity for compliant entrants targeting domestic formulation demand. Direct-to-foodservice distribution agreements with contract caterers offer a defensible go-to-market angle bypassing wholesale margin extraction.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with precision fermentation technology specialists holding bioreactor infrastructure but facing scale barriers and working capital consumption through extended EFSA approval timelines. Long-term viability across the analysis window favors vertically integrated operators controlling upstream extraction and downstream brand placement. The signal to watch is EFSA novel protein approval velocity as an inflection indicator for fermentation-derived ingredient commercialization.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Pea-Protein Extraction Capacity | Backward integration protects formulation margins against upstream price-setting power from consolidated isolate suppliers. |
| Direct-to-Foodservice Distribution Agreements | Bypassing wholesale intermediaries captures margin compression visible in German hospital and US university feeding systems. |
| Shear-Cell Processing Equipment Deployment | Reduced capital intensity enables regional brands to achieve fibrous texture replication without legacy extruder infrastructure. |
| EU Novel Food Regulatory Pre-Approval Investment | Early EFSA engagement compresses working capital consumption timelines for fermentation-derived protein entrants. |
| Hybrid Meat-Plant Formulation Development | 70/30 animal-plant ratios reduce saturated fat claims while maintaining familiar taste profiles for mainstream flexitarian consumers. |
Methodological Framework
A standing panel of extrusion equipment operators, pea-protein procurement leads at brand manufacturers, QSR menu development executives, and EFSA regulatory affairs specialists provided ongoing calibration across primary interview rounds. Secondary validation drew from USDA labeling rulemaking dockets, EU Farm to Fork strategy documentation, SAMR draft GB standards, and customs records tracking pea-protein isolate trade flows. Bottom-up volume modeling triangulated against top-down protein alternative consumption estimates.
Scenario-bracketing anchored the analytical framework across the projection horizon, with sensitivity testing around EFSA approval timelines and Chinese regulatory finalization. Segmentation dimensions modeled included protein source, product format, distribution channel, and end-user dietary commitment level. CAGRs derived from fitted growth curves applied to base-year consumption estimates, incorporating high-moisture extrusion capacity expansion rates and flexitarian purchase velocity as industry-specific inputs.
Practitioners should monitor EFSA novel protein evaluation velocity, SAMR GB standards promulgation, and North American pea crop yield projections for early signals of forecast revision. Quarterly review of upstream supplier consolidation indicators and QSR menu placement permanency rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Vegan Chocolate Market
Plant Based Food
United Kingdom Tofu Market
Plant Based Food
Plant Based Ice Cream Market
Plant Based Food
Lentil Protein Market
Plant Based Food
Plant-Based Bars Market
Plant Based Food
Faba Bean Protein Market
Plant Based Food
United States Rice Protein Market
Plant Based Food
Yucca Extract Market
Plant Based Food
Plant-Based Shrimp Market
Plant Based Food
South America Pea Protein Market
Plant Based Food
Smart Plant Based Food Packaging Market
Plant Based Food
Veggie Meals Market
Plant Based Food
Plant Based Eggs Market
Plant Based Food
Asia Pacific Plant-Based Milk Market
Plant Based Food
Plant Chocolate Protein Powder Market
Plant Based Food
Vegan Marshmallows Market